
 US Specialty Gas Market | 2026-2036
US Specialty Gas Market Size, Share, and Industry Trends Forecast 2026-2036
US Specialty Gas Market Insights
Aftermarket service revenue from cylinder management and gas delivery systems is reshaping margin distribution across the value chain. Air Products and Chemicals, Inc. leverages its Gulf Coast hydrogen pipeline network to anchor industrial supply contracts. Linde plc sustains leadership in on-site gas generation through long-term take-or-pay agreements with Texas refineries. Matheson Tri-Gas, Inc. specializes in ultra-high-purity gas purification for semiconductor customers in the Pacific Northwest.
US specialty gases comprise purified or chemically formulated gases meeting exacting purity grades, often specified at 99.999% or higher for critical processes such as epitaxial silicon deposition and magnetic resonance imaging coolant systems. These gases serve as process enablers where contamination at parts-per-billion levels can destroy batch yields or compromise diagnostic accuracy. Electronics end users command the largest volume pull, with helium and argon feeding etching and lithography steps in advanced node fabrication. Medical imaging applications represent a concentrated margin pool due to MRI magnet cooling requirements and constrained helium supply dynamics. Direct sales channels dominate bulk and on-site contracts, while wholesale and retail segments handle smaller packaged gas volumes for metal fabrication and food preservation customers.
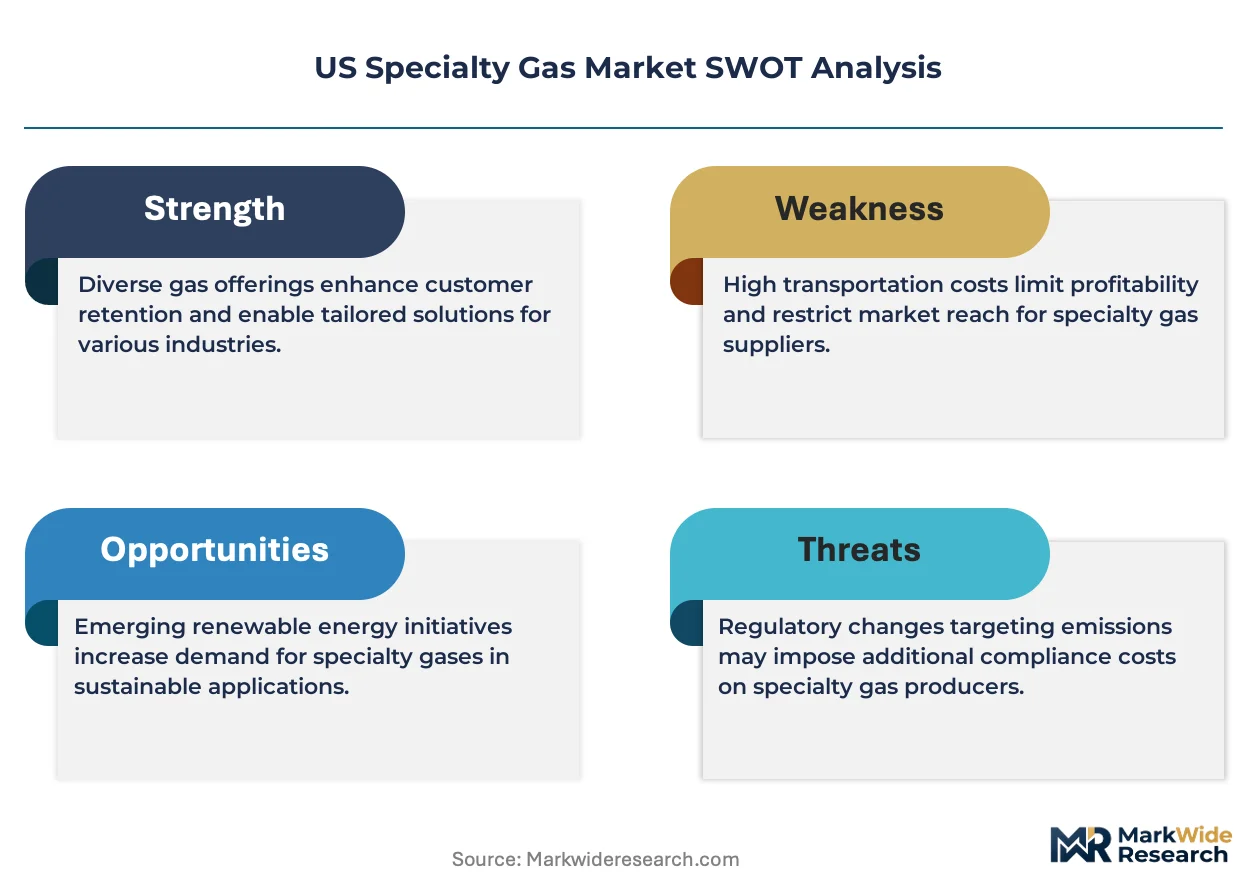
FDA oversight of medical-grade gases, EPA enforcement under the Clean Air Act for fluorinated compound emissions, and OSHA permissible exposure limits for hazardous gases collectively elevate compliance costs and technical barriers to market entry. DOT hazardous materials regulations govern interstate transport of compressed and cryogenic gases, shaping distribution network economics and regional supply reliability. Stakeholders must monitor helium conservation mandates and federal strategic reserve policy decisions that could redirect supply allocations across healthcare and electronics priorities.
Market Dynamics
Helium supply concentration from the Federal Helium Reserve and Bureau of Land Management auctions is forcing semiconductor fabs in Arizona and Texas to lock in multi-year supply contracts ahead of spot market volatility. This upstream constraint is reshaping procurement strategies across electronics manufacturing clusters.
Growth Catalysts
- Semiconductor node advancement:Sub-7nm lithography steps in Arizona and Texas fabs require argon and helium at 99.9999% purity grades, pulling specialty gas volumes upward as domestic wafer capacity expands.
- OSHA permissible exposure limits:Tightened workplace exposure thresholds for hazardous process gases are mandating upgraded ventilation and monitoring systems, creating pull for integrated gas delivery infrastructure.
- EPA Clean Air Act enforcement:Fluorinated compound emissions rules are accelerating replacement of conventional etching chemistries with lower-GWP alternatives, requiring new gas purification and recovery systems.
Market Restraints
- Helium supply concentration:Federal reserve depletion and limited domestic extraction infrastructure create allocation risk for MRI coolant and semiconductor customers dependent on BLM pipeline deliveries.
- Ultra-high-purity certification costs:FDA medical-grade gas validation and semiconductor-grade traceability documentation add fixed compliance burdens that disadvantage smaller packaged gas distributors.
- On-site generation capex barriers:Cryogenic air separation units and PSA systems require eight-figure capital commitments that lock out mid-scale buyers from cost-competitive supply.
Strategic Opportunities
- Southwest electronics cluster densification:TSMC and Intel fab construction in Arizona creates concentrated demand pockets where regional gas production hubs can anchor dedicated supply contracts.
- Helium recycling infrastructure:Closed-loop recovery systems for MRI magnet cooling represent underpenetrated service revenue streams as conservation mandates tighten.
- DOT hazmat transport specialization:Cryogenic logistics certification gaps create whitespace for distributors building dedicated fleets serving Texas and Arizona fabrication corridors.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized technician training for liquid helium and argon handling exceeds current vocational pipeline output, constraining facility expansion timelines.
- Multi-agency compliance synchronization:Simultaneous FDA, EPA, OSHA, and DOT audits create documentation overhead that delays product qualification for cross-sector gas suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Specialty Gas Market |
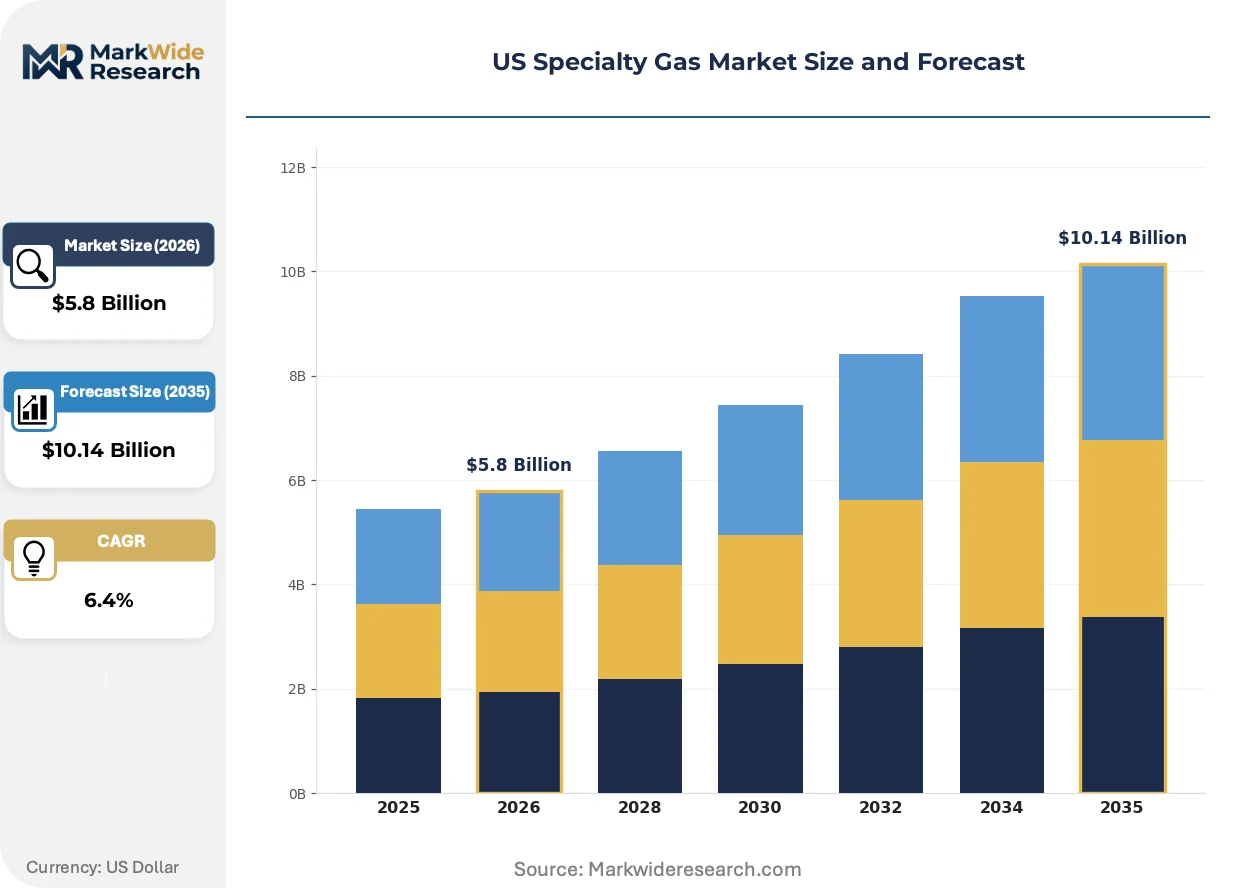
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helium, Hydrogen, Argon, Nitrogen End User: Electronics, Healthcare, Automotive, Food & Beverage Application: Welding, Medical Imaging, Metal Fabrication, Food Preservation Distribution Channel: Direct Sales, Online Sales, Retail, Wholesale |
| Companies Covered | Air Liquide, Air Products and Chemicals, Inc., Linde plc, Messer North America, Inc., Matheson Tri-Gas, Inc., Airgas USA, LLC, Norco, Inc., TAIYO NIPPON SANSO CORPORATION, MESA Specialty Gases & Equipment, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Specialty Gas Market Trends and Innovations
Digital integration of gas delivery systems with fab process control networks is compressing response times for purity excursions. Equipment suppliers and gas producers are co-developing sensor-embedded cylinder fleets that feed real-time consumption data into predictive maintenance algorithms.
Membrane and adsorption purification technology is hybridizing with traditional cryogenic distillation to enable modular, trailer-mounted gas generation units. Southwest semiconductor fabs are deploying these systems for argon and nitrogen supply to reduce dependency on bulk liquid deliveries. The hybrid architecture is compressing minimum efficient scale thresholds and enabling mid-size fabs to justify on-site production economics previously reserved for top-tier integrated device manufacturers.
EPA enforcement under the Clean Air Act is tightening fugitive emissions monitoring for fluorinated specialty gases used in plasma etching. Semiconductor manufacturers in Texas and Arizona are installing point-source capture and abatement systems to preempt enforcement actions. The regulatory pressure is accelerating qualification of lower-global-warming-potential etching chemistries that require reformulated gas blends and updated handling protocols.
Consolidated procurement by large wafer fabs is displacing fragmented spot-market purchasing across the Southwest electronics corridor. Multi-year take-or-pay agreements now dominate argon and helium contracting, with volume commitments tied to fab production schedules. Arizona and Texas fabrication clusters exhibit the most pronounced buyer concentration, with tier-one foundries extracting preferential pricing and dedicated logistics capacity from incumbent suppliers.
US Specialty Gas Market Segmentation
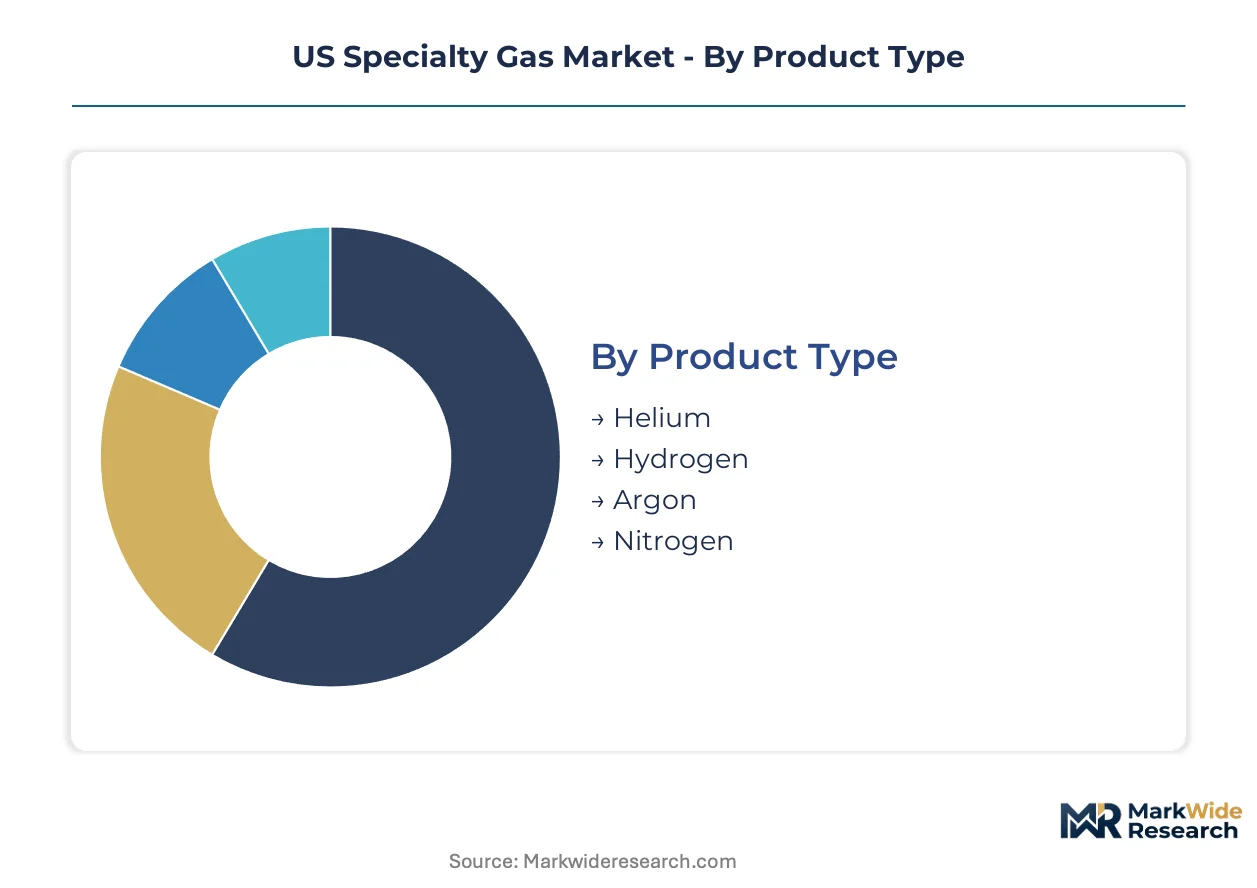
Specialty gas procurement patterns diverge sharply across end-use requirements, with semiconductor fabs demanding ultra-high-purity certification while food preservation customers prioritize cost-efficient bulk delivery. Understanding these segment boundaries clarifies where margin pools concentrate and which technical specifications command pricing premiums.
Product Type:
Each gas serves distinct process temperatures and reactivity profiles across the US industrial base.
- Helium:Inert monatomic gas with the lowest boiling point of any element, enabling superconducting magnet cooling in MRI systems and inert atmosphere control in fiber optic manufacturing. Arizona and Texas semiconductor clusters consume rising volumes for lithography purge applications, though Federal Reserve depletion constrains allocation flexibility for healthcare customers.
- Hydrogen:Lightest molecular gas with high thermal conductivity and reducing properties, essential for semiconductor epitaxy and refinery hydrocracking processes. Gulf Coast pipeline networks anchor industrial supply contracts, with on-site generation economics improving for Texas petrochemical complexes seeking to decarbonize process heat.
- Argon:Inert noble gas denser than air, deployed for plasma etching shielding and titanium alloy welding in aerospace fabrication. Southwest electronics manufacturing densification is pulling argon volumes upward as TSMC and Intel fabs qualify 99.9999% purity grades for sub-7nm node production.
- Nitrogen:Abundant inert gas produced via cryogenic air separation, serving blanket gas applications across food packaging and pharmaceutical manufacturing. Modular PSA systems are compressing minimum efficient scale thresholds for mid-size nitrogen consumers in metal fabrication corridors.
Established volume favors argon; emerging adoption favors hydrogen.
End User:
Customer technical sophistication determines certification burden and contract structure across the value chain.
- Electronics:Wafer fabs and display manufacturers requiring parts-per-billion contamination control, multi-year take-or-pay agreements, and dedicated logistics capacity. Arizona and Texas fabrication clusters exhibit pronounced buyer concentration, with tier-one foundries extracting preferential pricing through consolidated procurement.
- Healthcare:MRI operators and pharmaceutical manufacturers dependent on helium for magnet cooling and nitrogen for cryopreservation. FDA medical-grade gas validation adds fixed compliance burdens that disadvantage smaller distributors serving regional hospital networks.
- Automotive:EV battery cell manufacturers and hydrogen fueling infrastructure operators seeking high-purity gases for electrode coating and fuel cell membrane conditioning. California and Michigan production hubs are qualifying new supply chains for solid-state battery prototyping.
- Food & Beverage:Modified atmosphere packaging operations and beverage carbonation plants prioritizing cost-efficient bulk nitrogen and carbon dioxide delivery. This segment tolerates lower purity grades and fragmented spot-market purchasing compared to semiconductor or medical customers.
Margin concentration sits with electronics; volume expansion is climbing the fastest in automotive.
Application:
Process-specific purity thresholds and safety protocols segment the market by technical intensity.
- Welding:Argon and helium mixtures shielding molten metal from atmospheric contamination in aerospace and automotive fabrication. Texas and California shipyards drive demand for high-flow bulk deliveries with on-site mixing capabilities.
- Medical Imaging:Liquid helium cooling superconducting niobium-titanium magnets in MRI systems, representing a concentrated margin pool due to supply constraints and captive recycling infrastructure requirements. Closed-loop recovery systems are penetrating slowly due to cryogenic engineering talent scarcity.
- Metal Fabrication:Oxygen-acetylene cutting and plasma arc processes consuming industrial-grade gases through wholesale and retail channels. OSHA permissible exposure limits for hazardous process gases are mandating upgraded ventilation systems in Midwest fabrication shops.
- Food Preservation:Nitrogen flushing of snack packaging and controlled atmosphere storage for fresh produce, where cost efficiency dominates over ultra-high-purity certification. Direct sales channels serve large processors while retail distributors handle smaller meat locker operations.
Technical barriers protect medical imaging margins; standardization pressures compress metal fabrication returns.
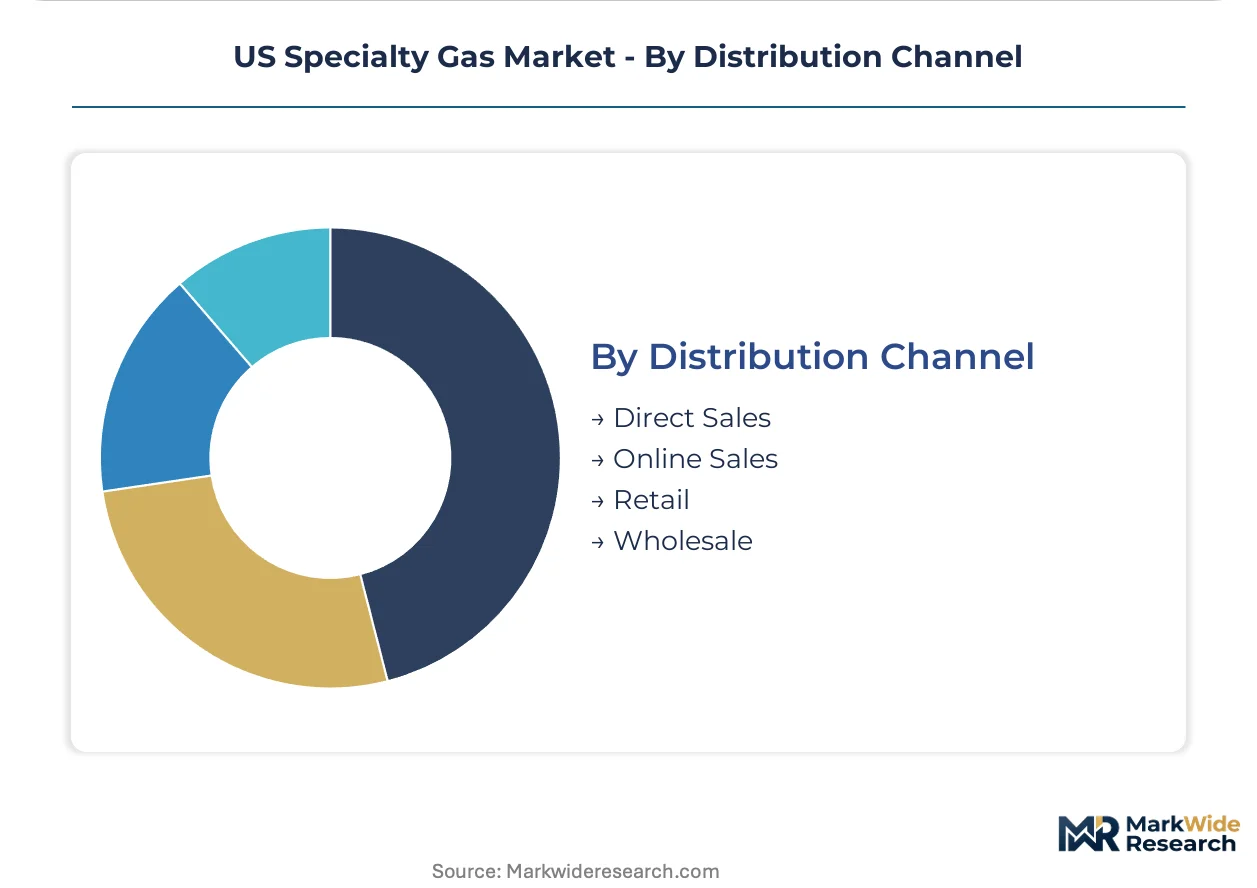
Distribution Channel:
Channel selection reflects order scale, delivery frequency, and technical service requirements.
- Direct Sales:Bulk liquid and on-site generation contracts with dedicated account engineering support, dominating semiconductor and refinery procurement. Long-term agreements now tie volume commitments to production schedules with minimum take obligations.
- Online Sales:E-procurement platforms for standardized cylinder sizes and predictable reorder cycles, gaining traction among mid-size research laboratories and contract manufacturers seeking transparent pricing.
- Retail:Local welding supply stores and gas distributors serving walk-in customers with packaged cylinders for maintenance welding and small fabrication jobs. This channel carries higher per-unit logistics costs and limited technical consultation depth.
- Wholesale:Regional distributors aggregating demand from fragmented metal fabrication and food processing customers, capturing economies in cylinder fleet management and route optimization.
Contract value concentrates in direct sales; digital penetration is expanding most quickly in online sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across US states diverge sharply: electronics manufacturing clusters in the Southwest pull ultra-high-purity helium and argon, while Gulf Coast refineries anchor industrial hydrogen demand through pipeline networks.
Southwest
Arizona and Texas semiconductor fabs drive concentrated demand for 99.9999% purity argon and helium in sub-7nm lithography steps. EPA Clean Air Act enforcement on fluorinated compound emissions mandates upgraded abatement systems at Phoenix and Austin fabrication sites. The TSMC and Intel construction corridors near Phoenix and Dallas-Fort Worth concentrate procurement power among tier-one foundries extracting multi-year take-or-pay supply terms.
Gulf Coast
Texas and Louisiana petrochemical complexes consume hydrogen volumes for hydrocracking and process heat decarbonization initiatives. OSHA permissible exposure limits for hazardous process gases require upgraded ventilation infrastructure at Beaumont and Port Arthur refineries. The Houston Ship Channel anchors industrial gas pipeline networks where on-site generation economics improve for mid-scale hydrogen consumers.
Pacific Northwest
Oregon and Washington semiconductor cleanrooms qualify ultra-high-purity gas purification systems for silicon epitaxy and etching applications. FDA medical-grade gas validation protocols govern helium supply for Seattle and Portland MRI magnet cooling operations. The Hillsboro silicon forest concentration enables Matheson Tri-Gas to anchor dedicated purification capacity for regional wafer fabs.
Midwest
Illinois, Michigan, and Ohio metal fabrication shops purchase argon-helium welding mixtures through wholesale distributors serving automotive stamping and aerospace machining. DOT hazardous materials regulations shape cylinder fleet logistics for Chicago and Detroit industrial gas routes. The Detroit-Windsor automotive corridor drives demand for high-flow bulk argon deliveries with on-site mixing capabilities.
Northeast
Massachusetts and New York pharmaceutical manufacturers require nitrogen for cryopreservation and controlled atmosphere processing. FDA oversight of medical-grade gases adds compliance documentation burdens for Boston and New York City regional hospital networks. The Cambridge biotech cluster concentrates specialty gas procurement among contract research organizations qualifying GMP-grade supply chains.
US Specialty Gas Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The US specialty gas market structures around three to four dominant integrated suppliers controlling bulk production and pipeline infrastructure, while mid-scale distributors compete on packaged gas logistics and regional service density. Strategic archetypes separate global gas majors with captive air separation assets from regional purification specialists and industrial distribution platforms. Competitive moves concentrate on long-term take-or-pay contract lockups with semiconductor fabs and helium recycling infrastructure investments serving MRI coolant闭环 recovery.
Among the integrated production tier, Air Products and Chemicals, Inc., Linde plc, and Air Liquide occupy positions defined by Gulf Coast hydrogen pipeline networks and Southwest on-site generation deployments. Air Products exemplifies the pipeline-anchored industrial supplier archetype through its Texas corridor infrastructure. Linde plc represents the on-site generation leader securing multi-year refinery and fab commitments. Air Liquide sits within the global gas major category with US-based air separation and electronics-grade purification capabilities.
| Leading Market Players |
|---|
| Air Liquide |
| Air Products and Chemicals, Inc. |
| Linde plc |
| Messer North America, Inc. |
| Matheson Tri-Gas, Inc. |
| Airgas USA, LLC |
| Norco, Inc. |
| TAIYO NIPPON SANSO CORPORATION |
| MESA Specialty Gases & Equipment |
| Others |
Pricing and Supply Chain Analysis
Federal Helium Reserve depletion risk determines both the spread between long-term contract and spot helium pricing and the geographic clustering of regional production hubs near Arizona and Texas semiconductor corridors. This single-source dependency forces buyers into minimum volume commitments while concentrating supplier pricing power around BLM pipeline access points.
Pricing Analysis
Long-term take-or-pay contracts dominate semiconductor and refinery procurement, with multi-year offtake agreements locking in argon and helium volumes against Federal Reserve auction volatility. Price differentiation rests on purity certification grade and dedicated logistics capacity, with 99.9999% semiconductor-grade helium commanding substantial premiums over industrial grades. Pricing pressure stems from helium allocation constraints tightening margins for MRI coolant customers. Spot-market buyers in metal fabrication exhibit highest price sensitivity; captive on-site generation customers show lowest sensitivity due to sunk capital commitments.
Supply Chain Analysis
Export-control restrictions on cryogenic equipment and purification technology limit US access to certain advanced membrane systems, compressing domestic supplier options for modular gas generation. Supply concentrates in the United States, Qatar, and Algeria for helium; the US, Russia, and China for argon production. Raw material dependencies include natural gas feedstocks for helium extraction, air separation units for noble gas recovery, and specialized alloys for cryogenic containment vessels. Single-source vulnerability runs through BLM pipeline infrastructure serving the Southwest. Distribution runs through dedicated bulk liquid tanker fleets for direct sales and wholesale cylinder networks for fragmented metal fabrication demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US specialty gas markets reward service-attach strategies where cylinder management, predictive maintenance, and helium recycling infrastructure expand recurring revenue faster than commoditized bulk gas sales. Aftermarket service layers now capture margin pools that hardware margins alone cannot sustain.
For Market Incumbents: Pre-empt helium recycling infrastructure deployment in Phoenix and Dallas-Fort Worth corridors before conservation mandates tighten. Lock in cryogenic engineering talent pipelines through vocational partnerships to defend against technician scarcity constraining expansion timelines. Backward integration into trailer-mounted PSA and membrane purification systems preserves margin capture from modular generation demand.
For New Entrants and Emerging Players: Establish a beachhead in DOT-certified cryogenic transport services for Texas and Arizona fabrication corridors where dedicated fleet gaps persist. Target mid-scale nitrogen consumers in Midwest metal fabrication with modular PSA systems that compress minimum efficient scale thresholds. Lead with transparent e-procurement platforms for research laboratories seeking price visibility on standardized cylinder sizes.
For Investors and Strategic Acquirers: EPA Clean Air Act enforcement on fluorinated compound emissions reshapes the acquisition landscape toward gas recovery and abatement technology providers. Long-term viability across the analysis window favors targets with captive helium recycling capabilities and semiconductor-grade purification certifications. Monitor BLM auction price volatility as the signal indicating supply allocation stress between healthcare and electronics priorities.
| Strategic Initiative | Industry Significance |
|---|---|
| Helium Recycling Infrastructure Deployment | Closed-loop recovery systems capture service revenue from MRI operators facing conservation mandates. |
| Modular Gas Generation Capacity Expansion | Trailer-mounted PSA units enable mid-scale fabs to justify on-site argon and nitrogen economics. |
| Long-term Supply Agreement with Semiconductor Fabs | Multi-year take-or-pay contracts with TSMC and Intel anchor volume commitments in Arizona. |
| Backward Integration into Purification Technology | In-house membrane and adsorption capabilities protect margin capture from hybrid system demand. |
| DOT Hazmat Transport Fleet Specialization | Cryogenic logistics certification gaps create defensible positioning in Southwest fabrication corridors. |
Research Methodology
Initial hypotheses were tested against primary input from gas procurement managers at wafer fabs, cryogenic logistics operators, MRI facility engineers, and refinery hydrogen supply coordinators and refined through secondary validation against BLM auction records, EPA enforcement actions, DOT hazardous materials incident reports, and SEC filings from integrated gas majors. Bottom-up demand modeling across end-use segments triangulated with top-down supply-side capacity assessments.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by gas type, purity grade tier, end-use industry, and regional production cluster. CAGRs were derived from elasticity-adjusted volume projections and price trajectory assumptions. Forecast inputs incorporated semiconductor fab construction timelines, helium reserve depletion curves, and OSHA regulatory amendment pipelines.
Sensitivities concentrate around BLM reserve auction outcomes, EPA enforcement intensity on fluorinated emissions, and cryogenic engineering labor availability. Forecasts reflect documented assumptions on substitution elasticities and regulatory implementation schedules. Material shifts in Federal Helium Reserve privatization policy or Clean Air Act amendment timing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Krypton-85 Market
Industrial Gases
Industrial Hydrogen Market
Industrial Gases
Global Sulfur Dioxide Market
Industrial Gases
Welding Shielding Gas Market
Industrial Gases
Oxygen Market
Industrial Gases
Low-Carbon Hydrogen Solutions for Industrial Cluster Decarbonization Market
Industrial Gases
North America Syngas Market
Industrial Gases
Metal Cutting Gas Market
Industrial Gases
Industrial Oxygen Market
Industrial Gases
Commercial Hydrogen Market
Industrial Gases
Neon Gas for Laser Market
Industrial Gases
Gas Sampling Line Market
Industrial Gases
South-East Asia (SEA) Syngas Market
Industrial Gases
Gas Purifiers Market
Industrial Gases
Global Syngas and Derivatives Market
Industrial Gases
Global Helium Gas Market