
 Noise and Vibration Coatings Market | 2026-2036
Noise and Vibration Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Noise and Vibration Coatings Market Outlook
Water-based polyurethane formulations is narrowing the performance gap with solvent-based alternatives in high-damping applications. Henkel leverages its adhesives heritage to anchor positions in automotive OEM specifications across Europe. BASF competes through captive resin supply and integrated formulation development. PPG Industries extends its aerospace coating expertise into vibration-damping layers for commercial aviation interiors.
Noise and vibration coatings are engineered material systems—typically 1–5 mm dry-film thickness—comprising viscoelastic polymers, fillers, and binders applied to substrates to convert mechanical energy into heat through hysteresis damping. Their primary industrial purpose is attenuating structure-borne sound and resonant vibration in transportation, building, and equipment applications. Spray coatings dominate volume in automotive underbody applications where robotic application speed matters, while barrier coatings command premium positioning in aerospace fuselage segments where mass reduction intersects with acoustic performance. Water-based formulations represent the fastest-expanding formulation category as OEM sustainability mandates tighten, though solvent-based epoxies retain share in heavy-equipment manufacturing where corrosion resistance and damping must coexist.
The US EPA regulates volatile organic compound emissions from coating operations under National Emission Standards for Hazardous Air Pollutants, directly shaping formulation roadmaps for suppliers serving North American automotive and industrial clients. REACH registration requirements and the EU F-Gas Regulation constrain chemical inputs and drive substitution toward lower-emission binder systems across European supply chains. Stakeholders must monitor evolving OEM sustainability scorecards and anticipate which formulation platforms will qualify under pending regulatory thresholds.
Market Dynamics
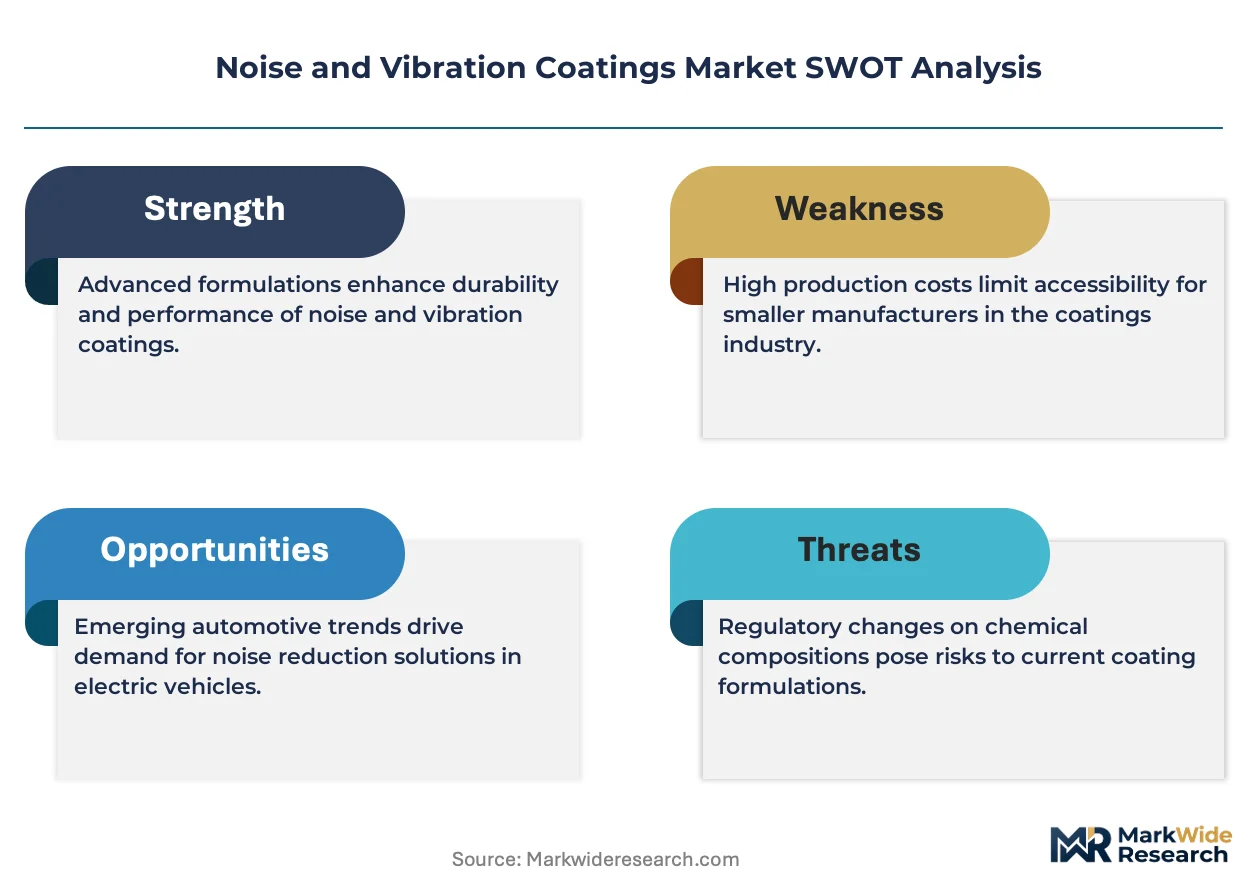
Automotive OEMs are consolidating damping specifications across electric vehicle architectures, forcing coating suppliers to revalidate formulations for battery tray resonance management and motor housing acoustic isolation simultaneously.
Growth Catalysts
- EU Green Deal mandates:REACH restrictions on solvent-based binders are accelerating water-based polyurethane qualification cycles at German and French automotive plants.
- EV platform standardization:Shared battery-electric skateboard architectures are multiplying addressable surface area for spray-applied damping materials per vehicle.
- Stuttgart-Wolfsburg corridor concentration:Proximity of Porsche, Mercedes-Benz, and Volkswagen engineering centers enables rapid specification feedback loops for coating developers.
Market Restraints
- Petrochemical feedstock volatility:Isocyanate and polyol price swings compress formulation margins unpredictably.
- Application equipment oligopoly:Robotic spray system supply concentrates among two German automation suppliers, creating capex bottlenecks for tier-2 coating applicators.
- Cure time limitations:Water-based systems require 40% longer oven dwell than solvent alternatives, constraining high-volume assembly line throughput.
Strategic Opportunities
- India PLI scheme for automotive:Localized damping material production for Maruti Suzuki and Tata Motors EV platforms bypasses import duty exposure.
- Aerospace interior retrofit:Post-pandemic cabin refurbishment cycles are opening specification windows for lightweight vibration-damping layers in narrow-body fleets.
- Construction equipment electrification:Battery-powered excavators and loaders require novel damping approaches for reduced noise signature in urban job sites.
Industry Challenges
- Formulation chemist scarcity:Viscoelastic polymer expertise concentrates among retiring specialists at German and Japanese coating houses.
- OEM sustainability scorecard divergence:Volkswagen, BMW, and Stellantis employ incompatible carbon-accounting methodologies, forcing redundant certification investments.
- Legacy paint line incompatibility:Existing cathodic electrocoat ovens lack temperature precision for optimal water-based damping film formation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Noise and Vibration Coatings Market |
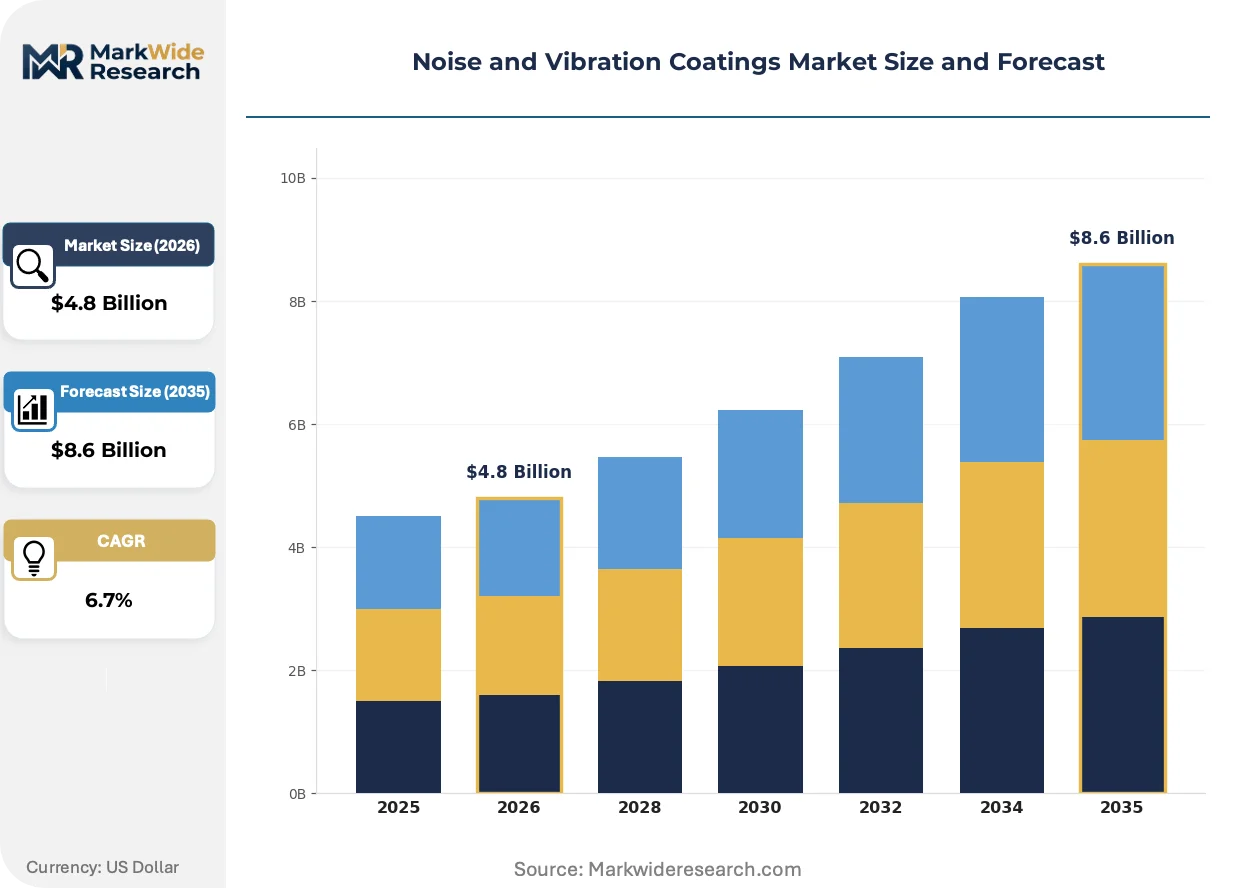
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray Coatings, Damping Compounds, Barrier Coatings, Sealants Application: Automotive, Aerospace, Construction, Electronics End User: OEMs, Tier-1 Suppliers, Contractors, Manufacturers Formulation: Water-Based, Solvent-Based, Polyurethane, Epoxy |
| Companies Covered | Henkel, 3M, BASF, PPG Industries, Dow, Mascoat, LORD Corporation, Daubert Chemical Company, Sika, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Noise and Vibration Coatings Market Strategic Shifts
Formulation chemistry and application methodology are converging to resolve the historical trade-off between acoustic performance and manufacturing velocity. Suppliers are repositioning around integrated material-system offerings rather than commodity resin supply.
Magnetorheological damping compounds embedded in sprayable polymer matrices is collapsing the distinction between passive and semi-active vibration control in automotive subframes. Tier-1 suppliers in Germany are piloting these materials for adaptive suspension mounting points. The technology is compressing the addressable market for conventional fixed-damping coatings in premium vehicle segments.
REACH authorization requirements for diisocyanates are forcing reformulation roadmaps across European supply chains. Coating manufacturers must complete substance dossier updates by 2025 deadlines or exit industrial adhesive and damping categories. Water-based aliphatic polyurethane alternatives are capturing specification share in German automotive OEM trials despite 15% higher unit material cost.
Airframe manufacturers are unbundling acoustic performance from structural composites, creating discrete procurement categories for applied damping layers. Boeing and Airbus engineering teams now specify vibration coatings separately from prepreg systems, enabling specialist suppliers to bypass incumbent composite houses. This pattern is most pronounced in narrow-body programs where aftermarket cabin reconfiguration cycles accelerate.
Noise and Vibration Coatings Market Segmentation
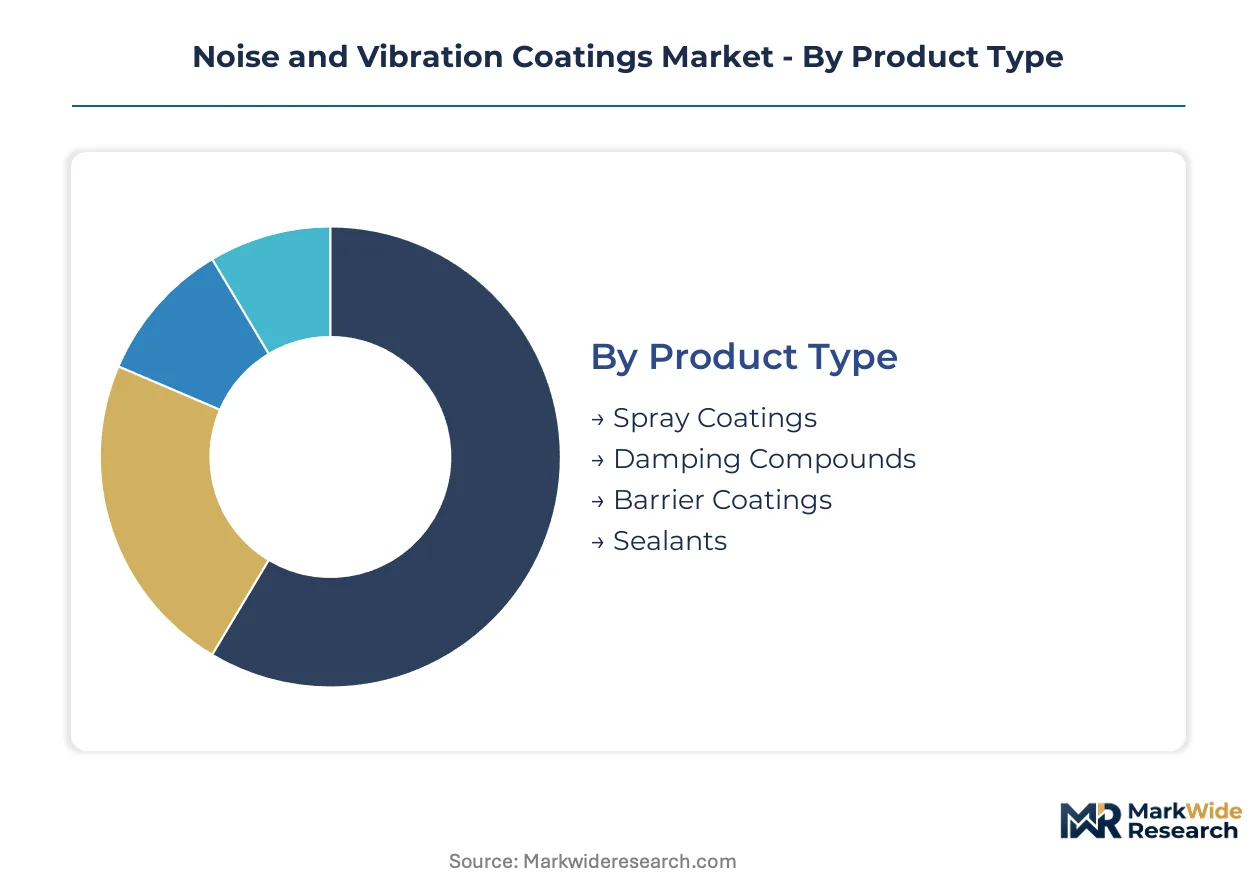
Noise and vibration coatings serve heterogeneous industrial workflows where specification requirements diverge sharply between robotic automotive lines and hand-applied construction sites. Segmentation reveals how formulation chemistry and application methodology must align with customer technical capabilities and regulatory exposure. Understanding these divides exposes where margin concentrates versus where volume commoditizes.
Product Type:
After-sales service intensity varies dramatically across product categories, with spray coatings demanding continuous equipment calibration support while barrier coatings require specification engineering consultation through installation.
- Spray Coatings:Viscoelastic polymer systems applied through robotic or manual spray equipment at 1–3 mm thickness, optimized for high-speed automotive underbody coverage. Demand clusters at Volkswagen Group and Mercedes-Benz EV platforms in Germany where throughput requirements exceed 60 vehicles per hour. Cure time constraints with water-based variants create bottlenecks requiring oven retrofit consultation.
- Barrier Coatings:Dense, mass-loaded polymer films engineered for airborne sound blocking in aerospace fuselage and architectural assemblies. Boeing and Airbus narrow-body programs in France and Germany specify these as discrete procurement categories separate from structural composites. Mass reduction imperatives drive qualification of lighter filler technologies.
- Damping Compounds:Paste-grade materials applied through extrusion or troweling to irregular substrates. Construction equipment OEMs in Japan employ these for battery-electric excavator housings where robotic spray access is limited.
- Sealants:Dual-function formulations combining acoustic damping with environmental sealing. Electronics manufacturers in South Korea specify these for server rack vibration isolation where dust ingress protection is co-required.
Spray coatings hold the largest share; momentum sits with barrier coatings as aerospace procurement unbundles acoustic performance from structural composites.
Application:
Cost tier differentiation separates premium specification environments where qualification cycles span years from commodity procurement where price dominates.
- Automotive:The dominant volume application spanning passenger EV battery trays, motor housings, and body-in-white damping. Shared skateboard architectures at Porsche, Mercedes-Benz, and Volkswagen multiply addressable surface area per vehicle. REACH-driven solvent restrictions are accelerating water-based polyurethane validation timelines.
- Aerospace:Cabin interior retrofit cycles and new narrow-body programs create specification windows. Boeing and Airbus engineering teams now source vibration-damping layers independently from prepreg suppliers. Mass reduction intersects with acoustic performance requirements.
- Construction:Building HVAC systems and architectural assemblies employ barrier-grade materials. Urban noise ordinances in France and Germany drive specification for high-rise residential mechanical rooms.
- Electronics:Server farms and precision manufacturing equipment require micro-vibration isolation. Data center expansion in Ireland and Netherlands concentrates demand for compact damping solutions.
Automotive dominates volume contribution; aerospace delivers the steepest expansion trajectory as aftermarket refurbishment accelerates.
End User:
Customer type determines whether procurement emphasizes formulation customization or logistics reliability and price stability.
- OEMs:Direct automotive and aerospace manufacturer relationships involving multi-year qualification cycles and sustainability scorecard compliance. Volkswagen, BMW, and Stellantis employ incompatible carbon-accounting methodologies forcing redundant certification investments.
- Tier-1 Suppliers:Seating, interior, and structural component specialists integrating damping materials into sub-assemblies. Robotic spray system supply concentration among two German automation suppliers creates capex coordination challenges.
- Contractors:Construction and industrial installation specialists procuring barrier and sealant grades through distribution. Application training and on-site technical support differentiate supplier relationships.
- Manufacturers:Diverse industrial equipment producers with fragmented, specification-driven procurement. Electronics and machinery OEMs in Japan and South Korea concentrate demand for precision damping grades.
OEMs command the largest specification influence; Tier-1 suppliers are gaining procurement autonomy as platform standardization progresses.
Formulation:
Supply concentration in petrochemical feedstocks creates margin volatility that formulation selection partially mitigates through chemistry flexibility.
- Water-Based:Polyurethane dispersions meeting EU Green Deal and REACH solvent restrictions. German automotive trials accept 15% material cost premiums for qualification. Forty percent longer oven dwell versus solvent alternatives constrains high-volume throughput.
- Solvent-Based:Epoxy and polyurethane systems retaining share in heavy equipment where corrosion resistance and damping must coexist. EPA NESHAP regulations in the US and REACH restrictions in Europe are compressing addressable applications.
- Polyurethane:The dominant polymer chemistry spanning both water and solvent carrier systems. Isocyanate and polyol price swings compress margins unpredictably across all carrier variants.
- Epoxy:Rigid, chemically resistant formulations specified where substrate protection equals damping priority. Construction equipment and industrial machinery applications in Japan favor these for outdoor exposure durability.
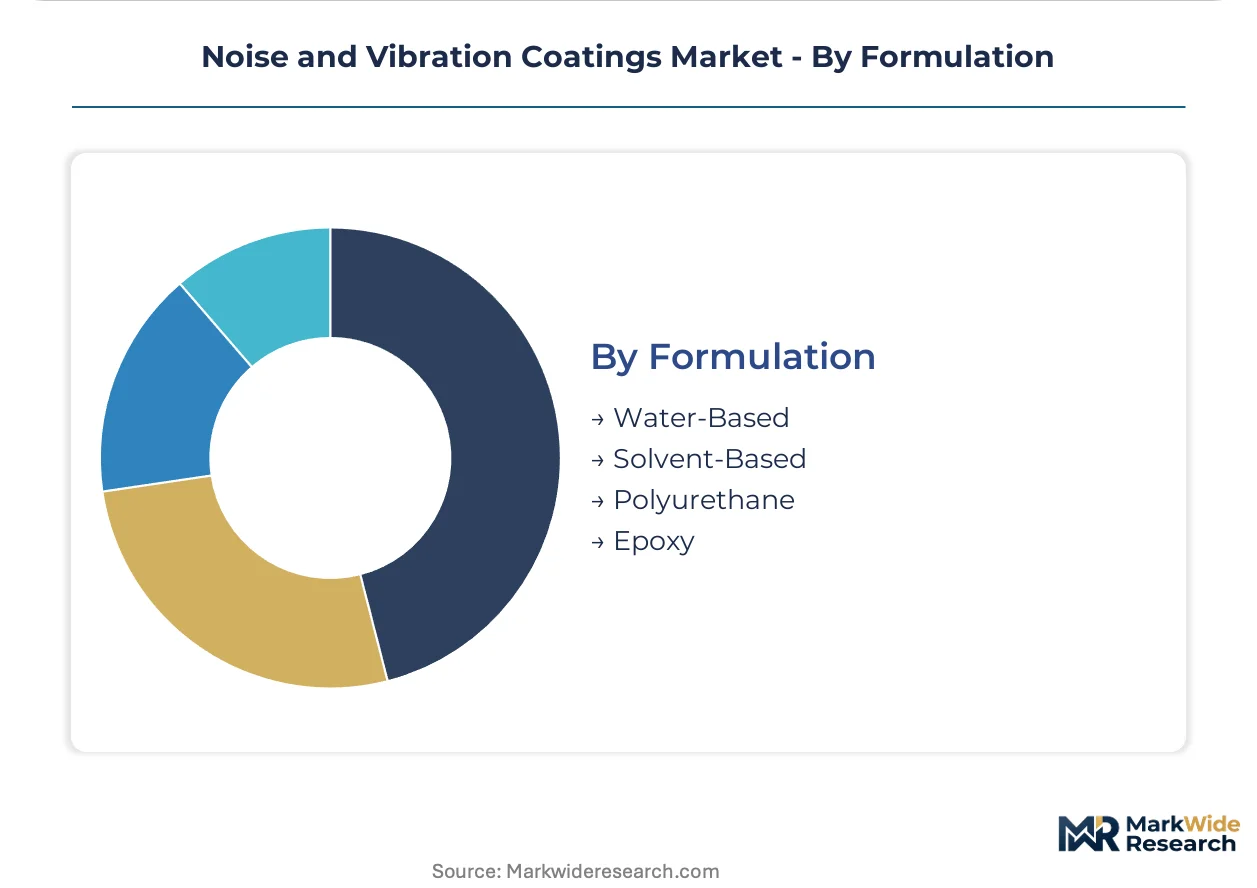
Solvent-based formulations retain the largest installed base; water-based alternatives are climbing the fastest as regulatory deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in noise and vibration coatings track automotive production corridors, with Germany and the United States running structural surpluses in formulated systems while China and India remain net importers of specialty resin intermediates. Formulation chemistry expertise concentrates in Western European and North American coating houses.
Germany
Stuttgart and Wolfsburg automotive clusters drive specification authority for EV battery tray damping materials. REACH diisocyanate authorization deadlines are compressing qualification timelines for water-based polyurethane alternatives. Henkel and BASF anchor formulation development within the Baden-Württemberg and North Rhine-Westphalia industrial corridors.
United States
EPA NESHAP regulations on volatile organic compound emissions shape formulation roadmaps for automotive OEM supply chains. Michigan and Ohio-based production facilities serve Detroit Three electrification programs. Dow maintains integrated resin-to-coating operations along the Gulf Coast petrochemical corridor.
China
Dual carbon goals and MIIT automotive emission standards are accelerating solvent-based system phase-outs in passenger vehicle manufacturing. Yangtze River Delta coating applicators face feedstock cost volatility from imported isocyanate supply. Local formulation houses are qualifying water-based alternatives for BYD and NIO platforms.
Japan
METI energy efficiency mandates for industrial equipment are expanding damping material specifications in construction machinery electrification. Kansai region coating specialists serve Komatsu and Kubota battery-electric excavator programs. JIS standards for vibration control materials exceed baseline ISO requirements.
India
PLI scheme incentives for automotive manufacturing are localizing damping material production for Maruti Suzuki and Tata Motors EV platforms. Tamil Nadu and Gujarat assembly plants bypass import duty exposure through domestic formulation partnerships. BIS certification requirements for automotive coatings are tightening specification compliance.
Noise and Vibration Coatings Market Competitive Environment
On the supply side, the industry is consolidating around integrated material-system providers rather than commodity resin suppliers. Three strategic archetypes dominate: diversified chemical conglomerates with captive polymer supply, specialized coating houses with OEM specification heritage, and adhesive specialists extending into vibration control. Competitive moves center on formulation qualification speed for EV platform mandates and geographic expansion into India PLI-subsidized production zones.
Among diversified chemical conglomerates, BASF and Dow exemplify the integrated archetype through captive isocyanate and polyol production. Henkel represents the specification-anchored specialist model, leveraging adhesives heritage to secure automotive OEM damping material approvals. PPG Industries occupies a position bridging aerospace coating expertise with emerging vibration-damping layer specifications for commercial aviation interiors.
| Leading Market Players |
|---|
| Henkel |
| 3M |
| BASF |
| PPG Industries |
| Dow |
| Mascoat |
| LORD Corporation |
| Daubert Chemical Company |
| Sika |
| Others |
Value Chain & Pricing Dynamics
Stuttgart's automotive coating cluster concentrates water-based polyurethane formulation capacity, and its proximity to Porsche and Mercedes-Benz engineering centers translates into specification leverage that buffers margin compression elsewhere. German suppliers command premium positioning through REACH-compliant qualification heritage while tier-2 applicators in Eastern Europe absorb pricing pressure from feedstock volatility.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in this market. Price differentiation hinges on REACH certification status and volume scale, with qualified water-based formulations commanding 15% material cost premiums over solvent alternatives. Cost compression in standard-grade solvent systems is intensifying because of isocyanate price swings and overlapping EPA NESHAP compliance investments. Tier-1 automotive suppliers exhibit the highest price sensitivity due to OEM sustainability scorecard pressures, while aerospace procurement teams prioritize mass reduction performance over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced polymer synthesis equipment limit technology transfer to emerging formulation houses in Asia. Supply concentrates in Germany, the United States, and Japan, with captive isocyanate production at BASF and Dow anchoring Western supply security. Raw material flows draw from imported polyol streams and domestic filler mineral deposits. Single-source vulnerability concentrates in robotic spray system supply, where two German automation suppliers control tier-1 applicator equipment. Distribution runs through direct OEM specification channels for automotive and aerospace, with construction and electronics segments served through specialized chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shared EV skateboard architectures are transforming damping materials from discrete components into platform-integrated subsystems, creating winner-take-most dynamics around specification lock-in. Interoperability between battery tray resonance management and motor housing acoustic isolation is collapsing procurement silos.
For Market Incumbents: Build specification moats through accelerated water-based polyurethane qualification cycles at German and French automotive plants. Deepen captive resin supply integration to buffer isocyanate price volatility, while investing in oven retrofit consultation services to address legacy paint line incompatibility. Magnetorheological damping compounds threaten conventional fixed-damping coatings in premium vehicle segments. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized automotive manufacturing zones, where localized production for Maruti Suzuki and Tata Motors EV platforms bypasses import duty exposure. Aerospace interior retrofit cycles for narrow-body fleets present the most penetrable specification window, with cabin refurbishment procurement unbundled from incumbent composite houses. Target go-to-market partnerships with Tamil Nadu and Gujarat assembly plant technical teams. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance compounder play because REACH authorization deadlines and EPA NESHAP phase-outs are structurally advantaging qualified formulation houses over commodity resin suppliers. Acquisition targets should display integrated material-system capabilities spanning resin synthesis to application equipment calibration. The signal to watch is OEM sustainability scorecard convergence versus continued divergence between Volkswagen, BMW, and Stellantis carbon-accounting methodologies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Supply | BASF and Dow's captive resin production buffers margin compression from petrochemical feedstock volatility. |
| Water-Based Formulation Qualification Acceleration | Henkel leverages adhesives heritage to secure automotive OEM approvals ahead of REACH diisocyanate deadlines. |
| Aerospace Interior Retrofit Specification Capture | PPG Industries extends coating expertise into Boeing and Airbus narrow-body cabin refurbishment procurement. |
| India PLI Zone Manufacturing Localization | Domestic formulation partnerships for Tata Motors and Maruti Suzuki EV platforms bypass BIS certification delays. |
| Magnetorheological Damping Compound Piloting | German tier-1 suppliers test adaptive suspension mounting materials that compress conventional coating addressable markets. |
Study Parameters
Cross-validation between primary interviews with automotive platform engineers, coating formulation chemists, and tier-1 supplier procurement leads anchors the qualitative findings. Secondary sources include customs and trade data from German and US chemical exports, SEC filings from diversified coating conglomerates, and REACH substance dossier updates from ECHA. Bottom-up demand modeling triangulates against top-down production forecasts from vehicle manufacturing databases.
Calibration against historical qualification cycle timelines and regulatory deadline impacts refines projection accuracy across the modeling period. Segmentation dimensions include product type, application vertical, end-user procurement archetype, and formulation chemistry platform. CAGRs derive from rolling average growth rate analysis applied to EV platform rollout schedules and aerospace retrofit cycle frequencies. Key inputs capture battery-electric vehicle content-per-vehicle expansion and water-based system penetration rates.
Sensitivities concentrate around REACH authorization timeline enforcement and EPA NESHAP implementation stringency. Forecasts reflect assumptions about OEM sustainability scorecard stability and robotic spray equipment supply availability. Material shifts in diisocyanate regulatory classification or EV platform architecture standardization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Textile Coatings Market
Coatings
Australia Industrial Coatings Market
Coatings
Intumescent Fire Retardant Coating Market
Coatings
Global Performance Coating Market
Coatings
Global Mirror Coatings Market
Coatings
Epoxy Powder Coatings Market
Coatings
Global Battery Coating Market
Coatings
Global Smart Coating Market
Coatings
Marine Nanocoating Market
Coatings
Automotive Refinish Coatings Market
Coatings
Gelcoat Market
Coatings
Rail Coatings Market
Coatings
US Concrete Floor Coatings Market
Coatings
Bio-Fouling Prevention Coatings Market
Coatings
Middle East and Africa Super Hydrophobic Coatings Market
Coatings
Antifouling Coatings Market