
 Canada Industrial Wood Coatings Market | 2026-2036
Canada Industrial Wood Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Industrial Wood Coatings Market Outlook
Multi-source procurement among large Canadian furniture makers is consolidating toward fewer coating suppliers with full technical-service capabilities. PPG Canada Inc. leverages its automotive-refinish heritage to transfer weathering and scratch-resistance technology into industrial wood applications. Sherwin-Williams Canada Inc. anchors its position through an extensive distribution network that reaches secondary manufacturing centers across Quebec and British Columbia. Akzo Nobel Canada Inc. differentiates via water-based formulation leadership aligned with federal environmental compliance timelines.
Canada industrial wood coatings are liquid or solid film-forming systems applied to timber, engineered wood, and composite substrates to provide moisture resistance, UV stability, and aesthetic finish; formulations typically incorporate binders such as acrylic or polyurethane resins at solids contents ranging from 20% to 45% depending on technology. Their primary industrial purpose is to extend service life and enable color consistency across high-volume furniture, cabinet, and flooring production lines. Polyurethane coatings command the deepest margin pools in flooring applications where abrasion resistance carries premium pricing, while water-based technology represents the fastest-growing segment as Ontario and Quebec manufacturers retrofit spray lines to meet volatile organic compound restrictions. Acrylic formulations sustain steady share in furniture finishing where clarity and color retention outweigh extreme durability requirements.
Health Canada governs allowable VOC content through the Canadian Environmental Protection Act, while the Canadian General Standards Board maintains performance benchmarks for coating adhesion and weathering that influence provincial procurement specifications. The SCAQMD-equivalent standards emerging in Ontario and British Columbia are forcing solvent-based product lines toward reformulation or regional phase-out. Buyers and formulators must track how provincial carbon-pricing mechanisms and federal clean-fuel regulations reshape the operating cost structure of coating production and application facilities.
Market Dynamics
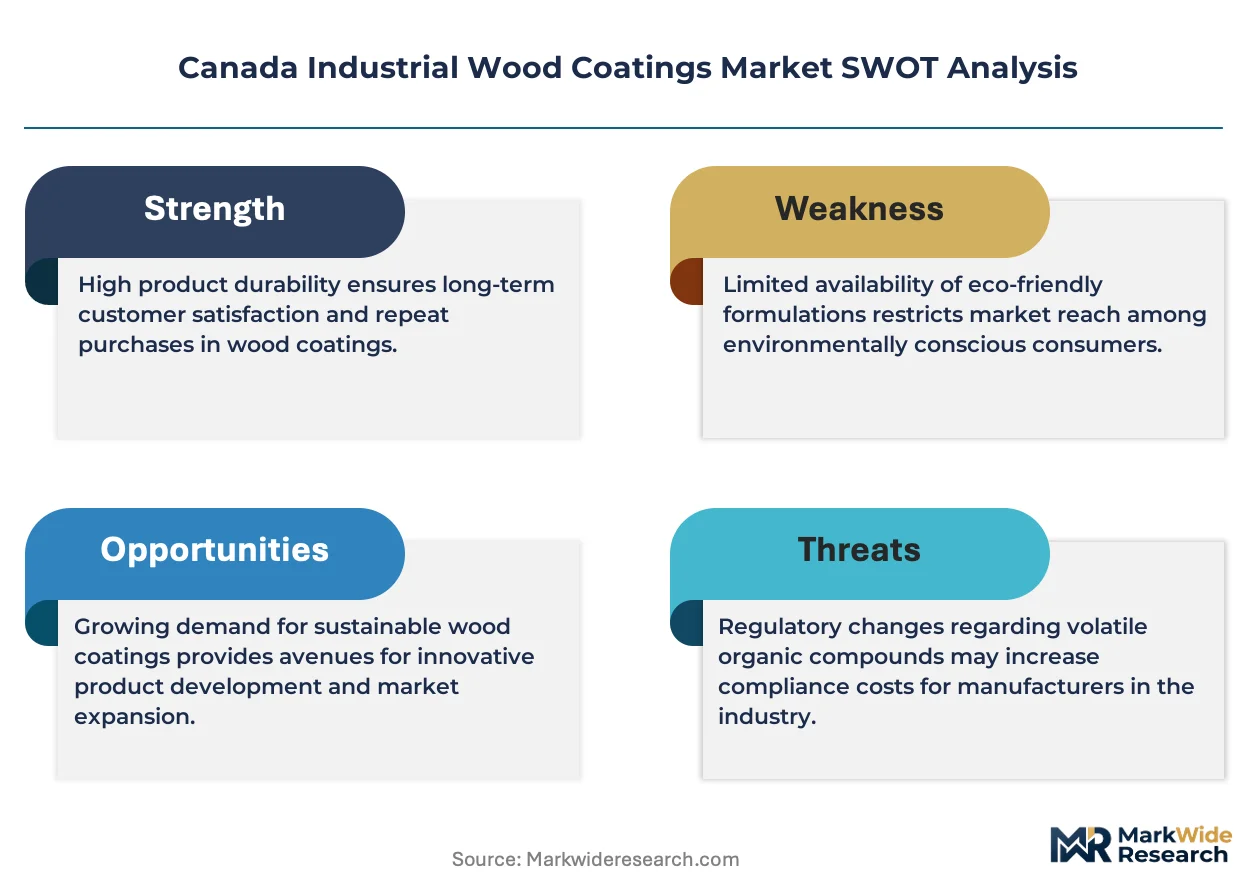
Health Canada's tightening VOC emissions standards under the Canadian Environmental Protection Act are forcing Ontario and Quebec manufacturers to accelerate spray-line retrofits, consolidating procurement toward suppliers with proven water-based formulation expertise and on-site technical service capabilities.
Growth Catalysts
- Ontario cabinet cluster demand:Concentrated millwork and furniture production in the Toronto-Waterloo corridor generates volume procurement contracts that reward coating suppliers with localized inventory and same-day technical response.
- Carbon pricing mechanisms:Federal and provincial carbon-cost structures raise the operating expense of solvent-based coating application, accelerating buyer migration toward low-VOC water-based alternatives that reduce compliance burdens.
- UV-curable technology maturation:Energy-cured coatings are penetrating flooring and high-throughput furniture lines where instant hardness and reduced drying footprint offset higher equipment capital requirements.
Market Restraints
- Petrochemical resin volatility:Acrylic and polyurethane binder costs fluctuate with propylene and isocyanate feedstock pricing, compressing margin predictability for formulators serving price-locked annual contracts.
- Quebec supply concentration:Specialty additive and crosslinker production clusters in Greater Montreal create geographic single-point vulnerability for western Canadian coating blenders.
- Solvent-based phase-out friction:Health Canada's accelerated VOC reduction timelines force premature equipment obsolescence among smaller Ontario furniture shops lacking capital for spray-booth replacement.
Strategic Opportunities
- British Columbia mass timber integration:Cross-laminated timber and glulam construction growth in Vancouver and Kelowna creates specification-grade coating demand for fire-retardant and exterior-durable finishes.
- Health Canada clean-fuel alignment:Federal regulations linking industrial energy use to carbon intensity scoring reward coating applicators adopting electrically cured or infrared-dried process technologies.
- Digital color-matching platforms:Cloud-based spectrophotometry and predictive formulation software are enabling remote color development, reducing sample-cycle time for Alberta and Saskatchewan distributors serving dispersed secondary markets.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in water-based polyurethane dispersion stability and additive synergy is concentrating among senior technical staff at established suppliers, constraining new entrant R&D velocity.
- Legacy booth incompatibility:Existing solvent-optimized spray environments in older Quebec furniture plants require costly humidity-control and flash-off modifications to handle extended water-based drying cycles without defect rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Industrial Wood Coatings Market |
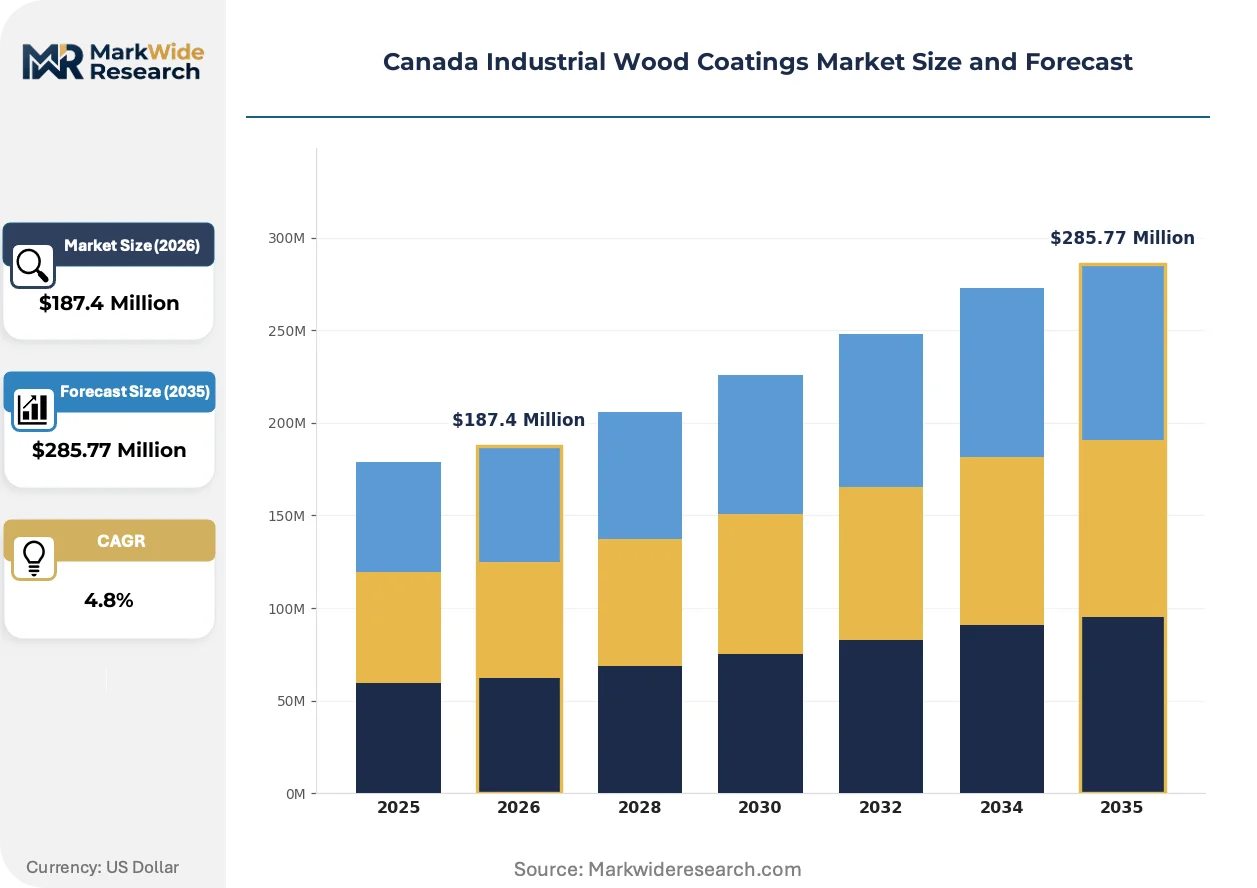
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Lacquer, Polyurethane, Stains Application: Furniture, Cabinets, Floors, Doors End User: Manufacturers, Distributors, Retailers, Contractors Technology: Water-Based, Solvent-Based, UV-Cured, Electrostatic |
| Companies Covered | Akzo Nobel Canada Inc., PPG Canada Inc., Sherwin-Williams Canada Inc., Axalta Coating Systems Canada Company, Benjamin Moore & Co. Ltd., Cloverdale Paint Inc., Hempel (Canada) Inc., General Paint Corporation, Nippon Paint (Canada) Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Industrial Wood Coatings Market Strategic Shifts
Formulation chemistry and application technology are converging around environmental compliance mandates, with Canadian manufacturers prioritizing process efficiency gains that offset the performance premiums historically associated with low-emission coating systems.
Water-based polyurethane dispersions are expanding into flooring and high-wear furniture segments previously dominated by solvent-borne two-component systems. Ontario hardwood flooring producers are adopting these formulations at accelerating rates as scratch-resistance and chemical-stain performance gaps narrow. The technology is expanding into premium specification tiers where environmental certification requirements now outweigh absolute durability benchmarks in buyer decision frameworks.
Health Canada's VOC concentration limits under the Canadian Environmental Protection Act are tightening on five-year review cycles, with draft amendments targeting architectural and industrial maintenance coatings. This regulatory compression is forcing reformulation investments across Quebec and Ontario manufacturing bases. Water-based product lines are capturing share fastest in cabinet and millwork segments where finish clarity and color-matching precision are primary purchase criteria.
Buyer concentration among large Canadian furniture OEMs is compressing supplier rosters toward integrated coating-and-service providers. Ontario's manufacturing corridor is witnessing procurement consolidation as technical-service responsiveness and inventory proximity outweigh pure price competition. British Columbia buyers are extending this pattern, demanding predictive maintenance support and color-lab access as standard contract inclusions rather than premium add-ons.
Canada Industrial Wood Coatings Market Segmentation
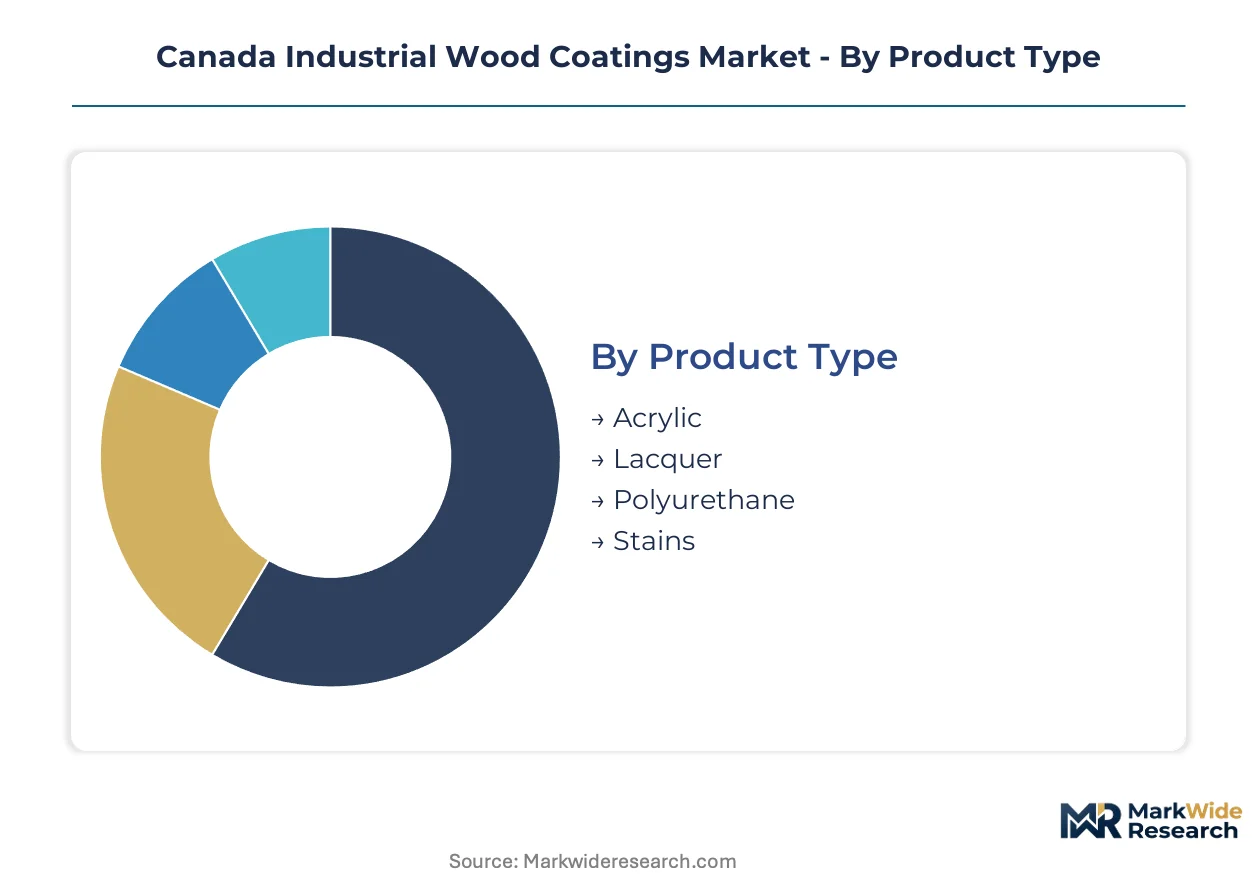
Canadian industrial wood coatings segmentation reveals how formulation chemistry, application environment, and regulatory pressure intersect to reshape procurement patterns across Ontario's manufacturing corridor and British Columbia's emerging mass timber sector. Understanding these divides clarifies where technical service capabilities and compliance-ready product lines command premium positioning.
Product Type:
Customization intensity spans from commodity stains requiring minimal technical support to engineered polyurethane systems demanding formulation partnerships and on-site troubleshooting.
- Polyurethane:Two-component and water-based dispersions deliver superior abrasion resistance and chemical stability for flooring and high-traffic furniture applications. Ontario hardwood flooring producers concentrate procurement here as scratch-performance gaps against solvent-borne alternatives narrow under Health Canada VOC pressure.
- Acrylic:Thermoplastic emulsions provide clarity, color retention, and UV stability for premium furniture and decorative millwork where aesthetic consistency outweighs extreme durability requirements. Quebec cabinet manufacturers favor acrylics for their forgiving application windows and rapid color-matching turnaround.
- Lacquer:Nitrocellulose and CAB-acrylic variants dominate fast-turn furniture repair and refinishing segments.
- Stains:Pigment and dye concentrates serve as penetration colorants for raw wood preparation prior to topcoat sealing.
Leading the category by volume: Polyurethane. Growing fastest: Water-based polyurethane dispersions.
Application:
Volume concentration tracks Ontario's manufacturing geography, with finish durability requirements and environmental exposure severity determining margin structure.
- Furniture:Residential and contract seating, case goods, and hospitality fixtures demand balanced aesthetics and moderate wear resistance. Toronto-Waterloo corridor OEMs drive specification-grade volume, prioritizing suppliers with localized inventory and same-day technical response.
- Floors:Residential and commercial hardwood, engineered, and resilient flooring substrates require maximum abrasion resistance and chemical stain protection. Polyurethane systems capture value here through performance premiums that offset higher material costs.
- Cabinets:Kitchen, bath, and built-in millwork applications emphasize moisture resistance, color consistency, and repairability.
- Doors:Interior and exterior architectural entry systems balance dimensional stability with weathering performance.
Flooring commands the steepest performance premiums. Furniture generates the highest absolute volume.
End User:
Procurement sophistication escalates from spot-buying contractors to integrated manufacturers with predictive demand planning and vendor-managed inventory arrangements.
- Manufacturers:Large-scale furniture, cabinet, and flooring producers with dedicated finishing lines and specification authority. Ontario and Quebec OEMs are consolidating supplier rosters toward full-service coating providers offering on-site technical support and color-lab access.
- Distributors:Regional coating and industrial supply intermediaries serving secondary manufacturing centers across Alberta, Saskatchewan, and Atlantic Canada.
- Retailers:Big-box and specialty channel players stocking consumer-directed refinishing and touch-up products.
- Contractors:Installation and refinishing specialists purchasing on a project-specific basis with limited formulation technical requirements.
Manufacturer direct procurement captures the deepest margin pools. Distributor channels show the steepest expansion trajectory in western provinces.
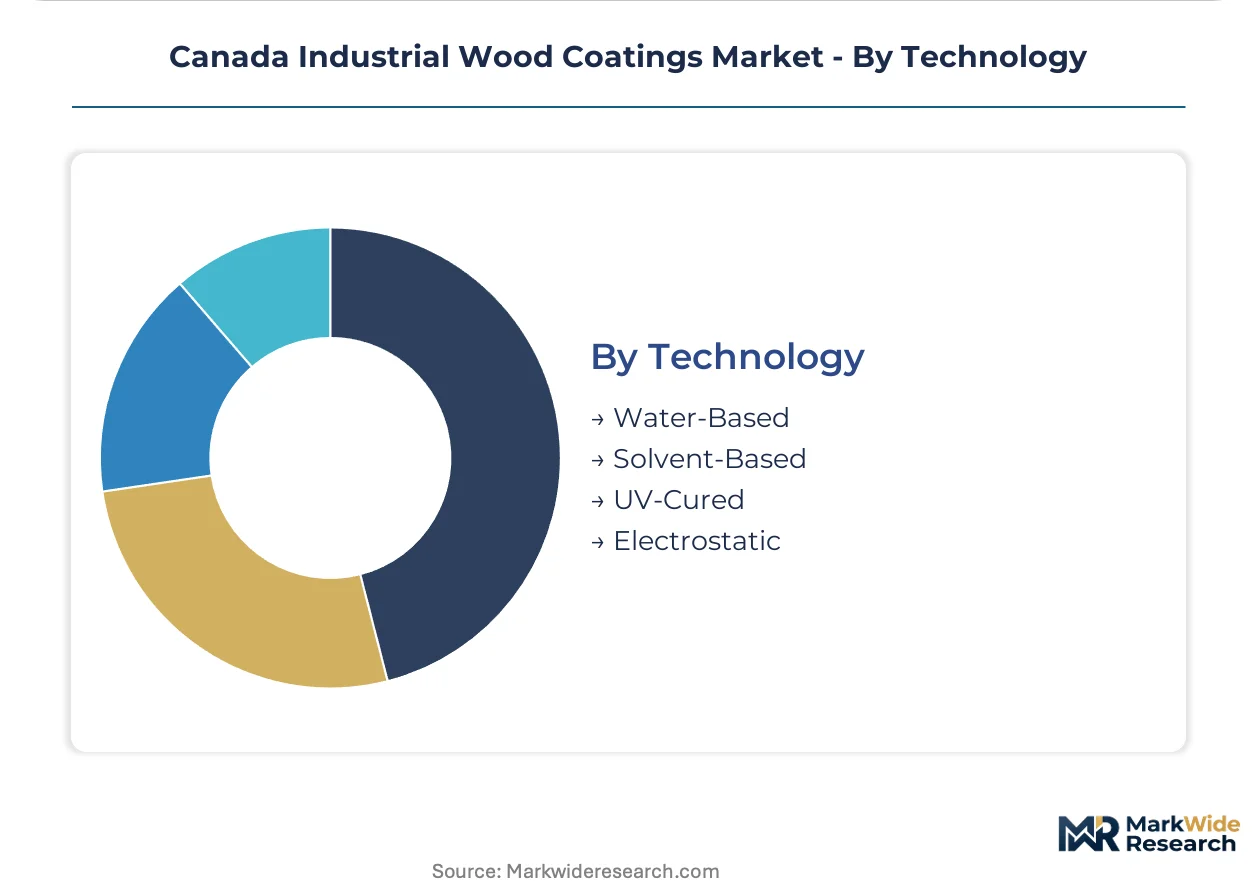
Technology:
Environmental compliance timelines and capital equipment requirements segment adopters by facility age, scale, and geographic regulatory intensity.
- Water-Based:Acrylic and polyurethane dispersions with VOC content below Health Canada limits under the Canadian Environmental Protection Act. Ontario and Quebec manufacturers retrofitting spray lines drive fastest adoption as SCAQMD-equivalent standards emerge provincially.
- Solvent-Based:Traditional alkyd, nitrocellulose, and two-component polyurethane systems facing phased reduction timelines. Legacy equipment in older Quebec furniture plants creates conversion friction due to humidity-control and flash-off modification costs.
- UV-Cured:Energy-cured acrylate oligomers delivering instant hardness and reduced drying footprint for high-throughput flooring and flat-stock furniture lines.
- Electrostatic:Charged particle application systems for complex three-dimensional components with wrap-around efficiency.
Water-based systems lead by new installation volume. UV-cured technology shows the steepest growth rate in greenfield flooring capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's petrochemical feedstock corridor anchors Canadian coating resin production, with propylene and isocyanate supply chains feeding formulation facilities across the Toronto-Waterloo manufacturing belt.
Ontario
Toronto-Waterloo cabinet and millwork clusters drive volume procurement for water-based polyurethane systems. Health Canada's Canadian Environmental Protection Act enforcement pressures manufacturers toward low-VOC retrofit investments. Guelph and Kitchener finishing facilities are consolidating supplier rosters toward full-service providers with localized technical support teams.
Quebec
Montreal-area specialty additive production concentrates crosslinker supply for eastern Canadian blenders. Provincial carbon-pricing mechanisms raise solvent-based application costs and accelerate buyer migration to compliant alternatives. Greater Montreal furniture plants face legacy booth incompatibility challenges requiring humidity-control modifications for water-based conversion.
British Columbia
Vancouver and Kelowna mass timber construction expands specification-grade demand for fire-retardant and exterior-durable finishes. Emerging SCAQMD-equivalent standards in the province force reformulation timelines for imported solvent-based product lines. Cross-laminated timber fabricators in the Lower Mainland are specifying coating systems with predictive maintenance support as standard contract terms.
Alberta
Calgary and Edmonton distributors serve dispersed secondary manufacturing centers across the Prairie Provinces with digital color-matching platforms. Federal clean-fuel regulations linking industrial energy use to carbon intensity scoring reward electrically cured process adoption. Alberta furniture and fixture producers are leveraging cloud-based spectrophotometry to reduce sample-cycle times for remote specification development.
Canada Industrial Wood Coatings Market Competitive Environment
Consolidation among full-service coating suppliers dominates the current landscape as technical-service capabilities and inventory proximity outweigh pure price competition. The vendor base concentrates around integrated providers with formulation expertise and on-site support infrastructure. Three strategic archetypes occupy distinct positions: multinational chemical conglomerates with automotive heritage transfers, dedicated coating specialists with water-based leadership, and regional distributors with digital platform investments. M&A activity and capacity expansion for low-VOC production lines represent the dominant competitive moves reshaping supplier rosters.
Within the multinational tier, Akzo Nobel Canada Inc., PPG Canada Inc., and Sherwin-Williams Canada Inc. exemplify integrated coating-and-service providers. Akzo Nobel Canada Inc. occupies a position aligned with federal environmental compliance timelines through water-based formulation leadership. PPG Canada Inc. represents the automotive-refinish heritage transfer archetype, leveraging weathering and scratch-resistance technology migration. Sherwin-Williams Canada Inc. anchors the extensive distribution network model, reaching secondary manufacturing centers across Quebec and British Columbia with localized inventory positioning.
| Leading Market Players |
|---|
| Akzo Nobel Canada Inc. |
| PPG Canada Inc. |
| Sherwin-Williams Canada Inc. |
| Axalta Coating Systems Canada Company |
| Benjamin Moore & Co. Ltd. |
| Cloverdale Paint Inc. |
| Hempel (Canada) Inc. |
| General Paint Corporation |
| Nippon Paint (Canada) Inc. |
| Others |
Value Chain & Pricing Dynamics
Specialized formulation chemists concentrated in Greater Montreal create labor-cost differentials that widen pricing-tier spreads between premium water-based systems and commodity solvent-based alternatives. Ontario manufacturers absorbing Health Canada compliance retrofit costs face steeper procurement premiums for technical-service-bundled coatings versus unbundled spot-buy options.
Pricing Analysis
Warranty and predictive maintenance bundling separates premium coating contracts from unbundled transactional purchases in the Ontario manufacturing corridor. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with large furniture OEMs capturing standard-tier discounts through multi-year offtake commitments. Pricing pressure stems from petrochemical resin volatility compressing margins on price-locked annual contracts. Small Quebec furniture shops exhibit highest price sensitivity due to capital constraints on spray-line conversion, while mass timber fabricators in British Columbia show lowest sensitivity given specification-grade performance requirements.
Supply Chain Analysis
Domestic-content alignment with federal procurement preferences reshapes sourcing patterns toward Ontario-based resin production and Quebec specialty additive manufacturing. Propylene and isocyanate feedstocks draw from Alberta petrochemical corridors and imported US Gulf Coast supply, with acrylic binder precursors resting on Asian import channels. Single-source vulnerability concentrates in Greater Montreal crosslinker production clusters serving eastern Canadian blenders. Distribution runs through direct manufacturer relationships with large Ontario OEMs, supplemented by distributor networks reaching secondary Prairie and Atlantic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada industrial wood coatings market reads as a cost-of-compliance story where Health Canada's Canadian Environmental Protection Act VOC timelines erect barrier-to-entry moats favoring incumbents with proven water-based formulation pipelines and on-site technical infrastructure.
For Market Incumbents: Lock in Ontario cabinet cluster procurement through localized inventory positioning and same-day technical response capabilities. Deepen backward integration into water-based polyurethane dispersion production to capture margin compression from petrochemical feedstock volatility. Defend against emerging digital color-matching platforms by embedding predictive maintenance software as standard contract inclusions rather than premium add-ons.
For New Entrants and Emerging Players: Capture British Columbia mass timber specification-grade demand for fire-retardant and exterior-durable finishes where incumbent technical-service density remains lowest. Target Alberta and Saskatchewan distributor channels with cloud-based spectrophotometry platforms that reduce sample-cycle times for dispersed secondary markets. Enter through digitally enabled color-matching partnerships with regional industrial supply intermediaries rather than direct OEM competition.
For Investors and Strategic Acquirers: Re-rating potential sits with water-based formulation specialists given Health Canada regulatory compression accelerating buyer migration from solvent-based alternatives. Five-to-ten year viability favors targets with captive Quebec additive supply relationships and Ontario technical-service infrastructure. Watch for inflection where provincial SCAQMD-equivalent standards trigger forced conversion timelines among legacy Quebec furniture plants lacking capital for humidity-control retrofit.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Low-VOC Production Lines | Ontario retrofit demand from Health Canada enforcement creates localized supply shortage for compliant water-based systems. |
| Backward Integration into Polyurethane Dispersion Manufacturing | Captive resin production insulates margin compression from propylene and isocyanate feedstock volatility. |
| Digital Color-Matching Platform Deployment | Cloud-based spectrophotometry reduces sample-cycle times for Alberta distributors serving dispersed Prairie markets. |
| Technical-Service Team Localization | Same-day response capabilities lock in Toronto-Waterloo corridor procurement against price-competitive distant suppliers. |
| Fire-Retardant Formulation Development | British Columbia mass timber construction specifications create premium positioning for exterior-durable coating systems. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with coating plant managers, furniture OEM procurement leads, distribution channel partners, and technical R&D directors. Health Canada Canadian Environmental Protection Act documentation, Canadian General Standards Board performance benchmarks, and provincial carbon-pricing regulatory disclosures provided compliance timeline validation. Bottom-up volume estimates from Ontario and Quebec manufacturing facility throughput reconciled against top-down market sizing from petrochemical feedstock consumption patterns.
Data-stream reconciliation across shipment records, production capacity disclosures, and end-use consumption surveys informed the analytical framework. Segmentation dimensions modeled include formulation chemistry, application environment, technology type, and regional regulatory intensity across the projection horizon. CAGRs derived from trend-line extrapolation of retrofit investment cycles and buyer migration patterns from solvent-based to water-based systems, with cross-validation against resin price elasticity and equipment replacement timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Health Canada VOC amendment timing and provincial SCAQMD-equivalent standard adoption rates. Forecasts reflect documented assumptions regarding spray-line conversion capital availability among small Quebec furniture shops and mass timber construction growth trajectories in British Columbia. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Stain Resistance Coatings Market
Coatings
Bio-Fouling Prevention Coatings Market
Coatings
Fluid Bed and Coating System Market
Coatings
Compound Coating Market
Coatings
US Protective Coatings Market
Coatings
Global Surface Protection Films Market
Coatings
France Protective Coatings Market
Coatings
Powder Coating Booth Market
Coatings
Cool Roof Coatings Market
Coatings
Global Low Friction Coatings Market
Coatings
Coating Auxiliaries Market
Coatings
Global Pipe Coatings Market
Coatings
North America Powder Coatings Market
Coatings
Germany Automotive OEM Coatings Market
Coatings
Asia-Pacific Superhydrophobic Coating Market
Coatings
Conductive Coatings Market