
 France Smart Home Market | 2026-2036
France Smart Home Market Size, Share, and Industry Trends Forecast 2026-2036
France Smart Home Market Insights
CE marking for radio equipment is reorganizing competitive entry into France's smart home sector, filtering out uncertified hardware imports. Schneider Electric SE leverages its deep electrical infrastructure heritage to dominate whole-home energy management deployments. Somfy sustains leadership in automated shading and window controls through specialized channel relationships with French builders. Legrand SA anchors its position in connected lighting through extensive distribution across residential and commercial electrician networks.
France smart home systems comprise networked sensors, actuators, and control interfaces that communicate through protocols such as Zigbee mesh topology or Wi-Fi to automate environmental, security, and entertainment functions. These installations typically integrate with centralized hubs processing data at the edge to enable real-time occupancy detection and predictive energy optimization. Smart Lighting and Smart Security Cameras together capture dominant value share, as French consumers prioritize visible safety upgrades and ambiance control before deeper automation investments. Wi-Fi technology leads volume deployment due to existing household infrastructure, though Z-Wave commands premium positioning in professionally installed multi-protocol estates where builders seek reliable interoperability.
ANSM oversees device cybersecurity standards for connected health-adjacent home products, while CNIL enforces GDPR-compliant data handling across voice assistants and camera feeds streaming to cloud servers. France's transposition of the EU Radio Equipment Directive mandates specific electromagnetic compatibility testing that shapes product development timelines and import eligibility. Stakeholders must monitor evolving CSRD disclosure requirements affecting smart home platform operators' supply chain reporting obligations.
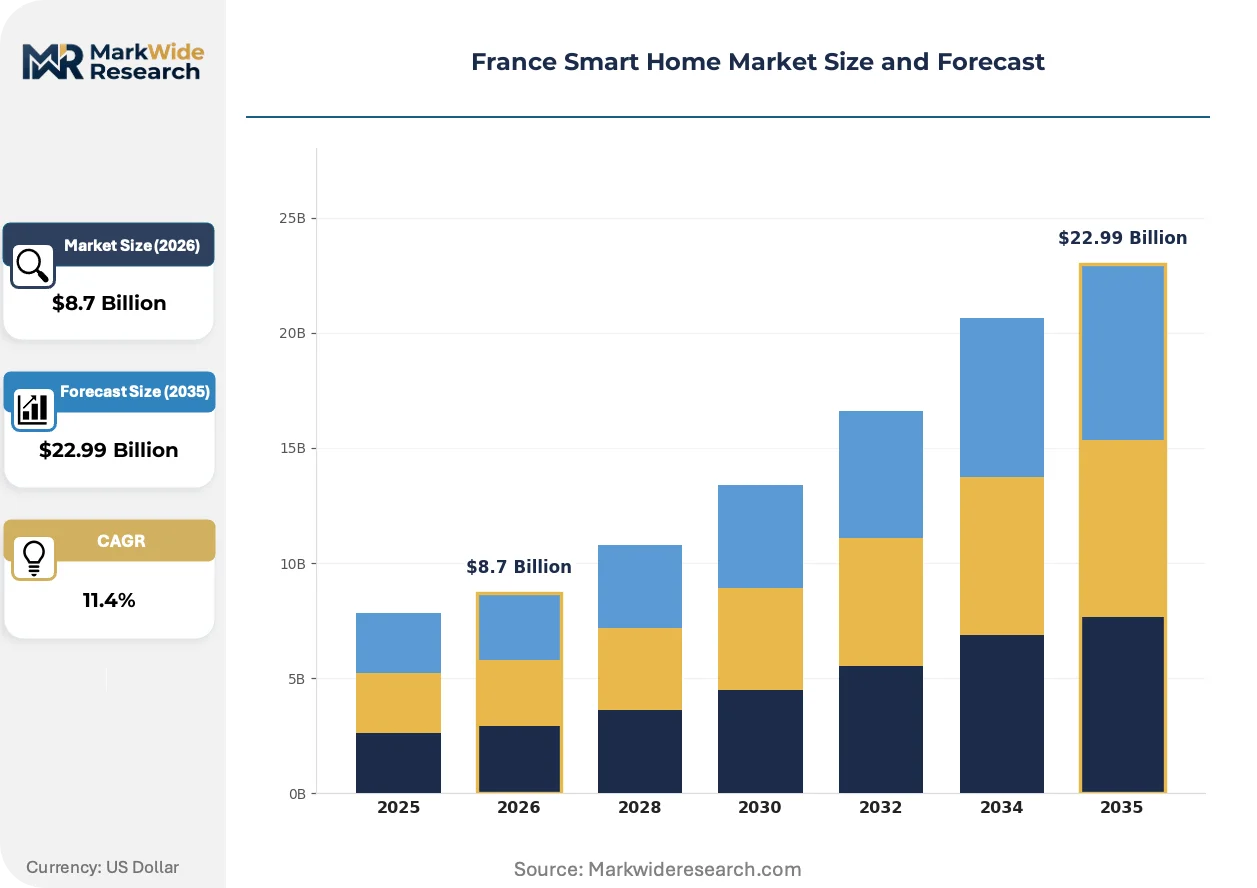
Market Dynamics
France's RE2020 environmental regulation mandates stricter building energy performance standards, forcing developers toward integrated smart infrastructure and accelerating retrofit demand across Île-de-France's aging housing stock.
Growth Catalysts
- RE2020 Building Codes:The regulation mandates connected climate systems in new construction, creating guaranteed demand for smart thermostats and energy management hardware.
- Île-de-France Metropolitan Corridor:Energy-conscious homeowners in Paris and surrounding departments are accelerating adoption of whole-home automation platforms.
- Zigbee Mesh Topology:This protocol enables reliable device-to-device communication without Wi-Fi dependency, solving connectivity dead zones in concrete-heavy French architecture.
Market Restraints
- CE Marking Reorganization:The EU Radio Equipment Directive's electromagnetic compatibility testing requirements extend product development timelines and filter out uncertified hardware imports.
- Silicon Supply Concentration:Semiconductor fabrication concentrates in East Asian foundries, exposing French smart home manufacturers to input volatility and extended lead times.
- Interoperability Fragmentation:Competing protocols create technical limitations where Z-Wave estates cannot integrate with Zigbee devices without expensive multi-protocol hubs.
Strategic Opportunities
- Auvergne-Rhône-Alpes:This underpenetrated region outside Paris offers white space for smart security and lighting deployments as secondary cities urbanize.
- CSRD Disclosure Requirements:The Corporate Sustainability Reporting Directive creates procurement mandates for ESG-compliant smart building platforms across commercial real estate.
- Matter-Thread Convergence:The interoperability standard combining IP-based connectivity with low-power mesh networking simplifies installation complexity for professional integrators.
Industry Challenges
- GDPR-Compliant Data Architecture:CNIL enforcement requires edge-processing redesigns for voice assistants and camera systems, compressing development cycles.
- Legacy Electrical Integration:Pre-1990s French housing stock lacks neutral wiring, forcing expensive retrofitting for smart switch deployment.
- Cybersecurity Certification Timelines:ANSM oversight for health-adjacent connected products adds months to product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Smart Home Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, Smart Security Cameras, Smart Thermostats, Smart Appliances Technology: Wi-Fi, Zigbee, Bluetooth, Z-Wave End User: Homeowners, Renters, Property Managers, Builders Distribution Channel: Online Retail, Brick-and-Mortar Stores, Distributors, Direct Sales |
| Companies Covered | Schneider Electric SE, Somfy, Legrand SA, Netatmo, ABB Ltd, Honeywell International Inc., Siemens AG, Delta Dore, Bosch Smart Home GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Smart Home Market Trends and Innovations
Edge computing architectures are actively reshaping how French smart homes process sensor data, reducing cloud dependency while addressing CNIL's data localization requirements. This shift enables real-time automation without latency penalties.
Matter-over-Thread is supplanting proprietary Zigbee implementations in premium installations. The protocol enables direct smartphone-to-device commissioning without manufacturer-specific hubs. Professional integrators in Lyon and Bordeaux are specifying Matter-native hardware for multi-vendor estates, compressing installation timelines and reducing callback rates for interoperability failures.
France's transposition of the EU AI Act introduces risk-classification requirements for smart home systems employing biometric recognition or predictive occupancy algorithms. Hardware manufacturers must now document training data provenance and algorithmic transparency. Connected camera and voice assistant segments face the steepest compliance burden, with vendors restructuring cloud architectures to limit automated decision-making scope.
Homeowners are consolidating vendor relationships around ecosystem-integrated platforms rather than assembling point solutions. The electrician channel is capturing this shift by bundling Legrand lighting with Schneider energy management into single-quote installations. This pattern concentrates most visibly in Parisian apartment renovations, where buyers prioritize unified app control over best-of-breed feature depth.
France Smart Home Market Segmentation
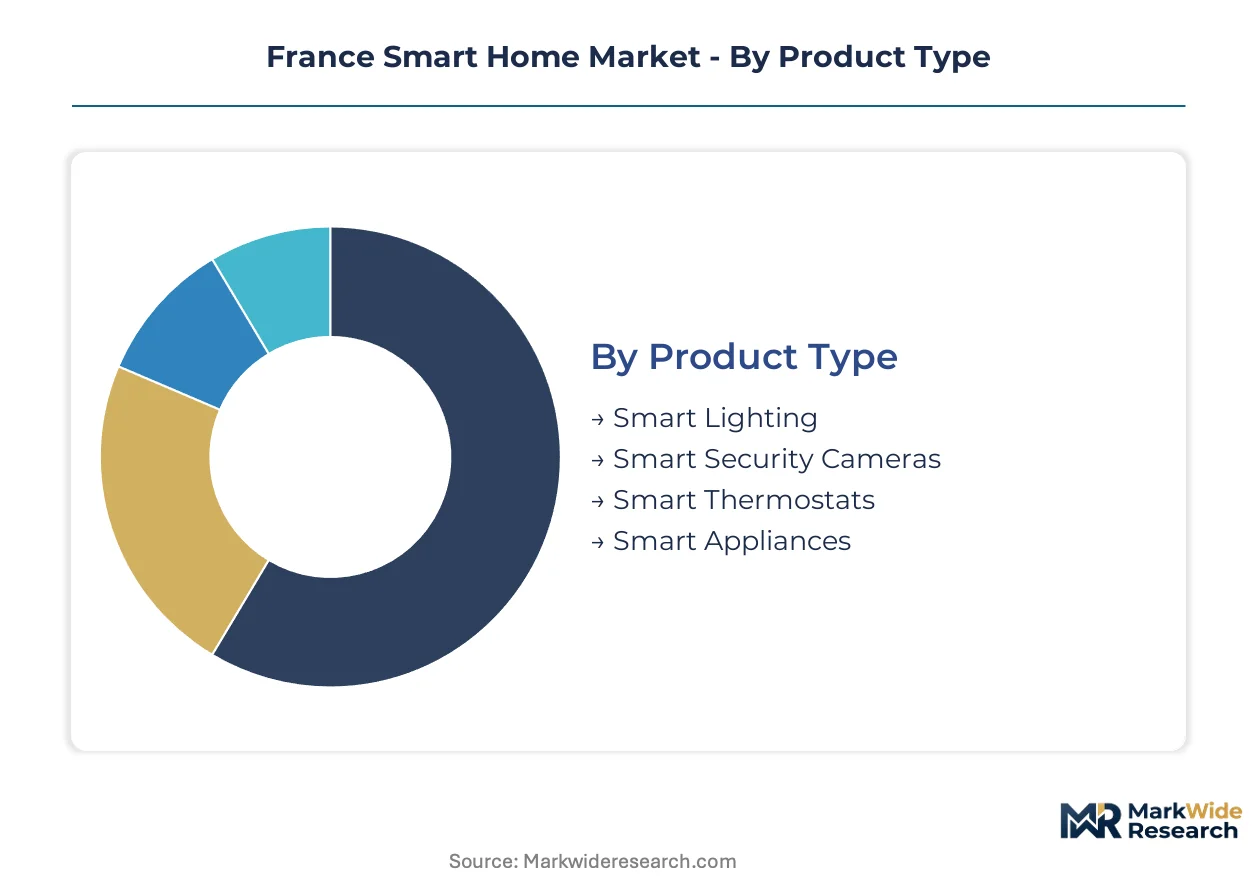
Segmentation in the France Smart Home Market reveals how regulatory mandates, infrastructure constraints, and channel economics concentrate value across distinct product configurations. Understanding these divisions exposes where professional integrators capture margin versus where mass retail dominates volume.
Product Type:
Premium margins pool in systems requiring professional installation and ongoing service relationships, while hardware-only categories compete on price through retail channels.
- Smart Lighting:Connected fixtures and switches enabling centralized ambiance control through dimming, color temperature adjustment, and scheduling automation. Demand clusters in Parisian apartment renovations where RE2020 compliance drives LED retrofits with integrated controls. Legrand's electrician channel dominance sustains professional-grade pricing power in this segment.
- Smart Security Cameras:Networked video surveillance with motion detection, cloud storage, and mobile alert capabilities. CNIL's GDPR enforcement pushes edge-processing architectures that eliminate cloud dependency, favoring premium hardware with local AI inference over subscription-dependent models. Île-de-France homeowners prioritize visible security upgrades in multi-unit buildings.
- Smart Thermostats:Climate control devices learning occupancy patterns to optimize heating schedules. RE2020 mandates guarantee new-construction demand, though retrofit penetration lags in pre-1990s housing lacking compatible wiring infrastructure.
- Smart Appliances:Connected white goods with remote monitoring and predictive maintenance capabilities. Adoption concentrates in high-income suburban departments where whole-home automation platforms justify premium appliance investments.
The dominant share belongs to Smart Lighting, while Smart Security Cameras is closing the gap fastest.
Technology:
Protocol selection determines installation complexity, interoperability scope, and whether deployments rely on existing household infrastructure or require dedicated hardware investment.
- Wi-Fi:Leverages ubiquitous home internet connectivity for direct cloud communication without intermediary hubs. Volume leadership stems from zero incremental hardware cost for consumers, though congestion and range limitations constrain reliability in concrete-heavy French construction typical of Parisian buildings.
- Zigbee:Mesh topology enabling battery-powered devices to relay signals through intermediate nodes, eliminating dead zones. Île-de-France's dense urban housing drives adoption where concrete walls block direct Wi-Fi paths and professional integrators specify multi-device estates.
- Bluetooth:Short-range protocol for direct smartphone commissioning of individual devices. Limited to single-room applications and temporary configurations where permanent hub infrastructure is impractical.
- Z-Wave:Sub-GHz frequency protocol optimized for reliable penetration through building materials. Commands premium positioning in professionally installed multi-protocol estates where builders prioritize guaranteed interoperability over cost minimization.
Zigbee captures the broadest deployment base among professional installers, though Matter-over-Thread is gaining share fastest as integrators consolidate around unified commissioning standards.
End User:
Customer type dictates purchasing authority, installation method, and whether transactions flow through retail or professional channels.
- Homeowners:Primary decision-makers controlling renovation budgets and long-term technology investments. Energy-conscious households in Île-de-France drive whole-platform adoption integrating climate, security, and lighting under unified control.
- Renters:Tenants with limited modification rights seeking non-invasive solutions. Demand concentrates on plug-and-play cameras, smart speakers, and portable climate devices avoiding permanent electrical work.
- Property Managers:Commercial operators of multi-unit residential portfolios. CSRD disclosure requirements create procurement mandates for ESG-compliant smart building platforms across commercial real estate holdings.
- Builders:Construction firms integrating smart infrastructure during new development. RE2020 compliance obligations guarantee pre-installation of connected climate systems, locking in thermostat and energy management hardware specifications.
Homeowners retain the largest addressable base, while Property Managers represent the steepest expansion trajectory as CSRD mandates accelerate commercial retrofit cycles.
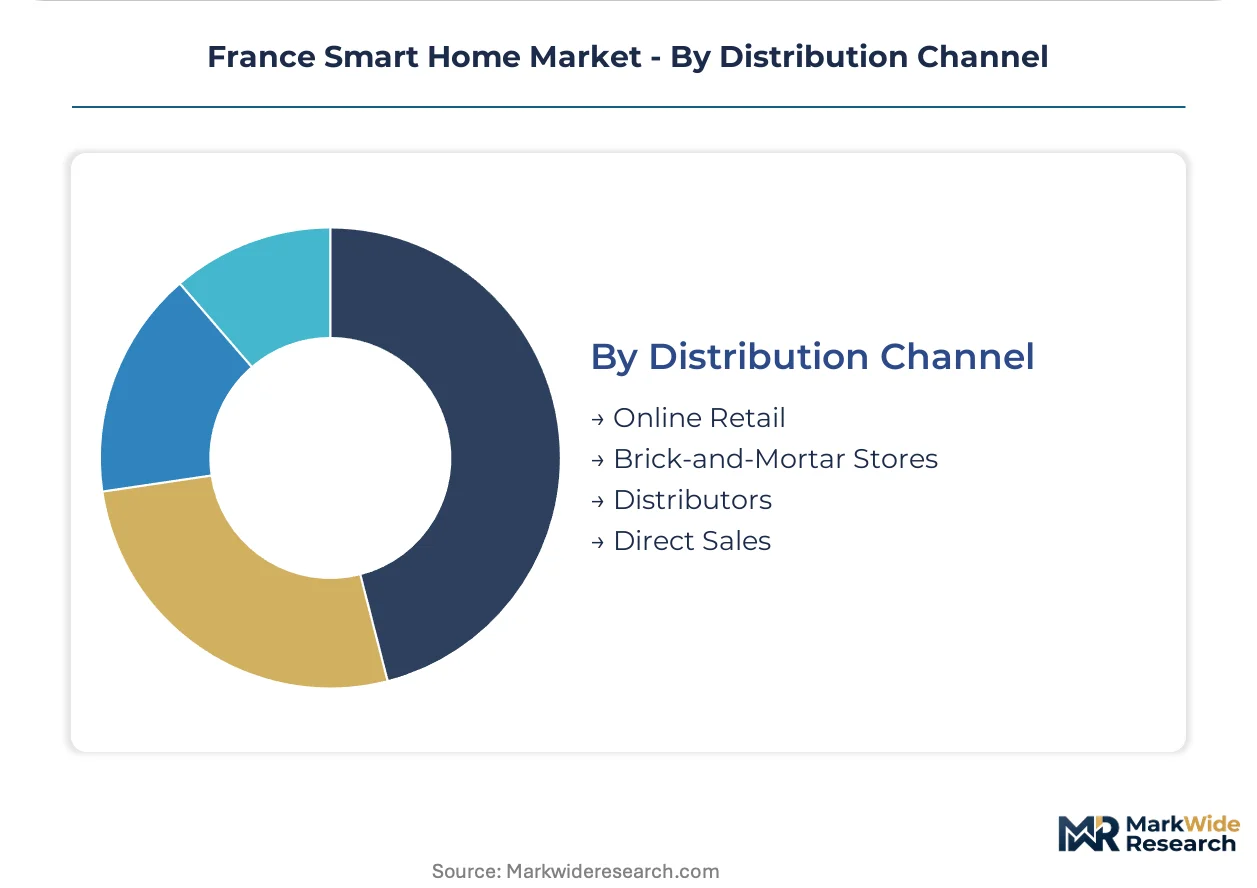
Distribution Channel:
Channel structure determines margin capture, technical support burden, and whether vendors control customer relationships or cede them to intermediaries.
- Online Retail:E-commerce platforms offering price transparency and consumer reviews. Wi-Fi-dependent point solutions dominate this channel where self-installation capability eliminates professional service requirements.
- Brick-and-Mortar Stores:Physical retail providing tactile evaluation and immediate fulfillment. Leroy Merlin and Boulanger anchor smart home visibility for mass-market consumers seeking hands-on product comparison.
- Distributors:Wholesale channels supplying electricians and professional integrators. Legrand and Schneider Electric leverage this infrastructure to maintain specification control in commercial and residential projects.
- Direct Sales:Manufacturer-controlled transactions bypassing retail markup. Somfy sustains automated shading leadership through direct builder relationships that bundle specification, installation, and service.
Distributors command the professional project pipeline, though Online Retail is climbing fastest as Wi-Fi-enabled devices simplify self-installation for mainstream consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's RE2020 building codes and CNIL data localization requirements are redistributing smart home deployment patterns across metropolitan corridors and secondary urban zones. Regional variation reflects housing stock age, income concentration, and local enforcement of energy performance mandates.
Île-de-France
Paris and its surrounding departments concentrate over half of national smart home value, driven by energy-conscious homeowners retrofitting Haussmann-era apartments with connected climate systems. ANSM cybersecurity oversight for health-adjacent devices shapes product availability in this dense urban market. Boulogne-Billancourt and Neuilly-sur-Seine anchor professional integrator networks specifying multi-protocol estates for high-end renovations.
Auvergne-Rhône-Alpes
Lyon's construction boom and Grenoble's energy research cluster create white space for smart security and lighting deployments outside the Paris orbit. RE2020 compliance deadlines for new commercial developments in Lyon Part-Dieu drive thermostat and energy management hardware specifications. Saint-Étienne's aging industrial housing stock presents retrofit challenges requiring neutral-wire solutions for smart switch deployment.
Provence-Alpes-Côte d'Azur
Nice and Marseille's luxury residential developments prioritize visible security upgrades and automated shading for climate control. GDPR-compliant edge-processing architectures from CNIL enforcement favor premium camera hardware with local AI inference over cloud-dependent models. Aix-en-Provence's university-driven rental market sustains demand for non-invasive plug-and-play devices among tenant populations.
Hauts-de-France
Lille's cross-border commerce with Belgium creates procurement patterns blending French RE2020 mandates with Flemish building standards. The region's post-industrial housing stock lacks compatible wiring infrastructure, compressing smart thermostat penetration in retrofit segments. Roubaix's data center cluster supports edge-computing architectures addressing CNIL localization requirements for voice assistant deployments.
Nouvelle-Aquitaine
Bordeaux's wine industry affluence and tech sector growth sustain whole-home automation platform adoption among energy-conscious households. Matter-over-Thread protocol specification is accelerating fastest here as professional integrators consolidate around unified commissioning standards. Biarritz's seasonal residence patterns drive demand for remote monitoring capabilities in secondary homes.
France Smart Home Market Competitive Landscape
Listed leaders compete with private specialists across channel access and installation service integration, producing a tiered structure where electrical heritage firms command specification control in professional projects while retail-oriented brands capture volume through self-installation channels. Three archetypes dominate: infrastructure-rooted conglomerates leveraging distribution depth, specialized automation pure-plays with builder relationships, and consumer electronics entrants competing on price transparency. Consolidation pressures are intensifying through strategic partnerships between hardware manufacturers and professional integrator networks, alongside portfolio diversification into adjacent building automation segments.
Within the infrastructure-rooted tier, Schneider Electric SE exemplifies the electrical heritage archetype, while Somfy and Legrand SA occupy positions spanning professional specification and retail accessibility. These three anchors illustrate how French market leadership derives from channel control rather than technology differentiation alone, with each representing distinct pathways to customer lock-in through either energy management integration, automated shading specialization, or connected lighting distribution density.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Somfy |
| Legrand SA |
| Netatmo |
| ABB Ltd |
| Honeywell International Inc. |
| Siemens AG |
| Delta Dore |
| Bosch Smart Home GmbH |
| Others |
Pricing and Supply Chain Analysis
CE marking reorganization under the EU Radio Equipment Directive gates both supply qualification and price differentiation simultaneously, filtering uncertified hardware imports while compressing development timelines for compliant manufacturers seeking premium positioning in Île-de-France's professional installation channel.
Pricing Analysis
Certification level creates the primary spread across France's smart home hardware tiers. Three-tier pricing structure across premium, standard, and economy levels separates Matter-certified multi-protocol hubs from single-standard Wi-Fi devices and uncertified imports. Pricing pressure stems from silicon supply concentration in East Asian foundries, compressing margins on mid-tier Zigbee hardware. Property managers under CSRD procurement mandates exhibit lowest price sensitivity, while mass-market renters through online retail channels drive hardest bargain hunting.
Supply Chain Analysis
Inventory lead times for radio-frequency chipsets now stretch eighteen to twenty-four weeks, forcing French integrators into speculative stocking positions. Semiconductor fabrication concentrates in Taiwan, South Korea, and mainland China, exposing thermostat and sensor manufacturers to input volatility. Critical dependencies include RF transceivers, power management ICs, and lithium battery cells. Single-source vulnerability concentrates in Zigbee protocol stack licensing. Distribution runs through wholesale electrical distributors serving Parisian electrician networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's smart home sector presents a service-attach opportunity where recurring platform subscription revenue expands faster than transactional hardware sales, particularly around energy management analytics and predictive maintenance layers bundled with Schneider and Legrand installations.
For Market Incumbents: Shield specification control in Île-de-France's renovation pipeline by deepening captive supply of Matter-compatible radio modules. Invest in edge-processing R&D to preempt CNIL compliance redesigns threatening cloud-dependent camera architectures. Secure exclusive channel terms with Leroy Merlin and Boulanger against direct-to-consumer entrants.
For New Entrants and Emerging Players: ANSM cybersecurity fast-track certification opens white space in health-adjacent connected products for assisted living applications. Target Auvergne-Rhône-Alpes secondary cities where professional integrator networks remain underdeveloped versus Paris saturation. Pursue co-development partnerships with regional builders facing RE2020 compliance deadlines.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant smart home divisions lacking channel integration. Five-to-ten-year viability hinges on Matter-Thread protocol consolidation eliminating multi-hub complexity. Monitor ANSM certification backlog as inflection signal for regulatory-capable assets commanding acquisition premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter-Thread Protocol Certification | Ensures interoperability with Schneider Electric and Legrand ecosystems across Île-de-France installations. |
| Edge Computing Architecture Deployment | Addresses CNIL data localization requirements while reducing cloud latency for real-time automation. |
| Professional Integrator Network Partnership | Captures specification authority in RE2020-mandated new construction through direct builder relationships. |
| Subscription Analytics Platform Launch | Attaches recurring revenue to hardware sales through predictive energy optimization services. |
| Auvergne-Rhône-Alpes Geographic Expansion | Penetrates underdeveloped secondary urban markets outside Paris metropolitan concentration. |
Research Methodology
A spread of perspectives from smart home platform engineers, electrical distributor procurement leads, professional integrator network heads, and CNIL compliance officers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against ANSM device registration databases, RE2020 regulatory filings, and customs import records for radio equipment. Bottom-up unit economics triangulated against top-down construction permit data across French departments.
Segmentation dimensions modeled include product type, protocol technology, end-user archetype, and distribution channel across the analysis window. CAGRs derived from installation volume trends correlated with building energy regulation phase-in schedules. Forecast inputs incorporated RE2020 compliance deadline clustering and Matter protocol adoption curves among professional integrators.
The analysis sits within stated boundaries; outcomes outside sustained RE2020 enforcement or accelerated Matter-Thread standardization would require recalibration. Forecasts reflect documented assumptions regarding silicon supply normalization and CNIL interpretation stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
High Frequency Vibrator Market
Others
Digital Signage Media Player Market
Others
Global Injectable Nanomedicine Market
Others
Roasted Wheat Market
Others
Global Molded Plastics Market
Others
Global Hydraulics Market
Others
Ceramic Machinery Market
Others
Global Active Speaker Market
Others
Eye Balm Market
Others
Africa Cotton Market
Others
Fluorapatite Market
Others
UK Automotive LED Lighting Market
Others
Global Automotive LED Lighting Market
Others
5G Smartphone Market
Others
Latin America IT Device Market
Others
Video Paas Market