
 Heavy Duty Vacuum Bottle Market | 2026-2036
Heavy Duty Vacuum Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Duty Vacuum Bottle Market Foresight
The EU Green Deal is decoupling disposable container demand from institutional procurement cycles across European public sectors. Thermos LLC leverages its century-old manufacturing footprint to sustain defense and aerospace contracts requiring MIL-SPEC thermal retention. YETI Holdings, Inc. anchors premium positioning through direct-to-consumer channel control and limited wholesale distribution. Zojirushi Corporation differentiates via precision vacuum insulation technology developed for its domestic Japanese market.
Heavy duty vacuum bottles employ double-wall construction with evacuated airspace between stainless steel layers, achieving thermal retention exceeding twelve hours for liquids between negative twenty and positive ninety-nine degrees Celsius. Food jars and travel mugs command higher margin pools in the product type dimension due to specialized sealing mechanisms and narrower competitive sets. Stainless steel dominates the material category by volume, though aluminum variants gain traction in weight-sensitive applications such as ultralight backpacking and cycling segments. The 32 oz and 64 oz capacity tiers attract the strongest replenishment rates among outdoor enthusiasts and athletes.
The EPA regulates heavy metals content in consumer products sold through US federal channels, while the EU F-Gas Regulation indirectly shapes insulation gas alternatives in manufacturing processes. BIS certification requirements in India restrict market access for uncertified imports, creating compliance barriers for Western brands. ISO 9001 quality management standards function as baseline procurement filters across institutional buyers. Stakeholders must monitor evolving extended producer responsibility frameworks in the European Union and individual US state legislatures to anticipate redesign obligations and material recovery mandates.
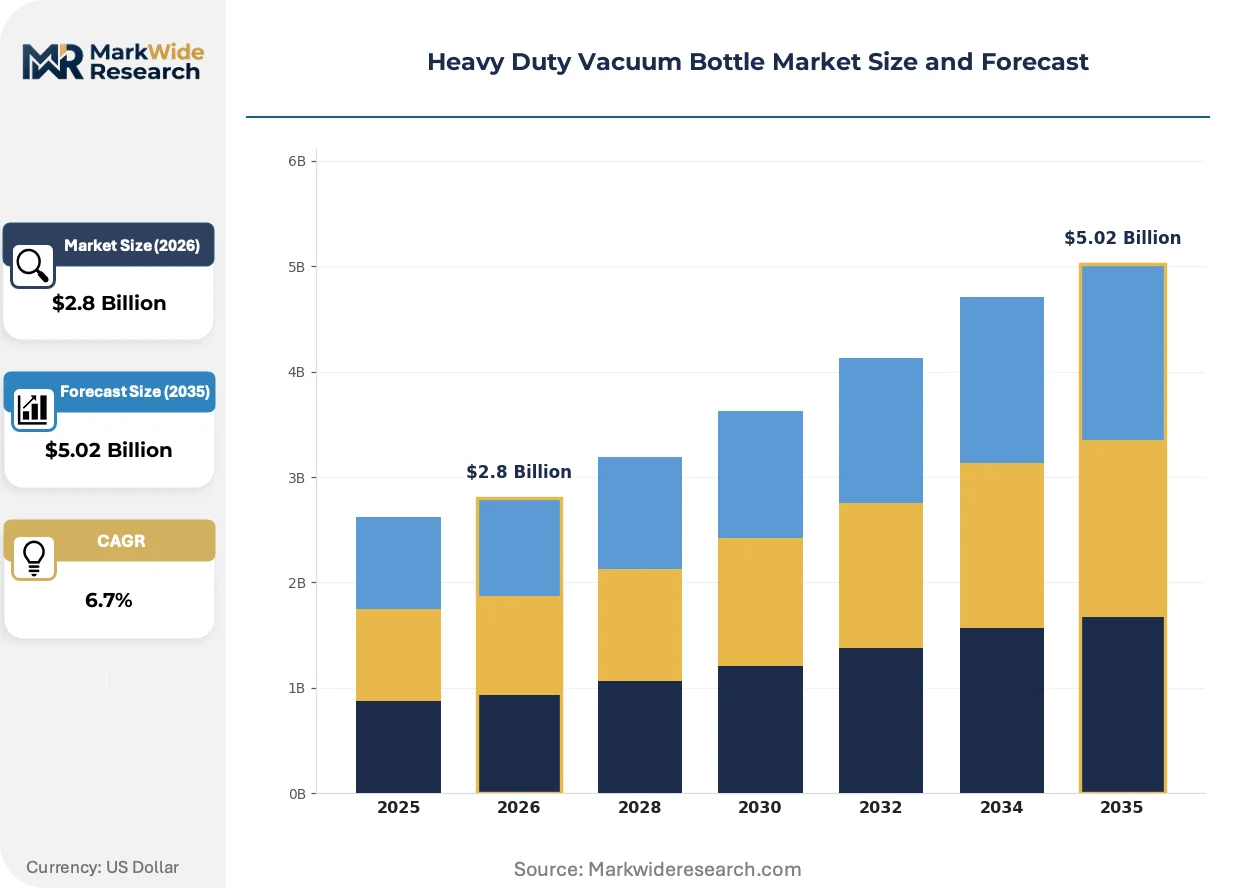
Market Dynamics
The EU Green Deal's durability mandates are forcing manufacturers to redesign vacuum insulation systems for extended service life, while federal procurement channels in the United States consolidate purchasing power around MIL-SPEC certified suppliers.
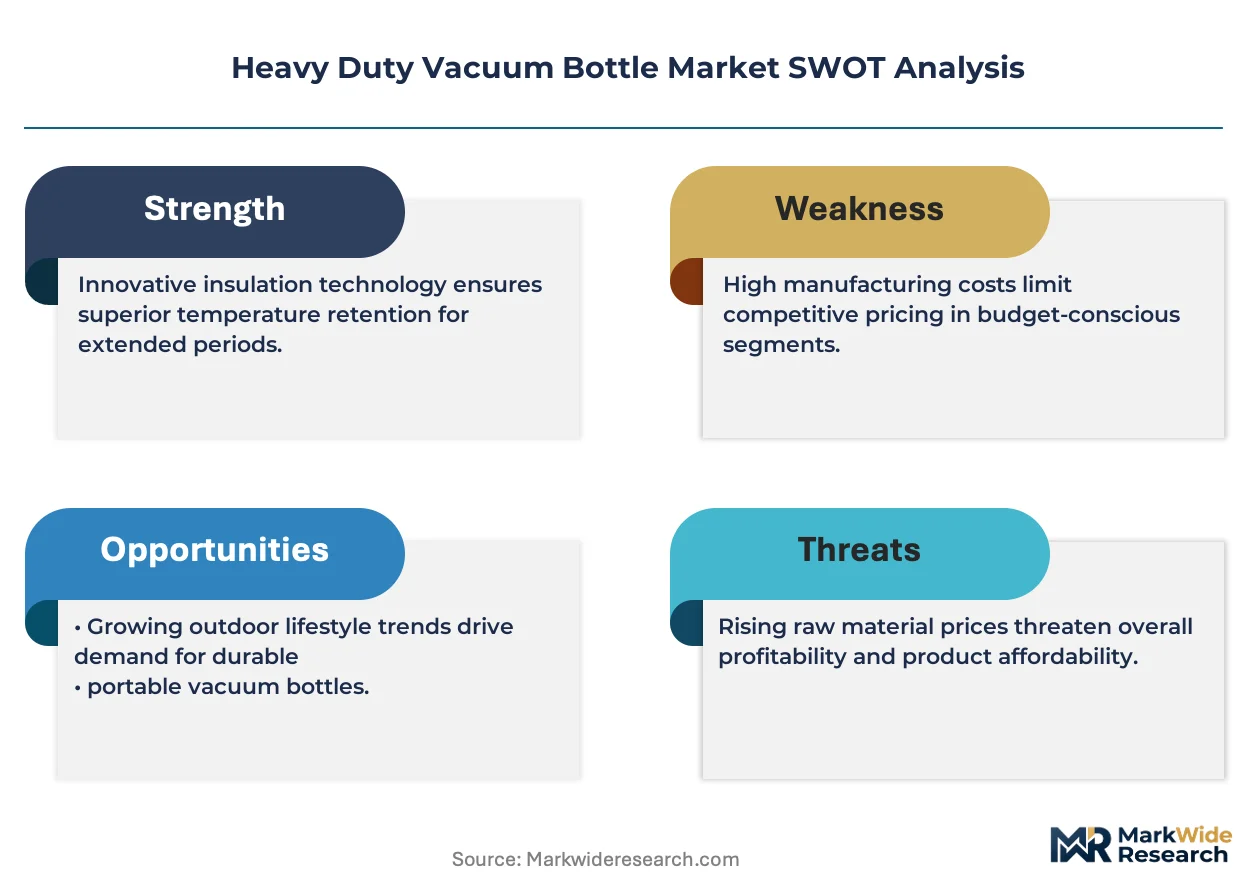
Growth Catalysts
- Outdoor Recreation Expansion:Federal parks services and military supply chains in the United States sustain bulk institutional orders for double-wall insulated containers.
- F-Gas Regulation Compliance:European manufacturers are retrofitting production lines to eliminate hydrofluorocarbon blowing agents from insulation gas mixtures.
- Ultralight Material Substitution:Aluminum variants capture share in weight-sensitive cycling and backpacking segments where every gram determines equipment selection.
Market Restraints
- Nickel Price Volatility:Austenitic stainless steel input costs fluctuate with London Metal Exchange pricing, compressing margin pools on standard-grade products.
- BIS Certification Barriers:India's Bureau of Indian Standards testing requirements create 18-24 month market entry timelines for Western brands seeking import authorization.
- Single-Use Plastic Substitution:Disposable insulated pouches and cartons threaten low-capacity vacuum bottle demand in food service and event catering channels.
Strategic Opportunities
- Extended Producer Responsibility Tailwinds:EU member state frameworks for material recovery and redesign obligations create first-mover advantages for closed-loop manufacturing systems.
- Precision Sealing Convergence:Integration of automotive-grade gasket technology with vacuum insulation is opening medical specimen transport and pharmaceutical cold chain applications.
- Direct-to-Channel Innovation:Limited wholesale distribution models bypass traditional retail markup structures, capturing full margin on premium-tier thermal retention products.
Industry Challenges
- ISO 9001 Audit Compression:Institutional buyers now require simultaneous quality management and environmental management certification, extending vendor qualification cycles.
- Evacuation Equipment Capex:High-vacuum pump installations and helium leak detection systems demand seven-figure capital commitments for new production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Duty Vacuum Bottle Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Bottles, Water Bottles, Food Jars, Travel Mugs Material: Stainless Steel, Glass, Plastic, Aluminum End User: Outdoor Enthusiasts, Office Workers, Athletes, Travelers Capacity: 12 oz, 20 oz, 32 oz, 64 oz |
| Companies Covered | Thermos LLC, YETI Holdings, Inc., Hydro Flask, Stanley, Klean Kanteen, Zojirushi Corporation, Contigo, S'well, CamelBak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Duty Vacuum Bottle Market Shifts & Advancements
Active redesign of thermal retention architecture is compressing product development cycles while regulatory pressure on insulation gases forces material science pivots across manufacturing bases.
Copper vacuum insulation technology is consolidating position in premium-tier products through superior thermal conductivity management. Aerospace contractors and Antarctic research programs specify copper-lined vessels for missions requiring 24-hour liquid temperature stability. This metallurgical shift is compressing demand for traditional glass-wool insulated alternatives in extreme-environment procurement channels.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in polyurethane foam blowing processes, compelling insulation manufacturers to adopt pentane or hydro-olefin alternatives. German and Italian production facilities face 2027 compliance deadlines for retrofitting foaming lines. Vacuum bottle assemblers sourcing EU-origin insulation cores must verify alternative gas documentation to maintain CE marking eligibility.
Institutional buyers are consolidating vendor lists around dual-certified suppliers holding both ISO 9001 quality management and ISO 14001 environmental management credentials. United States federal procurement channels now require documented conflict mineral exclusion for stainless steel inputs. Defense and parks service supply chains are responding by pre-qualifying smaller vendor pools with integrated certification packages, displacing fragmented multi-source purchasing patterns.
Heavy Duty Vacuum Bottle Market Segmentation
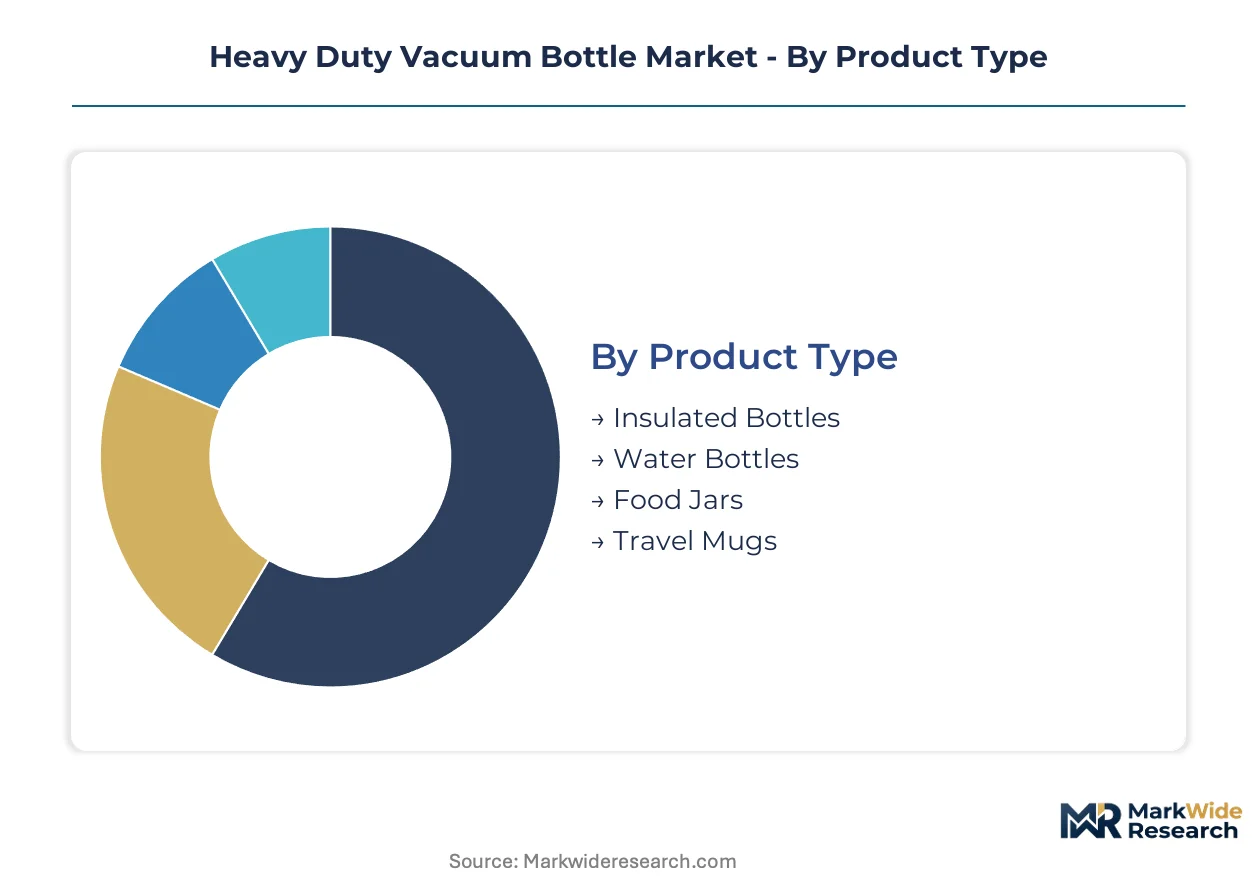
Segmentation in the heavy duty vacuum bottle market determines procurement pathways, margin structures, and certification burdens. Institutional buyers filter vendor pools by product type and material compliance, while consumer channels sort by capacity tiers and end-use scenarios.
Product Type:
ISO 9001 and MIL-SPEC certifications concentrate demand in insulated bottles and food jars, while travel mugs face lighter regulatory screening through retail channels.
- Insulated Bottles:Double-wall stainless steel construction with evacuated airspace delivers thermal retention exceeding twelve hours across temperature extremes from negative twenty to positive ninety-nine degrees Celsius. Federal parks services and military supply chains in the United States sustain bulk institutional procurement for this segment, driven by defense contract specifications requiring documented conflict mineral exclusion.
- Food Jars:Specialized sealing mechanisms with precision-engineered gaskets create narrower competitive sets and higher margin pools compared to standard bottles. Antarctic research programs and aerospace contractors specify copper-lined variants for missions demanding 24-hour liquid temperature stability, compressing demand for traditional glass-wool insulated alternatives.
- Water Bottles:Standard-grade configurations dominate volume through outdoor retail and direct-to-consumer channels.
- Travel Mugs:Narrower diameter profiles target automotive cup-holder compatibility and commuter convenience segments.
Insulated bottles sit at the top of the volume ranking, with food jars climbing the fastest.
Material:
Cost tiers stratify sharply across material categories, with austenitic stainless steel commanding premium pricing against aluminum's weight-sensitive positioning.
- Stainless Steel:Austenitic grades dominate by volume, though London Metal Exchange nickel price volatility compresses margin pools on standard-grade products. EPA heavy metals regulations for US federal channel sales and EU Green Deal durability mandates reshape supplier qualification requirements for this material tier.
- Aluminum:Ultralight variants capture share in cycling and backpacking segments where equipment selection hinges on gram-level weight differentials. German and Italian production facilities face F-Gas Regulation compliance deadlines for retrofitting foaming lines, affecting insulation core sourcing documentation for CE marking eligibility.
- Glass:Borosilicate configurations serve taste-purists and chemical-averse consumer niches with limited institutional penetration.
- Plastic:Polypropylene and Tritan copolyester variants occupy economy pricing tiers with reduced thermal retention performance.
Stainless steel maintains the steepest expansion trajectory in absolute dollar terms, while aluminum gains share fastest on a percentage basis.
End User:
Customer type determines channel configuration, with institutional procurement consolidating around outdoor enthusiasts and athletes while office workers fragment across retail touchpoints.
- Outdoor Enthusiasts:Federal parks services and military supply chains consolidate purchasing power around MIL-SPEC certified suppliers, requiring simultaneous ISO 9001 quality management and ISO 14001 environmental management credentials. The 32 oz and 64 oz capacity tiers attract the strongest replenishment rates in this segment.
- Athletes:Hydration-focused designs with rapid-flow caps and integrated carry systems target training and competition scenarios. Precision vacuum insulation technology developed for the Japanese domestic market differentiates premium-tier offerings in this segment.
- Office Workers:Commuter-oriented travel mugs with leak-proof sealing dominate this fragmented consumer category.
- Travelers:Collapsible and multi-compartment configurations address space-constrained luggage scenarios.
Outdoor enthusiasts anchor procurement volume, with athletes expanding most quickly through specialized sporting goods channels.
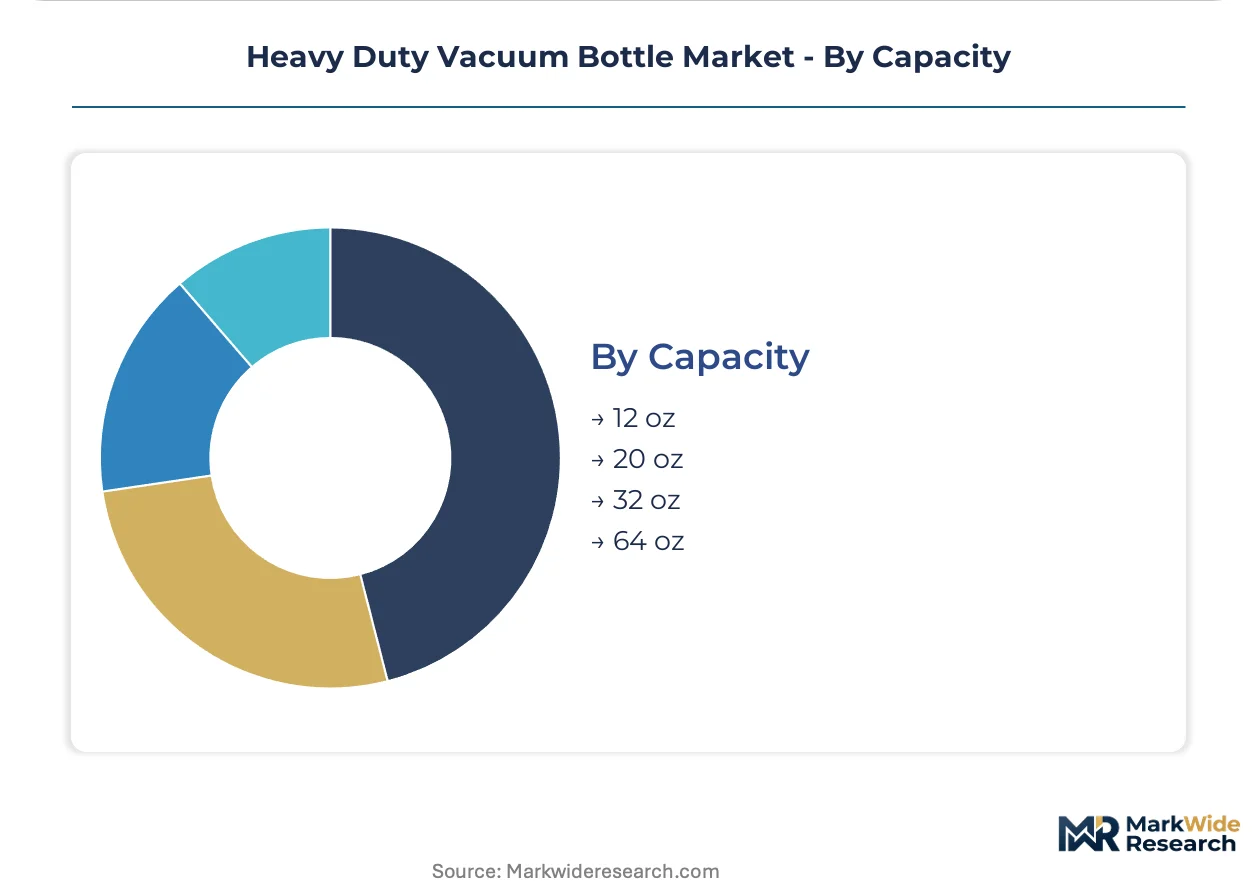
Capacity:
Volume scale economics favor mid-tier capacities, where production runs achieve optimal throughput without the tooling complexity of niche sizes.
- 32 oz:The standard bearer for outdoor enthusiasts and athletes, balancing portability against hydration duration. Replenishment rates in this tier outpace smaller capacities due to wear-and-tear replacement cycles in rugged use environments.
- 64 oz:Base camp and vehicle-based expedition configurations dominate this tier, with demand concentrating in United States federal procurement channels and Antarctic research program specifications.
- 12 oz:Espresso and single-serve beverage niches occupy this compact tier with limited institutional uptake.
- 20 oz:Commuter and everyday carry segments fragment demand across retail channels with moderate growth velocity.
Thirty-two ounce vessels lead absolute shipment volumes, with sixty-four ounce configurations gaining share fastest in institutional procurement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vacuum insulation manufacturing traces its industrial lineage to early twentieth century Germany and post-war Japan, where precision metalworking traditions established the technical foundations for double-wall vessel production. These origins continue to shape regional specialization patterns across contemporary supply chains.
United States
Federal parks services and military supply chains sustain bulk institutional procurement for MIL-SPEC certified containers. EPA heavy metals regulations govern consumer products sold through federal channels, mandating documented conflict mineral exclusion for stainless steel inputs. Tennessee and Texas host concentrated manufacturing footprints serving defense and aerospace thermal retention contracts.
Germany
Antarctic research programs and aerospace contractors specify copper-lined precision vessels for extreme-environment missions. The EU F-Gas Regulation compels insulation manufacturers to eliminate hydrofluorocarbon blowing agents from polyurethane foam processes by 2027. Bavarian and North Rhine-Westphalian production facilities lead retrofitting investments for pentane and hydro-olefin alternative gas systems.
Japan
Domestic precision vacuum insulation technology developed for consumer markets differentiates premium-tier offerings exported globally. METI industrial standards and JIS certification requirements shape quality benchmarks for double-wall construction. Osaka and Nagoya industrial clusters concentrate evacuated airspace manufacturing expertise and helium leak detection system capabilities.
China
Yangtze River Delta manufacturing bases supply volume production of austenitic stainless steel vessels for export markets. GB standards and SAMR market supervision frameworks regulate domestic product safety and material compliance. Zhejiang and Jiangsu provinces concentrate vacuum pump installation and double-wall assembly line capacity.
India
Outdoor recreation expansion and institutional procurement growth drive demand for durable insulated containers across Himalayan trekking and military supply applications. BIS certification requirements impose 18-24 month market entry timelines for import authorization, creating compliance barriers for Western brands. Maharashtra and Gujarat host emerging domestic fabrication capacity serving South Asian distribution networks.
Heavy Duty Vacuum Bottle Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification and channel control dimensions, with institutional procurement consolidating vendor lists around dual-certified suppliers. The competitive structure segments into heritage manufacturers with century-old technical foundations, direct-to-consumer specialists controlling limited wholesale distribution, and precision engineering firms leveraging domestic market technology transfer. Strategic moves concentrate on backward integration into evacuated airspace manufacturing and upstream control over conflict-mineral-excluded stainless steel supply chains.
Among heritage-positioned manufacturers, Thermos LLC and Zojirushi Corporation exemplify archetypes built on technical lineage and precision engineering foundations. YETI Holdings, Inc. occupies a position within the direct-to-consumer tier where channel control and premium positioning anchor competitive differentiation. These three companies represent distinct strategic vectors: institutional contract specialization, precision vacuum technology export, and brand-direct margin capture.
| Leading Market Players |
|---|
| Thermos LLC |
| YETI Holdings, Inc. |
| Hydro Flask |
| Stanley |
| Klean Kanteen |
| Zojirushi Corporation |
| Contigo |
| S'well |
| CamelBak |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between MIL-SPEC institutional suppliers and retail-grade commodity producers manifests in divergent margin structures and procurement pathways across the heavy duty vacuum bottle market. Premium-tier manufacturers commanding defense and aerospace contracts capture pricing power through integrated quality management systems, while standard-grade assemblers compete on nickel-input cost management and volume throughput in Yangtze River Delta export channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels organizes the competitive landscape, with copper-lined precision vessels and dual-certified supply chains anchoring the top tier against aluminum ultralight alternatives in the middle. Price differentiation hinges on ISO 9001/14001 certification bundles and documented conflict mineral exclusion for federal channel eligibility. Cost compression in austenitic stainless steel tiers is intensifying because London Metal Exchange nickel volatility feeds directly into standard-grade product margins. Institutional buyers in United States federal procurement channels exhibit the lowest price sensitivity, while event catering and commuter segments fragment across price-driven retail selections.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale institutional demand from defense and parks service procurement offices, while specialized distributors serve Antarctic research and aerospace contractor specifications with precision-engineered copper-lined variants. Manufacturing gravity centers on China, Japan, and Germany, with Zhejiang and Jiangsu provinces dominating evacuated airspace assembly capacity and Osaka-Nagoya clusters feeding precision vacuum technology exports. Raw material dependencies draw from Indonesian nickel ore, Chilean copper cathode, and specialty austenitic steel grades from German and Japanese mills. Single-source vulnerability concentrates in helium leak detection equipment and high-vacuum pump installations, where seven-figure capital commitments create barriers to supplier diversification. Distribution runs through consolidated vendor lists pre-qualified for dual certification packages, displacing fragmented multi-source purchasing patterns in institutional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The heavy duty vacuum bottle market has entered a late-cycle quality phase where institutional procurement consolidation favors suppliers with integrated certification packages and demonstrated thermal retention performance under extreme-environment specifications.
For Market Incumbents: Acquire evacuated airspace manufacturing capabilities and helium leak detection system operators to deepen backward integration into core vacuum insulation production. Pre-qualify for simultaneous ISO 9001 and ISO 14001 audits ahead of vendor list consolidation in United States federal channels. Threat exposure concentrates in emerging aluminum ultralight specialists capturing cycling and backpacking share through gram-level weight optimization. For New Entrants and Emerging Players: EU F-Gas Regulation compliance deadlines in Germany and Italy open a window for alternative gas documentation services and pentane-based insulation core sourcing. Target medical specimen transport and pharmaceutical cold chain applications where precision sealing convergence with automotive-grade gasket technology creates penetrable white space. Go-to-market leverage rests on direct relationships with Antarctic research programs and aerospace contractors specifying 24-hour liquid temperature stability. For Investors and Strategic Acquirers: Asymmetric upside sits with precision engineering firms holding captive vacuum insulation technology and established METI/JIS certification pathways in the Japanese domestic market. Long-term viability across a multi-year horizon favors dual-certified suppliers with demonstrated conflict mineral exclusion documentation and defense contract execution history. Watch BIS certification timeline compression in India as an inflection indicator for South Asian market access restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Evacuated Airspace Manufacturing | Captures margin pools from vacuum pump installations and reduces dependency on Yangtze River Delta assembly capacity. |
| Dual Certification Investment (ISO 9001/14001) | Qualifies suppliers for consolidated United States federal vendor lists displacing fragmented multi-source procurement. |
| Copper Vacuum Insulation Technology Deployment | Meets Antarctic research and aerospace specifications for 24-hour thermal retention in extreme environments. |
| Alternative Gas Documentation Compliance | Maintains CE marking eligibility as EU F-Gas Regulation phases down hydrofluorocarbon blowing agents by 2027. |
| Direct-to-Consumer Channel Expansion | Bypasses traditional retail markup structures to capture full margin on premium-tier thermal retention products. |
Research Methodology
Direct dialogue with vacuum insulation plant managers, federal procurement officers at parks services and military supply chains, precision engineering directors at Japanese manufacturing clusters, and distribution channel partners in outdoor retail informed primary intelligence synthesis. Secondary validation drew from EPA heavy metals regulatory filings, EU F-Gas Regulation implementation documentation, BIS certification procedural records, London Metal Exchange nickel pricing data, and ISO certification registry databases. Bottom-up shipment analysis across capacity tiers and material categories triangulated against top-down institutional procurement budget allocations.
Segmentation outputs across product type, material grade, end-user archetype, and capacity tier fed into analytical framework construction over the projection horizon. CAGRs were derived from regression analysis against outdoor recreation program expansion rates and federal procurement cycle documentation. Industry-specific forecast inputs incorporated F-Gas Regulation compliance timeline assumptions and BIS certification backlog estimates for Western brand market entry scenarios.
Revisions become necessary when nickel price volatility exceeds historical bands, when EU member state extended producer responsibility frameworks accelerate redesign obligations, or when BIS testing protocols undergo procedural modification. Forecasts reflect documented assumptions regarding institutional procurement consolidation velocity and alternative gas adoption rates in European insulation manufacturing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Binoculars and Mounting Solutions Market
Others
US Quantum Computing Market
Others
Fluorite Market
Others
Hookah Tobacco Market
Others
Global Injectable Nanomedicine Market
Others
Underwater Communication System Market
Others
US 3D Printing Construction Market
Others
Global Pregnancy Tracker Apps Market
Others
Pet Care Packaging Market
Others
US Luxury Travel Market
Others
Canada 3D Printing Construction Market
Others
UK Cat Food Market
Others
Composite Copper Foil Production Equipment Market
Others
Global Military and Aerospace Sensors Market
Others
Thermal Insulation Solution for LNG and LPG Market
Others
Textile Composites Market