
 Europe Methyl Acrylate Market | 2026-2036
Europe Methyl Acrylate Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Methyl Acrylate Market Foresight
Bio-based acrylate monomers is repositioning conventional petroleum-derived methyl acrylate economics across European formulation labs. BASF SE anchors its competitive stance through backward integration into propylene oxide feedstock. Arkema S.A. differentiates via specialized high-purity grades for medical adhesive applications. Evonik Industries AG leverages emulsion polymerization technology leadership to sustain premium positioning in waterborne coatings.
Methyl acrylate is an ester of acrylic acid with a molecular weight of 86.09 g/mol, produced industrially through acid-catalyzed esterification of acrylic acid with methanol, serving primarily as a reactive monomer for polymer synthesis in coatings, adhesives, and textile treatments. The coatings segment dominates value generation due to architectural and automotive refinishing demand, while adhesives represents the fastest-expanding application driven by electronics miniaturization and flexible packaging assembly needs. Emulsion polymerization technology leads production volume because of its lower volatile organic compound emissions profile, aligning with EU industrial emissions directives.
REACH registration requirements administered by ECHA mandate comprehensive toxicological data for methyl acrylate imports and manufacturing above one tonne annually, elevating compliance costs for smaller compounders. The EU Green Deal's chemical sustainability targets are accelerating substitution pressure toward bio-attributed monomer variants. Germany's Federal Institute for Risk Assessment coordinates with ECHA on workplace exposure limit reviews affecting downstream processor operations. Stakeholders must monitor feedstock propylene availability from crackers and assess captive versus merchant monomer sourcing ahead of anticipated carbon border adjustment mechanism expansions.
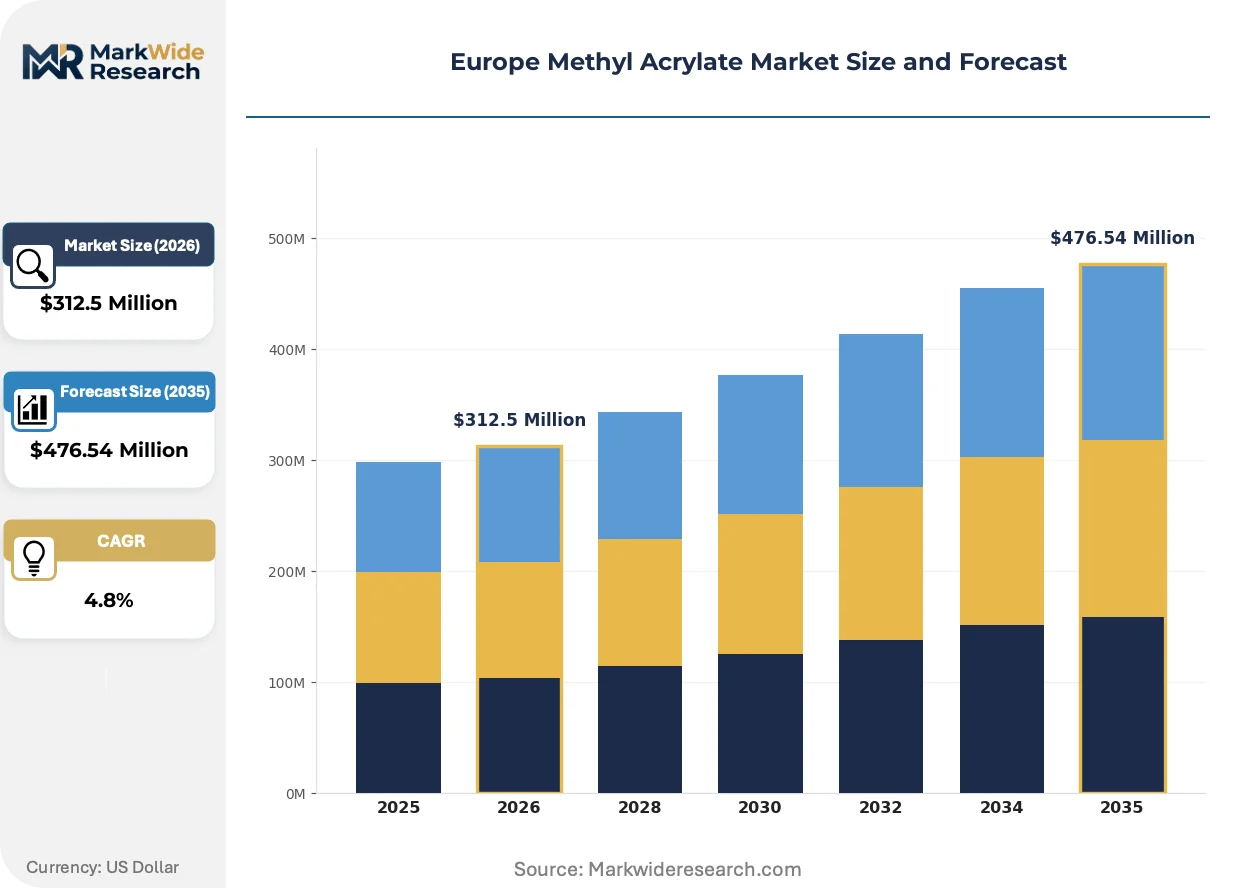
Market Dynamics
REACH chemical registration requirements administered by ECHA are compressing the supplier base as compliance costs disproportionately burden smaller compounders, concentrating formulation-grade methyl acrylate supply among integrated producers with captive toxicological data capabilities.
Growth Catalysts
- EU Green Deal chemical sustainability targets:Bio-attributed monomer variants gain procurement preference among automotive OEMs seeking scope 3 emissions reductions in coating supply chains.
- Water-based automotive refinishing coatings:German vehicle manufacturers are expanding low-VOC formulation mandates across their European assembly networks.
- Electronics miniaturization:Flexible packaging assembly requirements in France and Italy are pulling high-purity methyl acrylate into medical-grade adhesive applications.
Market Restraints
- Propylene feedstock volatility:Naphtha cracker operating rates across the ARA region directly determine monomer cost structure for non-integrated compounders.
- REACH data cost concentration:ECHA's comprehensive toxicological registration requirements above one tonne annual threshold create structural barriers to market entry.
- Bio-based acrylate substitution:Petroleum-derived methyl acrylate faces displacement pressure from bio-attributed alternatives in premium formulation segments.
Strategic Opportunities
- Carbon border adjustment mechanism preparation:German industrial chemical corridor processors can secure competitive positioning through verified low-carbon monomer sourcing ahead of phased implementation.
- Medical adhesive specialization:High-purity grades for healthcare applications command formulation premiums in Switzerland and the Netherlands.
- Emulsion polymerization technology convergence:Waterborne coating producers in Belgium are integrating continuous reactor designs with real-time VOC monitoring systems.
Industry Challenges
- Workplace exposure limit compliance:Germany's Federal Institute for Risk Assessment coordinates with ECHA on revised occupational thresholds affecting downstream processor ventilation capex.
- Legacy batch reactor retrofitting:Smaller Italian and Spanish compounders face capital intensity barriers in transitioning from solvent-based to emulsion polymerization systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Methyl Acrylate Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coatings, Adhesives, Textiles, Plastics Application: Paints, Sealants, Inks, Foam End User: Automotive, Construction, Electronics, Packaging Technology: Emulsion Polymerization, Suspension Polymerization, Solution Polymerization, Bulk Polymerization |
| Companies Covered | Dow Chemical Company, Mitsubishi Chemical Corporation, BASF SE, Kuraray Co., Ltd., LG Chem, Ltd., Arkema S.A., Synthomer, Nippon Shokubai Co., Ltd., Evonik Industries AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Methyl Acrylate Market Shifts & Advancements
Bio-based acrylate monomers are repositioning conventional petroleum-derived methyl acrylate economics across European formulation labs, while regulatory pressure on volatile organic compound emissions accelerates process technology turnover.
Emulsion polymerization technology is overtaking solvent-based batch processes in coating-grade methyl acrylate production. Automotive refinishing shops in Germany and France are specifying waterborne systems for 90% of new formulation procurement. This technology compression is enabling integrated producers to capture margin from compounders lacking reactor conversion capital.
REACH registration requirements administered by ECHA mandate comprehensive toxicological data for methyl acrylate imports and manufacturing above one tonne annually. Industrial consequence includes elevated compliance costs that structurally favor backward-integrated producers with captive regulatory affairs capabilities. The coatings segment across Germany's industrial chemical corridor is responding through consolidated supplier relationships with tier-one monomer manufacturers.
Specification-driven procurement now dominates methyl acrylate buying patterns among European coating formulators. Long-term supply agreements with certified low-carbon monomer producers are displacing spot market purchasing in automotive OEM supply chains. This shift is most visible in Germany, where vehicle manufacturers have embedded carbon intensity thresholds into supplier qualification protocols.
Europe Methyl Acrylate Market Segmentation
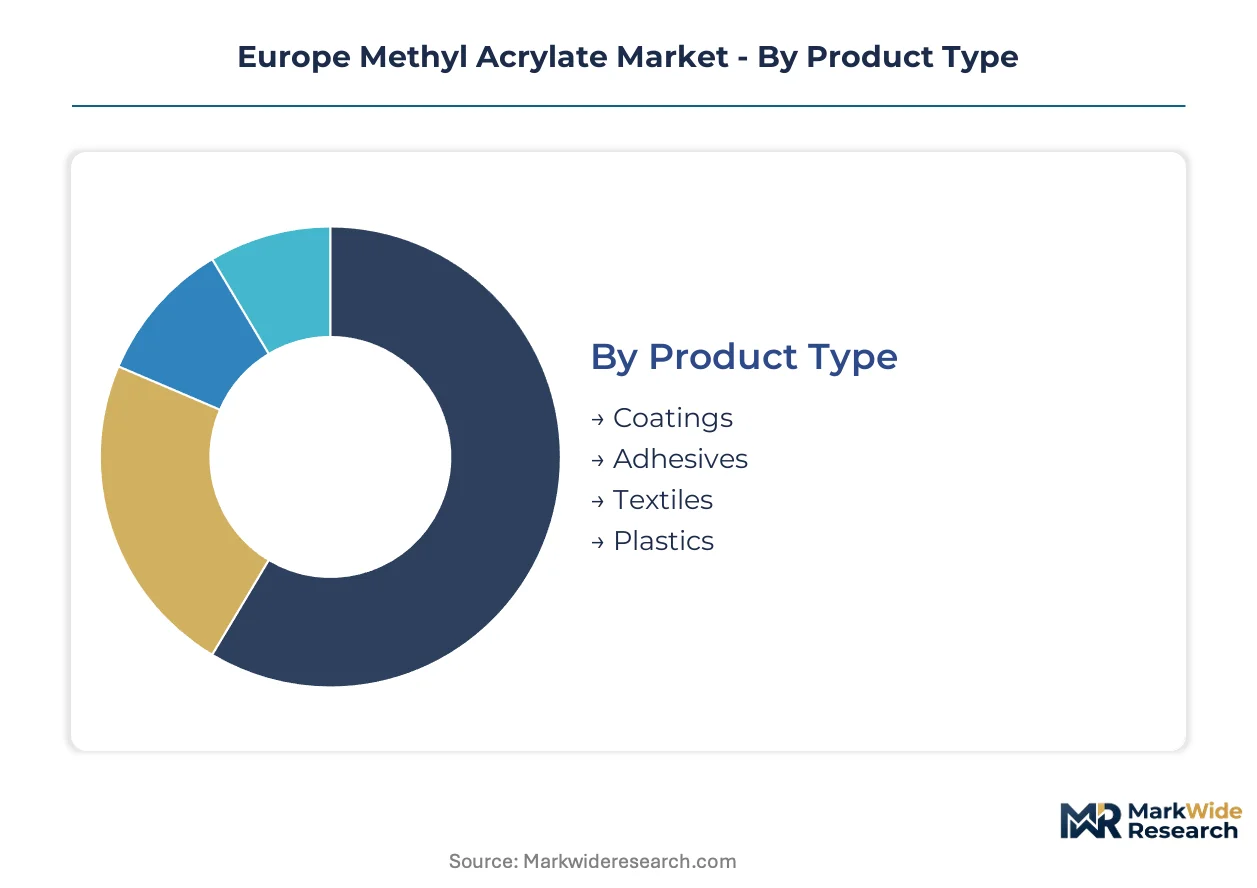
Methyl acrylate demand fragments across formulation chemistries, end-use specifications, and polymerization technologies. Each segmentation axis reveals distinct procurement patterns and margin structures that suppliers must navigate across European industrial corridors.
Product Type:
Formulators select product types based on curing speed, VOC content thresholds, and substrate compatibility requirements.
- Coatings:Architectural and automotive refinishing formulations dominate consumption. German vehicle manufacturers specify waterborne acrylic coatings across their European assembly networks, pulling methyl acrylate into low-emission polymer systems.
- Adhesives:Pressure-sensitive and structural bonding applications command premium-grade monomer specifications. Electronics miniaturization in France and Italy drives medical-grade adhesive demand with purity thresholds exceeding standard industrial grades.
- Textiles:Fiber finishing and nonwoven binders utilize methyl acrylate for hand-modification and durability enhancement.
- Plastics:Impact modifiers and processing aids incorporate acrylate monomers for weatherability and optical clarity.
Volume sits with Coatings; growth tilts toward Adhesives.
Application:
Application selection correlates with regulatory exposure and performance certification requirements.
- Paints:Decorative and protective coatings represent the largest application outlet. REACH-registered monomer grades from integrated producers supply formulators serving Germany's industrial chemical corridor.
- Sealants:Construction and automotive joint sealing applications require low-shrinkage polymer systems with adhesion to diverse substrates.
- Inks:Flexographic and gravure printing formulations utilize methyl acrylate for pigment dispersion and film formation.
- Foam:Open-cell and closed-cell polyurethane modifications incorporate acrylate monomers for resilience and compression set properties.
Revenue concentrates in Paints; formulation innovation clusters in Sealants.
End User:
End-user procurement patterns diverge between specification-driven OEMs and price-sensitive industrial compounders.
- Automotive:OEM coating mandates for scope 3 emissions reduction favor bio-attributed monomer sourcing. German manufacturers embed carbon intensity thresholds into supplier qualification protocols.
- Construction:Architectural coatings and sealants for building envelope applications drive steady demand across Benelux and Northern France.
- Electronics:Flexible circuit assembly and display bonding applications in Switzerland and the Netherlands pull high-purity grades.
- Packaging:Food-contact adhesive regulations administered by EFSA constrain monomer impurity profiles for flexible packaging laminations.
Procurement scale favors Automotive; specification intensity peaks in Electronics.
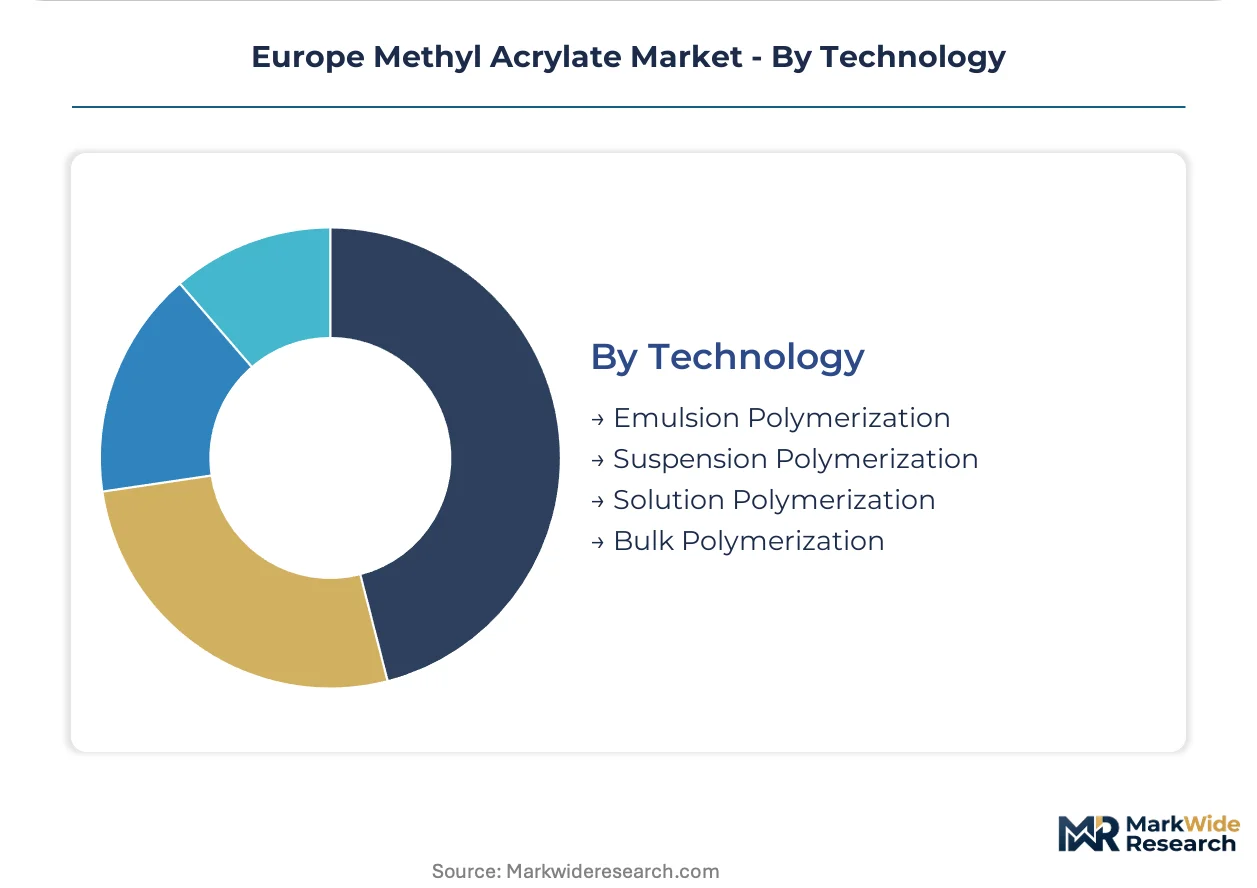
Technology:
Polymerization technology selection determines capital intensity, emissions profile, and product consistency.
- Emulsion Polymerization:Waterborne systems dominate new capacity investment. Belgian producers integrate continuous reactor designs with real-time VOC monitoring to align with EU industrial emissions directives.
- Suspension Polymerization:Bead-form polymer production serves specialized adhesive and coating applications requiring controlled particle size distribution.
- Solution Polymerization:Solvent-based systems retain niche positions in high-performance coatings where film clarity and gloss are critical.
- Bulk Polymerization:Mass polymerization without solvent or water carrier yields high-molecular-weight polymers for thermoplastic applications.
Capacity expansion concentrates in Emulsion Polymerization; legacy systems persist in Solution Polymerization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European methyl acrylate demand concentrates in Germany's industrial chemical corridor, where automotive OEMs and coating formulators drive procurement volumes. REACH compliance costs and carbon intensity thresholds now shape supplier selection across the continent.
Germany
Automotive refinishing coatings and industrial adhesives anchor consumption in the North Rhine-Westphalia and Bavaria chemical clusters. The Federal Institute for Risk Assessment coordinates with ECHA on workplace exposure limit revisions affecting processor ventilation investments. Ludwigshafen and Leverkusen host backward-integrated producers supplying formulation-grade monomer to domestic OEM networks.
France
Flexible packaging assembly and electronics bonding applications pull high-purity methyl acrylate into the Île-de-France and Auvergne-Rhône-Alpes manufacturing zones. EFSA food-contact regulations constrain monomer impurity profiles for adhesive laminations serving the Parisian packaging hub. Lyon-based formulators are consolidating supplier relationships with REACH-registered producers.
Netherlands
Medical-grade adhesive specifications and waterborne coating technologies concentrate demand in the Randstad and Eindhoven regions. The Dutch National Institute for Public Health and the Environment aligns with ECHA on emissions monitoring protocols. Rotterdam's port infrastructure facilitates propylene feedstock flows to ARA-region polymerization facilities.
Belgium
Emulsion polymerization capacity expansion and continuous reactor integration characterize the Antwerp chemical cluster. EU industrial emissions directives drive real-time VOC monitoring system adoption among coating producers. Ghent and Brussels host formulation labs specifying low-carbon monomer grades for Benelux automotive supply chains.
Switzerland
Healthcare adhesive applications and precision electronics bonding command premium-grade specifications in the Basel and Zurich industrial zones. Swissmedic medical device regulations elevate purity thresholds beyond standard industrial grades. Swiss converters source certified low-carbon monomer through long-term agreements with German suppliers.
Europe Methyl Acrylate Market Competitive Landscape
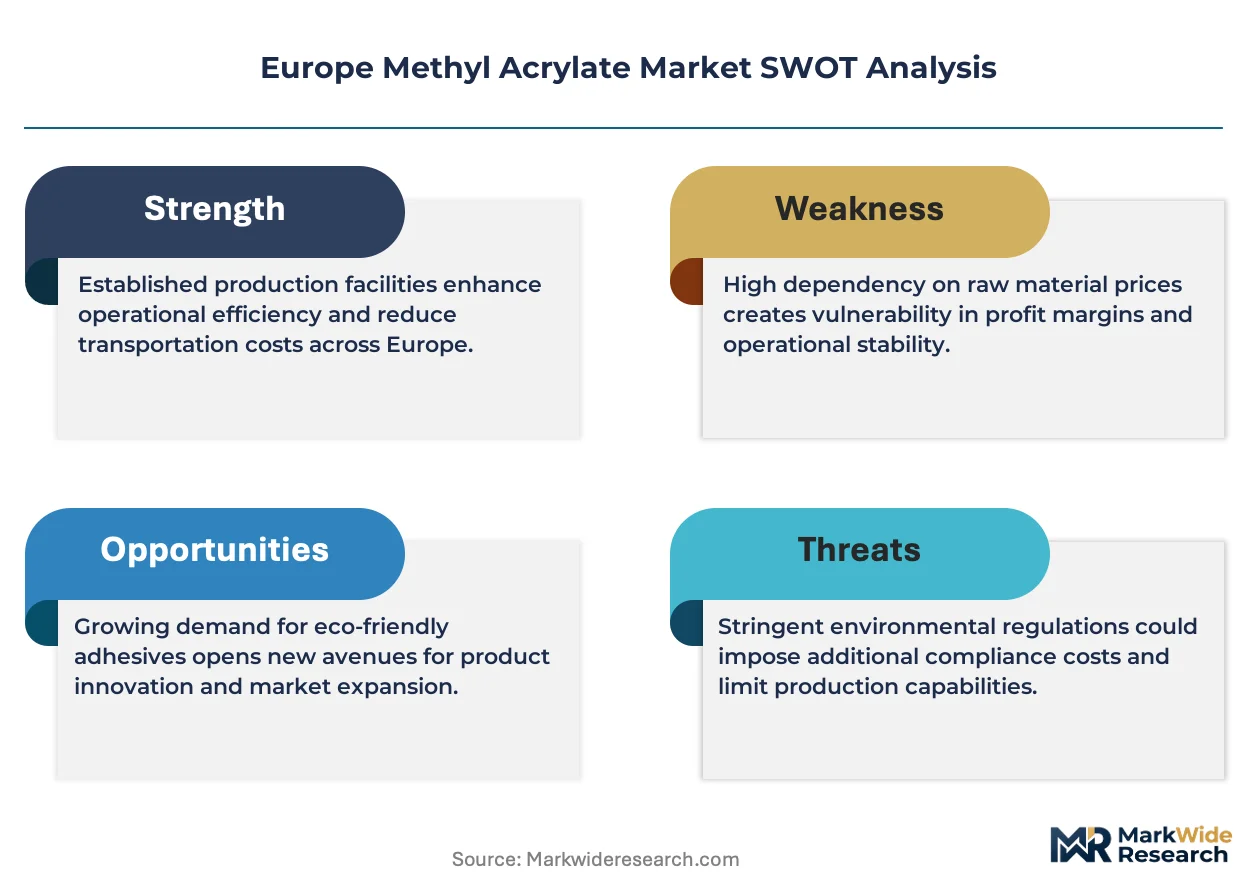
Backward integration into propylene oxide feedstock dominates the current landscape among European methyl acrylate producers. The supplier base compresses around integrated chemical conglomerates with captive toxicological data capabilities and merchant compounders dependent on spot propylene sourcing. Three archetypes define competitive positioning: petrochemical majors with cracker-to-monomer integration, specialized acrylate producers with medical-grade purification expertise, and Asian exporters leveraging scale economics for commodity volumes. Capacity expansion in waterborne polymerization systems and strategic partnerships for bio-attributed monomer certification represent the dominant competitive moves.
Within the integrated petrochemical tier, BASF SE anchors German supply through its Ludwigshafen Verbund structure, while Arkema S.A. exemplifies specialized acrylate positioning with French-based production assets. Evonik Industries AG occupies the performance materials intersection, representing emulsion polymerization technology leadership for coating applications. These three entities capture disproportionate formulation-grade market access through REACH registration depth and carbon certification capabilities.
| Leading Market Players |
|---|
| Dow Chemical Company |
| Mitsubishi Chemical Corporation |
| BASF SE |
| Kuraray Co., Ltd. |
| LG Chem, Ltd. |
| Arkema S.A. |
| Synthomer |
| Nippon Shokubai Co., Ltd. |
| Evonik Industries AG |
| Others |
Supply & Pricing Matrix
Propylene oxide feedstock costs cascade through three pricing tiers for European methyl acrylate buyers, with integrated producers capturing margin from compounders exposed to spot naphtha cracker volatility. REACH registration compliance costs concentrate supply relationships toward backward-integrated suppliers with captive toxicological data capabilities.
Pricing Analysis
Volume concentrates in standard industrial grades while margins accrue to high-purity medical specifications and bio-attributed certifications. Three-tier pricing structure across pharmaceutical-grade, REACH-registered industrial, and commodity spot tiers separates buyers by application stringency. Pricing pressure stems from bio-based acrylate substitution in automotive OEM coating supply chains, where scope 3 emissions thresholds favor certified low-carbon sourcing. Spot-market compounders exhibit highest price sensitivity; medical adhesive formulators in Switzerland and the Netherlands demonstrate lowest elasticity due to Swissmedic purity mandates.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Antwerp, and Ludwigshafen form a hub-and-spoke network serving Benelux and German chemical corridors. Supply concentrates in Germany, Belgium, and the Netherlands, with propylene feedstock drawing from ARA-region naphtha crackers and pipeline networks. Raw material dependencies span propylene oxide, methanol, and acrylic acid intermediates. Single-source vulnerability runs through Ludwigshafen Verbund structures for formulation-grade monomer. Distribution runs through long-term supply agreements with certified producers, displacing spot purchasing in automotive OEM procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European methyl acrylate competition has become a vertical-integration race, with producers securing propylene oxide feedstock control to defend margin against bio-based substitution and REACH compliance cost concentration.
For Market Incumbents: Cement supply relationships with German automotive OEMs through certified low-carbon monomer sourcing ahead of carbon border adjustment mechanism implementation. Expand emulsion polymerization capacity in Belgium and the Netherlands to capture waterborne coating specification shifts. Bio-attributed monomer certification investment represents the critical defensive lever against petroleum-grade displacement. For New Entrants and Emerging Players: Enter via medical-grade adhesive specialization in Switzerland and the Netherlands, where Swissmedic regulations create premium pricing umbrellas that offset REACH registration burdens. Target flexible packaging laminations in France's Île-de-France hub, where EFSA food-contact regulations constrain incumbent impurity profiles. White-space exists in bio-attributed monomer toll manufacturing for automotive coating supply chains. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale emulsion polymerization specialists in Belgium with stranded batch-reactor assets requiring continuous system retrofit capital. Long-term viability hinges on carbon intensity verification capabilities and REACH registration depth. Watch for propylene cracker operating rate inflections in the ARA region as margin compression signals for non-integrated compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide | Captive feedstock supply insulates margin from ARA naphtha cracker volatility. |
| Bio-Attributed Monomer Certification | Automotive OEM scope 3 protocols favor certified low-carbon acrylate sourcing. |
| Continuous Reactor Conversion | Belgian producers align with EU industrial emissions directives through real-time VOC monitoring. |
| Medical-Grade Purification Investment | Swissmedic regulations in Switzerland sustain premium pricing for healthcare applications. |
| Long-Term Supply Agreement Expansion | German vehicle manufacturers embed carbon intensity thresholds into supplier qualification protocols. |
Research Methodology
Multi-period observation of propylene cracker operating rates, REACH registration timelines, and automotive OEM coating procurement patterns anchored the trend analysis, supplemented by interviews with plant managers at polymerization facilities, procurement leads at downstream coating formulators, technical R&D directors, and distribution channel partners. Secondary validation drew from Cefic chemical industry reports, ECHA registration databases, customs trade data, and SEC filings of integrated chemical conglomerates. Bottom-up segment sizing triangulated against top-down demand modeling across formulation-grade tiers.
Input-output matrices mapped methyl acrylate flow from propylene oxide feedstock through emulsion polymerization capacity to end-use consumption in coatings, adhesives, and textile treatments across the analysis window. Segmentation dimensions modeled included product purity grade, polymerization technology type, end-use industry vertical, and regional production hub clustering. CAGRs derived from regression analysis of historical consumption patterns against automotive production forecasts and construction activity indices. Forecast inputs incorporated EU Green Deal chemical sustainability target trajectories and carbon border adjustment mechanism implementation phasing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under propylene feedstock disruption scenarios or accelerated bio-based acrylate substitution in premium formulation segments. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Isoprene Market
Bulk Chemicals
Aniline Market
Bulk Chemicals
Sodium Bicarbonate Market
Bulk Chemicals
Global Sodium Phosphate Market
Bulk Chemicals
Global Capric Acid Market
Bulk Chemicals
Global Fermentation Chemicals Market
Bulk Chemicals
Di-Isobutylene Market
Bulk Chemicals
Middle East Ammonia Market
Bulk Chemicals
Muconic Acid Market
Bulk Chemicals
Mercaptan Scavenger Market
Bulk Chemicals
Global Lithium Carbonate Market
Bulk Chemicals
Global Naphthalene Derivatives Market
Bulk Chemicals
Cresylic Acid Market
Bulk Chemicals
Putty Powder Market
Bulk Chemicals
Mancozeb Market
Bulk Chemicals
Ammonium Bromide Market