
 Sodium Formate Market | 2026-2036
Sodium Formate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Formate Market Analysis
ISO 9001 certification is rotating as the baseline qualification for sodium formate suppliers bidding into European deicing and pharmaceutical chains. Henan Formate Group leverages captive carbon monoxide feedstock from regional syngas plants to sustain cost parity across industrial-grade batches. BASF SE anchors premium pharmaceutical-grade supply through Ludwigshafen-based quality systems that compete on documentation depth rather than volume. Jiangsu Formate Technologies specializes in membrane-cell sodium formate with reduced chloride carryover, a specification that dominates textile-dyeing accounts in East Asia.
Sodium formate is the sodium salt of formic acid, typically produced via the reaction of sodium hydroxide with carbon monoxide under controlled pressure and temperature to yield crystals with melting points near 253°C; its primary industrial purpose centers on serving as a reducing agent, buffering salt, and freeze-point depressant across process industries. Industrial-grade material occupies the largest volume position given its penetration into leather tanning and oilfield drilling fluids, while pharmaceutical-grade commands the deepest margin pool due to compendial testing burdens and limited qualified supply. Chemical manufacturing applications are expanding fastest as sodium formate replaces conventional reductants in certain catalytic hydrogen transfer reactions.
REACH registration in Europe and EPA TSCA Section 8(a) reporting in the United States both shape product standards by mandating impurity disclosure thresholds that filter out small-scale traders. China's GB standards under SAMR enforce chloride and sulfate ceilings that determine which plants can access domestic food-grade channels. Stakeholders must monitor how ECHA's evolving restriction proposals on formic acid derivatives could cascade into downstream sodium formate qualification requirements.
Market Dynamics
Membrane-electrolysis upgrades across Chinese chlor-alkali corridors are compressing chloride carryover in industrial-grade output, forcing legacy soda-ash based producers to absorb higher purification costs or exit REACH-eligible supply chains.
Growth Catalysts
- REACH-compliant leather tanning:Italian and Turkish tanneries are substituting sodium formate for conventional salts in chrome-reduction processes, pulling membrane-grade volumes from Shandong producers.
- Oilfield drilling fluid reformulation:Synthetic-based mud systems in North American shale plays require low-chloride formate brines to prevent formation damage, opening specification-grade demand.
- Dual carbon targets:China's MIIT environmental audits are accelerating capacity consolidation around carbon monoxide-fed membrane cells that reduce wastewater discharge intensity.
Market Restraints
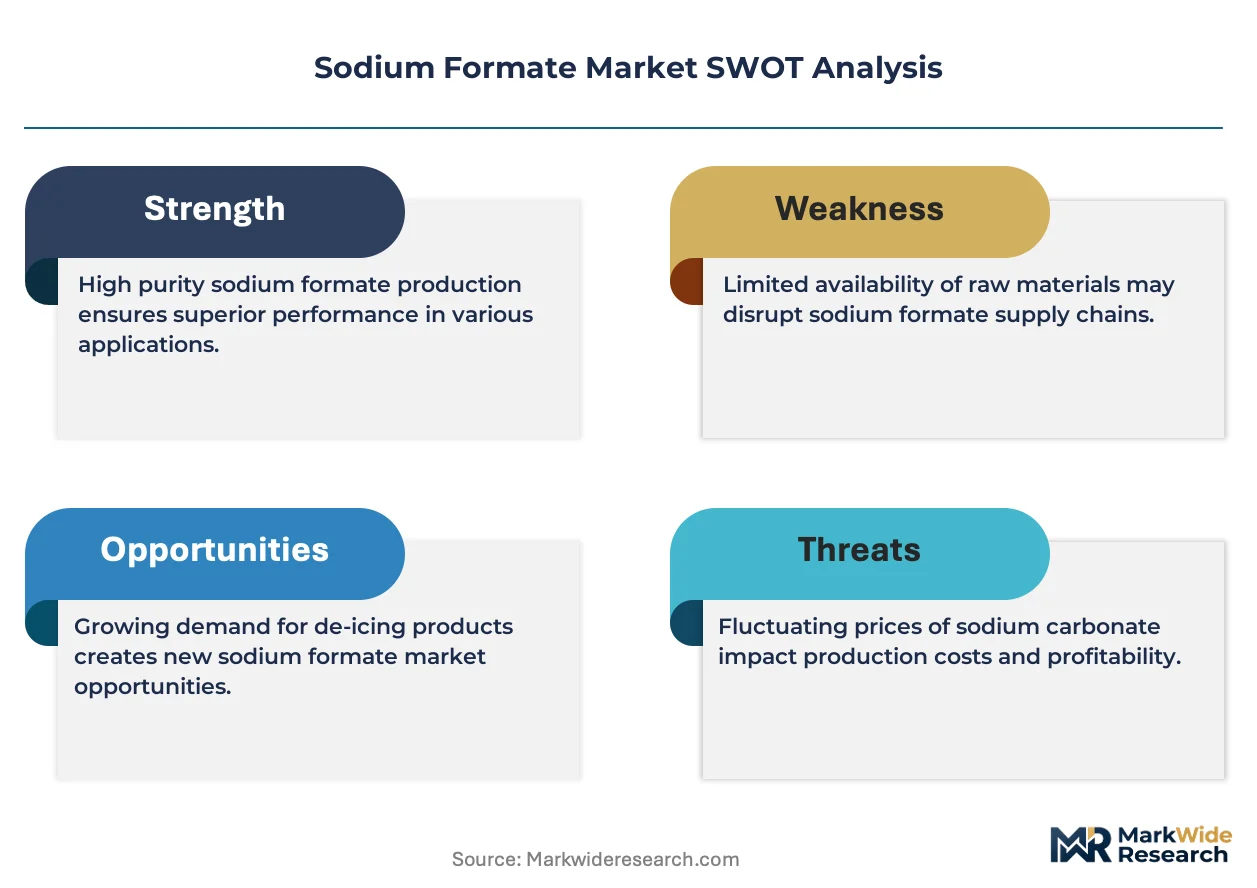
- Carbon monoxide feedstock concentration:Syngas supply in Henan and Shandong provinces dominates captive production economics, exposing non-integrated processors to volatile CO spot markets.
- Pharmaceutical-grade qualification timelines:EMA and FDA drug master file requirements extend certification cycles to 18-24 months, freezing out mid-scale entrants.
- Formic acid substitution:Direct formic acid dosing in certain textile dyeing applications bypasses sodium salt conversion, eroding volume in East Asian fabric processing.
Strategic Opportunities
- Food-grade channel expansion:SAMR's GB 1886.243 standard enforcement is disqualifying sulfate-heavy production lines, creating qualification vacancies for membrane-purified supply.
- Catalytic hydrogen transfer:Chemical manufacturing applications are absorbing pharmaceutical-grade formate as a reducing agent in palladium-catalyzed cross-couplings, displacing toxic stannane reagents.
- Biomass-derived syngas integration:Nordic pulp mills are piloting black liquor gasification to produce renewable carbon monoxide feedstock for formate synthesis.
Industry Challenges
- Membrane-cell engineering talent scarcity:Chlor-alkali process engineers with electrolyzer retrofit experience command premium compensation, constraining Chinese plant upgrade timelines.
- Legacy soda-ash asset strandedness:Conventional formate producers face write-down pressure as membrane economics render their purification train uncompetitive.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Formate Market |
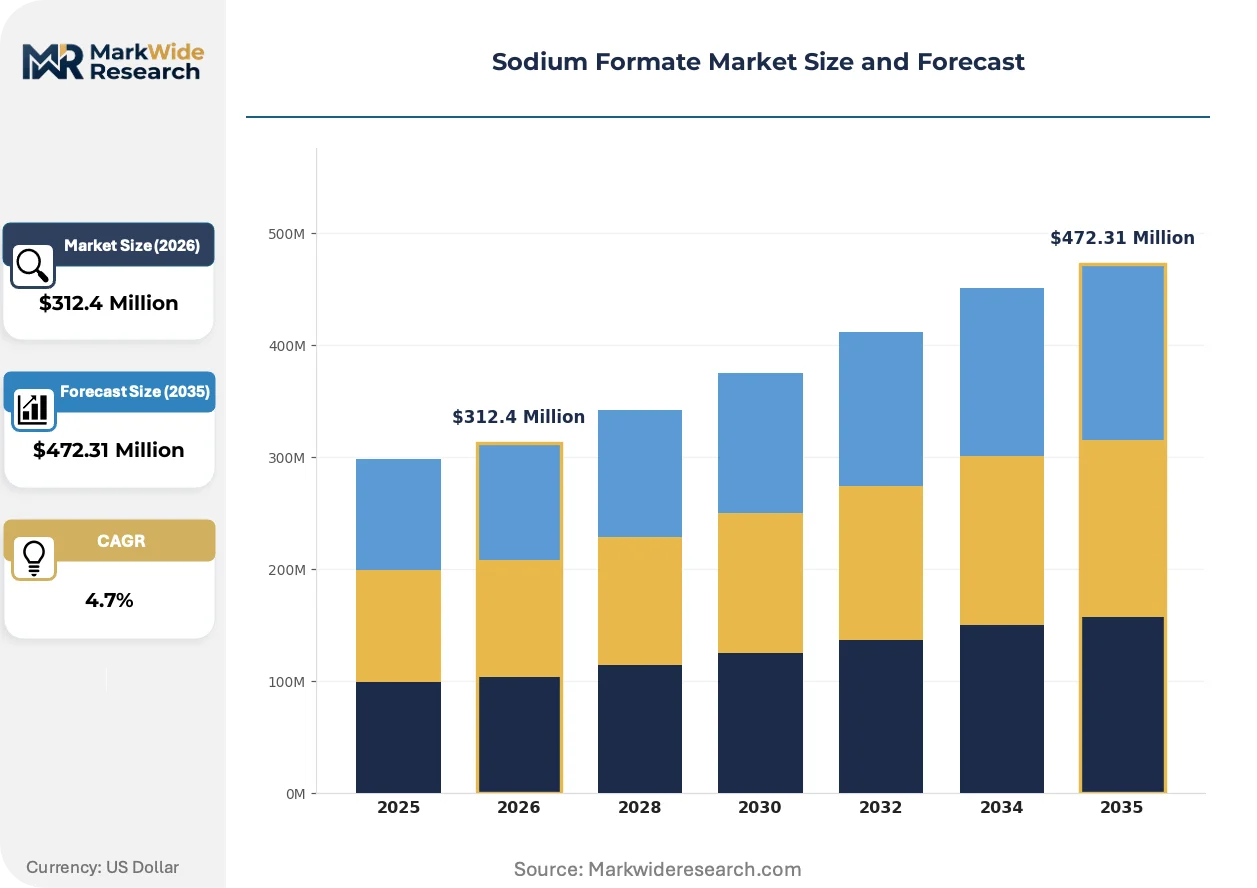
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Laboratory Grade, Pharmaceutical Grade Application: Deicing Agents, Textile Industry, Leather Tanning, Chemical Manufacturing End User: Food Industry, Automotive, Research Institutions, Pharmaceuticals Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | AnHui Formate Industry, Henan Formate Group, ChemChina Sodium Formate Co., Guangdong Formate Enterprise, Jiangsu Formate Technologies, Shandong Jiuan Chemical, Hubei Formate International, BASF SE, SinoPharm Sodium Formate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Formate Market Emerging Trajectories
Process intensification and regulatory disclosure mandates are compressing the viable technology set, while buyer consolidation in downstream leather and pharma verticals is amplifying certification requirements.
Membrane-electrolysis cell technology with reduced chloride carryover is displacing conventional soda-ash neutralization in industrial-grade production. Textile dyers in Zhejiang and Jiangsu provinces are rejecting high-chloride batches, forcing Shandong producers to accelerate membrane retrofits or forfeit East Asian fabric accounts. The technology is displacing legacy purification trains that relied on multi-stage recrystallization, collapsing unit capital requirements by half.
ECHA's evolving restriction proposals on formic acid derivatives are cascading into downstream sodium formate qualification burdens. REACH registrants must now disclose impurity thresholds below 100 ppm for certain transition metals, compelling suppliers to install ICP-MS analytical capability. Pharmaceutical-grade batches destined for European compounding pharmacies face the steepest documentation depth requirements.
Specification-driven procurement is consolidating vendor panels around ISO 9001-certified suppliers with captive carbon monoxide integration. Italian leather groups and Turkish tanneries are reducing qualified supplier lists from twelve to four, prioritizing membrane-grade producers with documented REACH compliance. The pattern is most visible across Mediterranean tanning clusters where brand-traceability requirements intersect with chemical safety mandates.
Sodium Formate Market Segmentation
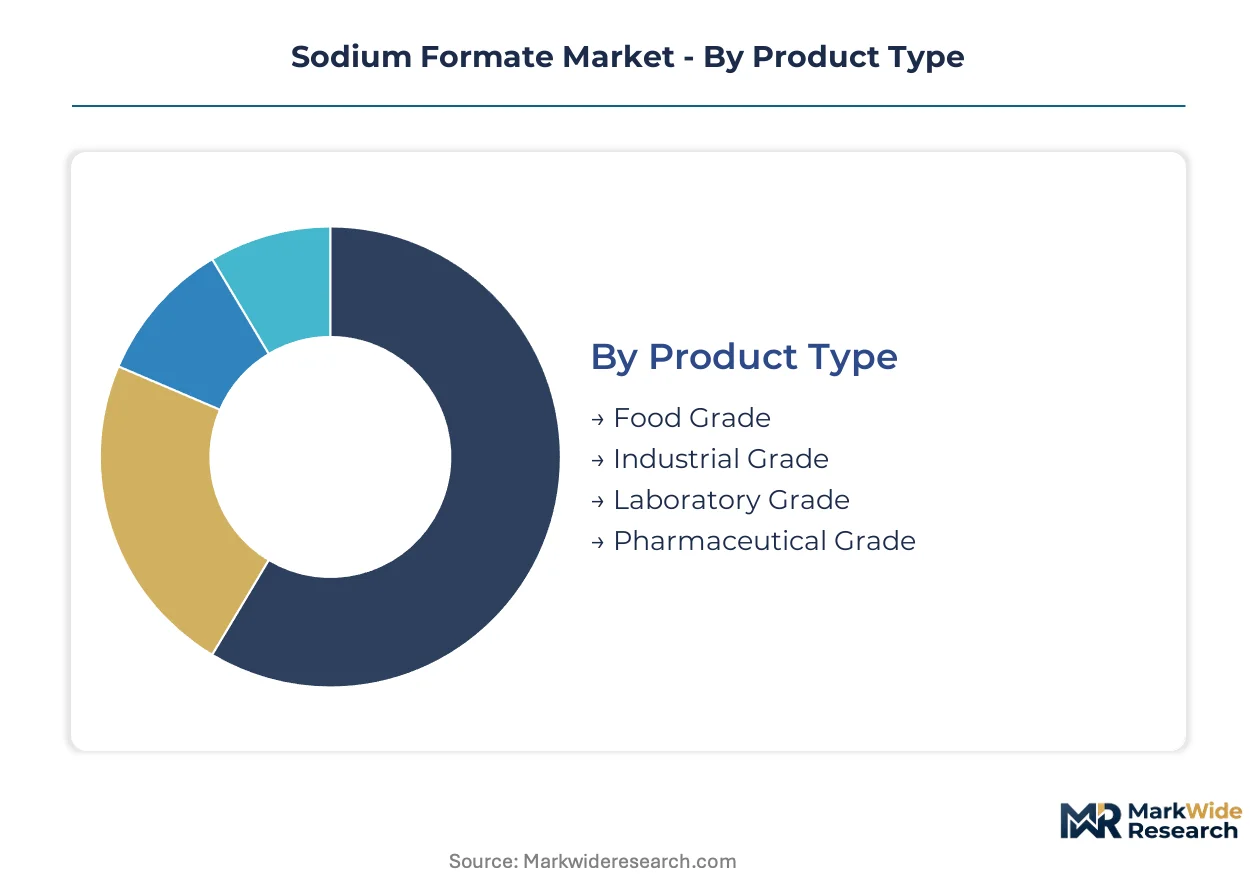
Sodium formate market segmentation reflects divergent purity requirements and regulatory burdens across end-use verticals. Grade-specific qualification timelines and application-driven specification thresholds create distinct competitive arenas with varying margin profiles and supplier concentration.
Product Type:
Industrial-grade volumes face acute substitution pressure from direct formic acid dosing in textile processing, while pharmaceutical-grade supply chains defend against biosynthetic reductant alternatives.
- Industrial Grade:Membrane-electrolysis output with chloride carryover below 500 ppm dominates leather tanning in Italian and Turkish tanneries. REACH-compliant batches from Shandong producers command premium pricing over soda-ash neutralized alternatives facing purification cost disadvantages.
- Pharmaceutical Grade:Compendial-grade material meeting USP-NF and EP monographs requires ICP-MS trace metal documentation below 100 ppm. EMA drug master file cycles extending 18-24 months freeze out mid-scale entrants and concentrate supply around Ludwigshafen-based quality systems.
- Food Grade:GB 1886.243 standard enforcement by SAMR disqualifies sulfate-heavy production lines, creating qualification vacancies for membrane-purified supply in Chinese food preservation applications.
- Laboratory Grade:ACS-certified batches for analytical reagent use carry moderate volume but require lot-level COA documentation that favors established chemical distributors.
Industrial Grade retains volume leadership; Pharmaceutical Grade holds the steepest expansion curve.
Application:
Cost-tier stratification separates specification-grade drilling fluid formulations from commodity deicing salt alternatives, with leather tanning occupying the mid-tier qualification intensity band.
- Leather Tanning:Chrome-reduction processes in Mediterranean tanneries absorb membrane-grade volumes as REACH-compliant formulations displace conventional salts. Italian leather groups consolidate vendor panels from twelve to four qualified suppliers.
- Chemical Manufacturing:Palladium-catalyzed cross-couplings deploy pharmaceutical-grade formate as a reducing agent, displacing toxic stannane reagents in fine chemical synthesis.
- Deicing Agents:Airport runway applications favor sodium formate over urea for reduced aquatic toxicity, though price sensitivity limits penetration against bulk salt in municipal road markets.
- Textile Industry:Zhejiang and Jiangsu dyers reject high-chloride batches, forcing Shandong producers into membrane retrofits or regional market forfeiture.
Leather Tanning anchors current volume absorption; Chemical Manufacturing gains share fastest through catalytic hydrogen transfer adoption.
End User:
Customer-type concentration amplifies certification requirements, with pharmaceutical compounders demanding documentation depth that excludes trader intermediaries.
- Pharmaceuticals:FDA and EMA drug master file requirements extend qualification cycles, freezing supply chains around established producers with dedicated regulatory affairs capacity.
- Automotive:Synthetic-based mud systems in North American shale plays require low-chloride formate brines to prevent formation damage, opening specification-grade demand from oilfield service companies.
- Food Industry:Preservative applications in processed meat and bread sectors face SAMR GB standard enforcement that filters out sulfate-heavy production lines.
- Research Institutions:Academic procurement prioritizes lot-level COA availability and ISO 17025-certified testing over price minimization.
Pharmaceuticals concentrate margin capture; Automotive expands most quickly through drilling fluid reformulation.
Distribution Channel:
Supply concentration in Shandong and Henan provinces shapes channel viability, with direct sales dominating membrane-grade volumes and distributor networks handling commodity grades.
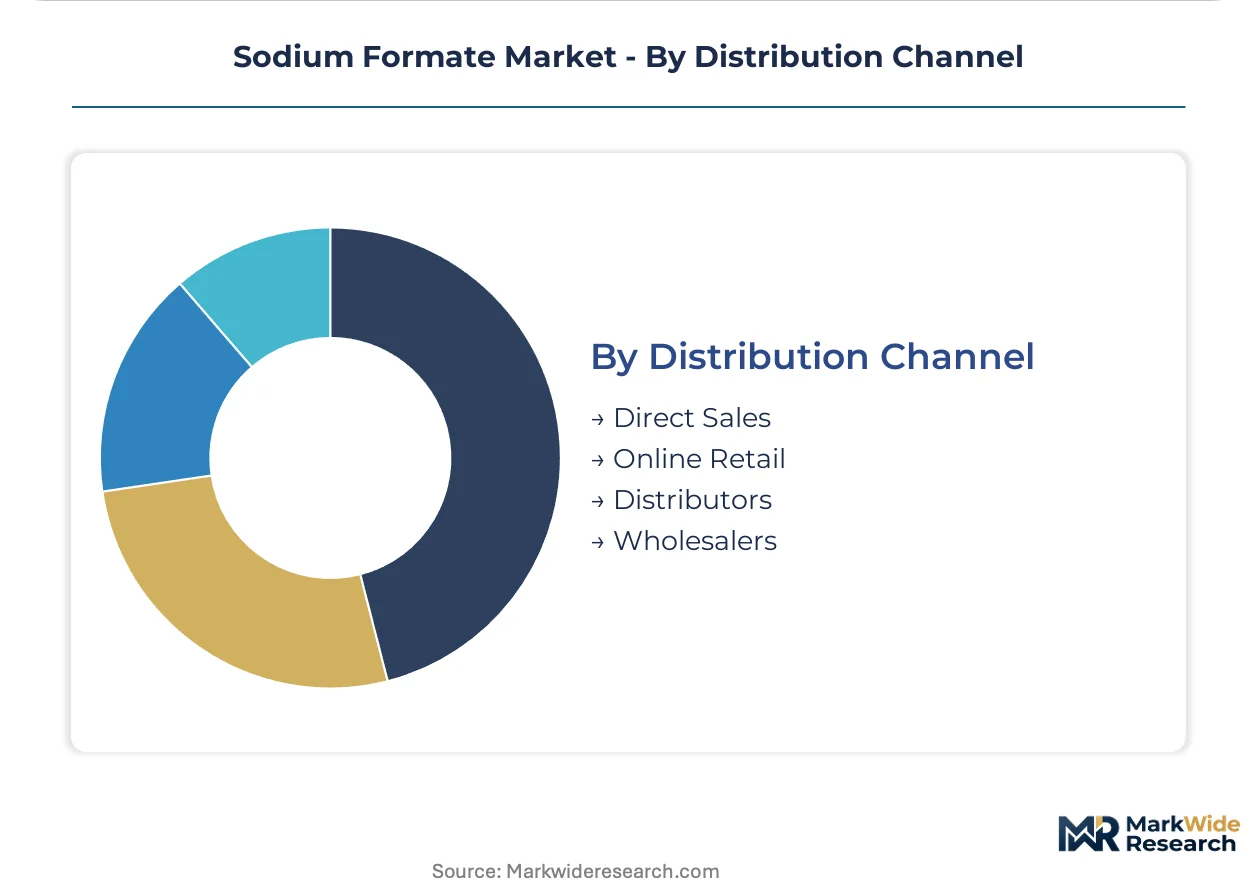
- Direct Sales:Italian leather groups and Turkish tanneries procure membrane-grade volumes through mill-direct contracts with documented REACH compliance and batch traceability.
- Distributors:Established chemical distributors with ISO 9001 certification and ICP-MS analytical capability intermediate pharmaceutical-grade supply to European compounding pharmacies.
- Wholesalers:Bulk industrial-grade volumes for deicing and oilfield applications move through regional wholesalers with storage infrastructure in North American and European port zones.
- Online Retail:Laboratory-grade and small-package industrial grades reach research institutions and mid-scale processors through specialized chemical e-commerce platforms.
Direct Sales commands premium-grade volume; Distributors capture the steepest margin expansion through qualification-intensive intermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance mandates and China's dual carbon targets are redirecting supply chain investment toward membrane-electrolysis capacity. Regional demand patterns diverge sharply between specification-grade pharmaceutical absorption and commodity industrial volumes.
China
Shandong and Henan provinces concentrate membrane-cell sodium formate output feeding leather tanning and textile dyeing accounts. MIIT environmental audits are accelerating capacity consolidation around carbon monoxide-fed electrolyzer upgrades that reduce wastewater discharge. The Shandong chemical corridor now hosts integrated chlor-alkali plants with captive formate synthesis.
Germany
Ludwigshafen-based quality systems anchor premium pharmaceutical-grade supply chains serving EMA-registered compounders. ECHA's evolving restriction proposals on formic acid derivatives are cascading into downstream documentation burdens that favor established producers with ICP-MS analytical capability. BASF SE exemplifies the documentation-depth competitive vector.
Italy
Mediterranean tanning clusters in Tuscany and Veneto are absorbing membrane-grade volumes as REACH-compliant chrome-reduction processes displace conventional salts. Italian leather groups have consolidated vendor panels from twelve to four qualified suppliers. Solofra and Santa Croce sull'Arno remain the dominant processing hubs.
Turkey
Tuzla and Menemen industrial zones host tanneries substituting sodium formate for conventional salts under brand-traceability requirements intersecting with chemical safety mandates. Turkish processors prioritize membrane-grade producers with documented REACH compliance. Direct mill contracts now dominate procurement patterns.
United States
North American shale plays in the Permian and Bakken formations require low-chloride formate brines for synthetic-based mud systems. EPA TSCA Section 8(a) reporting mandates filter out small-scale traders from specification-grade supply chains. Oilfield service companies are opening new demand channels for purified industrial grades.
Sodium Formate Market Vendor Landscape
Player mix skews toward Chinese chlor-alkali integrators and European pharmaceutical-grade specialists. The vendor base separates into three tiers: membrane-electrolysis producers with captive carbon monoxide feedstock, legacy soda-ash neutralizers facing purification cost disadvantages, and documentation-intensive pharmaceutical-grade suppliers. Competitive moves concentrate on capacity consolidation around environmental compliance upgrades and REACH registration maintenance.
Among Chinese membrane-cell specialists, Jiangsu Formate Technologies and Shandong Jiuan Chemical exemplify the electrolyzer-upgrade archetype. Henan Formate Group occupies a position within the captive-syngas tier. BASF SE anchors the premium pharmaceutical-grade segment. AnHui Formate Industry and ChemChina Sodium Formate Co. sit within the scale-driven industrial-grade cluster.
| Leading Market Players |
|---|
| AnHui Formate Industry |
| Henan Formate Group |
| ChemChina Sodium Formate Co. |
| Guangdong Formate Enterprise |
| Jiangsu Formate Technologies |
| Shandong Jiuan Chemical |
| Hubei Formate International |
| BASF SE |
| SinoPharm Sodium Formate |
| Others |
Supply Flow & Price Mechanics
Membrane-electrolysis substitution of legacy soda-ash neutralization simultaneously concentrates production in Shandong and Henan provinces and compresses pricing power for REACH-compliant batches. This technical transition rewards integrated chlor-alkali plants with captive carbon monoxide feedstock while stranding conventional producers with uncompetitive purification economics.
Pricing Analysis
Certification level creates the primary spread across sodium formate tiers, with membrane-grade material commanding substantial premia over soda-ash neutralized alternatives. Three-tier pricing structure across pharmaceutical, industrial, and food-grade levels reflects differential documentation burdens, with ISO 9001-certified batches from Shandong producers capturing margin premiums in Italian leather accounts. Cost compression in industrial-grade supply is intensifying because textile dyers in Zhejiang and Jiangsu provinces reject high-chloride batches. Deicing and oilfield service buyers exhibit the highest price sensitivity, while pharmaceutical compounders prioritize documentation depth over unit cost minimization.
Supply Chain Analysis
Port congestion on Shanghai-Ningbo and Qingdao lanes elevates inbound logistics costs for membrane-cell equipment and analytical instrumentation imports. Supply concentrates in China, Germany, and Turkey, with Shandong chemical corridor hosting integrated chlor-alkali plants that source carbon monoxide from regional syngas facilities. Raw material dependencies rest on carbon monoxide feedstock, sodium hydroxide from membrane cells, and specialized ion-exchange membranes. Single-source vulnerability around membrane-electrolysis engineering talent constrains upgrade timelines. Distribution runs through direct mill contracts for membrane-grade volumes and established chemical distributors for pharmaceutical-grade intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sodium formate incumbents must defend against direct formic acid substitution in textile dyeing applications, a threat that erodes volume in East Asian fabric processing and pressures industrial-grade pricing.
For Market Incumbents: Compound membrane-cell capacity advantages through backward integration into captive syngas production in Henan and Shandong provinces. Accelerate ICP-MS analytical capability installation to meet ECHA's evolving trace metal disclosure thresholds below 100 ppm. Lock in mill-direct contracts with Italian leather groups before vendor panel consolidation completes. For New Entrants and Emerging Players: FDA drug master file fast-track positions emerging players to capture pharmaceutical-grade qualification vacancies as EMA cycles freeze out mid-scale competitors. Target food-grade channels in China where SAMR's GB 1886.243 standard enforcement disqualifies sulfate-heavy legacy production lines. Pursue joint development agreements with Nordic pulp mills piloting biomass-derived syngas for renewable carbon monoxide feedstock. For Investors and Strategic Acquirers: Capital is best deployed toward membrane-electrolysis specialists with documented REACH registration and captive carbon monoxide integration across the analysis window. Acquisition targets should demonstrate verified chlor-alkali retrofit execution capability and established mill-direct relationships with Mediterranean tanning clusters. Monitor ECHA restriction proposal advancement on formic acid derivatives as the critical inflection signal for downstream qualification burden intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane-Electrolysis Capacity Expansion | Shandong producers with integrated chlor-alkali feedstock capture REACH-compliant leather tanning demand from Italian tanneries. |
| Backward Integration into Syngas | Henan Formate Group's captive carbon monoxide supply sustains cost parity against volatile CO spot market exposure. |
| ICP-MS Analytical Capability Installation | Documentation depth for EMA drug master files concentrates pharmaceutical-grade supply around Ludwigshafen-based quality systems. |
| Food-Grade Channel Qualification | Membrane-purified supply captures SAMR GB 1886.243 vacancies as sulfate-heavy production lines face disqualification. |
| Biomass-Derived Syngas Pilot Partnership | Nordic pulp mill black liquor gasification opens renewable carbon monoxide pathways for formate synthesis. |
Methodological Framework
Desk research of customs/trade data, ACC/Cefic chemical industry reports, and SEC 10-K filings preceded structured interviews with chlor-alkali plant managers, leather tanning procurement leads, pharmaceutical regulatory affairs directors, and oilfield service chemical supply specialists. Primary intelligence combined with secondary validation through ECHA registration databases and SAMR GB standard enforcement records. Bottom-up capacity modeling triangulated against top-down end-use demand estimates across leather tanning, oilfield drilling fluids, and pharmaceutical manufacturing segments.
Variance decomposition across grade tier, end-use industry, and regional production hub dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume absorption rates applied to price trajectory assumptions for membrane-grade versus soda-ash neutralized material. Industry-specific inputs included MIIT environmental audit timelines for Chinese capacity consolidation and EMA drug master file cycle duration for pharmaceutical-grade qualification modeling.
Underlying assumptions cover continued REACH compliance enforcement in European leather tanning, MIIT dual carbon target adherence in Shandong chemical corridor, and sustained oilfield drilling fluid reformulation in North American shale plays, with deviation risk concentrated in ECHA restriction proposal outcomes and carbon monoxide feedstock price volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Valeric Acid Market
Bulk Chemicals
China Starch and Starch Derivatives Market
Bulk Chemicals
Cesium Hydroxide Market
Bulk Chemicals
Aluminum Potassium Sulfate Market
Bulk Chemicals
Carbonate Market
Bulk Chemicals
Sodium Nitrate Market
Bulk Chemicals
Methionine Market
Bulk Chemicals
Global Naphthenic Base Oil Market
Bulk Chemicals
North America Vinyl Chloride Monomer Market
Bulk Chemicals
Global Vinyl Chloride Monomer Market
Bulk Chemicals
Asia Pacific Dry PVC Compound Market
Bulk Chemicals
Commodity Plastics Market
Bulk Chemicals
ASEAN Sulfur Market
Bulk Chemicals
Zinc Carbonate Market
Bulk Chemicals
Calcium Bromide Market
Bulk Chemicals
Global Quinine Sulphate Market