
 Commodity Plastics Market | 2026-2036
Commodity Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Commodity Plastics Market Intelligence
Europe's REACH regulation, with its stringent chemical registration requirements, is consolidating the supplier base for polymer additives. This environment favors large-scale producers like Dow Inc., which leverages its integrated production for polyethylene to meet global demand. BASF SE differentiates with a portfolio of specialized polymer compounds, while SABIC anchors its competitive position through significant feedstock control in the Middle East.
Commodity plastics are high-volume synthetic polymers produced to standardized specifications, such as a defined Melt Flow Index (MFI) for processing. Their primary purpose is enabling cost-effective mass production of items where price is a key selection criterion. Polyethylene and polypropylene account for the majority of production volume due to their versatility. The packaging application remains the dominant end-use, consuming a substantial share of total output for films and containers.
Market access and product design are heavily influenced by a complex web of national and regional regulations. In the United States, the EPA sets emissions standards for polymer manufacturing facilities. Concurrently, the EU's ECHA enforces rules under the Green Deal that mandate recycled content, while China's MEE sets GB standards for product quality. Producer decisions will increasingly hinge on balancing the cost advantages of virgin feedstocks against mounting regulatory and consumer pressure for circularity.
Market Dynamics
The central dynamic in the commodity plastics market is the escalating tension between the established, cost-efficient production of virgin polymers from fossil feedstocks and the global regulatory push for circular economy models that mandate increased use of recycled materials.
Growth Catalysts
- Packaging Sector Expansion:Continued growth in e-commerce and packaged food consumption, particularly in developing economies, sustains high-volume demand for polyethylene films and polypropylene containers.
- Regulatory Mandates for Recycled Content:The EU Green Deal and similar policies in states like California create legally binding targets for recycled plastic in products, directly stimulating investment in recycling infrastructure and demand for post-consumer resin.
- Industrialization in China:China's vast manufacturing base for consumer electronics, automotive parts, and household appliances remains a primary consumer of standard polymers, anchoring a significant portion of global production volume.
Market Restraints
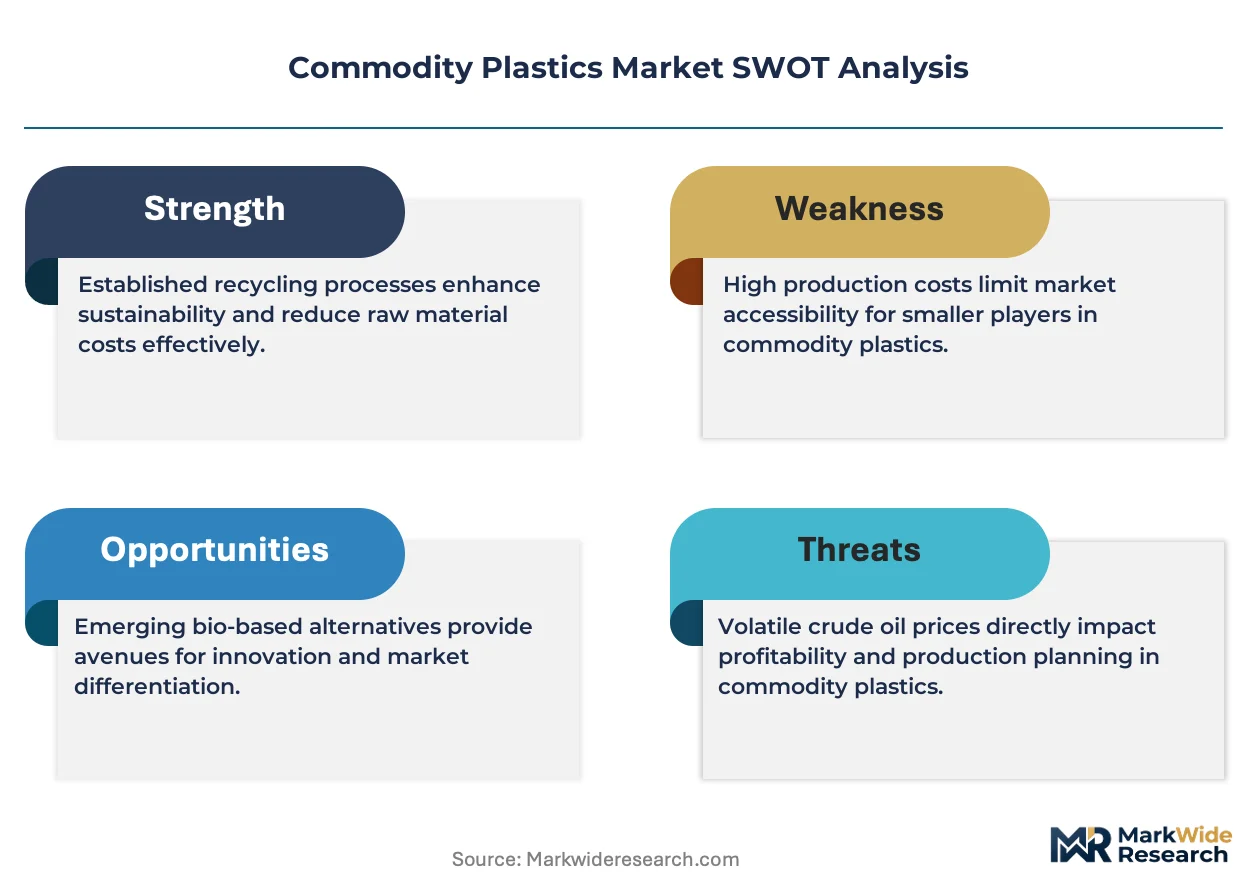
- Feedstock Price Volatility:The market's profitability is directly tied to the fluctuating prices of crude oil and natural gas, creating significant cost instability for producers of virgin polyethylene and polypropylene.
- Recycled Polymer Performance Gaps:Mechanically recycled plastics often exhibit inferior properties compared to virgin materials, limiting their use in demanding applications such as high-barrier food packaging or medical devices.
- Complex Chemical Regulations:Compliance with chemical control laws like Europe's REACH imposes substantial administrative and testing costs on producers, particularly for additives used to achieve specific polymer properties.
Strategic Opportunities
- Advanced Chemical Recycling:Technologies like pyrolysis and gasification offer a path to convert mixed plastic waste back into feedstock, creating high-quality, circular polymers that can overcome the limitations of mechanical recycling.
- Electric Vehicle Components:The automotive industry's transition to electric vehicles opens new applications for lightweight, durable commodity polymers in battery enclosures, interior trims, and charging components.
- Bio-based Feedstocks:The development of bio-polyethylene and bio-polypropylene from renewable sources such as sugarcane or corn presents an opportunity to produce polymers with a lower carbon footprint, appealing to sustainability-focused brands.
Industry Challenges
- Waste Collection Infrastructure Deficits:A primary operational hurdle is the lack of harmonized and efficient collection, sorting, and baling systems for post-consumer plastic waste on a scale that can reliably feed large chemical recycling plants.
- Recycled Content Verification:The absence of a single, globally accepted standard for certifying and tracing recycled content through complex supply chains creates friction and risks of greenwashing, undermining market confidence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commodity Plastics Market |
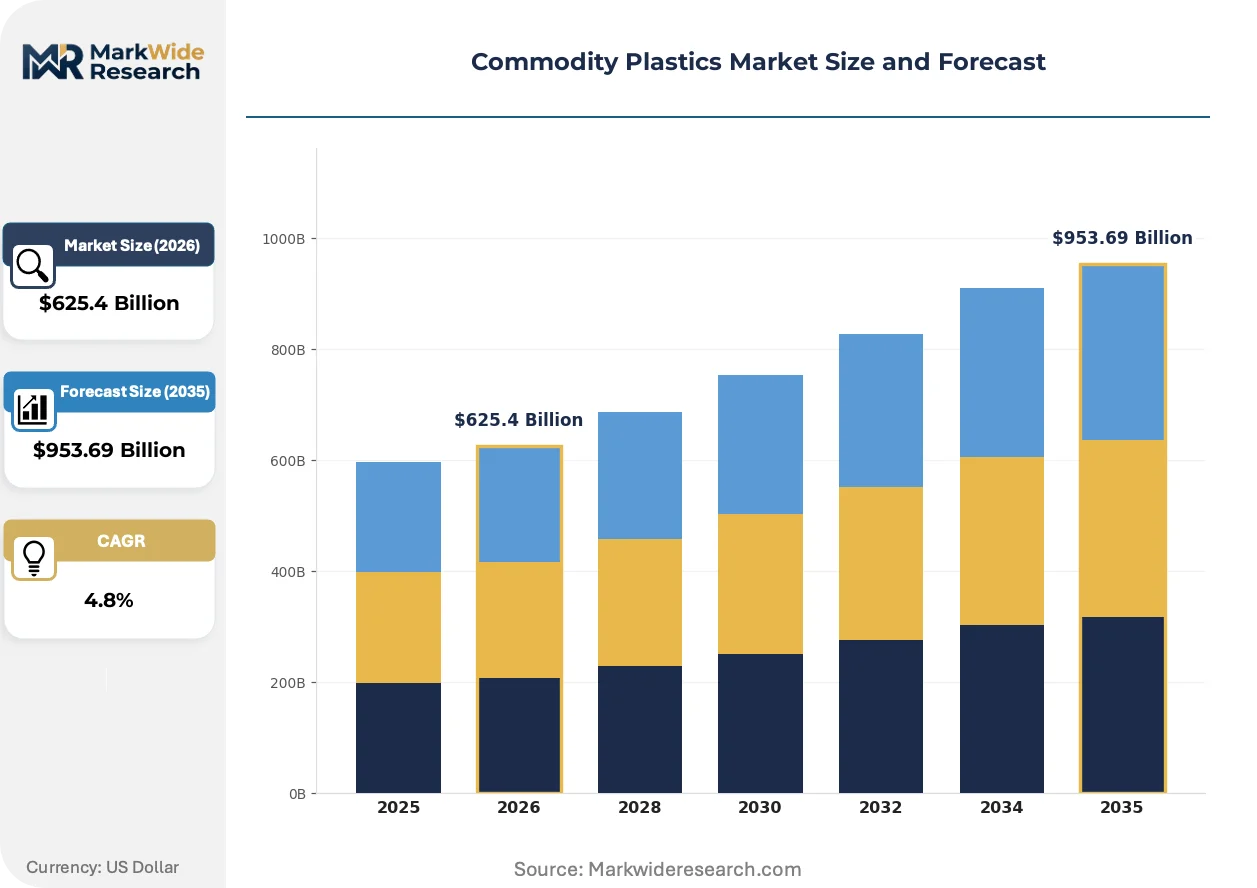
| Market Size in 2026 | $625.4 Billion |
| Market Size in 2035 | $953.69 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene Application: Pipes, Packaging, Automotive Components, Consumer Goods End User: Construction, Automotive, Electronics, Food & Beverage Form: Granules, Sheets, Films, Fibers |
| Companies Covered | Exxon Mobil Corporation, BASF SE, SABIC, Dow Inc., LyondellBasell Industries, INEOS Group, Formosa Plastics Corporation, Sumitomo Chemical Co. Ltd., China Petroleum & Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commodity Plastics Market Strategic Shifts & Innovations
Digitalization and circularity are fundamentally reconfiguring the operational logic of the commodity plastics industry. These forces are shifting the focus from pure volume and cost to include verifiable sustainability metrics and process intelligence as key competitive differentiators.
Digital twin technology creates a virtual, real-time replica of a polymer production line. Major producers and compounders are adopting this to simulate process adjustments, optimize energy consumption, and predict final polymer properties like Melt Flow Index before production. This data-driven approach is electrifying process control, enabling quicker grade changes and reducing the output of off-spec material.
The European Union's Corporate Sustainability Reporting Directive (CSRD) imposes mandatory, audited reporting on circularity performance. This regulation compels polymer manufacturers to provide transparent data on recycled content, end-of-life management, and lifecycle carbon footprint. The packaging and consumer goods segments are most impacted, accelerating the redesign of products to improve recyclability and meet disclosure rules.
A shift toward performance-based procurement is altering how large buyers source polymers. Instead of purchasing solely based on standard technical data sheets, major brand owners are issuing specifications that include certified recycled content percentages and maximum carbon footprints. This trend is most advanced in the European food and beverage sector, where consumer-facing sustainability goals drive procurement decisions.
Commodity Plastics Market Segmentation
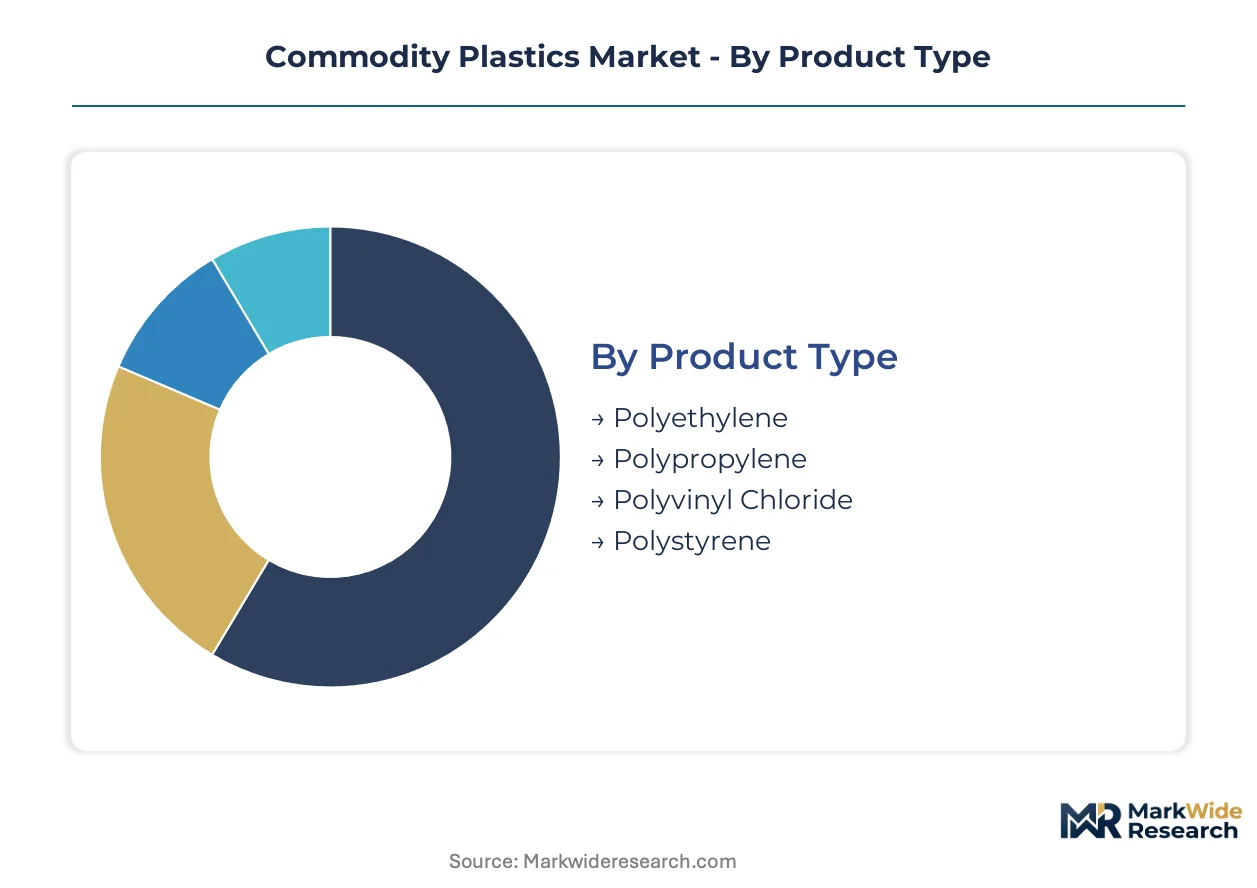
The commodity plastics market is a foundational industry, and its segmentation clarifies the diverse material properties, demand drivers, and competitive dynamics. Understanding these distinct segments guides strategic investment, product development efforts, and market access strategies for manufacturers and suppliers.
Product Type:
The market for commodity plastics is delineated by product type, reflecting the inherent material properties and their suitability for either standalone applications or integration into complex systems.
- Polyethylene:Polyethylene is a versatile thermoplastic polymer, known for its high ductility and chemical resistance. It exists in various densities (HDPE, LDPE, LLDPE) influencing its rigidity. Demand concentrates heavily in food packaging films and containers across Asia-Pacific, driven by e-commerce expansion and consumer goods consumption.
- Polypropylene:Polypropylene is a semi-crystalline thermoplastic, offering excellent strength-to-weight ratio and resistance to fatigue. It is easily molded and processed into various forms. The automotive sector in Europe drives significant demand for polypropylene in interior and under-the-hood components, emphasizing lightweighting for fuel efficiency.
- Polyvinyl Chloride:Polyvinyl Chloride (PVC) is a rigid or flexible polymer, valued for its durability and flame retardancy, predominantly used in construction pipes and window profiles.
- Polystyrene:Polystyrene is a transparent thermoplastic with good insulation properties, primarily found in disposable packaging and insulation panels.
Volume placements concentrate in Polyethylene; the faster expansion belongs to Polypropylene.
Application:
Application segmentation highlights where the largest volumes of commodity plastics are consumed, reflecting diverse functional requirements across industries.
- Packaging:Packaging applications utilize commodity plastics for protective barriers, containment, and preservation of goods. It encompasses films, bottles, and rigid containers. Demand for packaging materials is substantial in the food and beverage sector globally, driven by convenience trends and extended shelf-life requirements.
- Automotive Components:Automotive components leverage commodity plastics for lightweighting, cost reduction, and design flexibility in vehicle manufacturing. This includes interior trims and under-hood parts. The shift towards electric vehicles in Germany and China is accelerating demand for advanced polymer composites in battery enclosures and structural elements.
- Pipes:Pipes utilize commodity plastics like PVC and PE for water, drainage, and gas distribution infrastructure, valued for corrosion resistance.
- Consumer Goods:Consumer goods encompass a broad range of products, from household items to toys, where commodity plastics offer cost-effective manufacturing solutions.
Packaging applications command the largest share; automotive components are expanding most quickly.
End User:
End-user classification groups demand by the primary industry that procures and integrates commodity plastics into their final products.
- Food & Beverage:The Food & Beverage sector relies on commodity plastics for hygienic, protective, and convenient packaging solutions. This includes bottles, trays, and flexible pouches. Rising disposable incomes in emerging markets like India fuel significant consumption of packaged foods, driving demand for cost-effective polymer solutions.
- Construction:The Construction industry uses commodity plastics for durable and lightweight materials in pipes, insulation, and window frames. PVC and polyethylene are widely employed. Infrastructure development projects in China and Southeast Asia sustain high demand for plastic pipes and profiles, supporting urban expansion.
- Automotive:The Automotive industry integrates commodity plastics into vehicle interiors, exteriors, and engine components, prioritizing weight reduction and impact resistance.
- Electronics:The Electronics sector uses commodity plastics for housings, insulations, and internal components, valuing their electrical properties and moldability.
Food & Beverage represents a dominant end-user segment; the Automotive sector shows significant growth potential.
Form:
Segmentation by form details the physical state in which commodity plastics are supplied and processed, influencing manufacturing methods and final product characteristics.
- Granules:Granules are the most common primary form of commodity plastics, supplied as small pellets for subsequent processing via injection molding, extrusion, or blow molding. Their high volume usage across all end-user industries, particularly in China's manufacturing base, makes them foundational for mass production.
- Films:Films are thin, flexible sheets of plastic, typically produced by extrusion or blown film processes, offering barrier properties and transparency. The packaging industry, especially for food and consumer goods in Europe, drives substantial demand for films due to their versatility and protective qualities.
- Sheets:Sheets are flat, rigid or semi-rigid plastic forms, used in thermoforming and fabrication for applications like signage, glazing, and automotive parts.
- Fibers:Fibers are fine, thread-like strands of polymer, woven into textiles or non-wovens for applications in apparel, carpeting, and technical fabrics.
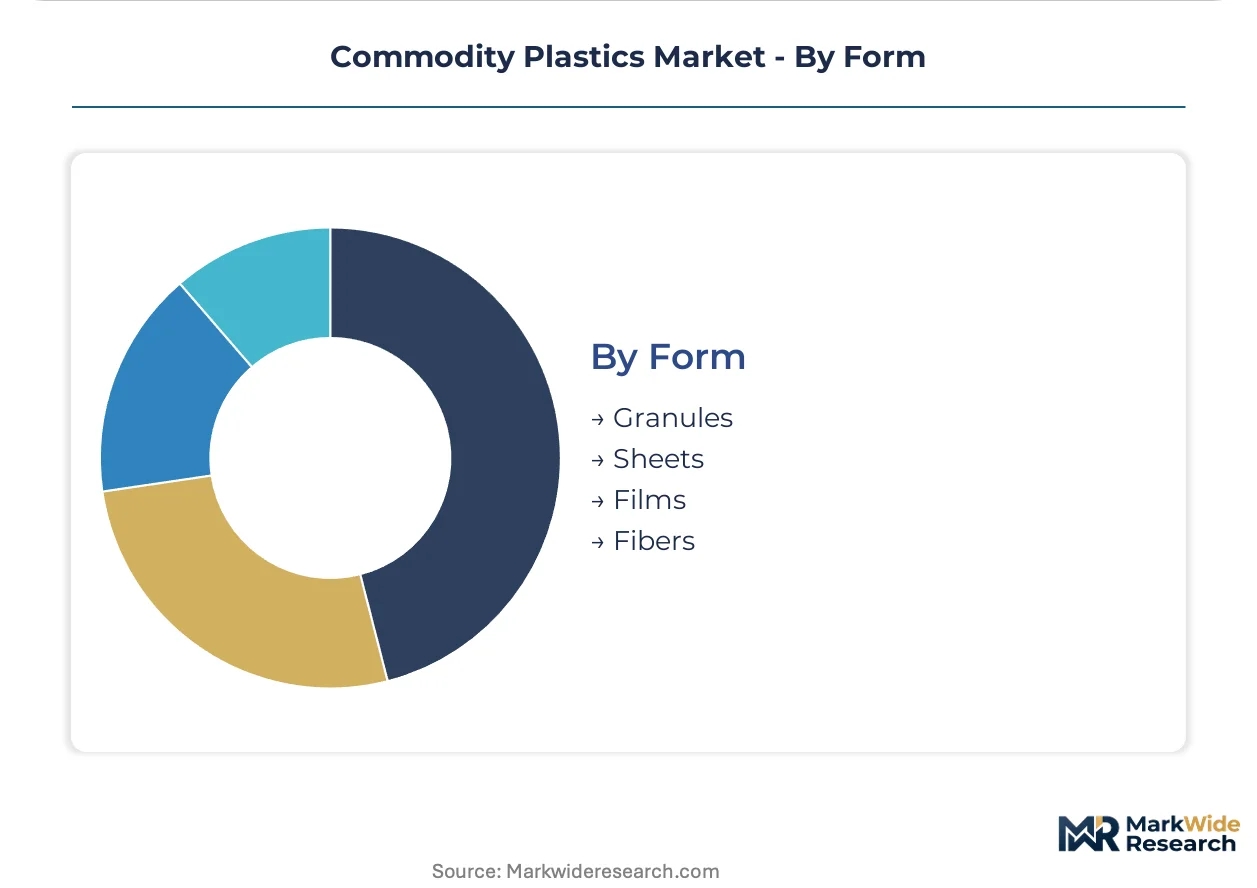
Granules represent the fundamental input form; Films exhibit strong demand tied to packaging innovations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commodity plastics production often benefits from strategic industrial zones globally. China's special economic zones, for example, have significantly boosted manufacturing output. These concentrated areas attract investment, facilitating large-scale polymer production and consumption across diverse end-use sectors.
China
China's vast manufacturing base drives substantial demand for standard polymers in consumer electronics and household appliances. The MEE enforces GB standards for product quality across the plastics industry, impacting local and imported materials. Production gravity centers on the Yangtze River Delta, facilitating cost-effective mass production and distribution for global markets.
United States
The United States market consumes significant commodity plastics for packaging and automotive applications, driven by domestic consumption. The EPA sets stringent emissions standards for polymer manufacturing facilities, influencing operational costs. Petrochemical production on the Gulf Coast provides abundant feedstock, supporting large-scale polymer synthesis for various end-uses.
Germany
Germany's automotive sector drives demand for polypropylene in lightweighting initiatives and interior components, seeking performance materials. The EU's ECHA enforces REACH regulations, consolidating the polymer additive supplier base towards larger entities. Chemical parks like those in Ludwigshafen house integrated production facilities, fostering innovation in specialized compounds and circularity.
India
India's rising disposable incomes fuel significant consumption of packaged foods, increasing demand for cost-effective polymer solutions across urban centers. The BIS sets national standards for plastic products, ensuring quality and safety for local manufacturing. Gujarat's industrial corridors are expanding petrochemical capacities, supporting domestic polymer supply for a growing market.
Saudi Arabia
Saudi Arabia leverages significant feedstock control to anchor its competitive position in commodity plastics production and export. The SFDA ensures product safety and quality for polymers produced in the kingdom, facilitating international trade. Jubail Industrial City hosts massive petrochemical complexes, enabling efficient, large-scale polymer export to key Asian markets.
Commodity Plastics Market Key Industry Players
China-based producers anchor one tier; European specialists hold another. The commodity plastics market exhibits a tiered structure, with large integrated players dominating primary polymer production. Smaller, specialized compounders differentiate through niche applications and additive formulations. This environment fosters both scale-driven competition and innovation-led differentiation among integrated petrochemical giants and specialized compounders. Capacity expansion initiatives and portfolio diversification remain dominant competitive moves.
Within the integrated petrochemical giants tier, Dow Inc. and SABIC exemplify scale-driven production and global market reach. Dow Inc. leverages its integrated production for polyethylene to meet global demand, reflecting a strategy of broad market penetration across diverse applications. BASF SE, a German-based chemical company, occupies a position focused on specialized polymer compounds, differentiating its offering through advanced material science and tailored solutions. These companies anchor significant portions of the global commodity plastics supply chain, influencing pricing dynamics and material availability for downstream industries.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| BASF SE |
| SABIC |
| Dow Inc. |
| LyondellBasell Industries |
| INEOS Group |
| Formosa Plastics Corporation |
| Sumitomo Chemical Co. Ltd. |
| China Petroleum & Chemical Corporation |
| Others |
Cost & Logistics Intelligence
Crude oil and natural gas prices, as primary feedstocks for virgin polymers, cascade directly through the commodity plastics supply chain, influencing downstream product pricing tiers. This foundational market dynamic dictates cost structures for producers and ultimately impacts procurement decisions for end-users globally.
Pricing Analysis
Lead-time-driven pricing offers premiums for immediate availability, while long-term contracts secure volume discounts for commodity plastics. The dominant pricing model is a hybrid of commodity spot pricing and contract-based long-term offtake agreements. Price differentiation stems from quality grade, particularly for specialized polymer compounds, and volume scale for large industrial buyers. Pricing softness reflects intense competition among producers and the increasing availability of lower-cost recycled alternatives. The packaging sector exhibits the most price sensitivity, while automotive components prioritize performance over absolute cost.
Supply Chain Analysis
Direct-to-compounder channels and large-scale distributors manage the flow of commodity plastics from major producers. Geographic supply concentration exists in China, the US Gulf Coast, and Saudi Arabia, leveraging abundant feedstock and established infrastructure. The supply chain relies heavily on crude oil and natural gas as raw material inputs for virgin polymer production. Feedstock price volatility represents a significant structural risk for producers. The distribution model primarily involves direct sales from integrated petrochemical giants to large industrial converters, supplemented by regional distributors for smaller buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is currently engaged in a vertical-integration race, with major players pursuing upstream feedstock control and downstream recycling infrastructure to secure future supply and meet circularity demands.
For Market Incumbents:
Anticipate continued regulatory pressure for recycled content, particularly from the EU Green Deal, by investing in advanced chemical recycling technologies. Optimize existing production capacities to reduce energy consumption and enhance cost efficiency against fluctuating feedstock prices. Diversify feedstock sources beyond traditional fossil fuels by exploring bio-based alternatives to mitigate geopolitical supply risks. Develop a portfolio of certified circular polymers to address mounting consumer and brand owner demand for sustainable solutions.
For New Entrants and Emerging Players:
Capture white-space opportunities in specialized recycled content applications, particularly for high-performance packaging and automotive parts in Europe. Target the nascent bio-based polymer segment with innovative materials offering verifiable lower carbon footprints. The most penetrable segment lies in providing traceable, high-quality post-consumer resins to brands with ambitious sustainability targets. A focused go-to-market angle involves collaborating directly with waste management companies to secure reliable feedstock for advanced recycling processes.
For Investors and Strategic Acquirers:
Distressed-cycle entries favor technology providers in advanced chemical recycling, particularly in Europe, as regulatory mandates accelerate demand for circular solutions. Long-term viability hinges on companies demonstrating verifiable progress towards circular economy models and reduced carbon intensity. Acquisition targets should include firms with proven intellectual property in pyrolysis or gasification, or those with established waste collection and sorting infrastructure. The signal to watch is the consistent enforcement of recycled content mandates across major economies.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Circular Polymers | Increases supply of sustainable materials, addressing regulatory mandates and brand owner demand for recycled content. |
| Backward Integration into Feedstock | Secures raw material supply, mitigating price volatility and enhancing cost competitiveness for polymer producers. |
| Investment in Advanced Recycling | Enables conversion of mixed plastic waste into high-quality feedstocks, overcoming mechanical recycling limitations. |
| Long-term Offtake Agreements | Provides stable demand for circular polymers, de-risking investments in new recycling infrastructure. |
| Certification for Recycled Content | Builds trust and transparency in the supply chain, meeting mandatory reporting and procurement requirements. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a robust foundation for market sizing and trend analysis. Primary research involved in-depth interviews with R&D directors, procurement leads, sustainability officers, and plant managers across the value chain. This dual approach ensured comprehensive data collection, triangulating findings from both top-down market overviews and bottom-up operational insights.
Modeling granularity extended to product type, application, end-user, and form, alongside a detailed regional production hub analysis. The analytical framework integrated historical data with projected market dynamics to derive compound annual growth rates across the modeling period. Key industry-specific forecast inputs included anticipated crude oil price trends and the impact of evolving recycled content mandates in major economies.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical events impacting feedstock supply and rapid shifts in regulatory enforcement. All forecasts reflect a detailed set of assumptions regarding technological advancements and economic stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Benzyl Chloroformate Market
Bulk Chemicals
Electronic Batio3 Powder Market
Bulk Chemicals
Nahcolite Market
Bulk Chemicals
Methyl Gluceth-10 Market
Bulk Chemicals
Isophorone Market
Bulk Chemicals
United States Iodine Market
Bulk Chemicals
Heavy Alkyl Benzenes Market
Bulk Chemicals
Global Sodium Borohydride Market
Bulk Chemicals
Phosphate Rock Market
Bulk Chemicals
Sodium Thiosulphate Market
Bulk Chemicals
Cellulose Powder Market
Bulk Chemicals
Asia-Pacific Caustic Soda Market
Bulk Chemicals
United Kingdom Lime Market
Bulk Chemicals
Butachlor Market
Bulk Chemicals
Barium Sulphate Market
Bulk Chemicals
Europe Acetic Acid Market