
 Thailand Adhesives Market | 2026-2036
Thailand Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Adhesives Market Analytics
Hot-melt and reactive curing systems are reshaping how Thai manufacturers assemble electronics, automotive interiors, and flexible packaging. Henkel AG & Co. KGaA leverages its global formulation expertise to supply high-performance bonding solutions for automotive tier-one suppliers operating in Rayong and Chonburi. SCG Chemicals Co., Ltd. anchors domestic supply chains through backward integration into petrochemical feedstocks and localized production capacity. Dow Chemical competes on advanced acrylic and silicone platforms designed for humidity-resistant electronics applications in Thailand's coastal manufacturing zones.
Adhesives are non-metallic substances applied to substrate surfaces that develop structural or semi-structural bonds through chemical curing, mechanical interlocking, or diffusion mechanisms, with specifications typically encompassing shear strength, peel resistance, and cure temperature windows. Their primary industrial purpose spans permanent joining, sealing, and stress distribution across dissimilar materials in manufacturing and construction. Water-based acrylic and polyurethane formulations lead volume in packaging and woodworking applications where low VOC emissions align with tightening environmental rules. Reactive epoxy and silicone systems capture premium margin pools in electronics and automotive sectors demanding thermal cycling durability and dielectric stability.
Thailand Industrial Standards Institute (TISI) mandates VOC content limits and labeling requirements for solvent-based adhesive products sold domestically, while Ministry of Industry regulations on hazardous substance control shape import and manufacturing compliance costs. The Department of Industrial Works enforces wastewater and air emission standards that push manufacturers toward cleaner curing technologies and closed-loop solvent recovery. Stakeholders must monitor evolving TISI standards alignment with ASEAN harmonization frameworks and assess capital allocation between water-based capacity expansion and reactive system specialization.
Market Dynamics
TISI certification requirements are compressing formulation windows for solvent-based adhesives while automotive electrification in the Eastern Economic Corridor accelerates demand for thermally conductive bonding systems.
Growth Catalysts
- Water-based reformulation mandates:Thailand Industrial Standards Institute VOC limits are compelling manufacturers to retool production lines toward acrylic and polyurethane dispersions for packaging applications.
- Automotive bonding substitution:Tier-one suppliers in Rayong and Chonburi are replacing mechanical fasteners with structural adhesives to reduce vehicle weight and assembly steps.
- Electronics coastal clustering:Humidity-resistant epoxy and silicone platforms are capturing expanded share as coastal manufacturing zones near Bangkok scale precision assembly operations.
Market Restraints
- Petrochemical feedstock volatility:Crude oil price swings directly compress margins for acrylic and polyurethane resin producers dependent on naphtha-derived inputs.
- Import dependency for specialty monomers:Domestic supply chains lack captive production of high-purity epoxy hardeners and silicone crosslinkers, exposing formulators to currency and shipping cost shocks.
- Cure temperature limitations:Heat-sensitive substrates in electronics assembly constrain the deployable chemistry set, blocking some high-performance structural systems from qualifying for sensitive applications.
Strategic Opportunities
- Underpenetrated northeastern provinces:Isan region manufacturing parks lack localized adhesive blending capacity, creating white space for distributed production facilities serving packaging converters.
- ASEAN harmonization alignment:TISI standards convergence with regional frameworks is enabling certified Thai producers to access duty-advantaged export channels into neighboring Vietnam and Indonesia.
- UV-LED curing convergence:Combination of photoinitiator chemistry with energy-efficient LED arrays is opening seconds-scale cure applications in high-throughput flexible packaging lines.
Industry Challenges
- Formulation chemist scarcity:Domestic universities produce insufficient polymer science graduates to staff technical service laboratories supporting water-based system transitions.
- TISI certification timeline compression:Reformulation cycles must compress from 18 months to 9 months to meet revised VOC enforcement deadlines without disrupting customer qualification pipelines.
- Legacy solvent recovery asset stranding:Closed-loop distillation investments made under earlier regulations face accelerated obsolescence as water-based capacity expansion consumes limited capex budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Adhesives Market |
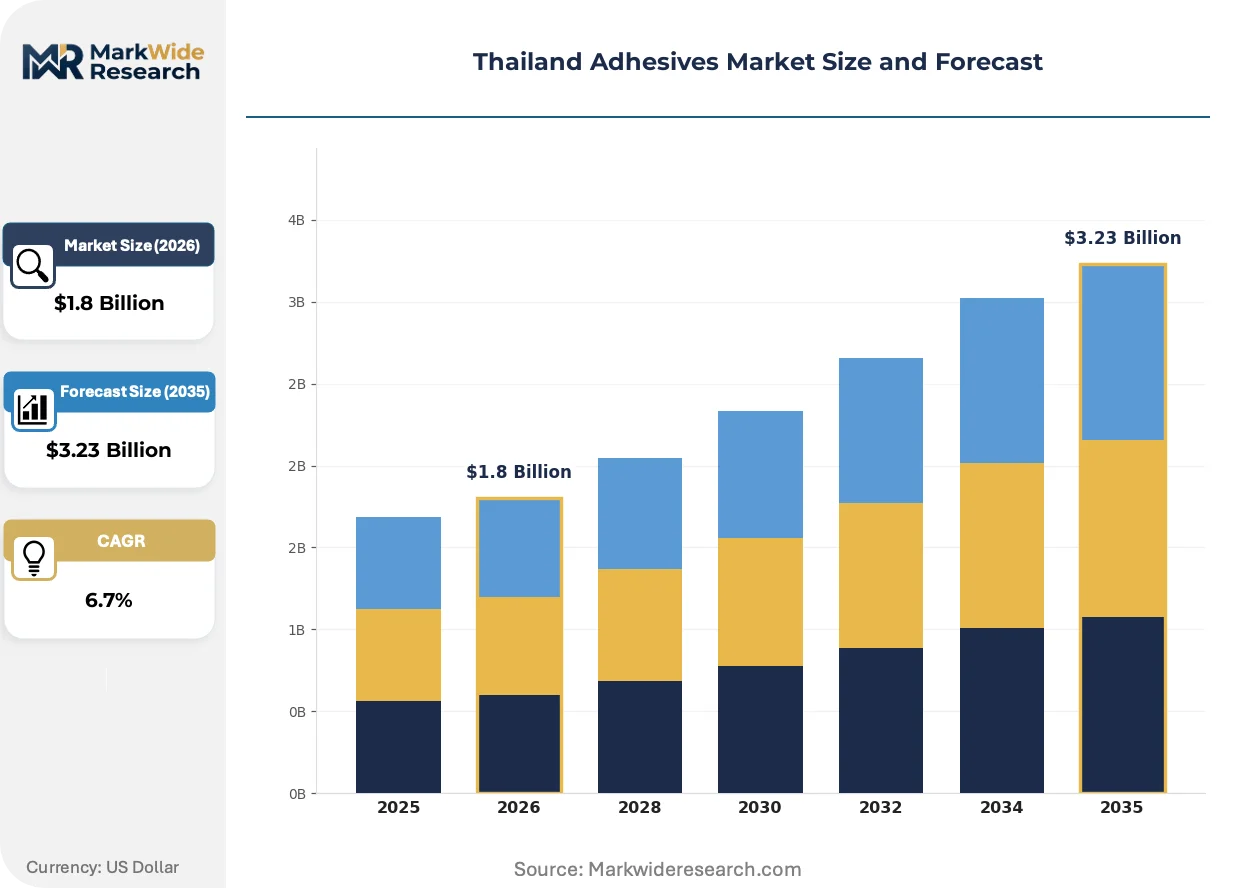
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Silicone, Acrylic End User: Construction, Automotive, Electronics, Packaging Technology: Hot Melt, Water-Based, Solvent-Based, Reactive Packaging Type: Cartridges, Tubs, Pouches, Drums |
| Companies Covered | Dow Chemical, Arkema Group, Henkel AG & Co. KGaA, Huntsman International LLC, SCG Chemicals Co., Ltd., Sika AG, H.B. Fuller Company, Star Bond (Thailand) Company Limited, 3M, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Adhesives Market Evolving Landscape
Reactive curing systems and photopolymerization technologies are restructuring how Thai manufacturers balance throughput, bond durability, and environmental compliance across automotive and electronics assembly.
UV-curable acrylic oligomers are collapsing the traditional tradeoff between cure speed and adhesion strength on low-surface-energy substrates. Flexible packaging converters in Samut Prakan and Pathum Thani are retrofitting laminating lines with LED-curable stations to eliminate thermal damage to heat-sensitive films. This technology is collapsing energy consumption per bonded square meter by seventy percent versus conventional hot-melt systems while enabling thinner gauge material usage.
Thailand Industrial Standards Institute alignment with ASEAN harmonization frameworks is accelerating cross-border certification reciprocity for adhesive products. Domestic manufacturers holding TISI certification now face reduced retesting burdens when exporting to Vietnam, Indonesia, and Malaysia under mutual recognition protocols. Electronics assemblers in coastal manufacturing zones are leveraging this regulatory convergence to consolidate supplier bases across the region.
Buyer consolidation among automotive tier-one suppliers is compressing qualification timelines and compressing approved vendor lists to single-digit counts. Procurement teams at Rayong-based interior module producers now demand bonded assembly validation data within 90-day windows versus historical 12-month cycles. This behavioral shift is most visible in seating and dashboard assembly contracts where adhesive performance guarantees carry explicit warranty pass-through clauses.
Thailand Adhesives Market Segmentation
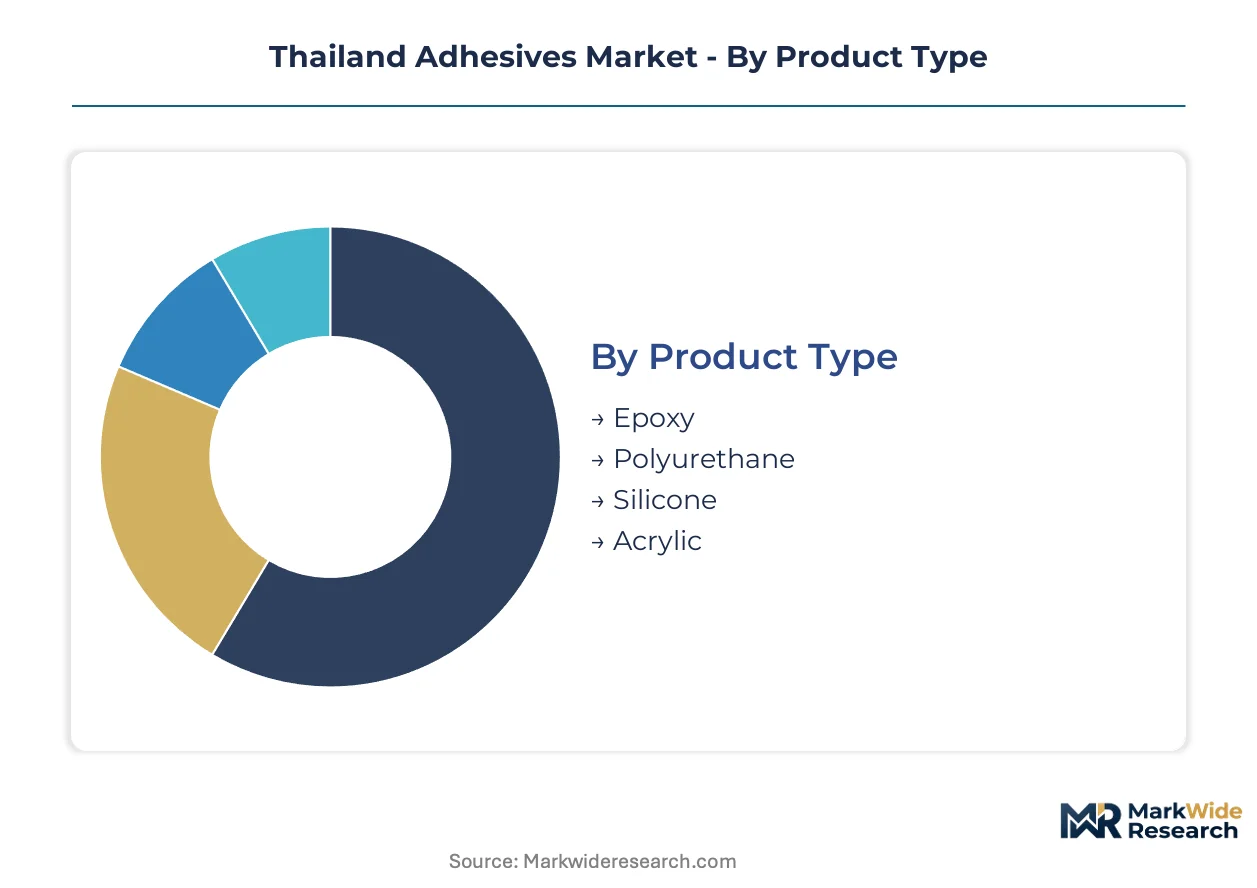
Thai adhesive buyers segment procurement by cure chemistry, regulatory compliance tier, and substrate sensitivity. Formulators must align product portfolios across multiple taxonomies simultaneously to capture share in Bangkok's electronics corridors and Eastern Economic Corridor automotive plants.
Product Type:
Cycle times vary dramatically across chemistries, with acrylic dispersions turning inventory weekly while reactive epoxies sit on specification holds for months awaiting customer qualification.
- Epoxy:Two-part thermosetting systems built from bisphenol-A and amine hardeners deliver shear strength exceeding 20 MPa for structural automotive bonding. Demand concentrates in Rayong province where tier-one seating and dashboard module producers specify epoxy for metal-to-composite joints under TISI durability testing protocols.
- Polyurethane:Moisture-curing and two-part formulations provide flexibility across temperature cycling ranges from -40°C to 120°C. Bangkok metropolitan area construction contractors specify polyurethane for exterior panel bonding where TISI-mandated VOC limits now block solvent-based alternatives.
- Silicone:Room-temperature-vulcanizing systems dominate electronics sealing in coastal humidity zones.
- Acrylic:Water-based dispersions and UV-curable oligomers serve high-throughput packaging laminators in Samut Prakan.
Acrylic anchors the volume base while epoxy gains share at the steepest rate.
End User:
Margin structures diverge sharply by buyer sophistication, with automotive procurement teams demanding full technical dossiers while construction distributors move commodity volumes on price alone.
- Construction:Tile adhesives, waterproofing membranes, and panel bonding systems face TISI VOC enforcement deadlines compressing solvent-based inventory. Contractors in Bangkok and surrounding industrial provinces now specify water-based acrylic and cementitious systems for interior applications where humidity resistance requirements are less severe.
- Automotive:Structural bonding for lightweight vehicle architectures displaces spot welding and mechanical fasteners across the Eastern Economic Corridor. Chonburi-based electric vehicle battery pack assemblers specify thermally conductive adhesives for cell-to-cell bonding where dielectric isolation and thermal runaway containment are non-negotiable.
- Electronics:Coastal manufacturing zones near Laem Chabang drive humidity-resistant formulations.
- Packaging:Flexible film converters in Pathum Thani prioritize seconds-scale cure speeds.
Packaging commands the highest shipment frequency while automotive exhibits the steepest expansion trajectory.
Technology:
Capital intensity separates winners from losers, with water-based systems demanding dispersion equipment investments that solvent-based legacy players struggle to fund.
- Hot Melt:Thermoplastic EVA and polyolefin formulations deliver instant green strength for packaging and woodworking applications. Samut Prakan carton sealing operations run hot-melt applicators at 150-180°C where TISI workplace safety inspections now mandate automated guarding and fume extraction upgrades.
- Water-Based:Acrylic and polyurethane dispersions carry 40-60% solids content with zero solvent contribution to VOC tallies. Bangkok electronics assemblers specify water-based pressure-sensitive adhesives for temporary bonding of components prior to permanent epoxy cure.
- Solvent-Based:Remaining applications concentrate in specialty coatings where TISI grandfathering provisions still permit limited production.
- Reactive:Epoxy, polyurethane, and silicone systems cure through polymerization rather than solvent evaporation.
Water-based technology anchors current volume while reactive systems climb the fastest.
Packaging Type:
Logistics economics favor bulk formats for high-volume converters while precision applications demand metered-dose delivery systems.
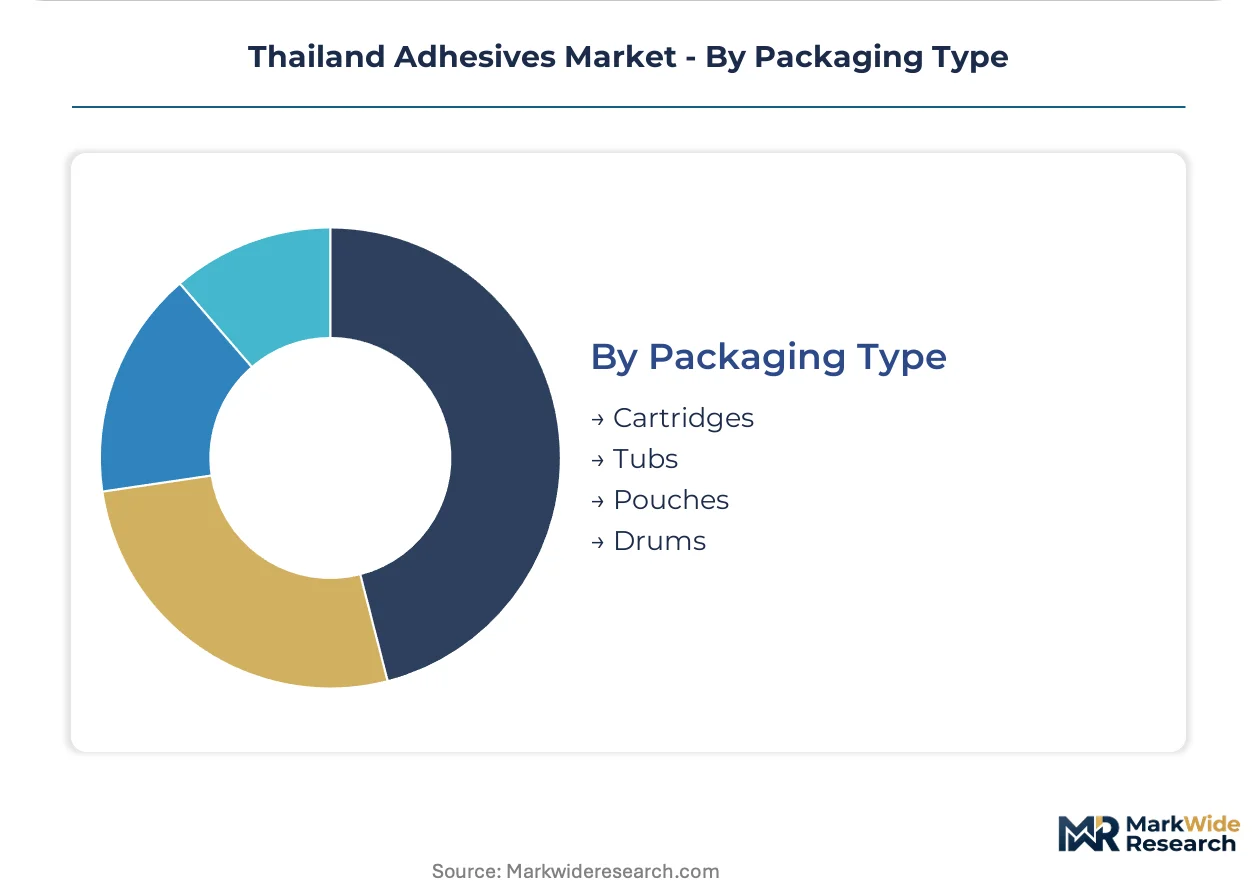
- Cartridges:Dual-barrel side-by-side and coaxial cartridges meter precise mix ratios for two-part epoxies and polyurethanes. Automotive repair shops and electronics contract manufacturers in Bangkok specify 50ml and 400ml cartridges where manual dispensing control outweighs bulk cost advantages.
- Drums:200-liter steel and plastic drums supply continuous production lines in flexible packaging and woodworking. Pathum Thani laminating operations consume drum quantities of hot-melt and water-based adhesives where automated pumping systems eliminate manual handling.
- Tubs:Intermediate bulk containers serve mid-scale construction and assembly operations.
- Pouches:Single-use sachets address field repair and remote construction sites.
Drums dominate tonnage movements while cartridges expand most quickly in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging converters and automotive assemblers concentrate procurement in Bangkok's industrial corridor and the Eastern Economic Corridor, with secondary demand emerging from Isan region manufacturing parks.
Bangkok Metropolitan Region
Electronics contract manufacturers and flexible packaging converters drive water-based acrylic and UV-curable adhesive consumption. TISI workplace safety inspections mandate automated fume extraction upgrades for hot-melt applicators operating at 150-180°C. Samut Prakan and Pathum Thani laminating operations consume drum quantities of adhesives where automated pumping systems eliminate manual handling.
Eastern Economic Corridor
Tier-one automotive suppliers in Rayong and Chonburi specify structural epoxies and thermally conductive systems for electric vehicle battery pack assembly. Board of Investment incentives for EV manufacturing are accelerating localization requirements for adhesive component sourcing. Chonburi-based interior module producers now demand bonded assembly validation data within 90-day qualification windows.
Central Plains
Construction contractors in Ayutthaya and Saraburi specify water-based polyurethane for exterior panel bonding where TISI-mandated VOC limits now block solvent-based alternatives. Ministry of Industry hazardous substance control regulations shape import compliance costs for cementitious tile adhesive formulations. Distribution networks radiate from Bangkok to serve mid-scale residential and commercial building projects.
Southern Coastal Zone
Rubber processing and marine equipment manufacturers in Songkhla and Surat Thani drive demand for humidity-resistant silicone and polyurethane systems. Department of Industrial Works enforces wastewater standards that push manufacturers toward cleaner curing technologies. Port infrastructure at Laem Chabang supports chemical import logistics for regional formulators.
Northeastern Region
Isan manufacturing parks in Khon Kaen and Nakhon Ratchasima lack localized adhesive blending capacity, creating white space for distributed production facilities. Board of Investment promotional zones offer tax incentives for packaging converter investments. Domestic universities in the region produce insufficient polymer science graduates to staff technical service laboratories.
Thailand Adhesives Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation tiers, with petrochemical-integrated domestic groups holding feedstock cost advantages against multinational technology leaders. The vendor base spans three strategic tiers: global chemical conglomerates with full portfolio coverage, regional Asian specialists with cost-optimized water-based systems, and domestic Thai producers leveraging backward integration into naphtha-derived resin inputs. Competitive dynamics center on qualification timeline compression and TISI certification reciprocity for ASEAN export access.
Among global chemical conglomerates, Henkel AG & Co. KGaA and Dow Chemical occupy positions exemplifying technology-led premium positioning, while SCG Chemicals Co., Ltd. anchors the domestic integrated tier with captive petrochemical feedstock supply. These three companies represent the dominant competitive archetypes: multinational formulation expertise, advanced materials platforms, and regional backward integration respectively.
| Leading Market Players |
|---|
| Dow Chemical |
| Arkema Group |
| Henkel AG & Co. KGaA |
| Huntsman International LLC |
| SCG Chemicals Co., Ltd. |
| Sika AG |
| H.B. Fuller Company |
| Star Bond (Thailand) Company Limited |
| 3M |
| Others |
Value Network & Pricing Analysis
Naphtha-derived acrylic and polyurethane resin feedstocks from South Korea, Japan, and Singapore anchor cost structures for Thai formulators, concentrating margin capture with petrochemical-integrated domestic producers while compressing independent compounders during crude price volatility cycles.
Pricing Analysis
Cost-plus contracts indexed to ICIS Asian naphtha assessments dominate procurement between resin suppliers and adhesive formulators. Pricing stratifies across TISI-certified premium grades, standard industrial tiers, and economy packaging formulations. Cost compression in water-based acrylics is intensifying because SCG Chemicals' backward integration into olefin feedstocks undercuts import-dependent competitors. Construction distributors exhibit highest price sensitivity, while automotive tier-one suppliers prioritize qualification speed over unit cost.
Supply Chain Analysis
Extended sixty-to-ninety-day payment terms from automotive OEMs cascade through tier-one suppliers, forcing adhesive formulators to utilize supply-chain finance facilities anchored in Bangkok-based trade banks. Epoxy hardeners and silicone crosslinkers draw from Japan, South Korea, and Germany, exposing formulators to yen and euro volatility. Single-source vulnerability concentrates in high-purity amine hardeners for automotive structural systems. Distribution runs through Bangkok-based chemical distributors with satellite warehouses in Rayong and Chonburi.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Thailand adhesives market rewards players who control formulation chemistry talent pools, as domestic universities produce insufficient polymer science graduates to staff technical service laboratories supporting water-based system transitions.
For Market Incumbents: Build certification moats by accelerating TISI compliance timelines ahead of ASEAN harmonization deadlines. Deepen backward integration into water-based acrylic dispersion capacity in Rayong to offset petrochemical feedstock volatility. Defensive positioning must counter regional Asian specialists entering through Vietnam and Indonesia duty-advantaged channels. For New Entrants and Emerging Players: Establish a beachhead in Isan region packaging converter supply, where Khon Kaen and Nakhon Ratchasima manufacturing parks lack localized adhesive blending capacity. Target mid-scale construction contractors in Ayutthaya and Saraburi with cementitious tile adhesive formulations. Go-to-market leverage rests on Board of Investment promotional zone tax incentives for distributed production facilities. For Investors and Strategic Acquirers: Capital is best deployed toward domestic Thai producers with captive petrochemical feedstock supply and existing TISI certification infrastructure. Long-term viability hinges on water-based capacity positioning ahead of solvent-based phase-out deadlines. Monitor ASEAN mutual recognition protocol expansion as inflection signal for export channel scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Resin Production | SCG Chemicals' olefin feedstock control insulates margins from naphtha price swings. |
| TISI Certification Acceleration | Early compliance with revised VOC limits secures qualification pipelines for automotive tier-one contracts. |
| UV-LED Curing Line Retrofit | Samut Prakan packaging converters reduce energy consumption seventy percent versus hot-melt systems. |
| Isan Region Distributed Production | Khon Kaen facilities capture underpenetrated northeastern packaging converter demand. |
| ASEAN Export Channel Development | Mutual recognition protocols enable duty-advantaged access to Vietnam and Indonesia markets. |
Research Methodology
A spread of perspectives from adhesive formulator R&D directors, automotive tier-one procurement managers, packaging converter operations heads, and TISI certification consultants converged on the working assumptions. Primary fieldwork combined with secondary validation from Thailand Industrial Standards Institute regulatory filings, Ministry of Industry hazardous substance control records, and customs trade data. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Demand-supply balance dynamics across cure chemistry segments, end-use industries, and regional production clusters shaped the analytical framework throughout the forecast period. Modeled dimensions included product type, technology platform, packaging format, and provincial demand concentration. CAGRs derived from elasticity-adjusted consumption trends and capacity expansion announcements. Forecast inputs incorporated TISI enforcement timeline assumptions and Eastern Economic Corridor EV manufacturing localization rates.
Stress conditions across crude oil price bands, currency volatility ranges, and regulatory compliance timeline scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about ASEAN harmonization progression and petrochemical feedstock cost trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Flooring Adhesive Market
Adhesives & Sealants
Epoxy Curing Agents Market
Adhesives & Sealants
Global Stone and Tile Adhesives and Sealants Market
Adhesives & Sealants
Indonesia Sealants Market
Adhesives & Sealants
Dimethylaminoethyl Acrylate Market
Adhesives & Sealants
Europe Cyanoacrylate Adhesives Market
Adhesives & Sealants
Global Lithium Ion Battery Binders Market
Adhesives & Sealants
Global Bioadhesive Market
Adhesives & Sealants
Carpet Adhesive Market
Adhesives & Sealants
Japan Sealants Market
Adhesives & Sealants
Restorative Materials and Bonding Agents Market
Adhesives & Sealants
Ocular Sealants and Glues Market
Adhesives & Sealants
Global Automotive Adhesive Market
Adhesives & Sealants
Butyl Adhesive Market
Adhesives & Sealants
Global Sealants Market
Adhesives & Sealants
North America Epoxy Adhesives Market