
 Central Reinforced Tape Market | 2026-2036
Central Reinforced Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Central Reinforced Tape Market Outlook
Multi-sourced raw material procurement is broadening as tape manufacturers reduce dependence on single polymer suppliers. 3M leverages captive resin production to control formulation consistency across industrial grades. Nitto Denko anchors its position through precision coating technology developed for electronics-grade applications. Berry Global competes on blown film extrusion scale, supplying polypropylene backings to private-label distributors.
Central reinforced tape consists of a pressure-sensitive adhesive laminated to a woven or filament-reinforced carrier, typically rated for tensile strengths exceeding 100 pounds per inch to prevent package rupture or structural seam failure. Glass fiber variants command premium positioning due to dimensional stability under load, while polyester films sustain higher margins in electrical insulation where dielectric resistance matters. Industrial packaging absorbs the largest volume share, though automotive assembly applications are expanding fastest as OEMs replace mechanical fasteners with bonded joints.
EPA guidelines on volatile organic compound emissions from adhesive manufacturing constrain solvent-based formulation options in the United States, while REACH substance restrictions in Europe limit certain phthalate plasticizers in tape backings. OSHA workplace exposure standards further shape product selection for contractors in construction end-uses. Stakeholders must monitor evolving chemical compliance thresholds to avoid reformulation costs that could erode position in price-sensitive distribution channels.
Market Dynamics
Construction contractors in Germany and Japan are replacing mechanical fasteners with glass fiber reinforced tapes for structural bonding, compressing installation cycles while tightening material disclosure requirements under REACH and China's GB standards.
Growth Catalysts
- Automotive Lightweighting Mandates:OEM assembly lines in Stuttgart and Toyota City are substituting bonded joints for rivets and welds to meet fleet efficiency targets, pulling filament-reinforced tape volumes into body-in-white applications.
- REACH Substance Restrictions:ECHA's tightening limits on phthalate plasticizers in tape backings are accelerating reformulation toward bio-based polyester carriers that command specification preference in European industrial distribution.
- East Asian Manufacturing Cluster Density:Concentrated demand around Shanghai and Osaka industrial zones creates localized procurement hubs where just-in-time tape supply integrates directly with electronics and appliance assembly lines.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene and acrylic adhesive monomers fluctuate with naphtha cracking margins, squeezing formulation cost predictability for blown film extruders serving private-label distributors.
- Glass Fiber Supply Concentration:High-tenacity E-glass roving production concentrates in Chinese state-owned smelters, exposing tape laminators to export quota disruptions and freight rate spikes on Asia-Europe routes.
- Dielectric Performance Ceiling:Polyester film carriers hit thermal stability limits above 130°C continuous operation, blocking penetration into EV battery module insulation where polyimide films dominate.
Strategic Opportunities
- Underpenetrated Indian Infrastructure:National highway expansion and metro rail construction in Mumbai and Delhi create specification openings for structural bonding tapes as IRC bridge codes modernize toward adhesive-based joining methods.
- EU Green Deal Procurement Incentives:Public infrastructure tenders awarding technical preference points for recycled-content backings and solvent-free adhesives reward early movers in circular formulation development.
- Convergence of Digital Printing and Reinforced Carriers:Variable-data inkjet systems are personalizing tape surfaces with handling instructions and branding, opening premium positioning in e-commerce fulfillment where unboxing experience differentiates.
Industry Challenges
- Precision Coating Talent Scarcity:Electronics-grade thickness control requires operators trained in micrometer-scale adhesive deposition, a skill set concentrated in Japanese and Korean technical institutes with limited graduate pipelines.
- Multi-Jurisdiction Certification Timelines:Simultaneous UL 510 electrical recognition, DIN 30672 construction approval, and JIS Z 1541 packaging compliance extend product launch cycles by 14-18 months for cross-regional portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Central Reinforced Tape Market |
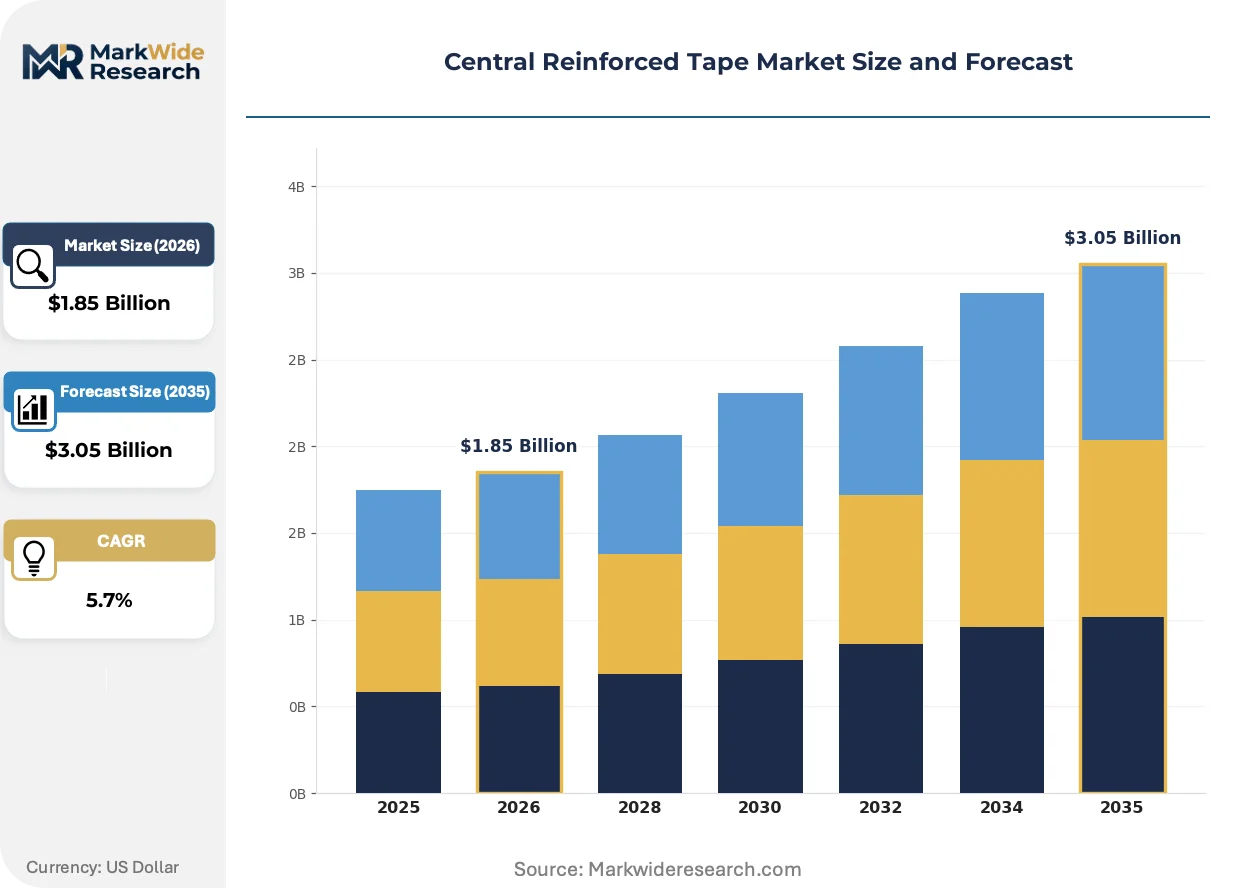
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.05 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Fiber, Polyester, Polypropylene, Cotton Application: Industrial Packaging, Construction, Automotive Assembly, Electrical Insulation End User: Manufacturers, Contractors, Distributors, Retailers Distribution Channel: Online Retailers, Wholesale Suppliers, Direct Sales, Specialty Stores |
| Companies Covered | 3M, Nitto Denko, Berry Global, Intertape Polymer Group, Scapa Group, Uline, Holland Manufacturing, Can-Do National Tape, Vibac Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Central Reinforced Tape Market Strategic Shifts
Precision coating automation and regulatory disclosure mandates are compressing batch-to-batch variation while fragmenting procurement channels between direct mill relationships and specialized distributors serving niche performance tiers.
Laser-guided web tensioning systems are automating micron-level adhesive thickness control across woven glass fiber carriers. Automotive tier-one suppliers in Bavaria and Aichi Prefecture are qualifying these lines for zero-defect bonding tape supply to EV battery pack assembly. The technology is automating quality assurance labor out of high-volume lamination operations while enabling lot-traceable digital records for OEM audit requirements.
REACH Article 33 disclosure obligations on Substances of Very High Concern are forcing downstream tape formulators to map full polymer and additive supply chains. Industrial distributors in the Netherlands and Belgium now require extended safety data sheets before listing construction-grade products. Electrical insulation tape categories face the steepest compliance burden as brominated flame retardants trigger substitution alerts across German automotive harness specifications.
Consolidated buying desks at Amazon fulfillment networks and Zalando logistics hubs are compressing supplier rosters to three approved tape vendors per regional warehouse. Direct mill contracts with volume commitments are displacing spot purchasing through packaging distributors in Leipzig and Rotterdam. This concentration is most visible in German e-commerce fulfillment where bonded carton sealing specifications now flow from central procurement rather than individual facility managers.
Central Reinforced Tape Market Segmentation
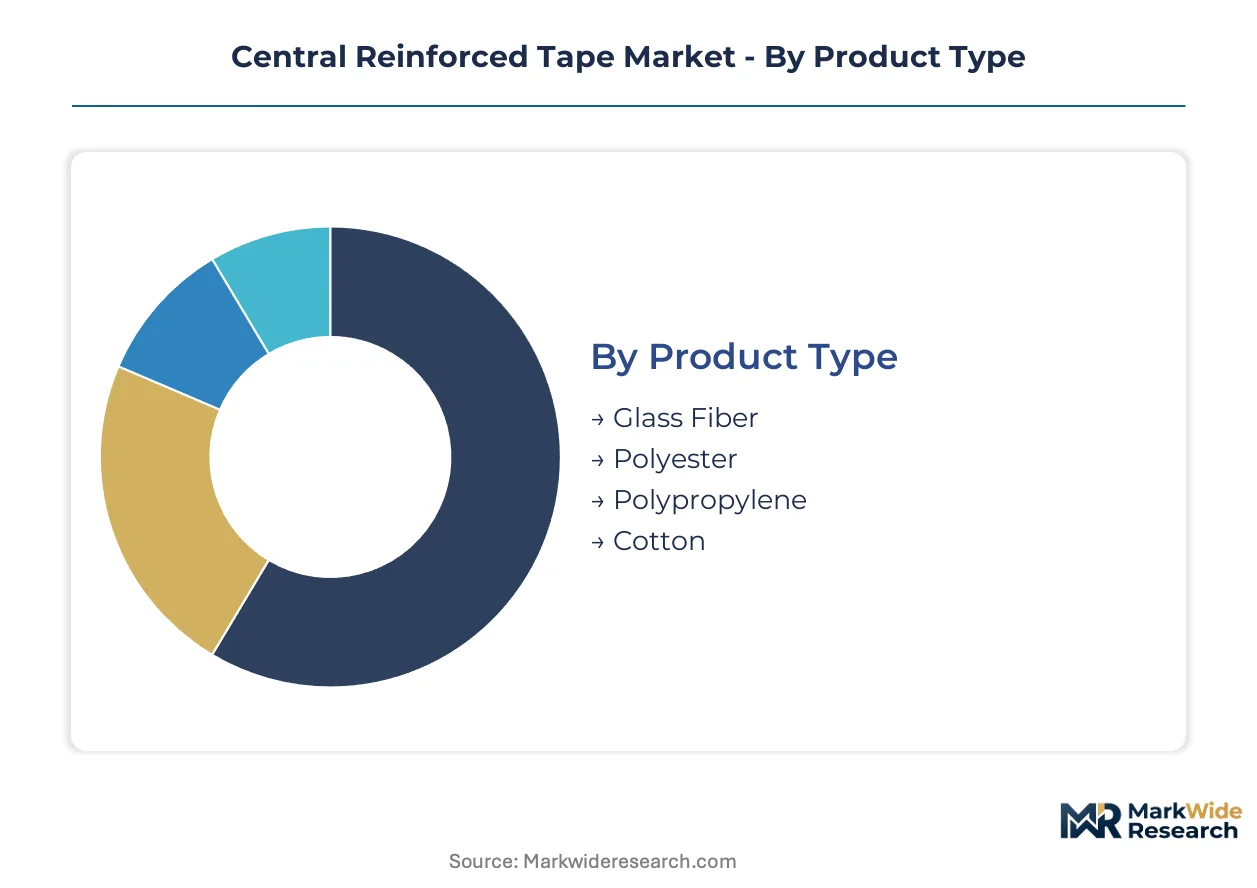
Central reinforced tape segmentation reflects divergent technical requirements across load-bearing and insulating applications. Carrier material selection and distribution channel configuration determine margin structures and compliance exposure for formulators serving distinct end-use clusters.
Product Type:
Glass fiber variants integrate into structural bonding systems demanding dimensional stability under sustained mechanical load, while polyester and polypropylene carriers serve standalone applications where dielectric or moisture barrier properties dominate.
- Glass Fiber:Woven E-glass rovings laminated with pressure-sensitive adhesives deliver tensile ratings exceeding 150 pounds per inch. Demand concentrates in Stuttgart automotive body-in-white operations and Osaka electronics assembly plants where bonded joints replace mechanical fasteners under REACH substance restrictions.
- Polyester:Biaxially oriented film carriers sustain dielectric resistance for electrical insulation tapes. German automotive harness specifications favor these grades as ECHA phthalate alerts drive substitution away from plasticized vinyl alternatives.
- Polypropylene:Blown film backings dominate industrial carton sealing where cost predictability matters more than thermal stability. Berry Global's extrusion scale supplies private-label distributors serving Amazon fulfillment networks.
- Cotton:Woven natural fiber carriers persist in heritage packaging applications and theatrical rigging where hand-tearability and conformability to irregular surfaces outweigh synthetic performance advantages.
Volume placements concentrate in polypropylene backings; the faster expansion belongs to glass fiber variants.
Application:
Cost tier stratification separates commodity carton sealing from specification-grade structural bonding where certification overhead and lot traceability command premium positioning.
- Industrial Packaging:High-volume carton sealing and pallet unitization absorb the largest tonnage share. E-commerce fulfillment consolidation at Amazon and Zalando logistics hubs compresses supplier rosters to three approved vendors per regional warehouse.
- Construction:Glass fiber reinforced tapes bond structural panels and replace mechanical fasteners in German and Japanese building codes. REACH Article 33 disclosure obligations force full polymer supply chain mapping before Dutch and Belgian distributors list construction-grade products.
- Automotive Assembly:Filament-reinforced tapes secure lightweight body panels and interior trim as OEMs pursue fleet efficiency targets. Laser-guided web tensioning systems from Bavarian tier-one suppliers enable zero-defect qualification for EV battery pack bonding.
- Electrical Insulation:Polyester and polyimide carriers face the steepest compliance burden as brominated flame retardants trigger substitution alerts across German automotive harness specifications. Thermal stability above 130°C continuous operation blocks penetration into EV battery module insulation.
Industrial packaging captures the highest shipment volumes; automotive assembly climbs the fastest as bonded joints displace rivets and welds.
End User:
Customer type determines procurement sophistication, with consolidated manufacturing buyers extracting volume commitments while fragmented contractor channels reward technical service intensity.
- Manufacturers:Automotive OEMs and appliance assemblers in Shanghai and Osaka industrial zones specify lot-traceable tape grades with digital compliance records. Direct mill contracts displace spot purchasing through packaging distributors.
- Contractors:German and Japanese construction crews source glass fiber reinforced tapes for structural bonding applications. OSHA workplace exposure standards shape product selection for US job sites.
- Distributors:Industrial supply houses in Rotterdam and Leipzig curate portfolios across performance tiers, requiring extended safety data sheets for REACH compliance before listing construction-grade products.
- Retailers:Hardware and home improvement channels stock consumer-grade reinforced tapes for DIY repair and light-duty packaging, competing on shelf placement and brand recognition rather than technical specification.
Procurement concentration favors manufacturers; contractor channels offer the steepest service margin premiums.
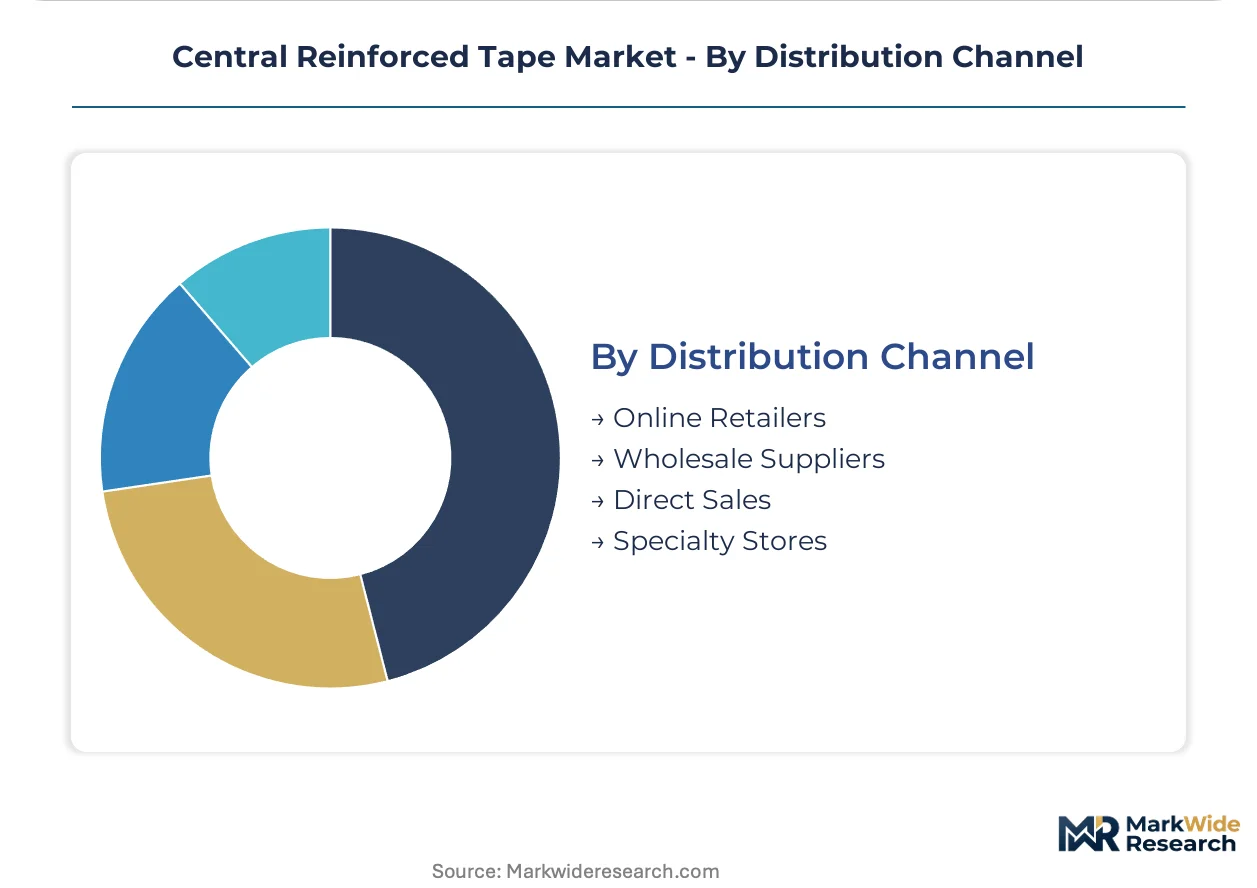
Distribution Channel:
Supply concentration shapes channel economics, with captive resin production enabling direct sales scale while specialty formulations depend on technical distributor relationships.
- Online Retailers:Amazon and Alibaba platforms aggregate demand for standardized industrial grades, compressing price transparency and delivery lead times. Variable-data inkjet personalization creates premium positioning in e-commerce fulfillment unboxing experience.
- Wholesale Suppliers:Regional packaging distributors in Leipzig and Rotterdam maintain inventory buffers for just-in-time manufacturing clusters, though consolidated buying desks are reducing approved vendor counts.
- Direct Sales:3M's captive resin production supports formulation consistency across industrial grades sold through mill-direct relationships with tier-one automotive and electronics assemblers.
- Specialty Stores:Electrical supply houses and construction material specialists stock specification-grade tapes requiring application engineering support, particularly for German DIN 30672 construction approval and JIS Z 1541 packaging compliance.
Direct sales anchor the highest value capture; online retail channels gain share fastest as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in East Asian manufacturing clusters and German automotive centers, with procurement patterns diverging between specification-grade structural bonding and commodity carton sealing applications.
China
Shanghai industrial zones anchor glass fiber tape consumption for electronics assembly and appliance manufacturing. GB standards for adhesive products mandate tightening material disclosure requirements for construction-grade imports. State-owned E-glass smelters in Jiangsu province supply high-tenacity roving to domestic laminators, though export quota exposure persists.
Germany
Stuttgart automotive body-in-white operations drive filament-reinforced tape qualification for bonded joint applications. REACH Article 33 obligations force full polymer supply chain mapping before Dutch and Belgian distributors list construction products. Bavarian tier-one suppliers deploy laser-guided web tensioning for zero-defect EV battery pack bonding.
Japan
Osaka electronics assembly plants specify lot-traceable glass fiber tapes under JIS Z 1541 packaging compliance. METI industrial efficiency programs accelerate mechanical fastener replacement in Aichi Prefecture automotive clusters. Precision coating technology developed for electronics-grade applications concentrates technical talent in Kansai region institutes.
United States
Amazon fulfillment network consolidation compresses approved vendor rosters to three tape suppliers per regional warehouse. EPA guidelines on volatile organic compound emissions constrain solvent-based adhesive formulation options. OSHA workplace exposure standards shape product selection for construction contractors in Texas and California infrastructure projects.
India
National highway expansion and Mumbai metro rail construction create specification openings for structural bonding tapes. IRC bridge code modernization toward adhesive-based joining methods lags European adoption curves. Domestic procurement relies on imported glass fiber carriers until local E-glass capacity scales in Gujarat industrial corridors.
Central Reinforced Tape Market Competitive Environment
Capacity expansion dominates the current landscape as tape laminators add precision coating lines to capture automotive and electronics qualification programs. The vendor base separates into three tiers: multinational chemical conglomerates with captive resin production, mid-scale specialists focused on regional distribution partnerships, and private-label converters competing on blown film extrusion scale. Strategic archetypes include backward-integrated formulators controlling polymer supply chains, precision coating specialists leveraging micrometer-scale deposition expertise, and scale-driven extruders serving consolidated e-commerce procurement desks. M&A activity targets niche compliance capabilities in REACH documentation and UL electrical recognition, while geographic expansion focuses on Indian infrastructure and Southeast Asian electronics manufacturing clusters.
Among diversified materials conglomerates, 3M exemplifies the backward-integrated archetype through in-house resin production that anchors formulation consistency across industrial grades. Nitto Denko occupies a position within the precision coating tier, drawing on technical institute pipelines in Japanese manufacturing clusters. Berry Global represents scale-driven extrusion specialists supplying polypropylene backings to consolidated buying desks at major e-commerce fulfillment networks.
| Leading Market Players |
|---|
| 3M |
| Nitto Denko |
| Berry Global |
| Intertape Polymer Group |
| Scapa Group |
| Uline |
| Holland Manufacturing |
| Can-Do National Tape |
| Vibac Group |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between UL-recognized electrical tapes and commodity carton-sealing grades manifests in divergent margin structures and supply chain configurations across the Central Reinforced Tape Market. Premium structural bonding tapes for Stuttgart automotive assembly command lot-traceable supply chains with captive resin production, while private-label polypropylene backings for Amazon fulfillment networks compete on blown film extrusion scale and spot resin purchasing.
Pricing Analysis
Volume-margin splits separate high-tonnage industrial packaging from specification-grade automotive and construction applications. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden differentiation, with UL 510 electrical recognition and DIN 30672 construction approval adding 15-20% price premiums over uncertified grades. Cost compression in commodity polypropylene backings is intensifying because consolidated e-commerce procurement desks extract volume commitments from three approved vendors per regional warehouse. Amazon fulfillment networks exhibit the highest price sensitivity, while Bavarian tier-one automotive suppliers prioritize zero-defect qualification over unit cost.
Supply Chain Analysis
China's GB standards for adhesive products and India's emerging domestic-content preferences for infrastructure procurement are reshaping sourcing patterns toward localized laminator capacity. High-tenacity E-glass roving production concentrates in Chinese state-owned smelters, South Korean precision coating equipment suppliers, and German automotive-grade adhesive formulators. Raw material dependencies rest on polypropylene resin from naphtha crackers, acrylic adhesive monomers, and woven glass fiber carriers. Single-source vulnerability in Chinese E-glass export quotas exposes tape laminators to freight rate spikes on Asia-Europe routes. Distribution runs through direct mill relationships with tier-one automotive assemblers and consolidated wholesale suppliers in Rotterdam and Leipzig.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as formulators pursue captive resin production to secure formulation consistency against petrochemical feedstock volatility. Players are anchoring position through upstream polymer supply control and downstream qualification programs with OEM specification committees.
For Market Incumbents: Anticipate REACH Article 33 disclosure obligations forcing full polymer supply chain mapping by securing backward integration into adhesive resin production or binding long-term offtake agreements with specialty monomer suppliers. Defend against precision coating automation by acquiring laser-guided web tensioning capabilities for zero-defect EV battery pack bonding qualifications. Capacity addition in Gujarat industrial corridors addresses Indian infrastructure procurement before local E-glass smelters scale.
For New Entrants and Emerging Players: EU Green Deal procurement incentives in European public infrastructure tenders open a window for circular formulation development with recycled-content backings and solvent-free adhesives. Target underpenetrated Indian highway and metro rail construction as IRC bridge codes modernize toward adhesive-based joining methods. Pursue technical distributor partnerships in Rotterdam and Leipzig requiring extended safety data sheets for REACH compliance as a go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with precision coating specialists given automotive lightweighting mandates pulling filament-reinforced tape volumes into body-in-white applications. Long-term viability favors formulators with demonstrated qualification timelines across UL, DIN, and JIS certification regimes. The signal to watch is laser-guided web tensioning system deployment rates among Bavarian and Aichi Prefecture tier-one suppliers as an inflection indicator for zero-defect supply chain migration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive adhesive formulation secures margin protection against naphtha cracking volatility. |
| Precision Coating Automation | Laser-guided web tensioning enables zero-defect qualification for Stuttgart automotive OEMs. |
| REACH Compliance Documentation | Extended safety data sheets unlock Dutch and Belgian distributor listing for construction grades. |
| Indian Infrastructure Localization | Gujarat industrial corridor positioning captures IRC bridge code modernization toward adhesive joining. |
| E-commerce Fulfillment Consolidation | Direct mill contracts with Amazon and Zalando displace spot purchasing through regional distributors. |
Study Parameters
Document review covered trade association filings from AFERA and PSTC, customs data on E-glass roving imports, and SEC disclosures from diversified materials conglomerates, complemented by interviews with procurement directors at Stuttgart automotive OEMs, plant managers at Chinese state-owned smelters, technical coating specialists from Kansai region institutes, and construction specification engineers in Munich and Osaka. Secondary validation drew from DIN standards documentation, ECHA substance restriction alerts, and JIS Z 1541 compliance records. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Segment-level projections across carrier material, application, and end-user dimensions produced volume and value trajectories across the analysis window. The analytical framework modeled glass fiber, polyester, polypropylene, and cotton carrier grades against industrial packaging, construction, automotive assembly, and electrical insulation applications. CAGRs derived from elasticity-adjusted demand curves incorporating automotive lightweighting mandates, REACH substance restriction timelines, and East Asian manufacturing cluster density indices. Forecast inputs included petrochemical feedstock futures curves and certification pipeline backlogs for multi-jurisdiction approval timelines.
The model assumes a particular technology adoption path; alternative pathways for solvent-free adhesive curing systems or bio-based polyester carrier substitution would alter the outlook. Forecasts reflect assumptions on REACH enforcement consistency, Chinese E-glass export quota stability, and Indian infrastructure procurement localization rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Spray Glue Market
Adhesives & Sealants
Asia-Pacific Contact Adhesives Market
Adhesives & Sealants
Global Bone Glue Market
Adhesives & Sealants
United Kingdom Sealants Market
Adhesives & Sealants
Dural Sealant Market
Adhesives & Sealants
North America & Europe Adhesives and Sealants Market
Adhesives & Sealants
Germany Sealants Market
Adhesives & Sealants
Europe Bone Glue Market
Adhesives & Sealants
Instant Adhesive Market
Adhesives & Sealants
Textile Binders Market
Adhesives & Sealants
Dibutyl Maleate (DBM) Market
Adhesives & Sealants
Brazil Adhesives Market
Adhesives & Sealants
Roofing Adhesive Market
Adhesives & Sealants
Russia Sealants Market
Adhesives & Sealants
Lead Encapsulants Market
Adhesives & Sealants
Saudi Arabia Adhesives Market