
 Packaging Adhesives Market | 2026-2036
Packaging Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Adhesives Market Intelligence
The shift toward asset-light manufacturing models, where specialized adhesive compounding is outsourced, is tilting the competitive landscape away from fully integrated chemical giants. This dynamic creates opportunities for focused players. H.B. Fuller Company specializes in a broad portfolio of hot melt and water-based solutions for diverse packaging needs. Henkel AG & Co. KGaA leverages its extensive global distribution network and brand recognition in the consumer goods sector to maintain market leadership.
Packaging adhesives are bonding agents formulated to join substrates such as paper, film, and rigid plastics in container fabrication and sealing. These formulations are engineered for specific performance traits including cure speed and food-contact safety compliance. Water-based adhesives command significant volume in paper and board applications due to cost-effectiveness. Hot melt adhesives, however, are gaining share rapidly, driven by their fast setting times essential for automated flexible packaging lines in the food & beverage sector.
Regulatory frameworks strictly govern the market, particularly for food-contact materials. The U.S. FDA's regulations for indirect food additives and Europe's REACH framework impose stringent chemical safety requirements. In parallel, China's GB standards for food packaging materials dictate formulation choices for market access. Navigating these divergent regional standards for recyclability and compostability is becoming a central strategic challenge for formulators and brand owners.
Market Dynamics
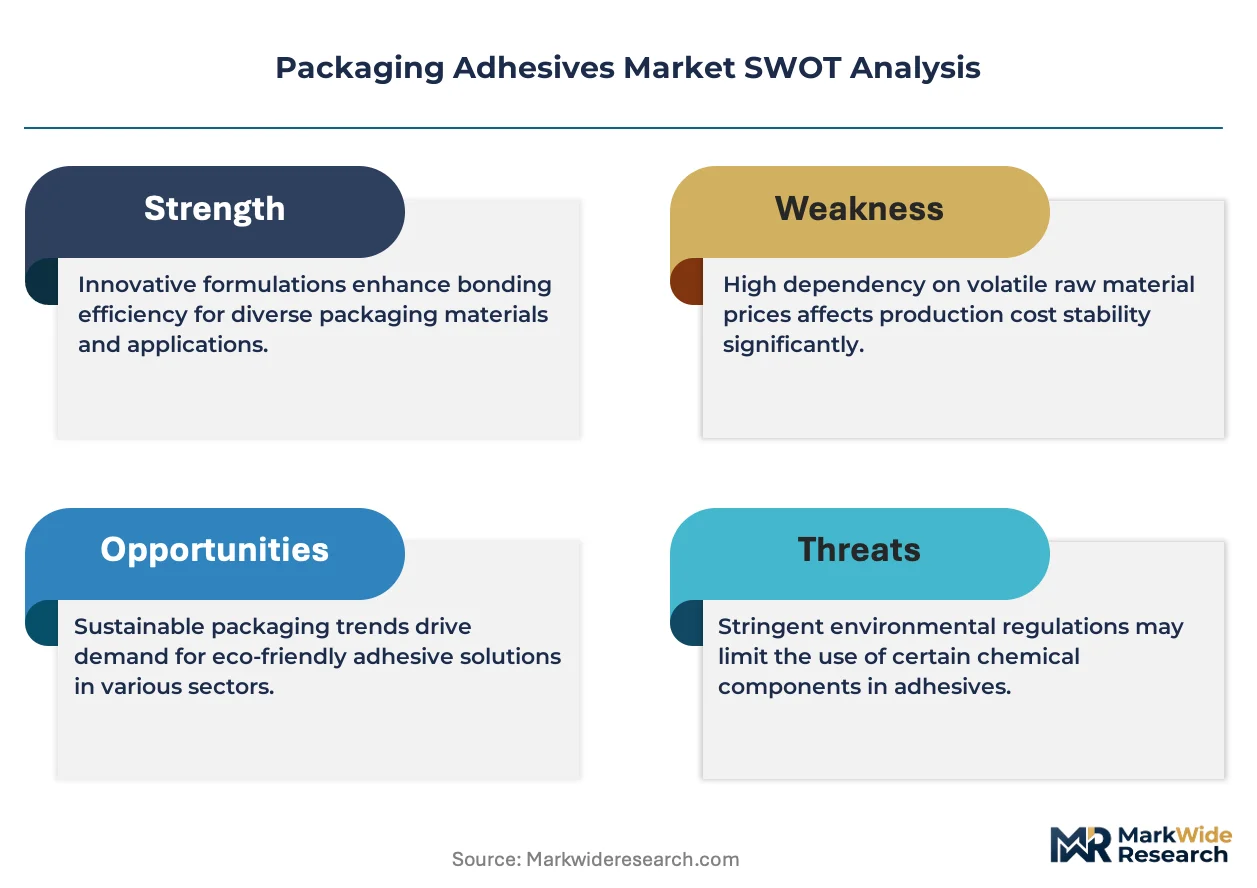
The central tension shaping the packaging adhesives market is the conflict between sustainability mandates demanding recyclable and bio-based materials, and the unyielding performance requirements of high-speed automated packaging lines for rapid curing and strong adhesion.
Growth Catalysts
- E-commerce Expansion:The rise of online retail accelerates consumption of hot melt and water-based adhesives for corrugated boxes and protective mailers, particularly for secondary and tertiary packaging applications.
- Food Safety Regulations:Stringent frameworks, including the U.S. FDA's regulations for indirect food additives, compel innovation in non-migrating, low-VOC adhesive formulations, creating a distinct premium product tier.
- Flexible Packaging Growth:A consumer shift toward pouches and sachets in the food and beverage industry, especially in India and China, boosts demand for specialized laminating and cold-seal adhesives.
Market Restraints
- Raw Material Volatility:Formulator margins are exposed to price fluctuations of key petrochemical feedstocks like ethylene vinyl acetate (EVA) and other polymers, which are tied to volatile global energy markets.
- Recycling Stream Contamination:Many conventional adhesives are incompatible with established paper and plastic recycling processes, acting as contaminants that can lead to their deselection by brand owners pursuing circular economy goals.
- Divergent Global Standards:Navigating disparate chemical safety and food contact regulations, such as Europe's REACH versus China's GB standards, increases compliance costs and complexity for multinational formulators.
Strategic Opportunities
- Bio-Based Formulations:Developing adhesives from renewable sources like starch or polylactic acid (PLA) allows suppliers to meet corporate sustainability targets and align with policy initiatives like the EU Green Deal.
- Designing for Recyclability:Creating "wash-off" or "de-bondable" adhesives that cleanly separate from PET containers and paper labels during the recycling process presents a significant value-add for packaging converters.
- Smart Packaging Integration:Opportunities exist in formulating conductive or functional adhesives for use in smart labels that incorporate RFID or NFC technologies for enhanced supply chain tracking and consumer engagement.
Industry Challenges
- Formulation Expertise Scarcity:A persistent shortage of chemists with dual expertise in polymer science and the application mechanics of high-speed converting machinery slows the development cycle for next-generation adhesives.
- Compliance and Testing Bottlenecks:The extensive time and cost required for food-contact migration analysis and certification, particularly for novel bio-based materials, can significantly delay market entry for new products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Adhesives Market |
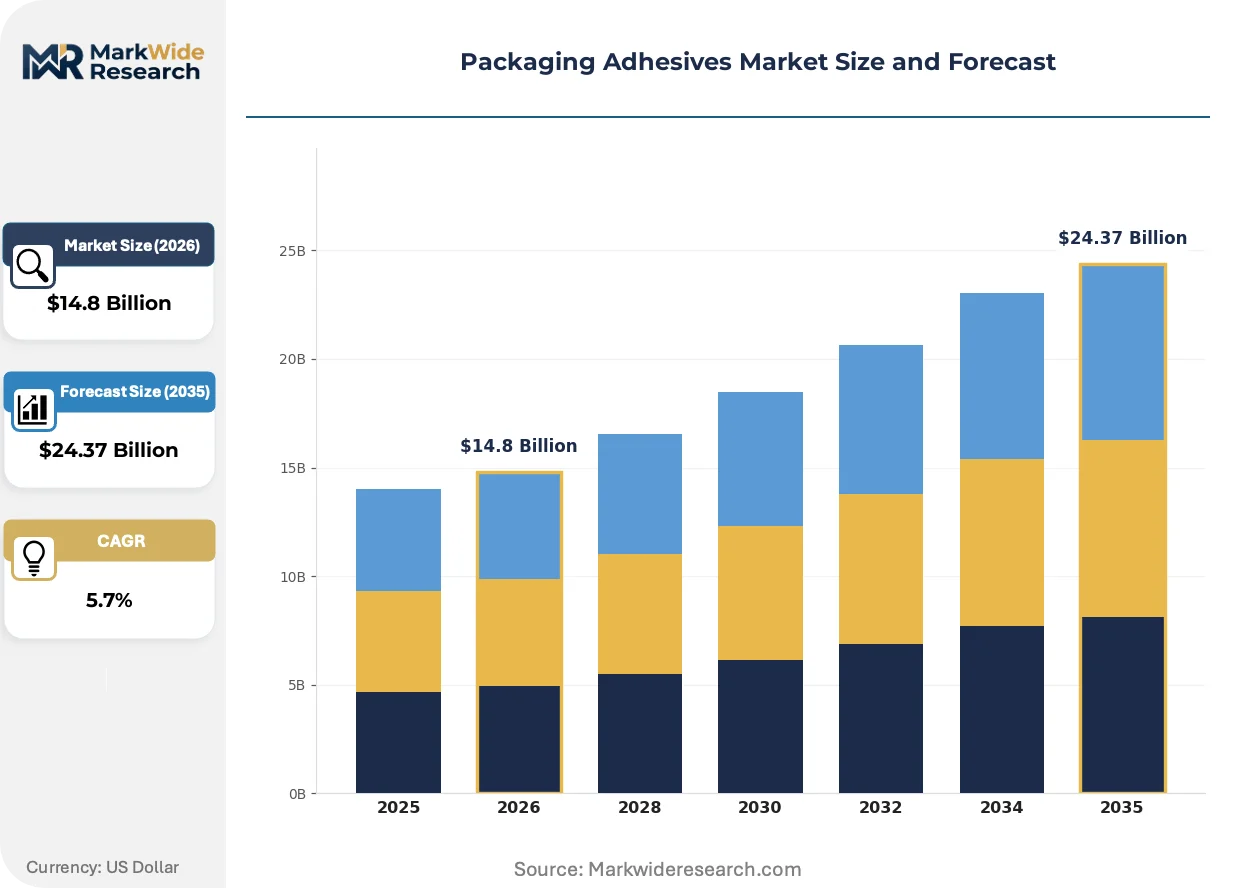
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Melt, Water-Based, Solvent-Based, UV-Curable Application: Flexible Packaging, Rigid Packaging, Labels, Sealing Material: Polyethylene, Polypropylene, Paper, Film End User: Food & Beverage, Consumer Goods, Healthcare, Electronics |
| Companies Covered | Arkema, Sika AG, Henkel AG & Co. KGaA, Wacker Chemie AG, Avery Dennison Corporation, H.B. Fuller Company, Dow, Huntsman Corporation, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Adhesives Market Strategic Shifts & Innovations
Formulation science is undergoing a significant transformation, driven by digitalization and the imperatives of a circular economy. This evolution prioritizes predictive modeling in development and end-of-life performance in material selection, altering traditional R&D and procurement cycles.
Digital Twinning
Digital twinning and material informatics platforms model adhesive performance with various substrates under different environmental conditions before physical compounding. R&D departments at major formulators are the primary adopters, using these tools to screen novel polymer combinations. This shift is virtualizing a large portion of the traditionally material-intensive product development process, compressing innovation timelines.
Sustainability Reporting Mandates
Europe's Corporate Sustainability Reporting Directive (CSRD) is reshaping supply chain transparency. The regulation compels companies to disclose detailed data on the environmental impact of their products, including the carbon footprint and recyclability of components like adhesives. This forces consumer goods brands and packaging converters to demand verifiable sustainability metrics from their adhesive suppliers, especially those operating in the EU.
Total Cost of Ownership Models
Brand owners and converters are shifting from purchasing adhesives as a commodity to procuring bonding solutions evaluated on a total cost of ownership basis. This model disrupts traditional volume-based sales by factoring in metrics like reduced line stoppages, lower energy consumption for curing, and decreased material waste. This trend is most visible within highly automated food and beverage packaging facilities in Germany and the United States.
Packaging Adhesives Market Segmentation
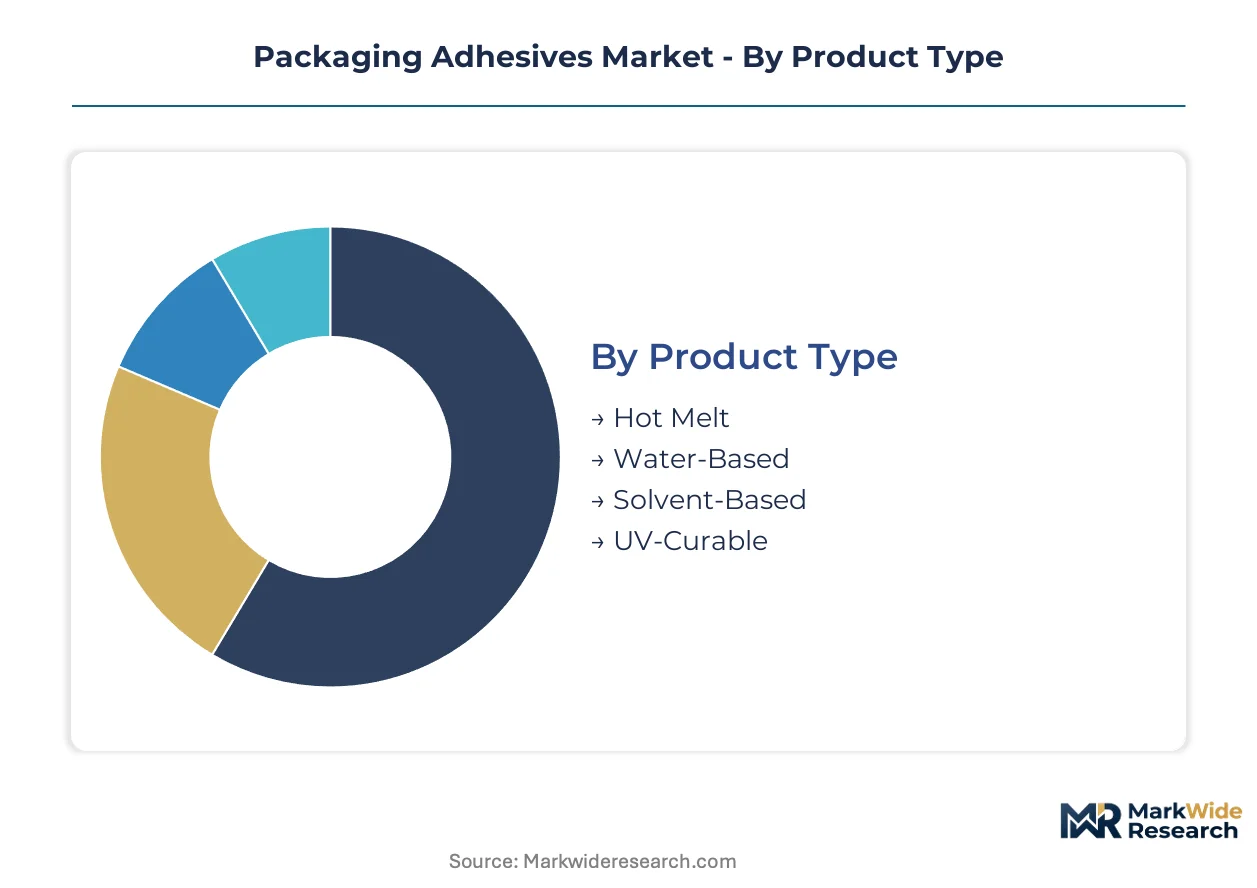
The packaging adhesives market is highly diversified, reflecting the varied performance requirements across different packaging formats and end-use applications. Understanding these distinct segments is crucial for formulators to address specific technical challenges and regulatory mandates efficiently.
Product Type:
The packaging adhesives market encompasses a diverse use-case spectrum, driven by specialized product types engineered for distinct bonding requirements.
- Hot Melt:These are thermoplastic polymers applied molten, rapidly solidifying upon cooling to form a strong bond. Hot melt adhesives are critical for high-speed automated flexible packaging lines, especially in the food & beverage sector in China, due to their fast setting times.
- Water-Based:Comprising polymer dispersions or emulsions where water acts as the carrier, these adhesives cure as water evaporates. They find extensive use in paper and board applications due to their cost-effectiveness and regulatory compliance in Europe for indirect food contact.
- Solvent-Based:Adhesives dissolved in organic solvents, offering strong bonds and good resistance to environmental factors. Their use is declining due to increasingly stringent VOC regulations, particularly in the United States and Germany.
- UV-Curable:Liquid adhesives that polymerize rapidly when exposed to ultraviolet light, offering instant cure speeds. These are valued for precision bonding in specialized electronics packaging and graphic arts applications.
The dominant share belongs to Water-Based adhesives, while Hot Melt solutions are closing the gap fastest.
Application:
Application complexity dictates adhesive selection across various packaging formats, from flexible films to rigid containers.
- Flexible Packaging:This segment utilizes specialized laminating and cold-seal adhesives for pouches, sachets, and films. Flexible packaging is experiencing significant growth, particularly in India and China, driven by consumer shifts towards convenience.
- Labels:Requires adhesives designed for diverse substrates and environmental conditions, including wash-off or de-bondable types for enhanced recyclability. Demand is high for consumer goods packaging in Germany, where sustainability mandates are strict.
- Rigid Packaging:Employs adhesives for bonding corrugated boxes, folding cartons, and other structured containers. This application benefits from the expansion of e-commerce, especially for secondary and tertiary packaging in the United States.
- Sealing:Focuses on end-of-line carton and tray sealing, prioritizing fast cure speeds and strong tamper-evident bonds. Automated packaging lines in Europe drive demand for highly efficient sealing solutions.
This segment is characterized by the diverse performance demands of packaging lines, with Flexible Packaging showing the most dynamic expansion.
Material:
Substrate compatibility is a primary consideration in adhesive formulation, ensuring optimal bond strength and durability.
- Paper:Requires water-based and starch-based adhesives for cost-effective bonding of corrugated board and cartons. This material remains a cornerstone for secondary and tertiary packaging, particularly in the United States and Japan.
- Film:Demands specialized laminating adhesives for multi-layer structures, crucial for barrier properties in food packaging. Polyethylene and polypropylene films dominate flexible packaging applications in China.
- Polyethylene:Utilizes specific hot melt and solvent-based formulations for robust adhesion in flexible packaging and container sealing. Its versatility drives widespread use across many consumer product categories.
- Polypropylene:Requires adhesives with good adhesion to its low surface energy, often found in labels and flexible packaging applications. Innovation focuses on enhancing bond strength for this challenging material.
Adhesive innovation in this category is heavily influenced by the material's surface properties, with Paper representing the largest volume.
End User:
Regulatory stringency and specific product protection needs define adhesive requirements across various end-user industries.
- Food & Beverage:This sector requires non-migrating, low-VOC adhesive formulations compliant with FDA and EU food-contact regulations. Food & beverage drives significant demand for flexible packaging solutions, particularly in India.
- Consumer Goods:Utilizes a broad spectrum of adhesives for diverse packaging, including personal care products, household items, and electronics. E-commerce expansion boosts demand for reliable carton sealing in Germany for these products.
- Healthcare:Demands high-performance, sterilizable adhesives for medical device packaging and pharmaceutical applications. Compliance with strict regulatory standards like those from the U.S. FDA is paramount.
- Electronics:Employs specialized conductive or functional adhesives for sensitive components and smart packaging applications. This segment values precision bonding and material compatibility.
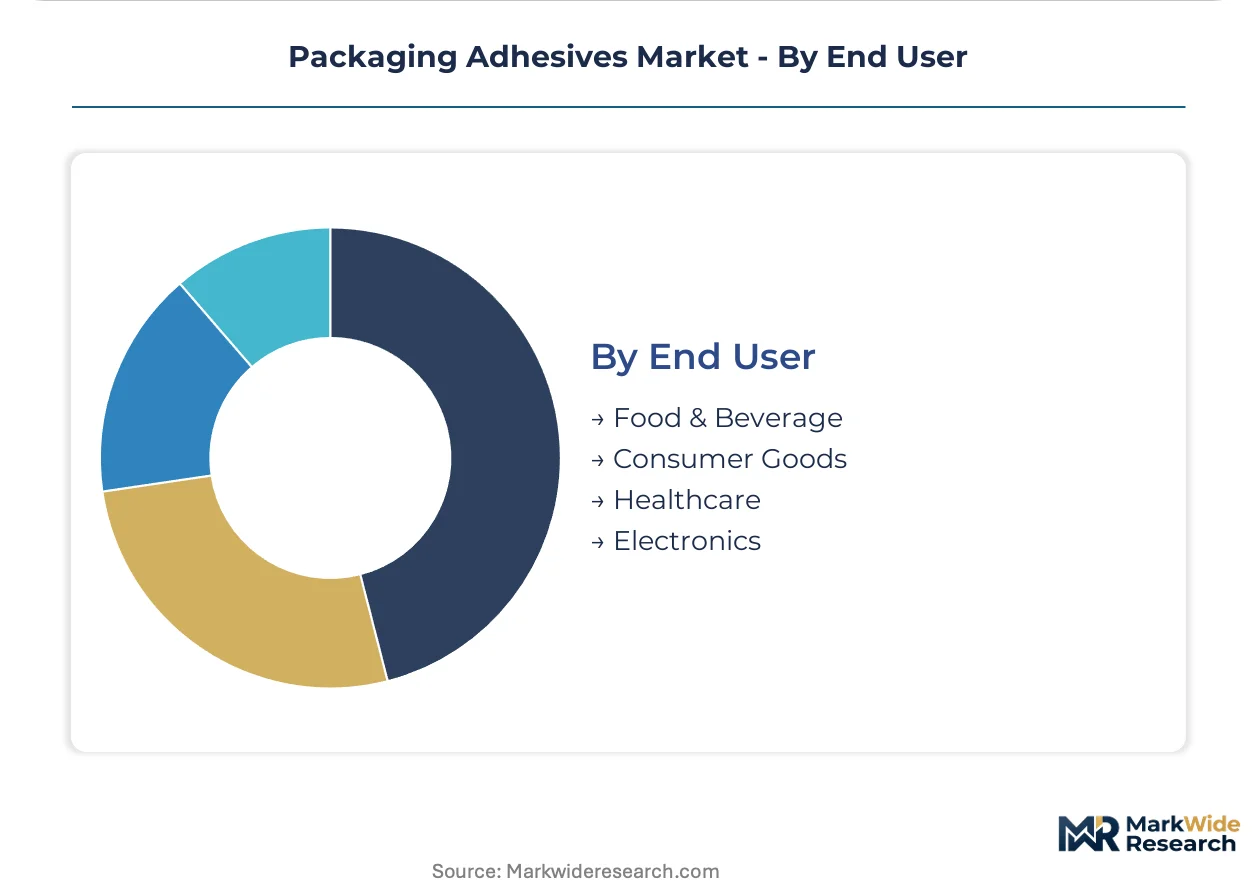
The Food & Beverage sector remains the largest consumer, while the Healthcare segment demands the most specialized formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory initiatives, such as the EU Green Deal and U.S. sustainability mandates, are fundamentally reshaping regional demand for packaging adhesives. These policies compel formulators to innovate in bio-based and recyclable materials, while stringent food safety regulations drive demand for non-migrating formulations across key markets. Consumption patterns for packaging adhesives reflect diverse industrial bases and consumer preferences in each major economy.
China
Rapid expansion of e-commerce and consumer goods manufacturing drives demand for hot melt adhesives in flexible packaging applications. China's GB standards for food packaging materials dictate formulation choices, emphasizing compliance for market access. Industrial clusters in the Yangtze River Delta and Pearl River Delta lead in adopting high-speed automated packaging lines.
India
A consumer shift toward pouches and sachets in the food and beverage industry fuels demand for specialized laminating and cold-seal adhesives. The Food Safety and Standards Authority of India (FSSAI) mandates strict food contact regulations, compelling innovation in safe formulations. Major manufacturing hubs in Maharashtra and Gujarat are key centers for packaging adhesive consumption.
United States
E-commerce expansion significantly boosts consumption of hot melt and water-based adhesives for corrugated boxes and protective mailers. The U.S. FDA's regulations for indirect food additives compel innovation in non-migrating, low-VOC adhesive formulations. Packaging and logistics operations across the Midwest and Southeast regions drive substantial adhesive volumes.
Germany
Strict sustainability mandates and automated food and beverage packaging facilities drive demand for advanced, recyclable, and bio-based adhesive solutions. Europe's Corporate Sustainability Reporting Directive (CSRD) forces transparency in environmental impact, influencing procurement decisions. North Rhine-Westphalia and Bavaria remain centers for advanced packaging and consumer goods manufacturing.
Japan
Emphasis on high-quality paper and board applications supports consistent demand for water-based and starch-based adhesives for secondary and tertiary packaging. Japan Industrial Standards (JIS) influence material specifications and performance requirements for packaging components. The Kanto region, including Tokyo, serves as a hub for sophisticated packaging innovation and consumer product development.
Packaging Adhesives Market Key Industry Players
On the supply side, the industry is undergoing a structural shift, moving away from fully integrated chemical giants toward more specialized, asset-light manufacturing models. This dynamic fosters a tiered competitive structure, where large chemical conglomerates coexist with focused adhesive formulators and niche technology providers. Key strategic archetypes include diversified chemical producers, specialized adhesive manufacturers, and regional players catering to specific market needs. Competitive moves center on M&A for portfolio expansion, significant R&D investment in sustainable formulations, and strategic partnerships for market access.
Specialized formulators like H.B. Fuller Company and Henkel AG & Co. KGaA exemplify this market evolution, offering broad portfolios and extensive global distribution networks. H.B. Fuller Company represents a player focused on diverse packaging needs with hot melt and water-based solutions. Henkel AG & Co. KGaA occupies a leadership position, leveraging strong brand recognition in consumer goods. Diversified chemical producers such as Dow anchor the supply chain, providing foundational raw materials while also developing specialized adhesive solutions.
| Leading Market Players |
|---|
| Arkema |
| Sika AG |
| Henkel AG & Co. KGaA |
| Wacker Chemie AG |
| Avery Dennison Corporation |
| H.B. Fuller Company |
| Dow |
| Huntsman Corporation |
| 3M Company |
Cost & Logistics Intelligence
Underutilized bio-based adhesive capacity in Europe drives supplier innovation and competitive pricing strategies. This dynamic influences investment in new sustainable formulations and impacts market entry for new product types.
Pricing Analysis
Certification level (FDA/EU food-contact grade) creates the primary spread in packaging adhesive pricing. The market operates on a hybrid model, combining value-based pricing for specialized formulations and contract-based long-term offtake for high-volume applications. Pricing softness stems from raw material volatility, particularly for petrochemical feedstocks like EVA. The Food & Beverage sector demonstrates lower price sensitivity due to stringent regulatory compliance, while Consumer Goods buyers are more cost-conscious.
Supply Chain Analysis
Upstream feedstock availability for polymers like ethylene vinyl acetate (EVA) and polylactic acid (PLA) significantly influences the packaging adhesives supply chain. Supply concentration centers around major chemical producers in China, the United States, and Germany. The industry relies on these foundational raw materials. Commodity price volatility for petrochemical feedstocks presents a structural supply chain risk. Distribution runs through a dual model, with direct sales to large packaging converters and specialized distributors serving smaller or niche formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The packaging adhesives market presents a significant service-attach opportunity, with digital twinning and material informatics expanding faster than traditional product sales. These platforms offer predictive performance modeling, creating a recurring-revenue layer for formulators.
For Market Incumbents: Construct a regulatory compliance moat through proactive investment in food-contact certification and advanced migration analysis. Diversified chemical producers like Dow must deepen R&D into bio-based formulations to counter emerging bio-based adhesive startups. Strategic partnerships with packaging converters can secure long-term supply agreements. Focus on high-speed automated lines in Germany and the United States for sustained volume.
For New Entrants and Emerging Players: Build out specialized portfolios targeting "wash-off" and de-bondable adhesives for enhanced recyclability. The labels segment, particularly for PET containers in Europe, offers a penetrable entry point. Formulate conductive adhesives for smart packaging integration, leveraging RFID and NFC technologies. Co-development with brand owners seeking circular economy solutions provides a strong go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward niche formulators with proprietary bio-based adhesive intellectual property and strong regulatory compliance expertise. Long-term viability over a five-to-ten-year window hinges on sustainability-driven innovation and circular economy alignment. Target companies demonstrating robust testing capabilities for food-contact materials. The signal to watch for inflection is a significant uptick in Corporate Sustainability Reporting Directive (CSRD) compliance requirements among consumer goods brands.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based R&D Investment | Accelerates development of adhesives compliant with EU Green Deal mandates. |
| Digital Twinning Adoption | Compresses innovation timelines for novel polymer combinations in Germany. |
| Food-Contact Certification Expansion | Secures market access for non-migrating formulations in the U.S. Food & Beverage sector. |
| "Wash-Off" Adhesive Development | Enhances recyclability of labels and flexible packaging, aligning with brand owner goals. |
| Supply Chain Digitization | Improves transparency and traceability of raw materials like EVA, mitigating volatility risks. |
Research Approach
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings for packaging adhesives. Conversations with R&D directors, procurement leads at packaging converters, packaging engineers, and regulatory affairs specialists provided granular insights. Secondary validation drew from industry association reports, government regulatory databases like the U.S. FDA, and company financial filings. A blend of bottom-up volume analysis and top-down market sizing ensured robust data triangulation.
Calibration of historical growth patterns against projected market dynamics formed the basis of the quantitative forecast across the analysis window. The model segmented the market by product type, application, material, end-user, and key geographic regions like China and the United States. Compound Annual Growth Rates (CAGRs) were derived from a multi-factor regression analysis. Key industry-specific forecast inputs included e-commerce expansion rates and flexible packaging consumption trends in emerging economies.
The forecast holds incumbent behavior within observed patterns; aggressive moves by specialized adhesive manufacturers or diversified chemical producers would shift outcomes. This analysis assumes current regulatory frameworks, such as Europe's REACH, remain consistent. Significant raw material supply disruptions or unforeseen regulatory shifts could alter market trajectories. Cross-checking against external market intelligence reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Spain Adhesives Market
Adhesives & Sealants
Epoxy Glue Market
Adhesives & Sealants
Elastic Bonding Adhesive and Sealant Market
Adhesives & Sealants
Co-Polymer Sealants Market
Adhesives & Sealants
Tile and Stone Adhesive Market
Adhesives & Sealants
Specialty Adhesives Market
Adhesives & Sealants
Skin Adhesives Market
Adhesives & Sealants
Asia-Pacific Reactive Adhesives Market
Adhesives & Sealants
Adhesives and Sealants Market
Adhesives & Sealants
Global Ethyl Methacrylate (97-63-2) Market
Adhesives & Sealants
Global Automotive Adhesive Market
Adhesives & Sealants
Adhesive Equipment Market
Adhesives & Sealants
Global Adhesives Market
Adhesives & Sealants
Global Human Fibrin Glue Market
Adhesives & Sealants
Global Construction Adhesive Tapes Market
Adhesives & Sealants
High Performance Adhesives Market