
 Energy Metering IC Chip Market | 2026-2036
Energy Metering IC Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Metering IC Chip Market Foresight
Semiconductor design talent with mixed-signal expertise is rotating toward energy metering applications as power utilities modernize infrastructure. Texas Instruments Incorporated leverages its analog portfolio depth to sustain leadership in high-precision measurement front-ends. Analog Devices, Inc. anchors its position through integrated metrology solutions that reduce bill-of-material complexity for meter manufacturers. STMicroelectronics N.V. competes on manufacturing scale across European and Asian production bases.
An energy metering IC chip is a purpose-built semiconductor device that combines analog-to-digital converters, digital signal processors, and communication interfaces to measure voltage, current, power factor, and energy consumption with accuracy classes typically spanning 0.1% to 1.0% error margins. These chips enable automated billing, load profiling, and grid stability monitoring across residential, commercial, and industrial installations. Mixed signal components command the deepest margin pools because they integrate precision analog sensing with digital processing in single-die architectures that OEMs prefer for cost and reliability. Single-phase technology dominates residential deployments while three-phase variants capture industrial automation and commercial building segments where higher power levels require multi-channel measurement. Smart grid application demand outpaces energy monitoring as utilities prioritize bi-directional communication and real-time load balancing over passive measurement.
The US Federal Energy Regulatory Commission shapes wholesale market participation rules that mandate interval metering for competitive suppliers, while the EPA's energy efficiency programs indirectly drive residential smart meter penetration through utility rebate structures. Europe's CE marking and MID certification requirements create compliance barriers that favor established semiconductor vendors with accredited testing histories. China's GB standards and MIIT technical regulations enforce domestic content preferences that localize supply chains for state-grid procurement. Stakeholders must monitor how evolving cybersecurity mandates for connected metering infrastructure reshape chip architecture requirements and vendor qualification timelines.
Market Dynamics
The European Union's F-Gas Regulation is forcing semiconductor manufacturers to eliminate high-global-warming-potential gases from wafer processing, compressing fabrication timelines and elevating compliance costs for energy metering IC production.
Growth Catalysts
- China's dual carbon goals:State-backed smart meter replacement programs are procuring precision measurement components at scale, creating sustained demand pull for mixed-signal architectures.
- Interval metering mandates:The US Federal Energy Regulatory Commission's wholesale market participation rules require competitive suppliers to deploy time-synchronized measurement infrastructure.
- Bi-directional communication protocols:Power utilities are prioritizing real-time load balancing capabilities that integrate metrology with RF subsystems on single silicon.
Market Restraints
- 300mm wafer supply concentration:Taiwan-based foundries control advanced mixed-signal fabrication capacity, exposing meter IC vendors to geopolitical supply disruption.
- Precision voltage reference material costs:Bandgap reference circuits require specialized epitaxial processes that resist cost-down scaling.
- CE marking certification friction:MID certification requirements create 18-24 month qualification barriers that favor incumbents with accredited testing histories.
Strategic Opportunities
- India's smart grid buildout:The country's central electricity authority is mandating smart metering for 250 million connections, opening procurement channels for certified component vendors.
- Edge AI metrology convergence:Neural network inference engines integrated with ADC front-ends enable anomaly detection without cloud dependency.
- Direct utility procurement channels:State-grid procurement offices in China and India are bypassing traditional distribution tiers for high-volume IC contracts.
Industry Challenges
- Mixed-signal design talent scarcity:Analog-to-digital converter architecture expertise is concentrating at legacy IDMs, constraining fabless entrants.
- Multi-jurisdiction certification stacking:Simultaneous MID, GB standard, and FCC Part 15 approvals extend product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Metering IC Chip Market |
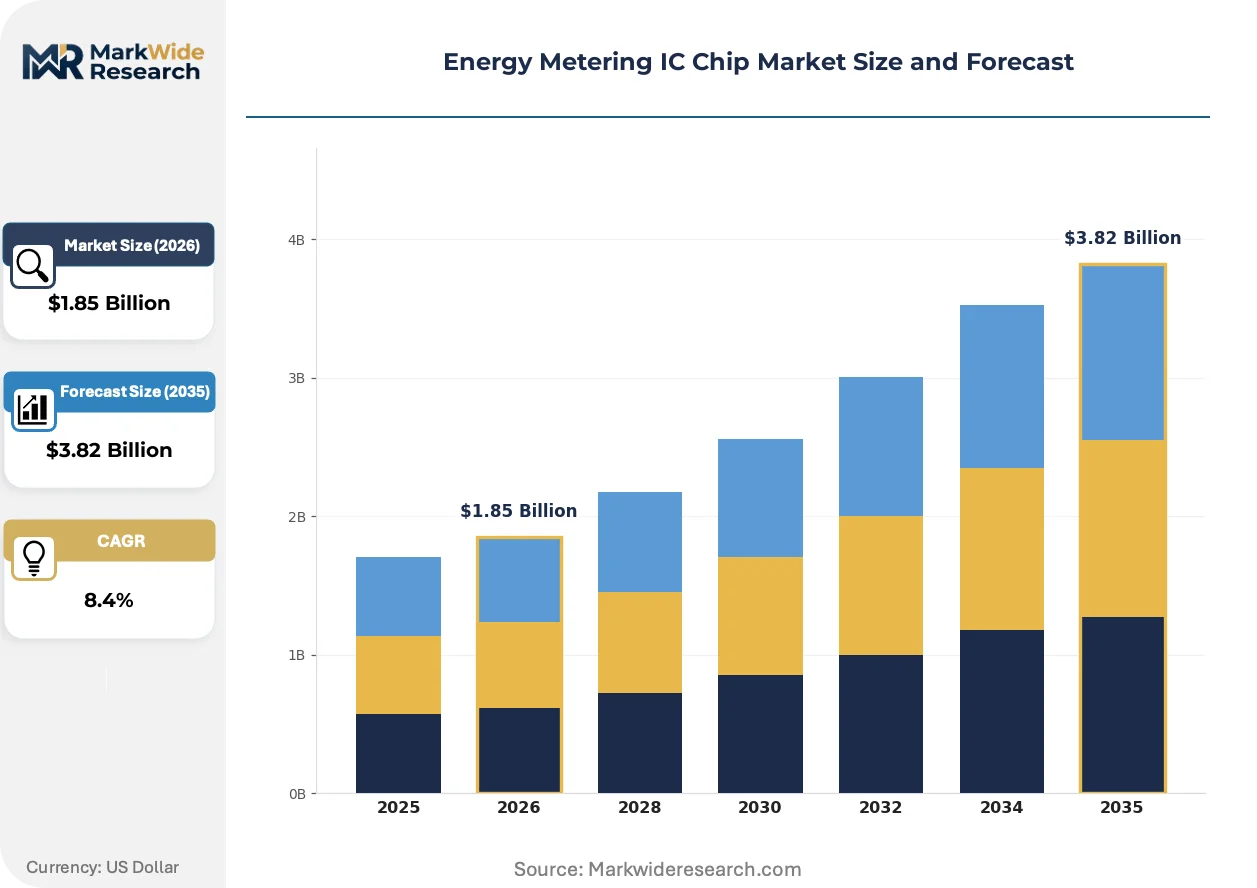
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Analog, Digital, Mixed Signal, Power Line Communication Application: Smart Grids, Smart Meters, Energy Monitoring, Industrial Automation End User: Utilities, Manufacturers, Residential Users, Commercial Users Technology: Single-Phase, Three-Phase, Wireless, Wired |
| Companies Covered | Texas Instruments Incorporated, Analog Devices, Inc., STMicroelectronics N.V., Renesas Electronics Corporation, NXP Semiconductors N.V., Microchip Technology Inc., Cirrus Logic, Inc., Infineon Technologies AG, Silicon Laboratories, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Metering IC Chip Market Shifts & Advancements
Silicon architectures for energy measurement are fragmenting into specialized compute islands that separate metrology precision from communication overhead, enabling modular upgrade paths without full chip redesign.
Multi-core DSP architectures with dedicated metrology accelerators are decomposing traditional monolithic metering designs into function-specific processing blocks. European meter manufacturers are adopting these heterogeneous designs to isolate safety-critical measurement paths from protocol-handling firmware. This decomposition is compressing time-to-certification by allowing independent validation of measurement accuracy and communication stacks.
The EU's F-Gas Regulation is banning sulfur hexafluoride and perfluorocarbons from semiconductor manufacturing processes by 2030. Wafer fabs serving the metering IC market are retrofitting etch and clean equipment for fluorinated gas alternatives. German and French production bases face the steepest transition costs due to older tool installations and stricter national environmental enforcement.
Utility procurement offices are consolidating vendor qualification lists to three approved sources per component category, compressing competitive access for second-tier semiconductor suppliers. Chinese state-grid procurement and Indian distribution companies are driving this concentration through master service agreements that bundle multi-year IC supply with firmware maintenance. Meter OEMs in these markets are responding by deepening technical collaboration with qualified chip vendors during the design phase rather than at production ramp.
Energy Metering IC Chip Market Segmentation
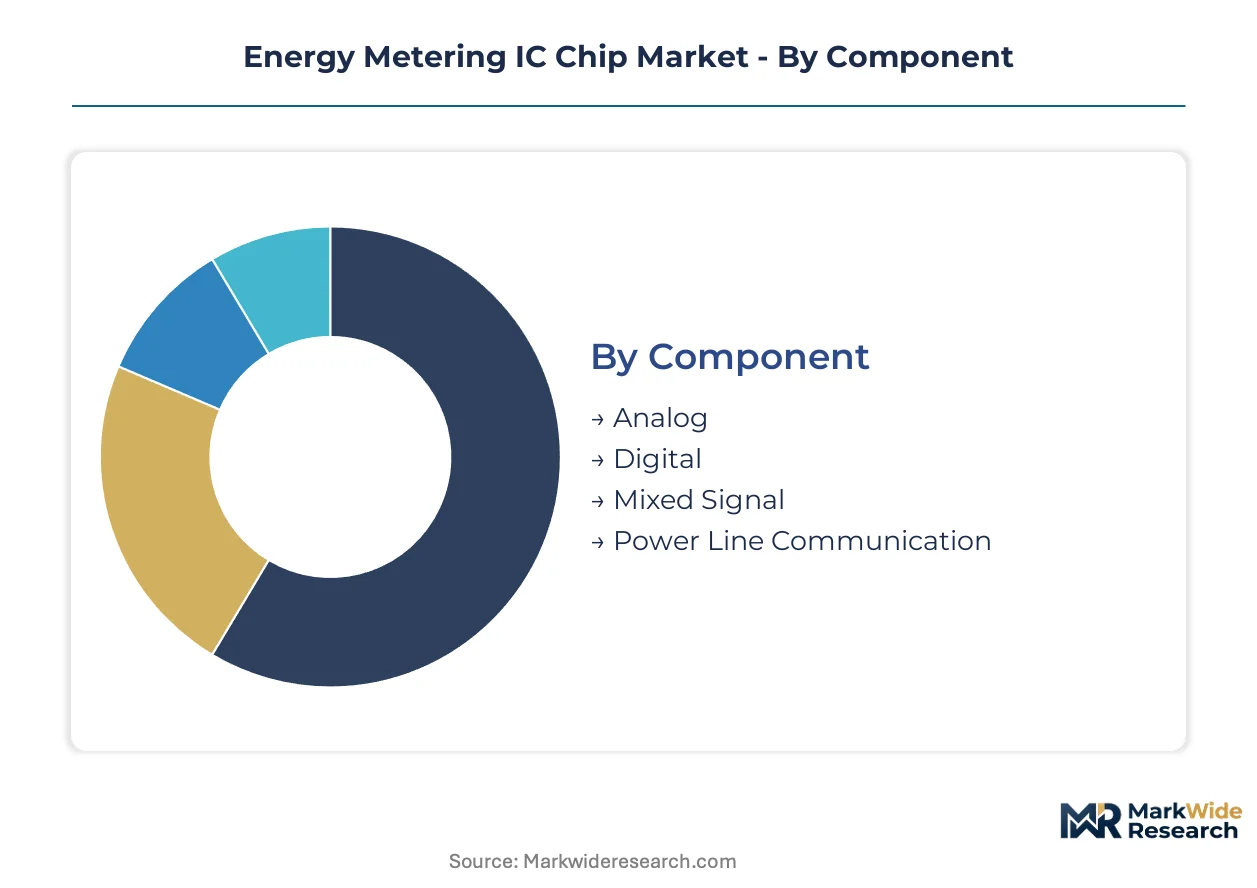
Segmentation in energy metering ICs reveals how procurement patterns fragment across utility modernization cycles, manufacturing automation needs, and residential electrification waves. Each dimension exposes different margin structures, certification requirements, and design-in barriers that shape vendor strategy.
Component:
Mixed signal and analog components concentrate in China and India where state-grid procurement drives domestic demand, while digital and power line communication chips serve export markets with stricter MID certification timelines.
- Analog:Precision voltage reference circuits and transimpedance amplifiers form the sensing front-end for current transformers. Demand clusters in European meter OEMs sourcing from German and French production bases to satisfy CE marking proximity requirements.
- Mixed Signal:Single-die architectures integrating ADC arrays with DSP cores reduce bill-of-material complexity for high-volume manufacturers. China's dual carbon goals are pulling procurement volumes for mixed-signal ICs through state-backed smart meter replacement programs at scale.
- Digital:Protocol processing engines and secure element cores handle communication stacks and cryptographic authentication.
- Power Line Communication:OFDM modems and coupling circuits enable data transmission over existing electrical infrastructure.
Mixed signal holds the largest share; momentum sits with power line communication as utilities prioritize bi-directional grid communication.
Application:
Cost tier separation runs deepest here, with smart grids commanding premium pricing for certified components while energy monitoring solutions compete on per-channel cost metrics.
- Smart Grids:Utility-scale deployments require synchronized phasor measurement and real-time load balancing capabilities. India's central electricity authority mandates smart metering for 250 million connections, opening procurement channels for certified vendors.
- Smart Meters:Residential and commercial endpoints combine metrology precision with RF subsystems for automated billing. China's state-grid procurement offices are bypassing distribution tiers for direct IC contracts at volume.
- Energy Monitoring:Sub-metering solutions for commercial buildings and industrial facilities track consumption by zone or equipment.
- Industrial Automation:Motor control integration and power quality monitoring serve manufacturing environments.
Smart meters dominate volume; smart grids are climbing the fastest as grid modernization accelerates.
End User:
Volume concentration sits with utilities consolidating vendor lists to three approved sources per component category, compressing access for second-tier suppliers.
- Utilities:State-grid procurement offices in China and India drive master service agreements bundling multi-year IC supply with firmware maintenance. FERC wholesale market participation rules mandate interval metering infrastructure for competitive suppliers in the US.
- Residential Users:Single-phase meter deployments scale through utility rebate programs and building code mandates. EPA energy efficiency programs indirectly drive penetration through rebate structures.
- Manufacturers:Meter OEMs deepen technical collaboration with qualified chip vendors during design phase rather than at production ramp.
- Commercial Users:Multi-tenant buildings and retail chains deploy sub-metering for tenant billing and sustainability reporting.
Utilities command the largest procurement value; commercial users are expanding most quickly behind ESG disclosure requirements.
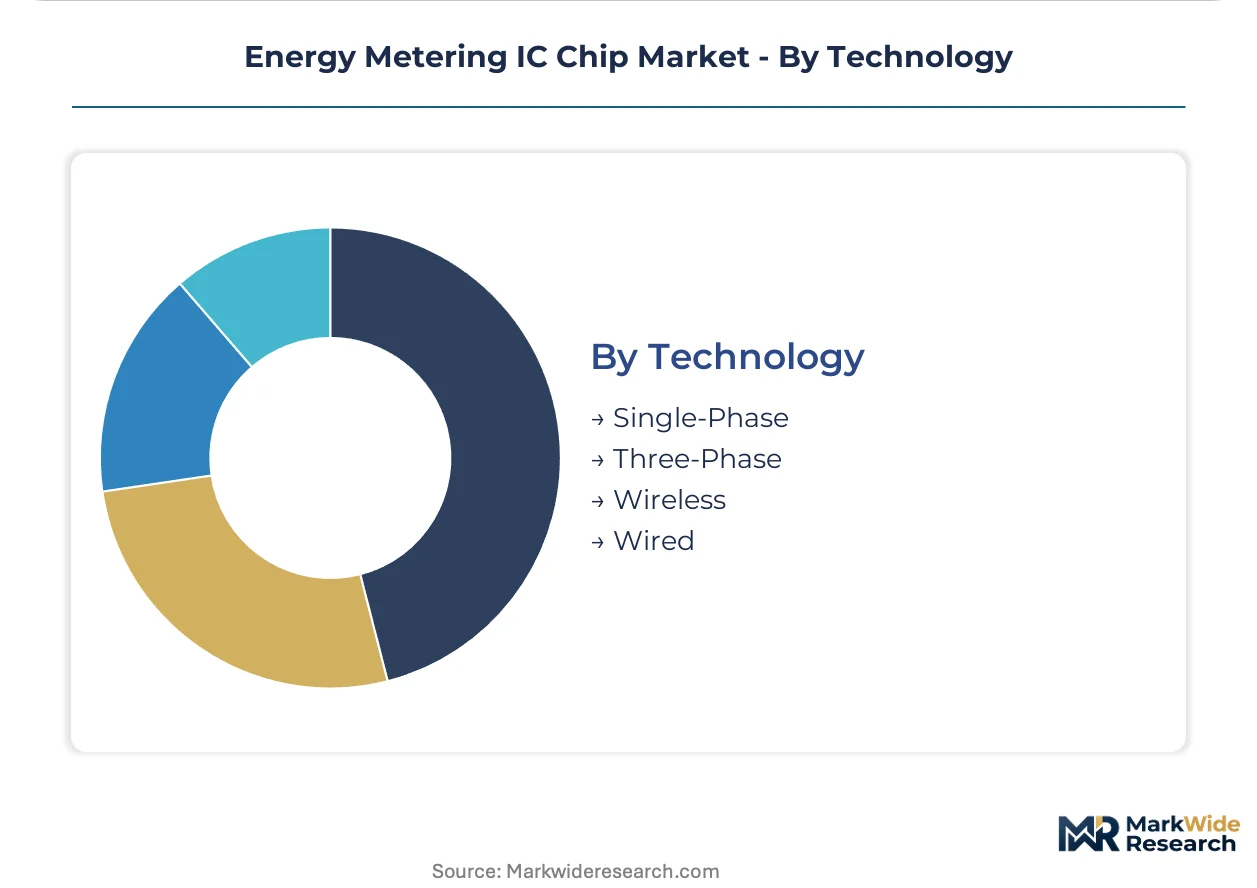
Technology:
Maturity gradients separate established wired and single-phase architectures from emerging wireless and three-phase variants with steeper certification curves.
- Single-Phase:Two-wire measurement circuits serve residential deployments with simplified calibration requirements. China's GB standards enforce domestic content preferences that localize supply chains for state-grid single-phase procurement.
- Three-Phase:Multi-channel measurement engines handle industrial automation and commercial building segments where higher power levels demand vector sum calculations. European meter manufacturers adopt heterogeneous designs isolating safety-critical measurement paths from protocol firmware.
- Wireless:RF subsystems integrating metrology with communication stacks enable deployment without dedicated wiring infrastructure.
- Wired:RS-485, M-Bus, and power line communication provide deterministic connectivity for utility-controlled endpoints.
Single-phase retains volume leadership; wireless is gaining share fastest behind edge AI metrology convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes energy metering ICs through state-directed smart meter replacement at utility scale, while Europe and India emphasize certification-heavy grid modernization with longer procurement cycles and stricter environmental compliance.
China
State-grid procurement offices drive volume through direct IC contracts bypassing distribution tiers. MIIT technical regulations and GB standards enforce domestic content preferences that localize supply chains. Yangtze River Delta fabs concentrate mixed-signal production for residential single-phase meter programs aligned with dual carbon goals.
United States
FERC wholesale market participation rules mandate interval metering infrastructure for competitive suppliers across deregulated markets. EPA energy efficiency programs channel rebate structures through utilities to accelerate residential smart meter penetration. Texas and California utilities consolidate vendor qualification lists to three approved sources per component category.
Germany
CE marking and MID certification requirements create 18-24 month qualification barriers favoring established semiconductor vendors with accredited testing histories. The EU's F-Gas Regulation forces wafer fab retrofits for fluorinated gas elimination by 2030. Bavarian and Saxon production bases face steepest transition costs due to older tool installations.
India
The Central Electricity Authority mandates smart metering for 250 million connections, opening procurement channels for certified component vendors. State distribution companies drive master service agreements bundling multi-year IC supply with firmware maintenance. Maharashtra and Gujarat meter OEMs deepen technical collaboration with qualified chip vendors during design phase.
Japan
METI grid modernization programs prioritize bi-directional communication and real-time load balancing capabilities. JIS standards enforce precision measurement requirements for industrial automation segments. Kanto and Kansai industrial clusters concentrate three-phase metering demand from manufacturing facilities and commercial building automation.
Energy Metering IC Chip Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the energy metering IC market. The upper tier commands premium positioning through analog portfolio depth and accredited certification histories that compress rival qualification timelines. Specialist competitors compete on manufacturing scale across European and Asian production bases or on integrated metrology solutions that reduce bill-of-material complexity. Dominant competitive moves include backward integration into precision voltage reference processes and strategic partnerships with state-grid procurement offices for direct volume contracts.
Among US-based integrated device manufacturers, Texas Instruments Incorporated and Analog Devices, Inc. occupy positions representing analog portfolio depth and integrated metrology specialization respectively. STMicroelectronics N.V. exemplifies the European scale-driven archetype with manufacturing bases across multiple continents. These three anchors illustrate how geographic production distribution and certification accreditation histories shape competitive access to utility procurement channels in China, India, and Europe.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Analog Devices, Inc. |
| STMicroelectronics N.V. |
| Renesas Electronics Corporation |
| NXP Semiconductors N.V. |
| Microchip Technology Inc. |
| Cirrus Logic, Inc. |
| Infineon Technologies AG |
| Silicon Laboratories, Inc. |
| Others |
Supply & Pricing Matrix
CE marking and MID certification regimes gate both supplier qualification and price tiering simultaneously, compressing competitive access for uncertified vendors while allowing accredited incumbents to command sustained premiums across European and Asian procurement channels.
Pricing Analysis
Long-term offtake contracts dominate utility-scale procurement, with China's state-grid offices and India's distribution companies bundling multi-year IC supply with firmware maintenance into master service agreements. Three-tier pricing structure across premium, standard, and economy levels separates MID-certified European vendors from GB-standard domestic suppliers and uncertified second-tier entrants. Cost compression in standard-tier mixed-signal components is intensifying because Yangtze River Delta fabs are absorbing F-Gas retrofit expenses into wafer pricing. Residential meter OEMs exhibit highest price sensitivity, while industrial automation buyers prioritize precision voltage reference stability over per-unit cost.
Supply Chain Analysis
Taiwan Strait transit vulnerabilities expose 300mm mixed-signal fabrication to geopolitical disruption, compressing buffer inventory strategies for meter IC vendors dependent on TSMC and UMC foundry allocations. Taiwan, South Korea, and Germany concentrate advanced analog-to-digital converter production, drawing from specialized epitaxial silicon, precision voltage reference materials, and fluorinated gas etch chemistries. Single-source vulnerability concentrates in bandgap reference circuit suppliers with captive epitaxial processes resisting substitution. Distribution runs through direct utility procurement channels in China and India, bypassing traditional semiconductor distribution tiers for volume contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Chinese and Indian state-grid procurement offices consolidate vendor qualification lists to three approved sources per component category, fragmenting access for second-tier semiconductor suppliers.
For Market Incumbents: Secure backward integration into precision voltage reference epitaxial processes to defend margin position against fabless entrants constrained by mixed-signal design talent scarcity. Deepen technical collaboration with meter OEMs during design phase rather than production ramp, locking in specification influence before competitor qualification. Monitor F-Gas Regulation compliance timelines as a regulatory shift that will eliminate competitors with older European tool installations. For New Entrants and Emerging Players: Lead with edge AI metrology convergence as a technical wedge, targeting India's 250 million-connection smart metering mandate where certification backlogs create temporary access windows for novel architectures. Focus on wireless three-phase variants for commercial building automation, the most penetrable segment behind ESG disclosure requirements accelerating sub-metering adoption. Pursue direct utility procurement channel development rather than distribution partnerships to bypass incumbent channel control. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive metering IC divisions lacking scale to justify continued R&D investment against specialized semiconductor competitors. Long-term viability hinges on analog portfolio depth and accredited certification histories that compress rival qualification timelines across multi-jurisdiction approval stacking. Watch for cybersecurity mandate implementation as an inflection indicator that reshapes chip architecture requirements and extends vendor qualification timelines favoring incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Voltage Reference | Captive epitaxial supply secures margin pools resisting cost-down scaling in mixed-signal architectures. |
| Direct State-Grid Procurement Channel Development | Master service agreements with China's MIIT-regulated offices bypass distribution tier compression. |
| Edge AI Metrology Convergence R&D | Neural network inference engines integrated with ADC front-ends enable anomaly detection without cloud dependency. |
| F-Gas Regulation Compliance Retrofit | German and French fab transitions eliminate competitors with older tool installations by 2030. |
| Multi-Jurisdiction Certification Stacking Investment | Simultaneous MID, GB standard, and FCC Part 15 approvals compress rival product launch timelines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility procurement officers, meter OEM design engineers, semiconductor foundry planning managers, and regulatory compliance specialists at certification bodies. Secondary validation drew from FERC wholesale market filings, EIA smart meter deployment databases, MIIT technical regulation publications, and CE marking accreditation records. Bottom-up unit shipment estimates triangulated against top-down utility capital expenditure forecasts across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning component type, application tier, end-user concentration, and technology maturity gradient. CAGRs were derived from utility modernization cycle phasing, state-grid procurement schedule visibility, and manufacturing automation content-per-meter trajectories. Forecast inputs incorporated F-Gas Regulation compliance cost pass-through assumptions and India CEA mandate implementation pacing.
The analysis sits within stated boundaries; outcomes outside sustained state-backed procurement volumes or accelerated F-Gas retrofit timelines would require recalibration. Forecasts reflect documented assumptions about certification backlog durations and foundry capacity allocation priorities. Practitioners should keep alternative scenarios live as cybersecurity mandate implementation and geopolitical supply disruption risks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Analog IC Market
IC (Integrated Circuits)
Gate Driver IC Market
IC (Integrated Circuits)
Motor Driver IC Market
IC (Integrated Circuits)
Global Computer and Peripherals Special Purpose Logic Ic Market
IC (Integrated Circuits)
Computer and Peripherals Standard Logic IC Market
IC (Integrated Circuits)
Japan Integrated Circuit (IC) Market
IC (Integrated Circuits)
Consumer Special Purpose Logic IC Market
IC (Integrated Circuits)
Global Amplifier and Comparator IC Market
IC (Integrated Circuits)
Integrated CMOS Tri-Gate Transistor Market
IC (Integrated Circuits)
China Logic Integrated Circuits Market
IC (Integrated Circuits)
Global Photonic Integrated Circuits (PIC) Market
IC (Integrated Circuits)
Global Analog Integrated Circuit (IC) Market
IC (Integrated Circuits)
Battery Fuel Gauge IC Market
IC (Integrated Circuits)
Europe Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global Interface IC Market
IC (Integrated Circuits)
Display LSI IC Market