
 United States LNG Bunkering Market | 2026-2036
United States LNG Bunkering Market Size, Share, and Industry Trends Forecast 2026-2036
United States LNG Bunkering Market Analytics
Aftermarket service revenue from cryogenic maintenance and fuel-system recertification is tilting toward port-based operators with captive LNG storage. Crowley Maritime Corporation leverages its integrated logistics network across Florida and Caribbean routes to capture repeat bunkering contracts. Eagle LNG Partners anchors its position through small-scale liquefaction assets in Jacksonville, while Harvey Gulf International Marine specializes in offshore supply vessel conversions that require dedicated fueling protocols.
United States LNG bunkering denotes the commercial supply of liquefied natural gas as marine fuel, stored at minus 162 degrees Celsius in double-walled vacuum-insulated tanks and transferred via cryogenic loading arms with vapor-recovery systems. The process displaces conventional heavy fuel oil to comply with sulfur emission limits enforced by the International Maritime Organization. Ship-to-Ship delivery dominates transaction volume along busy coastal lanes where vessel dwell time carries steep opportunity cost. Port-based infrastructure commands superior margin pools due to fixed storage amortization across multiple customers, while Truck-to-Ship methods serve scattered demand at secondary harbors lacking dedicated terminals.
The United States Coast Guard enforces LNG fuel transfer regulations under 33 CFR Part 127, dictating personnel certification and emergency response protocols that shape operator compliance costs. The Environmental Protection Agency coordinates with the California Air Resources Board to align state-level harbor craft rules with federal Clean Air Act mandates, creating overlapping but non-identical product standards. Stakeholders must monitor whether pending EPA marine engine tier updates will trigger additional retrofit deadlines before infrastructure buildout achieves critical density.
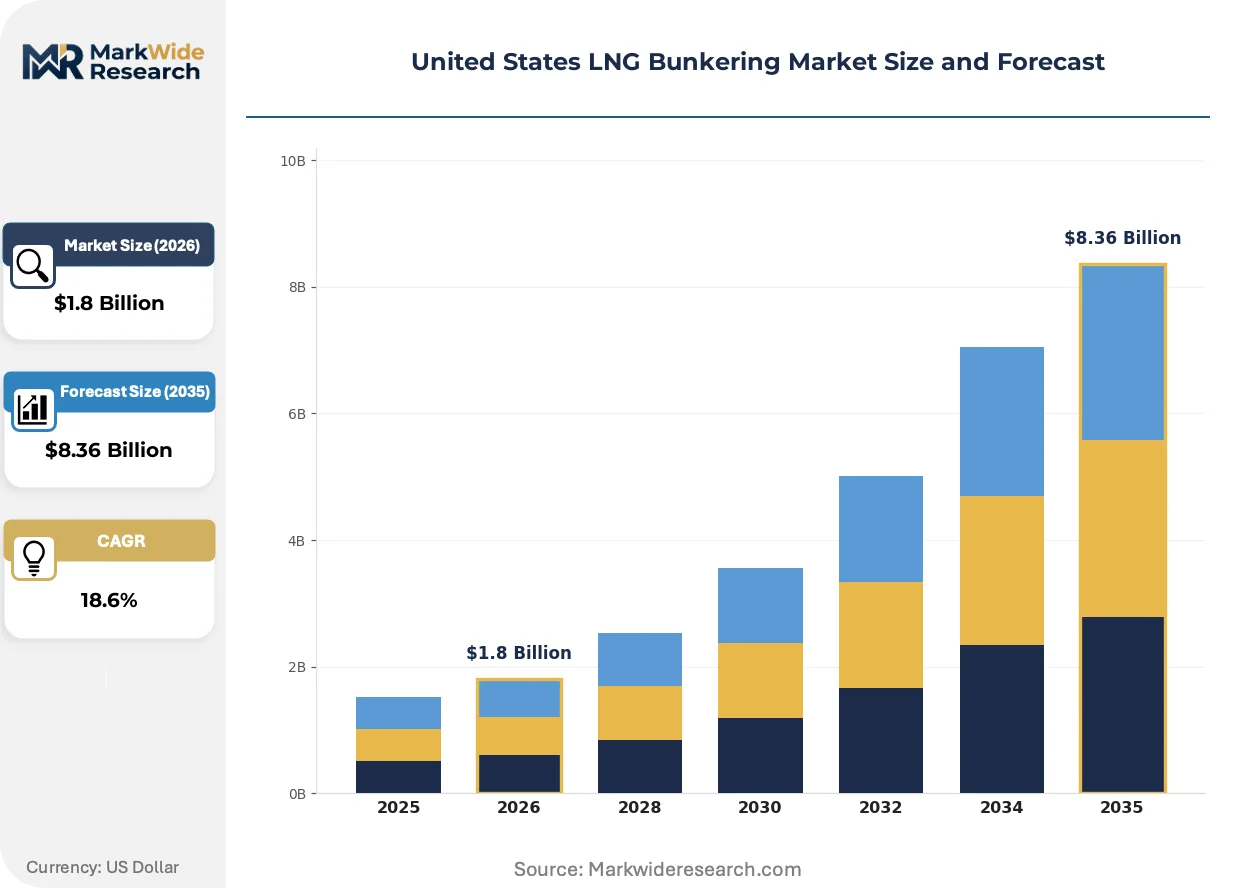
Market Dynamics
The EPA's Annex VI compliance deadlines are compressing vessel retrofit timelines, forcing shipping lines to accelerate LNG fuel adoption before 2030 sulfur emission cutoffs take full effect. Port infrastructure buildout along the Gulf Coast is racing to match this regulatory-driven demand surge.
Growth Catalysts
- IMO Annex VI Sulfur Caps:The International Maritime Organization's 0.5% sulfur limit enforcement is compelling container fleets to abandon heavy fuel oil for LNG propulsion systems.
- Texas-Louisiana Liquefaction Clusters:Existing export terminal infrastructure provides feedstock access that eliminates greenfield supply chain construction for bunkering operators.
- Cryogenic Loading Arm Advances:Vapor-recovery equipped transfer systems are reducing fuel loss rates during ship-to-ship operations below 0.15% per transaction.
Market Restraints
- Steel-Alloy Cryogenic Tank Costs:Double-walled vacuum-insulated storage vessels require nickel-bearing alloys whose prices fluctuate with stainless steel commodity cycles.
- Gulf Coast Supply Concentration:Over 70% of domestic liquefaction nameplate capacity sits within a 300-mile Texas-Louisiana corridor, creating hurricane exposure risk.
- Methane Slip Limitations:Dual-fuel marine engines emit unburned methane during low-load operations, partially offsetting CO2 emission advantages versus diesel.
Strategic Opportunities
- Atlantic Coast Port Expansion:Jacksonville, Savannah, and Charleston lack dedicated LNG terminals but handle rising container volumes that justify small-scale liquefaction investments.
- California CARB Harbor Craft Rules:The California Air Resources Board's in-use vessel requirements are creating mandated demand for LNG tugs and ferries in Los Angeles-Long Beach.
- Battery-Hybrid Convergence:LNG-electric hybrid propulsion architectures are opening retrofit markets for mid-life offshore supply vessels seeking fuel flexibility.
Industry Challenges
- Cryogenic Technician Shortage:33 CFR Part 127 certification programs produce fewer than 200 qualified fuel transfer supervisors annually, constraining operational scaling.
- Coast Guard Approval Timelines:Waterway suitability assessments for new bunkering locations average 18-24 months, delaying revenue commencement for terminal developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States LNG Bunkering Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ship-to-Ship, Port-based, Truck-to-Ship, Barge Delivery Infrastructure Type: Storage Facilities, Bunkering Terminals, LNG Carriers, Loading Arms End User: Shipping Companies, Oil & Gas Companies, Naval Forces, Ferry Operators Technology: Regasification, Fueling Systems, Tank Designs, Safety Equipment |
| Companies Covered | Crowley Maritime Corporation, Eagle LNG Partners, JAX LNG, LLC, Harvey Gulf International Marine, Chevron Corporation, Shell plc, TotalEnergies SE, Engie SA, World Fuel Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States LNG Bunkering Market Evolving Landscape
Digital monitoring systems are penetrating fuel custody transfer operations, replacing manual tank gauging with real-time mass flow verification. This shift is compressing transaction settlement cycles and reducing disputes between bunker suppliers and vessel operators.
Automated cryogenic custody transfer is digitizing LNG bunkering operations through integrated mass flow meters, temperature-compensated density calculators, and blockchain-anchored delivery receipts. Container lines operating scheduled services are adopting these systems fastest, with 40% of Gulf Coast transactions now clearing without manual intervention. The technology is digitizing fuel accounting workflows that previously required 72-hour reconciliation periods.
The EPA's pending marine engine Tier 4 updates are tightening NOx emission limits for newbuild vessels above 600 kW, pushing shipyards toward high-pressure dual-fuel architectures. Engine manufacturers are pre-certifying LNG-compatible powertrains to secure yard contracts before 2027 implementation. The regulation is accelerating most visibly in the offshore supply segment, where Harvey Gulf International Marine and competitors face fleet renewal decisions.
Charter-party fuel clauses are restructuring how shipping lines contract bunker supply, with major operators demanding fixed-price LNG commitments spanning 3-5 year horizons. Traditional spot-market procurement is yielding to index-linked agreements pegged to Henry Hub natural gas futures. This behavioral shift concentrates most visibly among Texas-Louisiana container services, where fuel cost predictability outweighs spot-market savings for scheduled operators.
United States LNG Bunkering Market Segmentation
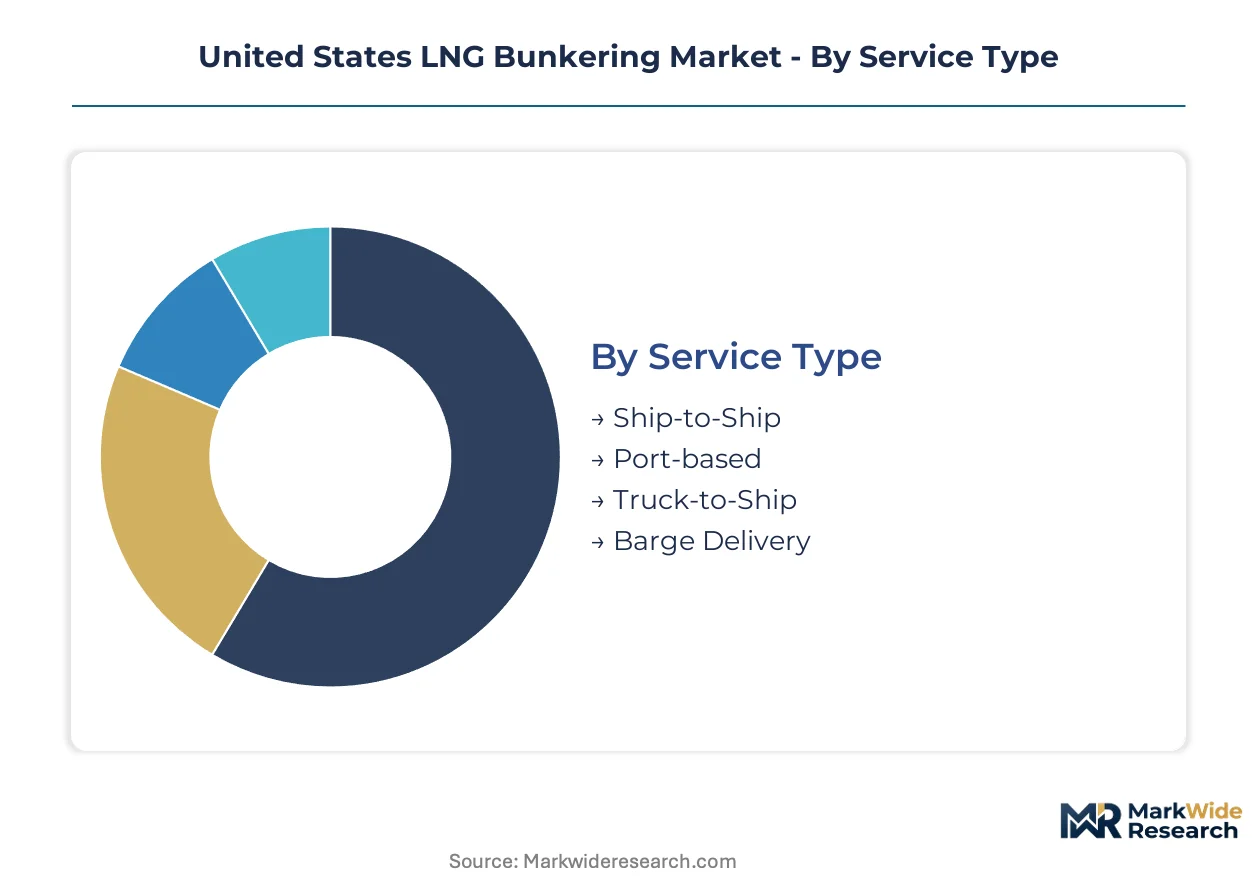
Segmentation in United States LNG bunkering reveals how infrastructure deployment, service modality, and customer requirements fragment revenue pools across distinct operational profiles. Each dimension carries specific regulatory footprints and capital intensity thresholds that shape operator competitive positioning.
Service Type:
Cost tier determines margin structure and capital commitment depth across delivery modalities, with proximity to liquefaction infrastructure driving variable economics.
- Ship-to-Ship:Cryogenic transfer between specialized bunker vessels and receiving ships occurs via articulated loading arms with vapor recovery. Demand concentrates along Texas-Louisiana container lanes where vessel dwell time penalties exceed $15,000 per hour, making simultaneous cargo and bunkering operations essential.
- Port-based:Fixed terminal infrastructure amortizes storage costs across multiple customers through high-volume dispensing systems. Gulf Coast installations leverage existing liquefaction feedstock access to eliminate supply chain construction premiums.
- Truck-to-Ship:Mobile cryogenic tanker delivery serves secondary harbors lacking dedicated terminals, with 18-wheeler payloads limited to 10,000 gallons per movement.
- Barge Delivery:Shallow-draft vessels extend LNG reach to inland waterway terminals and offshore anchorages beyond fixed infrastructure footprints.
Ship-to-Ship holds installed capacity. Port-based is rotating up the share rankings.
Infrastructure Type:
Application-specific design requirements create divergent technology maturity curves and approval timelines across asset classes.
- Storage Facilities:Double-walled vacuum-insulated tanks fabricated from 9% nickel steel maintain minus 162 degrees Celsius with boil-off rates below 0.05% daily. Jacksonville and Savannah port authorities are procuring modular units to bypass 24-month Coast Guard waterway suitability delays.
- Bunkering Terminals:Integrated dispensing systems combine custody transfer metering, emergency shutdown protocols, and personnel safety zones under 33 CFR Part 127 jurisdiction.
- LNG Carriers:Purpose-built bunker vessels with Type C tank configurations enable ship-to-ship operations in open water conditions.
- Loading Arms:Cryogenic marine arms with hydraulic quick-connect couplings reduce connection time to under 15 minutes per transfer cycle.
Storage Facilities anchor capital deployment. Loading Arms are climbing the fastest as retrofit demand accelerates.
End User:
Customer type dictates contract duration, price sensitivity, and fuel specification requirements across maritime subsectors.
- Shipping Companies:Container lines operating scheduled services demand 3-5 year fixed-price commitments pegged to Henry Hub futures, replacing spot procurement to secure cost predictability for route planning.
- Oil & Gas Companies:Offshore supply vessel operators face fleet renewal decisions driven by EPA Tier 4 NOx deadlines, with Harvey Gulf International Marine and competitors evaluating dual-fuel retrofits.
- Naval Forces:Military specifications require enhanced safety protocols and security clearances that extend procurement cycles.
- Ferry Operators:California CARB harbor craft mandates are compelling LNG conversions for Los Angeles-Long Beach tug and ferry fleets.
Shipping Companies dominate contract volume. Ferry Operators are expanding most quickly on regulatory mandate strength.
Technology:
Maturity gradients separate proven systems from emerging specifications still navigating certification pathways.
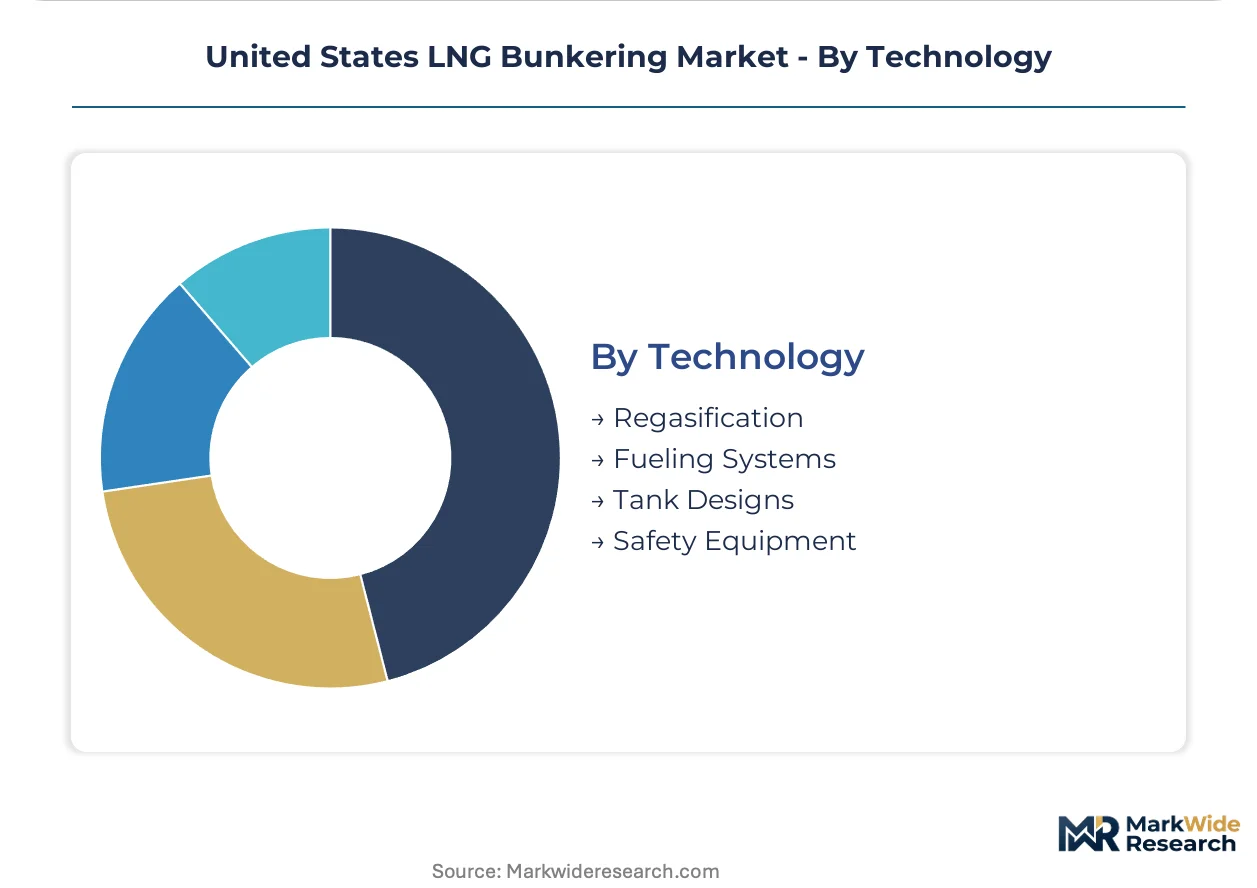
- Regasification:Ambient air vaporizers and submerged combustion units convert LNG back to gaseous state for dual-fuel engine injection, with high-pressure systems gaining preference for Tier 4 compliance.
- Fueling Systems:Automated custody transfer with mass flow meters and blockchain-anchored receipts is displacing 72-hour manual reconciliation cycles at 40% of Gulf Coast transactions.
- Tank Designs:Mark III membrane and Type C pressure vessel configurations compete on space efficiency versus structural simplicity tradeoffs.
- Safety Equipment:Gas detection arrays and emergency shutdown systems are mandatory under Coast Guard regulations with inspection intervals set at 12 months.
Fueling Systems command upgrade spending. Safety Equipment maintains steady replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive buyers cluster along secondary Atlantic harbors where truck-to-ship delivery dominates, while Gulf Coast operators absorb premium port-based costs through volume scale and Henry Hub feedstock proximity.
Texas-Louisiana Gulf Coast
Container shipping lines operating scheduled services demand simultaneous cargo and bunkering operations to minimize dwell time penalties exceeding $15,000 per hour. EPA Annex VI compliance deadlines under 33 CFR Part 127 accelerate vessel retrofit commitments. The Port of Houston and Port of Corpus Christi anchor liquefaction infrastructure that eliminates greenfield supply chain construction for operators.
Florida Atlantic Coast
Ferry operators and offshore supply vessel fleets seek LNG conversions driven by fuel cost predictability needs for route planning. The United States Coast Guard waterway suitability assessments average 18-24 months, delaying terminal revenue commencement. Jacksonville port authorities procure modular storage units to bypass federal approval timelines while Eagle LNG Partners anchors small-scale liquefaction assets.
California Pacific Coast
Harbor craft operators face mandated demand for LNG tugs and ferries under California Air Resources Board in-use vessel requirements. EPA coordination with CARB creates overlapping but non-identical product standards that shape operator compliance costs. The Los Angeles-Long Beach port complex concentrates retrofit activity for dual-fuel marine engines.
Georgia-South Carolina Atlantic Corridor
Mid-size container lines evaluate fixed-price LNG commitments spanning 3-5 year horizons pegged to Henry Hub futures. The Savannah Port Authority lacks dedicated LNG terminals but handles rising volumes that justify infrastructure investment. Secondary harbor demand relies on mobile cryogenic tanker delivery with 10,000-gallon payload limitations.
Pacific Northwest
Ferry operators and coastal shipping lines assess LNG-electric hybrid propulsion architectures for mid-life vessel retrofits. State-level environmental regulations align with federal Clean Air Act mandates through regional air quality management districts. Seattle and Tacoma port authorities evaluate barge delivery systems to extend LNG reach beyond fixed terminal footprints.
United States LNG Bunkering Market Competitive Landscape
Capability concentration sits with specialized marine fuel operators possessing cryogenic technician certification and Coast Guard-approved protocols; scale advantage sits with integrated energy majors leveraging existing liquefaction infrastructure and global trading desks. The vendor base organizes into three tiers: captive logistics networks, small-scale liquefaction specialists, and multinational oil companies. Consolidation pressure intensifies as charter-party fuel clauses shift toward long-term fixed-price commitments. Dominant competitive moves include strategic partnerships between terminal developers and container lines, plus geographic expansion into Atlantic Coast ports lacking dedicated infrastructure.
Within the integrated logistics tier, Crowley Maritime Corporation and Harvey Gulf International Marine exemplify operators combining vessel fleets with fuel supply capabilities. Eagle LNG Partners anchors the small-scale liquefaction specialist position through Jacksonville-based assets. These three entities represent contrasting strategic postures: Crowley leverages repeat contract capture across Florida and Caribbean routes, Harvey Gulf concentrates on offshore supply vessel conversion protocols, and Eagle LNG secures feedstock access without greenfield construction premiums.
| Leading Market Players |
|---|
| Crowley Maritime Corporation |
| Eagle LNG Partners |
| JAX LNG, LLC |
| Harvey Gulf International Marine |
| Chevron Corporation |
| Shell plc |
| TotalEnergies SE |
| Engie SA |
| World Fuel Services |
| Others |
Value Network & Pricing Analysis
The Texas-Louisiana liquefaction corridor concentrates over two-thirds of domestic nameplate capacity within a 300-mile band, granting port-based operators Henry Hub feedstock proximity that compresses delivered fuel costs and amplifies margin capture against Atlantic Coast competitors lacking comparable infrastructure density.
Pricing Analysis
Aftermarket service revenue from cryogenic maintenance and fuel-system recertification drives lifetime value for bunker suppliers, with three-tier pricing structure across premium, standard, and economy levels anchored to certification grade and volume commitment scale. Port-based terminals command premium positioning through fixed storage amortization across multiple customers, while truck-to-ship providers compete on geographic delivery cost to scattered secondary harbors. Pricing pressure stems from nickel-bearing alloy cost volatility in double-walled tank fabrication. Container shipping lines exhibit lowest price sensitivity due to dwell time penalty avoidance, whereas independent offshore supply operators negotiate aggressively on spot procurement.
Supply Chain Analysis
Hurricane exposure across the Texas-Louisiana Gulf Coast dominates supply chain risk assessment for domestic LNG bunkering. Feedstock draws from existing liquefaction export terminals, cryogenic storage vessels fabricated from 9% nickel steel, and specialized bunker vessels with Type C tank configurations. Single-source vulnerability concentrates in the 300-mile liquefaction corridor where storm disruption can sever supply continuity. Distribution feeds from port-based terminals through ship-to-ship transfer, with barge delivery and truck-to-ship methods extending reach to secondary harbors lacking dedicated infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States LNG bunkering market represents a high-growth disruption driven by EPA marine engine Tier 4 NOx compliance deadlines that compress vessel retrofit timelines before full sulfur emission cutoffs take effect.
For Market Incumbents: Harden terminal network density through captive storage additions in Jacksonville and Savannah to preempt Atlantic Coast competition. Deepen backward integration into small-scale liquefaction assets that eliminate greenfield construction premiums. Secure 33 CFR Part 127 certification pipelines to address cryogenic technician shortages constraining operational scaling.
For New Entrants and Emerging Players: Secondary Atlantic harbors lacking dedicated LNG terminals represent the most penetrable entry point for mobile truck-to-ship service deployment. California CARB harbor craft compliance mandates create mandated demand pockets for tug and ferry conversion specialists. Partner with regional port authorities on modular storage procurement to bypass 18-24 month Coast Guard waterway suitability delays.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated logistics operators combining vessel fleets with fuel supply capabilities over pure-play terminal developers. Long-term viability hinges on charter-party fuel clause convergence toward fixed-price commitments spanning multi-year horizons. Monitor EPA marine engine tier update announcements as the critical inflection signal for retrofit demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Small-Scale Liquefaction Buildout | Jacksonville and Savannah port authorities procure modular units to bypass Coast Guard approval timelines. |
| Ship-to-Ship Capacity Expansion | Cryogenic loading arm deployment along Texas-Louisiana container lanes captures dwell time penalty avoidance value. |
| Dual-Fuel Retrofit Certification | Harvey Gulf International Marine and competitors secure EPA Tier 4 pre-certification for offshore supply fleet renewal. |
| Long-Term Charter-Party Agreements | Container lines demand Henry Hub-indexed fixed-price commitments replacing spot-market procurement volatility. |
| Cryogenic Technician Pipeline Development | 33 CFR Part 127 training programs address operational scaling constraints from qualified supervisor shortages. |
Research Methodology
Initial hypotheses were tested against primary input from marine fuel procurement officers, Coast Guard regulatory compliance leads, port authority infrastructure planners, and cryogenic systems engineers, and refined through secondary validation against EPA regulatory filings, FERC liquefaction capacity reports, Coast Guard waterway suitability assessments, and customs trade data. Bottom-up vessel retrofit demand estimates were triangulated against top-down infrastructure capacity buildout projections.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across service modality, infrastructure type, end-user category, and technology maturity tier. CAGRs were derived from infrastructure deployment run rates and regulatory deadline compression effects. Forecast inputs incorporated EPA marine engine tier update timing, Henry Hub futures curve trajectories, and Coast Guard approval timeline distributions.
Practitioners should monitor hurricane frequency patterns, nickel alloy commodity cycles, and pending EPA regulatory announcements for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Canada Coal Market
Fuels
Pyrolysis Gas Market
Fuels
Oil Dispenser Market
Fuels
High-Temperature Industrial Burner Market
Fuels
Germany Bunker Fuel Market
Fuels
Fuel Conditioning System Market
Fuels
Global Wood Gas Generator Market
Fuels
Alcohol-To-Jet (ATJ) Fuel Market
Fuels
Coal Briquette Box Market
Fuels
Chafing Fuel Market
Fuels
Waste-Derived Pyrolysis Oil Market
Fuels
Hydrogen Cylinder Market
Fuels
Solid Fuel Tablet Market
Fuels
Middle-East and Africa Commercial Aircraft Aviation Fuel Market
Fuels
Gas Hydrates Market
Fuels
Australia Coal Market