
 SLD Market | 2026-2036
SLD Market Size, Share, and Industry Trends Forecast 2026-2036
SLD Market Outlook
Photonics engineering talent is bifurcating between semiconductor fabrication and systems integration tracks, constraining how quickly SLD suppliers can scale. Thorlabs leverages captive cleanroom capacity in New Jersey to sustain vertical control over epitaxial growth. Exalos anchors its competitive position through extended wavelength portfolios in the near-infrared band. DenseLight Semiconductors specializes in indium phosphide platforms for telecom test equipment, occupying a defensible niche against broader-line competitors.
Superluminescent diodes emit broadband, low-coherence light spanning 600 nm to 1700 nm depending on material composition, combining laser-like brightness with LED-like spectral width for interferometric imaging and sensing applications. Optical Components command established margin pools from replacement cycles in ophthalmology systems, while Light Engines represent the fastest-growing product type as AR headset makers demand compact, efficient illumination. LCoS technology leads in medical projection where pixel density requirements exceed LCD capability, though OLED microdisplays are displacing legacy architectures in premium wearable devices.
FDA 510(k) pathways govern SLD integration into diagnostic imaging systems in the United States, while ISO 13485 certification acts as a de facto market-access filter for component suppliers targeting OEMs. The EU MDR framework extends conformity obligations for devices incorporating SLD modules, pushing European manufacturers toward documented traceability across epitaxial wafer sourcing. Stakeholders must monitor how NMPA evolving standards in China reshape qualification protocols for export-bound medical instruments.
Market Dynamics
Photonics engineering capacity constraints are compressing SLD supplier scaling timelines, as cleanroom-qualified talent migrates toward semiconductor fabrication roles and away from discrete component manufacturing. This structural tension between upstream epitaxial growth capacity and downstream systems integration demand defines current competitive positioning.
Growth Catalysts
- FDA 510(k) pathway clarity:Streamlined premarket notification procedures for optical coherence tomography devices are accelerating OEM qualification cycles for SLD module suppliers targeting United States diagnostic imaging markets.
- Indium phosphide platform maturation:Advanced epitaxial growth techniques are extending wavelength coverage into the near-infrared band, opening spectroscopic sensing applications in precision agriculture and environmental monitoring.
- Jena-Munich optics corridor concentration:German precision manufacturing clusters provide captive access to specialized optical coating and packaging capabilities, reducing lead times for European medical device integrators.
Market Restraints
- III-V compound wafer cost volatility:Indium and gallium price swings transmit directly into epitaxial substrate costs, compressing margin buffers for mid-tier SLD suppliers without captive mining or refining arrangements.
- Single-source dependency risk:High-performance anti-reflection coatings for broadband emission faces concentration among Japanese and German specialty chemical suppliers, creating vulnerability to regional supply disruptions.
- Thermal management limitations:Power dissipation constraints in compact form factors restrict output power scaling for wearable AR illumination applications, capping addressable market scope.
Strategic Opportunities
- Chinese NMPA pathway development:Evolving medical device registration standards are creating first-mover advantage for SLD suppliers establishing local testing partnerships and technical documentation capabilities.
- LCoS-OLED convergence in surgical visualization:Hybrid illumination architectures combining superluminescent broadband sources with microdisplay engines are penetrating premium operating theater installations.
- Direct-to-device-maker distribution:Bypassing traditional photonics distributors through technical sales teams embedded in Shenzhen and Boston hardware ecosystems is compressing customer acquisition costs.
Industry Challenges
- ISO 13485 certification timeline compression:Medical OEMs are demanding 12-month qualification windows that strain quality management system implementation for component suppliers without prior healthcare experience.
- Multi-physics simulation talent scarcity:Opto-thermal-mechanical modeling expertise required for AR headset light engine miniaturization commands premium compensation and limited graduate program output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SLD Market |
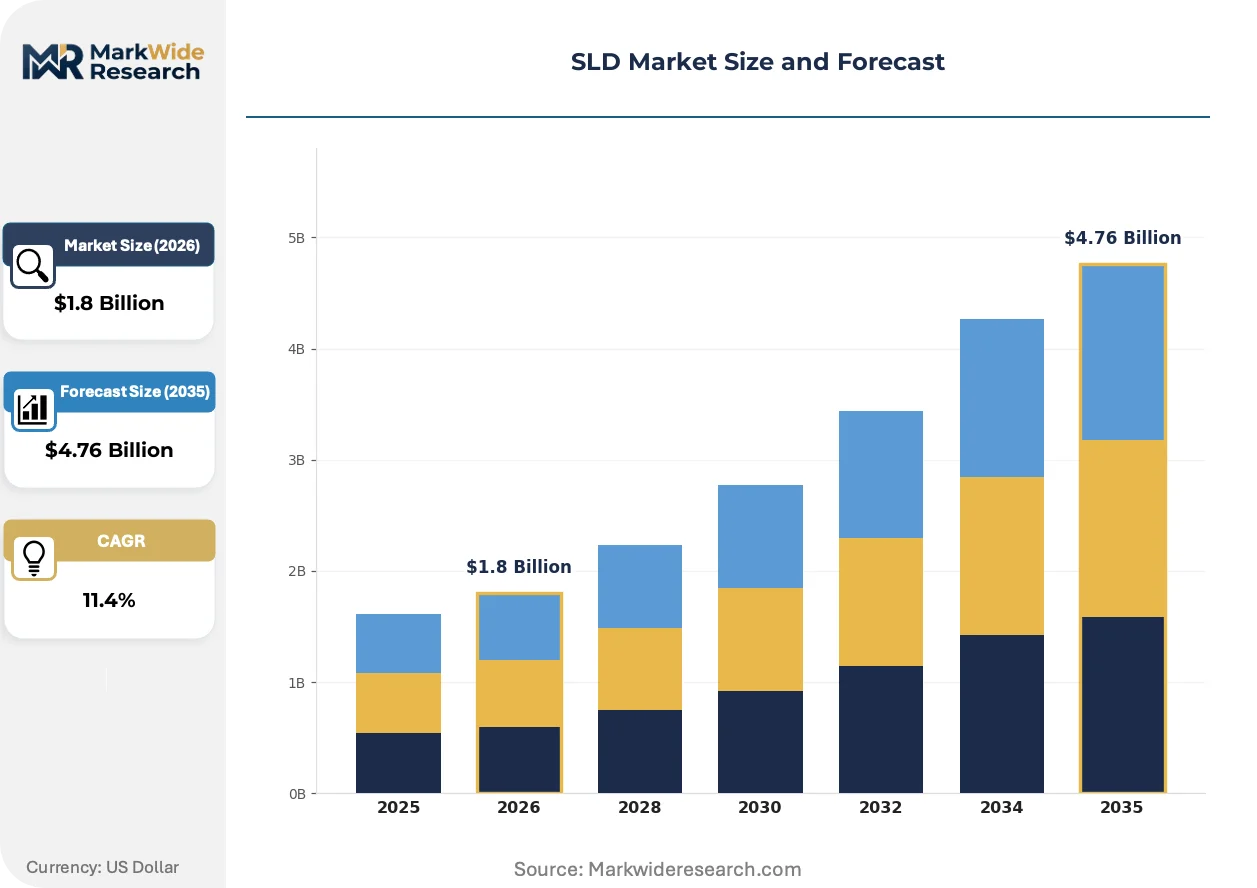
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microdisplays, Display Modules, Light Engines, Optical Components Technology: LCD, OLED, LCoS, DLP End User: Consumer Electronics, Automotive, Aerospace, Medical Devices Application: Augmented Reality, Virtual Reality, Projection Systems, Wearable Devices |
| Companies Covered | Thorlabs, Exalos, Innolume, Frankfurt Laser Company, QPhotonics, Anritsu, SuperLum, InPhenix, DenseLight Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SLD Market Strategic Shifts
Active reshaping of the SLD competitive landscape centers on wavelength portfolio expansion, regulatory documentation automation, and procurement model disintermediation between component suppliers and systems integrators.
Extended near-infrared emission architectures are bifurcating competitive positioning between broadband medical imaging specialists and narrow-line telecom test equipment suppliers. Automotive LiDAR developers are adopting 1060 nm and 1550 nm SLD sources for short-range backup sensing, compressing development cycles from qualification to production ramp. This wavelength diversification is forcing epitaxial foundries to retool MOCVD reactors for multi-material growth sequences.
EU MDR traceability mandates are extending conformity obligations through three tiers of component sourcing, pushing SLD manufacturers toward blockchain-enabled documentation for epitaxial wafer provenance. German notified bodies are interpreting Article 10 supplier requirements to encompass active optical components, not just finished devices. Medical OEMs are responding by consolidating supplier panels to reduce audit burden, favoring vertically integrated SLD houses with in-house crystal growth.
AR headset makers are unbundling light engine procurement from display module sourcing, creating direct commercial relationships with SLD suppliers previously isolated by tiered supply chains. Meta and Apple hardware divisions are establishing technical qualification teams in Singapore and Austin to evaluate broadband illumination performance independent of microdisplay vendor recommendations. This channel disintermediation is most pronounced in North American wearable development programs, where speed-to-prototype outweighs established distributor relationships.
SLD Market Segmentation
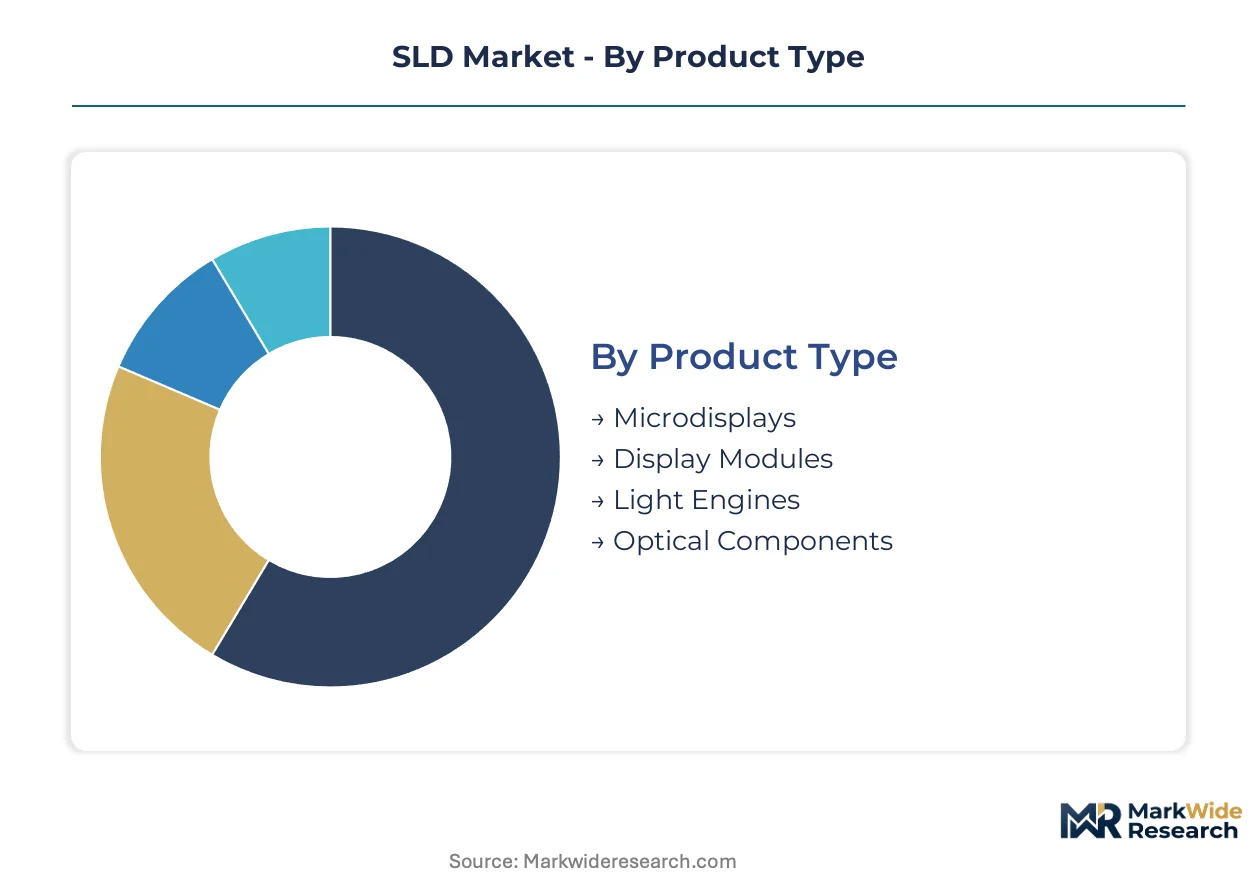
SLD market segmentation reveals how component suppliers align wavelength portfolios with divergent performance requirements across medical imaging, AR/VR headsets, and automotive sensing. Each dimension carries distinct margin structures and qualification barriers that reshape competitive positioning.
Product Type:
Margin pools concentrate in integrated subsystems where optical, thermal, and electronic functions merge into single deliverables.
- Light Engines:Compact illumination modules integrating SLD sources with beam-shaping optics and thermal management. AR headset makers in California and Washington demand these for waveguide-coupled architectures where space constraints dominate. Supply bottlenecks in multi-layer optical coatings extend lead times.
- Optical Components:Discrete SLD chips, collimators, and fiber-coupled packages serving replacement cycles in ophthalmology OCT systems. German and Japanese medical device OEMs drive volume through scheduled maintenance protocols and ISO 13485-mandated traceability requirements.
- Microdisplays:Backplane-integrated illumination for near-eye projection requiring pixel-precise brightness uniformity.
- Display Modules:Complete visual engines combining SLD sources with microdisplay panels and driver electronics.
The dominant share belongs to Optical Components, while Light Engines is closing the gap fastest.
Technology:
Cost tier separation follows the complexity of semiconductor backplane fabrication and foundry access.
- OLED:Self-emissive organic stacks displacing external illumination in premium wearable devices. Apple and Meta hardware programs in Austin and Cupertino are accelerating qualification timelines for micro-OLED architectures with integrated SLD pumping.
- LCoS:Reflective liquid crystal on silicon leveraging SLD broadband sources for surgical visualization and high-lumen projection. Pixel density requirements exceeding LCD capability sustain adoption in German and Swiss operating theater installations.
- LCD:Transmissive liquid crystal panels cost-optimized for volume projection applications.
- DLP:Digital micromirror devices using time-sequential color from SLD or alternative sources.
OLED commands the premium tier, yet LCoS defends share in medical applications where resolution specifications are non-negotiable.
End User:
Customer type determines whether procurement flows through distributor networks or direct technical sales engagement.
- Medical Devices:FDA 510(k) and EU MDR compliance requirements govern SLD integration into diagnostic imaging and surgical visualization systems. German notified bodies interpret supplier obligations to encompass active optical components, consolidating purchasing toward vertically integrated houses with in-house crystal growth.
- Consumer Electronics:AR/VR headset manufacturers unbundling light engine procurement from display module sourcing. Direct commercial relationships with SLD suppliers are compressing traditional tiered supply chains in North American and Chinese hardware ecosystems.
- Automotive:LiDAR developers adopting 1060 nm and 1550 nm SLD sources for short-range backup sensing.
- Aerospace:Ruggedized illumination for head-up displays and helmet-mounted cueing systems.
Medical Devices retains the deepest supplier relationships, though Consumer Electronics is expanding the addressable supplier base fastest.
Application:
Volume concentration tracks the intersection of unit economics and performance thresholds that SLD sources uniquely satisfy.
- Augmented Reality:Waveguide-coupled broadband illumination demanding compact form factors and thermal efficiency. Meta and Apple technical qualification teams in Singapore and Austin evaluate SLD performance independent of microdisplay vendor recommendations, disintermediating established distribution channels.
- Projection Systems:High-lumen medical and cinema applications where SLD coherence properties reduce speckle artifacts. German precision optics clusters in Jena and Munich anchor component sourcing for European OEMs serving surgical visualization markets.
- Virtual Reality:Near-eye displays with less stringent waveguide coupling requirements than AR.
- Wearable Devices:Fitness and industrial headsets balancing battery life with display brightness.
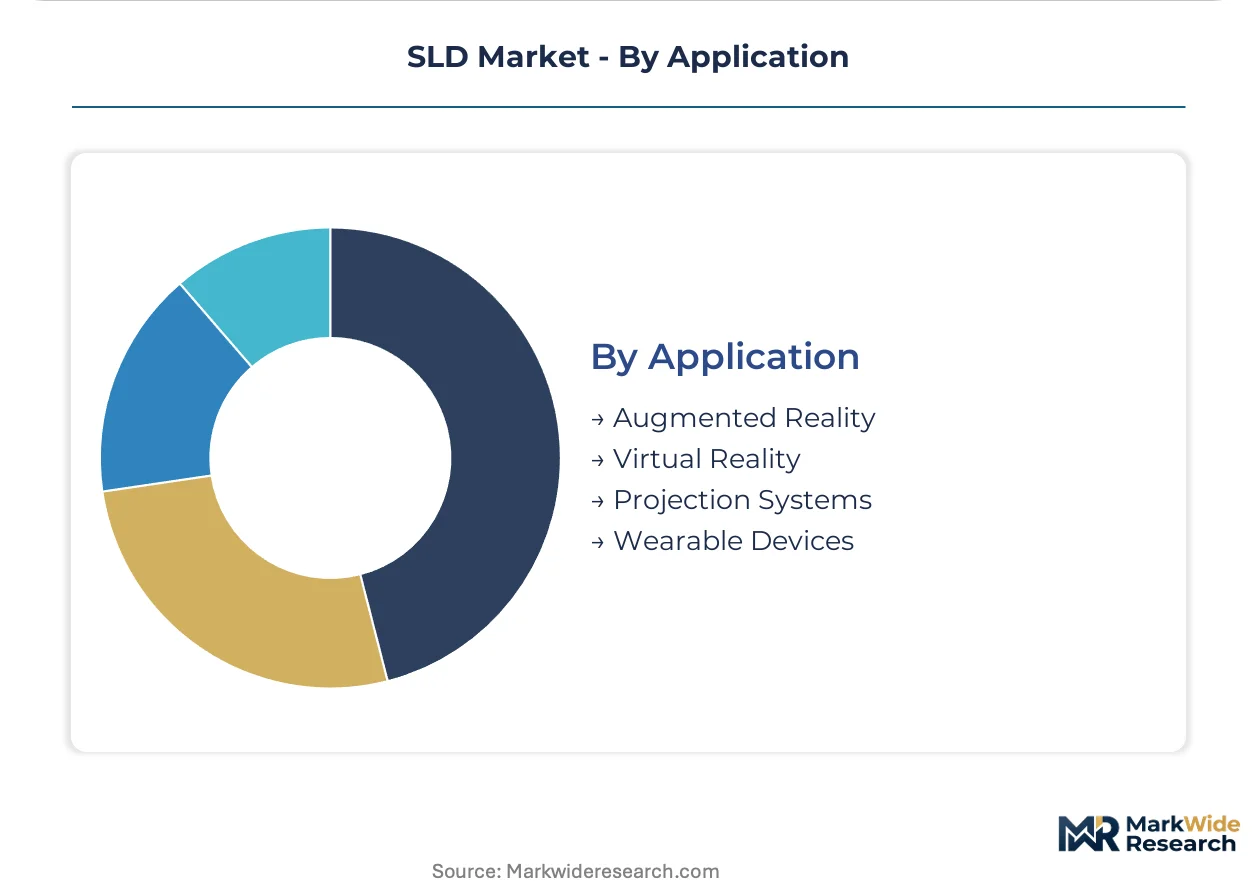
Projection Systems holds established revenue, while Augmented Reality is climbing the fastest as headset makers scale engineering headcount.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) pathway clarity in the United States anchors regulatory momentum for SLD integration into diagnostic imaging systems, while precision optics clusters in Germany and emerging qualification protocols in China reshape supplier geographic priorities.
United States
Medical device OEMs in Massachusetts and California drive SLD module demand for optical coherence tomography systems. FDA 510(k) premarket notification procedures compress qualification cycles for component suppliers. Greater Boston hardware ecosystems host technical sales teams evaluating broadband illumination performance independent of traditional distribution channels.
Germany
Precision manufacturing clusters in Jena and Munich anchor component sourcing for European medical device integrators. EU MDR traceability mandates extend conformity obligations through three tiers of component sourcing. German notified bodies interpret Article 10 supplier requirements to encompass active optical components, consolidating purchasing toward vertically integrated houses.
China
AR headset makers in Shenzhen and Beijing unbundle light engine procurement from display module sourcing. NMPA evolving medical device registration standards create first-mover advantage for suppliers establishing local testing partnerships. Yangtze River Delta hardware ecosystems compress customer acquisition costs through direct technical sales engagement.
Japan
High-performance anti-reflection coating suppliers concentrate among Japanese specialty chemical manufacturers serving broadband emission applications. METI industrial policy supports photonics engineering capacity retention amid cleanroom-qualified talent migration. Tokyo-Osaka manufacturing corridors face regional supply disruption vulnerability from single-source dependencies.
Singapore
Meta and Apple hardware divisions establish technical qualification teams to evaluate broadband illumination performance for waveguide-coupled AR architectures. The city-state's advanced packaging capabilities attract SLD suppliers seeking proximity to Southeast Asian electronics manufacturing. Local testing partnerships accelerate prototype-to-production timelines for near-infrared emission modules.
SLD Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the SLD market structure. Vertically integrated houses with captive epitaxial growth capacity command premium positioning in medical imaging segments, while specialized foundry-dependent suppliers compete on wavelength portfolio breadth. Two strategic archetypes dominate: broadband medical imaging specialists and narrow-line telecom test equipment suppliers. Competitive moves concentrate on M&A for cleanroom capacity acquisition and strategic partnerships for AR headset light engine co-development.
Among European-based suppliers, Thorlabs exemplifies the vertically integrated archetype through captive cleanroom operations, while Exalos occupies a position emphasizing extended wavelength portfolios. DenseLight Semiconductors represents the specialized foundry-dependent model, anchoring competitive positioning through indium phosphide platform concentration.
| Leading Market Players |
|---|
| Thorlabs |
| Exalos |
| Innolume |
| Frankfurt Laser Company |
| QPhotonics |
| Anritsu |
| SuperLum |
| InPhenix |
| DenseLight Semiconductors |
| Others |
Value Chain & Pricing Dynamics
Cleanroom capacity utilization above eighty percent at German and Japanese epitaxial foundries concentrates pricing power among vertically integrated SLD houses, compressing margin buffers for foundry-dependent suppliers while establishing price floors tethered to III-V wafer input costs. This scale asymmetry rewards Thorlabs and Exalos with captive crystal growth, forcing mid-tier competitors toward wavelength specialization or exit.
Pricing Analysis
German precision optics clusters command fifteen-to-twenty percent premiums over Asian-sourced SLD modules for ISO 13485-certified medical imaging applications. Pricing stratifies across FDA 510(k) cleared premium tiers, volume-scaled standard tiers, and uncertified economy tiers for industrial sensing. Cost compression in the economy tier intensifies because Chinese AR headset makers are unbundling procurement from display vendors. Medical device OEMs in Massachusetts and California exhibit least price sensitivity due to replacement cycle lock-in, while Shenzhen hardware startups drive hardest bargaining.
Supply Chain Analysis
Port congestion at Yokohama and Hamburg elevates inbound logistics costs for indium phosphide wafers sourced from Japanese and German specialty chemical suppliers. Epitaxial growth capacity concentrates in Germany, Japan, and the United States, drawing from indium, gallium arsenide, and anti-reflection coating inputs. Single-source vulnerability runs through Japanese high-performance coating manufacturers. Distribution runs through photonics distributors in Boston and Shenzhen, though direct technical sales teams are displacing traditional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a defensive-moat story anchored in ISO 13485 regulatory entrenchment, where certification timelines and notified body relationships create switching costs that protect incumbent positioning.
For Market Incumbents: Secure backward integration into epitaxial wafer sourcing to defend against III-V compound price volatility and single-source coating dependencies. Expand cleanroom capacity in New Jersey or Jena before photonics engineering talent migrates entirely to semiconductor fabrication. Consolidate supplier panels for European medical OEMs facing EU MDR audit burden.
For New Entrants and Emerging Players: Anchor in Chinese NMPA pathway development for medical device registration, where local testing partnerships create first-mover advantage against established Western suppliers. Target AR headset light engine procurement in Shenzhen and Austin, where speed-to-prototype outweighs distributor relationships. Pursue direct-to-device-maker distribution to compress customer acquisition costs.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated SLD houses with captive crystal growth and established FDA 510(k) clearance histories. Long-term viability favors suppliers with in-house MOCVD reactors and documented EU MDR traceability systems. Watch for NMPA registration acceleration as the inflection signal for Chinese market access premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxial Growth | Captive III-V wafer supply insulates Thorlabs from indium price volatility and German coating bottlenecks. |
| FDA 510(k) Pathway Acceleration | Streamlined premarket notification compresses OEM qualification cycles for Massachusetts diagnostic imaging suppliers. |
| NMPA Local Testing Partnership | First-mover registration advantage in Shenzhen medical device ecosystems ahead of evolving Chinese standards. |
| Direct Technical Sales Deployment | Bypassing photonics distributors in Austin and Singapore compresses customer acquisition for AR light engines. |
| EU MDR Blockchain Traceability | Documented epitaxial wafer provenance satisfies German notified body interpretations of Article 10 supplier obligations. |
Study Parameters
Operator-level perspectives from photonics engineering directors, medical device procurement managers, AR hardware program leads, epitaxial foundry operations heads, and German notified body auditors anchored the qualitative base. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, NMPA registration bulletins, SEC filings of listed photonics companies, and customs trade data for III-V compound wafer flows. Bottom-up segment sizing triangulated against top-down market envelope checks.
Sensitivity analysis tested volume and value outputs across the projection horizon against indium price volatility scenarios and cleanroom capacity expansion timelines. Segmentation dimensions modeled include product type, technology platform, end-user industry, application, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating replacement cycle dynamics in ophthalmology systems and engineering headcount scaling at Meta and Apple hardware divisions.
Material uncertainties — NMPA standard evolution, EU MDR enforcement variance across notified bodies, and photonics engineering talent migration rates — sit outside the modeled envelope. Forecasts reflect documented assumptions about qualification timeline compression and unbundling procurement trends. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Modular Plating System Market
Semiconductor Devices
Global Gan Semiconductor Device Market
Semiconductor Devices
Underfill Market
Semiconductor Devices
Digital Tunable Capacitors Market
Semiconductor Devices
Europe Touch Screen Controllers Market
Semiconductor Devices
Coated Silicon Wafer Market
Semiconductor Devices
Dynamic Electrograph Market
Semiconductor Devices
Bipolar Transistors Market
Semiconductor Devices
Europe Silicon Carbide Wafers Market
Semiconductor Devices
Europe Microcontroller Market
Semiconductor Devices
Europe Power Transistor Market
Semiconductor Devices
Voltage Controlled Oscillators Market
Semiconductor Devices
Global Probe Card Market
Semiconductor Devices
3D TSV Device Market
Semiconductor Devices
DNA Chip Market
Semiconductor Devices
Temperature-Controlled Semiconductor Market