
 North America Functional Water Market | 2026-2036
North America Functional Water Market Size, Share, and Industry Trends Forecast 2026-2036
North America Functional Water Market Analytics
Premium electrolyte specifications is collapsing the gap between sports nutrition and everyday hydration, forcing mainstream brands to reformulate at higher mineral concentrations. The Coca-Cola Company leverages its Powerade infrastructure to sustain shelf presence in convenience chains across the southern United States. PepsiCo anchors Gatorade's functional water extensions through direct-store-delivery networks that dominate gas station and pharmacy channels. Nestle SA competes in the premium mineral segment with regional sourcing claims that differentiate its North American portfolio from global lines.
Functional water comprises bottled water enhanced with electrolytes, vitamins, minerals, or herbal extracts to deliver targeted physiological benefits beyond basic hydration, typically formulated with sodium, potassium, magnesium, or B-vitamin complexes at concentrations between 50 and 300 milligrams per serving. Electrolyte variants lead volume due to established sports consumption rituals, while vitamin-infused lines capture the fastest expansion as wellness-oriented buyers shift from sugary juices. Distribution through supermarkets still occupies the largest revenue pool, though online retail is accelerating as subscription models lock in recurring purchases from health-conscious consumers.
The FDA enforces bottled water quality standards under 21 CFR 165.110 while Health Canada regulates functional claims through the Food and Drugs Act, creating a dual compliance burden for cross-border marketers. These frameworks shape demand by mandating substantiation for electrolyte replenishment and vitamin benefit claims, effectively raising formulation costs for smaller entrants. Stakeholders must monitor how proposed updates to FDA nutrient content claim rules will redefine permissible mineral thresholds before committing to new production lines.
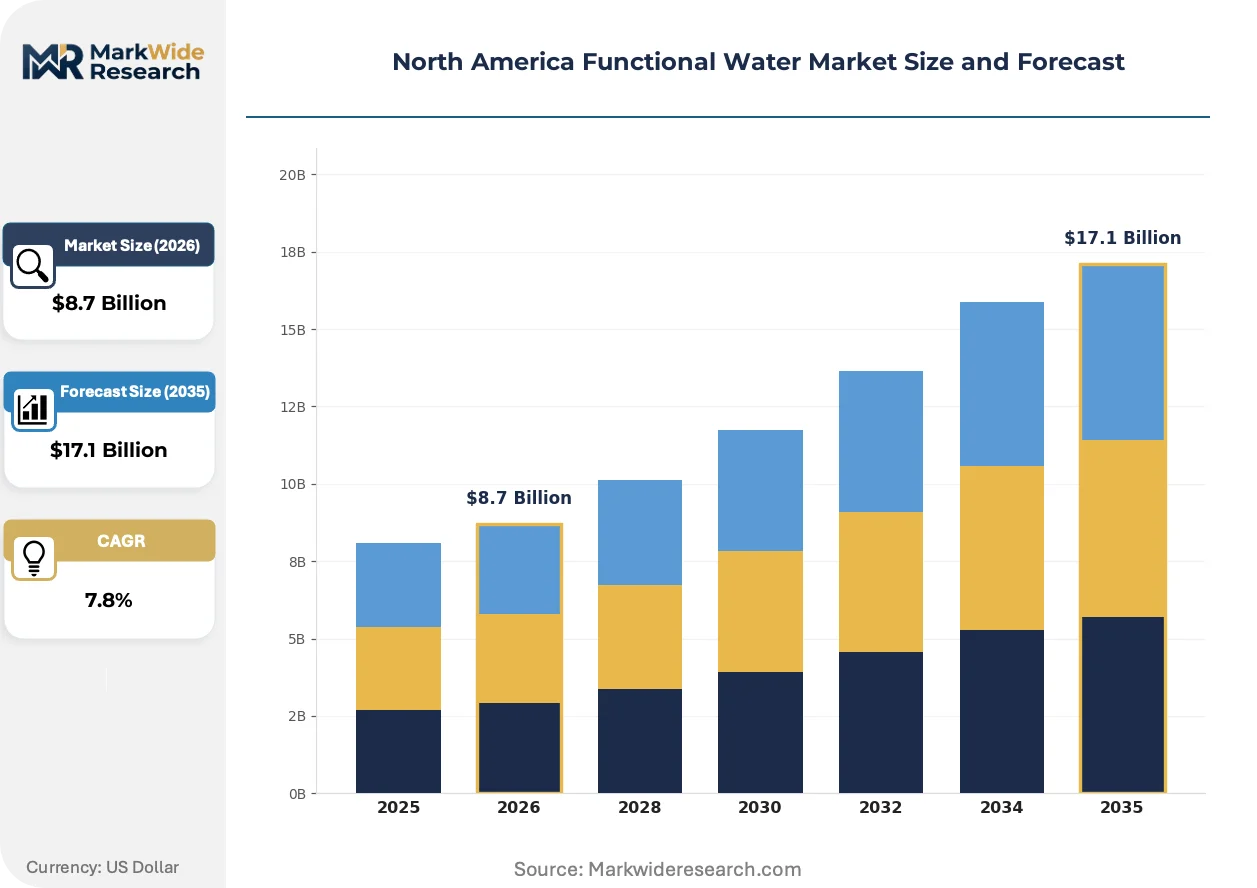
Market Dynamics
The functional water sector is experiencing a structural compression as electrolyte formulations migrate from athletic recovery into daily hydration rituals, forcing incumbent beverage manufacturers to recalibrate mineral specifications across their entire North American portfolios.
Growth Catalysts
- FDA Nutrient Content Claim Evolution:Proposed updates to 21 CFR 101 are expanding permissible electrolyte thresholds, enabling brands to market higher-concentration formulations as functional rather than supplemental.
- Fitness Culture Maturation:Post-workout hydration rituals in California, Texas, and Florida have normalized electrolyte consumption among non-athletes, creating habitual purchase frequency in convenience channels.
- Health Canada Labeling Harmonization:Streamlined bilingual nutrient disclosure requirements are reducing cross-border formulation complexity for US exporters targeting Ontario and British Columbia.
Market Restraints
- Mineral Input Volatility:Magnesium and potassium carbonate sourcing from Chilean and Israeli suppliers exposes margins to fertilizer market fluctuations and shipping route disruptions.
- Concentrated Retail Gatekeeping:Shelf space allocation at Kroger, Costco, and Loblaws favors established suppliers with direct-store-delivery infrastructure, constraining regional challenger brands.
- Tap Water Quality Perception:Municipal filtration improvements in cities like Chicago and Montreal are reducing the perceived functional gap between enhanced and standard hydration options.
Strategic Opportunities
- Subscription Direct-to-Consumer:Recurring delivery models bypass traditional retail slotting fees while capturing lifetime value from wellness-oriented households in Seattle and Vancouver.
- Pediatric Formulation White Space:Lower-sodium electrolyte profiles aligned with American Academy of Pediatrics guidance remain underserved in school lunch and youth sports channels.
- Biodegradable Bottle Mandates:California SB 54 implementation timelines are creating first-mover advantage for brands with validated compostable packaging supply chains.
Industry Challenges
- Formulation Talent Scarcity:Beverage chemists with dual expertise in mineral bioavailability and flavor masking command premium compensation, constraining R&D expansion at mid-tier producers.
- Co-Packer Capacity Bottlenecks:Aseptic filling lines capable of handling sensitive vitamin complexes operate at near-full utilization across the Great Lakes manufacturing corridor.
- Cross-Border Claim Substantiation:Divergent evidentiary standards between FDA and Health Canada require parallel clinical documentation, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Functional Water Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral, Electrolyte, Herbal, Vitamin-Infused End User: Athletes, Health-Conscious Consumers, Young Adults, Seniors Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Convenience Stores Packaging Type: Bottles, Pouches, Cans, Tetra Packs |
| Companies Covered | The Coca-Cola Company, PepsiCo, Dr Pepper Snapple Group Inc, Trimino Brands Company LLC, Disruptive Beverages Inc, Function Drinks, NYSW Beverage Brands Inc, Unique Foods (Canada) Inc, Nestle SA, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Functional Water Market Evolving Landscape
Reformulation priorities are pivoting toward clean-label mineral sourcing and precision-dose delivery systems as consumers scrutinize ingredient provenance with the same intensity previously reserved for organic food categories.
Electrolyte micro-dosing technology is displacing traditional single-serve bottles in workplace and travel contexts. Concentrated liquid mineral drops from Utah-sourced salt deposits allow consumers to customize sodium and magnesium levels in any water source. Corporate wellness programs in Austin and Denver are adopting these systems to reduce plastic waste while maintaining hydration tracking integration with wearable devices.
Health Canada's proposed amendments to the Food and Drugs Act are tightening substantiation requirements for vitamin benefit claims. Manufacturers must now provide clinical evidence for B-complex cognitive or immune assertions before bilingual packaging approval. This regulatory friction is compressing marketing timelines for new entrants while favoring established brands with existing Health Canada master files.
Subscription bundling is consolidating household beverage procurement around functional water assortments. Consumers in Toronto and Los Angeles are replacing sporadic convenience store purchases with curated monthly deliveries combining electrolyte, vitamin, and adaptogenic variants. This channel shift is reducing impulse-driven brand switching while increasing price transparency through direct comparison tools.
North America Functional Water Market Segmentation
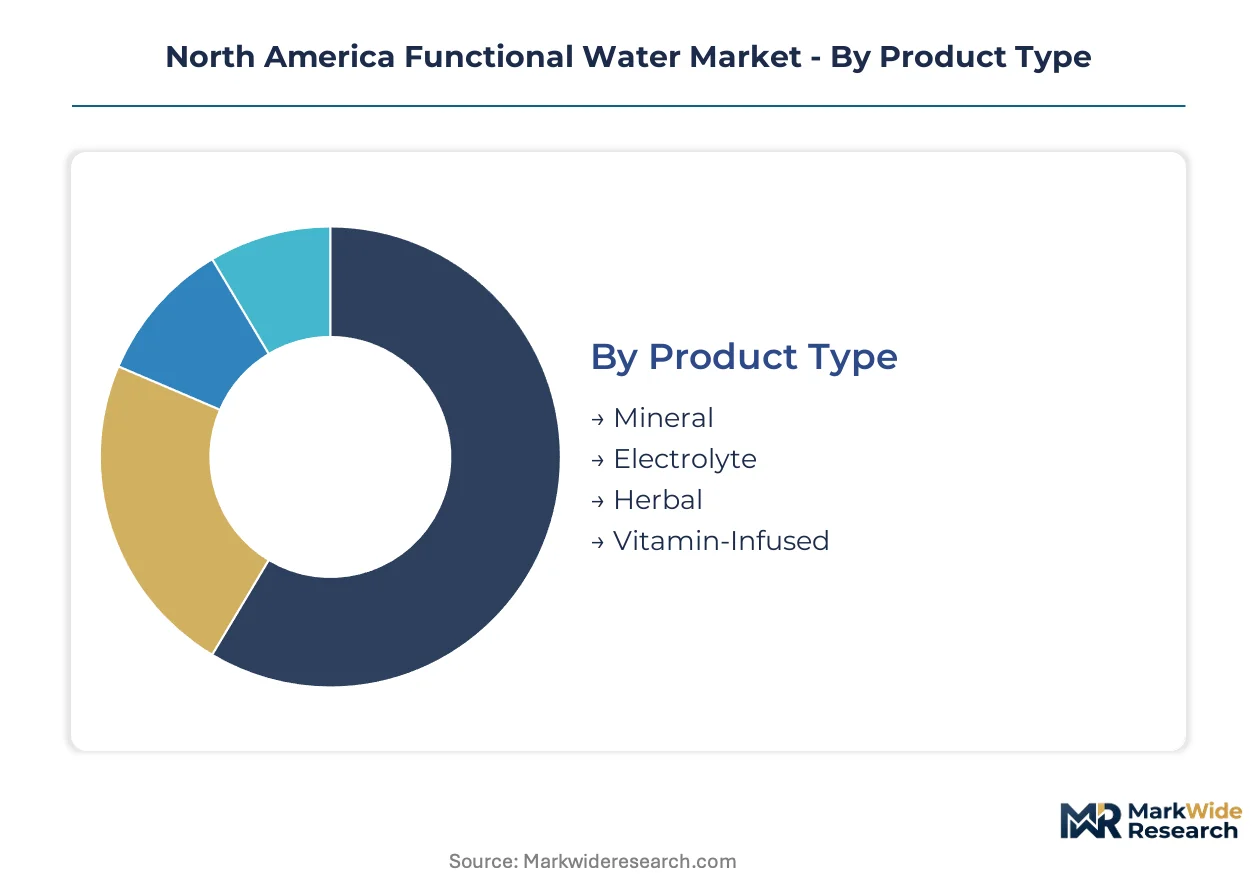
Functional water segmentation in North America reflects divergent channel economics and consumption rituals. Product formulation, packaging format, and retail placement each command distinct margin profiles and customer acquisition costs.
Product Type:
Channel mix varies sharply by formulation chemistry, with electrolyte variants dominating convenience and gas station networks while vitamin-infused lines concentrate in natural grocery and subscription channels.
- Electrolyte:Sodium-potassium-magnesium blends formulated at 50-300 milligrams per serving anchor sports consumption rituals. Demand concentrates in Texas, Florida, and California where fitness culture normalizes post-workout hydration as daily habit. Convenience chains capture the highest purchase frequency through single-serve placement at checkout.
- Vitamin-Infused:B-complex and antioxidant formulations target wellness-oriented households shifting from sugary juices. Expansion concentrates fastest in Seattle, Vancouver, and Toronto where subscription bundling reduces impulse brand switching. Health Canada's tightened substantiation requirements for cognitive benefit claims extend approval timelines for new entrants.
- Mineral:Regional sourcing claims from Appalachian or Rocky Mountain aquifers differentiate premium positioning in natural grocery channels.
- Herbal:Adaptogenic and botanical extracts occupy niche placement in health food stores with limited mainstream distribution penetration.
Electrolyte formulations dominate installed base. Vitamin-infused lines are where expansion concentrates.
End User:
Customer lifetime value stratifies sharply across demographic segments, with athletes generating the highest per-capita consumption and seniors presenting the stickiest subscription retention.
- Health-Conscious Consumers:Wellness-oriented households in Austin, Denver, and Portland drive curated subscription assortments combining multiple formulation types. These buyers exhibit the lowest price elasticity and highest loyalty to clean-label mineral sourcing claims.
- Athletes:Organized sports participants and fitness enthusiasts sustain habitual electrolyte consumption through convenience channel proximity to gyms and training facilities. California and Texas account for the densest concentration of high-frequency purchasers.
- Young Adults:Social media-influenced trial behavior concentrates in urban coastal markets with limited brand loyalty and high sensitivity to packaging aesthetics.
- Seniors:Medication-interaction awareness and lower-sodium requirements create demand for specialized formulations with reduced mineral concentrations.
Health-conscious consumers anchor premium pricing tiers. Athletes generate the highest volume throughput.
Distribution Channel:
Margin compression intensifies as slotting fees and direct-store-delivery infrastructure requirements favor incumbent beverage conglomerates over regional challengers.
- Supermarkets:Kroger, Costco, and Loblaws allocate shelf space through centralized category management favoring suppliers with proven velocity data. These channels capture the largest revenue pool but impose the steepest trade spend requirements.
- Online Retail:Subscription models lock in recurring purchases from wellness-oriented households while bypassing traditional slotting fees. Seattle, Los Angeles, and Toronto show the highest subscription penetration.
- Convenience Stores:Gas station and pharmacy channels dominate impulse-driven electrolyte purchases through single-serve placement.
- Health Food Stores:Natural grocery chains like Whole Foods and Sprouts prioritize clean-label and regional sourcing claims with limited SKU breadth.
Supermarkets dominate installed base. Online retail is expanding most quickly.
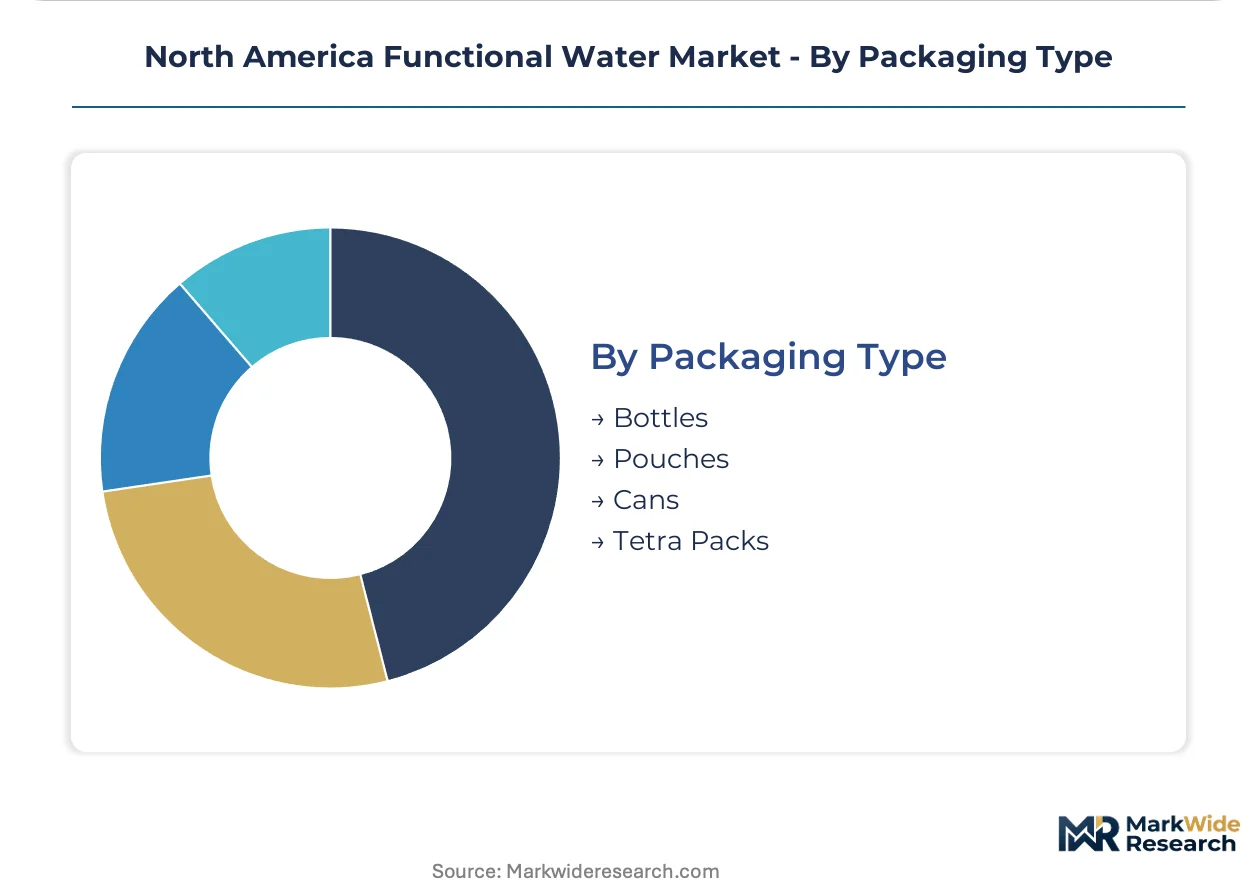
Packaging Type:
Sustainability mandates and logistics economics reshape format preferences, with California SB 54 implementation timelines accelerating compostable packaging investment.
- Bottles:PET and rPET formats retain volume leadership through established filling infrastructure and consumer familiarity. The Great Lakes manufacturing corridor hosts the densest concentration of aseptic bottling capacity.
- Cans:Aluminum formats gain share in fitness and outdoor consumption contexts where durability and temperature retention matter. Ball Corporation and Crown Holdings supply the majority of North American beverage can capacity.
- Pouches:Flexible formats reduce shipping cube and plastic weight but face limited adoption due to consumer perception of lower premium positioning.
- Tetra Packs:Aseptic carton formats occupy minimal share in functional water but see experimental placement in value-positioned vitamin lines.
Bottles dominate installed base. Cans are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian functional water exports flow primarily to the United States through cross-border retail networks, with Ontario and British Columbia serving as the primary production and distribution hubs for bilingual-labeled products entering American supermarkets.
United States
Fitness culture in California, Texas, and Florida drives electrolyte consumption beyond athletic contexts into daily hydration rituals. The FDA's evolving 21 CFR 165.110 standards mandate stricter mineral concentration disclosures on product labels. Austin and Denver clusters lead corporate wellness adoption of micro-dosing mineral systems that integrate with wearable hydration tracking devices.
Canada
Health-conscious households in Toronto and Vancouver sustain the fastest subscription bundling growth for vitamin-infused variants across North America. Health Canada's Food and Drugs Act amendments tighten substantiation requirements for cognitive benefit claims on bilingual packaging. The Ontario-Quebec corridor concentrates clean-label mineral sourcing infrastructure serving both domestic and export markets.
Mexico
Urban middle-class expansion in Mexico City and Guadalajara creates demand for premium hydration products positioned between basic bottled water and imported sports drinks. The country's national food safety regulator enforces NOM-141 labeling standards that align partially with FDA frameworks to facilitate cross-border manufacturing. Northern border states host co-packing facilities serving American brands seeking tariff-advantaged production.
North America Functional Water Market Competitive Landscape
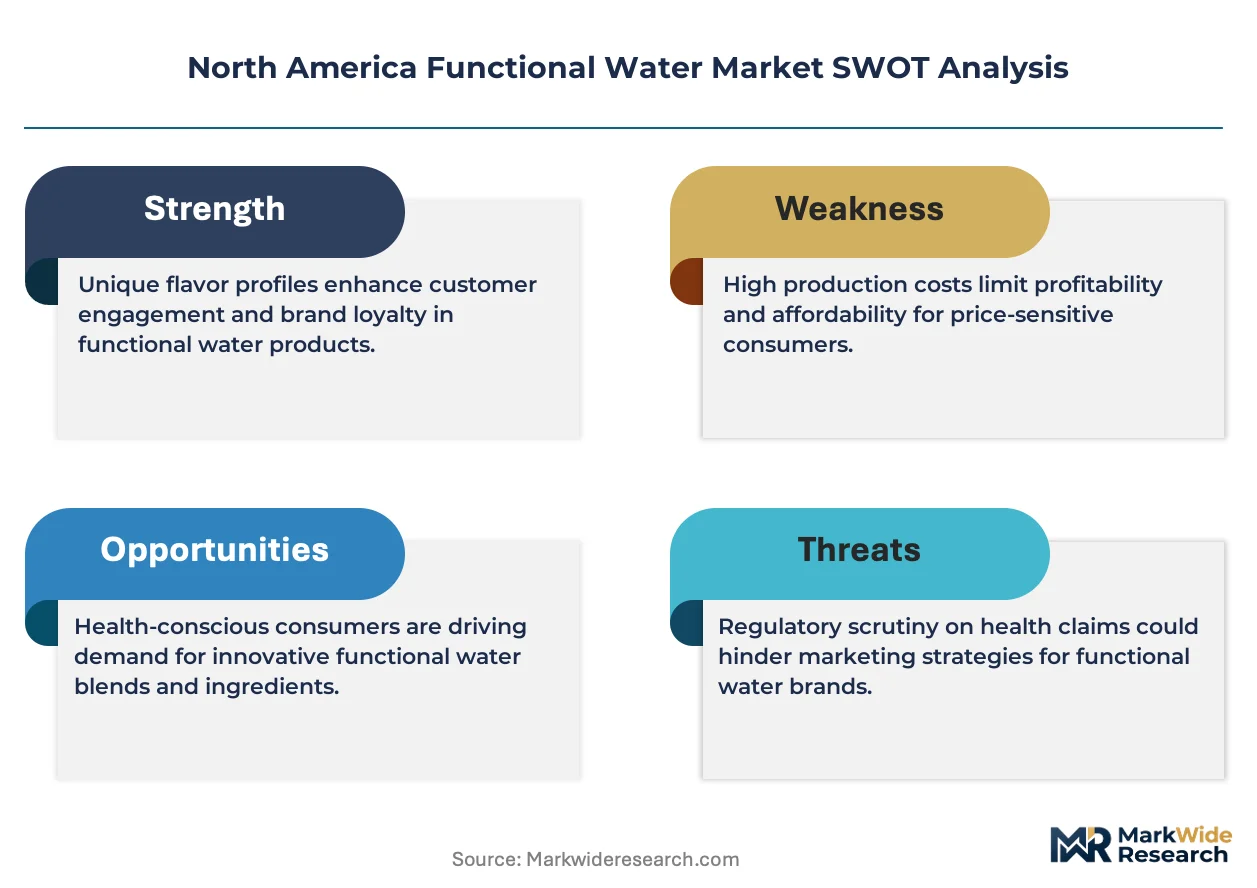
Listed beverage conglomerates compete with private functional water specialists across shelf space allocation and direct-store-delivery infrastructure. The market structure tilts toward consolidation at the mass retail tier while fragmenting across subscription and natural grocery channels. Three archetypes dominate: diversified beverage majors leveraging existing distribution networks, pure-play functional water startups targeting wellness demographics, and regional mineral water brands emphasizing provenance claims. Competitive moves center on portfolio diversification into adjacent wellness categories and strategic partnerships with fitness and corporate wellness platforms.
Within the diversified beverage major tier, The Coca-Cola Company and PepsiCo exemplify scale-driven market presence through established convenience and gas station channel dominance. Among private specialists, Trimino Brands Company LLC occupies a position targeting protein-enhanced functional hydration segments. Nestle SA anchors the premium mineral water archetype with regional sourcing narratives that differentiate its North American portfolio from global product lines.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo |
| Dr Pepper Snapple Group Inc |
| Trimino Brands Company LLC |
| Disruptive Beverages Inc |
| Function Drinks |
| NYSW Beverage Brands Inc |
| Unique Foods (Canada) Inc |
| Nestle SA |
| Others |
Value Network & Pricing Analysis
rPET substitution for virgin PET resin is simultaneously shifting supply geography toward Great Lakes recycling infrastructure and compressing price premiums across standard-tier functional water lines. This material transition rewards brands with backward-integrated recycling partnerships while penalizing smaller entrants dependent on spot resin markets.
Pricing Analysis
Current-generation electrolyte formulations command modest premiums over prior-generation basic mineral waters, while next-generation adaptogenic and precision-dosed variants capture the widest price spreads. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by mineral concentration certification and regional sourcing verification. Pricing pressure stems from concentrated retail gatekeeping at Kroger and Loblaws, where slotting fees absorb margin. Young adults exhibit highest price sensitivity, while health-conscious subscription households show lowest elasticity.
Supply Chain Analysis
Just-in-time mineral concentrate procurement dominates electrolyte formulation, though strategic stockpiling of magnesium and potassium carbonate is emerging among larger producers exposed to Chilean and Israeli supply volatility. Manufacturing concentrates in the United States, Canada, and Mexico, with the Great Lakes corridor hosting densest aseptic filling capacity. Key inputs include Utah-sourced salt deposits, Chilean magnesium carbonate, and Israeli potassium suppliers. Single-source vulnerability in South American magnesium exposes margins to fertilizer market fluctuations. Distribution runs through direct-store-delivery networks anchored by PepsiCo and Coca-Cola infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California SB 54's biodegradable packaging mandates are accelerating a technological inflection that will separate first-mover brands from laggards across the North American functional water sector. This regulatory compression creates asymmetric opportunity for supply chain-advantaged players.
For Market Incumbents: Consolidate shelf position through exclusive direct-store-delivery contracts with convenience chains in Texas and Florida, locking out regional challengers. Acquire co-packing capacity in the Great Lakes corridor to secure aseptic filling lines before utilization bottlenecks worsen. Vertical integration into Utah mineral sourcing insulates against Chilean supply volatility.
For New Entrants and Emerging Players: Lead with pediatric lower-sodium formulations targeting school lunch and youth sports channels, where American Academy of Pediatrics alignment creates defensible white space. Subscription bundling in Seattle and Vancouver bypasses retail slotting barriers while capturing wellness household lifetime value. Direct-to-consumer sampling integrates with corporate wellness platforms in Austin and Denver.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed functional water specialists possessing Health Canada master files but limited US distribution scale. Five-to-ten-year viability hinges on cross-border claim substantiation capabilities and compostable packaging validation. Watch California SB 54 compliance timelines as inflection signal for packaging technology winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Bypasses Kroger and Loblaws slotting fees while locking recurring revenue from wellness households. |
| Compostable Packaging Certification | California SB 54 compliance creates first-mover advantage ahead of mandate implementation. |
| Health Canada Master File Acquisition | Accelerates bilingual labeling approval for vitamin-infused cognitive benefit claims. |
| Utah Mineral Sourcing Integration | Captive supply of sodium and magnesium reduces exposure to Chilean carbonate volatility. |
| Pediatric Formulation Development | American Academy of Pediatrics alignment opens underserved school and youth sports channels. |
Research Methodology
The analysis maps electrolyte, vitamin-infused, mineral, and herbal functional water sub-sectors, each validated through beverage chemists, retail category managers, co-packing operations directors, and corporate wellness procurement leads. Primary interview intelligence triangulates against FDA 21 CFR filings, Health Canada Food and Drugs Act amendments, Nielsen retail audit data, and customs import records for magnesium and potassium carbonate. Bottom-up volume modeling reconciles with top-down category spending estimates.
Consistency checks validate projections against external benchmarks including convenience channel velocity data and subscription platform growth metrics. The forecast framework segments by formulation chemistry, packaging format, distribution channel, and end-user demographic across the projection horizon. CAGRs derive from mineral input cost trajectories, regulatory approval timeline assumptions, and retail shelf space allocation trends. Modeled inputs include California SB 54 implementation pace and Health Canada substantiation requirement evolution.
The analysis sits within stated boundaries; outcomes outside sustained fitness culture maturation in California, Texas, and Florida or absent Health Canada-FDA claim harmonization would require recalibration. Forecasts reflect documented assumptions regarding mineral supply stability and retail consolidation trajectories. Revision becomes warranted when Chilean magnesium export restrictions or Kroger category management shifts cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Galacto Oligosaccharides (GOS) Market
Functional Food and Beverage
Global Functional Mushrooms Market
Functional Food and Beverage
Prebiotic Fiber Market
Functional Food and Beverage
Keto Ice Cream Market
Functional Food and Beverage
Flavored and Functional Water Market
Functional Food and Beverage
Global Oral Proteins and Peptides Market
Functional Food and Beverage
Liquid Breakfast Products Market
Functional Food and Beverage
Europe Medical Foods Market
Functional Food and Beverage
Very Low Calorie Desserts Market
Functional Food and Beverage
Low Fat Product Market
Functional Food and Beverage
Yeast Beta Glucan Market
Functional Food and Beverage
Oat Beta-Glucan Market
Functional Food and Beverage
Europe Functional Beverages Market
Functional Food and Beverage
Reduced Sugar Food and Beverages Market
Functional Food and Beverage
Grape Skin–Carob Synergy Antioxidant Systems Market
Functional Food and Beverage
Functional Beverage Market