
 Severe Combined Immunodeficiency Market | 2026-2036
Severe Combined Immunodeficiency Market Size, Share, and Industry Trends Forecast 2026-2036
Severe Combined Immunodeficiency Market Analysis
Gene therapy manufacturing complexity is narrowing the pool of viable commercial suppliers for severe combined immunodeficiency treatments. CSL Behring leverages its plasma-derived immunoglobulin infrastructure to sustain reliable supply chains for pre-transplant bridging therapy. GSK Plc anchors European regulatory relationships that accelerate advanced therapy medicinal product approvals. Bluebird Bio specializes in lentiviral vector platforms that differentiate its autologous gene therapy approach from allogeneic alternatives.
Severe combined immunodeficiency comprises a heterogeneous group of genetic disorders characterized by absent or profoundly impaired T-cell development, often accompanied by defective B-cell and natural killer cell function, requiring hematopoietic stem cell transplantation or gene correction for survival. Gene therapy using viral vector delivery of corrected IL2RG or ADA genes into patient hematopoietic stem cells represents the most technically advanced treatment modality, with manufacturing scalability limiting commercial reach. Stem cell transplantation from matched sibling donors remains the established standard with highest long-term efficacy, while immunoglobulin therapy occupies a persistent maintenance role for patients awaiting definitive intervention. CRISPR-based editing platforms are attracting development investment but face manufacturing and regulatory validation hurdles before clinical translation.
FDA's Office of Therapeutic Products oversees gene therapy CMC requirements for SCID products, while EMA's Committee for Advanced Therapies shapes parallel European approval pathways through centralized marketing authorization procedures. National newborn screening programs governed by state health departments in the United States and comparable regional health authorities in Europe determine diagnostic case detection rates that directly shape addressable patient populations. Stakeholders must monitor evolving payer policies for single-administration curative therapies against chronic immunoglobulin replacement schedules.
Market Dynamics
Gene therapy manufacturing complexity is compressing the supplier base for severe combined immunodeficiency treatments, as lentiviral vector production bottlenecks and FDA CMC requirements force consolidation among contract development and manufacturing organizations serving this ultra-rare indication.
Growth Catalysts
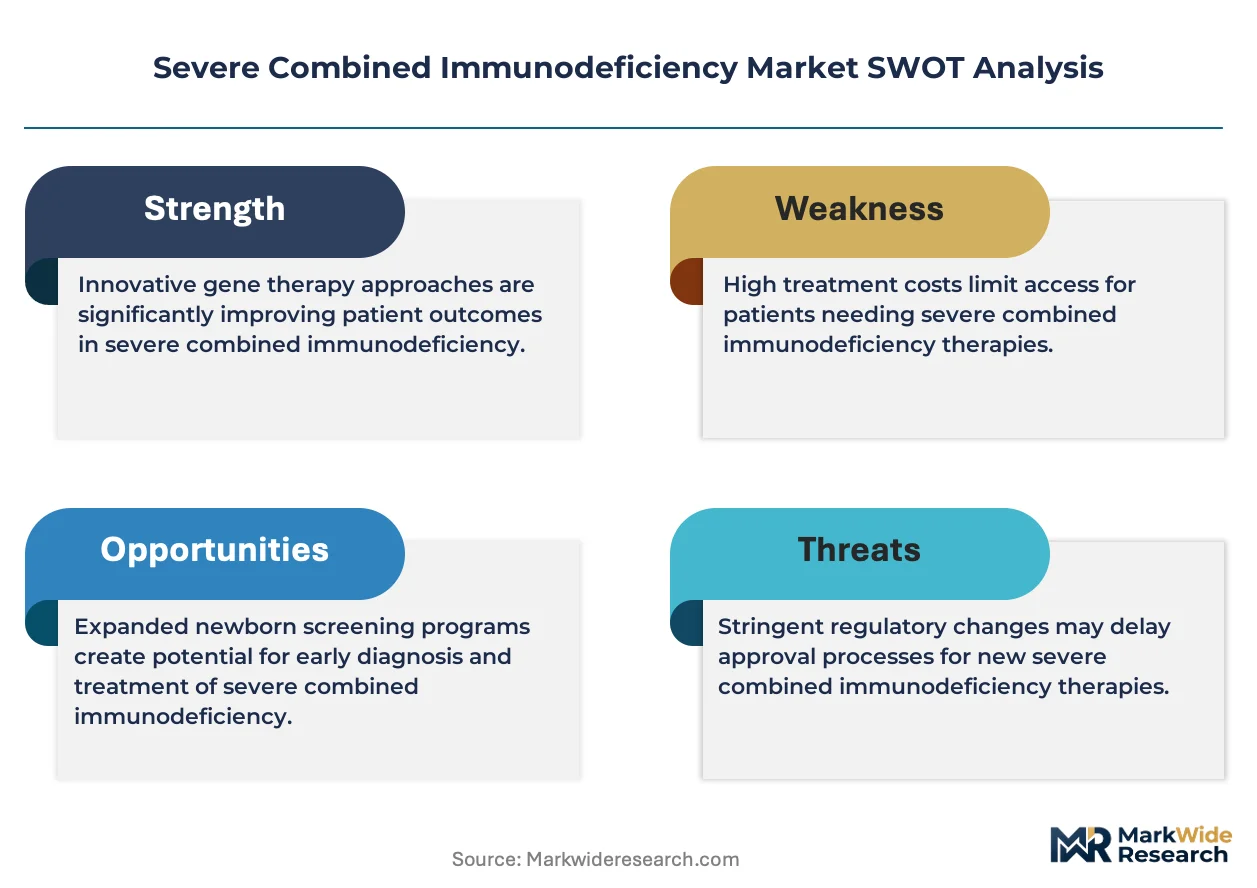
- Newborn screening mandates:State health departments across the United States have expanded SCID screening to all fifty states, creating a reliable diagnostic funnel that channels patients toward specialized treatment centers before opportunistic infections compromise transplant eligibility.
- CMS reimbursement evolution:The Centers for Medicare & Medicaid Services is developing novel payment mechanisms for single-administration curative gene therapies, reducing financial barriers that previously delayed patient access to definitive interventions.
- Academic medical center clustering:Pediatric hematopoietic stem cell transplantation programs at institutions like Boston Children's Hospital and the University of California San Francisco have concentrated expertise and referral networks, accelerating time-to-treatment for diagnosed infants.
Market Restraints
- Vector manufacturing scarcity:Lentiviral vector production capacity concentrates among a handful of CDMOs with compliant cleanroom infrastructure, creating supply chokepoints that limit commercial scale-up of autologous gene therapies.
- Allogeneic donor availability:Matched sibling donors remain unavailable for the majority of SCID patients, forcing reliance on haploidentical or unrelated donor transplants with inferior immune reconstitution profiles and higher graft-versus-host disease incidence.
- Preconditioning toxicity:Chemotherapy-based myeloablation regimens required for stem cell engraftment carry substantial morbidity in neonates and infants, deterring early intervention and complicating risk-benefit calculations for gene therapy candidates.
Strategic Opportunities
- CRISPR editing platforms:Next-generation gene correction technologies promise to bypass viral vector manufacturing constraints entirely, enabling electroporation-based delivery of ribonucleoprotein complexes directly into patient hematopoietic stem cells ex vivo.
- In-utero intervention protocols:Fetal transplantation and gene therapy approaches under investigation at the University of Pennsylvania and University of California San Francisco could eliminate the need for postnatal preconditioning by exploiting immunological tolerance windows.
- European ATMP acceleration:EMA's Committee for Advanced Therapies offers priority medicines designation and centralized marketing authorization procedures that compress regulatory timelines for innovative SCID therapies seeking European market entry.
Industry Challenges
- Gene therapy workforce scarcity:Competent cell processing specialists, vector biologists, and GMP manufacturing technicians remain concentrated at a limited number of academic and commercial sites, constraining expansion of production capacity.
- Long-term follow-up infrastructure:Fifteen-year post-treatment surveillance requirements for gene therapy recipients demand sustained clinical and data management resources that strain academic medical center budgets and patient retention protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Severe Combined Immunodeficiency Market |
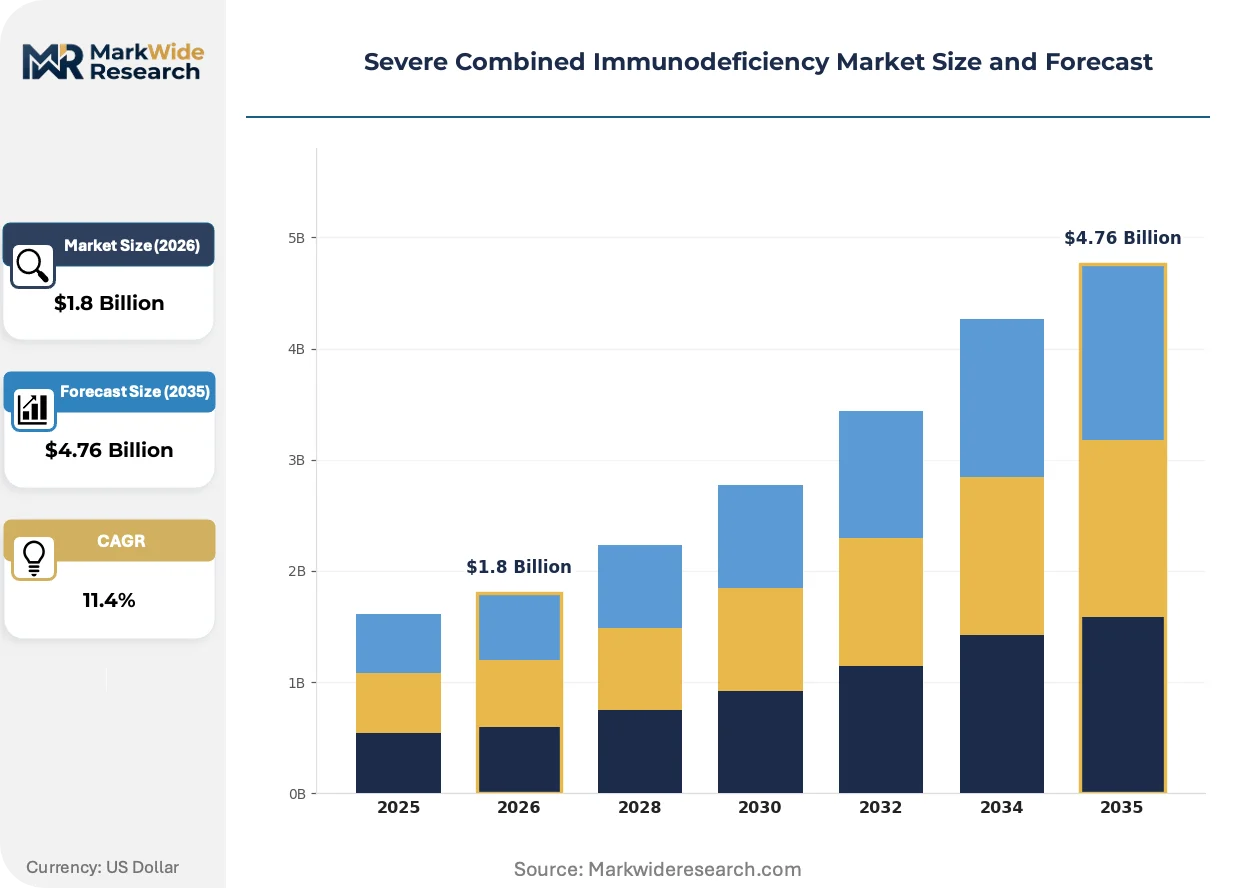
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Therapy, Stem Cell Transplantation, Enzyme Replacement Therapy, Immunoglobulin Therapy End User: Pediatric Hospitals, Specialty Clinics, Academic Research Centers, Homecare Settings Delivery Mode: Intravenous, Subcutaneous, Intraosseous, Oral Technology: CRISPR, Viral Vector, Electroporation, Microinjection |
| Companies Covered | CSL Behring, GSK Plc, Takeda Pharmaceutical, Grifols, ADMA Biologics, Octapharma, Novartis, Bluebird Bio, Revvity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Severe Combined Immunodeficiency Market Emerging Trajectories
Lentiviral vector engineering and ex vivo cell processing automation are compressing production timelines while regulatory frameworks adapt to single-administration curative modalities that defy conventional chronic therapy reimbursement structures.
Self-inactivating lentiviral vector designs with insulator elements are collapsing the genotoxicity risk profile that previously constrained SCID gene therapy dosing. Pediatric transplant centers at the National Institutes of Health and Memorial Sloan Kettering Cancer Center are adopting these third-generation platforms for clinical protocols. This safety improvement is collapsing the risk-benefit threshold for offering gene therapy to patients with available matched sibling donors, historically reserved for transplantation.
FDA's Office of Therapeutic Products issued finalized guidance on human gene therapy products for rare diseases, establishing chemistry, manufacturing, and controls expectations that harmonize with International Council for Harmonisation standards. The guidance mandates comparability protocols for manufacturing changes and potency assay validation that extend development timelines by twelve to eighteen months. Sponsors targeting the United States market are responding by front-loading CMC investment and engaging the agency through pre-IND meetings before clinical trial initiation.
Diagnostic referral patterns are consolidating around regional newborn screening hubs with direct electronic links to specialized treatment centers, bypassing community pediatricians who previously introduced treatment delays. State health departments in California, New York, and Massachusetts have pioneered this hub-and-spoke model. The consolidation is most visible in the Northeast corridor, where diagnosed infants now reach definitive care centers within seventy-two hours of positive screening results.
Severe Combined Immunodeficiency Market Segmentation
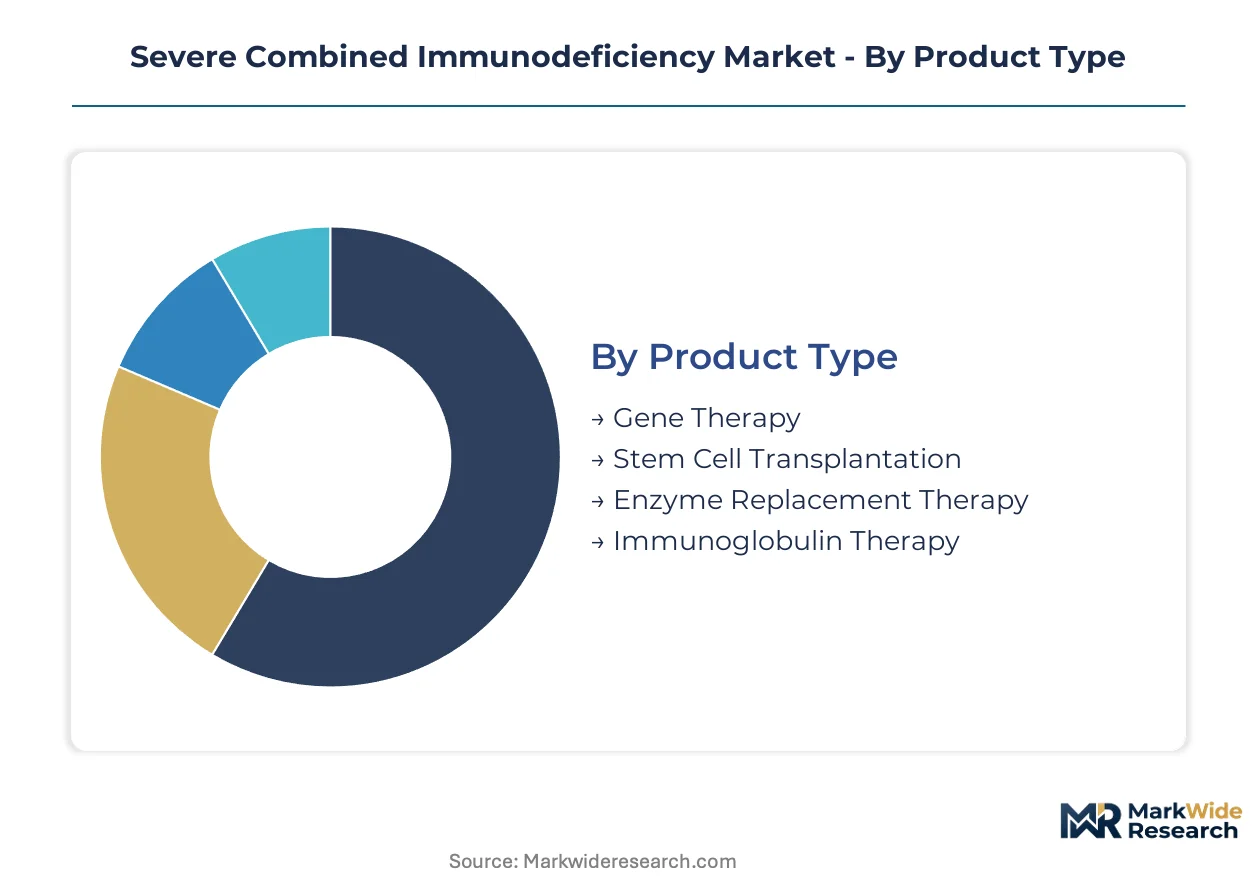
SCID treatment modalities span curative and maintenance interventions with divergent manufacturing requirements, reimbursement pathways, and clinical infrastructure needs. Each segment carries distinct regulatory classifications that shape competitive positioning and patient access dynamics.
Product Type:
Cost tier separates definitive interventions from chronic maintenance, with manufacturing complexity and reimbursement magnitude varying by orders of magnitude across the spectrum.
- Gene Therapy:Autologous lentiviral vector delivery of corrected IL2RG or ADA genes into patient hematopoietic stem cells requires dedicated cleanroom suites and fifteen-year post-treatment surveillance protocols. Academic medical centers in the United States concentrate demand as FDA CMC requirements limit commercial manufacturing scale.
- Stem Cell Transplantation:Allogeneic hematopoietic stem cell infusion from matched sibling, haploidentical, or unrelated donors remains the established standard with highest documented long-term immune reconstitution. Transplant volume clusters at pediatric hospitals with dedicated HLA-matching laboratories and intensive care infrastructure.
- Enzyme Replacement Therapy:PEGylated adenosine deaminase enzyme infusions for ADA-SCID subtype provide metabolic detoxification without genetic correction.
- Immunoglobulin Therapy:Plasma-derived or recombinant immunoglobulin G infusions bridge patients to definitive intervention or sustain immune function when curative options are contraindicated.
Gene therapy holds installed capacity. Stem cell transplantation is rotating up the share rankings as screening expansion channels patients toward definitive care.
End User:
Patient flow concentrates where newborn screening infrastructure connects directly to specialized treatment capabilities, creating hub-and-spoke referral patterns.
- Pediatric Hospitals:Comprehensive children's hospitals with integrated hematopoietic stem cell transplantation programs manage the full care continuum from diagnosis through long-term immune reconstitution monitoring. State-mandated screening programs in California, New York, and Massachusetts direct patient volume toward these centers.
- Specialty Clinics:Dedicated immunology and transplant outpatient facilities provide chronic immunoglobulin administration and pre-transplant evaluation services. These settings capture maintenance therapy demand in metropolitan areas with established SCID patient populations.
- Academic Research Centers:NIH-funded institutions conduct gene therapy clinical trials and natural history studies that shape treatment guidelines.
- Homecare Settings:Subcutaneous immunoglobulin self-administration programs enable chronic maintenance outside institutional settings.
Pediatric hospitals dominate curative procedure volume. Homecare settings are climbing the fastest as subcutaneous immunoglobulin protocols mature.
Delivery Mode:
Route selection hinges on vascular access feasibility, treatment urgency, and patient age, with neonatal physiology constraining options.
- Intravenous:Central venous catheter delivery enables high-volume stem cell infusions, gene therapy product administration, and plasma-derived immunoglobulin loading doses. This route dominates inpatient definitive interventions where vascular access is surgically established.
- Subcutaneous:Immunoglobulin replacement via abdominal or thigh infusion sites permits home-based maintenance therapy with portable pump systems. Pediatric homecare programs in the United States have expanded this modality to reduce hospital dependency.
- Intraosseous:Emergency vascular access through bone marrow cavity provides resuscitation capability when peripheral collapse precedes diagnosis.
- Oral:Limited applicability in SCID due to gastrointestinal immune dysfunction and malabsorption in affected infants.
Intravenous retains procedural dominance. Subcutaneous is expanding most quickly as homecare infrastructure spreads.
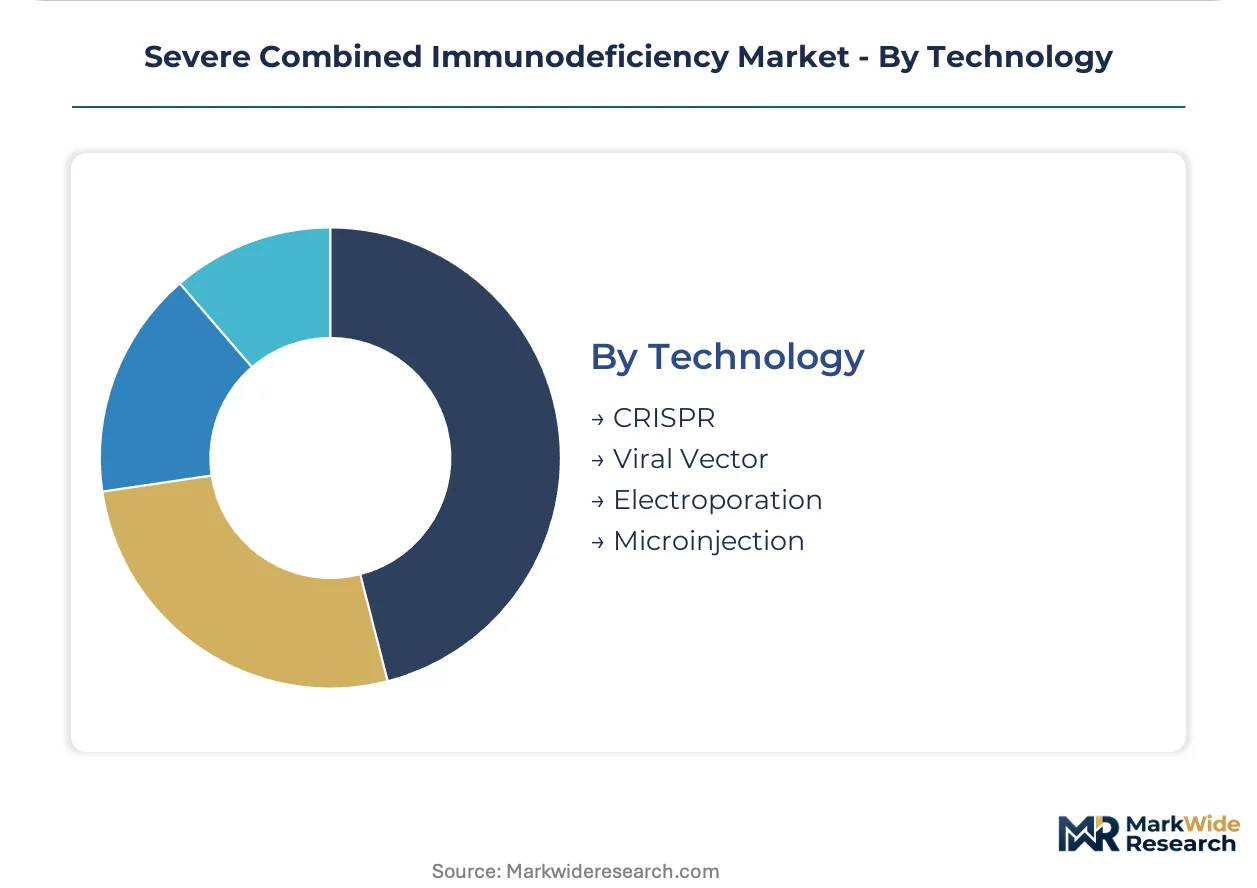
Technology:
Gene correction platforms differentiate by manufacturing scalability, editing precision, and regulatory validation status.
- Viral Vector:Self-inactivating lentiviral designs with insulator elements deliver therapeutic transgenes with collapsed genotoxicity risk profiles. Third-generation platforms from specialized CDMOs supply clinical trials and early commercial programs.
- CRISPR:Ribonucleoprotein complex delivery enables precise gene editing without persistent viral sequences, bypassing vector manufacturing constraints. Electroporation protocols at University of Pennsylvania and UCSF are advancing toward clinical translation.
- Electroporation:Ex vivo cell membrane permeabilization facilitates non-viral cargo delivery into hematopoietic stem cells.
- Microinjection:Direct pronuclear injection for in-utero intervention protocols remains investigational.
Viral vector holds installed capacity. CRISPR is rotating up the share rankings as manufacturing bottlenecks constrain lentiviral supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gene therapy vectors and plasma-derived immunoglobulins flow from United States manufacturing sites to pediatric treatment centers in Germany, Japan, and the United Kingdom. Diagnostic screening reagents and lentiviral production capacity concentrate in North American and European supply chains.
United States
State-mandated newborn screening programs in California, New York, and Massachusetts channel diagnosed infants toward academic medical centers within seventy-two hours. FDA's Office of Therapeutic Products oversees gene therapy CMC requirements that shape manufacturing investment decisions. Boston Children's Hospital and University of California San Francisco anchor concentrated expertise in hematopoietic stem cell transplantation and gene therapy protocols.
Germany
Specialized pediatric immunology clinics in Munich and Heidelberg manage referral networks for central European SCID patients seeking definitive intervention. EMA's Committee for Advanced Therapies accelerates ATMP approvals through centralized marketing authorization procedures. The Heidelberg University Hospital cluster coordinates cross-border patient flows from Austria, Switzerland, and Poland.
United Kingdom
Great Ormond Street Hospital in London operates one of Europe's highest-volume pediatric transplant programs for severe combined immunodeficiency. The UK National Screening Committee mandates dried blood spot testing protocols that align with NHS treatment pathways. Oxford and Cambridge research clusters advance lentiviral vector engineering and CRISPR editing platforms.
Japan
PMDA's regenerative medicine framework accommodates conditional approvals for gene therapies addressing ultra-rare indications like SCID. Tokyo and Osaka pediatric hospitals concentrate domestic transplant capacity amid limited matched sibling donor availability. Japanese pharmaceutical manufacturers invest in plasma fractionation capacity to reduce import dependency for immunoglobulin bridging therapy.
Canada
Health Canada coordinates with provincial health ministries to standardize newborn screening algorithms across Ontario, Quebec, and British Columbia. The Hospital for Sick Children in Toronto anchors national referral patterns for definitive SCID interventions. Canadian blood services infrastructure supports immunoglobulin distribution to remote pediatric populations awaiting transplantation.
Severe Combined Immunodeficiency Market Vendor Landscape
Channel-controlling players compete with product-specialist players across plasma-derived immunoglobulin, gene therapy vector manufacturing, and diagnostic screening segments. The supplier base concentrates around three strategic tiers: diversified plasma fractionators with established distribution networks, dedicated gene therapy developers with lentiviral platform expertise, and specialized CDMOs with compliant cleanroom infrastructure. Dominant competitive moves include backward integration into vector manufacturing capacity and strategic partnerships between academic medical centers and commercial sponsors.
Among diversified plasma specialists, CSL Behring, GSK Plc, and Bluebird Bio exemplify contrasting archetypes. CSL Behring represents the established fractionator model leveraging immunoglobulin infrastructure for bridging therapy supply. GSK Plc occupies a position anchoring European regulatory relationships for advanced therapy approvals. Bluebird Bio exemplifies the gene therapy pure-play focused on lentiviral vector platforms for autologous correction approaches.
| Leading Market Players |
|---|
| CSL Behring |
| GSK Plc |
| Takeda Pharmaceutical |
| Grifols |
| ADMA Biologics |
| Octapharma |
| Novartis |
| Bluebird Bio |
| Revvity |
| Others |
Supply Flow & Price Mechanics
Trans-Atlantic cold-chain logistics corridors connecting United States vector manufacturing sites to European pediatric treatment centers impose freight costs that compound supply scarcity premiums, concentrating pricing power among lentiviral producers while forcing academic medical centers to absorb differential costs across gene therapy, transplantation, and immunoglobulin bridging tiers.
Pricing Analysis
Third-generation self-inactivating lentiviral vector platforms command substantial premiums over earlier gamma-retroviral designs, while CRISPR-based electroporation protocols under development at University of Pennsylvania and UCSF promise to collapse manufacturing costs by eliminating viral production entirely. Pricing stratifies across premium gene correction, standard allogeneic transplantation, and economy immunoglobulin maintenance tiers, with quality grade and FDA CMC certification status as primary differentiation drivers. Pricing pressure stems from CMS reimbursement negotiations for single-administration curative therapies. Pediatric hospitals exhibit highest price sensitivity due to constrained specialty pharmacy budgets, while academic research centers demonstrate lowest sensitivity given grant-funded procurement channels.
Supply Chain Analysis
Lentiviral vector contract manufacturing concentrates among a handful of CDMOs with compliant cleanroom infrastructure in the United States, Germany, and Switzerland, with Oxford and Cambridge research clusters feeding specialized production expertise. Supply chains draw from plasmid DNA templates, packaging cell lines, and fetal bovine serum as critical inputs. Single-source vulnerability pervades vector manufacturing capacity, where qualified facility transfers require eighteen-month validation cycles. Distribution runs through regional newborn screening hubs with direct electronic links to specialized pediatric treatment centers, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stem cell transplantation faces substitution pressure from autologous gene therapy platforms, requiring incumbents to defend procedural volume through outcomes differentiation and strategic capacity positioning.
For Market Incumbents: Entrench matched sibling donor program volume by publishing long-term immune reconstitution data that contrasts favorably with gene therapy durability signals, while securing backward integration into vector manufacturing capacity to capture margin from substitution-driven demand shifts. Invest in FDA CMC certification for in-house lentiviral production to reduce dependency on concentrated CDMO supply.
For New Entrants and Emerging Players: Build out CRISPR editing platform capabilities targeting the European ATMP pathway, where EMA priority medicines designation accelerates regulatory timelines relative to United States FDA review. Penetrate the enzyme replacement therapy segment for ADA-SCID subtype, where PEGylated adenosine deaminase manufacturing presents lower technical barriers than viral vector platforms. Pursue academic medical center partnerships as primary go-to-market channel.
For Investors and Strategic Acquirers: Gene therapy pure-plays with validated lentiviral platforms and fifteen-year post-treatment surveillance infrastructure represent acquisition targets with durable competitive moats. Long-term viability hinges on manufacturing scalability resolution and reimbursement policy stabilization for curative modalities. Watch CMS novel payment mechanism implementation as inflection indicator for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | CDMO capacity expansion alleviates lentiviral vector bottlenecks constraining commercial gene therapy reach. |
| Regulatory Approval Pathway | EMA Committee for Advanced Therapies priority designation compresses European ATMP timelines versus standard procedures. |
| Clinical Trial Advancement | In-utero intervention protocols at University of California San Francisco could eliminate postnatal preconditioning toxicity barriers. |
| Long-term Supply Agreement | Plasma fractionators securing immunoglobulin sourcing contracts stabilize bridging therapy supply for transplantation waitlists. |
| Pipeline Diversification | CRISPR editing platforms bypass viral manufacturing constraints entirely through electroporation-based ribonucleoprotein delivery. |
Methodological Framework
Initial hypotheses were tested against primary input from gene therapy manufacturing executives, pediatric transplant program directors, FDA regulatory affairs specialists, and CMS reimbursement policy leads, and refined through secondary validation against FDA Office of Therapeutic Products guidance documents, EMA Committee for Advanced Therapies approval records, ClinicalTrials.gov protocol registrations, and newborn screening program expansion announcements. Bottom-up patient flow modeling and top-down market sizing triangulated volume estimates across the analysis window.
Demand-supply balance framing anchored the forecast framework, with segmentation dimensions encompassing treatment modality, end-user institution type, delivery route, and gene correction technology platform. CAGRs were derived from epidemiological incidence rates, screening penetration trajectories, and treatment center capacity expansion plans. Forecast inputs incorporated state-level mandate implementation timelines and vector manufacturing facility commissioning schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by CRISPR platform developers or in-utero therapy pioneers would shift outcomes beyond modeled ranges. Quarterly review of CMS reimbursement policy bulletins and EMA ATMP approval decisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Primary Immunodeficiency Therapeutics Market
Specialty Medicine
Nerve Entrapment Syndrome Therapeutics Market
Specialty Medicine
Global Actinic Keratosis Treatment Market
Specialty Medicine
Multiple Sclerosis Market
Specialty Medicine
Autosomal Dominant Polycystic Kidney Disease Treatment Market
Specialty Medicine
Polycystic Kidney Disease Treatment Market
Specialty Medicine
Exanthema Market
Specialty Medicine
Thyroid Cancer Therapeutics Market
Specialty Medicine
Global Hereditary Angioedema Therapeutics Market
Specialty Medicine
Hemangioma Treatment Market
Specialty Medicine
Global Spinal Muscular Atrophy Treatment Market
Specialty Medicine
APAC Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Premature Ejaculation Treatment Market
Specialty Medicine
Latin America Liver Cancer Treatment Market
Specialty Medicine
Bipolar Disorder Therapeutics Market
Specialty Medicine
Hairy Cell Leukemia Therapeutics Market