
 Global Frozen Breakfast Entrees/Sandwiches Market | 2026-2036
Global Frozen Breakfast Entrees/Sandwiches Market Size, Share, and Industry Trends Forecast 2026-2036
Global Frozen Breakfast Entrees/Sandwiches Market Analysis
The FDA's updated Nutrition Facts labeling is consolidating compliance costs around reformulation and front-of-pack disclosure. Nestle sustains its position through deep R&D investment in clean-label frozen breakfast platforms. General Mills anchors North American distribution through dominant placement in supermarket freezer doors. Conagra Brands competes aggressively on value-tier pricing across its frozen breakfast sandwich portfolio.
Frozen breakfast entrees and sandwiches comprise pre-cooked, individually quick-frozen meal components—typically proteins, eggs, cheese, and grains assembled into reheatable formats requiring microwave or oven thermal processing to achieve safe internal temperatures of 165°F. Their commercial purpose centers on delivering speed-scalable morning meal solutions to foodservice operators and retail consumers with constrained preparation time. The wraps and burritos segment leads volume due to handheld portability and format adaptability to protein and vegetable variations, while the online retail channel represents the fastest-growing distribution pathway as cold-chain logistics mature and direct-to-consumer subscription models gain traction. Sandwiches occupy the most mature position, with margin pools concentrating in premium cheese and specialty sausage ingredient tiers.
The USDA's FSIS oversight of meat and poultry components intersects with FDA jurisdiction over multi-ingredient assembled products, creating dual compliance exposure for manufacturers. EU Green Deal farm-to-fork targets on processed food salt and saturated fat content are reshaping export formulation standards for multinational suppliers. China's SAMR frozen food safety standards impose additional testing protocols for imported breakfast items. Stakeholders must monitor whether regulatory divergence between jurisdictions forces regional SKU proliferation or accelerates harmonized global product platforms.

Market Dynamics
Commuter culture in the United States sustains frozen breakfast sandwich velocity through convenience retail channels, while FDA sodium reformulation mandates compress formulation timelines and consolidate compliance costs among mid-tier manufacturers.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Processed food salt and saturated fat limits are accelerating clean-label R&D investment across multinational supplier portfolios, creating first-mover advantage in reformulated premium tiers.
- Quick-service restaurant grab-and-go expansion:Chains are scaling morning programs that source frozen breakfast components for back-of-house assembly speed, pulling volume through foodservice distribution.
- Cold-chain logistics maturation:Direct-to-consumer subscription models for frozen breakfast items are penetrating suburban markets previously underserved by convenience retail density.
Market Restraints
- Dual USDA-FDA jurisdiction:Meat and poultry components trigger FSIS oversight while assembled products fall under FDA authority, forcing redundant testing protocols and documentation burdens.
- Specialty cheese input concentration:Premium margin pools depend on aged cheddar and specialty sausage supply chains concentrated in Wisconsin and Vermont dairy networks.
- Fresh prepared meal substitution:Refrigerated breakfast bowls and delivery-based morning options are capturing time-constrained consumers seeking perceived freshness advantages.
Strategic Opportunities
- China SAMR frozen food safety standards:Import testing protocol complexity creates barrier-to-entry protection for early-compliant suppliers establishing branded presence in tier-one cities.
- Plant-based protein convergence:Pea protein isolate and mung bean egg analog technologies are opening formulation white space in vegetarian breakfast sandwich lines.
- Online retail channel velocity:Cold-chain last-mile investment by major e-commerce platforms is enabling subscription-based frozen breakfast penetration in secondary US metropolitan areas.
Industry Challenges
- Refrigeration technician scarcity:Cold-chain maintenance and blast-freezer operation require specialized HVAC-R credentials that food manufacturing regions struggle to source.
- Front-of-pack disclosure compliance:FDA updated Nutrition Facts implementation demands graphic redesign and label inventory management across multi-SKU portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Frozen Breakfast Entrees/Sandwiches Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wraps, Burritos, Sandwiches, Pancakes Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesale Key Ingredients: Eggs, Sausages, Vegetables, Cheese Target Consumers: Busy Professionals, Students, Families, Health-Conscious |
| Companies Covered | Conagra Brands, B&G Foods, Nestle, Amy's Kitchen, McCain Foods, General Mills, Kellogg Company, Unilever, Kraft Heinz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Frozen Breakfast Entrees/Sandwiches Market Emerging Trajectories
Reformulation pressure and channel fragmentation are simultaneously compressing traditional manufacturing margins and opening modular production architectures that separate protein preparation from final assembly.
Individual quick-freezing (IQF) technology is modularizing component production workflows. Protein processors now freeze sausage patties and egg rounds as discrete units before third-party assembly. Foodservice operators and retail brands mix-and-match components without captive production lines. This architecture compresses capital requirements for new market entrants while fragmenting margin capture across the value chain.
EU Green Deal farm-to-fork salt reduction targets are forcing sodium reformulation across export-bound breakfast portfolios. Processors must maintain sensory profiles while cutting sodium by mandated thresholds. Breakfast sandwich lines destined for European distribution bear the highest compliance burden, with manufacturers accelerating potassium chloride and yeast extract flavor masking trials.
Buyer concentration among convenience retail chains is compressing supplier negotiation cycles. Frozen breakfast sandwich procurement at major US convenience retailers now operates on 90-day price lock terms rather than annual contracts. This compression most visibly affects mid-tier manufacturers lacking vertical integration into protein processing, forcing accelerated cost engineering on packaging and logistics rather than formulation.
Global Frozen Breakfast Entrees/Sandwiches Market Segmentation
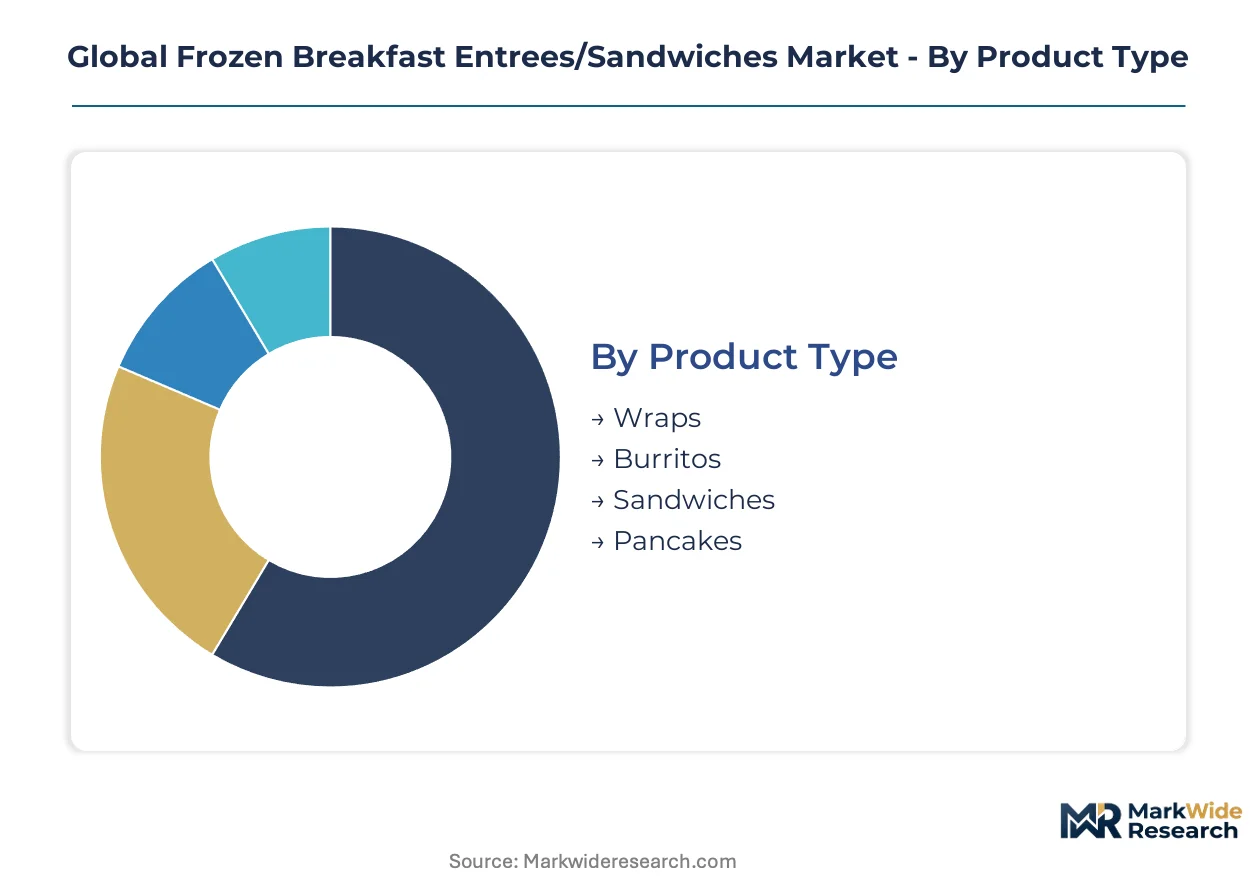
Format fragmentation in frozen breakfast reflects divergent morning routines across commuter corridors, campus clusters, and suburban households. Manufacturers configure production lines around specific product architectures and channel cold-chain requirements rather than pursuing universal platforms.
Product Type:
Portability requirements and eat-while-mobile occasions dominate buyer selection, with handheld formats commanding shelf space allocation in convenience retail.
- Wraps:Flour or whole-grain tortillas encasing scrambled egg, cheese, and protein fillings. Demand concentrates in southwestern US corridors and Texas-Arizona commuter belts where Hispanic breakfast traditions intersect with grab-and-go velocity.
- Burritos:Larger-format flour tortillas with rice, beans, and protein combinations requiring longer microwave cycles. Volume clusters in California and Colorado markets with established frozen Mexican food infrastructure.
- Sandwiches:English muffin, biscuit, or croissant platforms with egg, cheese, and meat patties. The most mature segment with margin pools concentrating in premium cheese and specialty sausage ingredient tiers.
- Pancakes:Griddle-cake formats with syrup pockets or pre-applied toppings targeting family breakfast occasions and child-oriented consumption.
Wraps lead on scale; burritos lead on momentum.
Distribution Channel:
Cold-chain maturity and inventory turnover economics determine channel viability, with frozen breakfast requiring sustained sub-zero handling through final handoff.
- Supermarkets:Full-size freezer door placement with multi-SKU facings dominates household stock-up occasions. Placement battles concentrate in Kroger, Albertsons, and Ahold Delhaize banner negotiations.
- Convenience Stores:Compact freezer units near checkout capture impulse and commuter substitution for QSR morning visits. 7-Eleven and Circle K procurement cycles compress to 90-day price locks.
- Online Retail:Direct-to-consumer subscription models and platform delivery penetrate suburban markets with limited convenience density. Cold-chain last-mile investment by Amazon and Instacart enables expansion.
- Wholesale:Club and foodservice bulk formats serving institutional buyers, QSR back-of-house programs, and workplace catering operations with case-lot minimums.
Supermarkets anchor volume; online retail climbs the fastest.
Key Ingredients:
Input cost volatility and reformulation mandates reshape supplier relationships, with protein and dairy networks commanding disproportionate margin influence.
- Eggs:Whole egg, egg white, and processed patty formats subject to avian influenza supply shocks and cage-free transition timelines.
- Sausages:Pork, turkey, and plant-based patty options with FSIS inspection requirements adding compliance layers absent from other proteins.
- Vegetables:Bell peppers, onions, spinach, and potato fillers enabling clean-label positioning and sodium reduction through flavor dilution.
- Cheese:Aged cheddar and processed American slices with supply concentration in Wisconsin and Vermont dairy networks creating input bottlenecks.
Sausages capture the highest value-add; vegetables gain share fastest.
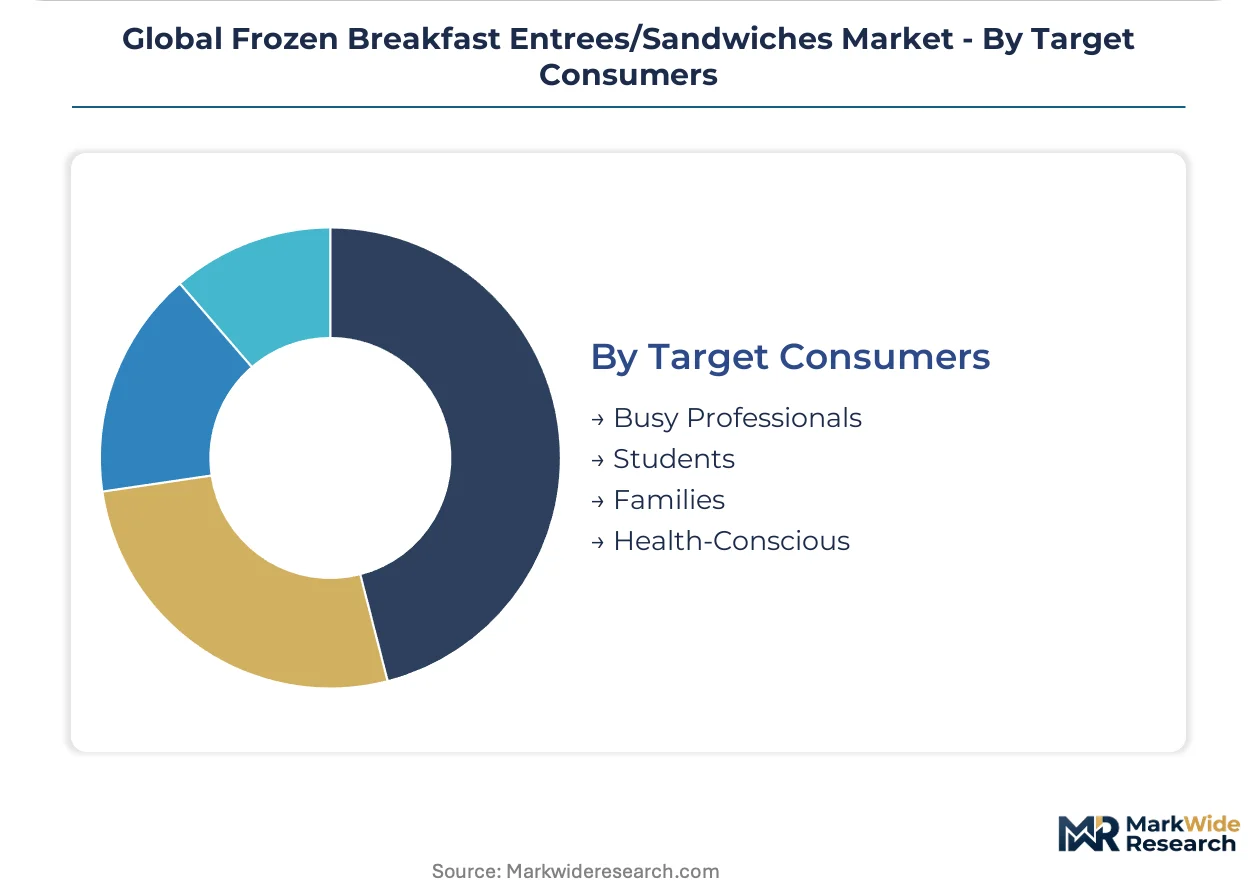
Target Consumers:
Time scarcity and preparation convenience separate addressable segments, with occasion-based positioning replacing demographic targeting in portfolio architecture.
- Busy Professionals:Commuter rail and highway corridor consumption with premium pricing tolerance for speed and protein density.
- Students:Campus-adjacent convenience and value-tier sensitivity with microwave-only preparation requirements in dormitory settings.
- Families:Multi-unit packaging and child-appeal formats with weekend brunch substitution and weekday breakfast rush applications.
- Health-Conscious:Sodium-aware, high-protein, and plant-based seekers driving reformulation investment and front-of-pack disclosure compliance.
Busy professionals generate highest per-unit revenue; health-conscious consumers drive steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food manufacturing talent clusters in Wisconsin and Vermont anchor North American frozen breakfast production. European regulatory pressure from the EU Green Deal farm-to-fork initiative is accelerating sodium reformulation across export portfolios. Asian cold-chain infrastructure investments in tier-one Chinese cities are enabling new distribution pathways for Western breakfast formats.
United States
Commuter rail corridors and highway-adjacent convenience retail sustain frozen breakfast sandwich velocity through 7-Eleven and Circle K procurement networks. FDA updated Nutrition Facts labeling mandates compress reformulation timelines for sodium disclosure compliance. Wisconsin's dairy processing belt concentrates aged cheddar and specialty sausage supply chains serving premium product tiers.
Germany
Discounter retail density and Aldi/Lidl private-label dominance shape frozen breakfast purchasing patterns across metropolitan commuter zones. EFSA processed food salt reduction guidance pressures reformulation investment in export-bound portfolios. Bavaria's food manufacturing corridor hosts multinational assembly operations supplying Central European distribution networks.
China
SAMR frozen food safety standards impose additional testing protocols for imported breakfast items entering Shanghai and Beijing cold-chain warehouses. Tier-one city middle-class expansion creates addressable demand for Western-format breakfast convenience. Yangtze River Delta logistics hubs enable last-mile frozen distribution to previously underserved suburban markets.
United Kingdom
Urban rail commuter density and Pret A Manger/QSR morning substitution patterns sustain grab-and-go frozen breakfast demand in London and Southeast England. Food Standards Agency salt reduction targets align with EU Green Deal trajectory for processed food reformulation. Midlands food manufacturing clusters host contract assembly operations for pan-European retail brands.
Canada
Cross-border supply chain integration with US Midwest dairy and protein networks shapes frozen breakfast input sourcing for Ontario and Quebec processors. Health Canada front-of-pack nutrition symbol requirements accelerate label redesign cycles for multi-SKU portfolios. Greater Toronto Area cold-chain distribution centers serve as consolidation points for national retail banner supply.
Global Frozen Breakfast Entrees/Sandwiches Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressure concentrates margin capture among vertically integrated protein processors and multinational CPG platforms. Three archetypes dominate: scale-driven diversified food manufacturers, regional pure-play frozen specialists, and private-label contract assemblers. Competitive moves center on backward integration into dairy and protein processing and accelerated clean-label reformulation pipelines.
Within the diversified conglomerate tier, Nestle and General Mills occupy positions defined by R&D depth and freezer-door placement leverage. Conagra Brands exemplifies value-tier positioning through aggressive pricing across frozen breakfast sandwich portfolios. Amy's Kitchen represents the organic-specialist archetype with clean-label positioning that commands premium shelf space allocation in natural retail channels.
| Leading Market Players |
|---|
| Conagra Brands |
| B&G Foods |
| Nestle |
| Amy's Kitchen |
| McCain Foods |
| General Mills |
| Kellogg Company |
| Unilever |
| Kraft Heinz |
| Others |
Supply Flow & Price Mechanics
CME lean hog futures and block cheddar spot prices cascade through frozen breakfast manufacturing into three-tier pricing structure across premium, standard, and economy levels, with Wisconsin dairy belt concentration amplifying margin volatility for processors lacking captive cheese supply.
Pricing Analysis
Component-unbundled IQF sourcing separates protein processors from final assemblers, enabling mix-and-match procurement that compresses capital barriers but fragments margin capture. Price differentiation hinges on specialty sausage provenance and aged cheddar grade, with premium tiers commanding shelf space through Vermont and Wisconsin dairy network access. Pricing pressure intensifies as 90-day convenience retail price locks displace annual contracts, squeezing mid-tier manufacturers on logistics rather than formulation. Value-tier buyers in campus and suburban channels exhibit highest price sensitivity; busy professional commuters show lowest.
Supply Chain Analysis
Refrigeration technician scarcity across Wisconsin, Vermont, and Ohio food manufacturing corridors constrains blast-freezer capacity expansion and cold-chain maintenance uptime. Protein preparation draws from Midwest pork processing and Texas-Arizona poultry networks; cheese inputs rest on Wisconsin cheddar and Vermont specialty dairy supply. Single-source vulnerability concentrates in aged cheddar supply chains, where regional dairy cooperative consolidation limits alternative sourcing. Distribution runs through supermarket freezer door placement battles, convenience retail compact units, and maturing direct-to-consumer cold-chain last-mile networks.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The frozen breakfast category reads as a late-cycle quality story, with EU Green Deal sodium mandates and FDA disclosure requirements accelerating demand migration toward clean-label premium specifications that reward reformulation investment.
For Market Incumbents: Anchor freezer-door placement leverage through dominant supermarket banner negotiations while accelerating backward integration into Wisconsin dairy processing to secure specialty cheese supply. Defend against refrigerated breakfast bowl substitution by compressing clean-label reformulation timelines and front-of-pack graphic redesign ahead of compliance deadlines. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms represent the most penetrable channel white space, with suburban secondary metropolitan areas offering density advantages over saturated convenience retail corridors. Target health-conscious consumer segments through plant-based protein convergence in mung bean egg analog and pea protein isolate formulations. Pursue modular IQF component supply partnerships rather than captive production lines to minimize capital requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated protein processors possessing Wisconsin cheddar supply chain access and EU export reformulation capabilities. Five-to-ten-year viability favors specialists with clean-label R&D pipelines and online retail channel infrastructure over pure-play contract assemblers exposed to buyer concentration risk. Monitor SAMR compliance progress among early entrants into Shanghai and Beijing cold-chain distribution as inflection signal for China market timing.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Pipeline | FDA sodium disclosure and EU Green Deal salt targets force accelerated potassium chloride and yeast extract masking trials. |
| Backward Integration into Dairy Processing | Wisconsin and Vermont specialty cheese supply concentration creates input bottlenecks that captive production mitigates. |
| Direct-to-Consumer Subscription Launch | Amazon and Instacart cold-chain last-mile investment enables suburban penetration beyond convenience retail density limits. |
| Plant-Based Protein Line Extension | Pea protein isolate and mung bean egg analog technologies open formulation white space in vegetarian breakfast segments. |
| EU Export Compliance Certification | EFSA processed food salt reduction guidance pressures reformulation investment in export-bound breakfast portfolios. |
Methodological Framework
Bottom-up convenience retail and foodservice operator modeling reconciled against top-down protein processor and dairy supplier tracking forms the analytical core of this study. Primary interviews with brand managers, category buyers at Kroger and Albertsons banners, supply planners at IQF component processors, and channel sales heads at major CPG platforms combined with secondary validation against Nielsen retail audit data, USDA FSIS inspection records, FDA labeling guidance documents, and EU farm-to-fork policy trackers. Triangulation between demand-side consumption patterns and supply-side capacity announcements ensures cross-verified volume estimates.
Historical trendline analysis across frozen breakfast format introductions, sodium reformulation cycles, and channel shift patterns informed projection assumptions. Segmentation dimensions modeled include product architecture, distribution channel cold-chain maturity, protein and dairy ingredient tier, and consumer occasion-based positioning. CAGRs derived from weighted average of bottom-up segment growth and top-down category expansion, with specific inputs from commuter rail corridor density indices, convenience retail procurement cycle compression, and SAMR import testing protocol implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU regulatory enforcement consistency, avian influenza supply shocks in egg networks, and China cold-chain infrastructure buildout pace. Forecasts reflect documented assumptions regarding sodium reformulation success rates, plant-based protein cost parity achievement, and online retail channel share gain trajectories. Material deviation in FDA disclosure compliance deadlines, EU salt threshold adjustments, or China SAMR inspection protocol changes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Latin America Frozen Finger Chips Market
Processed and Frozen Foods
Frozen Tart Shells Market
Processed and Frozen Foods
South America Frozen Food Market
Processed and Frozen Foods
Popsicle Market
Processed and Frozen Foods
Frozen Dough Market
Processed and Frozen Foods
North America Frozen Finger Chips Market
Processed and Frozen Foods
Freeze Dried Tropical Fruits Market
Processed and Frozen Foods
North America Frozen Pizza Market
Processed and Frozen Foods
Dumplings Market
Processed and Frozen Foods
Asia Pacific Frozen Desserts Market
Processed and Frozen Foods
Frozen Basil Leaves Market
Processed and Frozen Foods
Frozen Dumplings Market
Processed and Frozen Foods
Bangladesh Frozen Food Market
Processed and Frozen Foods
IQF Food Products Market
Processed and Frozen Foods
Popsicle and Ice Cream Bar Market
Processed and Frozen Foods
Chilled Processed Food Market