
 Freeze Dried Tropical Fruits Market | 2026-2036
Freeze Dried Tropical Fruits Market Size, Share, and Industry Trends Forecast 2026-2036
Freeze Dried Tropical Fruits Market Insights
A shift from single-source to multi-source fruit procurement is realigning how processors secure raw material consistency across harvest cycles. Dole leverages its integrated plantation networks to sustain year-round feedstock availability for freeze-drying lines. SunOpta competes through organic certification depth, while Van Drunen Farms anchors its position in private-label contract manufacturing for North American retail chains.
Freeze dried tropical fruits are dehydrated products manufactured through sublimation at temperatures below -40°C and pressures under 200 mTorr, preserving cellular structure, native color, and water-soluble vitamin content for shelf-stable food applications. Snack Foods dominates volume throughput as retail consumers prioritize portable, no-added-sugar alternatives to conventional confectionery. Bakery Products represents the fastest-growing application segment, where freeze dried mango and pineapple powders replace artificial flavoring systems in clean-label formulations.
The FDA enforces Current Good Manufacturing Practice and Preventive Controls for Human Foods rules that mandate hazard analysis across freeze-drying operations, directly elevating capital requirements for market entry. USDA Organic certification and Non-GMO Project verification function as de facto gatekeeping standards for shelf placement in premium retail channels. Stakeholders must monitor how evolving EU deforestation-free supply chain regulations reshape import documentation burdens for tropical fruit processors serving European food manufacturers.
Market Dynamics
Multi-source procurement strategies are realigning how processors secure raw material consistency across tropical fruit harvest cycles, forcing suppliers to build redundant sourcing networks rather than rely on single-origin supply.
Growth Catalysts
- Clean-label reformulation mandates:Bakery manufacturers in North America and Europe are replacing artificial flavoring systems with freeze-dried mango and pineapple powders to meet retailer clean-label requirements.
- Thailand's integrated freeze-drying clusters:Central plains processing hubs serve export-oriented contracts with captive cold-chain infrastructure linking plantation to sublimation line.
- FDA's updated FSMA traceability rules:New supplier qualification protocols favor processors with documented hazard analysis and preventive controls, elevating compliant operators above fragmented competition.
Market Restraints
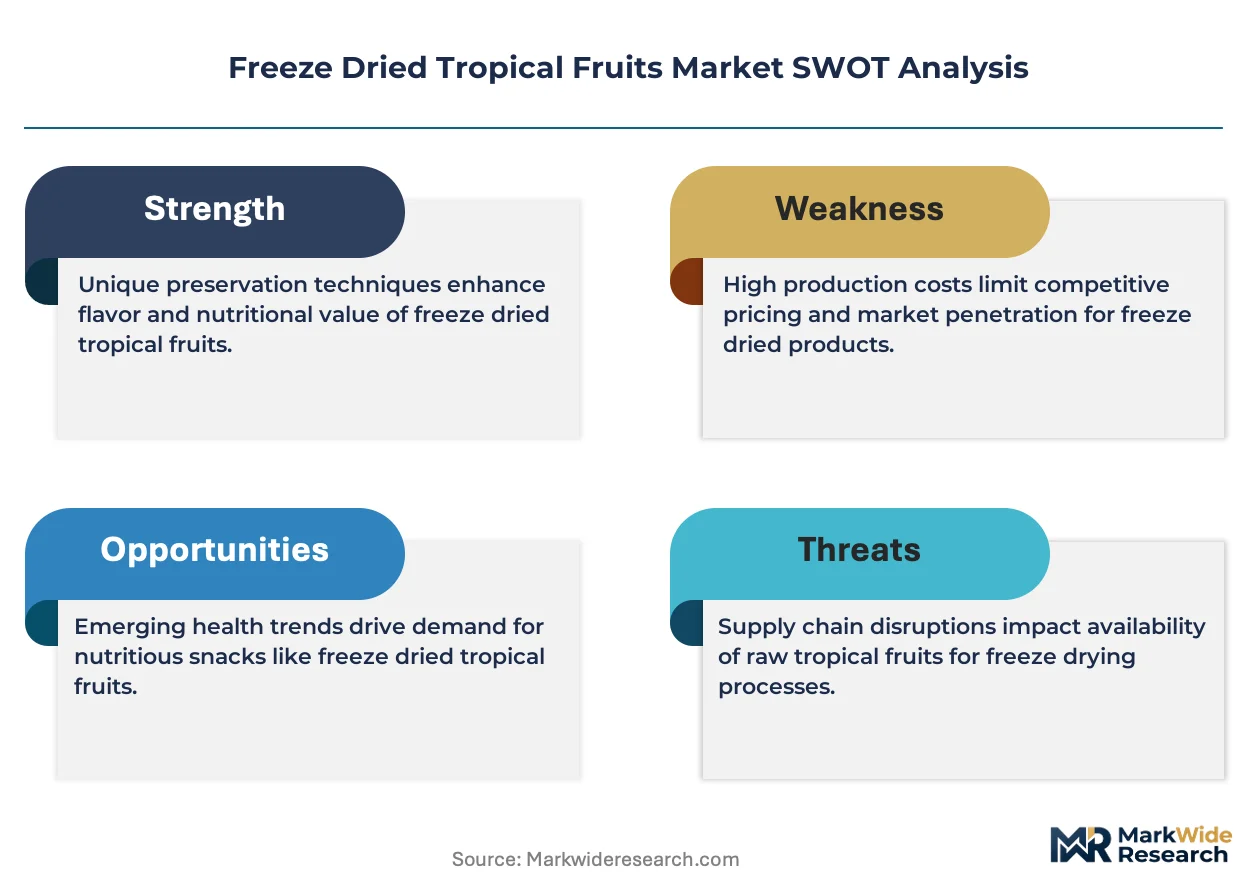
- Energy-intensive sublimation:Freeze-drying requires sustained temperatures below -40°C and pressures under 200 mTorr, locking in high electricity costs that compress margins during tariff spikes.
- Thai supply concentration:Raw material availability clusters in Southeast Asia's central plains, exposing processors to monsoon-driven harvest volatility and regional logistics bottlenecks.
- Fresh and frozen substitution:Cold-chain improvements in developing markets allow food manufacturers to revert to lower-cost frozen fruit when clean-label premiums compress.
Strategic Opportunities
- EU deforestation-free regulations:Importers with verified supply chain documentation gain preferential access to European food manufacturers facing mandatory due diligence obligations.
- Sports nutrition powder integration:Freeze-dried tropical fruit granules are penetrating protein shake and electrolyte formulations as natural flavor carriers without added sugars.
- Direct-to-foodservice channels:Specialty ingredient distributors are bypassing traditional retail brokerage to supply commercial bakeries and confectionery houses with custom particle sizes.
Industry Challenges
- Preventive controls specialist shortage:FDA-mandated hazard analysis requires qualified food safety personnel that smaller processors struggle to recruit and retain.
- USDA Organic certification timelines:Three-year transition periods for conventional orchards delay feedstock availability for processors targeting premium retail placement.
- Legacy drying asset stranding:Conventional hot-air dehydration facilities face accelerated obsolescence as buyers demand cellular-structure preservation only sublimation delivers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freeze Dried Tropical Fruits Market |
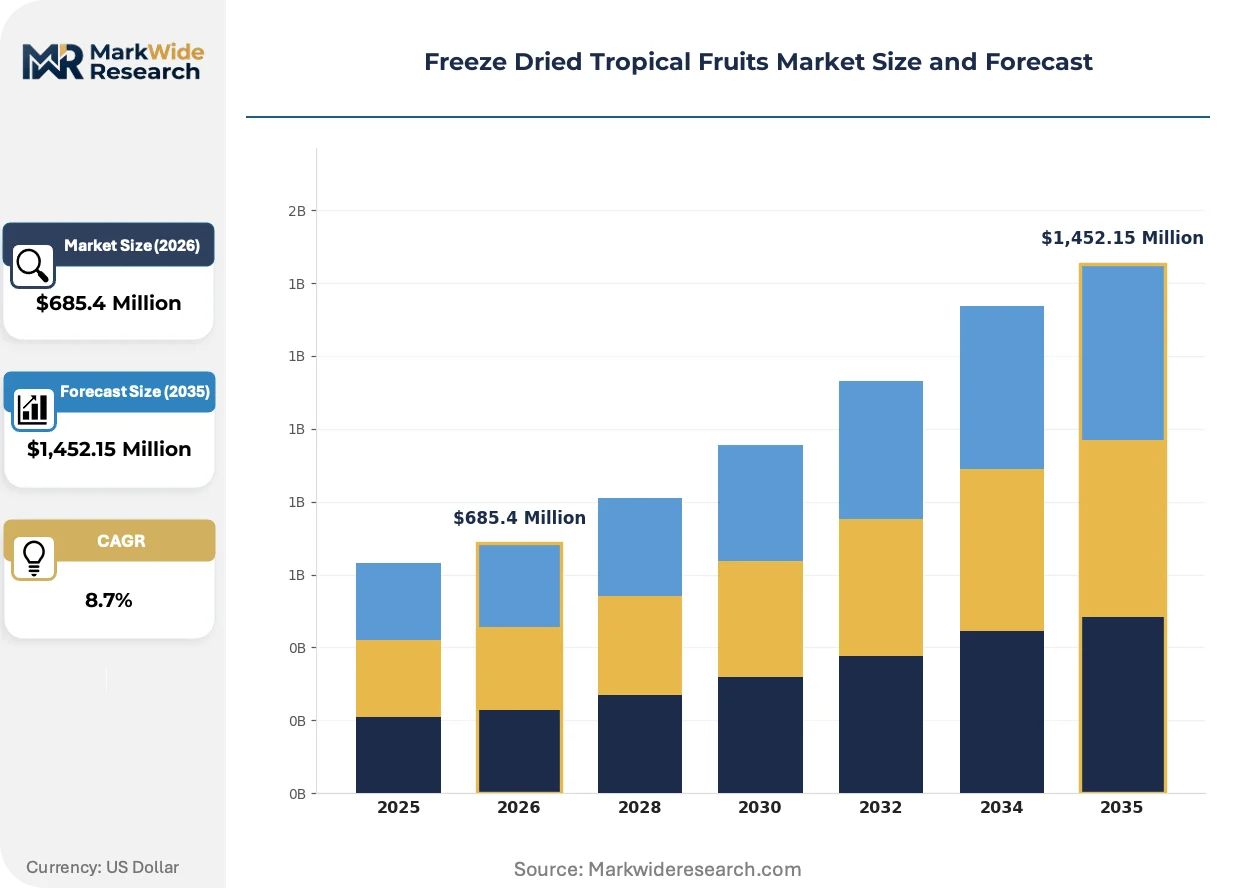
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mango, Pineapple, Banana, Dragon Fruit Application: Snack Foods, Bakery Products, Beverages, Nutritional Supplements End User: Retail Consumers, Food Manufacturers, Restaurants, Catering Services Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Distributors |
| Companies Covered | Dole, Fresh Del Monte, SunOpta, Ardo NV, Natierra, Harmony House Foods, Brothers International Food Holdings, Van Drunen Farms, Paradise Fruits, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freeze Dried Tropical Fruits Market Trends and Innovations
Active investment in sublimation technology variants and supply chain digitization is compressing the gap between plantation harvest and retail shelf placement.
Radio-frequency-assisted freeze-drying is decentralizing production economics by cutting cycle times from 20 hours to under 12 hours while preserving native vitamin content. Mid-scale processors in Vietnam and the Philippines are adopting hybrid RF-vacuum units to compete with Thai integrated clusters. The technology is decentralizing regional production gravity away from centralized mega-facilities toward distributed, orchard-adjacent processing nodes.
EU deforestation-free supply chain regulations are mandating geolocation verification for all tropical fruit imports above specified volume thresholds. European food manufacturers now require polygon mapping of plantation boundaries and harvest documentation back to individual orchard blocks. Bakery and confectionery segments serving EU retail chains are most affected, with processors investing in blockchain-traceability systems to satisfy EUDR due diligence obligations.
Ingredient specification contracts are compressing from annual to quarterly review cycles as food manufacturers demand flexibility on particle size, moisture content, and organic certification status. Specialty distributors are displacing traditional broadline brokers by offering technical formulation support alongside raw material supply. This pattern is most visible in North American clean-label bakery chains, where procurement teams rotate suppliers based on seasonal price and certification availability.
Freeze Dried Tropical Fruits Market Segmentation
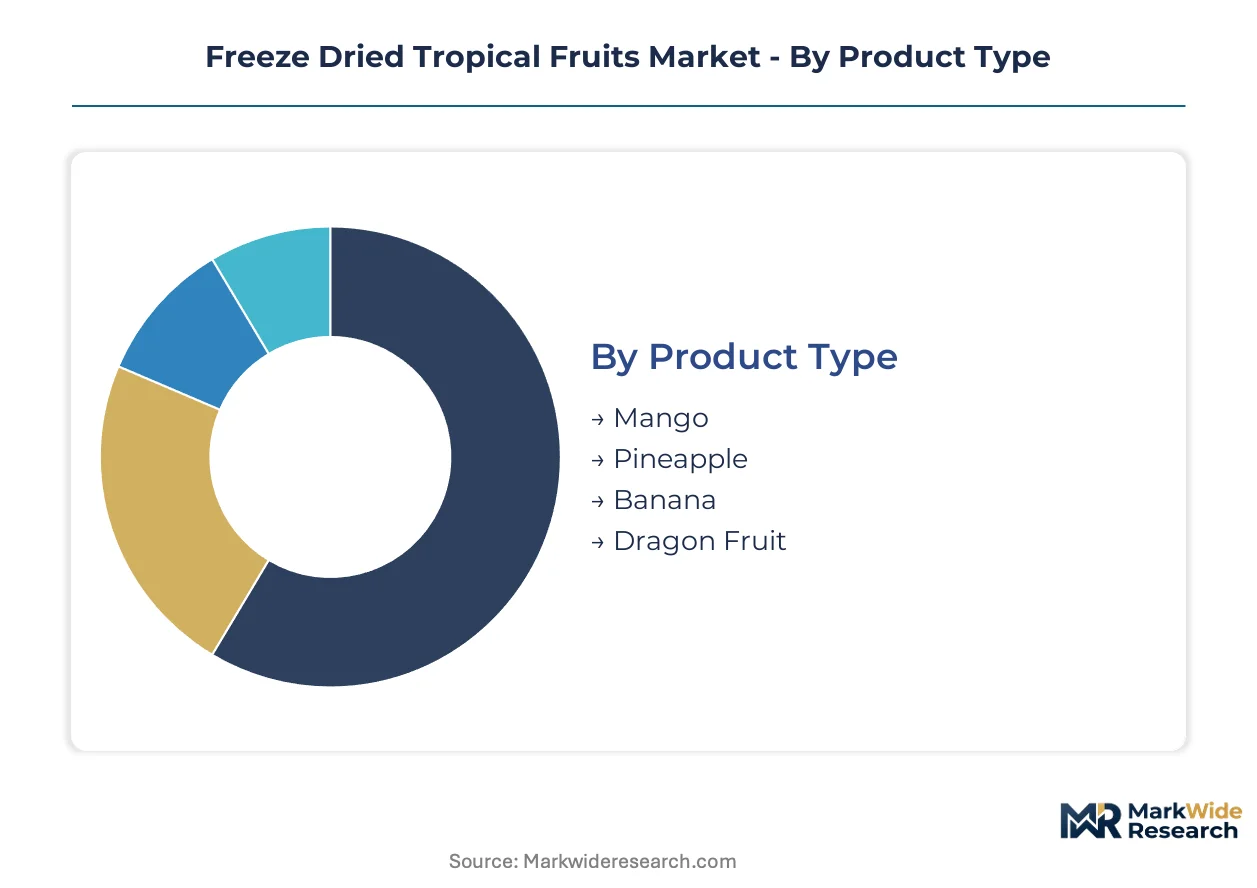
Segmentation in freeze-dried tropical fruits reveals how procurement priorities diverge between commodity buyers seeking volume scale and specialty formulators demanding precise cellular-structure preservation. Understanding these fault lines enables suppliers to align sublimation capacity with the margin structures each segment commands.
Product Type:
Buyers select fruit varieties based on sugar-acid profiles, cellular resilience during sublimation, and clean-label positioning potential in target applications.
- Mango:High β-carotene retention and vibrant orange coloration make this the reference standard for premium snack applications. Demand concentrates in North American clean-label bakery chains where processors specify particle sizes below 2mm for uniform distribution in muffin and cake batters.
- Pineapple:Bromelain enzyme activity requires precise temperature modulation during freeze-drying to prevent protein denaturation. Thai central plains processors dominate supply through integrated plantation-to-sublimation operations serving European confectionery houses.
- Banana:Starch gelatinization during pre-treatment creates textural versatility across infant nutrition and sports powder segments.
- Dragon Fruit:Betacyanin pigment stability appeals to beverage manufacturers seeking natural colorants without synthetic additives.
Mango leads on scale; dragon fruit leads on momentum.
Application:
Application selection dictates moisture specification tolerances, with snack foods demanding crisp fracture mechanics and beverages requiring instant solubility.
- Snack Foods:Whole-piece and chunked formats prioritize structural integrity for audible crispness in retail packaging. This segment anchors volume throughput across Southeast Asian export hubs where processors maintain dedicated lines for North American private-label contracts.
- Bakery Products:Powders and granules replace artificial flavoring systems in clean-label reformulations mandated by major US retail chains. European formulators are expanding fastest as EUDR documentation requirements favor processors with verified supply chain geolocation.
- Beverages:Fine-milled powders with sub-100 micron particle distribution enable suspension stability in ready-to-drink formulations.
- Nutritional Supplements:Vitamin C retention certification drives supplier qualification for sports nutrition and prenatal product lines.
Snack foods leads on scale; bakery products leads on momentum.
End User:
End-user category determines order pattern predictability, with food manufacturers offering contractual volume commitments absent in foodservice channels.
- Food Manufacturers:Contract specifications mandate quarterly certification audits and lot-level traceability documentation. This segment concentrates procurement spend among processors with integrated cold-chain infrastructure spanning Thai central plains plantation networks.
- Retail Consumers:Single-serve pouch formats and brand storytelling around origin narratives command premium shelf positioning in specialty grocers.
- Restaurants:Dessert and garnish applications favor whole-piece aesthetics over powder functionality.
- Catering Services:Bulk procurement of mixed-fruit formats emphasizes cost efficiency over varietal purity.
Food manufacturers leads on scale; retail consumers leads on momentum.
Distribution Channel:
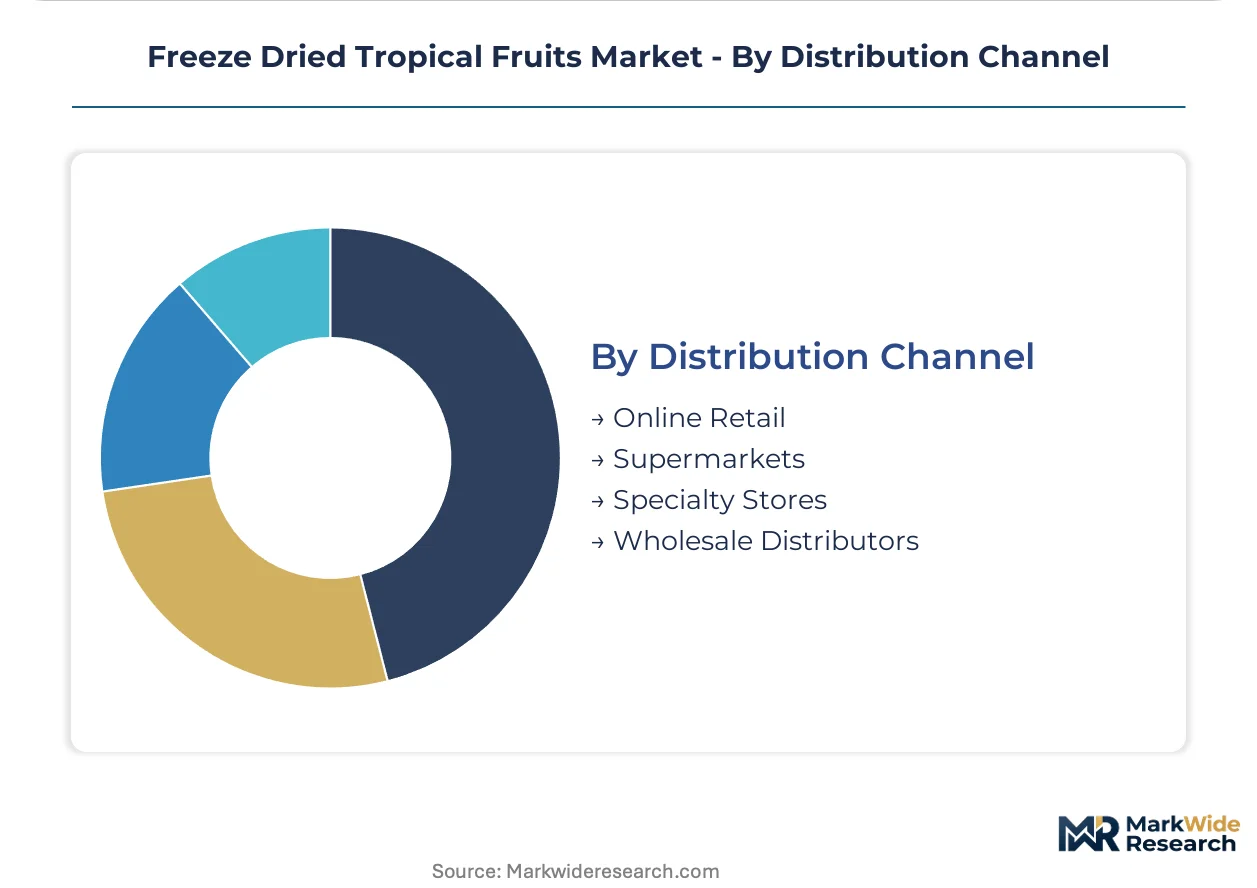
Channel selection reflects buyer urgency tolerance and technical specification complexity, with direct procurement displacing intermediaries for formulation-intensive applications.
- Wholesale Distributors:Technical sales support and custom particle size milling attract bakery and confectionery accounts away from broadline brokers. This channel anchors revenue concentration among processors with in-house formulation laboratories.
- Online Retail:Direct-to-consumer subscription models enable margin capture previously lost to retail slotting fees.
- Supermarkets:Clean-label placement in produce-adjacent aisles requires Non-GMO Project verification as table stakes.
- Specialty Stores:Organic certification depth and single-origin storytelling command price premiums in natural products channels.
Wholesale distributors leads on scale; online retail leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's central plains processing clusters anchor international supply for freeze-dried tropical fruits, with integrated cold-chain infrastructure linking plantation networks directly to sublimation facilities serving export contracts.
United States
Clean-label bakery reformulations drive procurement of freeze-dried mango and pineapple powders among North American retail chains. FDA enforcement of FSMA preventive controls rules elevates compliance costs for imported ingredient qualification. California-based snack food manufacturers maintain dedicated sourcing teams in Bangkok to secure year-round feedstock consistency.
Germany
European confectionery houses source bromelain-stable pineapple products for clean-label candy applications. EU deforestation-free supply chain regulations mandate geolocation verification for all tropical fruit imports above volume thresholds. Hamburg's specialty ingredient distributors invest in blockchain-traceability systems to satisfy EUDR due diligence documentation.
Thailand
Integrated freeze-drying clusters in the central plains region serve export-oriented processing contracts with captive plantation-to-sublimation infrastructure. The Thai FDA aligns hazard analysis protocols with international buyer audit requirements. Chonburi province hosts the densest concentration of RF-assisted vacuum units outside Bangkok metro.
Vietnam
Mid-scale processors adopt hybrid radio-frequency freeze-drying technology to compress sublimation cycles and compete with Thai integrated clusters. The Ministry of Agriculture and Rural Development promotes orchard-adjacent processing nodes through rural industrialization incentives. Mekong Delta dragon fruit cultivation zones attract decentralized drying facility investment.
Philippines
Beverage manufacturers demand fine-milled banana powders for infant nutrition and sports drink formulations. The Food and Drug Administration enforces current good manufacturing practice standards across tropical fruit processing operations. Davao region plantation networks supply raw material to emerging sublimation cooperatives.
Freeze Dried Tropical Fruits Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue RF-assisted technology adoption and organic certification depth as differentiation vectors. Market structure consolidates around integrated plantation processors, specialty organic certifiers, and private-label contract manufacturers. Three archetypes dominate: captive supply chain operators, certification-depth specialists, and formulation-support distributors. Competitive moves concentrate on backward integration into plantation networks and technology licensing for cycle-time compression.
Within the integrated supply chain tier, Dole and Fresh Del Monte exemplify plantation-to-processing control. SunOpta occupies a position emphasizing organic certification breadth across multiple tropical varieties. Van Drunen Farms anchors the private-label contract manufacturing segment for North American retail chain supply.
| Leading Market Players |
|---|
| Dole |
| Fresh Del Monte |
| SunOpta |
| Ardo NV |
| Natierra |
| Harmony House Foods |
| Brothers International Food Holdings |
| Van Drunen Farms |
| Paradise Fruits |
| Others |
Pricing and Supply Chain Analysis
Electricity costs for sublimation cycles flow through Thai central plains processing clusters into three-tier pricing structures separating organic-certified premium grades from conventional standard tiers and commodity economy lots for bulk foodservice procurement.
Pricing Analysis
Input-cost pass-through from energy-intensive sublimation operations shapes contract negotiations between Thai processors and North American snack food manufacturers. Pricing stratifies across premium, standard, and economy tiers based on organic certification depth and particle size customization. Cost compression in the economy tier is intensifying because RF-assisted technology adoption in Vietnam and the Philippines expands competitive supply. Private-label retail chains exhibit highest price sensitivity, while European confectionery houses purchasing bromelain-stable pineapple products show lowest sensitivity due to EUDR compliance requirements.
Supply Chain Analysis
Direct-to-foodservice channels handle formulation-intensive bakery demand, while wholesale distributors manage technical sales support for North American clean-label chains. Raw material availability clusters in Thailand, Vietnam, and the Philippines, with captive cold-chain infrastructure linking plantation networks to sublimation facilities. Feedstock supply draws from mango, pineapple, and dragon fruit cultivation zones exposed to monsoon-driven harvest volatility. Distribution runs through specialty ingredient distributors displacing traditional broadline brokers in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The freeze-dried tropical fruits market functions as a stable compounder anchored by irreversible clean-label reformulation mandates across North American and European bakery segments.
For Market Incumbents: Acquire RF-assisted sublimation technology assets to compress cycle times below 12 hours and defend margin position against Vietnamese mid-scale entrants. Secure backward integration into Thai central plains plantation networks to guarantee year-round feedstock consistency for FDA-audited export contracts. Prioritize USDA Organic certification depth across multiple tropical varieties to maintain shelf placement in premium retail channels.
For New Entrants and Emerging Players: Direct-to-consumer online retail subscriptions offer the most penetrable route for specialty organic brands seeking margin capture outside traditional retail slotting fee structures. Target sports nutrition powder integration as a white-space application where freeze-dried tropical fruit granules replace artificial flavor carriers. Pursue blockchain-traceability system partnerships to satisfy EUDR geolocation verification requirements for European bakery manufacturer supply.
For Investors and Strategic Acquirers: Consolidation pressure builds where smaller processors lack capital for FDA-mandated preventive controls infrastructure and qualified food safety personnel. The market exhibits long-term viability across a 5-10 year window driven by structural substitution of artificial flavoring systems in clean-label formulations. Monitor RF-assisted technology licensing deals as an inflection indicator for production economics decentralization away from Thai integrated clusters.
| Strategic Initiative | Industry Significance |
|---|---|
| RF-Assisted Sublimation Technology Licensing | Vietnamese and Philippine processors cut cycle times to compete with Thai central plains clusters. |
| Blockchain-Traceability System Implementation | European confectionery houses satisfy EUDR polygon mapping and harvest documentation obligations. |
| USDA Organic Certification Investment | Three-year orchard transition periods lock in premium pricing before conventional supply enters. |
| Direct-to-Foodservice Channel Development | Specialty distributors bypass retail brokerage to supply commercial bakeries with custom particle sizes. |
| Captive Plantation Network Integration | Thai processors secure year-round mango and pineapple feedstock for North American private-label contracts. |
Research Methodology
Bottom-up bakery and snack food application modeling reconciled against top-down Thai and Vietnamese sublimation capacity tracking forms the analytical core. Primary interviews with freeze-drying plant managers, procurement leads at North American retail chains, European confectionery formulators, and Thai FDA compliance officers combined with secondary validation from FDA FSMA guidance documents, USDA Organic certification databases, EU EUDR implementation texts, and Thai central plains agricultural trade statistics. Triangulation between demand-side consumption patterns and supply-side production asset deployment ensures cross-verified volume and value estimates.
Historical trendline analysis of freeze-dried tropical fruit trade flows and sublimation technology adoption rates established baseline growth parameters across the projection horizon. The analytical framework segments by fruit variety, application category, end-user type, and distribution channel, with additional modeling of organic certification status as a price-tier dimension. CAGRs derive from fitted trend extrapolation adjusted for RF-assisted technology penetration assumptions and EUDR documentation compliance timelines. Forecast inputs incorporate energy cost trajectories for sublimation operations and clean-label reformulation commitment durability among major retail chains.
The model assumes a particular technology adoption path; alternative pathways for radio-frequency-assisted freeze-drying would alter the outlook if cycle-time compression fails to materialize at projected rates. Forecasts reflect assumptions about Thai central plains infrastructure continuity, FDA preventive controls enforcement intensity, and European deforestation-free regulation implementation scope. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
North America Frozen Desserts Market
Processed and Frozen Foods
Icebreakers Market
Processed and Frozen Foods
Latin America Frozen Finger Chips Market
Processed and Frozen Foods
Europe Dehydrated Food Market
Processed and Frozen Foods
Frozen Mackerel Market
Processed and Frozen Foods
Global Chilled and Deli Foods Market
Processed and Frozen Foods
Freeze Dried Fruit Extract Market
Processed and Frozen Foods
Asia-Pacific Frozen Yogurt Market
Processed and Frozen Foods
Frozen Dough Market
Processed and Frozen Foods
Frozen Cheese Market
Processed and Frozen Foods
US Frozen Dessert Market
Processed and Frozen Foods
North America Dehydrated Food Market
Processed and Frozen Foods
Popsicle Market
Processed and Frozen Foods
Frozen Chicken Market
Processed and Frozen Foods
Europe Frozen Desserts Market
Processed and Frozen Foods
GCC Frozen Finger Chips Market