
 Frozen Dumplings Market | 2026-2036
Frozen Dumplings Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Dumplings Market Analysis
Aftermarket recipe licensing and co-manufacturing partnerships is rewriting how margin pools migrate from branded retail toward private-label production. CJ CheilJedang leverages its Bibigo brand strength to anchor premium positioning in North American freezer aisles. Sanquan Food dominates China's domestic quick-frozen food infrastructure through manufacturing scale and channel control. Ajinomoto competes in Southeast Asian markets with localized filling formulations that extend its MSG expertise into prepared foods.
Frozen dumplings are wheat- or rice-flour wrappers enclosing seasoned fillings, flash-frozen at minus 35 degrees Celsius to preserve cellular structure and reheating integrity. Commercial production employs tunnel freezing and modified-atmosphere packaging to prevent freezer burn and extend shelf stability. The steamed product category leads volume due to health-positioning and shorter preparation time, while fried variants command higher per-unit margins in foodservice channels. Seafood filling types represent the fastest-growing segment as coastal urban consumers seek protein variety beyond pork and chicken.
China's SAMR enforces GB standards for quick-frozen prepared foods, including microbial limits and labeling requirements that shape production investments. The FDA oversees U.S. import inspections and facility registration, while the USDA regulates meat-containing dumplings through FSIS inspection protocols. South Korea's MFDS mandates nutritional labeling and additive disclosures that influence reformulation cycles for export-oriented manufacturers. Stakeholders must monitor how evolving cold-chain energy regulations and carbon-accounting requirements reshape freezer logistics economics and facility location decisions.
Market Dynamics
Cold-chain infrastructure expansion into China's tier-two cities is redistributing frozen dumpling demand away from coastal manufacturing clusters toward inland consumption nodes. This logistics evolution compresses delivery windows and reshapes production facility siting decisions.
Growth Catalysts
- GB Standards Compliance:China's SAMR enforcement of updated microbial limits and labeling protocols is accelerating facility consolidation among mid-sized producers seeking certification economies.
- Urban Meal Routine Transformation:South Korean supermarket chains are reallocating freezer aisle space toward Asian-style frozen appetizers as single-person households displace traditional family cooking patterns.
- Tunnel Freezing Technology:Minus 35 degrees Celsius flash-freezing protocols now preserve cellular structure across extended distribution networks, enabling quality consistency in previously unreachable markets.
Market Restraints
- Wheat Flour Input Volatility:Global grain price fluctuations compress margin predictability for wrapper-dependent production lines, particularly affecting standard-tier product economics.
- Coastal Manufacturing Concentration:Over 60% of China's quick-frozen flour product capacity clusters in Shandong and Henan provinces, creating geographic vulnerability to regional logistics disruptions.
- Modified-Atmosphere Packaging Limitations:Current barrier film technologies constrain shelf-life extension beyond 12 months for seafood-filled variants, limiting export reach to ultra-long-haul destinations.
Strategic Opportunities
- Southeast Asian Penetration Gap:Vietnam and Indonesia present underdeveloped frozen appetizer infrastructure relative to per-capita protein consumption growth, creating first-mover positioning potential.
- Dual Carbon Policy Alignment:China's MEE carbon-accounting requirements for cold-chain logistics are incentivizing freezer facility relocation toward renewable energy zones with grid cost advantages.
- Direct-to-Restaurant Channel Development:Foodservice procurement bypasses traditional retail markup structures, capturing margin pools previously absorbed by supermarket intermediaries in North American urban markets.
Industry Challenges
- Refrigeration Technician Scarcity:Maintenance of minus 35 degrees Celsius tunnel freezing equipment requires specialized cryogenic system expertise that outpaces vocational training program output in emerging production regions.
- Cross-Border Certification Timelines:FDA facility registration and USDA FSIS meat-containing product inspection protocols create 18-24 month entry barriers for new Chinese exporters targeting US retail placement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Dumplings Market |
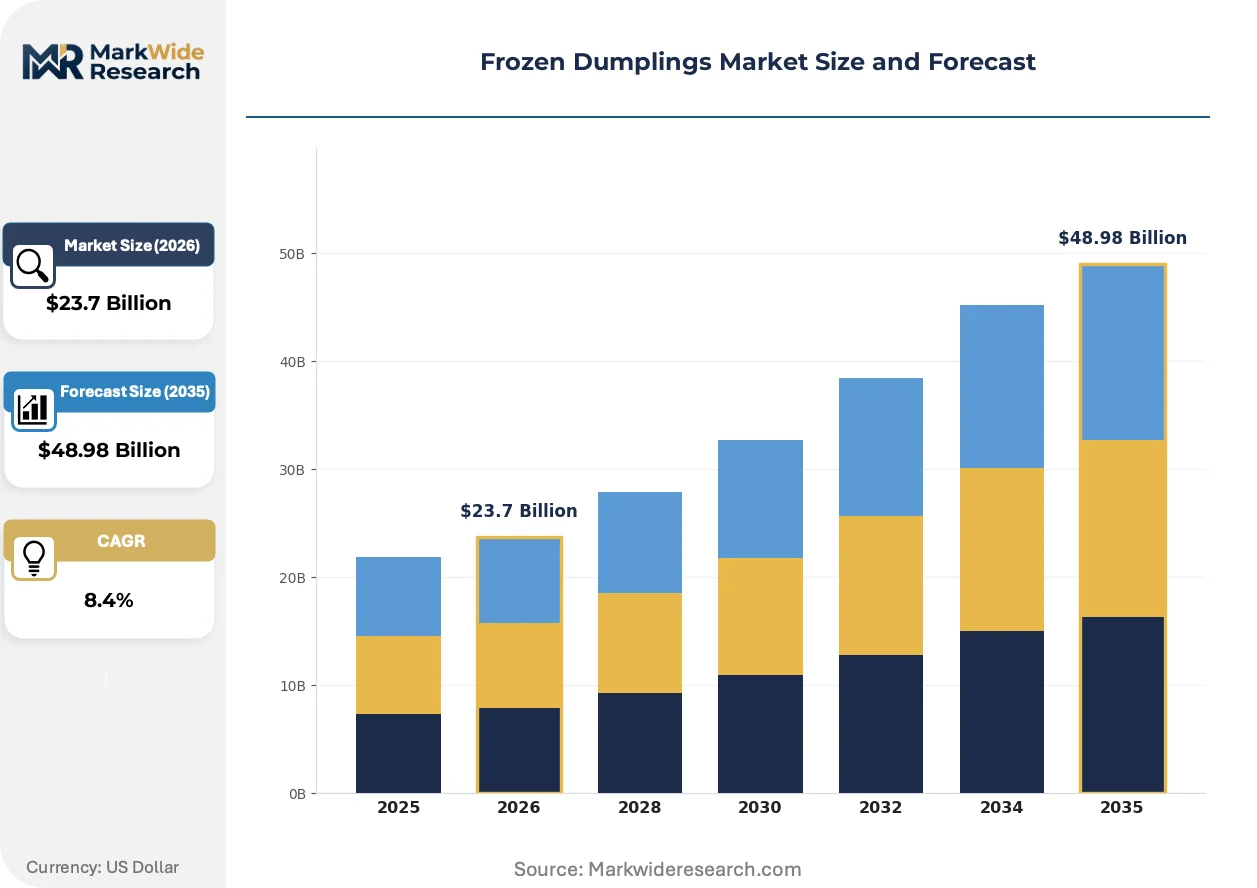
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steamed, Fried, Boiled, Baked Filling Type: Pork, Chicken, Vegetable, Seafood Packaging Type: Bag, Box, Tray, Clamshell Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Foodservice |
| Companies Covered | CJ CheilJedang, Sanquan Food, Ajinomoto, General Mills, Day-Lee Foods, Synear, Wei Chuan Foods, Hakka Pty Ltd, Bibigo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Dumplings Market Emerging Trajectories
Automation in wrapper formation and filling deposition is compressing unit labor costs while enabling portion-size customization previously uneconomical at scale. These production advances are converging with packaging material science breakthroughs and distribution model experimentation.
Individual quick-freezing (IQF) technology with nitrogen cryogenic injection is rendering obsolete batch-freezing methods that created ice crystal damage in delicate seafood fillings. Premium foodservice buyers in Japan and South Korea now specify IQF protocols as procurement prerequisites. The technology is compressing acceptable quality thresholds upward, disqualifying legacy equipment investments.
The EU's CSRD corporate sustainability reporting requirements are mandating scope-three emissions disclosure across imported prepared food supply chains. European retailers are now demanding carbon footprint documentation from Asian frozen dumpling suppliers as a contractual condition. Seafood-filled variants face the steepest compliance burden due to fishing fleet fuel intensity in upstream supply.
Meal-kit bundling is fragmenting bulk-case purchasing patterns that historically dominated frozen appetizer procurement. Younger urban consumers in China's tier-one cities now favor variety packs with four-to-six portion counts over traditional 50-unit foodservice cases. This pattern rotation is forcing production line reconfiguration toward smaller-batch changeover capability.
Frozen Dumplings Market Segmentation
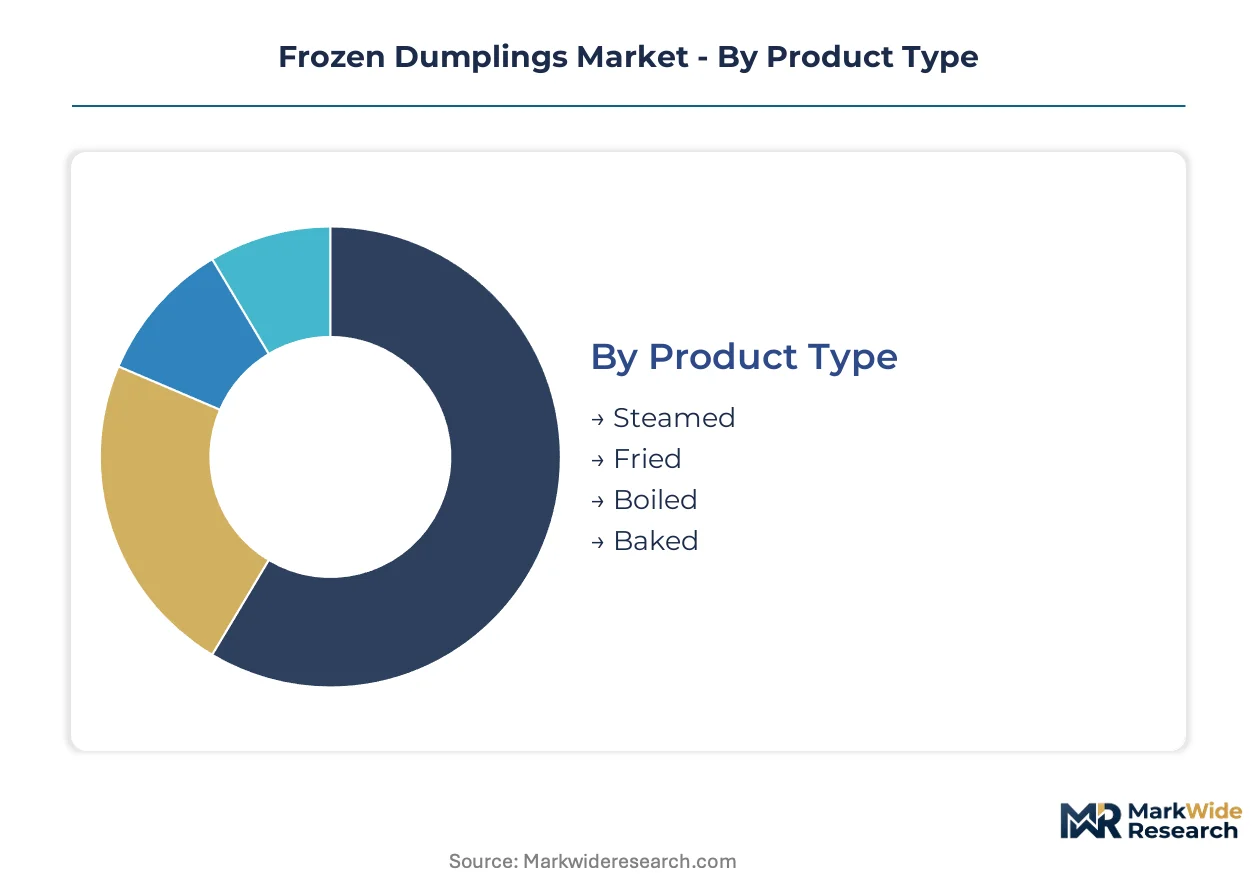
Frozen dumpling segmentation reveals how preparation method, protein source, and channel access shape margin architecture across consumer and commercial buyers. Understanding these divides exposes where technology investments and regulatory compliance burdens concentrate most heavily.
Product Type:
Mature preparation formats now compete against emerging variants as health positioning and convenience speed reshape household preferences.
- Steamed:Minus 35 degrees Celsius flash-freezing preserves wrapper elasticity and filling moisture without oil absorption. Urban China and South Korea drive volume as single-person households prioritize shorter preparation cycles and reduced fat content.
- Fried:Crisp-texture variants command premium placement in foodservice channels where oil-contact during reheating creates sensory differentiation. North American freezer aisles allocate expanded shelf space to this format as Asian-style appetizers displace traditional frozen snacks.
- Boiled:Traditional preparation format dominates China's inland tier-two cities where cold-chain penetration remains cost-sensitive.
- Baked:Emerging oven-ready format gaining traction in European markets with CSRD-aligned packaging requirements.
Steamed handles the majority of throughput; baked is the fastest mover on share.
Filling Type:
Cost tier stratification separates commodity protein inputs from premium sourcing requirements that reshape supply chain geography.
- Pork:Standard filling base subject to China's GB microbial limits and USDA FSIS inspection protocols for export-bound production. Shandong and Henan province facilities dominate capacity due to integrated hog farming and flour milling proximity.
- Seafood:Individual quick-freezing with nitrogen cryogenic injection preserves delicate cellular structure in shrimp and fish formulations. Coastal urban consumers across China, Japan, and South Korea seek protein variety beyond traditional land-animal options.
- Chicken:Mid-tier positioning benefits from lower input volatility than pork and broader religious dietary acceptance.
- Vegetable:Plant-forward variants face modified-atmosphere packaging constraints on shelf-life extension beyond twelve months.
Pork handles the majority of throughput; seafood is climbing the fastest on volume contribution.
Packaging Type:
Customer type divides between bulk procurement patterns and portion-controlled formats that alter production line economics.
- Bag:Flexible film construction dominates retail volume with cost-efficient material usage and compact freezer storage footprint. China's meal-kit bundling trend is fragmenting traditional 50-unit foodservice cases into 4-6 portion variety packs for younger urban consumers.
- Tray:Rigid presentation format supports premium positioning in Japanese and South Korean convenience store channels where visual appeal drives impulse purchase.
- Box:Cardboard outer shell enables brand storytelling and nutritional labeling compliance for EU CSRD documentation requirements.
- Clamshell:Dual-chamber designs separate sauce accompaniments from dumpling bodies in North American premium retail placement.
Bag handles the majority of throughput; tray is expanding most quickly on share.
Distribution Channel:
Geographic concentration of cold-chain infrastructure determines which channels remain accessible to producers at varying scale thresholds.
- Supermarkets:Primary volume channel where South Korean chains now reallocate expanded freezer space toward Asian-style frozen appetizers. Daily delivery frequency to tier-two Chinese cities compresses inventory holding requirements and reshapes production scheduling.
- Foodservice:Direct-to-restaurant procurement bypasses retail markup structures, capturing margin pools previously absorbed by supermarket intermediaries in North American urban markets.
- Online Retail:E-commerce penetration accelerates in China's tier-one cities where 30-minute delivery guarantees require localized micro-fulfillment centers with cryogenic storage capability.
- Convenience Stores:Grab-and-go positioning favors single-serve microwaveable formats with extended shelf stability through modified-atmosphere barrier films.
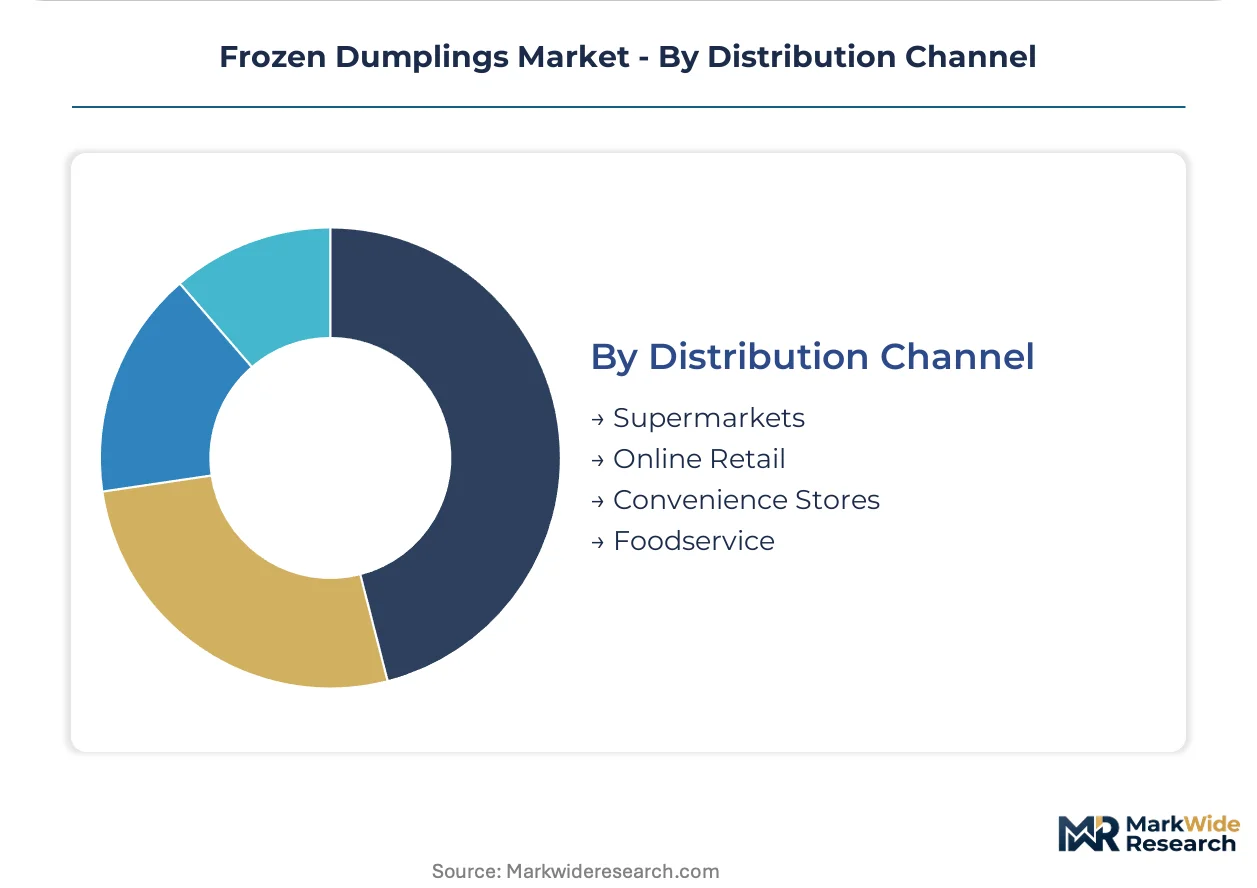
Supermarkets handle the majority of throughput; foodservice is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese buyers demonstrate the highest price elasticity, gravitating toward boiled formats in tier-two cities where cold-chain costs remain prohibitive, while Japanese and South Korean consumers absorb premium steamed and tray-packaged variants with minimal volume sensitivity.
China
Urban single-person households in Shanghai and Beijing drive steamed-format volume through 30-minute delivery guarantees from localized micro-fulfillment centers. SAMR's updated GB standards for quick-frozen flour products mandate microbial limit compliance that accelerates facility consolidation among mid-sized producers. Manufacturing gravity concentrates in Shandong and Henan provinces where integrated hog farming and flour milling proximity supports pork-filled production economics.
Japan
Premium foodservice buyers in Tokyo and Osaka specify individual quick-freezing protocols with nitrogen cryogenic injection as procurement prerequisites for delicate seafood fillings. METI's energy efficiency regulations for cold-chain logistics reshape freezer facility siting toward renewable energy zones. The Kansai region anchors demand for tray-packaged convenience store formats where visual appeal drives impulse purchase.
South Korea
Supermarket chains in Seoul reallocate expanded freezer aisle space toward Asian-style frozen appetizers as traditional family cooking patterns yield to single-person household routines. MFDS nutritional labeling and additive disclosure mandates influence reformulation cycles for export-oriented manufacturers. The Seoul Capital Area dominates consumption nodes while Busan-Ulsan handles coastal seafood supply integration.
United States
North American freezer aisles allocate expanded shelf space to fried-format Asian-style appetizers displacing traditional frozen snacks in urban markets. FDA facility registration and USDA FSIS inspection protocols create 18-24 month entry barriers for new exporters targeting retail placement. Direct-to-restaurant procurement in New York and Los Angeles captures margin pools previously absorbed by supermarket intermediaries.
Vietnam
Underdeveloped frozen appetizer infrastructure relative to per-capita protein consumption growth creates first-mover positioning potential in Hanoi and Ho Chi Minh City. The country's national food safety regulator enforces labeling requirements that shape import compliance investments. Cold-chain expansion into secondary cities redistributes demand toward inland consumption nodes with compressed delivery windows.
Frozen Dumplings Market Vendor Landscape
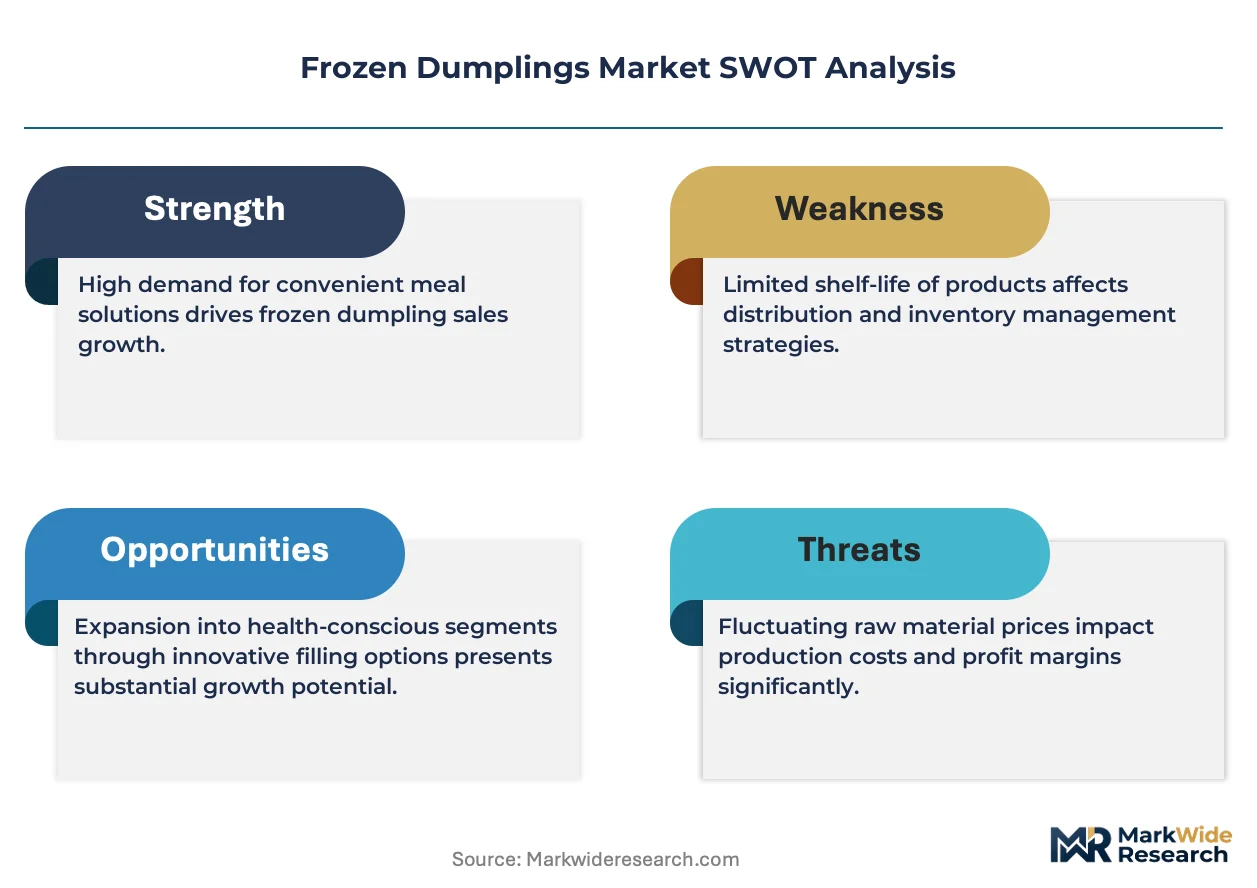
Integrated food conglomerates and specialized quick-frozen manufacturers split the market along brand strength versus manufacturing scale vectors. Tier concentration remains moderate, with top-ten players commanding significant but not dominant share. Three archetypes define competitive positioning: brand-led premium exporters, scale-driven domestic infrastructure owners, and co-manufacturing specialists serving private-label demand. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing cold-chain alliances to extend geographic reach.
Within the brand-led tier, CJ CheilJedang exemplifies premium positioning through its Bibigo brand strength in North American freezer aisles. Sanquan Food occupies a position as the archetypal scale-driven domestic infrastructure owner, controlling China's quick-frozen food manufacturing base through channel concentration. Ajinomoto represents the localized formulation specialist, extending core expertise into prepared foods across Southeast Asian markets where taste adaptation determines market access.
| Leading Market Players |
|---|
| CJ CheilJedang |
| Sanquan Food |
| Ajinomoto |
| General Mills |
| Day-Lee Foods |
| Synear |
| Wei Chuan Foods |
| Hakka Pty Ltd |
| Bibigo |
| Others |
Supply Flow & Price Mechanics
Shandong and Henan province flour milling clusters anchor wrapper cost structures, concentrating margin capture downstream with branded retail placement and foodservice direct procurement. Wheat flour input volatility transmits directly through standard-tier product economics, while premium steamed and seafood-filled variants buffer margin compression through brand premium and cryogenic technology differentiation.
Pricing Analysis
After-sales recipe licensing and co-manufacturing service contracts extend lifetime value beyond unit sales for private-label producers. Three-tier pricing structure across premium, standard, and economy levels separates IQF seafood-filled tray formats from boiled pork bag variants. Pricing pressure stems from global grain price fluctuation compressing wrapper-dependent production lines. Tier-two Chinese cities exhibit highest price sensitivity, while Japanese premium foodservice buyers absorb cryogenic protocol premiums with minimal volume response.
Supply Chain Analysis
Extended payment terms from Shandong flour mills and cold-chain logistics finance facilities from renewable energy zone operators are reshaping working capital structures. Manufacturing gravity draws from China, South Korea, and Vietnam, with seafood sourcing anchored in coastal Japan and South Korea. Raw material dependencies center on wheat flour, nitrogen cryogenic systems, and modified-atmosphere barrier films. Single-source vulnerability concentrates in tunnel freezing equipment maintenance expertise. Distribution runs through supermarket chains with daily delivery frequency to tier-two Chinese cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fresh meal-kit delivery services and ghost kitchen prepared appetizers threaten frozen dumpling incumbents by collapsing preparation convenience advantages. Substitution defense requires technology differentiation and channel control reinforcement.
For Market Incumbents: Build cryogenic IQF protocol moats through nitrogen injection equipment certification and technician training programs. Secure backward integration into coastal seafood sourcing to defend against Ajinomoto's localized formulation expansion. Reinforce supermarket freezer aisle space allocation through exclusive variety pack development for South Korean single-person households. Channel control in China's tier-two cities compresses delivery windows against emerging local brands. For New Entrants and Emerging Players: Vietnam's underdeveloped frozen appetizer infrastructure relative to protein consumption growth offers first-mover positioning potential. Target Indonesian convenience store channels with single-serve microwaveable formats using modified-atmosphere barrier films. Penetrate North American foodservice direct-to-restaurant procurement to bypass retail markup structures. Localized filling adaptation determines Southeast Asian market access. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cryogenic IQF production lines as nitrogen injection equipment and technician scarcity reshape facility economics. Five-to-ten year viability favors co-manufacturing specialists with private-label contract depth over pure-brand plays exposed to retail space competition. Watch carbon-accounting compliance cost pass-through as the signal indicating which facilities secure European retail placement.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic IQF Technology Licensing | Nitrogen injection protocol certification opens Japanese and South Korean premium foodservice procurement. |
| Coastal Seafood Backward Integration | Captive shrimp and fish supply secures delicate filling quality for export-bound production. |
| Renewable Energy Zone Facility Relocation | China's MEE carbon-accounting requirements incentivize freezer relocation toward grid cost advantages. |
| Direct-to-Restaurant Channel Development | Foodservice procurement bypasses supermarket intermediaries in North American urban markets. |
| Meal-Kit Variety Pack Reconfiguration | Smaller-batch changeover capability addresses China's tier-one city fragmentation toward 4-6 portion counts. |
Methodological Framework
Desk research of customs trade data, cold-chain logistics operator filings, and national food safety regulator protocols preceded structured interviews with quick-frozen food plant managers, supermarket category buyers, and foodservice procurement directors. Primary fieldwork with CJ CheilJedang and Sanquan Food channel partners validated production capacity claims. Secondary triangulation drew from SAMR GB standard documentation, MFDS labeling requirement filings, and EU CSRD scope-three disclosure guidance. Bottom-up facility capacity aggregation and top-down retail audit data were reconciled across the analysis.
Assumptions held cold-chain infrastructure expansion timelines and carbon-accounting enforcement intensity within observed regulatory patterns across the projection horizon. Segmentation modeling incorporated preparation method, protein source, packaging format, and distribution channel dimensions. CAGRs derived from volume trajectory analysis against population urbanization and single-person household formation rates. Wheat flour price volatility bands and seafood sourcing cost curves informed sensitivity testing.
The forecast holds incumbent behavior within observed patterns; aggressive facility consolidation by mid-sized Chinese producers seeking GB certification economies would shift outcomes. Macroeconomic grain price spikes, accelerated SAMR enforcement, or breakthrough alternative protein filling technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Indonesia Frozen Food Market
Processed and Frozen Foods
Frozen Mackerel Market
Processed and Frozen Foods
Frozen Ready Meals Market
Processed and Frozen Foods
Chilled Meal Kits Market
Processed and Frozen Foods
Frozen Fruit Bars Market
Processed and Frozen Foods
Scandinavia Frozen Food Market
Processed and Frozen Foods
Frozen Snacks Market
Processed and Frozen Foods
North America Frozen Food Market
Processed and Frozen Foods
Europe Frozen Finger Chips Market
Processed and Frozen Foods
Low-Fat Cool Whip Market
Processed and Frozen Foods
North America Freeze Dried Products Market
Processed and Frozen Foods
Frozen Dough Market
Processed and Frozen Foods
Frozen Processed Food Market
Processed and Frozen Foods
Frozen Yogurt Market
Processed and Frozen Foods
Frozen Soup Market
Processed and Frozen Foods
North America French Fries Market