
 North America Frozen Finger Chips Market | 2026-2036
North America Frozen Finger Chips Market Size, Share, and Industry Trends Forecast 2026-2036
North America Frozen Finger Chips Market Intelligence
A capital-intensity divergence between integrated processors and contract-reliant competitors is rotating competitive advantage toward firms with captive potato supply and in-house freezing infrastructure. McCain Foods Limited leverages its Manitoba-based vertical network to secure year-round raw material flow. Lamb Weston Holdings Inc sustains its position through Idaho and Washington processing scale that anchors foodservice contracts.
Frozen finger chips are par-fried potato strips, typically cut to 9.5–12.7 mm thickness, blast-frozen at minus 18 degrees Celsius, and designed for finish-frying or oven baking without thawing. The product serves commercial kitchens and retail consumers seeking consistent texture, extended shelf life, and minimal preparation labor. Regular product type occupies the volume core, yet sweet potato variants are capturing margin pools as health-positioned menus expand. Foodservice distribution channel dominates throughput, while online retail is growing fastest as direct-to-consumer frozen delivery infrastructure matures.
The U.S. FDA and USDA-FSIS jointly govern frozen potato safety, labeling, and nutritional disclosure, with sodium reduction mandates reshaping seasoning formulations across the category. Health Canada and the Canadian Food Inspection Agency enforce parallel standards that govern cross-border product movement and ingredient acceptability. Stakeholders must monitor evolving front-of-package labeling rules and potato sustainability certification requirements as procurement criteria tighten across major foodservice accounts.
Market Dynamics
Labor cost inflation across U.S. quick-service restaurants is accelerating frozen finger chip procurement as operators seek to eliminate on-site potato prep and reduce kitchen headcount.
Growth Catalysts
- USDA-FSIS safety modernization:Updated pathogen reduction standards are validating blast-freezing protocols, reinforcing foodservice confidence in frozen potato safety compared to fresh alternatives.
- Quick-service kitchen automation:Robotic fry stations and automated dispensing systems require consistent product dimensions that only frozen manufacturing lines deliver.
- Southeast processing corridor:Concentrated freezing capacity in Georgia and the Carolinas is shortening distribution lead times to dense QSR populations across Florida and Texas.
Market Restraints
- Input cost volatility:Russet potato futures fluctuate with Idaho and Washington weather patterns, compressing margins for processors without forward-contracted acreage.
- Supply concentration risk:Two integrated processors control over sixty percent of North American freezing capacity, creating vulnerability to single-site operational disruptions.
- Refrigerated logistics constraints:Reefer truck availability and diesel price spikes constrain just-in-time delivery reliability to remote foodservice accounts.
Strategic Opportunities
- Canadian retail penetration:Frozen finger chip household penetration in Ontario and Quebec trails U.S. levels by fifteen points, offering volume expansion for brands with bilingual packaging capabilities.
- Sweet potato premium tier:Orange-flesh variants command price multiples in health-positioned fast-casual chains seeking menu differentiation.
- Direct-to-consumer fulfillment:Temperature-controlled last-mile infrastructure from providers like Cold Chain Technologies is enabling subscription frozen potato delivery to suburban households.
Industry Challenges
- Refrigeration technician scarcity:Industrial ammonia system specialists are aging out of the workforce faster than technical colleges can replenish certified talent pools.
- Reformulation timeline compression:FDA sodium reduction mandates require twelve-to-eighteen-month seasoning redevelopment cycles that conflict with annual menu planning rhythms at major chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Frozen Finger Chips Market |
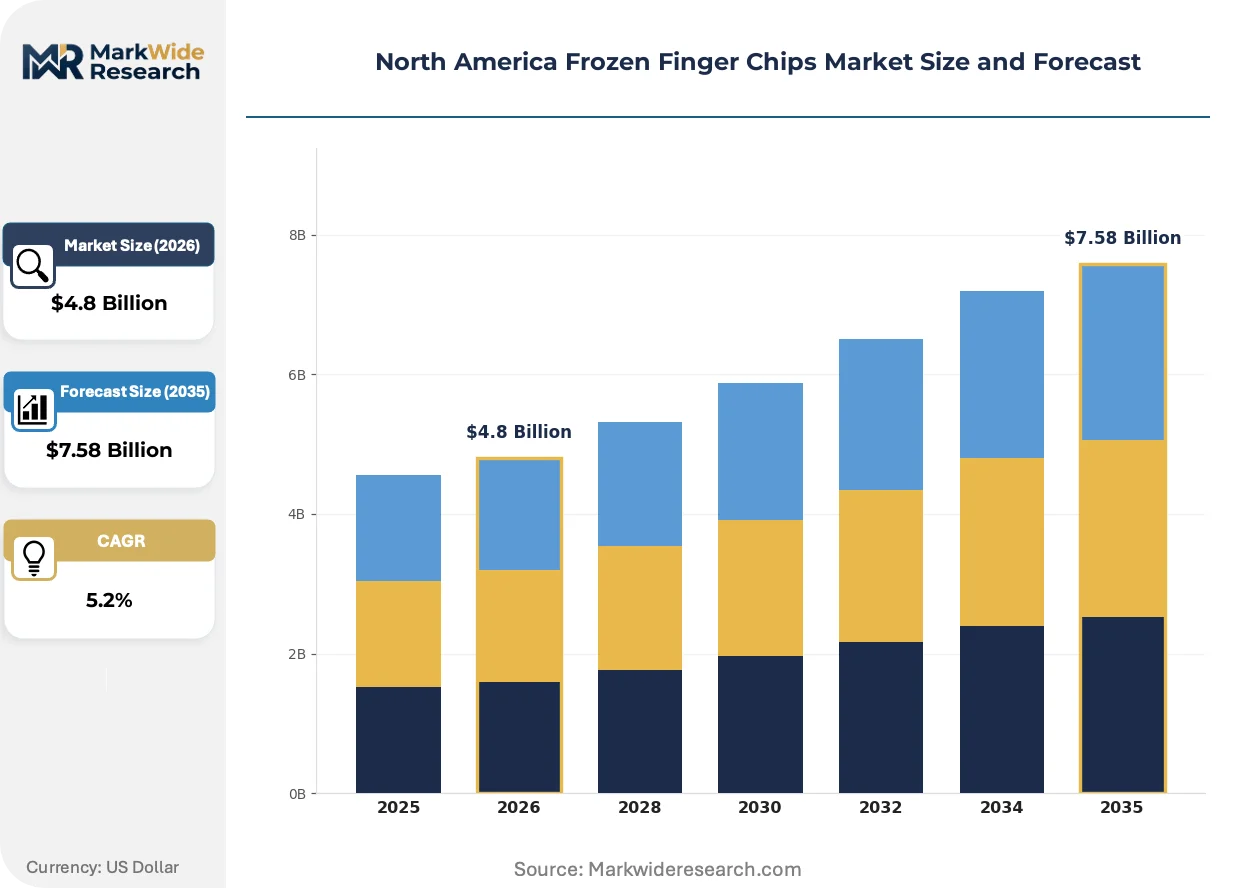
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Sweet Potato, Spicy, Garlic Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Foodservice Ingredient Type: Organic, Non-GMO, Gluten-Free, Conventional End User: Households, Restaurants, Cafeterias, Catering Services |
| Companies Covered | J.R. Simplot Company, McCain Foods Limited, Lamb Weston Holdings Inc, The Kraft Heinz Co, Aviko B.V., Agristo NV, Farm Frites International B.V., Bart’s Potato Company, Ore-Ida, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Frozen Finger Chips Market Strategic Shifts & Innovations
Processing technology and regulatory disclosure requirements are converging to reshape how frozen finger chips are manufactured, labeled, and procured across North American supply chains.
Air fryer-compatible par-fry formulations are supplanting traditional oil-blanching methods in new product development. Quick-service chains with dedicated air fryer equipment are specifying lower-oil pickup specifications to meet consumer health claims. This shift is compressing demand for conventional deep-fry-only product lines and rewarding processors with flexible oil-management systems.
The U.S. FDA's updated Nutrition Facts panel requirements are mandating added-sugar disclosure and revised serving-size definitions for frozen potato products. Processors must reformulate seasoned coatings and retest nutritional databases, adding six-to-nine months to product launch timelines. Foodservice accounts with tight menu-refresh cycles are prioritizing suppliers with in-house analytical laboratories to accelerate compliance documentation.
Consolidated procurement through group purchasing organizations is displacing direct supplier negotiations at mid-sized restaurant chains. These buying collectives aggregate volume across hundreds of independent operators to extract pricing concessions and standardized product specifications. The phenomenon is most visible in the U.S. Midwest, where regional GPOs like Dining Alliance have captured significant frozen potato contract flow from distributor house brands.
North America Frozen Finger Chips Market Segmentation
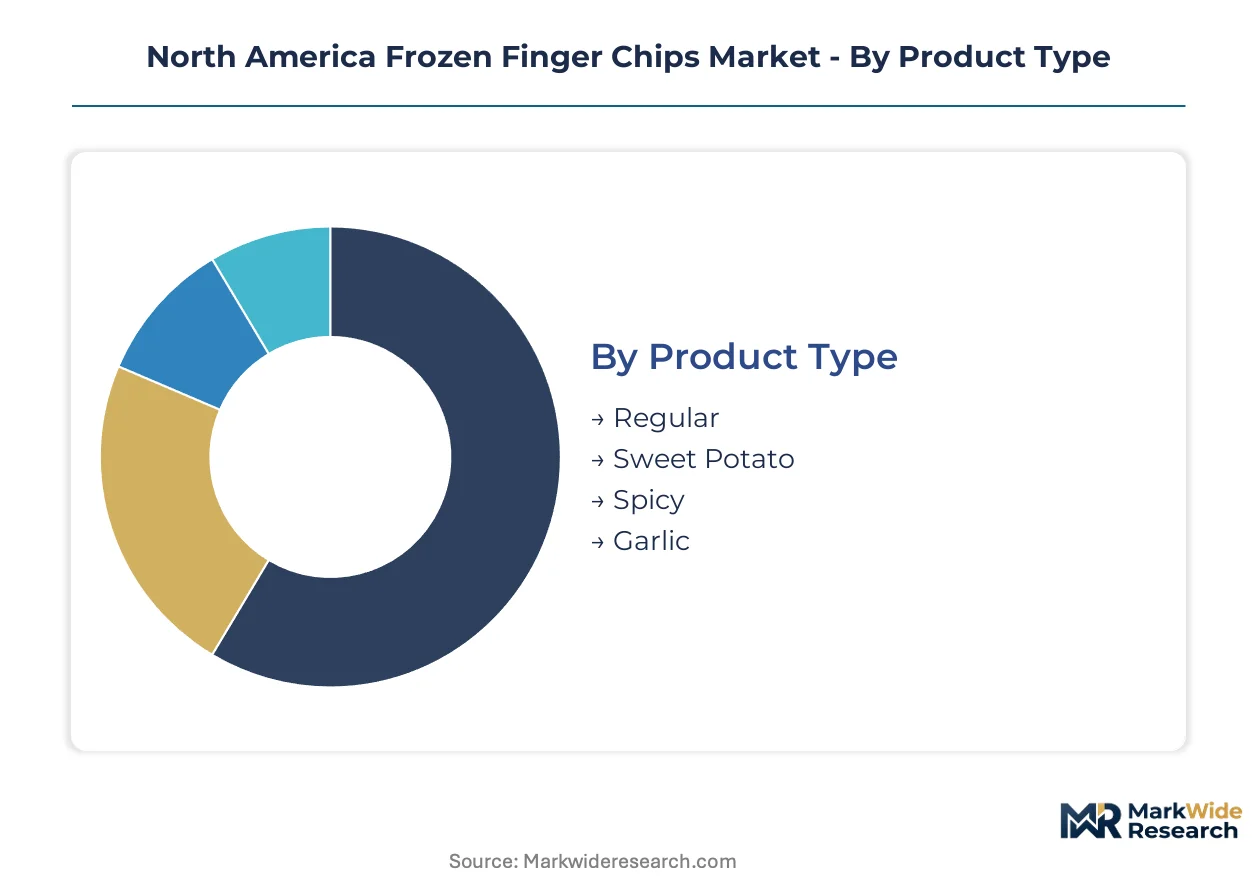
Frozen finger chip segmentation reveals distinct margin architectures across product formulation, channel infrastructure, and end-use application. Understanding these stratifications enables targeted resource allocation for processors navigating divergent growth velocities and regulatory exposure.
Product Type:
Margin pools concentrate in differentiated formulations that command health-positioning premiums and menu differentiation rents.
- Regular:Par-fried Russet strips cut to 9.5–12.7 mm thickness form the volume foundation of QSR procurement contracts. Southeast U.S. processing corridors anchor supply for Florida and Texas quick-service density, though commodity pricing pressure limits margin expansion.
- Sweet Potato:Orange-flesh variants with lower glycemic positioning capture expanding placement in fast-casual health menus. Procurement from Louisiana and North Carolina growing regions supports year-round raw material flow for processors with captive acreage.
- Spicy:Seasoned coatings with cayenne and paprika profiles target younger demographics in convenience retail.
- Garlic:Herb-infused formulations serve Mediterranean-themed restaurant chains seeking menu signature elements.
The dominant share belongs to Regular, while Sweet Potato is closing the gap fastest.
Distribution Channel:
Channel selection determines working capital intensity and temperature-control infrastructure requirements across the value chain.
- Foodservice:Direct procurement by quick-service chains and institutional buyers accounts for throughput concentration. Automated fry station compatibility and consistent dimensional specifications drive supplier stickiness in Georgia and Carolinas distribution zones.
- Supermarkets:Retail freezer space allocation in U.S. Southeast and Ontario provinces supports household penetration. Private-label competition from distributor house brands compresses branded pricing power in Midwest GPO territories.
- Online Retail:Temperature-controlled last-mile infrastructure enables suburban subscription delivery models. Cold Chain Technologies and similar providers are building direct-to-consumer frozen potato fulfillment networks.
- Convenience Stores:Grab-and-go hot case programs in Texas and Florida fuel impulse purchase occasions for smaller pack formats.
Foodservice holds the volume anchor, yet Online Retail is expanding most quickly as fulfillment infrastructure matures.
Ingredient Type:
Certification tiering creates price stratification that mirrors input sourcing complexity and audit trail documentation costs.
- Conventional:Standard Russet and processing potato varieties without certification overlays dominate procurement economics. Idaho and Washington growing regions supply the bulk of raw material for blast-freezing operations.
- Non-GMO:Identity-preserved supply chains with segregation protocols command modest premiums in health-positioned retail. FDA labeling requirements for bioengineered food disclosure are reshaping verification documentation.
- Organic:Certified acreage constraints in suitable potato-growing climates limit scalable supply. Health Canada and CFIA parallel standards govern cross-border organic product movement.
- Gluten-Free:Dedicated processing lines eliminate cross-contamination risk for celiac-sensitive consumer segments. Seasoning reformulation to remove wheat-based coatings adds six-to-nine months to product development cycles.
Conventional maintains cost leadership, though Non-GMO is gaining share fastest as labeling transparency pressures intensify.
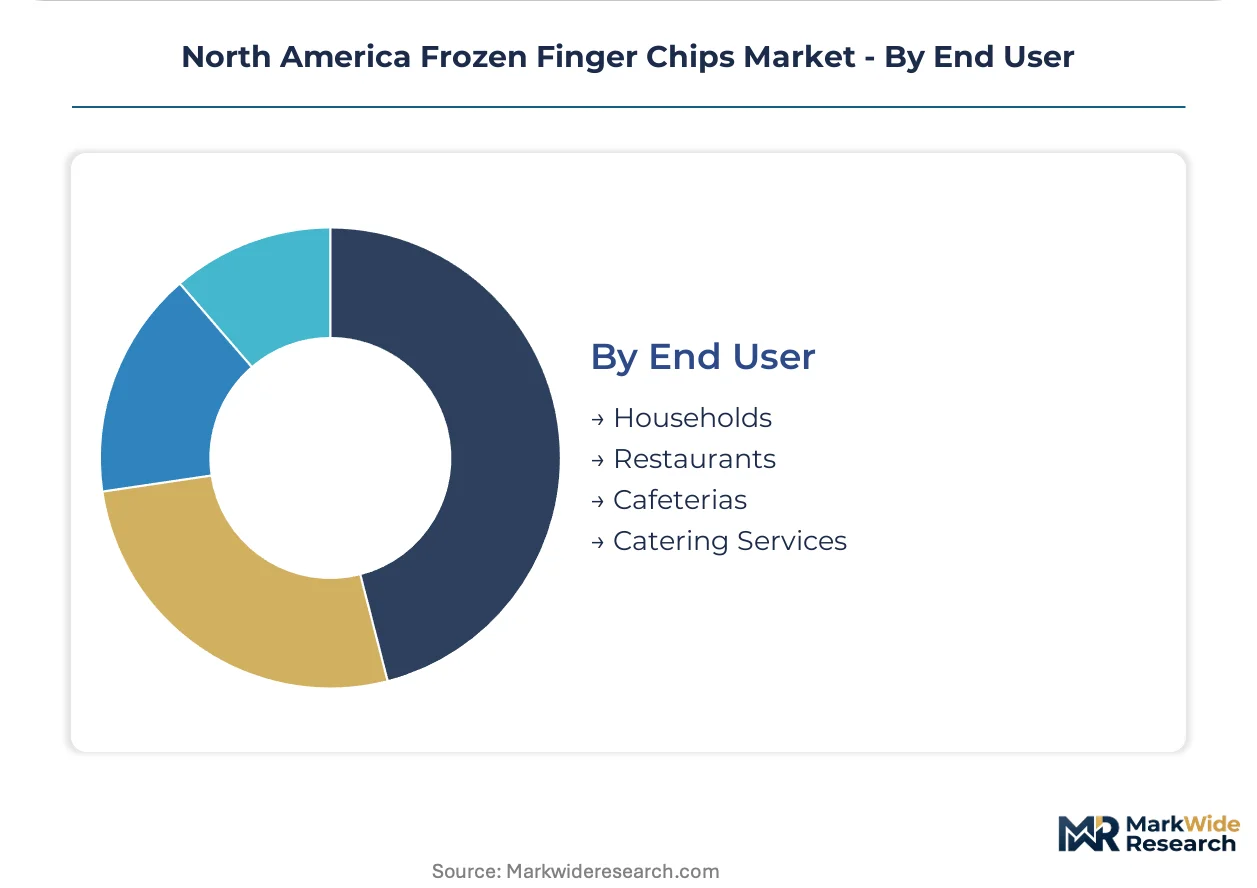
End User:
End-use concentration shapes product specification requirements and order frequency patterns across customer types.
- Restaurants:Quick-service chains with robotic fry stations demand dimensional consistency that only frozen manufacturing delivers. Labor cost inflation across U.S. QSRs is accelerating procurement to eliminate on-site potato prep.
- Households:Air fryer penetration in suburban U.S. markets is shifting preference toward lower-oil pickup formulations. Canadian household penetration in Ontario and Quebec trails U.S. benchmarks.
- Cafeterias:K-12 and university institutional buyers prioritize USDA-FSIS pathogen reduction compliance and extended shelf-life logistics.
- Catering Services:Event-based demand requires flexible pack sizes and rapid thaw-to-serve turnaround capabilities.
Restaurants command the specification-setting role, while Households are climbing the fastest as air fryer adoption reshapes retail demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian retail penetration trails U.S. benchmarks by fifteen percentage points, creating a pricing-power asymmetry that favors established brands with bilingual packaging capabilities. Mexican quick-service expansion is accelerating frozen potato procurement as labor costs climb across central Mexico.
United States
Quick-service kitchen automation and robotic fry stations demand dimensional consistency that frozen manufacturing delivers. The FDA's updated Nutrition Facts labeling requirements pressure reformulation toward reduced sodium and cleaner ingredient decks. Southeast processing corridors in Georgia and the Carolinas anchor supply for Florida and Texas QSR density.
Canada
Household frozen finger chip penetration in Ontario and Quebec lags U.S. levels, offering volume expansion for processors with French-English packaging. Health Canada and the Canadian Food Inspection Agency enforce parallel standards governing cross-border product movement and ingredient acceptability. Prairie potato growing regions in Manitoba and Alberta support integrated processors with captive acreage.
Mexico
Quick-service chain expansion across Mexico City and Guadalajara metro areas accelerates frozen potato procurement to eliminate on-site prep. The country's national food safety regulator mandates pathogen reduction standards that validate blast-freezing protocols. Central Mexico distribution zones concentrate cold chain infrastructure to serve emerging foodservice accounts.
North America Frozen Finger Chips Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the North American frozen finger chips market. Two integrated processors control over sixty percent of regional freezing capacity, creating a consolidated structure with vulnerability to single-site disruptions. The competitive terrain separates into three archetypes: integrated processors with captive potato supply, contract-reliant competitors dependent on spot markets, and specialty processors targeting premium health-positioned variants. Dominant competitive moves include backward integration into potato acreage and strategic partnerships with quick-service chains for automated fry station compatibility.
Within the integrated processor tier, McCain Foods Limited and Lamb Weston Holdings Inc exemplify archetypes with captive supply networks and in-house freezing infrastructure. McCain leverages its Manitoba-based vertical network to secure year-round raw material flow, while Lamb Weston sustains position through Idaho and Washington processing scale that anchors foodservice contracts.
| Leading Market Players |
|---|
| J.R. Simplot Company |
| McCain Foods Limited |
| Lamb Weston Holdings Inc |
| The Kraft Heinz Co |
| Aviko B.V. |
| Agristo NV |
| Farm Frites International B.V. |
| Bart's Potato Company |
| Ore-Ida |
| Others |
Cost & Logistics Intelligence
Blast-freezing capacity utilization above eighty percent in Idaho and Washington processing corridors anchors price floors across the North American frozen finger chips market. McCain Foods and Lamb Weston wield procurement-scale leverage that contract-reliant competitors cannot match, compressing margin recovery for spot-market-dependent processors during Russet potato futures volatility.
Pricing Analysis
The customization-premium spread between configured-to-order air fryer-compatible formulations and standard par-fried strips runs wide. Three-tier pricing structure across premium sweet potato variants, standard Russet strips, and economy private-label tiers dominates procurement economics. Price differentiation hinges on certification grade (USDA-FSIS pathogen reduction compliance) and volume scale (foodservice contract minimums). Pricing pressure stems from group purchasing organization consolidation in the U.S. Midwest. Quick-service chains with robotic fry stations show lowest price sensitivity; independent operators in remote distribution zones exhibit highest.
Supply Chain Analysis
Inventory lead times stretch longest for organic-certified product lines with identity-preserved acreage constraints. Geographic supply concentrates in the United States (Idaho, Washington, Georgia), Canada (Manitoba, Alberta), and Mexico (central distribution zones). Raw material flows draw from Russet potato futures markets, Louisiana sweet potato growing regions, and North Carolina orange-flesh variants. Single-source vulnerability to Idaho and Washington weather patterns threatens margin stability. Distribution runs through temperature-controlled foodservice channels anchored by Southeast processing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America frozen finger chips market rewards processors who attach temperature-controlled logistics services to core product contracts, as direct-to-consumer subscription fulfillment expands faster than conventional foodservice volume.
For Market Incumbents: Shield market position by deepening backward integration into captive potato acreage in Manitoba and Alberta to neutralize input cost volatility. Prioritize in-house analytical laboratory investment to compress FDA sodium reduction compliance timelines for major chain accounts. For New Entrants and Emerging Players: USDA-FSIS certification fast-track programs offer entry wedge into underserved Canadian retail channels in Ontario and Quebec. Target bilingual-packaged sweet potato variants for health-positioned fast-casual chains. Pursue direct-to-consumer fulfillment partnerships with Cold Chain Technologies to bypass entrenched foodservice distributor gatekeepers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among processors with multi-year quick-service chain contracts and integrated freezing infrastructure. Long-term viability favors acquisition targets with captive acreage and robotic fry station compatibility certification. Watch air fryer household penetration rates as demand inflection signal for lower-oil pickup formulation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Potato Acreage | McCain's Manitoba vertical network secures year-round raw material flow against weather-driven futures volatility. |
| Air Fryer-Compatible Formulation Launch | Lamb Weston's lower-oil pickup specifications capture placement in chains with dedicated air fryer equipment. |
| Direct-to-Consumer Fulfillment Partnership | Cold Chain Technologies infrastructure enables suburban subscription delivery bypassing traditional distributor channels. |
| Sodium Reduction Reformulation Program | In-house analytical laboratories accelerate FDA Nutrition Facts compliance documentation for menu-refresh cycles. |
| Canadian Retail Channel Expansion | Bilingual packaging capabilities unlock fifteen-point household penetration gap in Ontario and Quebec markets. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA labeling guidance documents, USDA-FSIS pathogen reduction standards, and quick-service chain procurement contracts. Interviews with foodservice procurement directors, frozen potato plant managers, refrigerated logistics operators, and retail category buyers informed demand-side validation. Secondary sources include customs trade data, Nielsen retail audit figures, and SEC processor filings. Bottom-up volume triangulation against top-down macroeconomic drivers anchored projection integrity.
Segmentation dimensions modeled span product type (regular, sweet potato, seasoned variants), distribution channel (foodservice, supermarket, online retail, convenience), ingredient certification tier (conventional, non-GMO, organic, gluten-free), and end-user application (restaurants, households, cafeterias, catering). CAGRs derive from trend extrapolation moderated by regulatory timeline constraints and technology adoption curves across the projection horizon. Forecast inputs incorporate air fryer household penetration trajectories and labor cost inflation assumptions for quick-service kitchen automation.
Underlying assumptions cover FDA sodium reduction mandate implementation pace and diesel price stability for refrigerated trucking, with deviation risk concentrated in Russet potato futures volatility and reefer truck availability constraints. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
French Fries Market
Processed and Frozen Foods
Turkey Cold Storage Market
Processed and Frozen Foods
Frozen Food and Snacks Market
Processed and Frozen Foods
Frozen Meat and Fish Market
Processed and Frozen Foods
Vegan Frozen Food Market
Processed and Frozen Foods
Europe Freeze-Dried Products Market
Processed and Frozen Foods
Frozen Mushroom Market
Processed and Frozen Foods
Frozen Dough Market
Processed and Frozen Foods
Cold Cuts Market
Processed and Frozen Foods
Kimchi Market
Processed and Frozen Foods
Global Frozen Fish and Seafood Market
Processed and Frozen Foods
Refrigerated Liquid Eggs Market
Processed and Frozen Foods
United States Frozen Pizza Market
Processed and Frozen Foods
Middle East and Africa Freeze-Dried Product Market
Processed and Frozen Foods
Low-Fat Low-Cholesterol Foods Market
Processed and Frozen Foods
US Frozen Food Market