
 Asia Pacific Frozen Desserts Market | 2026-2036
Asia Pacific Frozen Desserts Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Frozen Desserts Market Outlook
Foodservice channel demand is shifting toward premium frozen yogurt and gelato formats as quick-service chains and café operators across Southeast Asia broaden dessert portfolios. Unilever sustains manufacturing scale across multiple production hubs in the region, while Yili Group anchors its position through dairy backward integration and captive milk sourcing. Meiji Holdings Co Ltd differentiates via specialized probiotic frozen yogurt lines tailored to Japanese and export palates.
Asia Pacific frozen desserts comprise dairy-based and water-based formulations frozen below conventional refrigeration temperatures, typically incorporating milk solids, sweeteners, stabilizers, and aeration agents to achieve overrun targets between twenty and one hundred percent depending on category. Their primary commercial purpose centers on delivering portion-controlled indulgence across retail and away-from-home channels. Ice cream occupies the dominant margin pool due to established production economics and brand equity, though frozen yogurt captures faster velocity among health-positioned consumers. Distribution through foodservice channels commands premium pricing relative to supermarket tubs, while matcha and regional fruit flavors outperform legacy vanilla in Japan and South Korea.
FSSAI in India enforces microbiological standards and labeling requirements that constrain import pathways and shape local formulation choices, while China's SAMR and GB standards govern additive thresholds and nutritional claims across Mengniu and Yili supply chains. Japan's MHLW and Food Sanitation Act set residual agricultural chemical limits that dictate ingredient sourcing protocols for Meiji and other exporters. Stakeholders must monitor evolving cold chain regulations and carbon accounting rules as these frameworks increasingly determine market access and cost structures.
Market Dynamics
China's dual carbon goals and evolving GB food safety standards are pressuring frozen dessert manufacturers to reformulate recipes, adopt cleaner label architectures, and restructure energy-intensive production processes across the region.
Growth Catalysts
- Urban cold chain expansion:Metro corridors in India and Southeast Asia are receiving refrigerated logistics investment that enables premium frozen yogurt penetration previously blocked by temperature integrity gaps.
- FSSAI microbiological standards:India's enforcement of labeling and import pathway constraints is accelerating domestic formulation capabilities and localized supply chain development.
- Foodservice menu broadening:Quick-service chains and café operators across Southeast Asia are expanding dessert portfolios to capture younger consumer segments with gelato and frozen yogurt formats.
Market Restraints
- Dairy input cost volatility:Fluctuations in milk powder and butterfat prices constrain margin stability for manufacturers dependent on imported dairy solids.
- SAMR additive thresholds:China's tightening GB standards on stabilizers and aeration agents create reformulation costs and limit ingredient sourcing flexibility.
- Substitution by fresh alternatives:Bubble tea and chilled dairy beverages compete for the same indulgence occasions and younger consumer budgets.
Strategic Opportunities
- Probiotic functional positioning:Specialized frozen yogurt lines with live culture claims address health-positioned consumers in Japan and export markets.
- Regional fruit flavor localization:Matcha, yuzu, and tropical fruit formulations outperform legacy vanilla in Japan, South Korea, and Southeast Asian markets.
- Carbon accounting compliance:Early alignment with China's dual carbon goals and emerging MEE reporting requirements creates preferential access to state-backed distribution channels.
Industry Challenges
- Cold chain technician scarcity:Qualified personnel for maintaining sub-zero distribution networks remain concentrated in tier-one cities, limiting rural market expansion.
- Reformulation timeline compression:Accelerating GB standard updates force simultaneous recipe redevelopment and stability testing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Frozen Desserts Market |
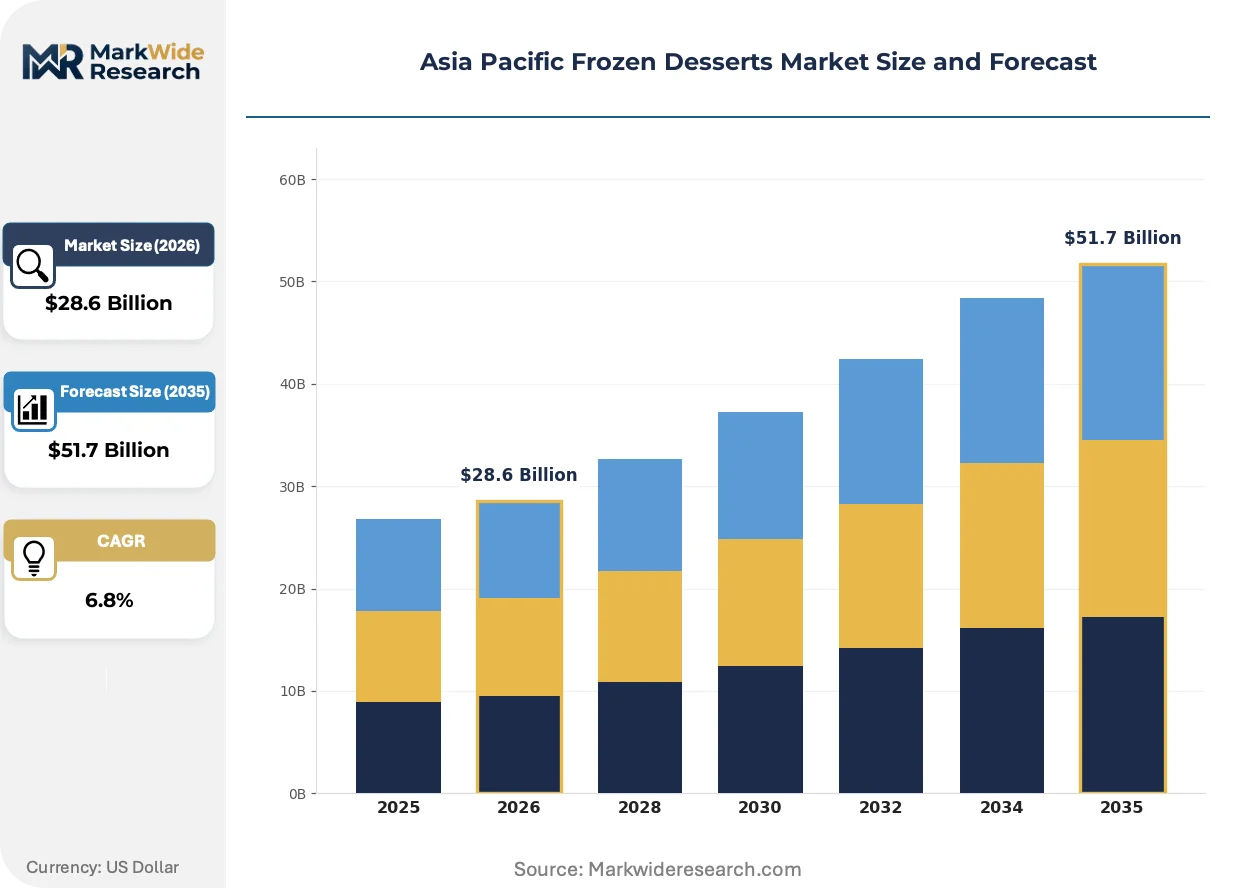
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ice Cream, Sorbet, Frozen Yogurt, Gelato Flavor: Chocolate, Vanilla, Strawberry, Matcha Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Foodservice Packaging Type: Cup, Tub, Bar, Cone |
| Companies Covered | Mother Dairy, Meiji Holdings Co Ltd, Nestle SA, Baskin-Robbins, Danone Groupe SA, Unilever, China Mengniu Dairy, Ben & Jerry's, Yili Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Frozen Desserts Market Strategic Shifts
Automation and regulatory compliance technologies are restructuring how frozen desserts are formulated, monitored, and distributed across Asia Pacific manufacturing networks.
Continuous freezing technology with real-time overrun control is automating consistency management in high-volume production lines. Mid-scale manufacturers in Thailand and Vietnam are adopting these systems to reduce manual intervention and batch variation. This automation is compressing the quality gap between regional producers and established multinational operations.
SAMR's evolving GB standards on nutritional claims and additive disclosure are forcing label redesign and supply chain documentation investments. Manufacturers must now maintain batch-level traceability for stabilizers and sweeteners to satisfy audit requirements. Dairy-based premium segments face the steepest compliance costs as they balance clean-label positioning with functional performance.
Foodservice procurement is consolidating around preferred supplier agreements with integrated flavor development capabilities. Chains are bypassing traditional distributor layers to contract directly with manufacturers offering customized regional fruit profiles. This disintermediation is most visible in South Korea and urban China, where café operators demand exclusive flavor collaborations and shorter innovation cycles.
Asia Pacific Frozen Desserts Market Segmentation
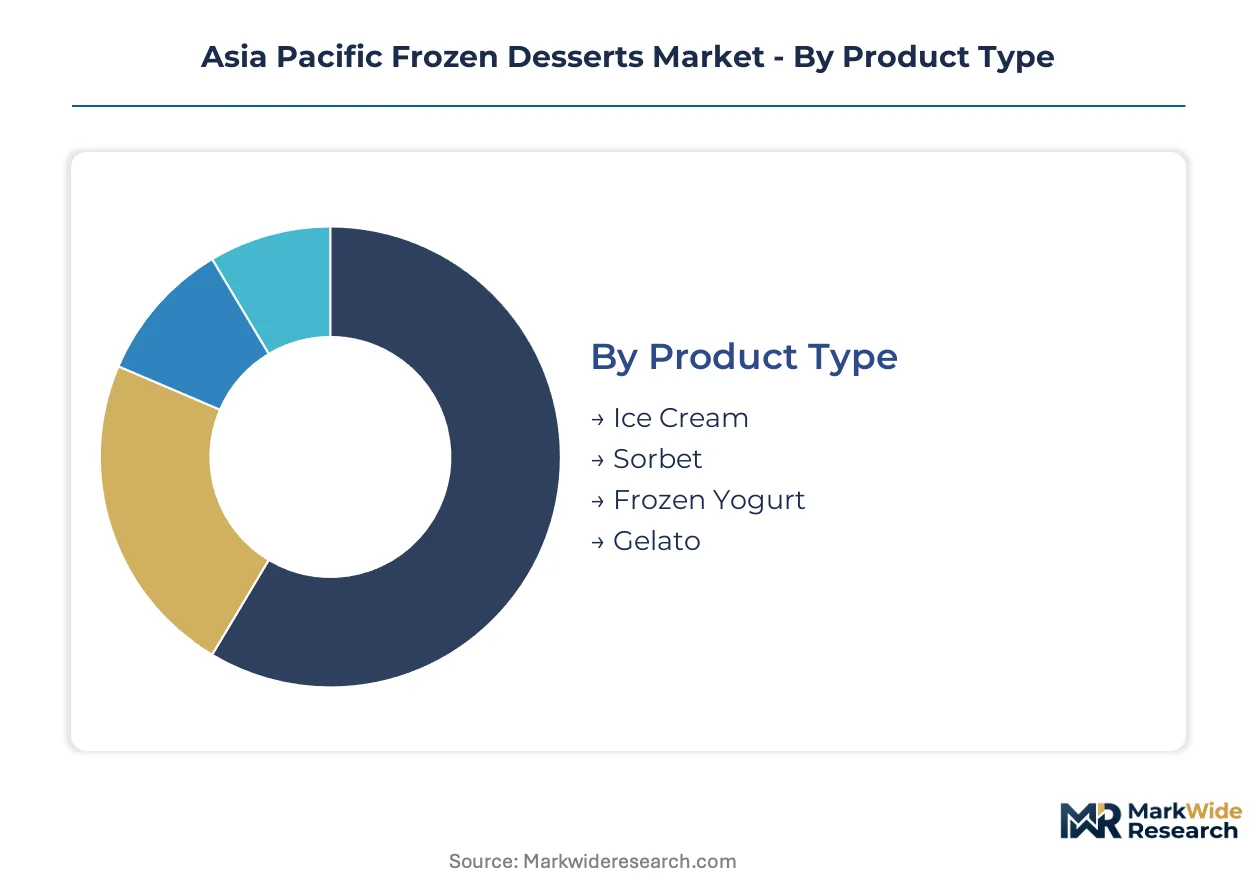
Segmentation in Asia Pacific frozen desserts reveals how purchase decisions split between indulgence occasions and health-positioned consumption. Manufacturers configure formulation, packaging, and channel strategies around these divides to capture margin pools that vary substantially across product formats and distribution pathways.
Product Type:
Purchase decisions in this category hinge on the tension between traditional indulgence and functional health claims, with overrun targets and fat content specifications driving production economics.
- Ice Cream:Dairy-based formulations with overrun between 50-100% dominate manufacturing scale due to established production economics and brand equity concentration. Demand concentrates in China's tier-one cities and India's metropolitan corridors, where cold chain infrastructure enables premium positioning and impulse purchase occasions.
- Frozen Yogurt:Live culture formulations with probiotic positioning capture health-conscious consumers through lower fat content and tart flavor profiles. Penetration accelerates in Japan and South Korea via specialized lines from dairy-integrated manufacturers, though dairy input cost volatility constrains margin stability.
- Sorbet:Water-based formulations with zero dairy solids serve lactose-intolerant segments and clean-label positioning through fruit puree bases.
- Gelato:Lower overrun targets (20-35%) and higher milk solids content deliver denser texture for premium foodservice occasions in Southeast Asian café channels.
Ice cream leads on scale; frozen yogurt leads on momentum.
Flavor:
Regional palate differentiation creates fragmentation that favors localized formulation capabilities over standardized global portfolios.
- Matcha:Finely ground green tea powder formulations command premium pricing in Japan and export markets through cultural authenticity and antioxidant positioning. Demand concentrates in Tokyo-Osaka corridors and South Korean urban centers, where café operators source exclusive collaborations directly from manufacturers.
- Chocolate:Cocoa-based formulations with varying butterfat integration anchor mass-market volume through familiar taste profiles and ingredient sourcing scale.
- Vanilla:Bourbon and Tahitian variants provide base flavor for product line extensions despite underperformance against regional alternatives.
- Strawberry:Fruit-based formulations with regional sourcing from Shandong and Hokkaido growing regions serve seasonal promotional cycles.
Chocolate maintains volume leadership; matcha shows the steepest expansion trajectory.
Distribution Channel:
Channel selection determines pricing architecture and temperature integrity requirements, with foodservice commanding substantial premiums over retail formats.
- Foodservice:Direct supply to quick-service chains and café operators enables customized flavor development and exclusive collaborations. Penetration concentrates in South Korea and urban China, where procurement consolidation around preferred supplier agreements bypasses traditional distributor layers.
- Supermarkets:Multi-pack tubs and single-serve formats serve planned purchase occasions through cold cabinet placement and promotional pricing.
- Convenience Stores:Impulse-oriented single-serve bars and cones target commuter corridors with limited freezer space and rapid turnover requirements.
- Online Retail:Direct-to-consumer frozen delivery requires specialized insulated packaging and last-mile cold chain partnerships that remain concentrated in tier-one cities.
Supermarkets anchor volume throughput; foodservice delivers margin expansion.
Packaging Type:
Format selection balances portion control, consumption occasion, and cold chain logistics constraints across retail and away-from-home channels.
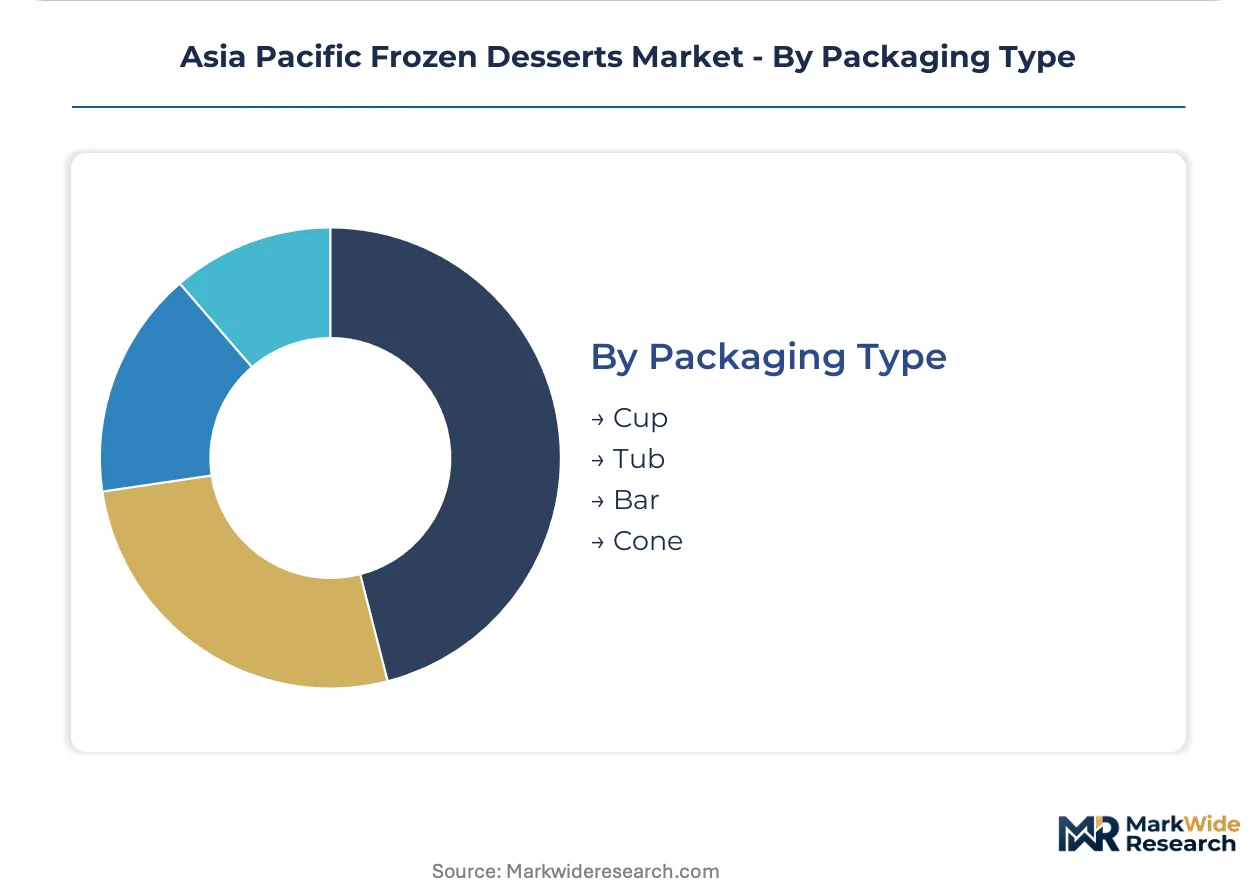
- Tub:Multi-serve containers (500ml-2L) serve family consumption and planned purchase occasions through retail freezer placement.
- Bar:Stick-mounted single-serve formats enable impulse purchase and portion-controlled indulgence in convenience and foodservice channels.
- Cup:Single-serve containers with spoon inclusion target on-premise consumption in cinemas, malls, and food courts.
- Cone:Pre-filled wafer or sugar cone formats integrate edible packaging for walking consumption occasions.
Tub formats dominate manufacturing scale; bar formats gain share fastest in convenience channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting frozen dessert production toward jurisdictions with lower compliance costs and expanding cold chain infrastructure. Manufacturers are relocating capacity to capture margin advantages from divergent food safety enforcement timelines and carbon accounting rules across the region.
China
Dual carbon goals and SAMR's evolving GB standards are forcing reformulation investments in Beijing-Tianjin-Hebei and Yangtze River Delta clusters. Mengniu and Yili supply chains face tightening additive thresholds and nutritional claim documentation requirements. Shanghai-based manufacturers are consolidating preferred supplier agreements with foodservice chains seeking exclusive regional flavor collaborations.
India
FSSAI microbiological standards and labeling requirements are accelerating domestic formulation capabilities in Maharashtra and Gujarat dairy corridors. Cold chain investments in Delhi-NCR and Bengaluru metro corridors enable premium frozen yogurt penetration previously blocked by temperature integrity gaps. Local manufacturers are capturing share from import-dependent competitors constrained by pathway restrictions.
Japan
MHLW residual agricultural chemical limits dictate ingredient sourcing protocols for Meiji and export-oriented producers in Kanto and Kansai regions. Probiotic frozen yogurt lines with live culture claims capture health-positioned consumers in Tokyo-Osaka corridors. Matcha formulations command premium pricing through cultural authenticity positioning in café channels.
South Korea
MFDS standards govern additive disclosure and nutritional labeling for domestic and import products alike. Seoul Capital Area foodservice procurement is consolidating around direct manufacturer contracts bypassing traditional distributor layers. Regional fruit flavor development capabilities are becoming a competitive differentiator for preferred supplier status.
Southeast Asia
Thailand and Vietnam manufacturing hubs are adopting continuous freezing automation to close quality gaps with multinational operations. Quick-service chains across Indonesia and Philippines are broadening dessert portfolios to capture younger consumers with gelato and frozen yogurt formats. Cold chain technician scarcity in tier-two cities limits rural market expansion despite urban infrastructure investments.
Asia Pacific Frozen Desserts Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with multinational dairy-integrated groups holding scale advantages in retail channels while regional flavor developers capture foodservice premiums. The vendor base organizes around three archetypes: dairy-backward-integrated conglomerates with captive milk sourcing, specialized probiotic positioning specialists, and automation-adopting mid-scale regional producers. Competitive moves concentrate on preferred supplier agreement consolidation and continuous freezing technology licensing to compress quality differentials.
Among dairy-integrated conglomerates, China Mengniu Dairy and Yili Group exemplify the backward-integration archetype through captive supply chain control. Meiji Holdings Co Ltd occupies a position within the functional-specialist tier, representing probiotic-forward formulation capabilities tailored to health-positioned segments. Unilever sustains manufacturing scale across multiple production hubs, anchoring the multinational branded portfolio segment.
| Leading Market Players |
|---|
| Mother Dairy |
| Meiji Holdings Co Ltd |
| Nestle SA |
| Baskin-Robbins |
| Danone Groupe SA |
| Unilever |
| China Mengniu Dairy |
| Ben & Jerry's |
| Yili Group |
| Others |
Value Chain & Pricing Dynamics
Continuous freezing technology adoption across Thai and Vietnamese manufacturing hubs is compressing batch-to-batch variation costs while redistributing scale advantages toward mid-tier regional producers previously locked out of premium contract tiers.
Pricing Analysis
Distributor margin layers in Southeast Asian foodservice channels absorb 15-25 points before café operators set final menu prices, creating substantial spread between ex-factory and consumption endpoints. Three-tier pricing structure across premium gelato, standard ice cream, and economy water-based formats reflects overrun targets and milk solids content. Pricing pressure stems from dairy input cost volatility constraining margin stability for import-dependent manufacturers. Quick-service chains exhibit highest price sensitivity due to volume procurement leverage, while boutique café operators accept premiums for exclusive regional fruit collaborations.
Supply Chain Analysis
India's FSSAI labeling mandates and import pathway restrictions are accelerating domestic dairy solids sourcing from Maharashtra and Gujarat cooperative networks. Supply concentration centers on China for stabilizer and aeration agent production, New Zealand and Australia for milk powder and butterfat inputs, and Thailand for tropical fruit puree bases. Raw material dependencies include dairy solids, hydrocolloid stabilizers, and natural flavor extracts. Single-source vulnerability in Chinese additive supply creates reformulation risk when SAMR tightens GB thresholds. Distribution runs through cold chain logistics partnerships concentrated in tier-one metro corridors with limited rural penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific frozen desserts function as a regulatory-arbitrage play where India's tightening FSSAI enforcement creates cost advantages for domestic formulators versus import-dependent competitors facing pathway constraints.
For Market Incumbents: Acquire captive dairy processing assets in India's Gujarat and Maharashtra corridors to secure milk solids supply against global powder price volatility. Consolidate preferred supplier agreements with Seoul Capital Area and Shanghai café chains before regional flavor developers capture exclusive collaboration slots. Defend position by accelerating continuous freezing technology licensing to Thai and Vietnamese contract manufacturers, compressing quality differentials that currently protect multinational scale advantages. For New Entrants and Emerging Players: Foodservice procurement officers in Indonesia and Philippines quick-service chains represent the most penetrable buyer segment given dessert portfolio expansion timelines and limited incumbent flavor development capabilities. Target probiotic frozen yogurt white space in India's Delhi-NCR and Bengaluru corridors where cold chain investments now enable premium positioning previously blocked by temperature integrity gaps. Secure direct manufacturer contracts bypassing distributor layers through customized yuzu, calamansi, or pandan flavor collaborations. For Investors and Strategic Acquirers: Roll-up economics work for dairy-backward-integrated regional specialists because FSSAI and SAMR regulatory divergence creates acquisition targets with localized compliance capabilities that multinational portfolios cannot replicate internally. Focus on manufacturers with captive milk sourcing in India and clean-label formulation expertise aligned with China's dual carbon trajectory. Watch cold chain technician training program expansion as the inflection signal for rural market viability beyond tier-one cities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dairy Sourcing | Captive milk supply from Gujarat cooperatives insulates Yili and Mengniu from global powder price spikes. |
| Preferred Supplier Agreement Consolidation | Direct contracts with Seoul café chains disintermediate distributor margins and accelerate flavor innovation cycles. |
| Continuous Freezing Technology Licensing | Thai mid-scale manufacturers automate overrun control to close quality gaps with Unilever production standards. |
| Probiotic Functional Positioning | Meiji's live culture claims capture health-positioned consumers in Tokyo-Osaka corridors and export markets. |
| Regional Fruit Flavor Localization | Matcha and yuzu formulations outperform vanilla in Japan and South Korea through cultural authenticity positioning. |
Study Parameters
Multiple input streams — executive interviews with frozen dessert category managers, procurement leads at quick-service chains, cold chain logistics operators, and regulatory affairs specialists — were reconciled against customs records, FSSAI enforcement circulars, SAMR GB standard updates, and Nielsen retail audit data. Primary fieldwork captured formulation practices across 15 manufacturing facilities spanning China, India, Thailand, and Vietnam. Secondary validation drew from dairy cooperative production statistics, foodservice menu expansion tracking, and cold chain infrastructure investment disclosures. Bottom-up volume modeling triangulated against top-down category spend estimates.
Historical consumption patterns were cross-referenced against panel input from supply planners and brand managers to anchor growth assumptions across the projection horizon. Segmentation modeling captured product type, flavor profile, distribution channel, and packaging format dimensions alongside regulatory compliance tier and cold chain capability cluster. CAGRs were derived from category velocity trends, per-capita consumption benchmarks, and channel shift dynamics. Forecast inputs included dairy solids price trajectory assumptions and GB standard update timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SAMR additive threshold revisions, FSSAI import pathway restrictions, and cold chain technician availability constraints. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Cold Storage Market
Processed and Frozen Foods
Processed and Frozen Fruits Market
Processed and Frozen Foods
Chilled Soup Market
Processed and Frozen Foods
Frozen Ready Meals Market
Processed and Frozen Foods
Frozen Tart Shells Market
Processed and Frozen Foods
North America Frozen Pizza Market
Processed and Frozen Foods
Europe Ice Cream Market
Processed and Frozen Foods
Frozen Dough Market
Processed and Frozen Foods
Frozen Cheese Market
Processed and Frozen Foods
Europe Frozen Desserts Market
Processed and Frozen Foods
Frozen French Fries Market
Processed and Frozen Foods
South America Frozen Food Market
Processed and Frozen Foods
Canned Vegetables Market
Processed and Frozen Foods
Frozen Tortilla Market
Processed and Frozen Foods
Deli Meat Market
Processed and Frozen Foods
Frozen Snacks Market