
 Bangladesh Frozen Food Market | 2026-2036
Bangladesh Frozen Food Market Size, Share, and Industry Trends Forecast 2026-2036
Bangladesh Frozen Food Market Outlook
Aftermarket cold-chain logistics revenue is tilting from fragmented transporters toward integrated operators with captive freezer fleets. PRAN-RFL Group Ltd leverages its nationwide distribution network to sustain direct store delivery in secondary cities. Golden Harvest Agro Industries Ltd anchors its position through backward integration into poultry farming. Apex Foods Limited competes on processed fish exports, drawing from Bangladesh's hilsa processing tradition.
Frozen food comprises thermally stabilized edible products preserved at sub-zero temperatures through blast freezing or individual quick freezing, maintaining cellular integrity for extended shelf life without chemical preservatives. The category serves commercial foodservice and retail households requiring consistent ingredient availability outside harvest seasons. Fish and chicken segments dominate volume, reflecting Bangladesh's riverine economy and broiler industry scale. Ready-to-eat meals represent the fastest-growing product type, capturing urban convenience demand. Supermarkets and online retail channels are expanding freezer infrastructure, though wholesale still controls rural penetration.
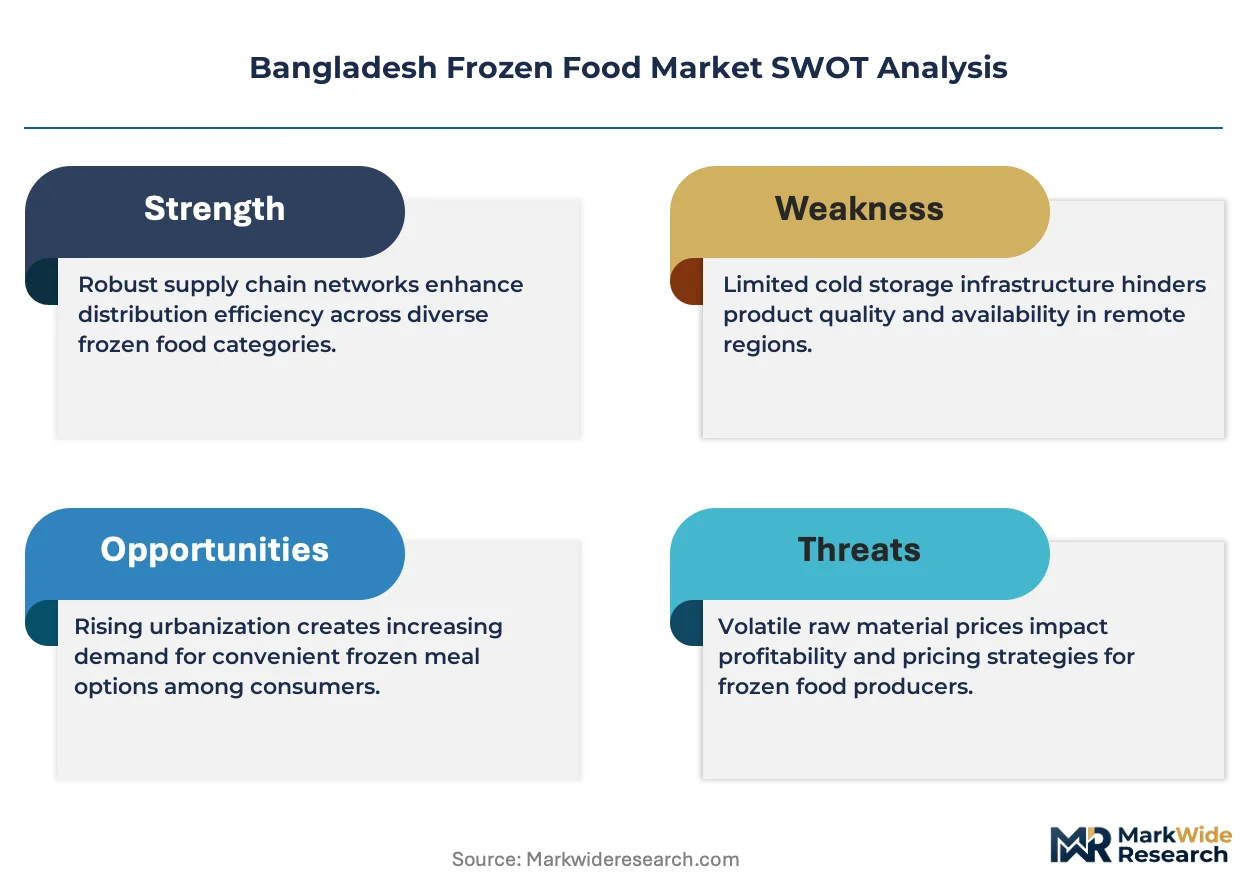
Bangladesh Standards and Testing Institution (BSTI) mandates nutritional labeling and cold-chain integrity certification for frozen products, while the Bangladesh Food Safety Authority enforces hazard analysis protocols at processing facilities. Compliance costs favor scaled manufacturers with in-house quality laboratories over informal processors. Stakeholders must monitor BSTI's impending frozen product standard revisions and assess cold-storage capacity investments before regulatory enforcement tightens.
Market Dynamics
Dual-income households in Dhaka and Chittagong are compressing meal preparation windows, pulling frozen ready-to-eat formats into daily consumption routines and forcing supply-side cold-chain investments ahead of regulatory deadlines.
Growth Catalysts
- Urban Time Scarcity:Working couples in metropolitan Bangladesh treat frozen parathas and biryanis as weekday staples, expanding addressable demand beyond traditional festival occasions.
- BSTI Cold-Chain Mandates:Certification requirements for freezer integrity during transport are professionalizing logistics, squeezing informal handlers and consolidating volume with compliant operators.
- Blast Freezing Diffusion:Individual quick freezing technology preserves hilsa texture for export markets, opening premium pricing tiers previously unavailable to Bangladeshi processors.
Market Restraints
- Power Grid Instability:Rural freezer storage depends on diesel generator backup, adding 18-25% to warehousing costs and capping penetration outside urban corridors.
- Import Concentration:Packaging films and refrigeration equipment originate from China, exposing margin compression when yuan-denominated contracts reprice.
- Fresh Preference Persistence:Wet market fishmongers in older Dhaka neighborhoods retain loyalty through morning availability and negotiated credit terms that frozen formats cannot replicate.
Strategic Opportunities
- Secondary City Modern Trade:Rajshahi and Khulna supermarket chains lack dedicated freezer aisles, creating first-mover positioning for direct store delivery networks.
- Foodservice Pre-Portioned Proteins:Quick-service restaurants in Chittagong's port zone require standardized chicken cuts, favoring frozen supply over variable fresh deliveries.
- Bangladesh Food Safety Authority Hazard Protocols:Early compliance with HACCP documentation opens institutional catering contracts requiring audit trails that informal processors cannot furnish.
Industry Challenges
- Cold-Chain Technician Scarcity:Refrigeration mechanics with frozen logistics experience cluster in Dhaka, forcing regional distributors to train staff internally or absorb contractor premiums.
- Freezer Asset Utilization:Seasonal demand spikes around Eid leave capital-intensive blast freezing capacity underemployed for eight months, straining unit economics.
- Legacy Wet Market Integration:Frozen distributors struggle to place products in traditional bazaars where vendors lack electrical infrastructure and consumer education on thawing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bangladesh Frozen Food Market |
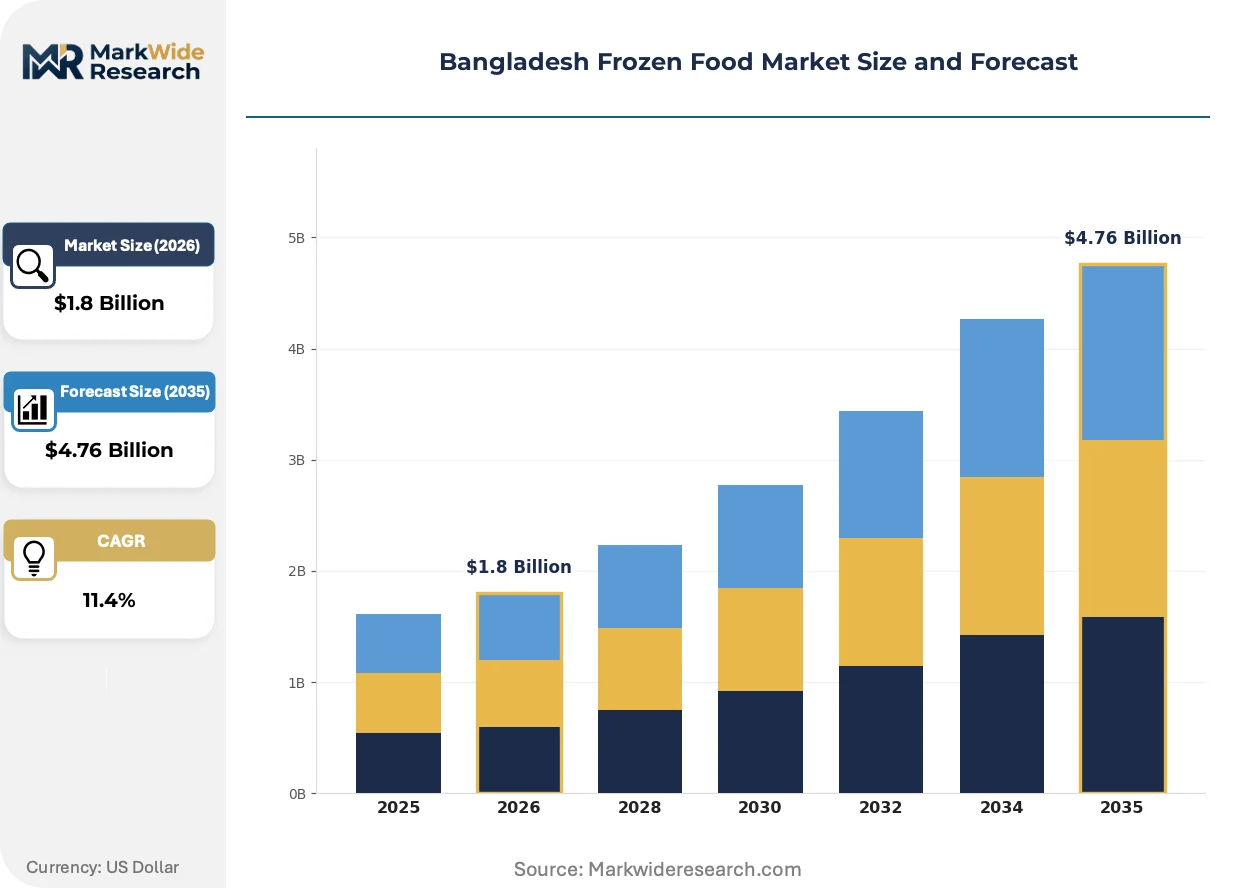
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish, Chicken, Vegetables, Ready-to-Eat Meals Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale End User: Households, Restaurants, Catering Services, Food Processors Packaging Type: Bags, Boxes, Pouches, Containers |
| Companies Covered | AG Agro Foods Limited, Apex Foods Limited, Golden Harvest Agro Industries Ltd, Royal Frozen Foods, Eurasia Food Processing (BD) Ltd, PRAN-RFL Group Ltd, McCain Foods, Taufika Group, Kazi Farms Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bangladesh Frozen Food Market Strategic Shifts
Digital traceability systems and modular freezing infrastructure are reconfiguring how Bangladeshi processors manage quality assurance and asset deployment across fragmented retail channels.
Blockchain-enabled temperature logging is virtualizing custody documentation for hilsa exports, replacing paper-based chain-of-cold records that European importers distrust. Bangladesh Frozen Foods Exporters Association members piloting this technology report faster customs clearance at Hamburg and London terminals. The shift is compressing dispute resolution timelines from weeks to hours when container temperature excursions occur.
Bangladesh Standards and Testing Institution is revising frozen product labeling requirements to mandate nutritional disclosure and origin tracing, effective upon publication in the official gazette. Processors with in-house laboratory capabilities will absorb compliance costs more readily than trading houses dependent on third-party certification. The ready-to-eat segment faces the steepest adaptation curve given multi-ingredient sourcing complexity.
Corporate cafeteria procurement now favors frozen pre-portioned proteins over daily fresh deliveries, driven by inventory predictability and waste reduction mandates. Multinational garment factories in Dhaka Export Processing Zone lead this shift, negotiating annual contracts with fixed pricing that frozen suppliers can underwrite. The behavior is most pronounced in export-oriented manufacturing campuses where audit-sensitive buyers demand documented food safety protocols.
Bangladesh Frozen Food Market Segmentation
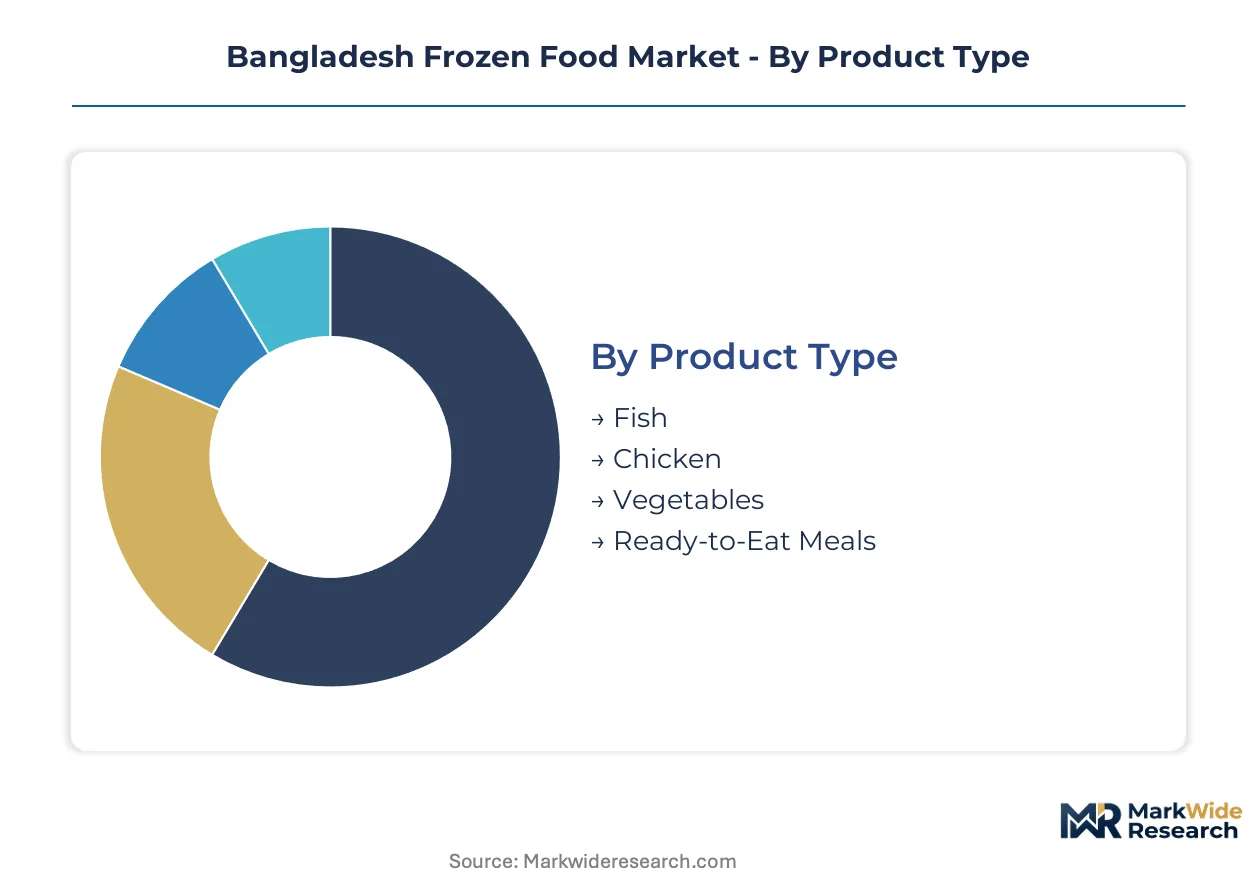
Frozen food segmentation in Bangladesh reflects competing pressures between export-grade processing standards and domestic consumption patterns shaped by infrastructure constraints. Understanding how product formats, channel access, and packaging specifications intersect reveals where margin capture concentrates versus where volume expansion remains trapped in low-margin wholesale circuits.
Product Type:
Cost tier stratification separates commodity proteins from value-added formats, with processing intensity determining cold-chain investment requirements and pricing power.
- Fish:Hilsa and pangasius fillets undergo individual quick freezing to preserve cellular structure for European export markets. Dhaka-based processors serving Hamburg and London terminals command premium pricing through blockchain-enabled temperature documentation that BSTI mandates for export certification.
- Ready-to-Eat Meals:Frozen parathas, biryanis, and curries target dual-income households in Dhaka and Chittagong where weekday meal preparation windows have compressed below thirty minutes. This segment climbs the fastest as urban time scarcity pulls convenience formats beyond traditional festival occasions into daily consumption routines.
- Chicken:Broiler cuts and whole birds dominate volume through backward integration into poultry farming by major processors. Rural penetration remains capped by wet market preference and generator-dependent cold storage costs.
- Vegetables:Peas, cauliflower, and mixed vegetable packs serve institutional catering contracts requiring standardized portioning. Export volumes trail fish and chicken due to lower processing margins and shorter shelf stability.
Fish holds installed capacity. Ready-to-Eat Meals is rotating up the share rankings.
Distribution Channel:
Channel selection determines compliance burden and working capital intensity, with modern trade formats extracting stricter cold-chain documentation than fragmented wholesale circuits.
- Supermarkets:Dedicated freezer aisles in Dhaka Division's retail corridor anchor branded frozen food visibility. Shwapno and Meena Bazar chains require direct store delivery networks with captive refrigerated fleets that exclude informal transporters.
- Wholesale:Traditional bazaars in Rajshahi and Khulna move bulk frozen fish and chicken through cash-based transactions without temperature logging. This channel captures volume but sacrifices margin to intermediaries lacking BSTI certification.
- Online Retail:Chaldal and Pickaboo deploy insulated packaging with dry ice for last-mile frozen delivery, targeting apartment-dwelling professionals in Gulshan and Banani. Customer acquisition costs run high against low-repeat purchase frequency outside metropolitan cores.
- Convenience Stores:Limited freezer infrastructure restricts assortment to high-velocity SKUs like frozen parathas. Secondary city penetration awaits modular cold-storage solutions that reduce capital deployment per outlet.
Wholesale holds installed capacity. Supermarkets is rotating up the share rankings.
End User:
Customer type dictates order predictability and specification stringency, with institutional buyers demanding audit trails that informal processors cannot furnish.
- Restaurants:Quick-service chains in Chittagong's port zone require standardized chicken cuts with consistent sizing for portion control. Frozen supply displaces variable fresh deliveries where supplier reliability trumps morning-market freshness.
- Households:Urban families in Dhaka treat frozen proteins as weekday staples while retaining wet market relationships for weekend fish purchases. Dual-income status correlates directly with freezer ownership and ready-to-eal trial rates.
- Catering Services:Wedding and corporate event caterers in Dhaka Export Processing Zone favor pre-portioned proteins for inventory predictability. Multinational garment factory cafeterias lead this shift with annual contracts requiring HACCP documentation.
- Food Processors:Downstream manufacturers of frozen snacks and bakery items source bulk frozen vegetables and proteins as input ingredients. This segment values supply consistency over branding and pays commodity-equivalent pricing.
Households holds installed capacity. Restaurants is rotating up the share rankings.
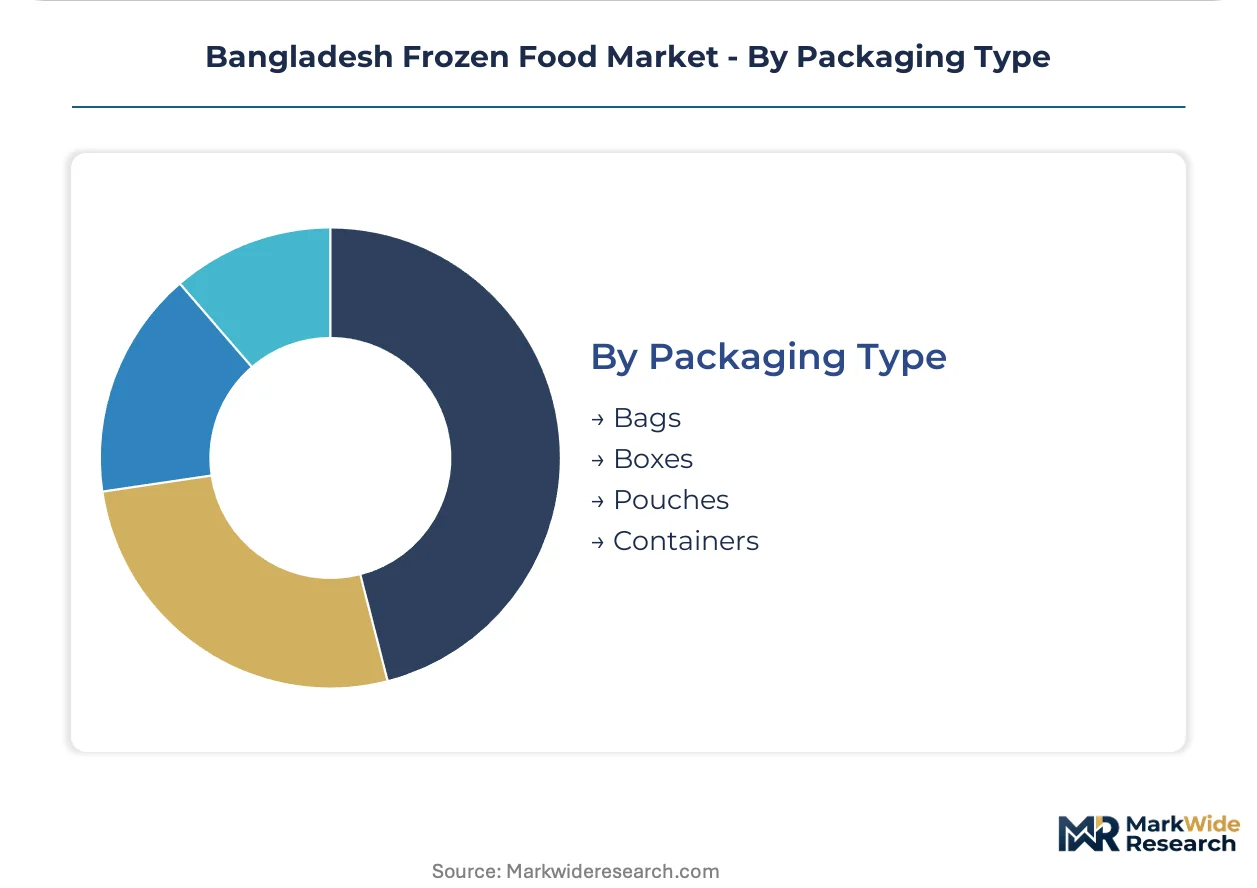
Packaging Type:
Packaging specification determines shelf visibility, portion flexibility, and cold-chain thermal mass, with material costs exposed to yuan-denominated import contracts.
- Pouches:Flexible laminated films dominate ready-to-eat meals and marinated chicken portions, enabling vertical display in limited freezer space. Chinese import concentration exposes margin compression when currency contracts reprice.
- Containers:Rigid plastic tubs with resealable lids target premium biryani and curry formats where leftovers retention justifies higher unit pricing. Dhaka supermarkets favor this format for organized shelf presentation.
- Bags:Polyethylene sacks handle bulk fish and vegetable shipments through wholesale channels where branding investment is minimal. Cost per unit lowest but offers no differentiation at point of sale.
- Boxes:Corrugated freezer-grade cartons protect export shipments through Hamburg and London terminals, incorporating temperature indicator strips that customs inspectors reference. BSTI mandates this format for hilsa exports to European Union markets.
Bags holds installed capacity. Pouches is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dhaka Division consumes frozen ready-to-eat meals as weekday staples while Chittagong prioritizes export-grade fish processing, revealing a domestic convenience-versus-export quality split that shapes cold-chain investment patterns across administrative regions.
Dhaka Division
Dual-income households in Gulshan and Banani drive frozen paratha and biryani consumption through supermarket channels. Bangladesh Standards and Testing Institution mandates nutritional labeling compliance for all packaged products sold through modern trade. The Dhaka Export Processing Zone anchors institutional catering contracts requiring HACCP documentation that informal processors cannot furnish.
Chittagong Division
Port-zone quick-service restaurants demand standardized chicken cuts with consistent portion sizing for inventory predictability. Bangladesh Food Safety Authority enforces hazard analysis protocols at processing facilities serving export markets. The Chittagong frozen fish cluster supplies Hamburg and London terminals through blockchain-enabled temperature logging that BSTI mandates for European Union certification.
Rajshahi Division
Secondary city supermarket chains lack dedicated freezer aisles, creating first-mover positioning for direct store delivery networks. National cold-chain compliance requirements professionalize logistics while squeezing informal transporters. Rajshahi's wholesale bazaars move bulk frozen fish through cash-based transactions without temperature logging, sacrificing margin to uncertified intermediaries.
Khulna Division
Rural freezer storage depends on diesel generator backup, adding warehousing costs that cap frozen food penetration outside urban corridors. Power grid instability forces distributors to absorb 18-25% cost premiums for backup refrigeration. Khulna's shrimp processing heritage supports frozen seafood exports though volume trails Chittagong's hilsa specialization.
Sylhet Division
Remittance-funded household consumption supports premium frozen product trial among diaspora-connected families. Bangladesh Standards and Testing Institution labeling requirements apply uniformly across all administrative divisions regardless of per-capita income differentials. Sylhet's retail corridor remains underserved by captive refrigerated fleets, limiting modern trade penetration.
Bangladesh Frozen Food Market Competitive Environment
Capability concentration sits with integrated processors possessing in-house quality laboratories; scale advantage sits with diversified conglomerates leveraging nationwide distribution networks. The vendor base separates into three tiers: export-certified specialists, domestic retail consolidators, and commodity wholesalers serving traditional bazaars. Competitive moves center on backward integration into poultry farming and direct store delivery network expansion into secondary cities.
Within the integrated processor tier, Golden Harvest Agro Industries Ltd and Apex Foods Limited exemplify archetypes built around upstream control over supply inputs. PRAN-RFL Group Ltd occupies a position representing diversified conglomerate scale advantages through captive distribution infrastructure. These three anchors illustrate how compliance burden favors scaled manufacturers over informal trading houses dependent on third-party certification.
| Leading Market Players |
|---|
| AG Agro Foods Limited |
| Apex Foods Limited |
| Golden Harvest Agro Industries Ltd |
| Royal Frozen Foods |
| Eurasia Food Processing (BD) Ltd |
| PRAN-RFL Group Ltd |
| McCain Foods |
| Taufika Group |
| Kazi Farms Group |
| Others |
Value Chain & Pricing Dynamics
The Chittagong-Dhaka refrigerated freight corridor anchors cost dynamics that concentrate supply with integrated operators while forcing three-tier price differentiation between export-certified, modern-trade, and traditional bazaar tiers. Diesel generator dependence in rural warehousing amplifies landed cost spreads between urban freezer hubs and peripheral distribution nodes.
Pricing Analysis
Long-term offtake contracts dominate institutional catering procurement in Dhaka Export Processing Zone, locking annual volume commitments with fixed pricing that frozen suppliers underwrite against spot-market volatility in packaging films and poultry feed inputs. Three-tier pricing structure across premium, standard, and economy levels separates blockchain-documented hilsa exports from BSTI-compliant domestic retail formats and uncertified wholesale commodities. Cost compression in the wholesale tier is intensifying because diesel generator premiums and informal transporter margins compound at each intermediary handoff. Quick-service restaurants in Chittagong's port zone exhibit lowest price sensitivity due to inventory predictability mandates, while rural household buyers in Khulna Division remain most responsive to per-kilogram differentials against wet market alternatives.
Supply Chain Analysis
Export-control regimes on refrigeration equipment and blast freezing technology limit capital goods flows from China, South Korea, and Germany into Bangladeshi processor facilities. Raw material dependencies center on Chinese-imported laminated packaging films, Thai-origin poultry feed additives, and domestic broiler farming output concentrated in Mymensingh and Gazipur districts. Single-source vulnerability in yuan-denominated equipment contracts exposes margin compression when currency repricing occurs without hedge coverage. Distribution runs through captive refrigerated fleets serving modern trade in Dhaka Division, while fragmented transporters with generator-dependent trucks handle rural wholesale circuits lacking BSTI temperature logging compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified refrigeration mechanics with frozen logistics experience cluster almost exclusively in Dhaka, creating a chokepoint that constrains regional expansion for any operator lacking internal training infrastructure or contractor premium absorption capacity.
For Market Incumbents: Entrench position through backward integration into captive poultry farming and blast freezing capacity that absorbs seasonal demand spikes around Eid without external dependency. Expand direct store delivery networks into Rajshahi and Khulna before secondary city supermarket chains install dedicated freezer aisles that would raise competitive entry barriers. BSTI's impending labeling standard revisions threaten trading-house competitors dependent on third-party certification. For New Entrants and Emerging Players: Mid-market ready-to-eat meal formats in Chittagong's underserved apartment corridors represent the most penetrable entry point where dual-income household density exceeds current freezer infrastructure coverage. Modular cold-storage solutions for convenience store penetration in Sylhet Division offer second-mover positioning before incumbent fleets extend northward. Lead with insulated dry-ice delivery partnerships targeting online retail platforms rather than asset-heavy fleet ownership. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified conglomerates with frozen food divisions that lack standalone export certification infrastructure but possess captive distribution networks worth retrofitting. Five-to-ten year viability hinges on regulatory compliance moats rather than commodity volume scale. Watch for BSTI enforcement actions against informal processors as the inflection signal indicating consolidation acceleration toward certified operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Poultry Farming | Golden Harvest's captive broiler supply secures margin control against feed price volatility. |
| Blockchain-Enabled Temperature Documentation | BSTI-mandated custody records accelerate customs clearance at Hamburg and London terminals. |
| Direct Store Delivery Network Expansion | PRAN-RFL's refrigerated fleet penetration captures secondary city modern trade before competitor infrastructure deployment. |
| Modular Cold-Storage Solutions | Reduced capital per outlet enables convenience store freezer aisle installation in Rajshahi and Khulna. |
| HACCP Documentation Investment | Early compliance opens multinational garment factory cafeteria contracts requiring audit trails. |
Study Parameters
The analysis maps frozen fish processing, ready-to-eat meal manufacturing, poultry integration, and cold-chain logistics segments, each validated through processor operations directors, supermarket category buyers, and BSTI compliance officers. Primary interviews with fleet managers at integrated distributors and procurement leads at Dhaka Export Processing Zone cafeterias combined with secondary validation through Bangladesh Frozen Foods Exporters Association trade data, BSTI gazette notifications, and customs export records. Bottom-up capacity utilization estimates triangulated against top-down consumption surveys across urban household panels.
Assumptions held fixed include BSTI regulatory enforcement timelines and diesel generator cost structures, while variables spanned urbanization rates and modern trade penetration speeds. Segmentation dimensions modeled encompass product type, distribution channel, end user, and packaging format across regional administrative divisions. CAGRs derived from volume trajectory analysis incorporating seasonal demand patterns and cold-storage capacity expansion pipelines. Forecast inputs included power grid reliability indices and remittance flow correlations with premium product trial rates.
Practitioners should monitor BSTI standard revision publication timing and diesel price subsidy adjustments for early signals of margin structure shifts. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and infrastructure investment continuity. Material shifts in power grid stabilization timelines or yuan exchange rate volatility corridors would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Icebreakers Market
Processed and Frozen Foods
Frozen Bread Market
Processed and Frozen Foods
Frozen Food and Snacks Market
Processed and Frozen Foods
North America Frozen Desserts Market
Processed and Frozen Foods
Kimchi Market
Processed and Frozen Foods
Individual Quick Frozen Cheese Market
Processed and Frozen Foods
Dehydrated Potato Market
Processed and Frozen Foods
Ice Structuring Protein Market
Processed and Frozen Foods
Low-Fat Low-Cholesterol Foods Market
Processed and Frozen Foods
Frozen Meat Market
Processed and Frozen Foods
Taiyaki Ice Cream Market
Processed and Frozen Foods
Cold Storage Market
Processed and Frozen Foods
Frozen Meat Grinder Market
Processed and Frozen Foods
Frozen Chicken Market
Processed and Frozen Foods
Europe Frozen Pizza Market
Processed and Frozen Foods
Frozen Tart Shells Market