
 Popsicle and Ice Cream Bar Market | 2026-2036
Popsicle and Ice Cream Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Popsicle and Ice Cream Bar Market Insights
Multi-pack bundling of single-serve novelty bars is realigning household purchase behavior toward variety-driven freezer loading. Unilever leverages its global manufacturing footprint to sustain year-round distribution across temperate and tropical climates. Nestlé anchors its competitive stance through R&D intensity in reduced-sugar formulations. Yili dominates domestic production networks across northern China, where cold-chain density supports mass-market penetration.
Popsicles and ice cream bars comprise frozen desserts manufactured through blast freezing of dairy, water, or plant-based mixes at temperatures below minus twenty degrees Celsius, designed for handheld consumption without utensil requirements. Novelty bars and ice cream sandwiches capture premium margin pools as consumers trade up toward textured, layered, and inclusion-heavy formats. Fruit-flavored entries within the flavor profile dimension compete most aggressively for shelf space in summer seasonal resets, while chocolate variants sustain year-round baseline velocity. Distribution through convenience stores and ice cream parlors concentrates impulse purchase volume, whereas supermarkets and online stores anchor planned replenishment cycles.
FDA oversight of nutrition labeling and serving-size declarations shapes product-portfolio architecture for manufacturers targeting the United States, while EFSA guidance on novel food ingredients governs reformulation pathways for European export compliance. China's SAMR enforces GB standards for frozen beverage hygiene and additive thresholds, conditioning market access for imported and domestic brands alike. Stakeholders must monitor evolving clean-label thresholds and cold-chain efficiency benchmarks as the primary determinants of margin sustainability and geographic expansion feasibility.
Market Dynamics
Clean-label ingredient mandates from the FDA and EFSA are forcing simultaneous reformulation across legacy portfolios and new product pipelines, compressing R&D cycles while expanding compliance overhead for multinational frozen dessert manufacturers.
Growth Catalysts
- Convenience store freezer expansion:Retailers in the United States are dedicating incremental linear footage to single-serve novelty bars, capturing impulse traffic from fuel and quick-service adjacencies.
- Blast freezing automation:Continuous processing lines operating below minus twenty degrees Celsius are reducing unit labor costs and enabling textured inclusion layers previously limited to artisanal production.
- Dual-income household time compression:Working parents are substituting multi-pack novelty bundles for scratch dessert preparation, rotating variety-driven freezer inventory as a household routine.
Market Restraints
- Dairy input cost volatility:Butterfat and milk powder prices on the Chicago Mercantile Exchange swing seasonally, squeezing margin predictability for dairy-forward ice cream bar formulations.
- Cold-chain infrastructure gaps:Last-mile frozen distribution in tropical latitudes relies on diesel-dependent reefer units with limited backup power redundancy.
- Clean-label compliance fragmentation:Divergent additive thresholds between FDA, EFSA, and China's SAMR force parallel formulation tracks rather than unified global SKUs.
Strategic Opportunities
- Plant-based base expansion:Oat and coconut milk frozen bar platforms address lactose-intolerant and flexitarian cohorts in northern European markets with established dairy alternatives infrastructure.
- Direct-to-home subscription channels:Insulated packaging innovations are enabling monthly curated novelty boxes bypassing traditional retail slotting fees.
- SAMR frozen beverage hygiene standardization:China's consolidation of GB standards creates a single compliance doorway for imported brands previously navigating provincial variation.
Industry Challenges
- Refrigeration technician scarcity:Industrial blast freezer maintenance requires certified ammonia and CO2 system specialists concentrated in legacy dairy processing regions.
- Cross-border phytosanitary documentation:Fruit inclusion sourcing from multiple origins triggers complex certificate-of-origin tracking for EFSA novel food dossiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Popsicle and Ice Cream Bar Market |
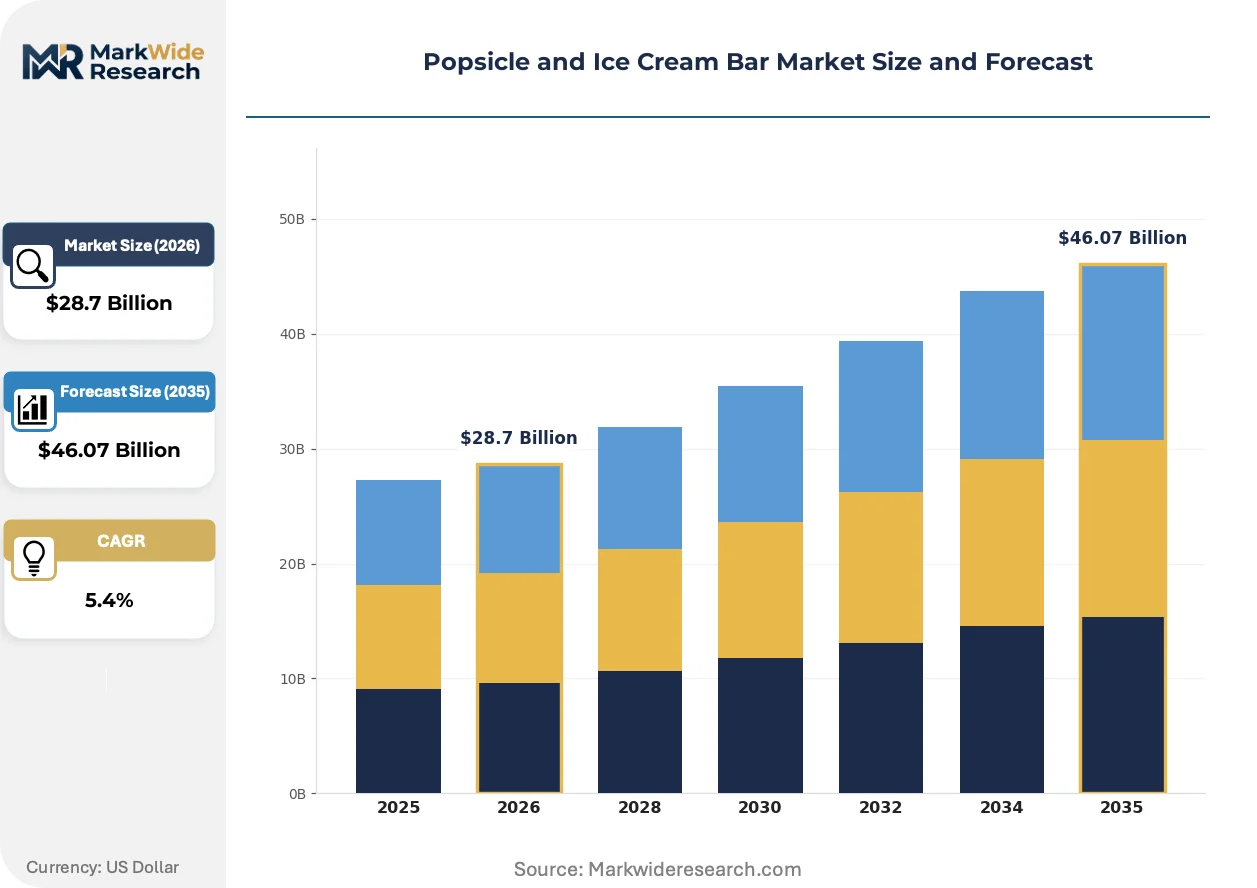
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $46.07 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Novelty Bars, Frozen Treats, Popsicles, Ice Cream Sandwiches Flavor Profile: Fruit, Chocolate, Vanilla, Mint Packaging Type: Boxes, Pouches, Cups, Tubs Distribution Channel: Supermarkets, Convenience Stores, Online Stores, Ice Cream Parlors |
| Companies Covered | Unilever, Nestlé, Yili, Mengniu, Ben & Jerry's, Häagen-Dazs, Magnum, LOTTE, Meiji, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Popsicle and Ice Cream Bar Market Trends and Innovations
Texture engineering and regulatory harmonization are converging to redefine what constitutes a premium frozen bar, shifting competitive advantage from flavor novelty to structural integrity and label transparency.
Extrusion-based inclusion layering is rewriting the economics of premium bar manufacturing. Equipment suppliers in Italy and Germany now deliver continuous depositors capable of embedding cookie dough, fruit purees, and caramel ribbons at throughput rates matching conventional single-flavor lines. Mid-tier brands in the United States are adopting these systems to close the texture gap with artisanal competitors without sacrificing scale economics.
EFSA guidance on novel food ingredients is accelerating reformulation timelines for European export portfolios. Manufacturers must submit comprehensive toxicological dossiers for non-traditional proteins and alternative sweeteners before market entry, compressing product launch windows by six to nine months. Chocolate-coated dairy alternatives face the steepest documentation burden, as cocoa butter equivalents and plant-based emulsifiers trigger separate safety assessments.
Households are rotating freezer inventory toward variety-driven multi-pack architectures rather than bulk tub replenishment. Parents with school-age children in suburban United States markets are purchasing four to six distinct novelty SKUs per trip, treating frozen dessert selection as a weekly decision-making ritual rather than a commodity restock. This pattern concentrates volume in convenience and club channels with high SKU breadth, disadvantaging supermarkets with limited frozen door space.
Popsicle and Ice Cream Bar Market Segmentation
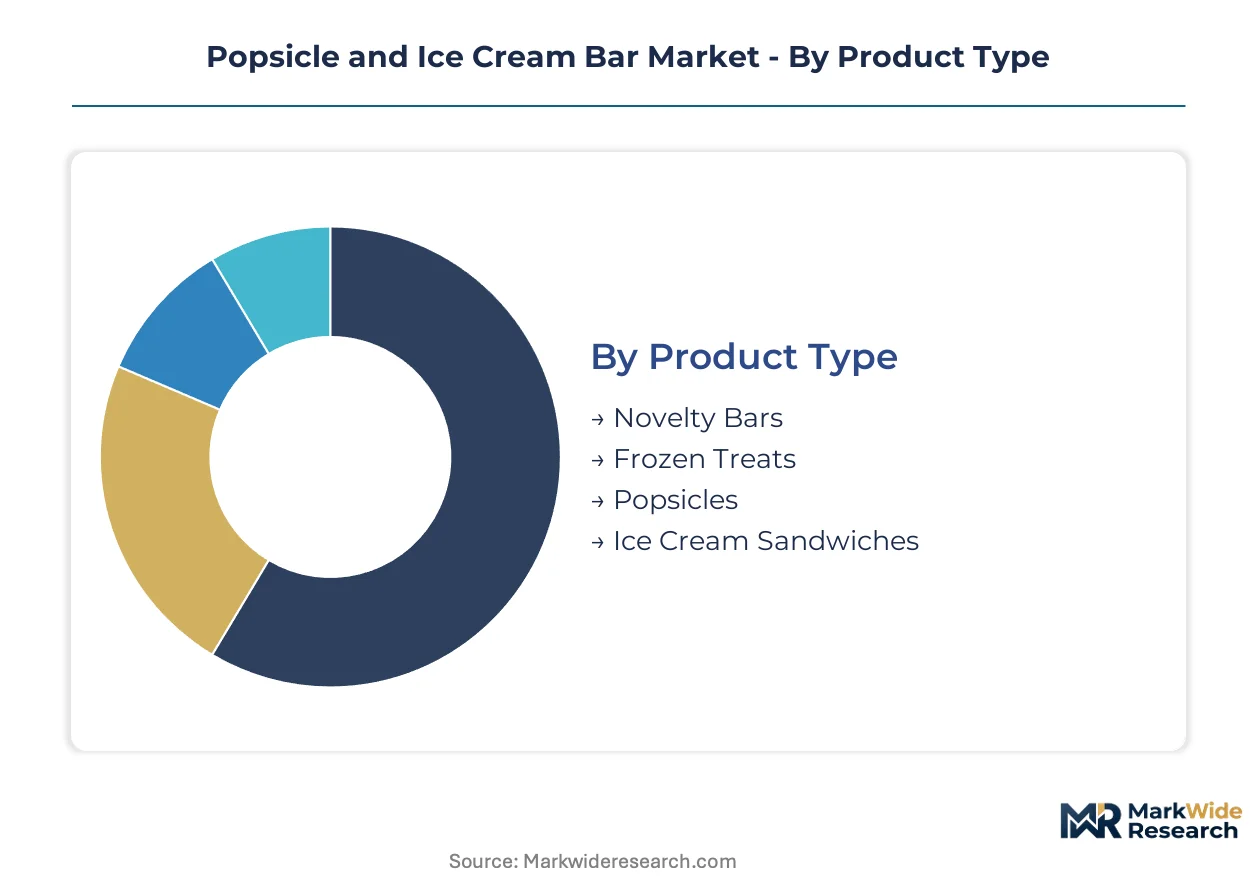
Segmentation in frozen handheld desserts reveals divergent margin architectures across product formats and purchase occasions. Manufacturers configure production lines and cold-chain investments around distinct velocity profiles and shelf-life requirements.
Product Type:
Premium-positioned buyers gravitate toward layered textures and inclusion-heavy formats, while value-seeking households prioritize single-flavor refreshment at lower price points.
- Novelty Bars:Multi-layer constructions combining ice cream, caramel, cookie inclusions, and chocolate coatings command shelf space in convenience and club channels. United States suburban households rotate four to six distinct novelty SKUs per shopping trip, treating selection as a weekly ritual rather than commodity restock.
- Frozen Treats:Water-based formulations with juice or puree bases target lactose-intolerant and dairy-avoidant consumers. Demand concentrates in tropical markets where cold-chain gaps favor lower-melt, higher-overrun products with extended ambient tolerance.
- Popsicles:Single-flavor frozen juice or dairy blends in stick format serve mass-market refreshment occasions. Brazil and Mexico drive volume through street-vendor and small-format retail distribution.
- Ice Cream Sandwiches:Cookie-wafer or cake-layer constructions with ice cream filling capture nostalgia-driven purchase in North American convenience stores. Extrusion-based continuous lines now match artisanal texture quality at industrial scale.
Novelty bars lead volumes today; frozen treats are gaining share fastest.
Flavor Profile:
Seasonal velocity patterns separate summer-peak fruit formulations from year-round chocolate baseline demand, reshaping production scheduling and ingredient procurement.
- Fruit:Berry, citrus, and tropical puree formulations compete aggressively for shelf space during summer seasonal resets. EFSA novel food dossier requirements for non-traditional fruit inclusions compress European launch timelines.
- Chocolate:Cocoa-based coatings and variegates sustain twelve-month baseline velocity across all climate zones. SAMR additive thresholds for cocoa butter equivalents condition China market access documentation.
- Vanilla:Classic dairy-forward base formulations anchor private-label portfolios and economy-tier positioning. Madagascar and Indonesian vanilla bean sourcing triggers complex phytosanitary certificate tracking.
- Mint:Seasonal limited-edition positioning in North American markets, with peppermint oil concentration regulated by FDA flavoring substance thresholds.
Chocolate dominates year-round velocity; fruit climbs fastest during seasonal expansion windows.
Packaging Type:
Cold-chain efficiency and impulse-versus-planned purchase behavior determine format selection, with insulation properties and unit economics diverging sharply.
- Boxes:Multi-count corrugated containers protect product integrity through direct-to-home subscription channels. Insulated packaging innovations enable monthly curated novelty boxes bypassing traditional retail slotting fees.
- Pouches:Flexible film single-serve wraps minimize freezer burn in convenience store open-air coffin cases. Lightweight formats reduce diesel-dependent reefer transport costs in last-mile tropical distribution.
- Cups:Rigid plastic tubs with resealable lids support spoonable consumption and portion control positioning. Higher unit costs limit penetration to premium-tier supermarket door space.
- Tubs:Bulk family-size containers for multi-scoop home consumption, increasingly displaced by novelty bar variety-seeking in dual-income households.
Pouches capture impulse volume; boxes expand fastest through e-commerce subscription.
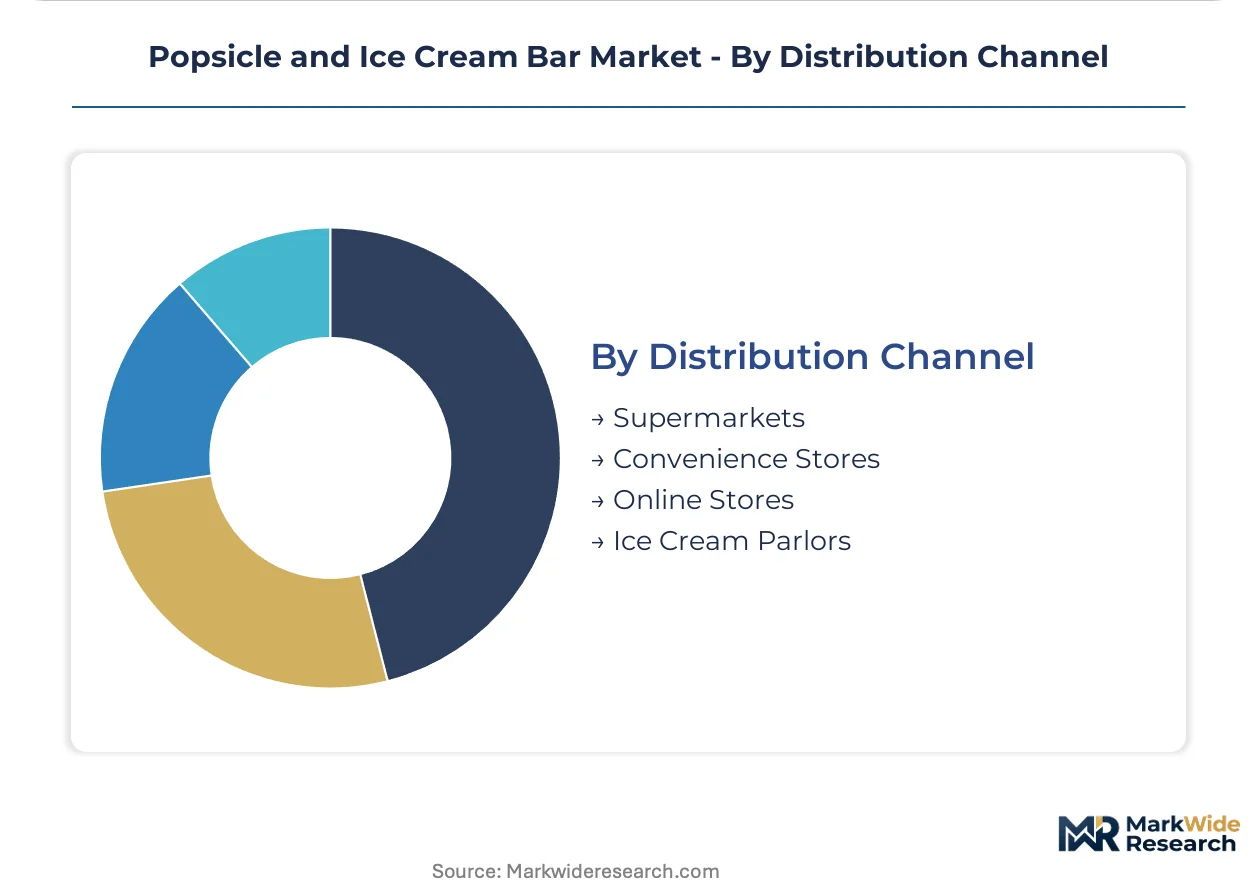
Distribution Channel:
Freezer door configuration and traffic patterns separate high-margin impulse capture from planned replenishment economics.
- Supermarkets:Planned replenishment cycles anchor household freezer loading, though SKU breadth constraints disadvantage formats against convenience and club alternatives.
- Convenience Stores:Incremental linear footage expansion in United States fuel-adjacent locations captures traffic from quick-service and automotive service intervals. Impulse purchase velocity concentrates here.
- Online Stores:Direct-to-home fulfillment requires dry-ice or gel-pack insulated packaging with 48-hour delivery guarantees. Slotting fee avoidance and curated variety drive mid-tier brand adoption.
- Ice Cream Parlors:Hand-dipped and soft-serve adjacent formats command premium pricing through experience-driven occasion. Limited scale constrains manufacturer partnership priority.
Convenience stores lead impulse volume; online stores expand fastest through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The frozen handheld dessert industry traces its industrial roots to early twentieth-century United States mechanization, when continuous freezer technology enabled mass production of ice cream bars. From this origin, manufacturing expertise diffused through European dairy networks and Asian cold-chain development, creating distinct regional consumption patterns today.
United States
Suburban dual-income households drive variety-seeking behavior through multi-pack novelty purchases. FDA nutrition labeling mandates reshape portfolio architecture for domestic and import brands. Convenience store freezer expansion in fuel-adjacent locations captures impulse traffic across Texas, Florida, and California metropolitan corridors.
China
Domestic production networks concentrate in northern provinces where cold-chain density supports mass-market penetration. SAMR enforcement of GB frozen beverage hygiene standards conditions market access for imported brands. Yili and Mengniu anchor manufacturing clusters in Inner Mongolia and Beijing-Tianjin-Hebei with integrated dairy supply bases.
Germany
Flexitarian and lactose-intolerant cohorts accelerate plant-based frozen bar adoption in northern European markets. EFSA novel food dossier requirements compress launch timelines for alternative protein formulations. Industrial equipment suppliers in Bavaria and Baden-Württemberg deliver continuous extrusion systems enabling textured inclusion layers at scale.
Brazil
Street-vendor and small-format retail distribution channels sustain popsicle volume in tropical urban centers. Phytosanitary documentation complexity for fruit inclusions triggers certificate-of-origin tracking from multiple sourcing origins. São Paulo and Rio de Janeiro metropolitan areas concentrate cold-chain infrastructure investment for last-mile frozen distribution.
Japan
Premium texture engineering and seasonal limited-edition positioning command household freezer space in dense urban markets. METI industrial standards guide manufacturing equipment specifications for continuous processing lines. Tokyo-Osaka corridor demand concentrates in convenience store networks with high SKU breadth and rapid product rotation cycles.
Popsicle and Ice Cream Bar Market Competitive Landscape
Premium-margin players sit above commodity-margin players across texture complexity and clean-label certification dimensions, creating a tiered structure with limited middle-ground viability. The vendor base spans multinational conglomerates with integrated dairy supply chains, regional specialists leveraging local cold-chain advantages, and artisanal producers competing on inclusion novelty. Three archetypes dominate: scale-driven global brands with year-round tropical distribution, domestic market leaders exploiting regulatory familiarity, and premium-tier specialists commanding price multiples through layered construction. Competitive intensity manifests through blast freezer automation investments and direct-to-home subscription channel development.
Among globally diversified conglomerates, Unilever and Nestlé occupy positions as archetype anchors for scale-driven, year-round distribution capabilities. Yili exemplifies the domestic market leader archetype with integrated northern China production networks. These three entities represent distinct strategic postures—multinational reach, multinational R&D intensity, and regional supply-chain capture—without implying specific market share or financial performance claims.
| Leading Market Players |
|---|
| Unilever |
| Nestlé |
| Yili |
| Mengniu |
| Ben & Jerry's |
| Häagen-Dazs |
| Magnum |
| LOTTE |
| Meiji |
| Others |
Pricing and Supply Chain Analysis
Dual-income household time compression in the United States is forcing manufacturers to reconfigure pack sizes and distribution density, which in turn concentrates procurement power among club-channel buyers and squeezes margin flexibility for mid-tier producers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates frozen handheld desserts. Price differentiation stems from texture complexity and clean-label certification grade. Cost compression in economy tiers is intensifying because of dairy input volatility on the Chicago Mercantile Exchange. Value-seeking households in Brazil and Mexico exhibit highest price sensitivity, while premium novelty buyers in Japan and Germany show lowest elasticity.
Supply Chain Analysis
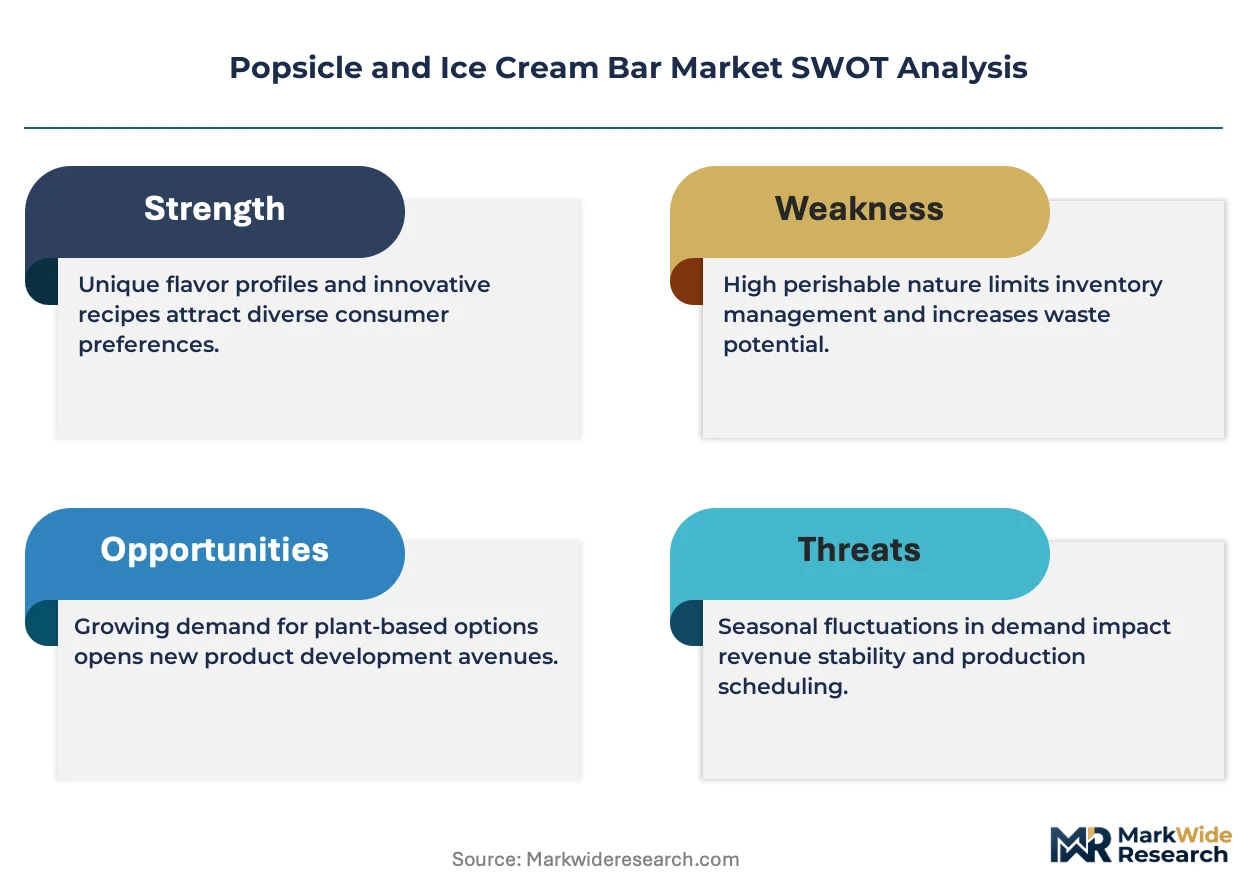
Butterfat and milk powder supply rests on dairy processing clusters in the United States, New Zealand, and the European Union. Cocoa butter equivalents and plant-based emulsifiers draw from Malaysian and Indonesian palm oil networks. Single-source vulnerability concentrates in Madagascar and Indonesian vanilla bean sourcing. Distribution runs through temperature-controlled reefer networks with diesel-dependent last-mile legs in tropical markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Popsicle and Ice Cream Bar Market functions as a stable compounder anchored by recurring household replenishment cycles and seasonal ritual consumption patterns.
For Market Incumbents: Deepen backward integration into dairy supply bases in northern China and Inner Mongolia to secure butterfat cost predictability against CME volatility. Expand blast freezer automation capacity in Bavaria and Baden-Württemberg to close texture gaps with artisanal competitors. Prioritize EFSA novel food dossier pre-submission for alternative protein formulations to compress European launch timelines. For New Entrants and Emerging Players: The mid-tier price gap between Magnum-positioned premium bars and mass-market popsicle entries offers white-space opportunity in direct-to-home subscription channels with insulated packaging bypassing retail slotting fees. Target suburban United States households rotating four to six distinct novelty SKUs weekly. Lead with plant-based oat and coconut milk platforms in northern European flexitarian cohorts. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists commanding local cold-chain density in underserved tropical markets. Long-term viability hinges on SAMR compliance capability for China market access and EFSA dossier expertise for European export positioning. Watch for SAMR consolidation of GB frozen beverage standards as inflection signal for import brand doorway widening.| Strategic Initiative | Industry Significance |
|---|---|
| Blast Freezer Automation Investment | Continuous extrusion systems from Italian and German equipment suppliers enable textured inclusion layers at industrial scale. |
| Direct-to-Consumer Subscription Launch | Insulated packaging innovations bypass convenience store slotting fees and capture variety-seeking household replenishment cycles. |
| Plant-Based Base Expansion | Oat and coconut milk platforms address lactose-intolerant cohorts in Germany and flexitarian demand across northern Europe. |
| EFSA Novel Food Dossier Pre-Submission | Early toxicological documentation for alternative sweeteners and plant proteins compresses European launch windows by six to nine months. |
| Cold-Chain Infrastructure Partnership | Diesel-dependent reefer redundancy investments in São Paulo and Rio de Janeiro metropolitan corridors reduce last-mile melt risk. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary conversations engaged brand managers at multinational conglomerates, category buyers at United States convenience store chains, supply planners at Chinese dairy processors, and channel sales heads at European retail networks. Secondary validation drew from FDA nutrition labeling filings, EFSA novel food dossier registries, SAMR GB standard publications, and Nielsen retail audit data for frozen dessert velocity. Bottom-up SKU-level modeling and top-down category sizing triangulated volume and value estimates.
Comparable-period anchoring tied projection assumptions to historical reference points across the analysis window. Segmentation dimensions modeled included product format, flavor profile, packaging type, distribution channel, and regional regulatory cluster. CAGRs were derived from trend extrapolation of velocity patterns and input cost trajectories. Forecast inputs incorporated cold-chain density indices and clean-label compliance threshold evolution.
Caveats apply where dairy commodity volatility, regulatory harmonization delays, or cold-chain infrastructure gaps could materially shift the outlook. Forecasts reflect documented assumptions about household replenishment cycle stability and impulse traffic patterns at fuel-adjacent retail locations. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Vegan Frozen Pizza Market
Processed and Frozen Foods
Canned Vegetables Market
Processed and Frozen Foods
Asia-Pacific Frozen Food Market
Processed and Frozen Foods
South America Frozen Desserts Market
Processed and Frozen Foods
Deli Meat Market
Processed and Frozen Foods
Spiral Freezer Market
Processed and Frozen Foods
Asia Pacific Freeze Dried Product Market
Processed and Frozen Foods
Frozen Soup Market
Processed and Frozen Foods
Europe Frozen Finger Chips Market
Processed and Frozen Foods
Kimchi Market
Processed and Frozen Foods
Frozen Food Market
Processed and Frozen Foods
North America Freeze Dried Products Market
Processed and Frozen Foods
Freeze Dried Mangos Market
Processed and Frozen Foods
Scandinavia Frozen Food Market
Processed and Frozen Foods
United States Frozen Yogurt Market
Processed and Frozen Foods
North America Dehydrated Food Market