
 Chilled Processed Food Market | 2026-2036
Chilled Processed Food Market Size, Share, and Industry Trends Forecast 2026-2036
Chilled Processed Food Market Analysis
Aftermarket cold-chain logistics revenue is reshaping margin distribution across the chilled processed food value chain, pulling profitability away from manufacturing toward temperature-controlled distribution and last-mile delivery services. Nestle SA leverages its refrigerated distribution network to sustain direct-to-retailer channel control in European markets. JBS S.A. anchors its chilled meat processing dominance through integrated slaughter-to-case-ready operations across Brazil and North America. Tyson Foods Inc. differentiates via antibiotic-free chilled poultry lines that command shelf-space premiums in US supermarket channels.
Chilled processed food comprises perishable items preserved through continuous refrigeration at temperatures between 0°C and 4°C, utilizing pasteurization, modified atmosphere packaging, or mild preservation to inhibit microbial growth while maintaining sensory quality. Ready-to-eat meals represent the largest product type segment, though chilled snacks are gaining velocity among time-constrained retail consumers seeking protein-forward alternatives to ambient shelf-stable options. Modified atmosphere packaging commands disproportionate margin contribution due to its shelf-life extension properties and premium positioning against conventional plastic containers. Food service providers constitute the fastest-growing end-user channel as restaurants and institutional caterers outsource meal preparation to reduce labor overhead and kitchen footprint.
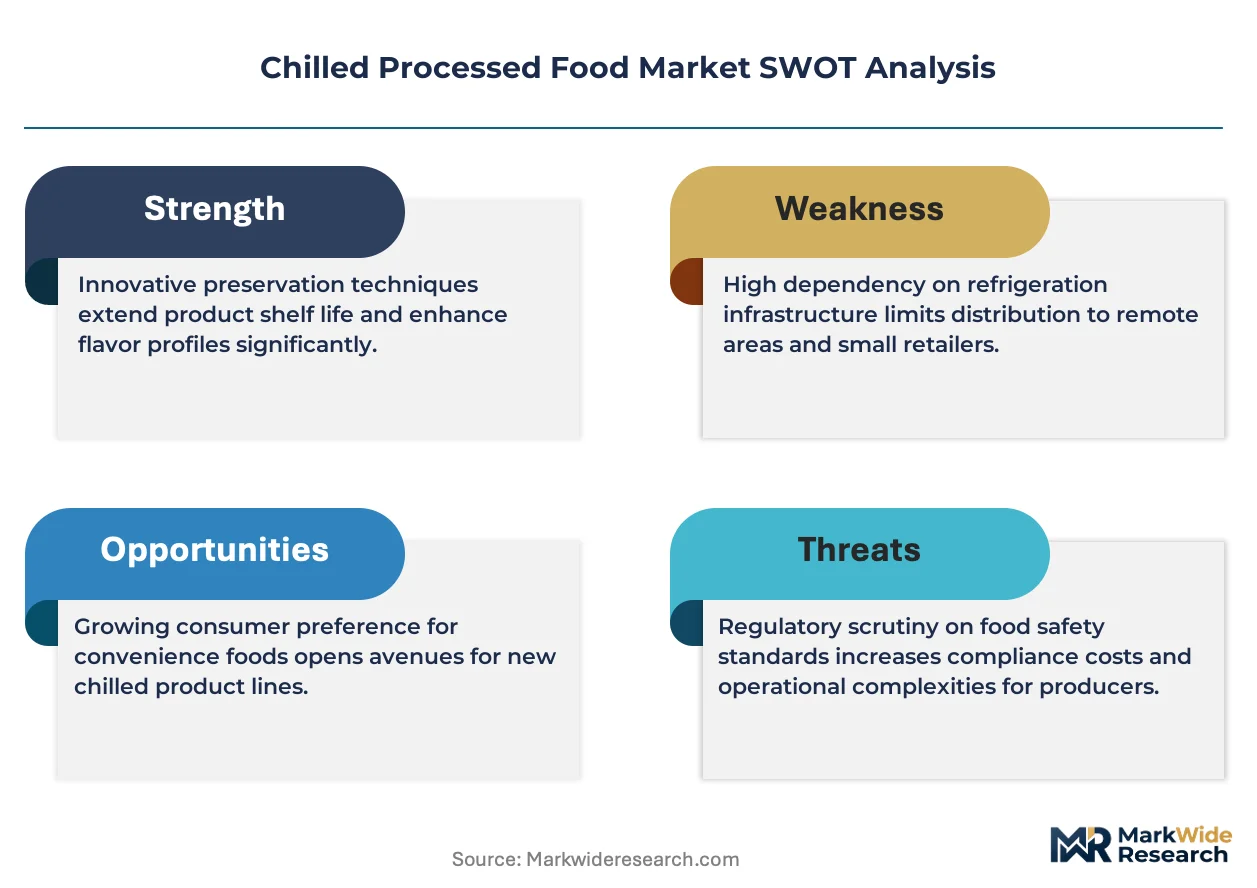
The FDA enforces Listeria monocytogenes control regulations for refrigerated ready-to-eat foods through its Food Safety Modernization Act framework, mandating environmental monitoring and corrective action protocols that elevate compliance costs for smaller processors. The USDA's Food Safety and Inspection Service oversees chilled meat and poultry labeling standards, including safe handling instructions and organic certification claims that influence consumer purchase decisions. EFSA's scientific opinions on clean-label preservatives are reshaping formulation strategies for European chilled product lines. Stakeholders must monitor evolving cold-chain energy standards and refrigerant phase-down schedules as regulatory pressure intersects with operational cost structures.
Market Dynamics
Cold-chain energy standards and refrigerant phase-down schedules are compressing operating margins across chilled processed food manufacturing while redistributing value toward temperature-controlled logistics providers capable of capitalizing on compliance infrastructure.
Growth Catalysts
- Food Safety Modernization Act environmental monitoring mandates:The FDA's Listeria control protocols are forcing facility upgrades that favor large-scale processors with capital reserves, accelerating consolidation among ready-to-eat meal manufacturers.
- Modified atmosphere packaging shelf-life extension:Nitrogen and carbon dioxide gas-flushing technologies are enabling longer distribution radii for chilled meat processors seeking retail placement beyond regional catchments.
- Food service labor cost pressures:Restaurants and institutional caterers are outsourcing meal preparation to reduce kitchen headcount and real estate footprint, pulling volume through chilled ready-to-eat channels.
Market Restraints
- Refrigerant input cost volatility:Hydrofluorocarbon phase-down schedules under the EPA's AIM Act are spiking retrofit costs for aging processing facilities dependent on legacy cooling systems.
- Supply concentration in Brazilian beef slaughter capacity:Integrated processors controlling captive cattle supply are limiting independent chilled meat packers' access to raw material at competitive clearing prices.
- Substitution threat from flash-frozen alternatives:Individual quick freezing technologies are narrowing the sensory quality gap with chilled products while offering superior logistics flexibility and waste reduction.
Strategic Opportunities
- Direct-to-retailer channel bypass:Processor-owned refrigerated fleets are enabling shelf-space negotiation leverage against traditional wholesale distributors in consolidated supermarket chains.
- EFSA clean-label preservative approvals:Emerging natural antimicrobial formulations are opening reformulation pathways for European chilled lines seeking to displace artificial additives without shelf-life penalty.
- Antibiotic-free certification premium capture:USDA Process Verified shield programs are creating price stratification opportunities in poultry and pork segments where retail buyers differentiate on animal welfare claims.
Industry Challenges
- Environmental monitoring technician scarcity:FDA-mandated sampling protocols require specialized microbiology personnel that smaller processors struggle to recruit and retain at competitive compensation.
- Cold-chain integration complexity:Legacy ERP systems at food service distributors lack real-time temperature traceability APIs, forcing manual reconciliation with processor logistics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chilled Processed Food Market |
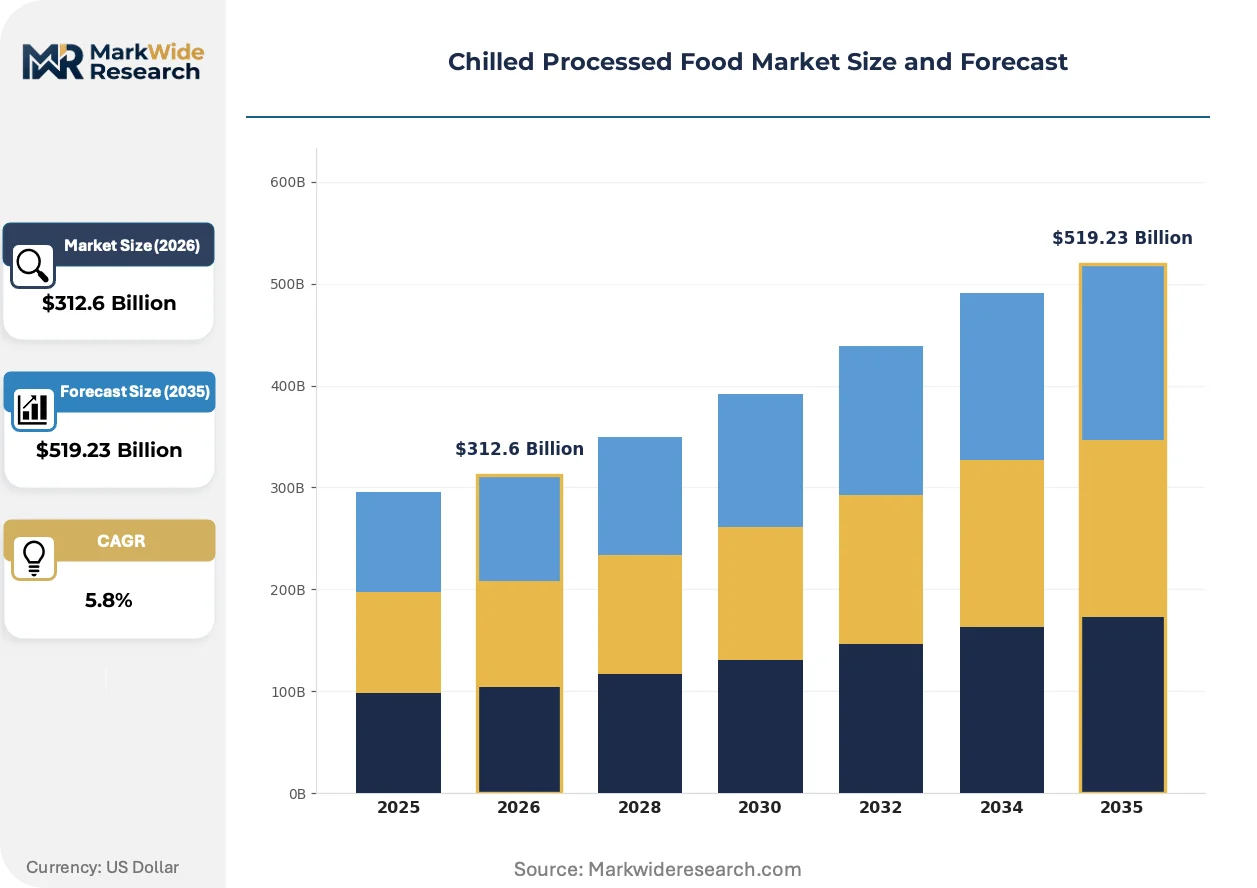
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $519.23 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
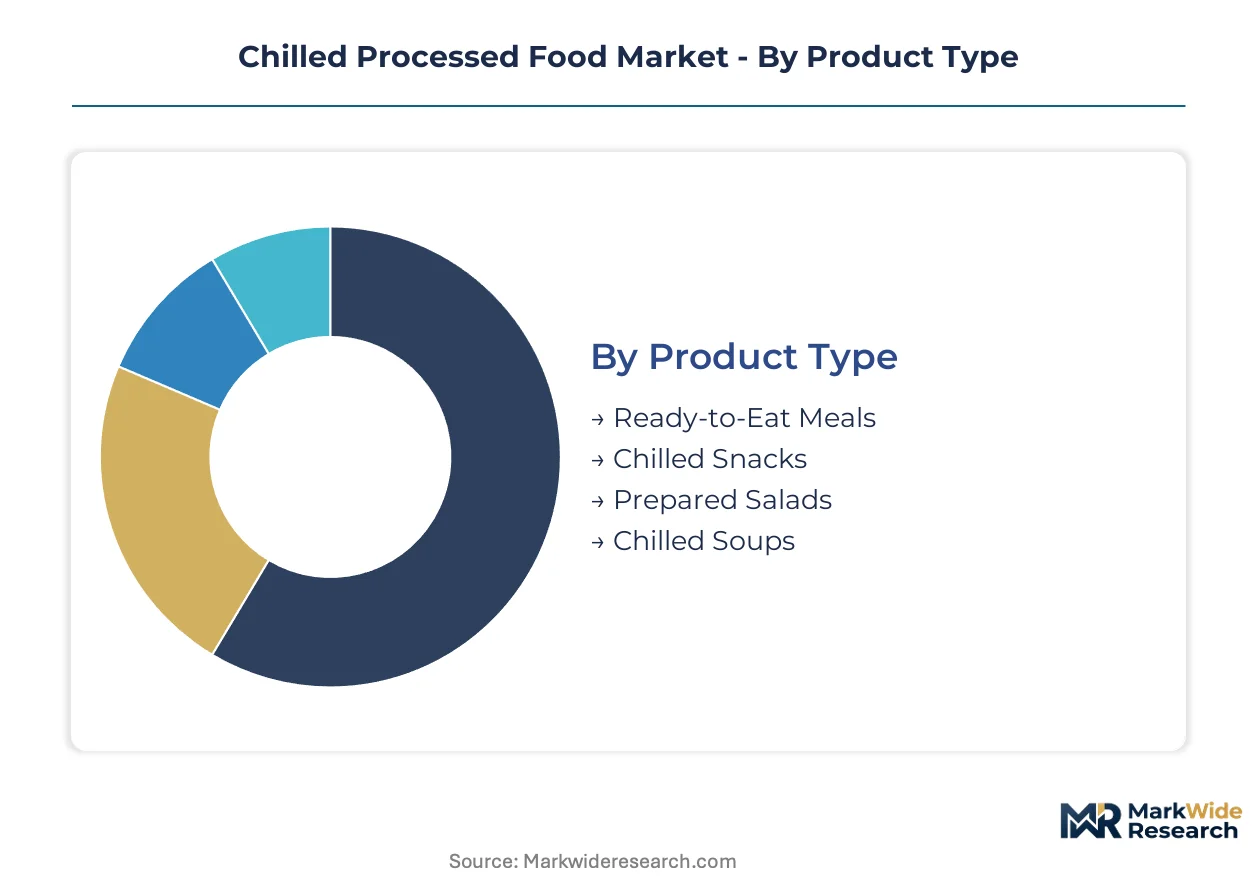
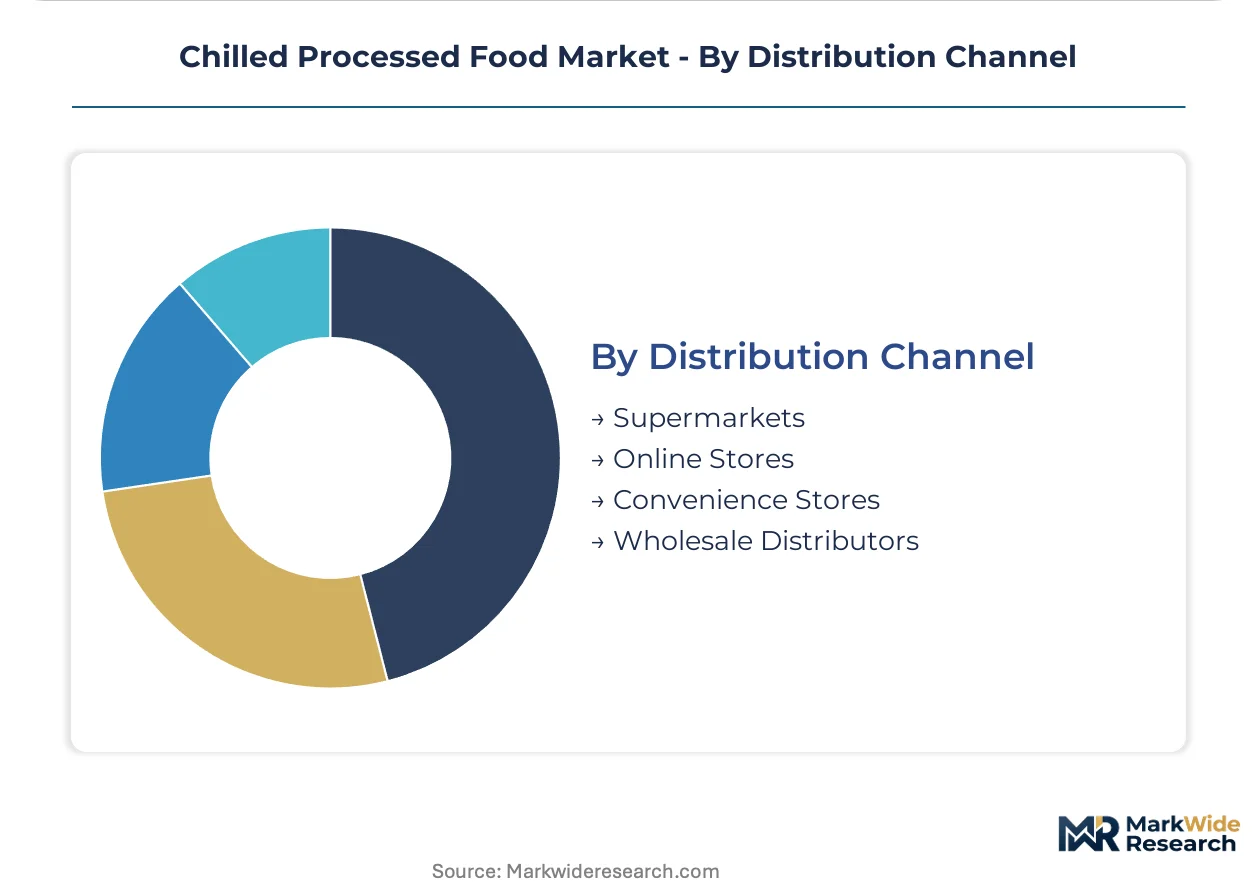
| Segmentation | Product Type: Ready-to-Eat Meals, Chilled Snacks, Prepared Salads, Chilled Soups End User: Retail Consumers, Food Service Providers, Institutions, Caterers Packaging Type: Plastic Containers, Vacuum Packs, Glass Jars, Modified Atmosphere Packaging Distribution Channel: Supermarkets, Online Stores, Convenience Stores, Wholesale Distributors |
| Companies Covered | Tyson Foods Inc., General Mills, Inc., Nestle SA, Mondelez International Inc., Hormel Foods Corporation, Kraft Heinz Company, JBS S.A., Ajinomoto Co. Inc., Conagra Brands, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chilled Processed Food Market Emerging Trajectories
Refrigeration chemistry, packaging barrier technology, and retail distribution economics are converging to redefine competitive advantage in temperature-controlled food preservation.
High-barrier ethylene vinyl alcohol films are migrating from premium organic meat applications toward mainstream chilled poultry and prepared meal segments. Mid-market retailers in Germany and France are adopting these structures to reduce shrinkage from premature spoilage. The technology is migrating from niche premium positioning toward standard shelf-life expectations, compressing margin premiums previously captured by early movers.
The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is forcing processor facility retrofits toward ammonia or carbon dioxide cascade systems. Capital expenditure requirements are filtering facility ownership toward entities with balance sheet capacity for multi-year payback periods. Chilled ready-to-eat manufacturers in California and Texas are most affected, with several accelerating consolidation timelines to access parent-company infrastructure.
Food service procurement is consolidating volume through group purchasing organizations that negotiate directly with processor national accounts teams. Distributor sales representatives are losing category management authority as institutional buyers centralize specification-setting and price benchmarking functions. This concentration is most visible in US healthcare and education catering contracts, where annual bid cycles now dominate chilled meal sourcing.
Chilled Processed Food Market Segmentation
Cold-chain service intensity varies sharply across chilled processed food segments, driving margin redistribution toward temperature-controlled logistics providers and reshaping procurement economics for manufacturers and distributors alike.
Product Type:
After-sales cold-chain service intensity peaks with temperature-sensitive formulations requiring continuous refrigeration integrity from production through consumption.
- Ready-to-Eat Meals:Complete protein-carbohydrate-vegetable combinations pasteurized and packaged under modified atmosphere for shelf-life extension. US supermarket chains and European convenience retailers concentrate procurement here as labor costs drive outsourcing of scratch cooking operations.
- Chilled Snacks:Protein-forward portable formats including sliced meats, cheese combinations, and hummus packs targeting time-constrained commuters. German and French retail channels are expanding facings for these items as consumers seek alternatives to ambient shelf-stable options.
- Prepared Salads:Leafy greens with protein toppings in high-barrier packaging.
- Chilled Soups:Pasteurized liquid formats in refrigerated retail cases.
Ready-to-Eat Meals holds the largest share; momentum sits with Chilled Snacks.
End User:
Cost tier stratification separates premium retail purchasers from volume-driven institutional buyers with divergent specifications for shelf-life, labeling, and delivery frequency.
- Retail Consumers:Individual households purchasing through supermarket and online channels with preference for clean-label claims and premium positioning. US coastal metropolitan markets and UK urban centers show strongest uptake of antibiotic-free and organic certified lines.
- Food Service Providers:Restaurants, cafes, and quick-service operators outsourcing meal components to reduce kitchen labor and real estate footprint. This channel is expanding most quickly as US healthcare and education caterers centralize procurement through group purchasing organizations.
- Institutions:Hospitals, nursing facilities, and correctional operations with standardized nutritional requirements.
- Caterers:Event and corporate dining services requiring batch-consistent quality at scale.
Retail Consumers dominate absolute volume; Food Service Providers are climbing the fastest.
Packaging Type:
Application requirements dictate barrier specifications, with high-value proteins and prepared meals demanding oxygen exclusion that commodity formats cannot deliver.
- Modified Atmosphere Packaging:Nitrogen and carbon dioxide gas-flushed enclosures extending chilled shelf-life by suppressing aerobic microbial growth. European organic meat processors and US poultry packers command price premiums through this technology, which is migrating from niche positioning toward mainstream retail expectation.
- Vacuum Packs:Oxygen-evacuated flexible films for protein preservation with minimal headspace. Brazilian and Australian beef exporters rely on this format for ocean freight distribution to Asian retail markets.
- Plastic Containers:Standard polypropylene and PET rigid formats for prepared meals and salads.
- Glass Jars:Premium-positioned containers for chilled soups and specialty sauces.
Modified Atmosphere Packaging captures the highest margin contribution; Vacuum Packs show steepest expansion trajectory in export-oriented protein segments.
Distribution Channel:
Geographic concentration of refrigerated infrastructure favors channels with captive cold-chain assets in dense urban catchments.
- Supermarkets:Full-service retail operators controlling refrigerated display case footage and category management authority. US consolidated chains and German discount retailers wield procurement leverage through direct processor negotiations, bypassing traditional wholesale intermediaries.
- Online Stores:E-commerce platforms with last-mile refrigerated delivery capability. UK and South Korean urban markets demonstrate strongest penetration as consumers accept premium delivery fees for temperature-integrity guarantees.
- Convenience Stores:Limited-assortment urban formats with restricted refrigerated space.
- Wholesale Distributors:Traditional broadline operators serving independent restaurants and institutions.
Supermarkets retain the largest share; Online Stores are gaining share fastest in metropolitan corridors with mature cold-chain logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail buyers in Germany and France absorb premium pricing for clean-label chilled products, while Brazilian food service operators remain acutely price-sensitive to commodity beef fluctuations. This elasticity divergence shapes where processors deploy high-margin versus volume-focused portfolios.
United States
Coastal metropolitan households drive antibiotic-free poultry uptake through supermarket direct procurement. The FDA's Listeria monocytogenes compliance guidelines mandate environmental monitoring protocols that elevate facility costs. Chicago and Dallas processing clusters are consolidating under parent-company infrastructure to access capital for refrigeration retrofits.
Germany
Discount retailers expand chilled snack facings as commuters seek protein-forward alternatives. The EFSA clean-label preservative framework is reshaping formulation strategies for organic meat lines. The Rhine-Ruhr industrial corridor hosts modified atmosphere packaging specialists serving pan-European distribution networks.
Brazil
Integrated slaughter-to-case-ready operations dominate domestic and export chilled meat supply. ANVISA sanitation protocols align with USDA equivalency requirements for North American market access. São Paulo state processors control captive cattle supply, limiting independent packers' raw material access.
Japan
Convenience store chains demand extended shelf-life chilled meals for dense urban catchments. The Ministry of Health, Labour and Welfare enforces strict cold-chain integrity standards for ready-to-eat products. The Kanto region around Tokyo concentrates high-barrier packaging innovation for premium retail channels.
United Kingdom
Online grocery platforms with last-mile refrigerated capability penetrate London and Southeast England metropolitan markets. The Food Standards Agency enforces traceability requirements that elevate ERP system investments. Midlands processing facilities serve group purchasing organizations consolidating healthcare and education catering contracts.
Chilled Processed Food Market Vendor Landscape
Vertically integrated protein conglomerates and diversified multinational food manufacturers split the market between volume-driven commodity supply and premium branded positioning. Consolidation favors entities with balance sheet capacity for cold-chain infrastructure and regulatory compliance. Three archetypes dominate: slaughter-integrated meat processors controlling captive supply, refrigerated distribution network owners sustaining direct retailer relationships, and brand portfolio managers leveraging clean-label certification premiums. Competitive intensity centers on M&A to acquire regional cold-chain assets and backward integration into primary protein production.
Within the integrated processor tier, Tyson Foods Inc. and JBS S.A. exemplify scale-driven supply control, while Nestle SA occupies a position as the diversified multinational archetype with European refrigerated distribution leverage. These three entities represent contrasting strategic foundations: US poultry vertical integration, Brazilian-North American beef slaughter dominance, and European direct-to-retailer channel ownership.
| Leading Market Players |
|---|
| Tyson Foods Inc. |
| General Mills, Inc. |
| Nestle SA |
| Mondelez International Inc. |
| Hormel Foods Corporation |
| Kraft Heinz Company |
| JBS S.A. |
| Ajinomoto Co. Inc. |
| Conagra Brands, Inc. |
| Others |
Supply Flow & Price Mechanics
Refrigerant phase-down schedules under the EPA's AIM Act compress operating margins unevenly across processor tiers, widening spreads between ammonia-retrofitted facilities and legacy HFC-dependent plants while forcing geographic consolidation toward capital-rich parent-company infrastructure. This regulatory chokepoint simultaneously elevates cold-chain logistics premiums and reshapes procurement geography as smaller manufacturers exit or sell.
Pricing Analysis
After-sales cold-chain service revenue drives lifetime value capture for temperature-controlled logistics providers serving processor networks. Three-tier pricing structure across premium certified-organic, standard case-ready, and economy private-label levels stratifies the market, with USDA Process Verified and EFSA clean-label certifications commanding shelf-space premiums. Pricing pressure stems from flash-frozen substitution narrowing sensory quality gaps at lower logistics cost. Food service group purchasing organizations exhibit highest price sensitivity, while coastal metropolitan retail consumers absorb premiums for antibiotic-free claims.
Supply Chain Analysis
Export-control regimes on high-barrier packaging films and natural antimicrobial formulations limit technology transfer to emerging processor markets, constraining clean-label reformulation pathways. Supply concentrates in Brazil for integrated beef slaughter-to-case-ready operations, the United States for poultry vertical integration, and Germany for modified atmosphere packaging equipment. Raw material dependencies include captive cattle supply, nitrogen and carbon dioxide gas systems, and ethylene vinyl alcohol barrier films. Single-source vulnerability sits with Brazilian integrated processors controlling export-grade chilled meat supply. Distribution runs through processor-owned refrigerated fleets bypassing traditional wholesale intermediaries in consolidated supermarket chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chilled processed food markets approach a platform-economics inflection as group purchasing organizations consolidate procurement authority and real-time temperature traceability APIs enable direct processor-retailer data exchange, collapsing traditional distributor margins.
For Market Incumbents: Pre-empt flash-frozen substitution threats by accelerating high-barrier packaging deployment across mid-market poultry and prepared meal lines. Consolidate regional processing capacity under parent-company infrastructure to access ammonia refrigeration retrofit capital. Defend shelf-space positioning through direct-to-retailer refrigerated fleet investments that bypass wholesale intermediaries. For New Entrants and Emerging Players: Mid-market chilled snack production for German and French commuter retail represents the most penetrable entry point, as discount retailers expand facings for protein-forward portable formats. Online grocery platforms in UK metropolitan corridors with last-mile refrigerated capability offer secondary white-space for premium-positioned prepared salads. Go-to-market through group purchasing organization subcontracting relationships bypasses direct supermarket slotting fee barriers. For Investors and Strategic Acquirers: FDA's updated Listeria monocytogenes compliance guidelines reshape the acquisition landscape by elevating environmental monitoring infrastructure requirements that favor scaled processors. Long-term viability centers on entities with balance sheet capacity for multi-year refrigeration chemistry transitions and captive cold-chain assets. Target acquisition archetype: regional ready-to-eat meal manufacturers with underutilized modified atmosphere packaging lines and pending parent-company consolidation timelines. Signal to monitor: EPA refrigerant phase-down enforcement acceleration in California and Texas processing clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigeration Retrofit Consolidation | Parent-company infrastructure access enables AIM Act compliance without standalone capital burden. |
| Direct-to-Retailer Fleet Investment | Processor-owned refrigerated trucks bypass wholesale distributors in Kroger and Albertsons negotiations. |
| Clean-Label Reformulation Partnership | EFSA-approved natural antimicrobial collaborations displace artificial preservatives in European organic lines. |
| Group Purchasing Organization Integration | US healthcare and education catering contracts centralize volume through annual bid cycles. |
| High-Barrier Packaging Scale-Up | Ethylene vinyl alcohol film migration reduces shrinkage for German discount retailers. |
Methodological Framework
Cross-validation between primary interviews with cold-chain logistics operators and secondary validation through FDA enforcement action databases anchors the qualitative findings. Processor facility managers, supermarket category buyers, food service procurement directors, and refrigerated transport fleet operators provided operational perspective. Bottom-up capacity modeling triangulated against top-down retail scanner data from Nielsen and customs trade records for chilled meat and prepared meal flows.
Calibration against historical facility consolidation patterns and refrigerant retrofit expenditure disclosures shaped the projection framework. Segmentation dimensions span product type, packaging technology, end-user channel, and regional cold-chain maturity across the modeling period. CAGRs derived from elasticity-adjusted volume projections incorporating substitution effects from flash-frozen alternatives and labor cost-driven food service outsourcing trends.
Macroeconomic conditions sit as an overlay; deviation in protein commodity prices, energy costs for refrigeration operations, or regulatory enforcement timelines would shift the trajectory. Forecasts reflect assumptions on cold-chain infrastructure investment continuity and clean-label certification adoption rates. Material shifts in EPA AIM Act implementation pace or EFSA preservative approval timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Middle East and Africa Frozen Food Market
Processed and Frozen Foods
Frozen Dumplings Market
Processed and Frozen Foods
Popsicle Market
Processed and Frozen Foods
Dumplings Market
Processed and Frozen Foods
GCC Frozen Finger Chips Market
Processed and Frozen Foods
Frozen Novelty Market
Processed and Frozen Foods
Cold Cuts Market
Processed and Frozen Foods
Frozen Potato Market
Processed and Frozen Foods
Vegan Frozen Food Market
Processed and Frozen Foods
Vegan Frozen Pizza Market
Processed and Frozen Foods
Ice Cream and Frozen Dessert Market
Processed and Frozen Foods
Chilled Meal Kits Market
Processed and Frozen Foods
Frozen Chicken Market
Processed and Frozen Foods
Frozen Noodles and Rice Products Market
Processed and Frozen Foods
Frozen Pizza Market
Processed and Frozen Foods
Ice Structuring Protein Market