
 IQF Food Products Market | 2026-2036
IQF Food Products Market Size, Share, and Industry Trends Forecast 2026-2036
IQF Food Products Market Insights
The EU Green Deal's farm-to-fork sustainability targets is expanding scrutiny of food preservation methods across European supply chains. Nestle leverages its vertically integrated frozen vegetable sourcing networks to secure consistent raw material flows. McCain Foods Limited anchors North American potato and vegetable IQF capacity through large-scale processing plants in Canada and the United States. Ajinomoto Co. Inc. competes in Asian seafood and prepared vegetable segments with specialized blast-freezing technology.
Individual quick freezing (IQF) subjects discrete food pieces to cryogenic or mechanical freezing at temperatures below minus thirty degrees Celsius, producing non-agglomerated units that retain cellular structure and nutritional content upon reconstitution. The process serves commercial buyers requiring portion-controlled ingredients with extended shelf stability and minimal thaw loss. Fruits and vegetables occupy mature volume positions where retail private-label competition compresses margins, while seafood commands premium positioning due to stringent catch-to-freeze traceability requirements. The food service end user segment leads growth as hotel and restaurant chains adopt IQF proteins and produce to standardize preparation times and reduce spoilage.
The U.S. FDA enforces Hazard Analysis Critical Control Point protocols for frozen food manufacturing, while the EU's REACH framework governs cryogenic refrigerant chemistry in European processing facilities. China's SAMR implements national food safety standards for frozen aquatic products that affect import eligibility and domestic production licensing. Stakeholders must monitor evolving refrigerant phase-down schedules and regional cold-chain energy regulations to anticipate compliance costs and equipment replacement cycles.
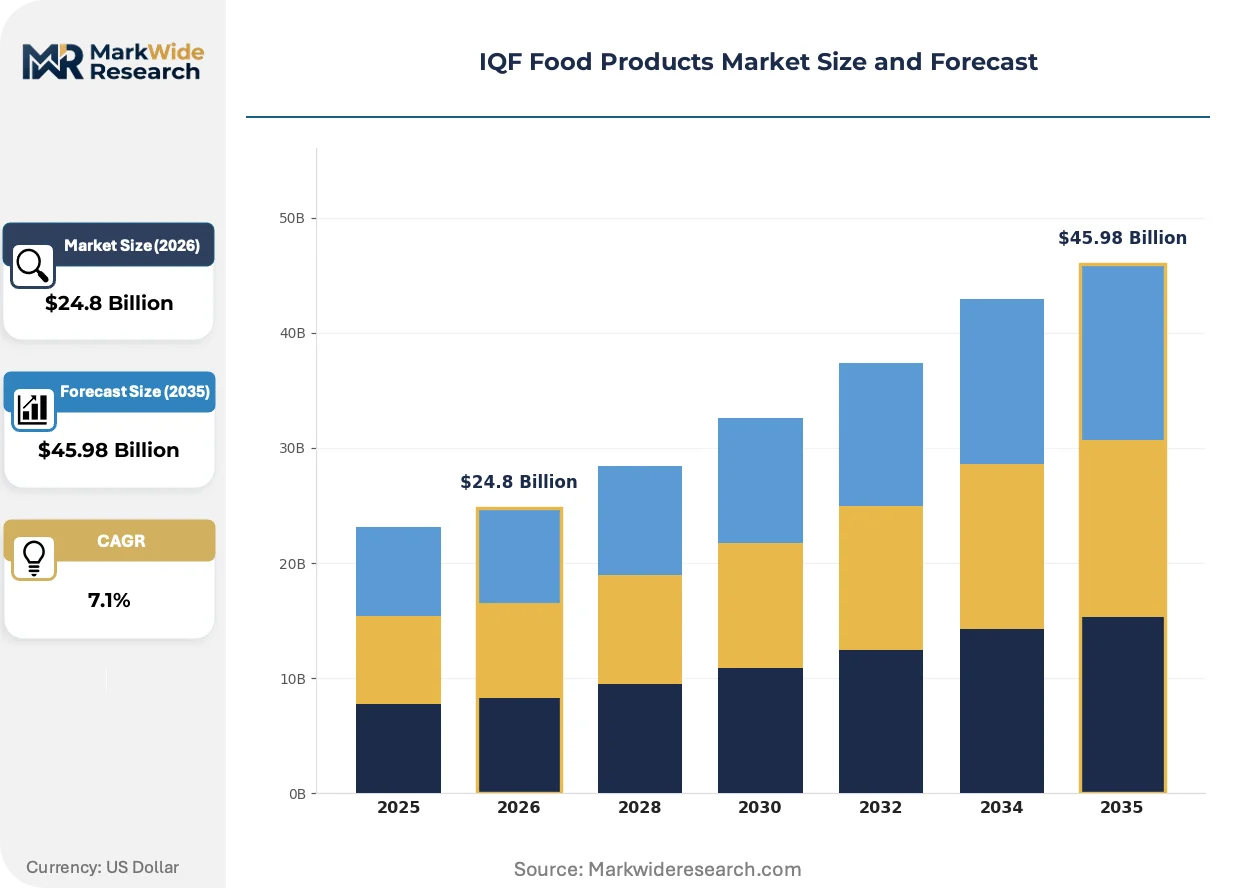
Market Dynamics
Quick-service restaurant chains are consolidating frozen ingredient procurement to compress kitchen labor costs and minimize spoilage, while tightening cold-chain documentation requirements from the U.S. FDA and China's SAMR are forcing processors to upgrade traceability infrastructure.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Sustainability mandates across European supply chains are favoring IQF preservation methods that extend shelf life without chemical additives, redirecting procurement toward verified low-waste suppliers.
- Blast-freezing technology maturation:Cryogenic and mechanical systems operating below minus thirty degrees Celsius now achieve cellular preservation at throughput rates that support commercial-scale discrete-piece processing.
- China cold storage modernization:Urban infrastructure upgrades in tier-one and tier-two cities are reducing distribution losses and enabling convenience-oriented meal solutions for time-constrained consumers.
Market Restraints
- Refrigerant chemistry constraints:The EU's F-Gas Regulation phase-down schedules are forcing processors to replace existing cryogenic systems ahead of planned depreciation cycles, elevating capital intensity.
- Catch-to-freeze traceability costs:Seafood IQF segments face disproportionate documentation burdens as China's SAMR and the U.S. FDA impose parallel but non-harmonized documentation standards on import eligibility.
- Energy price volatility:Cold-chain operations remain exposed to electricity and natural gas input swings that compress margins in mechanical freezing facilities.
Strategic Opportunities
- India cold-chain underpenetration:Domestic frozen food consumption remains concentrated in coastal metros, creating expansion room as FSSAI licensing frameworks formalize and retail modern trade penetrates secondary cities.
- Prepared vegetable convergence:IQF processors can capture value from meal-kit assembly lines by supplying pre-portioned, non-agglomerated vegetable units that reduce downstream preparation labor.
- Hotel chain standardization mandates:Procurement centralization among international hospitality groups is creating volume commitments for consistent-quality IQF proteins that withstand reconstitution without texture degradation.
Industry Challenges
- Cryogenic equipment technician scarcity:Specialized maintenance capabilities for sub-minus-thirty-degree mechanical systems remain concentrated among legacy equipment vendors, elevating downtime risk for mid-scale processors.
- Dual certification timelines:Simultaneous compliance with U.S. FDA Hazard Analysis Critical Control Point protocols and EU REACH refrigerant documentation is stretching quality assurance bandwidth at export-oriented facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IQF Food Products Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $45.98 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Seafood, Meat End User: Retailers, Food Service, Manufacturers, Wholesalers Packaging Type: Bags, Boxes, Trays, Pouches Distribution Channel: Online, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Nestle, Seenergy Foods, McCain Foods Limited, Ajinomoto Co. Inc., Rich Products Corporation, General Mills Inc., The Kraft Heinz Company, Schwan’s Company, Conagra Brands, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IQF Food Products Market Trends and Innovations
Automation and digitization are compressing freezing cycle times while embedding traceability at the unit level, reshaping how processors balance throughput against documentation burdens.
Cryogenic tunnel freezing systems are integrating nitrogen and carbon dioxide injection controls with real-time temperature telemetry to maintain discrete-piece separation throughout the freezing curve. Large-scale vegetable processors in Canada and the United States are retrofitting mechanical lines with these hybrid systems to reduce thaw loss rates. The technology is integrating quality assurance workflows into continuous production, eliminating batch-release delays that previously constrained daily throughput ceilings.
The EU's updated F-Gas Regulation is accelerating refrigerant transition timelines for cryogenic processing facilities across Germany, France, and Poland. Industrial operators face compressed windows to replace hydrofluorocarbon-based systems with ammonia or transcritical CO2 alternatives without interrupting seasonal harvest processing. Seafood IQF segments bear disproportionate compliance costs because their lower-volume, higher-SKU production profiles complicate equipment standardization.
Centralized procurement desks at multinational hospitality groups are displacing distributed local purchasing for frozen ingredients, consolidating supplier relationships around vendors with multi-continent certification coverage. This concentration favors processors with vertically controlled cold chains from raw material intake through port loading. The shift is most visible in Southeast Asian hotel markets where international brand standards override traditional wet-market sourcing patterns.
IQF Food Products Market Segmentation
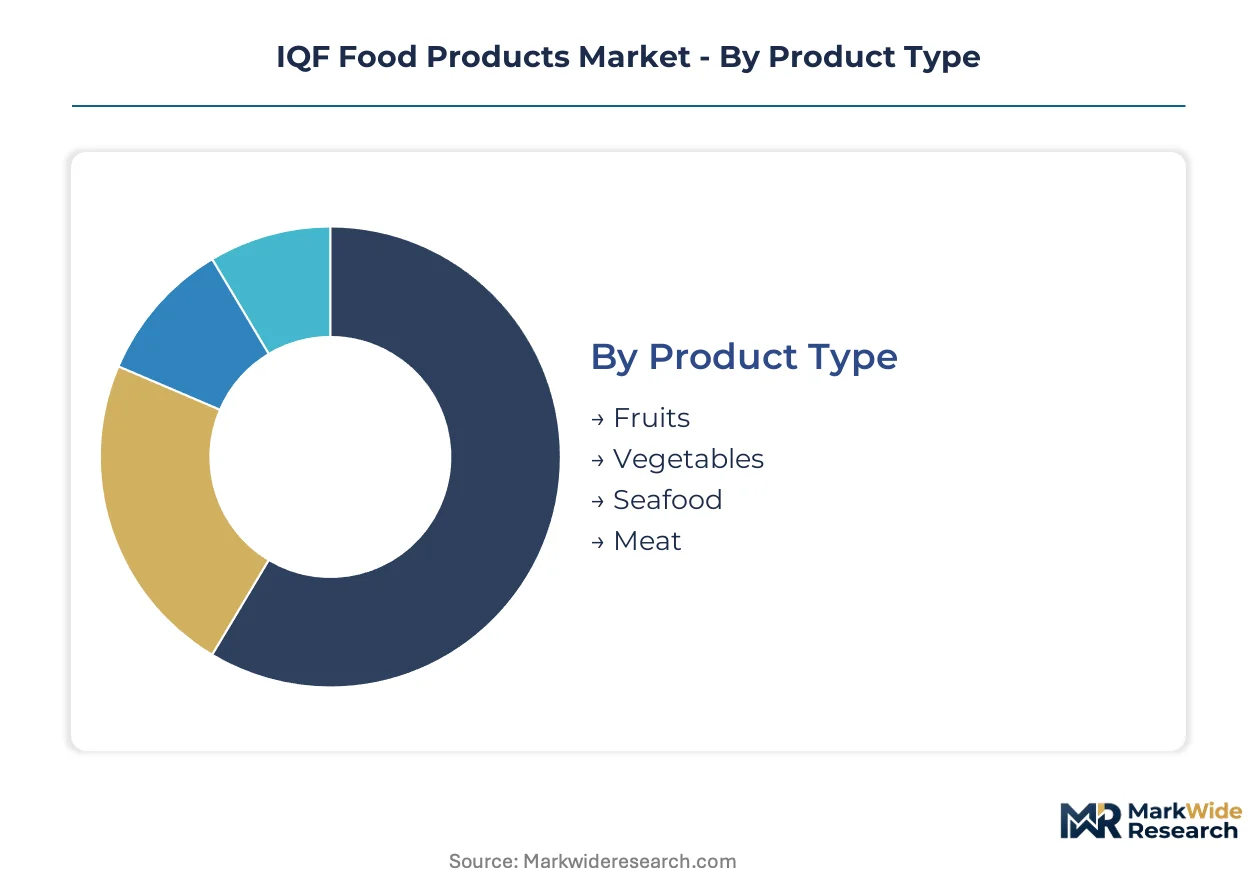
IQF processors configure production lines around discrete-piece handling requirements that vary sharply by raw material density and thermal conductivity. Segmentation discipline determines capital allocation between cryogenic tunnel systems for delicate fruits versus mechanical spiral freezers for dense protein cuts.
Product Type:
Purchase volume concentrates where catch-to-freeze traceability mandates elevate compliance costs and reward scale.
- Seafood:Blast-freezing at sub-minus-thirty temperatures preserves cellular integrity for high-value species requiring documentation from vessel to retail case. Chinese SAMR import eligibility rules and U.S. FDA HACCP protocols impose parallel certification burdens that favor processors with dedicated cold-chain infrastructure.
- Vegetables:Mature procurement relationships with quick-service restaurant chains drive volume, though retail private-label competition compresses margins. Nestle's vertically controlled sourcing networks demonstrate how backward integration into agricultural intake secures consistent raw material flows.
- Fruits:Seasonal harvest windows require flexible processing capacity that smaller regional operators supply to smoothie and bakery ingredient buyers.
- Meat:Portion-controlled poultry and beef units serve hotel chain central kitchens seeking preparation standardization across properties.
Vegetables leads on scale; seafood leads on momentum.
End User:
Operational complexity separates buyers with in-house cold storage from those dependent on third-party logistics.
- Food Service:Hotel and restaurant chains adopt IQF proteins and produce to compress kitchen labor and reduce spoilage. Procurement centralization among international hospitality groups is consolidating supplier relationships around vendors with multi-continent certification coverage.
- Retailers:Private-label frozen vegetable programs demand consistent quality at price points that strain processor margins. Supermarket chains in China are expanding frozen SKUs as urban consumers shift toward convenience-oriented meal solutions.
- Manufacturers:Meal-kit assembly lines source pre-portioned vegetable units that reduce downstream preparation labor.
- Wholesalers:Distributor networks in India remain concentrated in coastal metros, with FSSAI licensing frameworks gradually formalizing secondary city penetration.
Food service dominates current volume; retailers are gaining share fastest.
Packaging Type:
Thermal mass and shelf-visibility requirements dictate material selection across temperature zones.
- Bags:Flexible polyethylene structures dominate high-volume vegetable shipments to food service distributors. The format minimizes shipping cube and accommodates irregular product shapes.
- Trays:Rigid presentation packaging serves retail seafood segments where consumer inspection drives purchase decisions.
- Boxes:Corrugated containment for bulk institutional deliveries withstands pallet stacking in distribution centers.
- Pouches:Stand-up formats with resealable closures target household convenience in Asian urban markets.
Bags command the steepest expansion trajectory; trays hold premium positioning.
Distribution Channel:
Cold-chain reliability requirements filter channel viability by geography and product value density.
- Distributors:Specialized frozen food wholesalers maintain temperature-controlled fleets that link processors to fragmented food service accounts. McCain Foods leverages this channel to anchor North American potato and vegetable IQF capacity.
- Supermarkets:Modern trade penetration in China's tier-one and tier-two cities is reducing distribution losses and enabling convenience-oriented meal solutions.
- Online:Direct-to-consumer frozen delivery remains constrained by last-mile temperature maintenance costs.
- Specialty Stores:Ethnic and organic retailers stock premium seafood and fruit varieties with shorter production runs.
Distributors anchor volume throughput; supermarkets show the strongest growth curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cryogenic technicians concentrate in established processing hubs across Germany, the United States, China, Canada, and India, anchoring regional capacity expansion.
United States
Quick-service restaurant chains consolidate frozen vegetable procurement to compress kitchen labor costs. The FDA enforces Hazard Analysis Critical Control Point protocols that mandate upgraded traceability infrastructure. Large-scale processing plants in Idaho and Washington state anchor North American potato and vegetable IQF capacity.
China
Urban consumers in tier-one and tier-two cities shift toward convenience-oriented meal solutions. The SAMR implements national food safety standards for frozen aquatic products affecting import eligibility. Cold storage infrastructure modernization in Shanghai and Guangzhou reduces distribution losses.
Germany
Processors face compressed windows to replace hydrofluorocarbon-based cryogenic systems with ammonia alternatives. The EU's updated F-Gas Regulation accelerates refrigerant transition timelines. Industrial operators in Lower Saxony and Bavaria retrofit mechanical lines with hybrid cryogenic tunnel systems.
Canada
Hotel and restaurant chains adopt IQF proteins to standardize preparation times across properties. Health Canada maintains frozen food safety guidelines parallel to U.S. protocols. McCain Foods anchors North American capacity through processing plants in New Brunswick and Manitoba.
India
Domestic frozen food consumption remains concentrated in Mumbai and Chennai, creating expansion room. The FSSAI licensing framework gradually formalizes secondary city penetration. Regional operators supply seasonal fruit processing to smoothie and bakery ingredient buyers in Karnataka and Maharashtra.
IQF Food Products Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the IQF food products sector. Vertically integrated multinationals with captive agricultural sourcing face pressure from specialized regional processors with flexible seasonal capacity. The market structure stratifies into three archetypes: diversified food conglomerates with frozen divisions, dedicated IQF specialists with blast-freezing technology, and private-label suppliers serving retail chains. Dominant competitive moves include backward integration into agricultural intake and multi-continent certification coverage for hospitality procurement desks.
Among diversified food conglomerates, Nestle and General Mills occupy positions exemplifying vertically controlled sourcing networks. McCain Foods Limited represents the dedicated IQF specialist archetype with large-scale North American processing infrastructure. Ajinomoto Co. Inc. sits within the Asia-Pacific specialist tier, competing in seafood and prepared vegetable segments.
| Leading Market Players |
|---|
| Nestle |
| Seenergy Foods |
| McCain Foods Limited |
| Ajinomoto Co. Inc. |
| Rich Products Corporation |
| General Mills Inc. |
| The Kraft Heinz Company |
| Schwan's Company |
| Conagra Brands, Inc. |
| Others |
Pricing and Supply Chain Analysis
Global vegetable price indices and seafood commodity benchmarks cascade through IQF supply chains into three distinct pricing tiers. Raw material volatility at the agricultural intake stage compresses margins for standard-grade processors while premium seafood segments absorb cost fluctuations through catch-to-freeze traceability premiums. The interaction between concentrated cold-chain infrastructure and buyer consolidation shapes pricing power across food service, retail, and manufacturing channels.
Pricing Analysis
Bundled cold-chain logistics services command premiums over unbundled product-only transactions. Contract pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale. Pricing pressure stems from retail private-label competition in mature vegetable segments. Food service buyers exhibit lowest price sensitivity due to preparation standardization requirements, while wholesale distributors face margin compression from energy price volatility.
Supply Chain Analysis
Specialty cryogenic equipment supply rests on German, Japanese, and American engineering clusters. IQF processors draw from concentrated sources of liquid nitrogen, mechanical refrigeration compressors, and food-grade packaging films. Single-source vulnerability in ammonia refrigerant supply creates exposure for European facilities facing F-Gas Regulation transition deadlines. Distribution runs through specialized frozen food wholesalers with temperature-controlled fleet networks linking processors to fragmented food service accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IQF food products market functions as a stable compounder anchored by quick-service restaurant procurement consolidation. Food service centralization drives steady volume growth with predictable contract renewal patterns.
For Market Incumbents: Deepen backward integration into agricultural intake to secure raw material flows against seasonal volatility. Expand multi-continent certification coverage to capture hospitality procurement desk consolidation. Threats include emerging regional blast-freezing specialists with flexible seasonal capacity and compressed refrigerant transition timelines elevating capital intensity. For New Entrants and Emerging Players: Direct-to-food-service digital platforms offer low-friction entry into procurement centralization trends. Target India's underpenetrated secondary cities where FSSAI licensing formalization creates first-mover advantages. Prepared vegetable convergence with meal-kit assembly lines represents the most penetrable application segment. For Investors and Strategic Acquirers: Asymmetric upside sits with dedicated IQF specialists possessing blast-freezing technology and established cold-chain infrastructure. Long-term viability favors processors with vertically controlled supply networks spanning raw material intake through port loading. Watch refrigerant phase-down acceleration as an inflection indicator for equipment replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Intake | Nestle's vertically controlled sourcing networks demonstrate consistent raw material flow security. |
| Multi-Continent Certification Investment | McCain Foods anchors North American capacity through FDA-parallel Health Canada compliance. |
| Cryogenic Technology Retrofit | EU F-Gas Regulation accelerates ammonia and transcritical CO2 system adoption across German facilities. |
| Food Service Channel Expansion | Hotel chain standardization mandates create volume commitments for reconstitution-stable IQF proteins. |
| India Cold-Chain Infrastructure Buildout | FSSAI licensing formalization enables secondary city penetration beyond Mumbai and Chennai concentration. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with frozen food procurement directors, cold-chain logistics operators, blast-freezing equipment engineers, and regulatory compliance officers informed demand-side and supply-side dynamics. Secondary sources include FDA HACCP guidance documents, EU F-Gas Regulation filings, China SAMR frozen aquatic product standards, and customs trade data. Bottom-up processor capacity modeling triangulates against top-down food service and retail consumption estimates.
Granularity-level modeling operates at product type, end user, packaging format, and distribution channel dimensions across the projection horizon. Seafood, vegetable, fruit, and meat segments incorporate catch-to-freeze traceability cost structures and seasonal harvest window constraints. CAGRs derive from volume trajectory analysis calibrated against cold storage infrastructure expansion rates and quick-service restaurant chain procurement consolidation patterns. Energy price volatility and refrigerant transition timelines enter as scenario-weighted inputs.
The model assumes a particular technology adoption path; alternative pathways for ammonia and transcritical CO2 refrigerant systems would alter the outlook for European processor capital intensity. Forecasts reflect assumptions about food service procurement centralization persistence and China cold storage modernization rates. Regulatory acceleration in refrigerant phase-down schedules or import eligibility documentation represents a small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Freeze Dried Mangos Market
Processed and Frozen Foods
Popsicle and Ice Cream Bar Market
Processed and Frozen Foods
North America Frozen Pizza Market
Processed and Frozen Foods
Frozen Cheese Market
Processed and Frozen Foods
Global Frozen Fish and Seafood Market
Processed and Frozen Foods
Indonesia Frozen Food Market
Processed and Frozen Foods
Frozen Snacks Market
Processed and Frozen Foods
Popsicle Market
Processed and Frozen Foods
Chilled Processed Food Market
Processed and Frozen Foods
Processed and Frozen Vegetables Market
Processed and Frozen Foods
Frozen Ready Meals Market
Processed and Frozen Foods
Deli Meat Market
Processed and Frozen Foods
Spiral Freezer Market
Processed and Frozen Foods
Freeze Dried Vegetables Market
Processed and Frozen Foods
North America Freeze Dried Products Market
Processed and Frozen Foods
Frozen Desserts Market