
 Frozen Basil Leaves Market | 2026-2036
Frozen Basil Leaves Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Basil Leaves Market Foresight
Direct-to-foodservice distribution is narrowing as large retail consolidators demand longer shelf-life guarantees and traceability documentation. McCormick & Company Inc. leverages its spice-industry logistics backbone to control frozen herb cold-chain integrity across North American accounts. Giorgio Fresh anchors its position through vertical integration from controlled-environment agriculture to blast-freezing operations. Mastronardi Produce competes by extending its greenhouse-grown basil program into year-round frozen supply contracts with national restaurant chains.
Frozen basil leaves are culinary herbs harvested at peak essential-oil concentration, rapid-blanched to inactivate oxidative enzymes, then flash-frozen at minus eighteen degrees Celsius to preserve volatile aromatic compounds for industrial and consumer kitchens. Whole leaves command premium positioning in foodservice channels where visual integrity matters, while chopped leaves dominate volume in sauce manufacturing where particle size uniformity reduces processing variability. Powdered leaves represent the fastest-growing product type as nutraceutical formulators seek standardized rosmarinic acid content for encapsulation.
The FDA's Grade A Pasteurized Milk Ordinance cold-chain standards, USDA Good Agricultural Practices certification, and EU REACH compliance for pesticide residue thresholds collectively shape market access and buyer qualification protocols. Food manufacturers now require dual-certified suppliers meeting both FDA food safety modernization act traceability rules and EU organic equivalency arrangements. Stakeholders must monitor evolving refrigerant regulations under the EPA's phasedown of hydrofluorocarbons, which threatens to raise blast-freezing operational costs and reshape regional production economics.
Market Dynamics
The EU Green Deal's agricultural chemical restrictions are compressing herb supply chains toward controlled-environment agriculture and certified frozen alternatives, forcing food manufacturers to requalify suppliers under dual FDA-EU traceability protocols.
Growth Catalysts
- EU REACH pesticide thresholds:Tightening residue limits are disqualifying conventional fresh herb suppliers and redirecting sauce manufacturers toward blast-frozen certified alternatives with documented compliance chains.
- Industrial pasta sauce production:Emilia-Romagna's concentrated manufacturing base is generating bulk procurement contracts that favor frozen leaf consistency over seasonal fresh supply volatility.
- Controlled-environment agriculture:Greenhouse and vertical farming systems are enabling year-round basil cultivation with predictable essential-oil profiles, stabilizing raw material input for frozen processors.
Market Restraints
- Blast-freezing energy costs:The EPA's hydrofluorocarbon phasedown is threatening to raise refrigerant and electricity expenses for minus eighteen Celsius operations, squeezing processor margins.
- Dual-certification burden:Suppliers must simultaneously maintain FDA Food Safety Modernization Act traceability and EU organic equivalency, creating documentation overhead that excludes smaller growers.
- Fresh herb substitution:Local greenhouse basil in premium foodservice channels retains visual and aromatic advantages that frozen whole leaves struggle to match for plating applications.
Strategic Opportunities
- Nutraceutical encapsulation demand:Standardized rosmarinic acid content in powdered frozen basil is opening formulation contracts with supplement manufacturers seeking botanical actives.
- Direct retail channel expansion:National grocery consolidators are requesting longer shelf-life guarantees and single-origin traceability that frozen herb suppliers with captive agriculture can provide.
- EU F-Gas Regulation adaptation:Early adoption of natural refrigerant blast-freezing systems creates cost positioning advantages as hydrofluorocarbon equipment faces accelerated phaseout.
Industry Challenges
- Cold-chain integrity staffing:Maintaining uninterrupted minus eighteen Celsius logistics requires specialized technicians whose certification programs have not kept pace with expanding frozen herb volumes.
- Enzyme inactivation timing:Rapid-blanching protocols demand precise temperature control to prevent oxidative degradation without collapsing leaf cellular structure, requiring capital-intensive monitoring equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Basil Leaves Market |
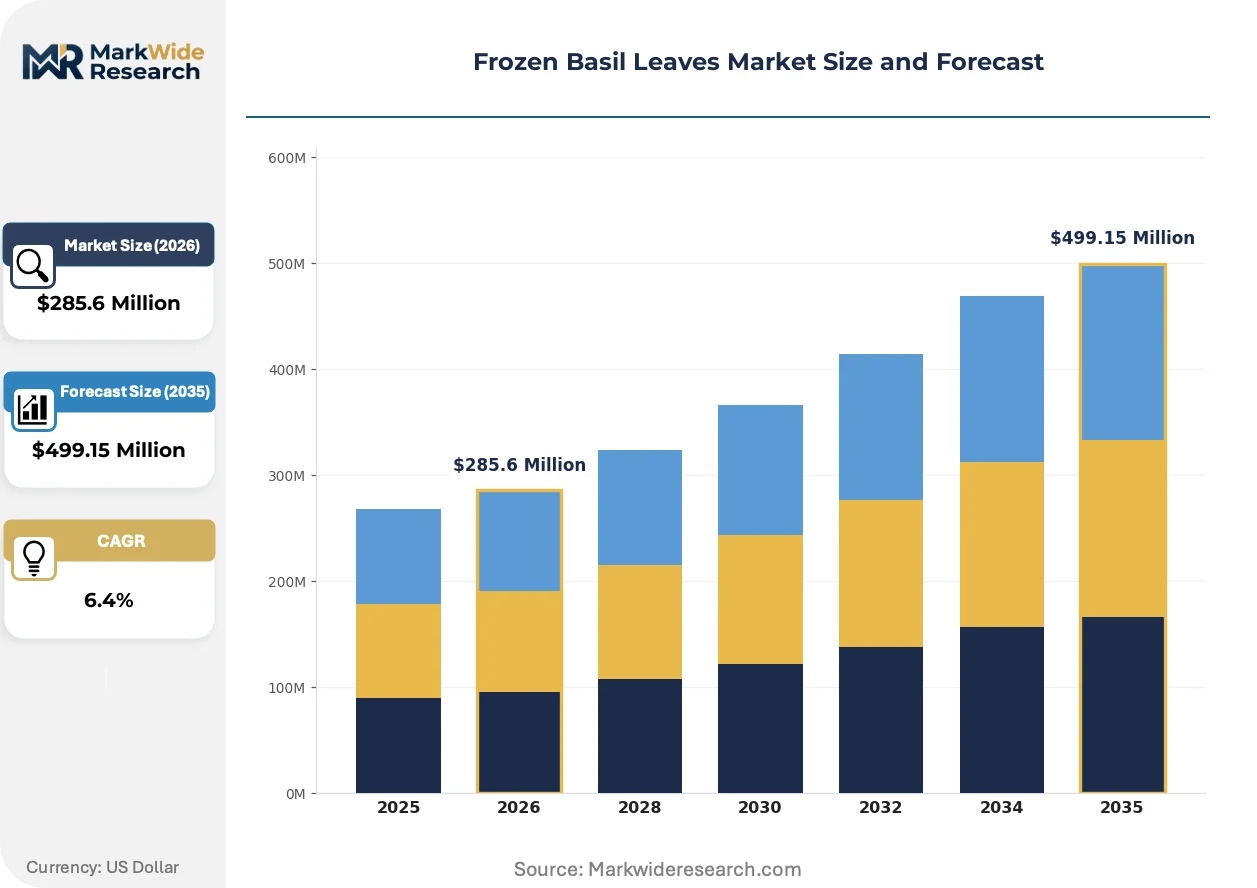
| Market Size in 2026 | $285.6 Million |
| Market Size in 2035 | $499.15 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Leaves, Chopped Leaves, Paste, Powdered Leaves Application: Food Service, Home Cooking, Pharmaceutical, Cosmetic, Nutraceutical Packaging Type: Plastic Bags, Vacuum Packs, Boxes, Pouches, Bulk Containers End User: Supermarkets, Food Manufacturers, Culinary Institutions, Pharmacies |
| Companies Covered | McCormick & Company Inc., Giorgio Fresh, Mastronardi Produce, Great American Spice Company, Village Farms, NatureFresh Farms, Greenhouse Produce, Frontier Co-op, Litehouse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Basil Leaves Market Shifts & Advancements
Flash-freezing technology advances and regulatory refrigerant transitions are compressing processing economics while nutraceutical buyers create new specification categories for standardized botanical extracts.
Individual quick freezing with cryogenic nitrogen injection is rendering obsolete traditional blast-freezing methods that produced ice crystal damage and volatile oil loss. Sauce manufacturers in Italy and industrial kitchens across Germany are adopting IQF whole leaves at accelerating rates. The technology is rendering obsolete bulk chopped leaf contracts that previously dominated foodservice procurement.
The EPA's hydrofluorocarbon phasedown under the AIM Act is forcing frozen herb processors to retool refrigeration infrastructure ahead of equipment end-of-life. Operational retrofit costs are concentrating among mid-scale blast-freezing facilities lacking capital reserves for natural refrigerant conversion. North American processors are responding by consolidating production into fewer large-scale facilities with ammonia-based systems.
Foodservice buyers are unbundling fresh herb contracts and inserting frozen alternatives into year-round supply agreements with traceability documentation requirements. National restaurant chains are displacing regional fresh distributors with direct frozen herb contracts that specify essential-oil concentration minimums. This pattern is most visible in quick-service pizza and pasta chains operating across the United States.
Frozen Basil Leaves Market Segmentation
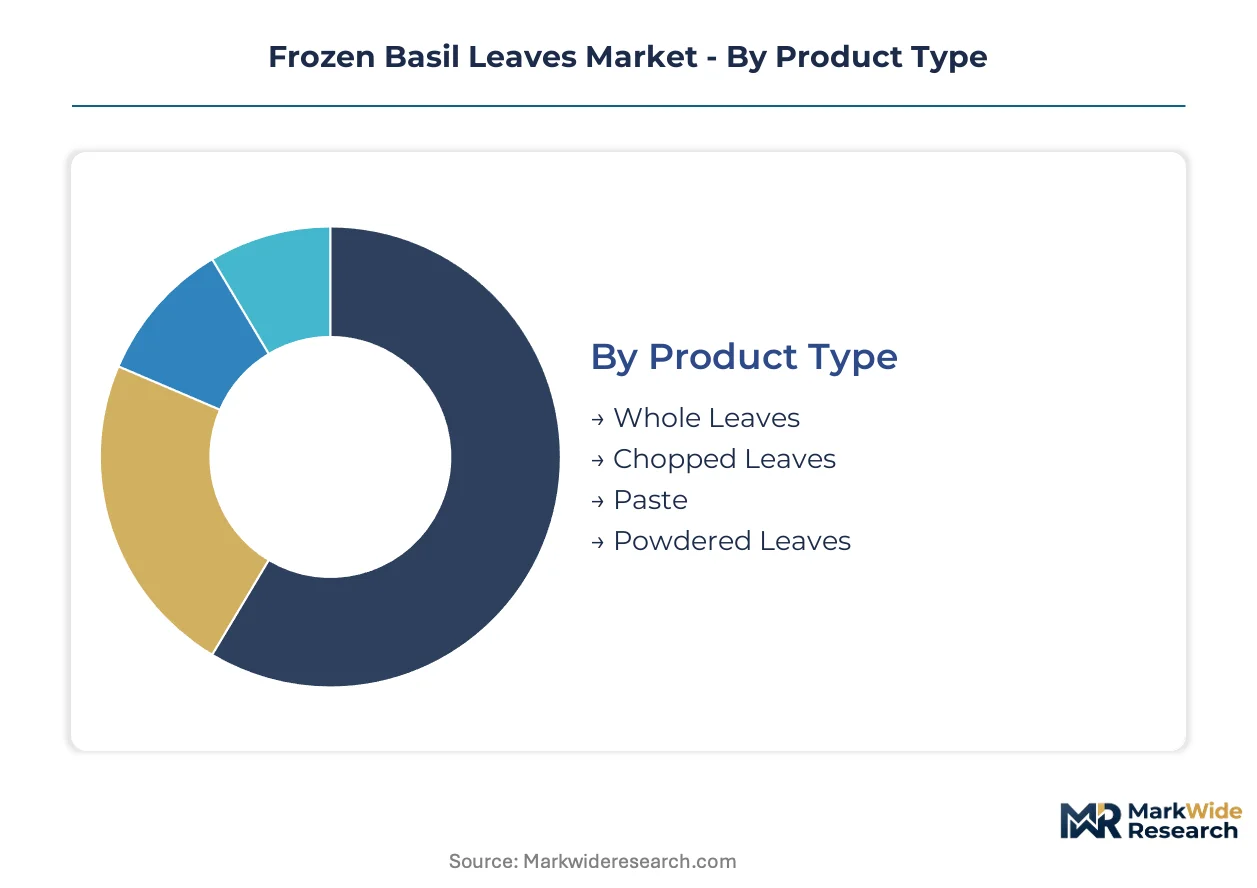
Segmentation in frozen basil leaves reveals how processing intensity and distribution channels reshape value capture. Each dimension exposes distinct margin structures and regulatory exposure that suppliers must navigate.
Product Type:
Mature formats dominate volume while emerging specifications capture premium positioning through functional standardization.
- Whole Leaves:Individual quick-frozen leaves retain cellular structure and volatile oil concentration for foodservice plating. Demand concentrates in Italian quick-service pizza chains where visual integrity determines supplier qualification.
- Chopped Leaves:Uniform particle size reduces processing variability in industrial sauce manufacturing. Emilia-Romagna pasta sauce producers anchor procurement contracts favoring this format for predictable batch consistency.
- Paste:Blended frozen basil with oil and salt serves Mediterranean restaurant kitchens seeking ready-to-use flavor bases.
- Powdered Leaves:Spray-dried or freeze-dried material standardized for rosmarinic acid content supplies nutraceutical encapsulation contracts.
Chopped leaves handle the majority of throughput; powdered leaves are expanding most quickly on share.
Application:
Cost tier separation runs from commodity food manufacturing through premium nutraceutical extraction.
- Food Service:National restaurant chains specify essential-oil concentration minimums in year-round frozen supply agreements displacing regional fresh distributors.
- Home Cooking:Retail pouches target convenience-seeking consumers in North American and European grocery consolidators demanding single-origin traceability.
- Pharmaceutical:Standardized botanical extracts meet pharmacopeial monograph requirements for anti-inflammatory formulation development.
- Cosmetic:Antioxidant-rich frozen basil supplies natural skincare manufacturers formulating preservative-free product lines.
- Nutraceutical:Encapsulation-grade powdered leaves with documented rosmarinic acid content open supplement manufacturer contracts.
Food service commands the volume base; nutraceutical applications are climbing the fastest on margin contribution.
Packaging Type:
Customer type determines barrier requirements from institutional bulk through consumer convenience.
- Plastic Bags:Standard polyethylene formats serve cost-sensitive food manufacturers with high-throughput processing lines.
- Vacuum Packs:Oxygen barrier films extend shelf life for retail channels requiring twelve-month minimum guarantees.
- Boxes:Corrugated containers with moisture barriers protect bulk shipments to industrial pasta sauce facilities.
- Pouches:Stand-up formats with resealable closures target home cooking segments in premium grocery positioning.
- Bulk Containers:Food-grade totes and drums supply pharmaceutical and nutraceutical extractors with drum-to-drum traceability.
Bulk containers move the heaviest tonnage; vacuum packs are gaining share fastest in retail consolidation.
End User:
Supply concentration varies from consolidated manufacturing clusters to fragmented institutional procurement.
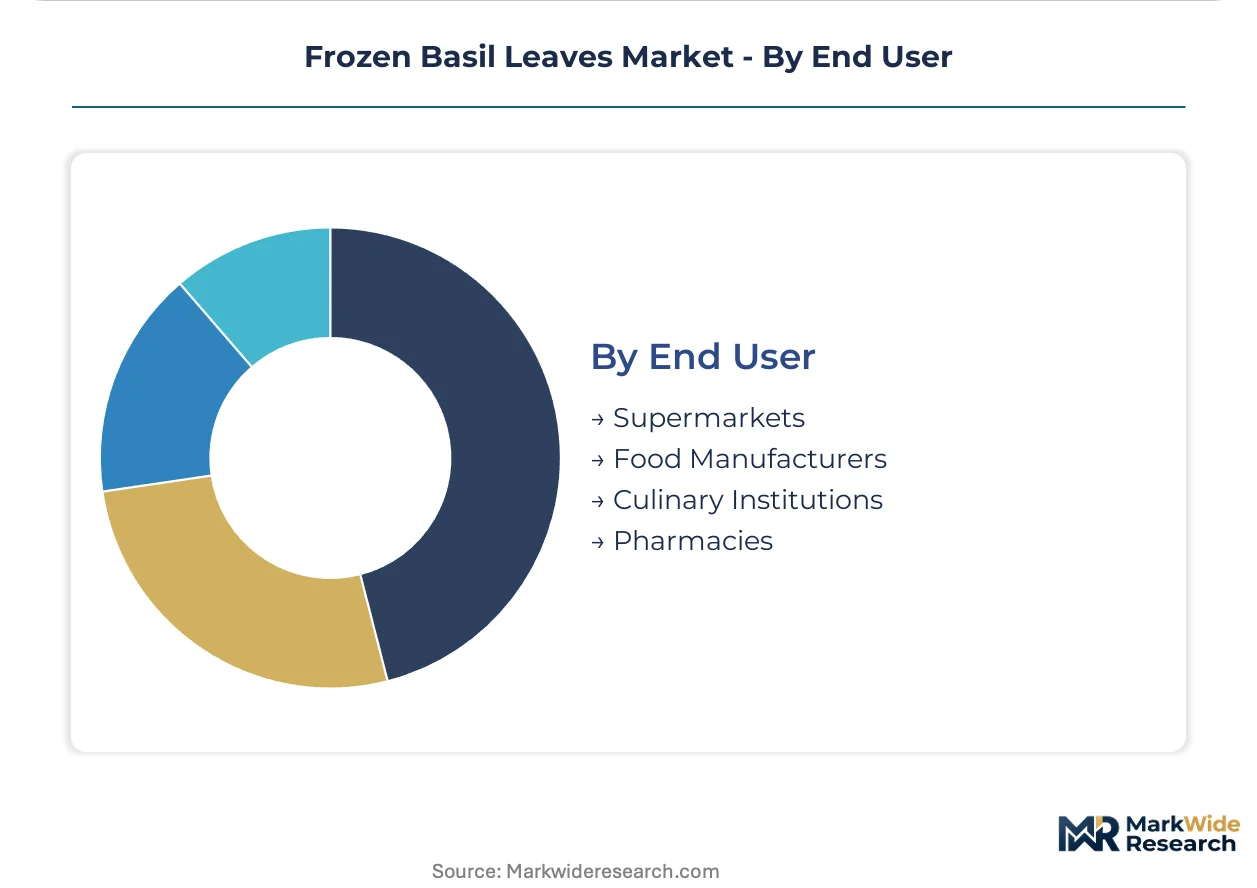
- Supermarkets:National grocery chains request extended shelf-life guarantees and single-origin documentation that captive agriculture suppliers can provide.
- Food Manufacturers:Industrial pasta sauce producers in Italy's Emilia-Romagna region generate bulk procurement contracts favoring frozen consistency over seasonal fresh volatility.
- Culinary Institutions:Hotel and restaurant school training kitchens balance cost control against pedagogical requirements for ingredient identification.
- Pharmacies:Compounding and retail pharmacy channels source standardized botanical materials for practitioner-grade supplement lines.
Food manufacturers absorb the dominant share of volume; supermarkets are expanding fastest on direct contract penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian frozen basil commands premium pricing power against North American supply, reflecting Emilia-Romagna's concentrated pasta sauce manufacturing base versus fragmented U.S. procurement. This asymmetry shapes regional investment patterns and cold-chain infrastructure deployment.
United States
National restaurant chains specify essential-oil concentration minimums in year-round frozen supply agreements. The FDA's Food Safety Modernization Act traceability rules require lot-level documentation. California's Central Valley greenhouse clusters anchor domestic basil cultivation for blast-freezing processors serving quick-service pizza chains.
Italy
Industrial pasta sauce producers in Emilia-Romagna generate bulk procurement contracts favoring frozen leaf consistency. The EU REACH pesticide residue thresholds disqualify conventional fresh herb suppliers. Parma and Modena manufacturing corridors concentrate frozen herb processing capacity for European export.
Germany
Industrial kitchens across Bavaria and Baden-Württemberg adopt IQF whole leaves at accelerating rates. The EU F-Gas Regulation forces refrigeration infrastructure retooling ahead of equipment end-of-life. Frankfurt's food logistics hub consolidates frozen herb distribution for Central European foodservice accounts.
Canada
Greenhouse-grown basil programs extend into year-round frozen supply contracts with national grocery chains. Health Canada's Pest Management Regulatory Agency enforces residue limits matching EU stringency. Ontario's Leamington greenhouse cluster supplies captive agriculture for blast-freezing operations.
Mexico
Export-oriented frozen herb processing expands to serve U.S. foodservice demand under USMCA tariff preferences. The country's national agricultural regulator enforces Good Agricultural Practices certification for cross-border shipments. Sinaloa's protected agriculture zones concentrate year-round basil cultivation for frozen export.
Frozen Basil Leaves Market Competitive Landscape
Vertically integrated greenhouse operators and spice-industry logistics specialists split the market between captive agriculture control and cold-chain distribution dominance. The vendor base concentrates among mid-scale processors with backward integration into controlled-environment agriculture and large-scale distributors leveraging existing temperature-controlled infrastructure. Three archetypes prevail: greenhouse-to-freezer integrators, spice-logistics platform extenders, and regional fresh-produce diversifiers. Competitive moves center on ammonia-based refrigeration retrofitting and direct retail contract penetration bypassing traditional distribution tiers.
Within the integration-focused tier, Giorgio Fresh exemplifies vertical control from controlled-environment agriculture through blast-freezing operations. McCormick & Company Inc. anchors the logistics-extender position, leveraging spice-industry cold-chain infrastructure for frozen herb integrity. Mastronardi Produce occupies the diversification archetype, extending greenhouse-grown programs into frozen supply contracts with national restaurant chains.
| Leading Market Players |
|---|
| McCormick & Company Inc. |
| Giorgio Fresh |
| Mastronardi Produce |
| Great American Spice Company |
| Village Farms |
| NatureFresh Farms |
| Greenhouse Produce |
| Frontier Co-op |
| Litehouse |
| Others |
Supply & Pricing Matrix
Blast-freezing capacity underutilization in North America's mid-scale facilities is compressing supplier margins and accelerating pricing concessions to secure year-round offtake contracts with food manufacturers. This utilization gap simultaneously pressures processors to absorb rising natural refrigerant conversion costs while buyers consolidate procurement leverage.
Pricing Analysis
The customization-premium spread between IQF whole leaves and standard chopped formats captures value from visual integrity requirements in Italian quick-service pizza chains. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and essential-oil concentration documentation. Price differentiation stems from EU organic equivalency credentials and captive greenhouse supply control. Pricing pressure stems from the EPA's hydrofluorocarbon phasedown raising blast-freezing operational costs. Food manufacturers exhibit highest price sensitivity due to bulk contract volumes, while nutraceutical formulators tolerate premium positioning for standardized rosmarinic acid content.
Supply Chain Analysis
Tariff exposure between Mexico and the United States under USMCA preferences dominates supply chain risk assessment for cross-border frozen herb shipments. Production concentrates in Italy, the United States, and Mexico, with Emilia-Romagna's pasta sauce corridor anchoring European supply. Raw material inputs draw from greenhouse cultivation substrates, cryogenic nitrogen for IQF processing, and oil-based paste blending components. Single-source vulnerability concentrates in California's Central Valley for domestic U.S. basil cultivation. Distribution runs through temperature-controlled logistics platforms extending from McCormick's spice-industry backbone to regional cold-chain consolidators serving national restaurant chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The frozen basil market reads as a service-attach opportunity where cold-chain integrity guarantees and traceability documentation subscriptions expand faster than commodity leaf tonnage. Recurring certification audits and essential-oil concentration testing contracts now outgrow base product margins.
For Market Incumbents: Harden cold-chain infrastructure against refrigerant transition risk by accelerating ammonia-based system retrofits in large-scale facilities before equipment end-of-life. Consolidate procurement leverage through captive greenhouse expansion in Ontario's Leamington cluster and California's Central Valley. Defensive positioning requires absorbing the dual-certification burden that excludes smaller growers, turning compliance overhead into competitive moats against mid-scale processors lacking capital reserves. For New Entrants and Emerging Players: Nutraceutical encapsulation contracts for standardized rosmarinic acid content represent the most penetrable entry point, with supplement manufacturers seeking botanical actives outpacing foodservice volume growth. Direct retail channel expansion through national grocery consolidators requesting single-origin traceability offers secondary white-space access. Go-to-market execution should anchor on ammonia-based blast-freezing infrastructure investments that position ahead of hydrofluorocarbon equipment phaseout. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated greenhouse operators with backward control over controlled-environment agriculture through blast-freezing operations, capturing margin compression resilience over the projection horizon. Target archetypes include mid-scale processors in Emilia-Romagna with established pasta sauce manufacturer relationships and underutilized capacity for natural refrigerant conversion. The signal to watch is EU F-Gas Regulation enforcement acceleration triggering distressed asset availability among conventional refrigerant-dependent facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Conversion | Ammonia-based blast-freezing retrofitting creates cost positioning ahead of hydrofluorocarbon phaseout deadlines. |
| Captive Greenhouse Expansion | Controlled-environment agriculture integration secures year-round raw material supply against seasonal volatility. |
| Nutraceutical Certification Investment | Standardized rosmarinic acid documentation opens formulation contracts with supplement manufacturers seeking botanical actives. |
| Direct Retail Channel Penetration | Single-origin traceability guarantees displace regional fresh distributors in national grocery consolidator contracts. |
| IQF Technology Deployment | Cryogenic nitrogen injection systems render obsolete bulk chopped leaf contracts with superior volatile oil retention. |
Research Methodology
The analysis maps frozen herb processing tiers, greenhouse cultivation clusters, and nutraceutical extraction specifications, each validated through procurement directors at industrial pasta sauce manufacturers, cold-chain logistics specialists, and regulatory compliance officers. Primary interviews with foodservice category managers and frozen herb processors combined with secondary validation from FDA Food Safety Modernization Act guidance documents, EU REACH pesticide residue databases, and EPA AIM Act refrigerant phasedown schedules. Bottom-up volume modeling across product type and application segments triangulated against top-down market sizing from trade flow analysis.
Assumptions held fixed include regulatory enforcement timelines for hydrofluorocarbon phaseout and EU Green Deal agricultural chemical restrictions, while variables included energy cost trajectories and nutraceutical demand elasticity. The forecast framework segments by product type, application, packaging format, and end user, with CAGRs derived from regression analysis against historical frozen herb trade volumes and essential-oil concentration premium realization. Industry-specific inputs incorporated greenhouse yield curves and blast-freezing capacity utilization rates across the analysis window.
Macroeconomic conditions sit as an overlay; deviation in energy pricing, agricultural input costs, or cross-border tariff regimes would shift the trajectory. Forecasts reflect assumptions about regulatory enforcement consistency and technology adoption curves in refrigerant infrastructure. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Cold Storage Market
Processed and Frozen Foods
Popsicle Market
Processed and Frozen Foods
North America Frozen Finger Chips Market
Processed and Frozen Foods
Europe Frozen Finger Chips Market
Processed and Frozen Foods
Frozen Pizza Market
Processed and Frozen Foods
Europe Frozen Food Market
Processed and Frozen Foods
IQF Food Products Market
Processed and Frozen Foods
Latin America Frozen Finger Chips Market
Processed and Frozen Foods
Popsicle and Ice Cream Bar Market
Processed and Frozen Foods
Low-Fat Low-Cholesterol Foods Market
Processed and Frozen Foods
Chilled Soup Market
Processed and Frozen Foods
Frozen Bread Market
Processed and Frozen Foods
Frozen Meat Market
Processed and Frozen Foods
Europe Frozen Pizza Market
Processed and Frozen Foods
Freeze-Dried Food Market
Processed and Frozen Foods
Global Frozen Breakfast Entrees/Sandwiches Market