
 Africa Sorghum Seed Market | 2026-2036
Africa Sorghum Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Sorghum Seed Market Outlook
Multi-source procurement of breeder stock is shifting how African seed houses manage genetic supply chains. Seed Co Limited leverages its southern African breeding stations to sustain regional germplasm leadership. Advanta Seeds - UPL anchors its position through hybrid trait platforms tailored to Sahelian stress conditions. Corteva Agriscience competes via technology transfer partnerships with national agricultural research institutes.
Sorghum seed comprises the reproductive propagule of Sorghum bicolor, typically bred for specific endosperm texture, tannin content, and Striga resistance at germination thresholds above 80 percent viability. Its primary commercial purpose is to deliver yield-stable, abiotic-stress-tolerant grain for food security and feed rations across semi-arid farming systems. Hybrid seeds command premium positioning due to heterosis-driven yield gains and proprietary trait stacks, while open-pollinated varieties retain share among subsistence growers with limited input access. The animal feed segment shows structural momentum as poultry and dairy operations in South Africa and Nigeria formalize contracted sorghum offtake.
Kenya's Seed and Plant Varieties Act, enforced by the Kenya Plant Health Inspectorate Service, mandates distinctness-uniformity-stability testing before commercial release, compressing time-to-market for new hybrids. South Africa's Department of Agriculture, Land Reform and Rural Development administers cultivar listing requirements that filter variety eligibility for subsidy programs. Ethiopia's national seed system, overseen by the Ethiopian Agricultural Authority, balances public breeder lines against private licensing terms. Stakeholders must monitor how evolving plant variety protection frameworks reshape royalty structures and farmer-saved seed enforcement across the continent's fragmented regulatory patchwork.
Market Dynamics
Hybrid seed penetration across East African smallholder systems is compressing the competitive window for open-pollinated varieties, forcing seed houses to accelerate variety turnover cycles and recalibrate germplasm licensing strategies.
Growth Catalysts
- Kenya Plant Health Inspectorate Service certification mandates:Accelerated distinctness-uniformity-stability testing protocols compress time-to-market for new hybrids, rewarding breeders with robust phenotyping infrastructure.
- Sahelian drought stress platforms:Hybrid trait stacks targeting abiotic stress tolerance are pulling commercial investment into Nigeria's northern savanna belt as irrigation infrastructure remains limited.
- Poultry sector formalization:Contracted offtake arrangements for feed-grade sorghum in South Africa are creating guaranteed demand corridors that de-risk seed production planning.
Market Restraints
- Fertilizer cost volatility:Hybrid seed performance depends on complementary nitrogen inputs, exposing farmers to urea price spikes that erode margin calculations.
- Striga-resistant germplasm concentration:Limited breeder stations with validated Striga biocontrol trait integration create supply bottlenecks for West African markets.
- Farmer-saved seed persistence:Open-pollinated variety recycling across Ethiopia's highland zones undermines royalty capture and hybrid conversion economics.
Strategic Opportunities
- Ethiopia's agricultural authority licensing reforms:Emerging public-private germplasm frameworks could unlock captive breeder line access for regional seed houses.
- Dairy feed ration substitution:Maize price premiums in South Africa are creating formulation flexibility for sorghum inclusion in compound feed manufacturing.
- Digital input financing:Mobile-money-linked seed credit platforms are emerging in Kenya's Rift Valley, reducing upfront cash barriers for hybrid adoption.
Industry Challenges
- Seed certification backlog:Ethiopia's variety registration queue delays commercial release timelines, compressing effective sales seasons for new hybrids.
- Germplasm IP fragmentation:Overlapping claims between national agricultural research institutes and private licensors complicate trait stacking negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Sorghum Seed Market |
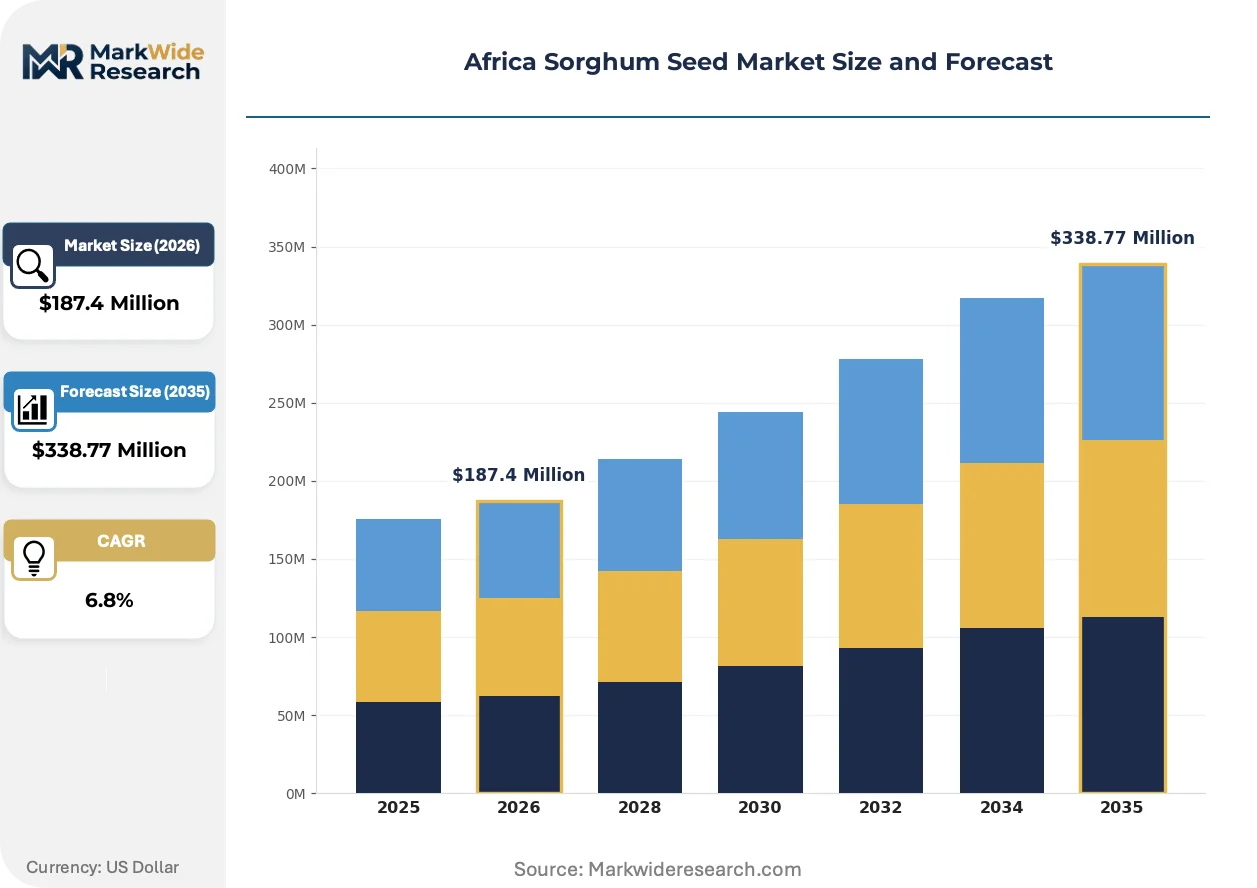
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Seeds, Open-Pollinated Varieties, Advanced Seeds, Specialty Seeds End Use Industry: Agriculture, Food Processing, Animal Feed, Biofuel Distribution Channel: Direct Sales, Wholesale Distributors, Online Retail, Agrochemical Stores Packaging Type: Bags, Bulk, Boxes, Pouches |
| Companies Covered | Zambia Seed Company Limited, Seed Co Limited, S&W Seed Co, Advanta Seeds - UPL, Capstone Seeds, Victoria Seeds Limited, Corteva Agriscience, FICA SEEDS, Syngenta, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Sorghum Seed Market Strategic Shifts
Digital phenotyping and accelerated breeding cycles are compressing the traditional variety development timeline, while regulatory harmonization efforts across the East African Community reshape market access rules for cross-border seed trade.
Marker-assisted selection platforms is consolidating control over complex trait introgression in sorghum breeding programs. Seed Co Limited and Advanta Seeds are deploying genomic selection to compress generational advancement for drought tolerance and grain mold resistance. This capability is consolidating competitive advantage among capital-intensive breeders with captive biotech infrastructure, marginalizing smaller operations reliant on conventional pedigree methods.
Kenya's Seed and Plant Varieties Act amendments are tightening distinctness thresholds for hybrid registration, forcing breeders to demonstrate wider genetic distance from existing commercial lines. The industrial consequence is elevated R&D expenditure for phenotypic characterization and extended field trial obligations. Small and mid-tier seed houses without dedicated trial station networks face exclusion from premium hybrid segments, concentrating release authority among established operators.
Contracted offtake arrangements are displacing spot-market grain sales as the dominant procurement mechanism for commercial sorghum production. Poultry integrators in South Africa's Mpumalanga province and feed compounders in Nigeria's Kaduna corridor are advancing volume-commitment contracts that specify seed variety, agronomic protocol, and delivery windows. This pattern is most visible among mid-scale farmers with irrigation access, who trade price volatility protection for loss of planting discretion and variety selection flexibility.
Africa Sorghum Seed Market Segmentation
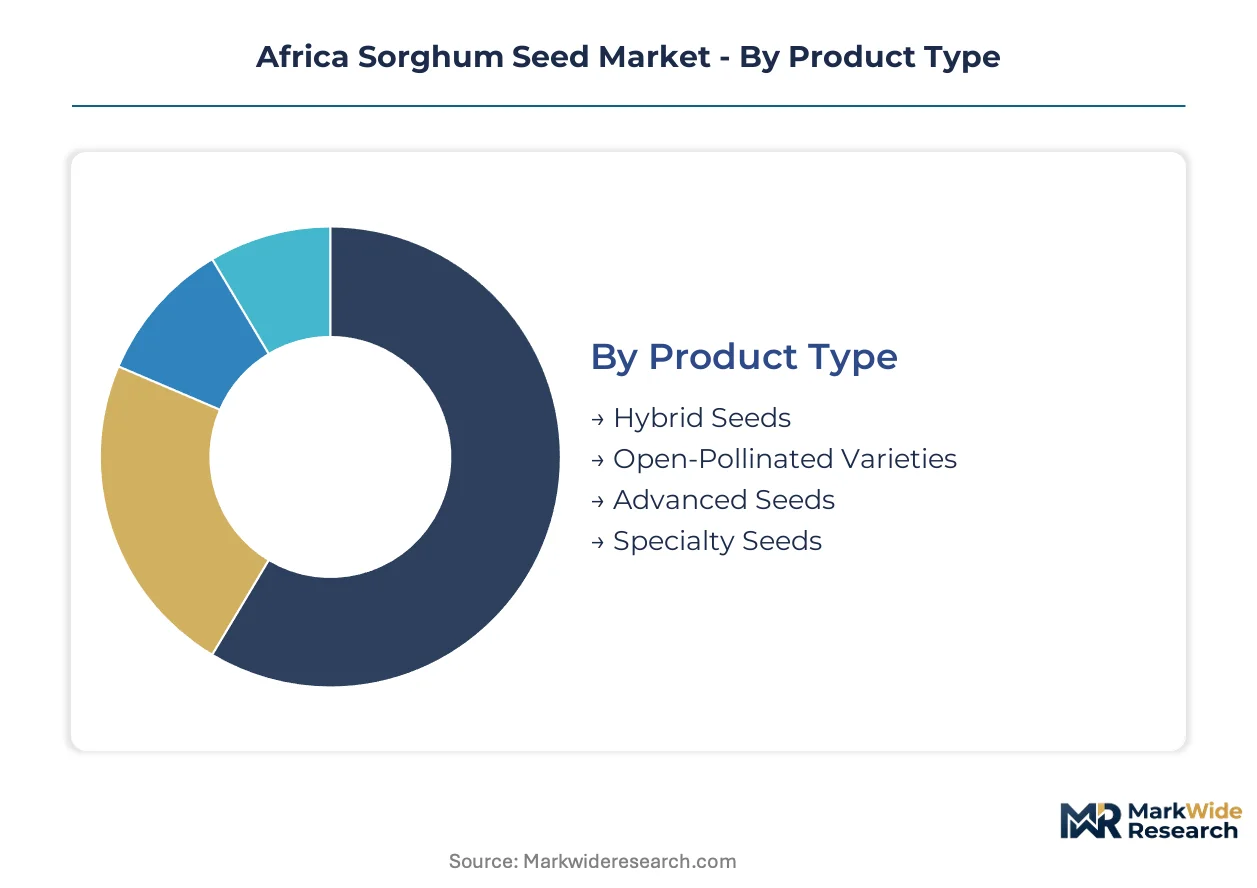
Sorghum seed segmentation in Africa reflects divergent farmer capabilities and commercial infrastructure maturity. Product type splits between premium hybrid systems and subsistence-oriented open-pollinated varieties, while distribution channels map onto rural financial access and input supply reliability.
Product Type:
Volume concentrates in low-margin open-pollinated varieties across Ethiopia's highland zones, while premium pricing accrues to proprietary hybrid stacks with validated Striga resistance.
- Hybrid Seeds:Proprietary F1 crosses delivering heterosis-driven yield gains of 30-50% over conventional varieties. Demand clusters in Nigeria's northern savanna belt where commercial farmers underwrite input costs for drought-resistant grain destined for poultry feed contracts. Royalty structures and plant variety protection enforcement determine breeder margins.
- Open-Pollinated Varieties:Farmer-saved seed systems predominate across smallholder plots with limited cash liquidity. Kenya's Rift Valley and Ethiopia's Oromia region show persistent recycling behavior that undermines certified seed conversion economics despite yield stagnation.
- Advanced Seeds:Marker-assisted selection products with stacked abiotic stress traits.
- Specialty Seeds:Niche germplasm for specific endosperm texture or tannin profiles.
Today's leader: Hybrid Seeds. Tomorrow's challenger: Advanced Seeds.
End Use Industry:
Application splits between subsistence grain security and formalized commercial offtake, with feed sector formalization accelerating fastest in southern African markets.
- Agriculture:Direct planting for household consumption and local market sales across semi-arid zones. Smallholders in Mali's Sikasso region and Burkina Faso's Sahel belt prioritize grain security over commercial optimization, constraining input intensification.
- Animal Feed:Contracted sorghum procurement for poultry integrators and dairy compounders. South Africa's Mpumalanga province and Nigeria's Kaduna corridor show volume-commitment structures that de-risk seed production planning for certified hybrid growers.
- Food Processing:Industrial malt and flour applications with specific grain quality specifications.
- Biofuel:Emerging cellulosic ethanol feedstock demand in pilot project phases.
Agriculture commands current volume. Animal Feed is gaining share fastest.
Distribution Channel:
Channel selection correlates with farmer scale, credit access, and proximity to agro-dealer infrastructure.
- Wholesale Distributors:Aggregated supply through regional depots serving agrochemical store networks. Seed Co Limited and Advanta Seeds leverage this channel to reach Kenya's eastern counties and Tanzania's Lake Zone with inventory financing arrangements.
- Agrochemical Stores:Last-mile retail points where smallholders purchase inputs with seasonal cash flows. Ethiopia's agricultural extension system and Nigeria's ADP networks influence stocking decisions at this tier.
- Direct Sales:Large commercial farm contracts with volume-based pricing.
- Online Retail:Mobile-platform seed ordering with digital payment integration.
Wholesale Distributors anchor current reach. Online Retail shows steepest expansion trajectory.
Packaging Type:
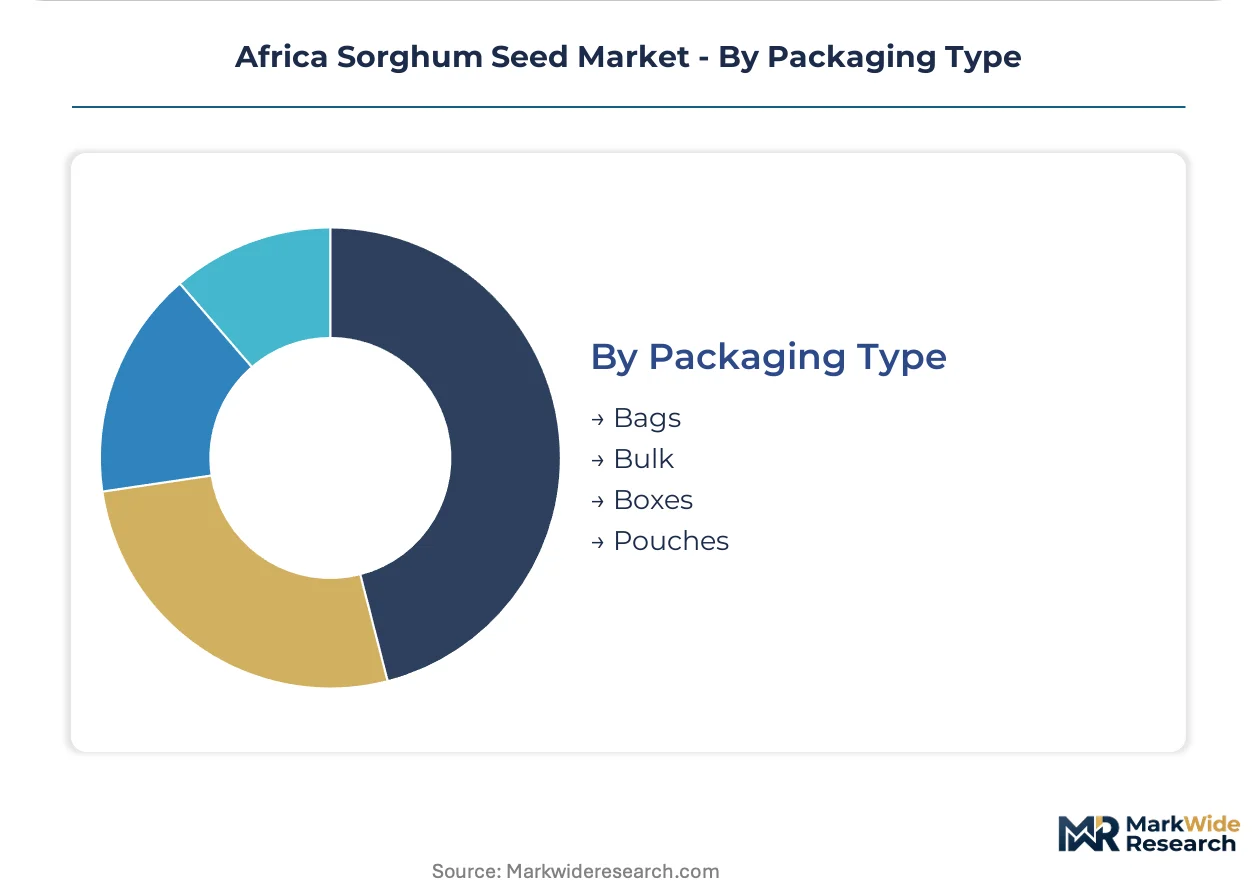
Packaging economics reflect seed value density and storage risk profiles across different product tiers.
- Bags:Standard 2-5kg woven polypropylene units for certified hybrid retail. Kenya Plant Health Inspectorate Service labeling requirements mandate germination percentage and lot number disclosure, elevating packaging compliance costs for formal sector products.
- Bulk:Loose seed delivery for large commercial operations with on-farm treatment capacity. South African contract farming arrangements and Nigerian mechanized estates favor this format for cost minimization at scale.
- Boxes:Rigid packaging for specialty or treated seed with handling protection.
- Pouches:Small-unit sachets for trial packets and promotional distribution.
Bags dominate revenue. Bulk is climbing the fastest as commercial farming scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting seed production toward jurisdictions with streamlined variety registration, as breeders seek to compress time-to-market for drought-tolerant hybrids.
Nigeria
Commercial sorghum farming scales rapidly across the northern savanna belt, driven by poultry feed contract demand and limited irrigation infrastructure. The National Agricultural Seeds Council enforces certification standards that filter variety eligibility for formal sector distribution. Kaduna corridor feed compounders are advancing volume-commitment contracts that specify seed variety and delivery windows.
Ethiopia
Highland smallholders persist with open-pollinated variety recycling despite yield stagnation, constraining certified seed conversion economics. The Ethiopian Agricultural Authority oversees national seed system licensing terms that balance public breeder lines against private sector access. Oromia region extension networks influence stocking decisions at agrochemical retail tiers.
Kenya
Hybrid seed penetration accelerates among Rift Valley smallholders through mobile-money-linked input financing platforms. The Kenya Plant Health Inspectorate Service mandates distinctness-uniformity-stability testing that compresses release timelines for breeders with robust phenotyping infrastructure. Eastern counties serve as deployment corridors for regional seed house inventory financing arrangements.
South Africa
Poultry and dairy operations in Mpumalanga province formalize contracted sorghum offtake, creating guaranteed demand corridors that de-risk seed production planning. The Department of Agriculture, Land Reform and Rural Development administers cultivar listing requirements tied to subsidy program eligibility. Mechanized estates favor bulk seed delivery formats for cost minimization at scale.
Tanzania
Lake Zone agro-dealer networks expand last-mile input distribution for hybrid varieties with validated Striga resistance. The Tanzania Official Seed Certification Institute regulates germplasm quality standards that influence cross-border trade flows from Kenyan breeding stations. Commercial farmers underwrite input costs for drought-resistant grain destined for regional feed markets.
Africa Sorghum Seed Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue digital input financing and accelerated breeding platforms. The market structure concentrates release authority among capital-intensive breeders with captive biotech infrastructure, marginalizing smaller operations reliant on conventional pedigree methods. Three strategic archetypes dominate: southern African germplasm leaders, Sahelian stress-condition specialists, and technology transfer partners with national agricultural research institutes. Competitive moves center on genomic selection deployment for trait compression and public-private licensing frameworks for captive breeder line access.
Within the regional germplasm leadership tier, Seed Co Limited and Zambia Seed Company Limited exemplify scale-driven positioning through southern African breeding station networks. Advanta Seeds - UPL occupies a position among Sahelian stress-condition specialists, anchoring hybrid trait platform development. Corteva Agriscience sits within the technology transfer partnership archetype, representing multinational integration with national agricultural research institute collaboration models.
| Leading Market Players |
|---|
| Zambia Seed Company Limited |
| Seed Co Limited |
| S&W Seed Co |
| Advanta Seeds - UPL |
| Capstone Seeds |
| Victoria Seeds Limited |
| Corteva Agriscience |
| FICA SEEDS |
| Syngenta |
| Others |
Value Chain & Pricing Dynamics
Poultry feed contract specifications in Nigeria's northern savanna belt are mandating certified hybrid seed with validated Striga resistance, forcing seed houses to absorb germplasm licensing premiums and recalibrate margin structures across distribution tiers.
Pricing Analysis
Input-cost pass-through from breeder stock royalties and nitrogen fertilizer bundles determines hybrid seed price floors. Three-tier pricing structure across premium, standard, and economy levels separates proprietary F1 stacks with trait licensing from certified open-pollinated varieties and informal farmer-saved systems. Cost compression in the standard tier is intensifying because urea price volatility erodes bundled input economics. Subsistence smallholders in Ethiopia's highland zones exhibit highest price sensitivity, while South African contract poultry farmers show lowest elasticity due to guaranteed offtake structures.
Supply Chain Analysis
Certification gating through Kenya Plant Health Inspectorate Service, Ethiopia Agricultural Authority, and Nigeria's National Agricultural Seeds Council filters variety eligibility and compresses release timelines for compliant breeders. Breeder stock supply concentrates in South Africa, Kenya, and Zimbabwe where phenotyping infrastructure supports distinctness-uniformity-stability testing. The chain rests on captive parent line propagation, nitrogen fertilizer co-distribution, and mobile-money credit platform integration. Single-source vulnerability in Striga-resistant germplasm creates supply bottlenecks for West African markets. Distribution runs through wholesale depots financing agrochemical store networks in Kenya's eastern counties and Tanzania's Lake Zone.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential in this market hinges on accelerating hybrid conversion economics through digital input financing platforms that reduce upfront cash barriers for smallholder adoption.
For Market Incumbents: Anchor germplasm leadership by deepening captive breeding station networks across southern Africa and accelerating marker-assisted selection deployment for drought tolerance compression. Defend against emerging digital-native entrants by controlling inventory financing terms at agrochemical retail tiers. Prioritize backward integration into parent line multiplication to capture royalty value currently flowing to multinational licensors. For New Entrants and Emerging Players: Begin with white-space targeting of Ethiopia's Oromia region where open-pollinated variety recycling persists and certified seed conversion economics remain underdeveloped. The most penetrable segment sits among mid-scale farmers with irrigation access seeking volume-commitment contracts from feed compounders. Deploy mobile-platform seed ordering with digital payment integration to bypass established wholesale distributor gatekeeping. For Investors and Strategic Acquirers: Asymmetric upside sits with regional seed houses possessing captive phenotyping infrastructure and pending variety registration pipelines. Long-term viability favors breeders with demonstrated Kenya Plant Health Inspectorate Service release velocity and existing poultry feed contract relationships. Watch for inflection upon Ethiopia Agricultural Authority licensing reform implementation unlocking public breeder line access.| Strategic Initiative | Industry Significance |
|---|---|
| Genomic Selection Platform Deployment | Compresses generational advancement timelines for drought tolerance and grain mold resistance traits. |
| Public-Private Germplasm Licensing Framework | Unlocks captive breeder line access through Ethiopia Agricultural Authority reform negotiations. |
| Digital Input Financing Integration | Mobile-money-linked seed credit reduces upfront cash barriers for Rift Valley hybrid adoption. |
| Contracted Offtake Arrangement Expansion | Volume-commitment structures with Kaduna corridor feed compounders de-risk production planning. |
| Striga-Resistant Trait Stack Development | Addresses supply bottlenecks limiting West African market penetration and royalty capture. |
Study Parameters
Multiple input streams — breeder station operational data, national seed registry filings, and poultry feed contract documentation — were reconciled through structured interviews with seed house R&D directors, Kenya Plant Health Inspectorate Service certification officers, Ethiopia Agricultural Authority licensing administrators, and Nigeria National Agricultural Seeds Council regulatory leads. Secondary validation drew from East African Community trade statistics, national agricultural research institute germplasm release records, and mobile-money platform transaction disclosures. Bottom-up variety-level demand modeling and top-down sectoral expenditure analysis were triangulated against cross-referenced primary intelligence.
Data-stream reconciliation across product type, end-use application, distribution channel, and packaging format dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented volume trajectory modeling incorporating hybrid penetration rate assumptions, farmer-saved seed persistence patterns, and poultry sector formalization velocity. Forecast inputs included Kenya Plant Health Inspectorate Service release timeline data and Ethiopia Agricultural Authority queue length indicators.
Caveats apply where regulatory harmonization delays, Striga biocontrol trait validation failures, or nitrogen fertilizer price spikes could materially shift the outlook. Forecasts reflect documented assumptions on smallholder credit access expansion and contract farming arrangement scalability. A model refresh is warranted upon material change in East African Community seed trade protocol negotiations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Global Fruit and Vegetable Seeds Market
Seeds
Africa Peas Market
Seeds
Europe Chia Seeds Market
Seeds
Southeast Asia Vegetable Seed Market
Seeds
North America Grain Seed Market
Seeds
South Africa Seed Market
Seeds
South America Seed Market
Seeds
Asia-Pacific Seed Market
Seeds
Global Packaged Chia Seeds Market
Seeds
Mustard Seeds Market
Seeds
Psyllium Seed Market
Seeds
Flax Crop Market
Seeds
Global Oilseed Market
Seeds
Dodder Seed Market
Seeds
Ghana Seed Extract Market
Seeds
Chamomile Seeds Market