
 Psyllium Seed Market | 2026-2036
Psyllium Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Psyllium Seed Market Analytics
Multi-source procurement is recalibrating how downstream buyers secure psyllium supply, with large nutraceutical formulators diversifying beyond traditional single-origin contracts. Keyur Industries leverages its Gujarat-based processing infrastructure to sustain bulk husk exports to European pharmaceutical buyers. Atlas Industries competes on geographic dominance, controlling significant acreage contracts across Rajasthan's Sirohi and Jalore districts. JYOT Overseas Pvt. Ltd. differentiates through specialized powder grades that meet pharmaceutical-grade specifications for North American dietary supplement brands.
Psyllium seed comprises the dried ripe seeds of Plantago ovata, containing approximately 10-15% mucilaginous husk by weight that swells to form a viscous gel when hydrated, functioning primarily as a soluble fiber source in laxative and cholesterol-management applications. The husk segment anchors value generation due to its superior swelling index and premium pricing in pharmaceutical formulations, while powder grades occupy the fastest-expanding demand channel as ready-to-mix supplement formats gain shelf space. Food-grade specifications dominate volume throughput, though pharmaceutical-grade certifications capture disproportionate margin pools as clinical validation of psyllium's lipid-lowering effects hardens.
India's FSSAI mandates microbial and heavy-metal testing for psyllium exports, while the US FDA classifies psyllium husk as a dietary fiber under updated Nutrition Facts labeling rules, directly shaping formulation decisions by US food manufacturers. The European Pharmacopoeia and ISO 9001 quality benchmarks further constrain market access for uncertified processors, compressing the viable supplier base. Stakeholders must monitor evolving fiber-definition disputes between Codex Alimentarius and national regulators, as reclassification would ripple through ingredient procurement thresholds and health-claim permissibility across major import markets.
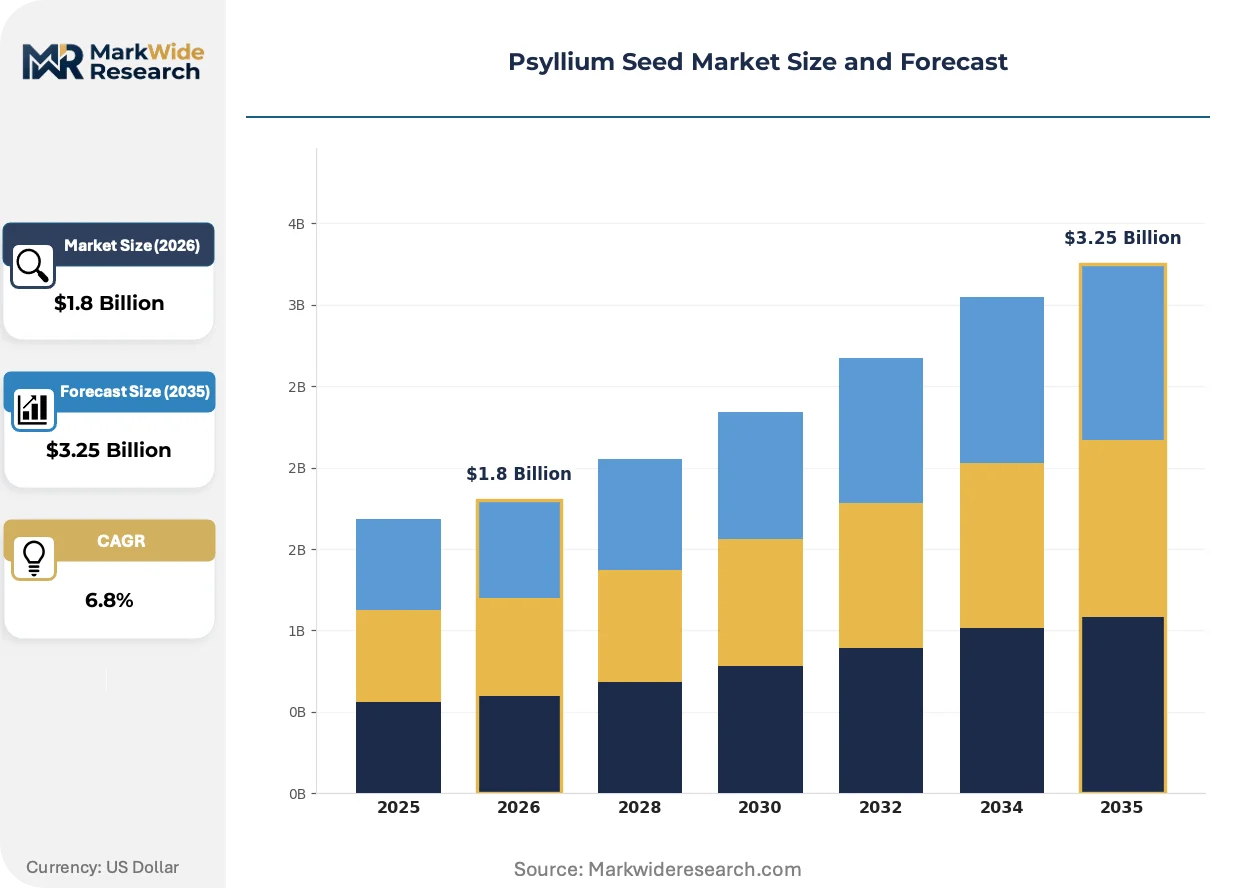
Market Dynamics
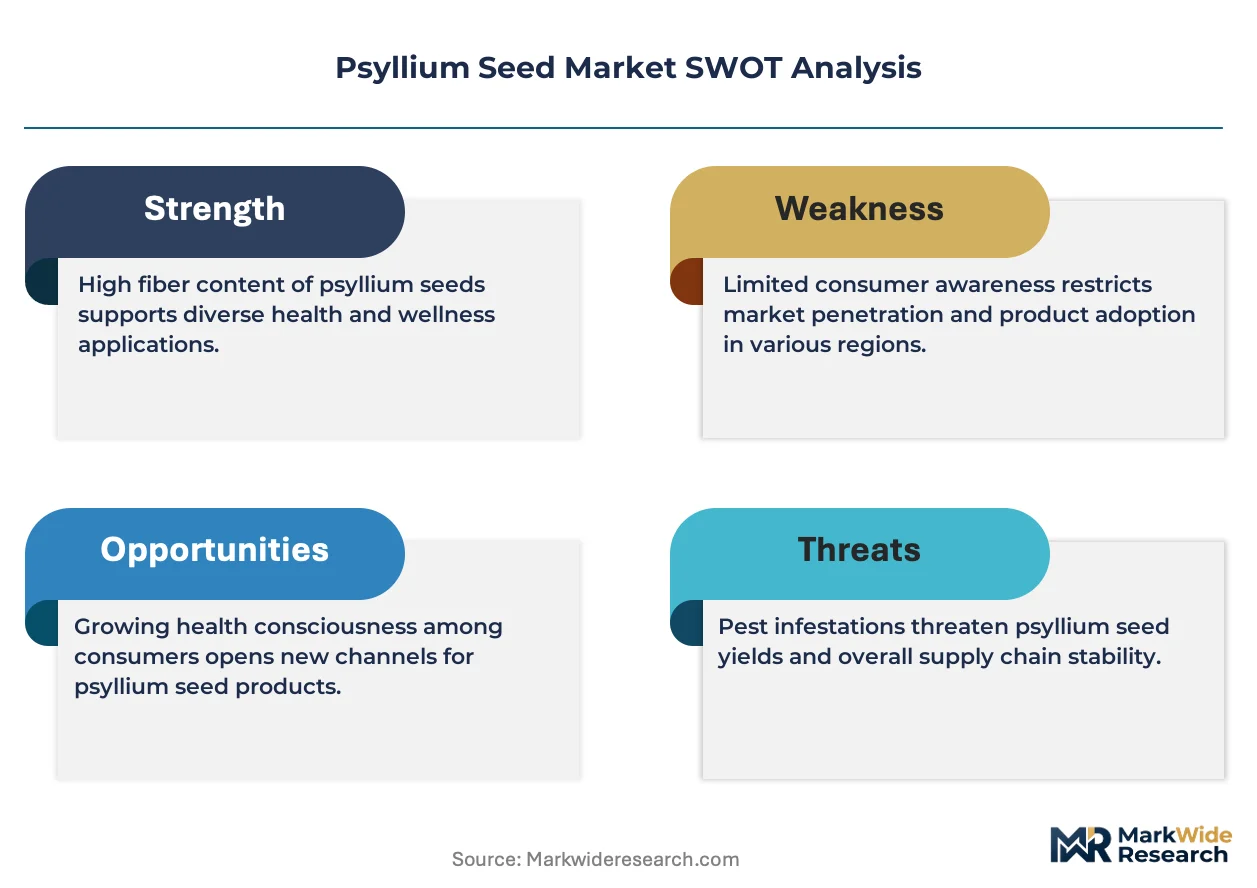
Regulatory tightening around purity standards and fiber-labeling definitions is compressing the viable supplier base while concentrating procurement power among certified processors capable of meeting multi-jurisdictional compliance requirements.
Growth Catalysts
- FDA fiber-definition clarity:The US FDA's classification of psyllium husk as a dietary fiber under updated Nutrition Facts rules compels food manufacturers to reformulate products, expanding ingredient offtake.
- Pharmaceutical-grade certification pipelines:European Pharmacopoeia compliance requirements filter out uncertified processors, creating protected margin pools for qualified suppliers serving clinical applications.
- Gujarat-Rajasthan cultivation clusters:Concentrated Plantago ovata farming around Unjha and Siddhpur enables integrated processing infrastructure that reduces logistics costs for export-bound husk.
Market Restraints
- Monsoon-dependent raw material volatility:Rainfall variability in Rajasthan and Gujarat directly impacts seed yields and husk quality, creating input cost instability for processors.
- Heavy-metal and microbial testing mandates:India's FSSAI export requirements impose compliance burdens that disproportionately constrain small-scale processors lacking laboratory infrastructure.
- Synthetic soluble fiber substitution:Methylcellulose and polydextrose formulations compete in laxative and cholesterol-management applications where price sensitivity dominates.
Strategic Opportunities
- Ready-to-mix supplement formats:Powder-grade psyllium is capturing shelf space in North American dietary supplement channels as consumers prioritize convenience.
- Gut microbiome clinical validation:Expanding research on soluble fiber's prebiotic effects creates entry points for pharmaceutical-grade suppliers into functional food formulations.
- EU Green Deal agricultural incentives:Sustainable farming certifications for Indian exporters could unlock premium positioning in European organic and clean-label segments.
Industry Challenges
- Multi-jurisdictional certification timelines:Simultaneous pursuit of US FDA, European Pharmacopoeia, and ISO 9001 approvals stretches quality-assurance teams and delays market entry.
- Specialized processing talent scarcity:Operators capable of maintaining pharmaceutical-grade hygiene standards while managing mucilage extraction efficiency remain concentrated in Gujarat's established clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Psyllium Seed Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Seeds, Husk, Powder, Extract End User: Food Industry, Pharmaceuticals, Dietary Supplements, Personal Care Application: Thickening Agent, Laxative, Stabilizer, Health Supplement Grade: Food Grade, Pharmaceutical Grade, Industrial Grade, Others |
| Companies Covered | Keyur Industries, JYOT Overseas Pvt. Ltd., Atlas Industries, Satnam Psyllium Industries, Abhyuday Industries, Shree Mahalaxmi Psyllium Pvt. Ltd., Rajganga Agro Product Pvt. Ltd., Jyotindra International, Ispasen Remedies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Psyllium Seed Market Evolving Landscape
Processing technology upgrades and evolving procurement protocols are reconfiguring competitive advantage around purity verification capabilities rather than raw volume throughput.
Supercritical CO2 extraction technology is absorbing residual oil and microbial contaminants from psyllium husk without degrading mucilage integrity. Pharmaceutical-grade formulators in Germany and Switzerland are adopting these systems to bypass conventional solvent-based cleaning methods. This shift is absorbing capital investment that smaller processors cannot match, consolidating premium supply relationships among capitalized operators.
REACH compliance documentation requirements for imported botanical ingredients now mandate full supply-chain traceability from farm to finished product. European buyers are demanding batch-level heavy-metal and pesticide residue testing that exceeds baseline food-grade specifications. Dietary supplement brands targeting German and French markets are responding by contracting exclusively with processors holding EMA-recognized GMP certifications.
Direct-procurement relationships between North American nutraceutical brands and Indian processors are displacing traditional trading-house intermediaries. Large supplement manufacturers are establishing quality-audit teams in Gujarat to verify cultivation practices and processing hygiene firsthand. This pattern is most visible among US brands marketing clinical-strength fiber products where provenance claims support premium pricing strategies.
Psyllium Seed Market Segmentation
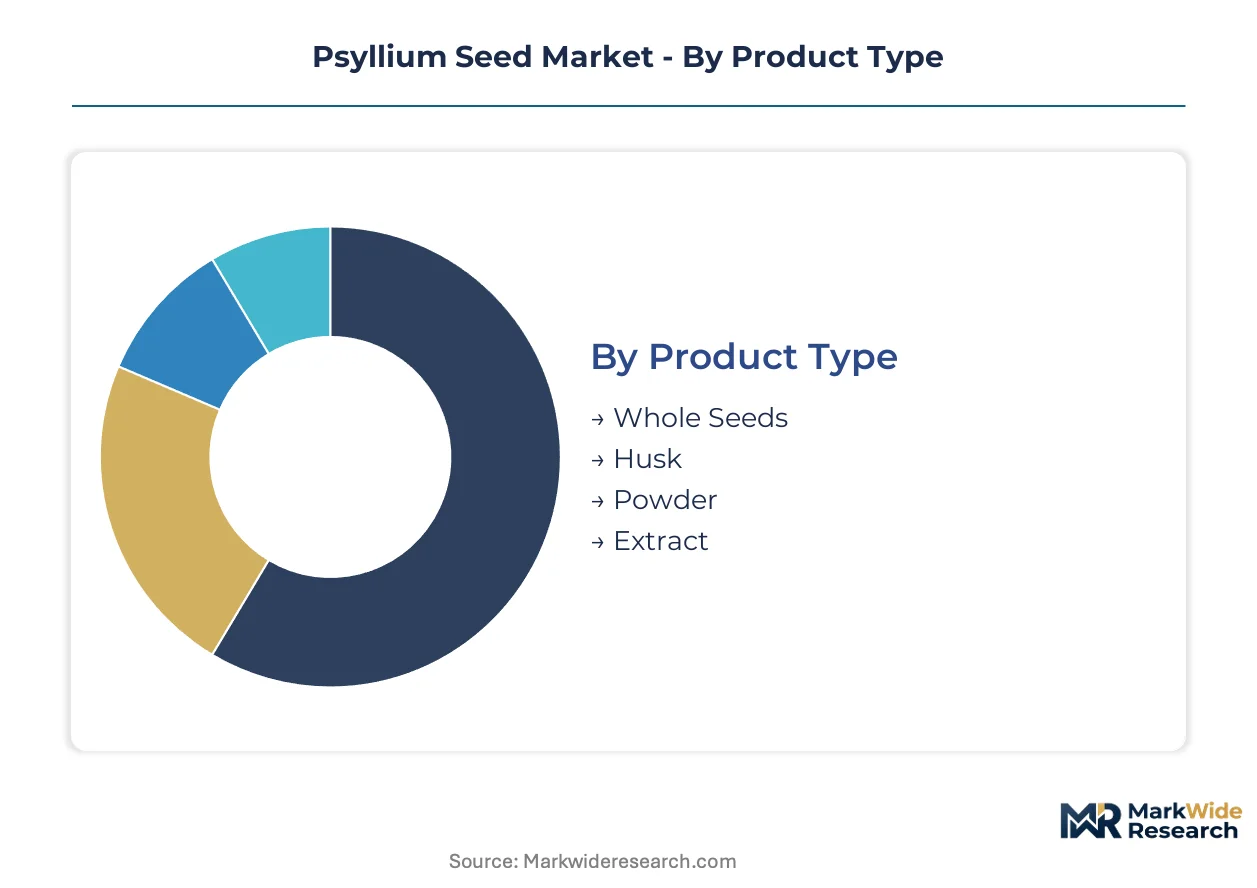
Psyllium seed segmentation reflects divergent compliance burdens across pharmaceutical, food, and industrial channels. Certification requirements fragment procurement strategies as buyers match grade specifications to end-use liability exposure.
Product Type:
Pharmaceutical-grade husk demands European Pharmacopoeia compliance and US FDA dietary fiber recognition, while food-grade powder navigates FSSAI export mandates and ISO 9001 benchmarks.
- Husk:The mucilaginous outer layer of Plantago ovata seeds, containing 85-95% soluble fiber with swelling indices exceeding 40 mL/g. Pharmaceutical formulators in Germany and Switzerland concentrate procurement here for clinical laxative and cholesterol-management applications, driven by mucilage integrity requirements that supercritical CO2 extraction now preserves.
- Powder:Finely milled psyllium with standardized particle size distribution for ready-to-mix supplement formats. North American dietary supplement brands in the US and Canada are expanding offtake fastest as convenience positioning captures shelf space, though this segment carries lighter regulatory burden than pharmaceutical husk.
- Whole Seeds:Unprocessed Plantago ovata seeds requiring mechanical dehusking before use. Industrial processors in Gujarat's Unjha cluster dominate supply.
- Extract:Concentrated mucilage isolates for specialized pharmaceutical and personal care applications. Limited commercial scale due to processing complexity.
Leading the category by volume: Husk. Growing fastest: Powder.
End User:
Customer type determines pricing power and contract structure, with pharmaceutical buyers commanding batch-level traceability that food manufacturers rarely require.
- Pharmaceuticals:Clinical laxative and lipid-lowering formulations requiring European Pharmacopoeia certification and EMA-recognized GMP compliance. German and Swiss buyers pay premiums for heavy-metal documentation exceeding baseline food-grade thresholds.
- Dietary Supplements:US and Canadian brands marketing clinical-strength fiber products where provenance claims support premium positioning. Direct-procurement relationships with Gujarat processors are displacing traditional trading-house intermediaries.
- Food Industry:Bakery, beverage, and functional food applications leveraging FDA fiber-definition clarity for Nutrition Facts reformulation.
- Personal Care:Cosmetic thickeners and topical formulations with lighter regulatory burden than ingestible grades.
Pharmaceuticals command the steepest margin premiums. Dietary supplements are climbing the fastest as convenience formats proliferate.
Application:
Functional purpose dictates mucilage specification, with therapeutic applications demanding higher swelling indices than industrial uses.
- Laxative:Osmotic bowel-regulation applications leveraging psyllium's water-retention capacity. Clinical validation in European markets supports pharmaceutical-grade pricing.
- Health Supplement:Cardiovascular and metabolic health positioning in North American retail channels. Cholesterol-management claims require substantiation under FTC and Health Canada guidelines.
- Thickening Agent:Viscosity modification in food and personal care formulations. Lower purity thresholds than therapeutic uses.
- Stabilizer:Emulsion stabilization in processed foods. Volume-driven with commodity pricing dynamics.
Laxative applications anchor revenue concentration. Health supplements are expanding most quickly as gut-microbiome research proliferates.
Grade:
Certification tier directly determines market access, with uncertified processors filtered out of pharmaceutical and premium food channels.
- Pharmaceutical Grade:Full European Pharmacopoeia compliance with batch-level heavy-metal, microbial, and pesticide residue documentation. REACH traceability mandates from ECHA constrain the viable supplier base to capitalized Gujarat processors.
- Food Grade:FSSAI export certification and ISO 9001 benchmarks for Indian-origin material. US FDA dietary fiber classification enables Nutrition Facts label claims.
- Industrial Grade:Non-ingestible applications with minimal regulatory burden. Price-sensitive substitution risk from synthetic fibers.
- Others:Emerging organic and sustainable farming certifications targeting EU Green Deal agricultural incentives.
Food grade dominates volume throughput. Pharmaceutical grade captures disproportionate margin pools as clinical validation hardens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dietary supplement manufacturers in the United States and Germany anchor import demand for psyllium husk and powder grades, while India's Gujarat and Rajasthan states concentrate cultivation and primary processing infrastructure. Regulatory divergence between FDA fiber-definition rules and European Pharmacopoeia certification requirements shapes procurement patterns across major consuming markets.
United States
US dietary supplement brands and functional food manufacturers drive psyllium offtake following FDA classification of psyllium husk as a dietary fiber under updated Nutrition Facts labeling rules. The FDA's fiber-definition clarity compels reformulation across bakery and beverage applications. Direct-procurement relationships with Gujarat processors are displacing traditional trading-house intermediaries for clinical-strength fiber products.
Germany
German pharmaceutical formulators concentrate European demand for pharmaceutical-grade psyllium husk used in clinical laxative and cholesterol-management applications. REACH compliance documentation from ECHA mandates full supply-chain traceability from farm to finished product. Supercritical CO2 extraction technology adoption in German processing facilities preserves mucilage integrity for premium formulations.
India
India's FSSAI mandates microbial and heavy-metal testing for psyllium exports, filtering the viable supplier base to certified processors. The Unjha and Siddhpur processing clusters in Gujarat integrate cultivation infrastructure with export-oriented husk production. Rajasthan's Sirohi and Jalore districts supply raw seed to these Gujarat-based processors under contracted acreage arrangements.
Switzerland
Swiss pharmaceutical-grade formulators source psyllium husk for European clinical applications requiring European Pharmacopoeia compliance and EMA-recognized GMP certifications. Swissmedic oversight reinforces batch-level heavy-metal documentation exceeding baseline food-grade thresholds. Swiss buyers pay premiums for processors maintaining pharmaceutical-grade hygiene standards through supercritical extraction systems.
Canada
Canadian dietary supplement brands expand psyllium powder procurement as ready-to-mix formats capture retail shelf space. Health Canada guidelines govern cholesterol-management claim substantiation for psyllium-containing products. British Columbia and Ontario-based supplement distributors establish quality-audit relationships with Gujarat processors to verify provenance claims supporting premium positioning.
Psyllium Seed Market Competitive Landscape
Multi-source procurement dominates the current landscape as large nutraceutical formulators diversify beyond traditional single-origin contracts. The supplier base concentrates among Gujarat and Rajasthan-based processors with integrated cultivation and export infrastructure. Three archetypes define competitive positioning: geographic-dominant controllers of contracted acreage, specialized pharmaceutical-grade certifiers, and diversified bulk husk exporters. Capacity expansion in supercritical extraction capabilities and backward integration into seed processing differentiate capitalized operators from commodity traders.
Among Gujarat-based processors, Keyur Industries leverages regional processing infrastructure to sustain bulk husk export relationships, while JYOT Overseas Pvt. Ltd. occupies a position within the pharmaceutical-grade specialization tier. Atlas Industries represents the geographic-dominant archetype through significant acreage contract control across Rajasthan's cultivation districts. These three exemplify how certification capabilities and geographic positioning stratify competitive advantage in a market where regulatory compliance filters out uncertified participants.
| Leading Market Players |
|---|
| Keyur Industries |
| JYOT Overseas Pvt. Ltd. |
| Atlas Industries |
| Satnam Psyllium Industries |
| Abhyuday Industries |
| Shree Mahalaxmi Psyllium Pvt. Ltd. |
| Rajganga Agro Product Pvt. Ltd. |
| Jyotindra International |
| Ispasen Remedies |
| Others |
Value Network & Pricing Analysis
Family-owned processing clusters in Gujarat's Unjha-Siddhpur corridor anchor supply discipline through backward integration into seed cultivation, translating acreage control into pricing power that resists spot-market volatility. Their captive sourcing from Rajasthan's Sirohi and Jalore districts insulates contract rates from monsoon-driven raw material swings that disrupt non-integrated traders.
Pricing Analysis
Volume throughput concentrates in food-grade powder where FSSAI-mandated testing compresses margins, while pharmaceutical-grade husk captures premium spreads through European Pharmacopoeia certification. Price differentiation rests on mucilage swelling index and heavy-metal documentation depth, with German and Swiss buyers paying substantial premiums for batch-level traceability. Cost compression in standard powder grades is intensifying as methylcellulose substitutes erode price floors. Industrial-grade buyers exhibit highest price sensitivity; pharmaceutical formulators show least.
Supply Chain Analysis
Regional distribution centers in Ahmedabad and Mundra feed hub-and-spoke patterns into European pharmaceutical hubs and North American supplement channels. Supply concentrates in India, with secondary processing nodes in Germany and Switzerland for supercritical CO2 extraction. Raw material flows draw from Gujarat and Rajasthan cultivation belts, with mucilage integrity and microbial purity as critical inputs. Single-source vulnerability runs through monsoon-dependent seed yields. Distribution runs through direct-procurement relationships that displace traditional trading-house intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction technology is displacing solvent-based cleaning methods, creating a capital-barrier transition that filters out subscale processors. This shift rewards operators with laboratory infrastructure and multi-jurisdictional certification pipelines.
For Market Incumbents: Anchor pharmaceutical-grade positioning through EMA-recognized GMP certification investment and supercritical extraction capacity expansion in Gujarat. Defend against methylcellulose substitution by clinical substantiation partnerships with German formulators. Prioritize backward integration into Rajasthan acreage contracts to secure seed supply against monsoon volatility. For New Entrants and Emerging Players: Capture white-space in ready-to-mix powder formats for North American dietary supplement channels where convenience positioning commands shelf space. Target EU Green Deal agricultural incentives for organic certification premiums in German and French markets. Lead with provenance-verification services that support clinical-strength fiber claims. For Investors and Strategic Acquirers: Distressed-cycle entries favor capitalized processors with dormant European Pharmacopoeia certifications in Gujarat's Unjha cluster. Long-term viability hinges on certification moats rather than volume scale. Watch FDA-European Pharmacopoeia fiber-definition harmonization disputes as inflection signal for procurement threshold shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Adoption | German pharmaceutical formulators preserve mucilage integrity for premium laxative formulations. |
| European Pharmacopoeia Certification | EMA-recognized GMP compliance unlocks protected margin pools in clinical applications. |
| Direct-Procurement Relationship Building | US supplement brands verify Gujarat cultivation practices firsthand for provenance claims. |
| Backward Integration into Seed Cultivation | Rajasthan acreage contracts insulate processors from monsoon-driven raw material volatility. |
| EU Green Deal Organic Certification | Sustainable farming credentials unlock premium positioning in German clean-label segments. |
Research Methodology
Multi-period observation of FSSAI enforcement patterns, FDA fiber-definition rulemaking, and European Pharmacopoeia compliance timelines anchored the trend analysis, supplemented by interviews with processing plant managers, pharmaceutical procurement leads at German formulators, dietary supplement brand managers in North America, and Unjha cluster logistics coordinators. Secondary validation drew from FSSAI export notifications, EMA GMP inspection databases, US FDA Nutrition Facts labeling guidance, and customs trade records. Bottom-up segment sizing triangulated against top-down market aggregation.
Segment-weighting across product type, end user, application, and grade dimensions structured the analytical framework across the projection horizon. CAGRs derived from fitted growth curves applied to certification-penetrated and non-certified volume baselines. Industry-specific forecast inputs included monsoon variability indices for Rajasthan-Gujarat cultivation belts and REACH documentation adoption rates among European buyers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Codex Alimentarius fiber-definition disputes and synthetic fiber substitution acceleration. Outputs reflect documented assumptions around regulatory stability and climate patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Tomato Seed Market
Seeds
Dragon Fruit Seeds Market
Seeds
Southeast Asia Vegetable Seed Market
Seeds
Southeast Asia Seed Market
Seeds
North America Quinoa Seeds Market
Seeds
Wax Gourd Seed Market
Seeds
Poppy Seed Market
Seeds
Morocco Seed Market
Seeds
Global Soybean Seed Market
Seeds
Organic Chia Seeds Market
Seeds
Europe Flaxseeds Market
Seeds
Africa Seed Market
Seeds
Psyllium Market
Seeds
North America Cannabis Seeds Market
Seeds
India Forage Seed Market
Seeds
Philippines Seed Market