
 North America Cannabis Seeds Market | 2026-2036
North America Cannabis Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cannabis Seeds Market Analytics
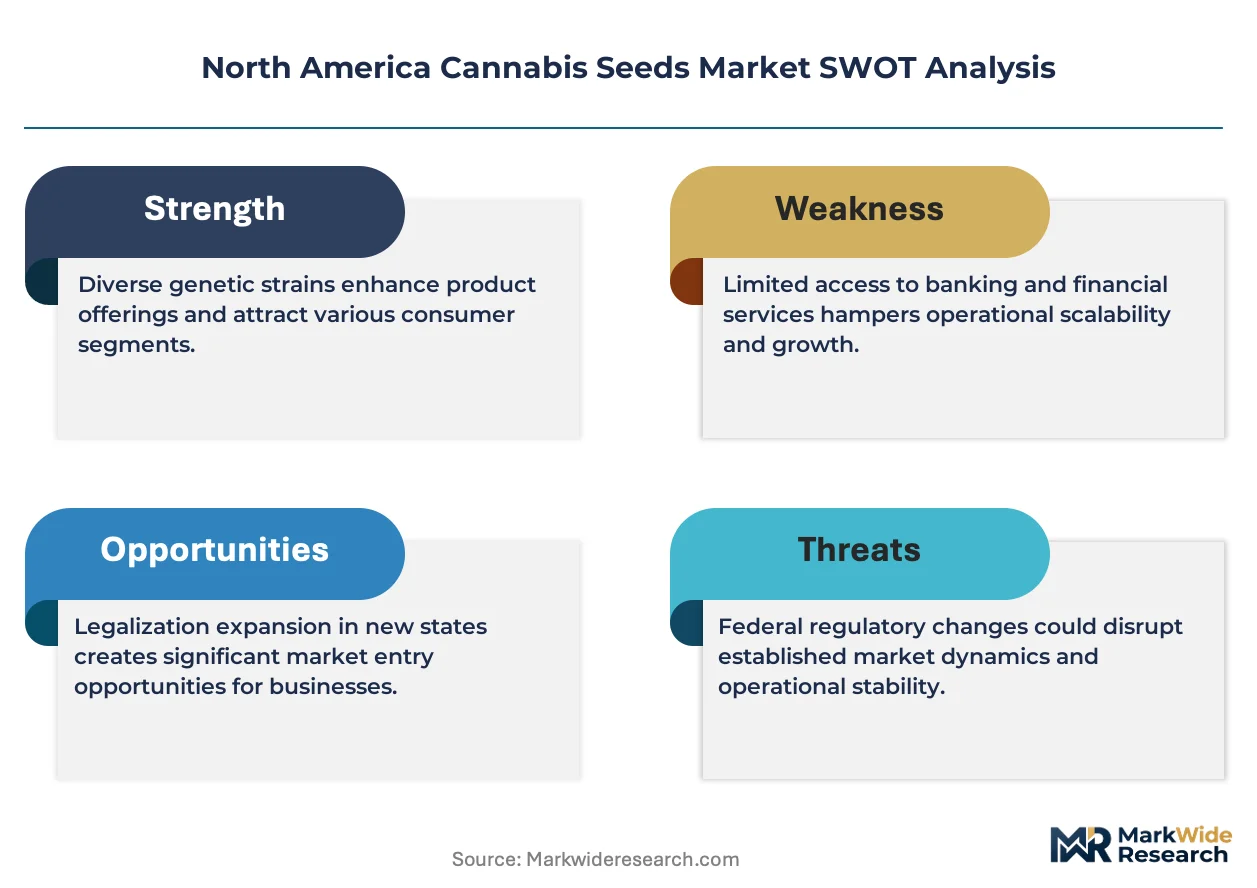
The split between premium genetics and commodity seed stock is hardening across licensed North American operations. Humboldt Seed Company leverages its California heritage to command breeder prestige among craft cultivators. Dutch Passion anchors European genetic credibility through stabilized autoflowering lines distributed via Canadian and US channels. Barney's Farm competes on strain diversity, extending catalog breadth to capture both novice home growers and commercial facilities.
Cannabis seeds are sexually propagated reproductive units containing diploid embryonic tissue encased in a durable testa, requiring controlled humidity below 8% and darkness for viable long-term storage; their primary commercial purpose is to establish genetically consistent, cannabinoid-targeted crops for regulated production. Feminized seeds dominate transaction volume across dispensary and wholesale channels due to operational efficiency in eliminating male plant culling. Autoflowering varieties represent the fastest-growing product type as indoor and greenhouse operators optimize turnaround cycles. Premium-grade genetics concentrate margin pools, with certified organic lines capturing specialty positioning.
The US Food and Drug Administration and state cannabis control boards shape product testing and packaging standards, while Health Canada oversees seed quality certification under the Cannabis Act, creating compliance costs that filter smaller operators from licensed channels. The US Farm Bill framework distinguishes hemp from marijuana at 0.3% THC, directing industrial hemp seed demand toward distinct regulatory and distribution pathways. Stakeholders must monitor evolving state reciprocity agreements and federal rescheduling deliberations that could reshape interstate commerce rules for viable genetics.
Market Dynamics
State-level legalization momentum in Illinois and New Jersey is compressing licensing timelines and forcing seed suppliers to pre-position inventory ahead of regulatory windows, creating inventory risk concentration among distributors serving newly opened adult-use markets.
Growth Catalysts
- Adult-use expansion frameworks:Illinois and New Jersey recently operationalized recreational markets, triggering wholesale seed procurement surges from licensed cultivators seeking feminized genetics for first commercial harvests.
- Autoflowering trait stabilization:Greenhouse operators across Michigan and California are adopting rapid-cycle varieties to achieve four annual harvests, compressing capital recovery timelines for indoor facilities.
- Health Canada certification reciprocity:Canadian breeders with Cannabis Act seed quality credentials gain streamlined access to US state-licensed channels, reducing cross-border compliance friction for verified genetics.
Market Restraints
- THC threshold rigidity:The US Farm Bill's 0.3% THC demarcation forces industrial hemp seed producers into segregated distribution channels, fragmenting breeding programs and limiting genetic cross-utilization.
- State regulatory fragmentation:Non-uniform testing and packaging standards across California, Michigan, and emerging markets force seed suppliers to maintain jurisdiction-specific SKUs, elevating operational complexity.
- Input cost volatility:Laboratory certification for feminization verification and pathogen screening consumes margin pools, particularly pressuring smaller breeding operations without captive testing infrastructure.
Strategic Opportunities
- Certified organic positioning:California's craft cultivator segment demonstrates willingness to pay premiums for organic-certified genetics, creating specialty margin pools distinct from commodity seed tiers.
- Direct-to-cultivator channels:E-commerce platforms with embedded compliance verification are displacing traditional wholesale distributors, enabling breeders to capture margin previously allocated to intermediaries.
- Federal rescheduling preparation:Interstate commerce liberalization under potential DEA rescheduling would enable California and Colorado genetics to penetrate eastern state markets currently served by regional breeders.
Industry Challenges
- Genetic IP enforcement complexity:Proprietary strain lineages face unauthorized reproduction across unlicensed operations, complicating royalty collection and brand integrity maintenance for established breeders.
- Legacy system integration friction:Seed-to-sale tracking mandates in Michigan and Illinois require API connectivity with state monitoring systems, forcing manual workaround costs among smaller suppliers lacking technical development capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cannabis Seeds Market |
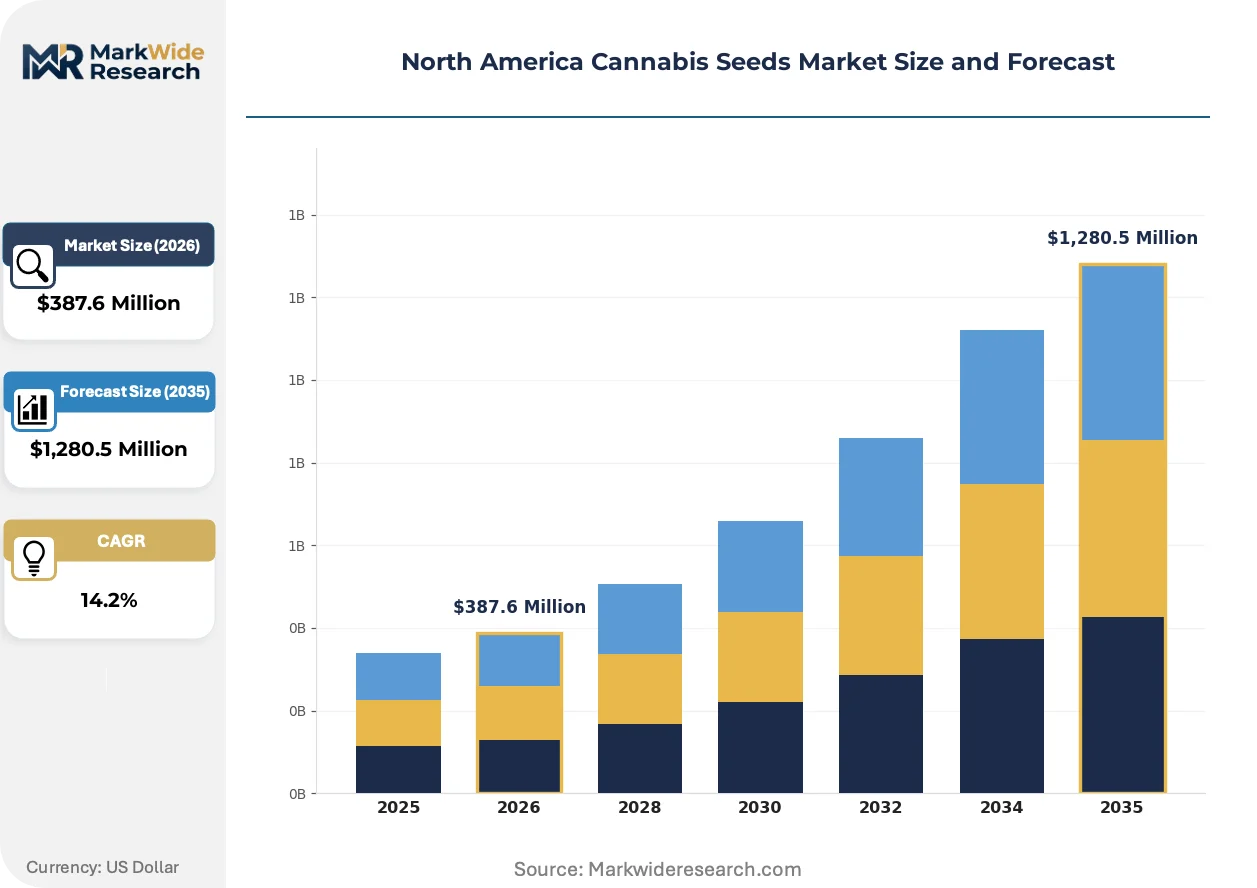
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feminized Seeds, Regular Seeds, Autoflowering Seeds, High-THC Seeds Application: Medical Use, Recreational Use, Research, Industrial Hemp Grade: Premium, Standard, Organic, Non-Organic Distribution Channel: Online Retail, Specialty Stores, Dispensaries, Wholesale |
| Companies Covered | Seed Cellar, Humboldt Seed Company, Dutch Passion, Green House Seed Co., Sensi Seeds, Sweet Seeds, Christiania Seeds, Barney's Farm, Royal Queen Seeds, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cannabis Seeds Market Evolving Landscape
Genetic verification technologies and regulatory data infrastructure are compressing transaction friction while reshaping how cultivators evaluate seed provenance and compliance credentials across North American licensed operations.
Blockchain-based genetic provenance tracking is consolidating trust mechanisms between breeders and commercial cultivators. Large-scale greenhouse operators in Michigan and California now require batch-level lineage documentation as a procurement precondition. This technology is consolidating breeder-cultivator relationships around transparent genetic history, displacing informal reputation-based verification that previously dominated wholesale transactions.
The US Farm Bill's hemp-marijuana demarcation is forcing dual-track breeding programs with divergent regulatory compliance pathways. Industrial hemp seed producers must maintain THC compliance documentation distinct from marijuana genetics, elevating administrative burden. Canadian operations under Health Canada oversight face streamlined cross-category genetic movement, creating regulatory arbitrage pressure on US-based breeding programs.
Certification-driven procurement preferences are displacing price-first buying patterns among licensed cultivators. California craft operators now prioritize organic and feminization-verified genetics over bulk commodity seed, redirecting distributor inventory composition. Michigan's commercial greenhouse sector exhibits the most pronounced shift, with procurement committees embedding quality documentation requirements into vendor scorecards.
North America Cannabis Seeds Market Segmentation
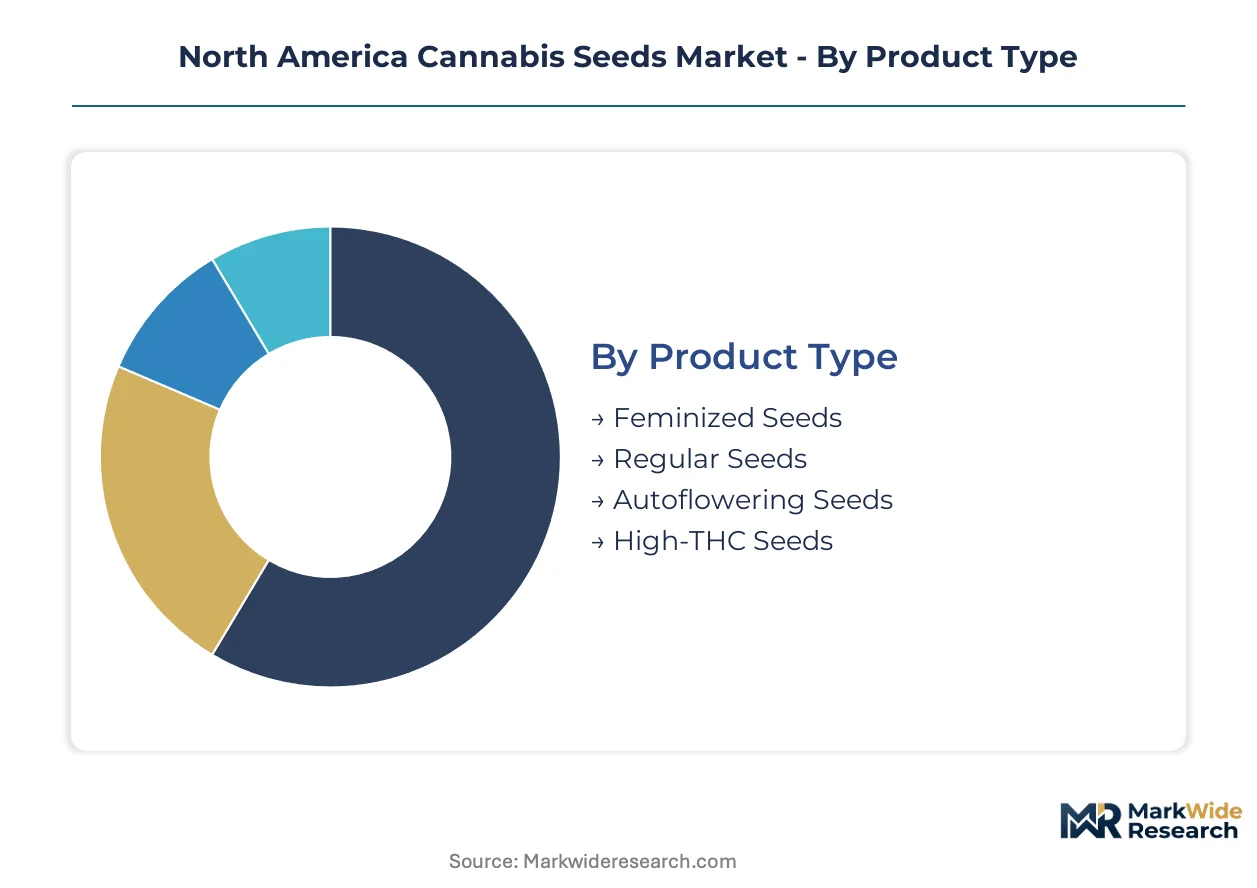
Cannabis seed purchasing patterns diverge sharply between commercial cultivators optimizing for operational throughput and craft growers prioritizing genetic provenance. Segmentation clarity enables suppliers to align breeding programs with distinct margin pools and regulatory compliance requirements across state-licensed channels.
Product Type:
Standalone seed formats dominate commercial procurement where cultivators require predictable phenotypic expression, while embedded genetic services remain nascent.
- Feminized Seeds:Diploid embryonic tissue chemically induced to express female chromosomes exclusively, eliminating male plant culling labor. Michigan greenhouse operators and California indoor facilities specify feminized stock for 95%+ flowering canopy efficiency. Health Canada certification requirements for feminization verification add laboratory cost burdens that filter smaller breeders from licensed supply chains.
- Autoflowering Seeds:Cannabis ruderalis genetics crossed with photoperiod varieties to trigger flowering independent of light cycle manipulation. Four annual harvest cycles now standard among Colorado and Michigan commercial operators compressing facility ROI timelines. Autoflowering trait instability in early-generation crosses creates quality variance risks that procurement committees address through breeder pedigree requirements.
- Regular Seeds:Sexually unmodified diploid genetics producing approximately equal male and female offspring, retaining breeding program utility for phenotype selection and strain stabilization.
- High-THC Seeds:Genetically selected lines targeting elevated tetrahydrocannabinol expression profiles, subject to state-specific potency caps that fragment demand concentration.
Feminized seeds lead volumes today; autoflowering varieties are gaining share fastest.
Application:
Cost tier stratification separates research-grade genetics commanding certification premiums from commodity industrial hemp seed sold on bulk volume metrics.
- Medical Use:Cannabinoid-profiled genetics targeting specific therapeutic indications with documented terpene and cannabinoid ratios. Illinois and New Jersey licensed medical cultivators prioritize CBD-dominant and balanced chemovars for patient formulation consistency. FDA drug development pathways for botanical cannabis extracts create parallel demand for research-grade seed with batch-level documentation.
- Recreational Use:THC-forward genetics selected for consumer sensory experience and cultivation operational efficiency. California craft and commercial operations drive strain diversity requirements spanning indica, sativa, and hybrid categories.
- Research:Standardized genetic material with verified lineage documentation for academic and clinical investigation protocols.
- Industrial Hemp:Fiber and seed-oil varieties bred for sub-0.3% THC compliance under US Farm Bill thresholds, segregated from marijuana distribution channels.
Recreational use commands the largest revenue pool; medical applications show steepest expansion trajectory as new state programs operationalize.
Grade:
Margin concentration follows certification depth, with organic credentials enabling price premiums that standard genetics cannot capture.
- Premium:Established breeder lines with multi-generation stabilization, proprietary phenotype documentation, and verified cannabinoid expression profiles. California craft cultivators pay substantial markups for Humboldt and Mendocino heritage genetics with documented organic cultivation history.
- Standard:Commercial-grade feminized and autoflowering stock meeting baseline germination and pathogen-screening thresholds without pedigree documentation. Michigan greenhouse operators prioritize standard-grade volume procurement for commodity flower production.
- Organic:Certified organic production protocols from breeding stock through seed processing, capturing specialty positioning among sustainability-focused cultivators.
- Non-Organic:Conventionally produced genetics without organic certification, dominating price-sensitive bulk procurement segments.
Premium grade leads revenue per unit; organic certification is climbing fastest as California procurement committees embed sustainability scorecards.
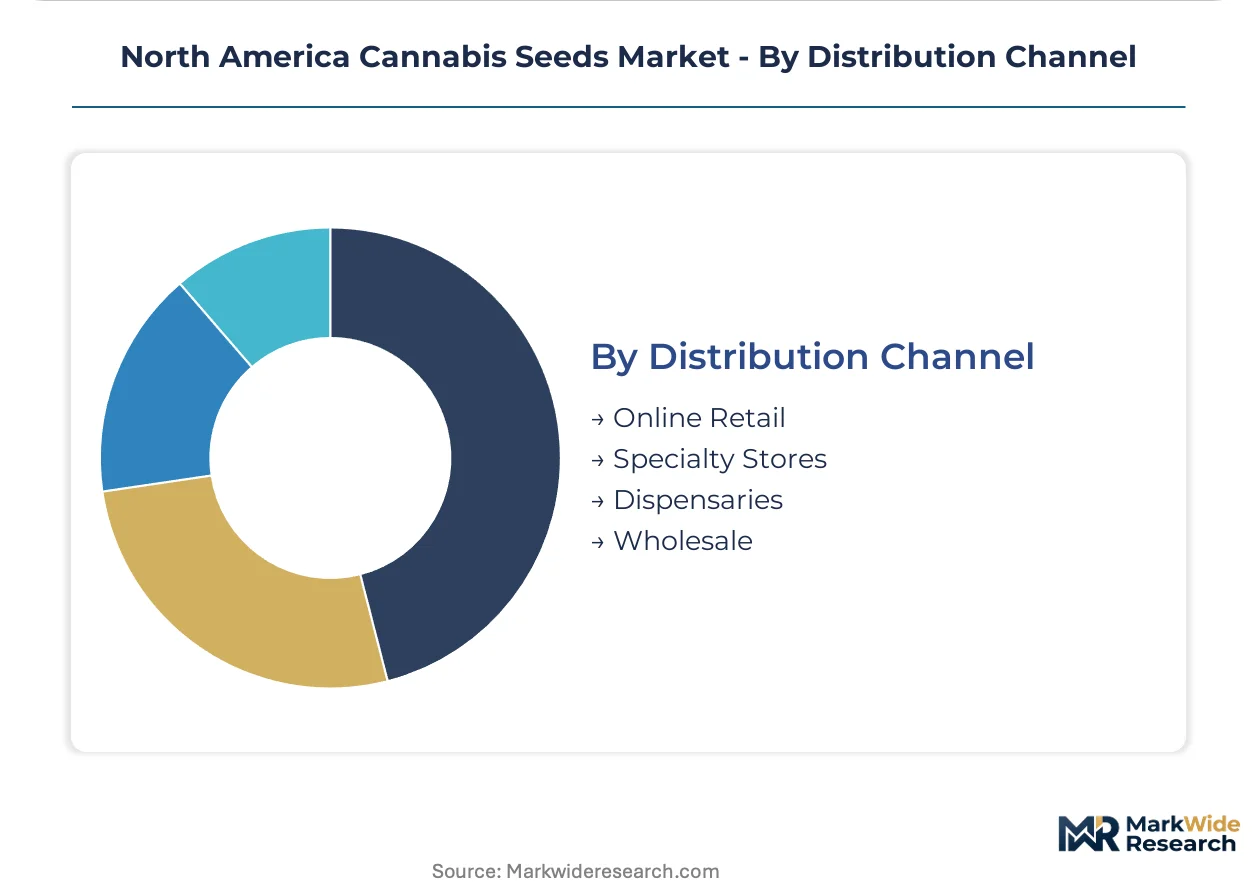
Distribution Channel:
Supply concentration favors direct breeder-to-cultivator relationships displacing traditional wholesale intermediaries in mature state markets.
- Online Retail:E-commerce platforms with embedded state compliance verification enabling direct breeder sales. California and Colorado operators increasingly bypass distributors for genetic transparency and margin capture.
- Specialty Stores:Brick-and-mortar cultivation supply retailers serving home-grower and small-scale craft segments with curated strain selections.
- Dispensaries:Adult-use retail channels in Illinois and New Jersey expanding seed sales alongside finished flower products.
- Wholesale:Traditional distributor networks pre-positioning inventory ahead of regulatory windows in newly legalized state markets.
Wholesale channels lead transaction volume today; online retail is expanding most quickly as compliance infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Experienced breeders and geneticists cluster in California's legacy cultivation corridors, anchoring premium seed development expertise that radiates across licensed North American markets.
United States
California and Michigan commercial greenhouse operators drive feminized and autoflowering seed procurement at scale. State cannabis control boards in Illinois and New Jersey enforce seed-to-sale tracking mandates through Metrc and BioTrackTHC systems. The Emerald Triangle region spanning Humboldt, Mendocino, and Trinity counties hosts the densest concentration of heritage breeders supplying craft cultivators nationwide.
Canada
Ontario and British Columbia licensed producers prioritize Health Canada-certified genetics for domestic cultivation and US export channels. The Cannabis Act requires batch-level seed quality documentation that Canadian breeders leverage for streamlined cross-border market access. Vancouver Island maintains established breeding cooperatives supplying both medical and adult-use licensed facilities.
Mexico
Jalisco and Mexico City cultivation zones anticipate regulatory clarity following Supreme Court mandates for adult-use legalization. The country's national health regulator, COFEPRIS, develops cannabis seed import protocols that will govern commercial distribution once federal frameworks operationalize. Guadalajara's agricultural research institutes position for genetic import partnerships with established North American breeders.
North America Cannabis Seeds Market Competitive Landscape
Top-tier vendors anchor heritage genetic credibility, while mid-tier operations compete on autoflowering trait stabilization and catalog breadth. The vendor base stratifies across three functional tiers: established breeders commanding breeder prestige premiums, specialized autoflowering geneticists, and regional distributors pre-positioning inventory ahead of regulatory windows. Competitive positioning crystallizes around genetic IP protection, direct-to-cultivator channel development, and organic certification acquisition.
Among heritage California breeders, Humboldt Seed Company exemplifies regional credibility monetization through documented organic cultivation history. Dutch Passion occupies a position as European autoflowering authority distributed through Canadian and US licensed channels. Barney's Farm represents catalog diversification strategy, extending strain breadth to capture both novice home growers and commercial facility procurement committees.
| Leading Market Players |
|---|
| Seed Cellar |
| Humboldt Seed Company |
| Dutch Passion |
| Green House Seed Co. |
| Sensi Seeds |
| Sweet Seeds |
| Christiania Seeds |
| Barney's Farm |
| Royal Queen Seeds |
| Others |
Value Network & Pricing Analysis
Laboratory certification costs for feminization verification and pathogen screening flow downstream through premium-grade pricing tiers, compressing margins for smaller breeding operations while concentrating pricing power among established California and Canadian breeders with captive testing infrastructure.
Pricing Analysis
Unbundled genetic material commands transactional per-unit pricing, while bundled compliance documentation and batch-level lineage verification capture recurring service premiums. Three-tier pricing structure across premium, standard, and economy levels separates Humboldt heritage genetics from Michigan greenhouse commodity stock and unverified home-grower assortments. Price differentiation hinges on organic certification depth and feminization verification rigor. Pricing pressure stems from input cost volatility in laboratory testing, with Michigan commercial operators exhibiting highest price sensitivity and California craft cultivators showing lowest.
Supply Chain Analysis
Regional distribution centers in Ontario, British Columbia, and California anchor hub-and-spoke patterns serving state-licensed channels across the US and Canada. Primary breeding concentration rests on California's Emerald Triangle, Vancouver Island cooperatives, and Dutch genetic houses distributing through Canadian portals. Raw material dependencies include stabilized ruderalis genetics, certified organic breeding stock, and laboratory reagents for feminization verification. Single-source vulnerability concentrates in Health Canada-certified genetics for cross-border US market access. Distribution runs through direct-to-cultivator e-commerce platforms displacing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through certified organic tier migration, as California procurement committees embed sustainability scorecards that redirect volume toward premium-grade genetics with documented cultivation history.
For Market Incumbents: Extend organic certification coverage to capture specialty positioning among sustainability-focused craft cultivators. Deepen backward integration into laboratory testing infrastructure to neutralize input cost volatility pressuring smaller competitors. Defend against unlicensed reproduction threats through blockchain-based genetic provenance tracking that displaces informal reputation-based verification. For New Entrants and Emerging Players: The gap between premium heritage genetics and unverified commodity stock presents white-space opportunity in mid-tier certified feminized offerings. Target Michigan greenhouse operators seeking rapid-cycle autoflowering varieties with verified germination rates. Enter through embedded compliance e-commerce platforms that bypass established distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where laboratory testing infrastructure requirements filter sub-scale breeding operations from licensed supply chains. Long-term viability favors vertically integrated breeders with captive certification capacity and direct channel control. Target acquisition archetype: Canadian operations with Health Canada credentials enabling streamlined US market access. Watch federal rescheduling deliberations as interstate commerce liberalization signal.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Acquisition | Captures California craft cultivator premiums through documented sustainable breeding protocols. |
| Direct-to-Cultivator Channel Development | Displaces wholesale intermediaries via e-commerce platforms with embedded state compliance verification. |
| Blockchain Provenance Implementation | Consolidates breeder-cultivator trust through transparent batch-level genetic history documentation. |
| Autoflowering Trait Stabilization R&D | Enables four annual harvest cycles for Michigan and Colorado greenhouse operators compressing facility ROI. |
| Health Canada Credential Leverage | Streamlines cross-border US market access for verified genetics under state reciprocity frameworks. |
Research Methodology
Direct dialogue with breeding program directors, state cannabis control board officials, licensed cultivator procurement managers, and laboratory certification specialists grounded qualitative findings. Secondary validation drew from Health Canada Cannabis Act filings, US state regulatory bulletins, FDA botanical drug development pathways, and licensed producer financial disclosures. Bottom-up and top-down triangulation cross-checked transaction volume estimates against facility capacity buildouts and seed-to-sale tracking data.
Bottom-up modeling aggregated cultivator procurement patterns across California, Michigan, Illinois, and New Jersey licensed operations, while top-down analysis tracked regulatory window timing and greenhouse facility expansion announcements. Segmentation dimensions included product type, application tier, certification grade, and distribution channel maturity. CAGRs were derived from facility ROI timelines and harvest cycle compression trends. Forecast inputs incorporated state legalization momentum and federal rescheduling probability assessments across the projection horizon.
Caveats apply where federal rescheduling delays or state regulatory reciprocity breakdowns could materially shift the outlook for interstate genetics commerce. Forecasts reflect assumptions around laboratory certification cost trajectories and organic certification adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Asia-Pacific Cannabis Seeds Market
Seeds
Melon Seed Market
Seeds
Russia Seed Market
Seeds
Psyllium Market
Seeds
North America Maize Seed Treatment Market
Seeds
Asia-Pacific Chia Seed Market
Seeds
Africa Peas Market
Seeds
Grass Seed Market
Seeds
Global Sports Turf Seed Market
Seeds
Europe Vegetable Seed Market
Seeds
Safflower Seeds Market
Seeds
Asia-Pacific Onion Seed Market
Seeds
Asia-Pacific Rice Seed Market
Seeds
Hybrid Rice Seeds Market
Seeds
Wax Gourd Seed Market
Seeds
Seed Health Market