
 Europe Flaxseeds Market | 2026-2036
Europe Flaxseeds Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Flaxseeds Market Intelligence
EU Organic Regulation certification is bifurcating the competitive landscape into certified and conventional supply tiers. Archer Daniels Midland Company leverages its continental grain handling infrastructure to sustain volume leadership across multiple European markets. Cargill Incorporated anchors its position through backward integration into oilseed crushing and refined flaxseed oil distribution. Linwoods (NI) Limited differentiates via specialization in premium ground seed and milled products targeting health-conscious retail channels in the United Kingdom and Ireland.
Europe flaxseeds comprise the dried ripe seeds of Linum usitatissimum, typically containing 35-45% oil by weight with alpha-linolenic acid representing 50-60% of total fatty acid content, primarily serving food fortification, dietary supplement, and industrial oil applications. Brown flaxseeds dominate volume throughput in animal feed and bulk oil extraction due to lower farmgate premiums and established crushing economics. Golden flaxseeds command premium positioning in bakery and consumer packaged goods where visual appeal and milder flavor profiles justify price separation. The organic flaxseeds category within product type is attracting disproportionate investment as EFSA health claim validations and retailer sustainability mandates tighten conventional product access.
EFSA nutrition and health claims regulation, EU Organic Regulation, and REACH chemical safety frameworks collectively shape ingredient approval timelines, labeling requirements, and import compliance burdens for flaxseed suppliers operating across member states. EFSA's ongoing evaluations of omega-3 cardiovascular and digestive health claims directly influence finished product marketing permissions and downstream demand pull from nutraceutical formulators. Stakeholders must monitor evolving EU deforestation-free supply chain regulations and their potential to redirect sourcing relationships toward verified European and Black Sea origin programs.
Market Dynamics
EFSA's validation of omega-3 cardiovascular health claims is redirecting formulation pipelines across European food manufacturers, compressing approval timelines and tightening organic certification requirements simultaneously. This regulatory momentum is bifurcating procurement into certified and conventional supply tiers.
Growth Catalysts
- EU Organic Regulation:Retailer sustainability mandates and clean-label formulation requirements are accelerating certified organic brown and golden flaxseed demand across French and German bakery channels.
- Functional food expansion:Oilseed processing infrastructure in Poland and France enables rapid scale-up of flaxseed-fortified consumer packaged goods with validated health positioning.
- Alpha-linolenic acid concentration:The 50-60% ALA content in European flaxseed varieties supports differentiated nutraceutical applications targeting cardiovascular wellness segments.
Market Restraints
- Import dependency concentration:Black Sea origin programs dominate non-European supply, exposing crushers to geopolitical disruption and currency volatility in Ukrainian and Russian export corridors.
- REACH compliance burden:Chemical safety documentation requirements for flaxseed oil derivatives extend ingredient approval timelines by 12-18 months for novel food applications.
- Substitute oilseeds:Chia and hemp seed alternatives with comparable omega-3 profiles are capturing shelf space in premium health food retail, compressing flaxseed margin expansion.
Strategic Opportunities
- Polish processing expansion:Underdeveloped organic crushing capacity in Lower Silesia and Greater Poland voivodeships offers first-mover positioning for certified oil extraction infrastructure.
- EU deforestation-free regulations:Verified European origin programs will command premium positioning as supply chain traceability mandates tighten import access for non-compliant sources.
- Pharmaceutical ALA isolation:Convergence of supercritical CO2 extraction and molecular distillation technologies is enabling high-purity alpha-linolenic acid for prescription nutraceutical formulations.
Industry Challenges
- Organic certification lag:Three-year conversion timelines for conventional farmland block rapid supply response to EFSA-validated demand surges in bakery and supplement channels.
- Specialized oilseed handling:Cross-contamination protocols for omega-3-sensitive crushing equipment require capital-intensive facility segregation that mid-scale processors struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Flaxseeds Market |
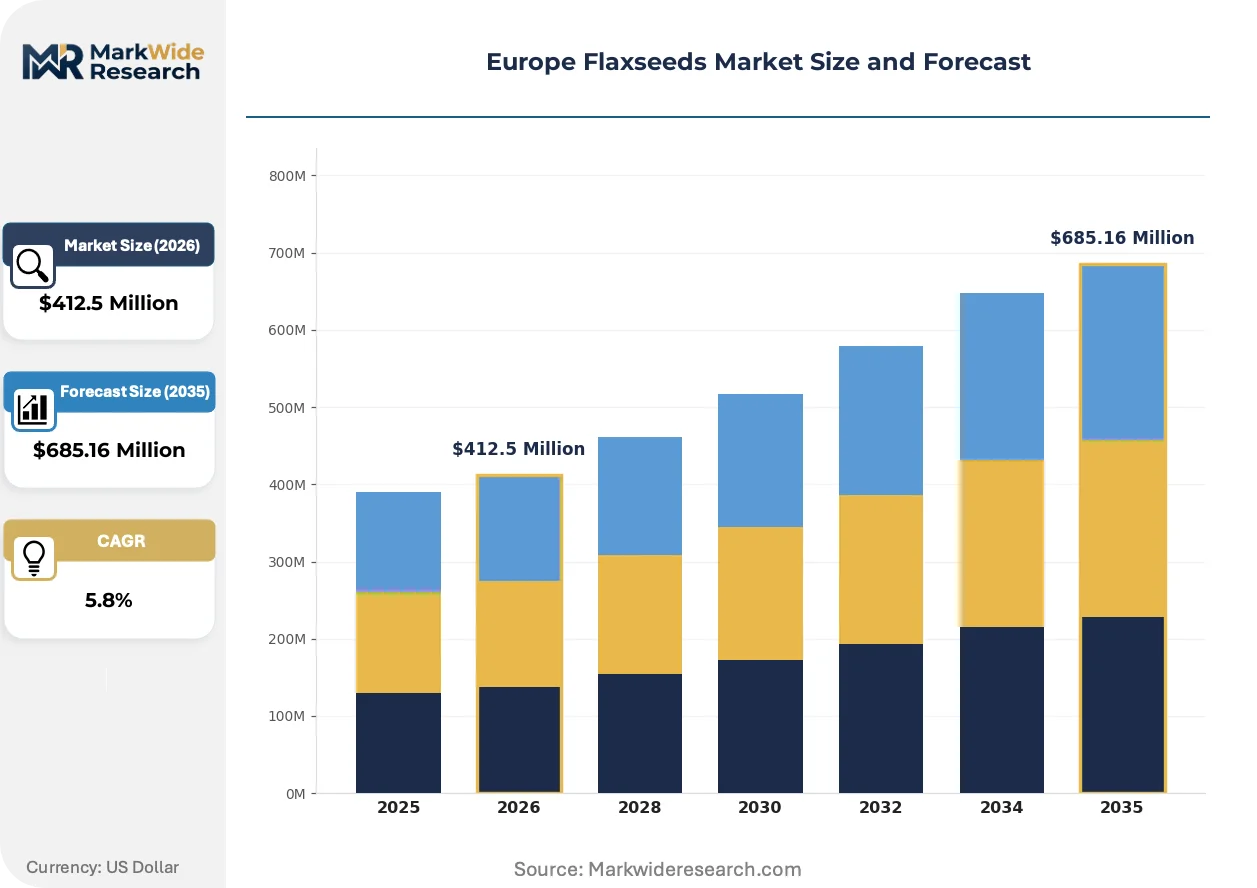
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brown Flaxseeds, Golden Flaxseeds, Organic Flaxseeds, Conventional Flaxseeds End User: Food Industry, Nutraceuticals, Animal Feed, Personal Care Form: Whole Seeds, Ground Seeds, Flaxseed Oil, Flaxseed Meal Packaging Type: Bags, Tins, Pouches, Bulk Containers |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Richardson International Limited, TA Foods Ltd, AgMotion, Inc., CanMar Foods Ltd, Bioriginal Food & Science Corporation, Linwoods (NI) Limited, Simosis International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Flaxseeds Market Strategic Shifts & Innovations
Clean-label formulation pressures and precision nutrition are compressing traditional commodity trading patterns, forcing suppliers to demonstrate chain-of-custody documentation from farmgate to finished product.
Cold-press micro-milling technology is miniaturizing. German equipment manufacturers are deploying compact 50-200 kg/hour units directly into bakery and supplement manufacturing facilities. This distributed processing model is compressing transportation costs and enabling just-in-time milled flaxseed incorporation with guaranteed freshness dating.
EFSA's ongoing cardiovascular health claim evaluations are tightening. The regulator's demand for human intervention trials with defined ALA dosage thresholds is extending validation timelines. French and German finished product marketers are responding by pre-submission engagement with EFSA's nutrition panel, front-loading clinical investment before commercial launch commitments.
Direct farm contracting is displacing spot market procurement. Large French retail cooperatives and German functional food manufacturers are establishing multi-year purchase agreements with certified organic growers in Picardy and Brandenburg. This bilateral sourcing model is most visible in golden flaxseed varieties where visual consistency requirements exceed commodity tolerance bands.
Europe Flaxseeds Market Segmentation
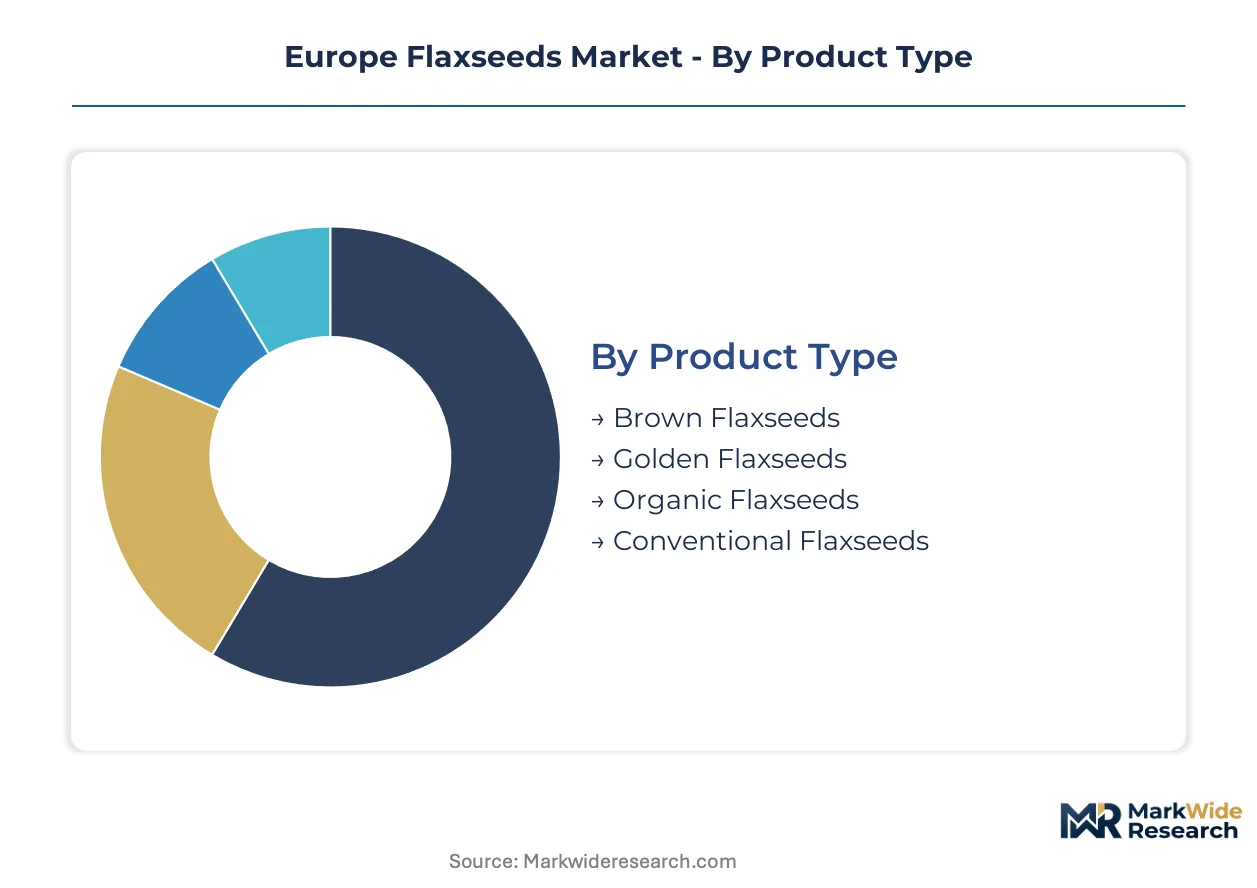
EFSA health claim validations and EU Organic Regulation compliance tiers are fragmenting procurement patterns across European flaxseed categories. Buyers now segment sourcing decisions by certification status, oilseed crushing economics, and finished product positioning requirements simultaneously.
Product Type:
REACH documentation burdens and EFSA omega-3 claim pathways diverge sharply between certified and conventional supply tiers.
- Brown Flaxseeds:These varieties contain 35-45% oil by weight with alpha-linolenic acid comprising 50-60% of total fatty acid content. Animal feed compounders in Poland and bulk oil crushers in France concentrate procurement here due to lower farmgate premiums and established crushing infrastructure.
- Organic Flaxseeds:EU Organic Regulation certification mandates three-year farmland conversion timelines that constrain rapid supply scaling. German and French bakery manufacturers are redirecting formulation pipelines toward certified organic brown and golden varieties as retailer sustainability mandates tighten conventional product access.
- Golden Flaxseeds:Visual consistency and milder flavor profiles command premium positioning in consumer packaged goods across United Kingdom and Ireland retail channels.
- Conventional Flaxseeds:Spot market liquidity remains highest for non-certified brown varieties serving industrial oil extraction and animal nutrition applications.
Brown flaxseeds handle the majority of throughput; organic flaxseeds are expanding most quickly on share.
End User:
Application-specific ALA concentration requirements and formulation complexity drive margin stratification across downstream channels.
- Food Industry:Bakery and functional food manufacturers in France and Germany leverage validated EFSA cardiovascular health claims to differentiate fortified bread, cereal, and dairy alternative lines. Clean-label formulation pressures intensify procurement scrutiny on chain-of-custody documentation.
- Nutraceuticals:Supercritical CO2 extraction and molecular distillation technologies are enabling high-purity alpha-linolenic acid isolation for prescription supplement formulations targeting cardiovascular wellness segments.
- Animal Feed:Poultry and ruminant nutritionists in Poland incorporate brown flaxseed meal for omega-3 enriched egg and dairy production.
- Personal Care:Cosmetic formulators utilize refined flaxseed oil derivatives for emollient and barrier function applications in premium skincare.
The food industry commands the largest volume absorption; nutraceuticals demonstrate the steepest expansion trajectory.
Form:
Processing intensity and shelf stability requirements determine logistics economics and customer switching costs.
- Ground Seeds:Cold-press micro-milling technology deployment by German equipment manufacturers enables 50-200 kg/hour compact units for direct bakery and supplement manufacturing facility integration. This distributed processing model compresses transportation expenditure and enables just-in-time freshness dating.
- Flaxseed Oil:Refined and crude oil fractions serve distinct customer tiers with differentiated oxidation stability specifications and packaging requirements.
- Whole Seeds:Longest shelf stability and lowest per-unit processing cost position this form for commodity trading and export-oriented crushing operations.
- Flaxseed Meal:Defatted cake byproducts from oil extraction channel into animal feed and fiber supplement applications with compressed margin profiles.
Ground seeds capture the dominant value-added position; flaxseed oil is climbing the fastest on application breadth.
Packaging Type:
Channel access requirements and oxidation protection needs shape format selection across retail and industrial segments.
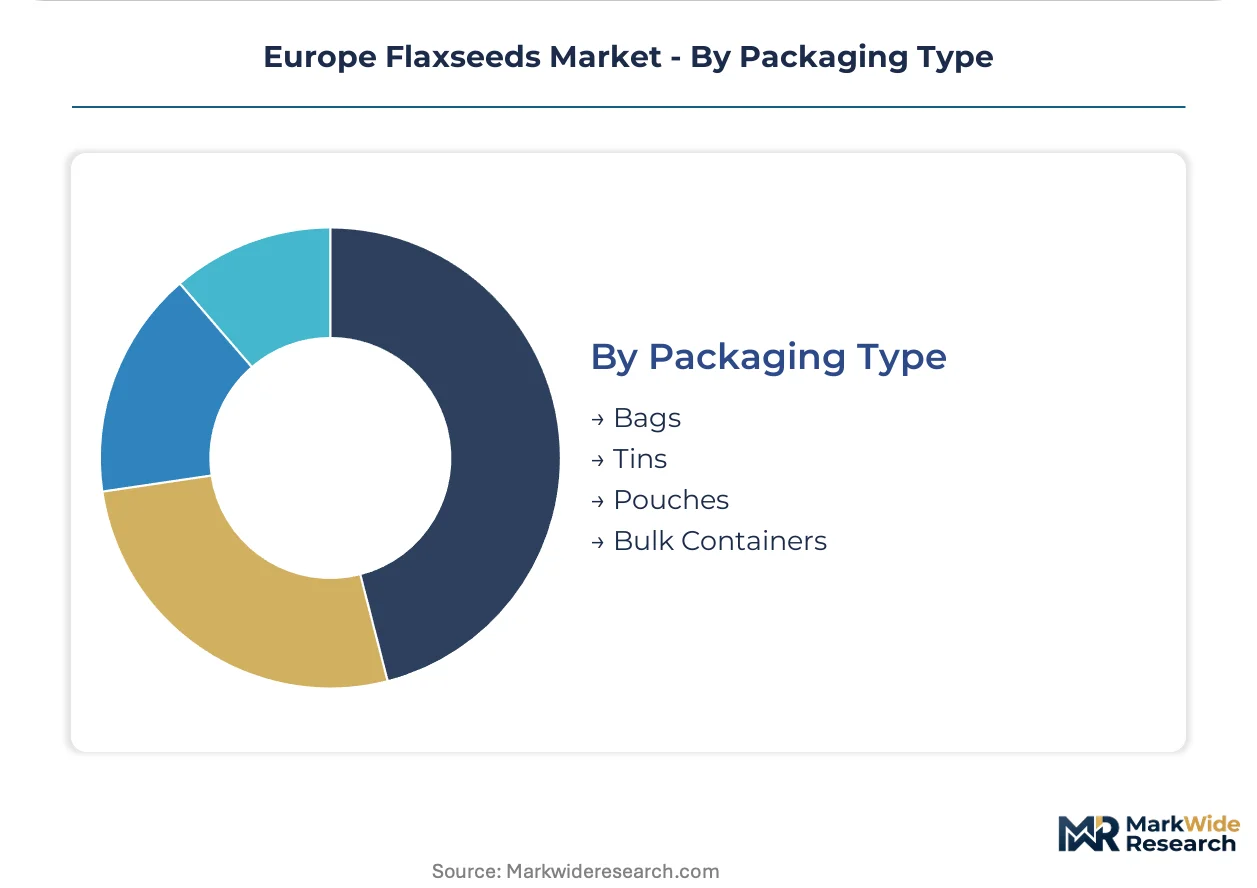
- Bulk Containers:1,000 kg flexible intermediate bulk containers and tanker shipments minimize unit logistics costs for oilseed crushers and compound feed manufacturers with dedicated handling infrastructure.
- Pouches:Resealable flexible formats with nitrogen flushing accommodate ground seed and oil products requiring oxidation protection in health food retail.
- Bags:Multi-wall paper and woven polypropylene constructions serve conventional whole seed distribution through agricultural supply cooperatives.
- Tins:Metal canister formats command shelf presence in premium specialty retail channels with extended shelf life requirements.
Bulk containers manage the greatest tonnage movement; pouches are gaining share fastest on clean-label retail expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European food manufacturers and nutraceutical formulators cluster procurement decisions around EFSA-validated health claims and EU Organic Regulation compliance tiers. Bakery chains in France and Germany drive premium golden flaxseed demand, while Polish crushers anchor brown variety throughput for compound feed applications.
France
EFSA omega-3 cardiovascular claim validations pull formulation investment toward Île-de-France and Hauts-de-France bakery clusters. The EU Organic Regulation three-year conversion mandate constrains rapid supply scaling from Picardy growers. Large retail cooperatives in northern France now contract directly with certified organic producers to secure golden flaxseed visual consistency for consumer packaged goods lines.
Germany
Clean-label formulation pressures from Berlin-Brandenburg and Bavaria retail chains redirect procurement toward certified organic brown and golden varieties. REACH chemical safety documentation extends novel food approval timelines for flaxseed oil derivatives. German equipment manufacturers in Baden-Württemberg deploy compact cold-press micro-milling units directly into bakery facilities, compressing transportation costs and enabling just-in-time freshness dating.
Poland
Animal feed compounders in Greater Poland and Lower Silesia voivodeships concentrate brown flaxseed procurement for omega-3 enriched egg and dairy production. Underdeveloped organic crushing capacity creates first-mover positioning opportunities for certified oil extraction infrastructure. Polish oilseed processing clusters enable rapid scale-up of flaxseed-fortified consumer packaged goods with validated EFSA health positioning for export markets.
United Kingdom
Health-conscious retail channels in London and the Southeast drive premium positioning for ground seed and milled flaxseed products. Brexit-adjusted import compliance burdens reshape sourcing relationships toward verified European origin programs. Specialist health food distributors across England and Ireland prioritize chain-of-custody documentation from farmgate to finished product.
Netherlands
Rotterdam port logistics and Randstad distribution infrastructure facilitate Black Sea origin flaxseed intake for continental European crushers. EU deforestation-free supply chain regulations tighten import access for non-compliant Ukrainian and Russian sources. Dutch traders increasingly verify European and Black Sea origin programs to preempt premium positioning as traceability mandates harden.
Europe Flaxseeds Market Key Industry Players
Player mix skews toward integrated grain handlers and specialized health food processors with divergent scale requirements. Continental crushing infrastructure dominates volume leadership, while premium milled product specialists capture health-conscious retail channels. Three archetypes define competitive positioning: multinational grain traders with backward integration into oilseed crushing, regional equipment-integrated processors, and specialist health food marketers. Dominant competitive moves include direct farm contracting for certified organic supply and distributed micro-milling technology deployment into end-user facilities.
Among integrated grain handlers, Archer Daniels Midland Company and Cargill Incorporated exemplify scale-driven archetypes with continental infrastructure spanning multiple European markets. Linwoods (NI) Limited occupies a specialist position within the premium milled product tier, targeting health-conscious retail channels in the United Kingdom and Ireland. These three entities represent the structural bifurcation between volume-led crushing economics and value-added health food positioning that defines procurement segmentation across brown, golden, and certified organic supply tiers.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Richardson International Limited |
| TA Foods Ltd |
| AgMotion, Inc. |
| CanMar Foods Ltd |
| Bioriginal Food & Science Corporation |
| Linwoods (NI) Limited |
| Simosis International |
| Others |
Cost & Logistics Intelligence
Crushing capacity utilization rates in French and Polish oilseed facilities establish floor pricing for brown flaxseed varieties, while organic certification scarcity in German and Baltic growing regions elevates premium tier thresholds. Scale asymmetry between commodity crushers and micro-milling specialists concentrates bargaining power upstream, compressing mid-processor margins.
Pricing Analysis
Cost-plus contracts indexed to Black Sea FOB benchmarks dominate spot procurement for conventional brown varieties, with EU Organic Regulation certification adding tiered premiums for certified supply. Price differentiation hinges on EFSA health claim validation status and three-year organic conversion timelines. Pricing pressure intensifies in golden flaxseed segments as visual consistency requirements tighten specification tolerances. Animal feed compounders exhibit highest price sensitivity, while nutraceutical formulators absorb organic premiums for validated ALA concentration guarantees.
Supply Chain Analysis
Ukraine and Russia anchor non-European flaxseed supply for continental crushers, with French Picardy and German Brandenburg growers commanding premium positioning for certified organic output. Raw material flows draw from Black Sea export corridors, Baltic organic conversion programs, and Black Sea origin verification schemes. Single-source vulnerability concentrates in Ukrainian export logistics subject to geopolitical disruption. Distribution runs through Rotterdam port infrastructure for bulk intake, with direct farm contracting displacing spot procurement for certified organic tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of certified organic crushing capacity with cross-contamination protocols creates structural bottlenecks for EFSA-validated supply expansion. The capability gap sits most acutely with mid-scale processors lacking capital for facility segregation.
For Market Incumbents: Shield organic supply positions through multi-year farm contracting in Picardy and Brandenburg conversion zones. Accelerate backward integration into certified oilseed crushing to preempt competitor access to EFSA-validated supply tiers. Chia and hemp seed substitution threats in premium retail channels demand rapid certification pipeline investment. For New Entrants and Emerging Players: Differentiate on Polish organic crushing infrastructure where Lower Silesia and Greater Poland voivodeships offer first-mover positioning. Target underdeveloped certified oil extraction capacity serving German bakery and supplement manufacturers. Establish direct equipment-integrated micro-milling partnerships with Baden-Württemberg machinery suppliers to bypass conventional distribution. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors equipment-integrated processors with captive organic supply and distributed micro-milling deployment capabilities. Long-term viability rests on EFSA claim validation durability and EU deforestation-free regulatory enforcement trajectories. Monitor organic farmland conversion completion rates in northern France and eastern Germany as inflection indicators for certified supply elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Farm Contracting | Secures EFSA-validated organic supply chains through multi-year Picardy and Brandenburg grower agreements. |
| Micro-Milling Equipment Deployment | Compresses transportation costs via Baden-Württemberg compact unit integration into bakery facilities. |
| Organic Certification Investment | Preempts EU Organic Regulation compliance barriers tightening conventional product retail access. |
| Polish Crushing Capacity Expansion | Captures first-mover positioning in underdeveloped Lower Silesia certified oil extraction infrastructure. |
| Deforestation-Free Verification | Aligns sourcing with tightening EU supply chain traceability mandates for Black Sea origin programs. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with oilseed procurement managers at French and German bakery manufacturers, crushing facility operators in Polish voivodeships, and regulatory affairs specialists navigating EFSA health claim pathways. Secondary validation drew from EU Organic Regulation certification databases, EFSA nutrition panel submissions, REACH chemical safety documentation, and customs trade flows through Rotterdam port authorities. Bottom-up volume modeling triangulated against top-down market sizing across product type, end-use application, and form factor segmentation.
Across the analysis window, the forecasting framework modeled price-volume dynamics by certification tier, crushing economics, and retail channel positioning. CAGRs were derived from trend extrapolation of EFSA validation timelines, organic farmland conversion rates, and equipment deployment patterns in distributed micro-milling. Industry-specific inputs included ALA concentration specifications, oxidation stability requirements for oil derivatives, and clean-label formulation penetration in German and French retail chains.
Decision-makers should treat outputs as directional under stable EFSA regulatory interpretation and intact Black Sea export corridor assumptions; material deviation in geopolitical conditions or health claim validation scope would warrant model refresh. Recalibration cycles align with material shifts in EU deforestation-free enforcement, organic certification capacity, and substitute oilseed competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Garden Seeds Market
Seeds
Africa Chia Seeds Market
Seeds
United States Garden Seeds Market
Seeds
Cover Crop Seed Varieties Market
Seeds
Seed Cracker Market
Seeds
North America Vegetable Seed Market
Seeds
South America Quinoa Seeds Market
Seeds
Asia-Pacific Vegetable Seed Market
Seeds
Thailand Seed Market
Seeds
North America Grain Seed Market
Seeds
Global Oilseed Market
Seeds
India Vegetable Seed Market
Seeds
Hybrid Rice Seeds Market
Seeds
India Rice Seed Market
Seeds
South America Vegetable Seed Market
Seeds
Russia Forage Seed Market