
 Europe Vegetable Seed Market | 2026-2036
Europe Vegetable Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Vegetable Seed Market Foresight
Modular trait stacking in hybrid vegetable seeds is consolidating buyer choice around disease-resistance bundles rather than standalone varieties. Bayer AG leverages its vegetable seed pipeline to anchor positions in tomato and pepper genetics. Rijk Zwaan Zaadteelt en Zaadhandel B.V. sustains Dutch greenhouse dominance through proprietary rootstock programs. Enza Zaden BV differentiates via high-wire cucumber and sweet pepper breeding for Mediterranean protected agriculture.
Europe vegetable seed comprises genetically stabilized propagules bred for specific agro-climatic zones, with hybrid lines requiring controlled pollination between inbred parent lines to express heterosis in yield, uniformity, and pathogen resistance. These seeds serve commercial growers supplying retail chains and food processors with volume-contracted produce. Hybrid seeds occupy the dominant value share as growers prioritize single-season performance and shelf-life extension. Open-pollinated varieties retain footholds in organic farming segments where seed-saving compliance and lower input costs govern selection. Heirloom categories command niche premiums in direct-to-consumer channels emphasizing varietal provenance and flavor differentiation.
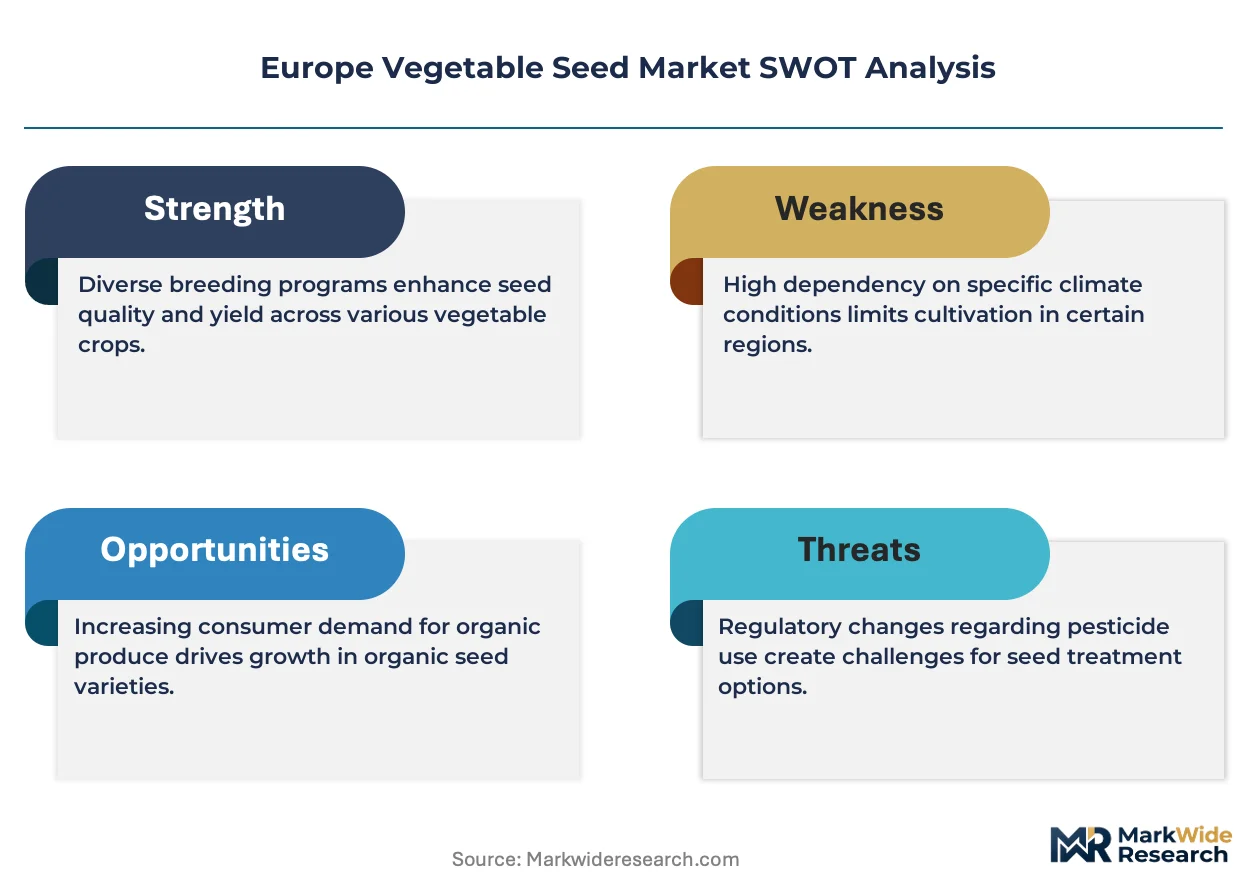
EU Green Deal targets and REACH chemical governance shape breeding priorities by restricting candidate trait chemistries and accelerating low-input variety development. EFSA novel food and feed assessments, alongside national variety registration through CPVO and member-state authorities, gate market access for new cultivars. Stakeholders must monitor evolving EU AI Act implications for genomic selection algorithms and decide whether to build in-house bioinformatics capacity or partner with specialized service providers.
Market Dynamics
The EU Green Deal's pesticide reduction mandates are compressing breeding timelines as seed developers race to deliver disease-resistant genetics before 2030 compliance deadlines hit commercial growers.
Growth Catalysts
- Protected Cultivation Expansion:Dutch greenhouse operators are extending acreage under high-tech glass, pulling demand for hybrid tomato and pepper varieties optimized for controlled environments.
- REACH Chemical Governance:ECHA's tightening candidate substance restrictions are accelerating breeder investment in low-input trait stacks that reduce agrochemical dependency.
- CPVO Fast-Track Registration:The Community Plant Variety Office's streamlined examination protocols for DUS-tested hybrids are cutting time-to-market for new cultivars entering the EU seed catalog.
Market Restraints
- Parent Line Concentration:Inbred germplasm for hybrid production concentrates among three Dutch breeding clusters, creating genetic bottleneck risk across European supply.
- Energy Input Volatility:Natural gas price swings directly destabilize greenhouse heating economics, eroding grower willingness to pay premium seed prices for protected-culture varieties.
- EFSA Novel Trait Assessment:Extended timelines for stacked transgenic event approvals create regulatory friction that delays CRISPR-edited variety commercialization despite exclusion from GMO frameworks.
Strategic Opportunities
- Poland Protected Agriculture:Underpenetrated high-wire cucumber and sweet pepper segments in Polish commercial greenhouses offer expansion terrain for Dutch genetics adapted to continental climate stress.
- Organic Seed Mandates:EU Farm to Fork targets for 25% organic farmland by 2030 are creating regulatory tailwind for open-pollinated and hybrid organic-compliant variety development.
- Genomic Selection Convergence:Machine learning algorithms trained on multi-environment trial data are compressing breeding cycles when integrated with high-throughput phenotyping platforms.
Industry Challenges
- Bioinformatics Talent Scarcity:Breeding programs face acute shortage of computational biologists capable of deploying genomic selection pipelines for polygenic trait optimization.
- Seed Health Certification Complexity:National phytosanitary requirements diverging from EPPO standards create compliance fragmentation for cross-border seed movement within the single market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Vegetable Seed Market |
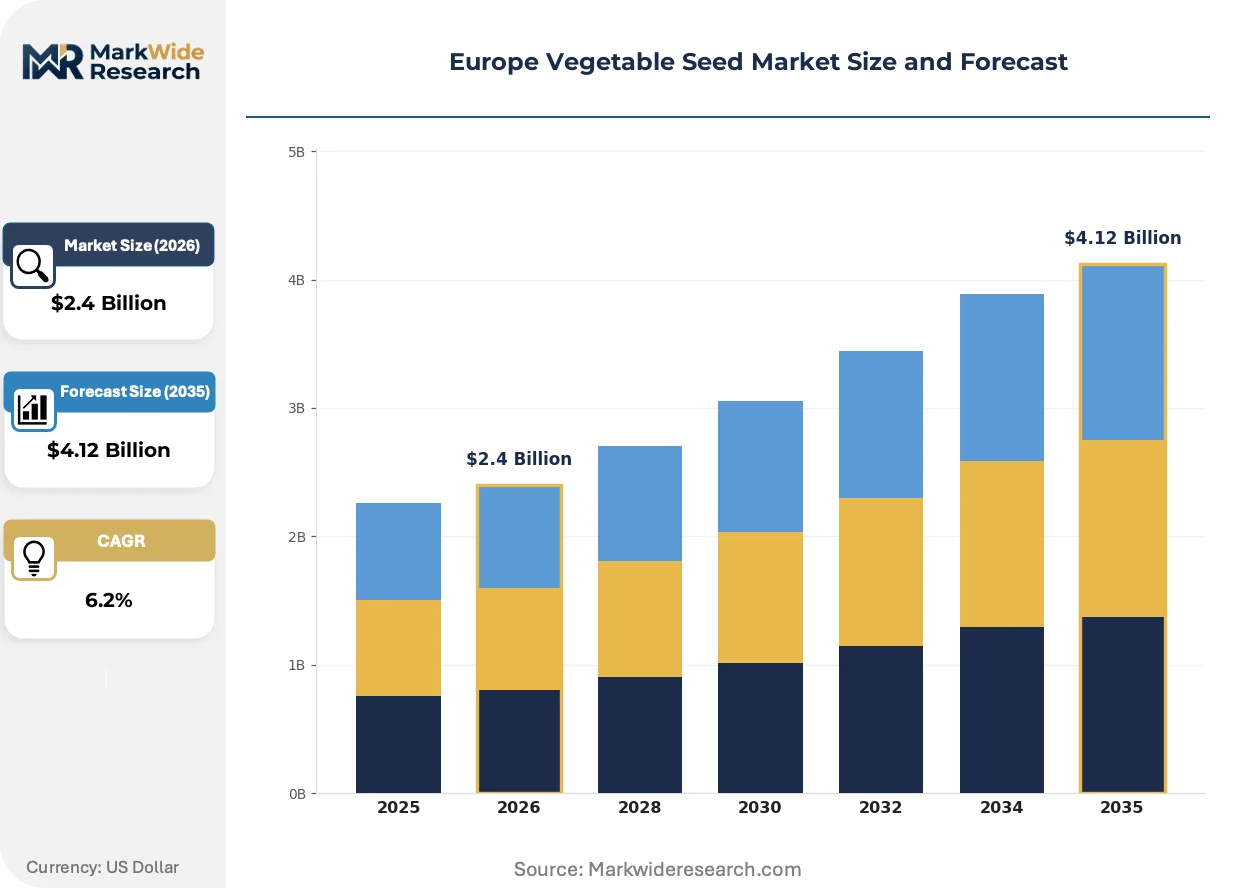
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid, Open-Pollinated, Heirloom, GMO End Use Industry: Agriculture, Horticulture, Greenhouse, Organic Farming Packaging Type: Bulk, Retail Packs, Seed Bags, Sachets Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Distributors |
| Companies Covered | Rijk Zwaan Zaadteelt en Zaadhandel B.V., Enza Zaden BV, Syngenta Group, Nunhems BV, Bejo Zaden BV, Groupe Limagrain Holding S.A., BASF SE, Axia Vegetable Seeds, Bayer AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Vegetable Seed Market Shifts & Advancements
Gene editing platforms are compressing trait introgression timelines while digital phenotyping infrastructure reshapes how breeders validate performance claims across heterogeneous European agro-climates.
CRISPR-Cas9 applications in vegetable breeding are absorbing regulatory uncertainty as breeders navigate EFSA's evolving stance on site-directed nuclease products. Dutch tomato and brassica programs are adopting edited lines for powdery mildew resistance at accelerated pace. The technology is absorbing development risk that previously terminated projects at the field trial stage.
REACH authorization requirements for candidate list substances are forcing reformulation of seed treatment chemistries. ECHA's 2024-2027 sunset date schedule for approved active ingredients is compressing the effective patent life of conventional fungicide coatings. Breeder-treated seed volumes in Southern Europe are shifting toward biological priming agents as chemical options narrow.
Retail chain consolidation is compressing grower procurement autonomy. Supermarket groups in Germany and France are mandating variety approval lists that exclude non-contracted genetics. This behavior concentrates seed purchasing power with designated supply cooperatives in the Netherlands and Spain, marginalizing independent variety selection by individual farm managers.
Europe Vegetable Seed Market Segmentation
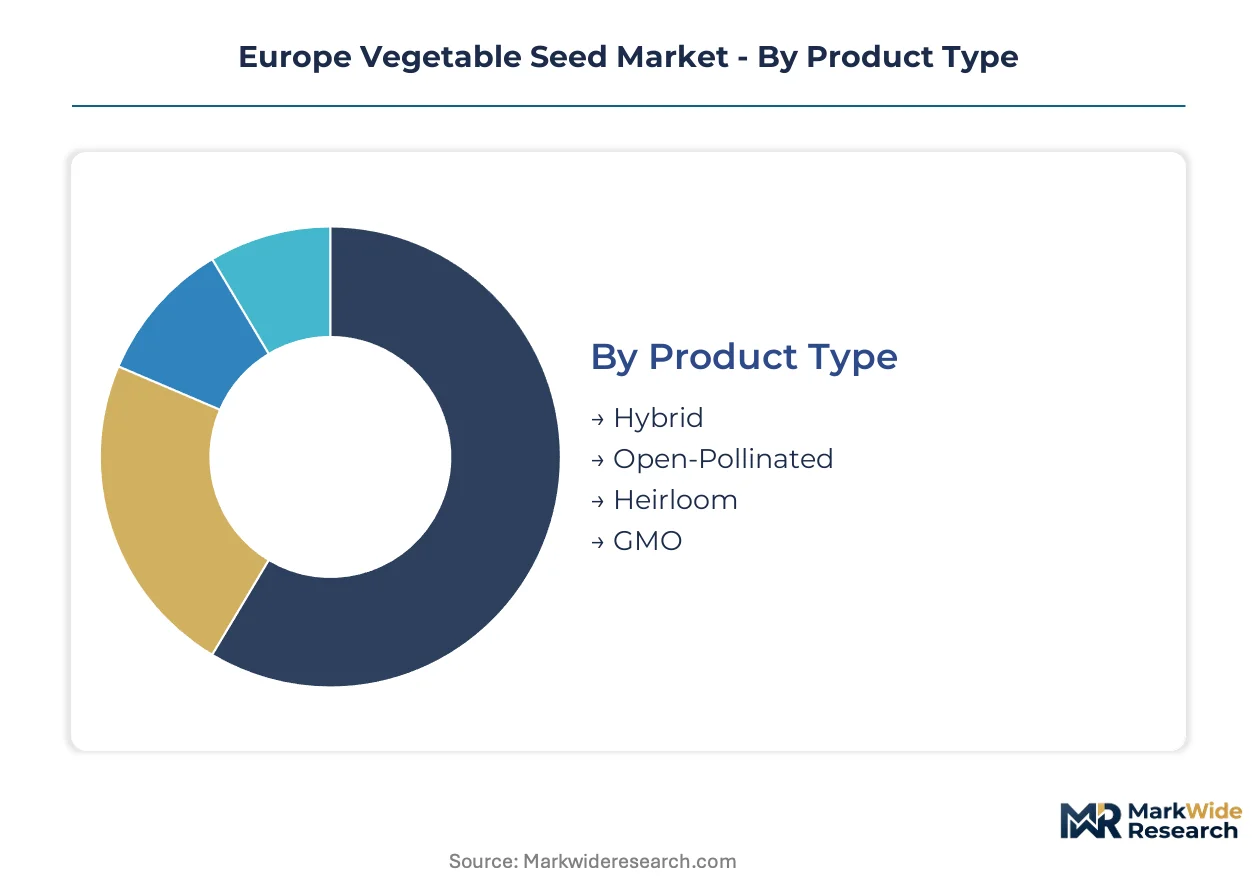
Vegetable seed segmentation in Europe reflects divergent grower economics across protected cultivation, open-field commodity production, and organic compliance regimes. Breeders configure product portfolios around pollination biology, input intensity, and downstream channel certification requirements.
Product Type:
Genetic stabilization methodology determines performance reliability, input dependency, and regulatory classification across European cultivation systems.
- Hybrid:Controlled cross-pollination between distinct inbred parent lines exploits heterosis for yield uniformity, disease resistance, and post-harvest shelf stability. Dutch greenhouse operators and Spanish protected agriculture specialists anchor demand for tomato, pepper, and cucumber F1 hybrids optimized for high-wire cultivation. EU Green Deal pesticide reduction mandates accelerate breeder investment in stacked resistance traits.
- Open-Pollinated:Naturally fertilized varieties maintain genetic diversity across generations, enabling on-farm seed saving and lower per-unit input costs. Polish and Romanian open-field vegetable growers favor these lines for brassica and root crops where mechanization tolerates phenotypic variation. Organic certification compliance drives residual demand.
- Heirloom:Landrace varieties preserved through generational cultivation carry distinct regional provenance and flavor profiles. Italian and French direct-to-consumer channels command niche premiums for heritage tomato and bean genetics.
- GMO:Transgenic events incorporating exogenous resistance traits face EFSA novel food assessment and national cultivation bans in multiple member states. Stacked event approvals absorb extended regulatory timelines despite CRISPR exclusion from GMO frameworks.
Mature deployment sits with Hybrid. Newer deployment is concentrated in Heirloom.
End Use Industry:
Cultivation system architecture dictates seed specification, volume scale, and procurement channel structure across European production geographies.
- Agriculture:Large-scale open-field operations supply commodity vegetables to processing contracts and wholesale markets. Mechanized harvesting requirements prioritize uniformity traits and synchronized maturity windows.
- Horticulture:Specialized fresh-market production emphasizes visual quality grades and flavor differentiation for retail chain specifications. Breeder variety approval lists increasingly constrain independent farm manager selection.
- Greenhouse:High-tech glass and polytunnel systems in the Netherlands, Spain, and Belgium pull demand for rootstock-grafted solanaceous and cucurbit varieties. Energy input volatility destabilizes grower willingness to pay premium seed prices.
- Organic Farming:EU Farm to Fork targets for organic farmland expansion create regulatory tailwind for open-pollinated and hybrid organic-compliant variety development. Seed health certification complexity fragments cross-border supply.
Volume concentration sits with Agriculture. Margin expansion is concentrated in Greenhouse.
Packaging Type:
Unit configuration aligns with grower scale, treatment requirements, and inventory management protocols across distribution tiers.
- Bulk:Untreated or film-coated seed delivered in industrial quantities serves large-scale greenhouse operators and agricultural cooperatives with on-site treatment capacity. REACH sunset schedules for approved active ingredients compress effective patent life of conventional fungicide coatings.
- Retail Packs:Consumer-facing units target home gardeners and smallholder segments through garden center and supermarket channels. Unit economics constrain trait sophistication relative to professional-grade genetics.
- Seed Bags:Intermediate-scale packaging accommodates independent commercial growers with moderate acreage and seasonal procurement patterns.
- Sachets:Precision-portioned units enable treated seed distribution with embedded biological priming agents replacing restricted chemistries.
Procurement scale sits with Bulk. Channel diversification is concentrated in Sachets.
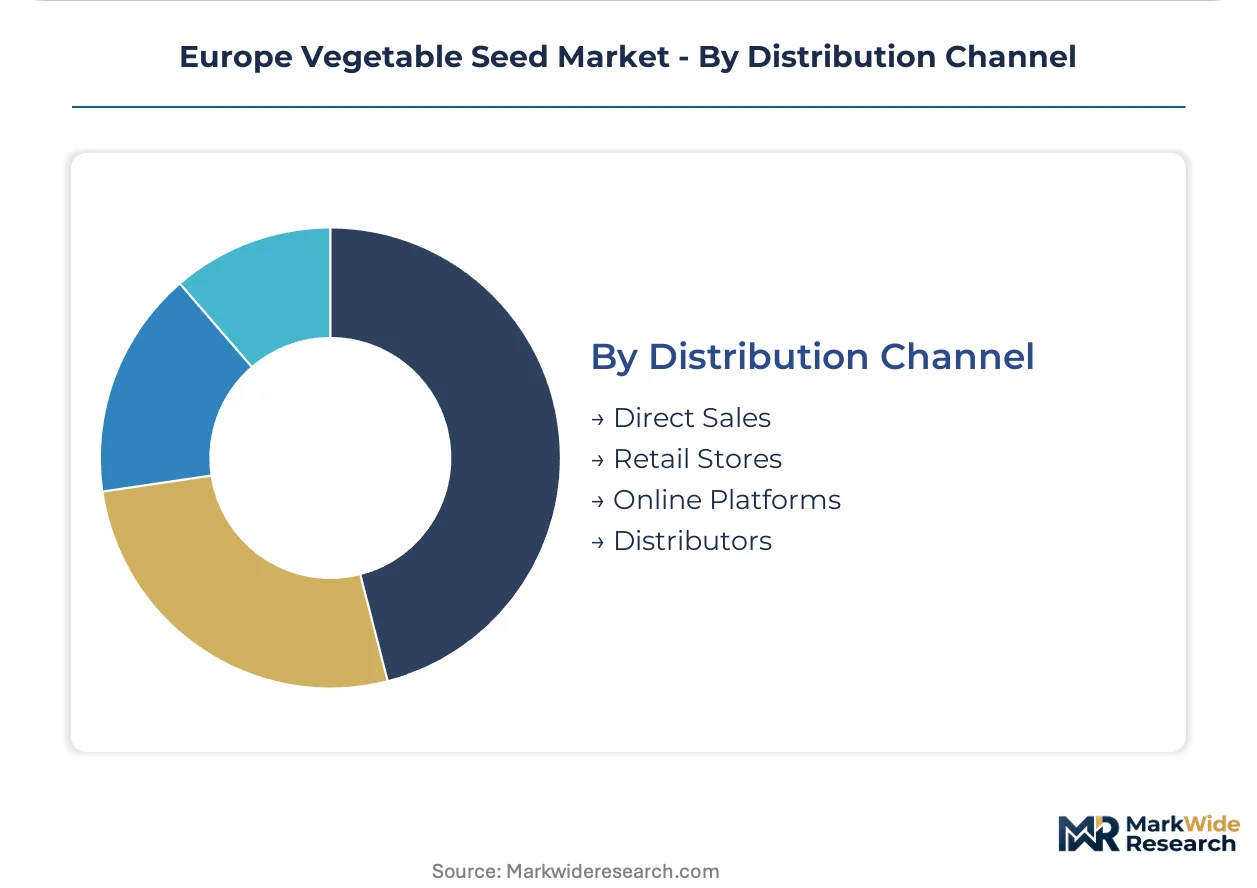
Distribution Channel:
Channel structure reflects consolidation dynamics in European retail and the geographic clustering of breeding expertise.
- Direct Sales:Breeder-to-grower relationships dominate Dutch greenhouse clusters and Spanish Almería protected agriculture zones. Retail chain consolidation concentrates purchasing power with designated supply cooperatives.
- Retail Stores:Garden center and agricultural supply depots serve hobbyist and small commercial segments with limited technical support.
- Online Platforms:Digital procurement channels expand reach for specialty and organic-compliant varieties outside breeder direct territories.
- Distributors:Regional wholesalers bridge breeding clusters in the Netherlands to peripheral European markets including Poland and the Baltic states.
Relationship density sits with Direct Sales. Geographic extension is concentrated in Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wageningen University's research corridor functions as Europe's de facto seed innovation special economic zone, concentrating breeding infrastructure and attracting cross-border R&D investment through Dutch tax incentives for agricultural technology development.
Netherlands
Dutch greenhouse operators command premium hybrid tomato and pepper acreage under high-tech glass, driving demand for rootstock-grafted varieties. EU Green Deal pesticide reduction mandates accelerate breeder investment in stacked disease-resistance traits. Wageningen-area clusters supply genetics across continental Europe through direct breeder-to-grower relationships.
Spain
Almería's protected agriculture zone anchors Mediterranean demand for high-wire cucumber and sweet pepper genetics adapted to continental climate stress. EFSA novel food assessments create regulatory friction for CRISPR-edited variety commercialization despite exclusion from GMO frameworks. Spanish supply cooperatives concentrate seed purchasing power under retail chain consolidation pressure.
Germany
German supermarket groups mandate variety approval lists that exclude non-contracted genetics, compressing grower procurement autonomy. REACH chemical governance through ECHA accelerates breeder investment in low-input trait stacks. Bavarian and Lower Saxony greenhouse operations pull Dutch genetics for regional fresh-market supply.
Poland
Underpenetrated high-wire cucumber and sweet pepper segments in Polish commercial greenhouses offer expansion terrain for Dutch breeding programs. Open-field brassica and root crop growers favor open-pollinated lines where mechanization tolerates phenotypic variation. National phytosanitary requirements diverging from EPPO standards fragment cross-border seed movement compliance.
France
Direct-to-consumer channels in Provence and Île-de-France command niche premiums for heritage tomato and bean genetics. ANSM and national variety registration through CPVO gate market access for new cultivars. Farm to Fork organic farmland targets create regulatory tailwind for open-pollinated and hybrid organic-compliant variety development.
Europe Vegetable Seed Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Europe's vegetable seed landscape. Bayer AG and BASF SE anchor the diversified tier through agrochemical-seed convergence, while Dutch family-owned breeders concentrate proprietary germplasm expertise. Three strategic archetypes dominate: integrated life-science conglomerates, specialized vegetable breeding houses, and regional cooperatives with captive distribution. Competitive moves center on genomic selection capability building and exclusive variety approval relationships with retail chain procurement consortia.
Among Dutch pure-play specialists, Rijk Zwaan Zaadteelt en Zaadhandel B.V., Enza Zaden BV, and Bejo Zaden BV exemplify the focused breeding house archetype, occupying positions sustained through multi-generational germplasm development and greenhouse-cluster proximity. Syngenta Group and Bayer AG represent the integrated life-science model, leveraging broader agricultural input portfolios to anchor grower relationships across multiple crop categories.
| Leading Market Players |
|---|
| Rijk Zwaan Zaadteelt en Zaadhandel B.V. |
| Enza Zaden BV |
| Syngenta Group |
| Nunhems BV |
| Bejo Zaden BV |
| Groupe Limagrain Holding S.A. |
| BASF SE |
| Axia Vegetable Seeds |
| Bayer AG |
| Others |
Supply & Pricing Matrix
Family-owned Dutch breeding houses anchor supply concentration around Wageningen-area clusters, translating multi-generational germplasm control into pricing discipline that resists commoditization despite retail chain procurement consolidation.
Pricing Analysis
Margin tightening in F1 hybrid tiers reflects energy input volatility destabilizing greenhouse operator willingness to pay premium genetics prices. Three-tier pricing structure across performance-validated, standard-certified, and economy bulk tiers separates breeders with CPVO-registered DUS testing from uncertified competitors. Cost-down pressure on open-pollinated lines accelerates as Polish and Romanian open-field growers prioritize per-unit input savings over trait sophistication. Price differentiation hinges on stacked disease-resistance bundles versus standalone variety claims, with Dutch greenhouse operators least sensitive and Eastern European commodity brassica growers most responsive to unit cost.
Supply Chain Analysis
Seed health certification divergence from EPPO standards fragments cross-border movement compliance for multi-national distribution. Parent line germplasm concentrates in the Netherlands, Spain, and Belgium, with inbred development anchored in Wageningen-area R&D corridors. Raw material dependencies span controlled-pollination infrastructure, biological priming agents replacing REACH-restricted chemistries, and high-throughput phenotyping platforms. Single-source vulnerability sits with three Dutch breeding clusters supplying rootstock genetics across European protected cultivation. Distribution runs through direct breeder-to-grower relationships in Dutch greenhouse zones, regional wholesalers extending to Poland and Baltic markets, and supply cooperatives consolidating under German and French retail chain mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration races are reshaping competitive positioning as breeders pursue captive control over genomic selection pipelines and high-throughput phenotyping infrastructure to compress breeding cycles ahead of EU Green Deal compliance deadlines.
For Market Incumbents: To counter genetic bottleneck risk from parent line concentration, acquire or exclusive-license CRISPR-editing platforms from specialized service providers and deepen backward integration into high-throughput phenotyping infrastructure to reduce reliance on external bioinformatics talent pools. For New Entrants and Emerging Players: Begin with underpenetrated Polish high-wire cucumber and sweet pepper greenhouse segments where Dutch genetics face continental climate adaptation gaps, leveraging CPVO fast-track registration protocols and biological priming agent formulations as differentiated go-to-market positioning against established chemical treatment portfolios. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Dutch breeders with proprietary rootstock programs and existing CPVO variety registrations, positioned for consolidation into integrated life-science conglomerates seeking greenhouse-cluster proximity; watch EFSA novel trait assessment timeline compression as inflection signal for gene-edited variety commercialization acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Genomic Selection Pipeline Buildout | Machine learning algorithms trained on multi-environment trial data compress breeding cycles for EU Green Deal compliance. |
| CRISPR Trait Licensing Agreement | Site-directed nuclease partnerships accelerate powdery mildew resistance development despite EFSA regulatory uncertainty. |
| Biological Priming Agent Scale-Up | REACH sunset schedules for approved chemistries force reformulation of seed treatment portfolios toward ECHA-compliant alternatives. |
| CPVO Fast-Track Registration Investment | Streamlined DUS examination protocols cut time-to-market for hybrid cultivars entering EU seed catalogs. |
| Polish Greenhouse Cluster Partnership | Continental climate stress adaptation creates first-mover terrain for high-wire cucumber and sweet pepper genetics expansion. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across breeding program directors, greenhouse operation managers, CPVO examination officers, retail chain procurement leads, and biological input formulators. Secondary validation drew from EU Green Deal implementation reports, ECHA candidate substance restriction schedules, EFSA novel food assessment disclosures, and national variety registration databases. Bottom-up acreage and volume estimates triangulated against top-down breeder revenue allocations across hybrid, open-pollinated, and heirloom categories.
Segment-level granularity modeled pollination biology, cultivation system architecture, packaging configuration, and distribution channel structure across the projection horizon. CAGRs derived from breeder investment trajectories in stacked trait development, protected cultivation expansion rates, and organic farmland compliance targets. Industry-specific forecast inputs incorporated energy price volatility effects on greenhouse economics and REACH authorization timelines compressing chemical seed treatment patent life.
EFSA regulatory stance evolution, energy input price volatility, and CRISPR commercialization pathway clarity are the dominant revision risks warranting forecast reassessment. A model refresh is warranted upon material change in EU AI Act implementation affecting genomic selection algorithm deployment permissions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Fruit Tomatoes Seed Market
Seeds
Southeast Asia Vegetable Seed Market
Seeds
China Rice Seed Market
Seeds
Global Fruit and Vegetable Seeds Market
Seeds
Global Oilseed Market
Seeds
Global Seed Market
Seeds
North America Forage Seed Market
Seeds
Canary Seeds Market
Seeds
Celery Seed Oil Market
Seeds
Grass Seed Market
Seeds
Myanmar Rice Seed Market
Seeds
Global Forage Sorghum Seed Market
Seeds
Southeast Asia Seed Market
Seeds
Buckwheat Seed Market
Seeds
Guar Market
Seeds
North America Tomato Seed Market