
 Punnet Market | 2026-2036
Punnet Market Size, Share, and Industry Trends Forecast 2026-2036
Punnet Market Analytics
Modular multi-count punnets is expanding as the dominant configuration pattern across European berry and cherry tomato supply chains. Smurfit Kappa Group Plc leverages its molded fiber expertise to capture shelf-ready formats for Tesco and Carrefour private-label programs. Groupe Guillin SA anchors its position through deep specialization in thermoformed rPET punnets for soft-fruit exporters in Southern France and Morocco. Berry Global, Inc. competes on high-speed forming lines that cut unit costs for mass-market strawberry volumes in North American retail.
A punnet denotes a small, open-top container engineered with integral ventilation apertures and stacking lugs, typically formed from thermoformed PET, molded pulp, or corrugated cardboard, designed to protect, display, and ventilate soft fruits during post-harvest handling and retail presentation. Cardboard punnets lead value contribution in premium organic segments where retailers ban plastic, while compostable punnets represent the fastest-growing product type as PLA and bagasse formulations achieve commercial scale at competitive unit economics. Small and medium sizes dominate volume for berry and grape packaging, though extra-large formats gain traction in club-store and wholesale channels for bulk tomato and stone-fruit distribution.
EFSA migration limits and the EU Single-Use Plastics Directive reshape material selection across European punnet supply chains, forcing converters to certify fiber alternatives for food-contact compliance. REACH substance restrictions on certain plasticizers and the EU Packaging and Packaging Waste Regulation mandate minimum recycled content thresholds that elevate rPET and mechanically recycled pulp demand. Stakeholders must monitor emerging national extended-producer-responsibility fee structures and substrate-specific labeling requirements that will determine cost-competitive positioning between plastic, fiber, and next-generation compostable formats.
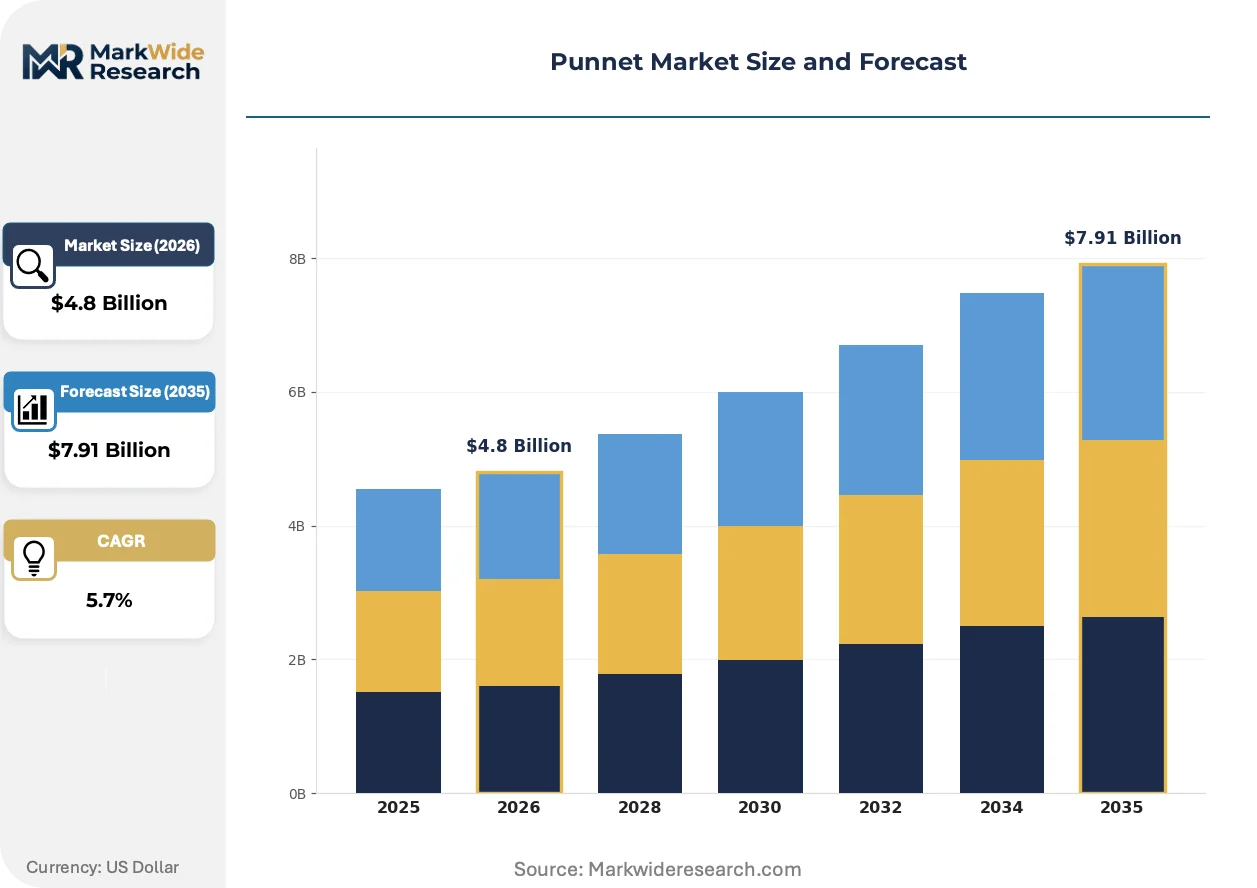
Market Dynamics
The EU Single-Use Plastics Directive is forcing converters across Spain, France, and the Netherlands to certify fiber alternatives for food-contact compliance, reshaping material selection and supplier qualification timelines.
Growth Catalysts
- REACH substance restrictions:Limits on certain plasticizers accelerate demand for mechanically recycled pulp and rPET formulations in German and Italian retail channels.
- Almería greenhouse cluster:Spain's concentrated soft-fruit export base requires ventilated, stackable punnet formats for berry and tomato shipments to Northern European supermarkets.
- Compostable PLA formulations:Commercial-scale bagasse and polylactic acid blends achieve unit economics competitive with conventional thermoformed PET in premium organic segments.
Market Restraints
- Pulp fiber input volatility:Recycled paperboard and bagasse pricing fluctuates with agricultural residue harvest cycles and energy-intensive drying costs.
- Thermoforming equipment concentration:High-speed forming line suppliers cluster in Germany and Northern Italy, creating lead-time bottlenecks for Southern European converters.
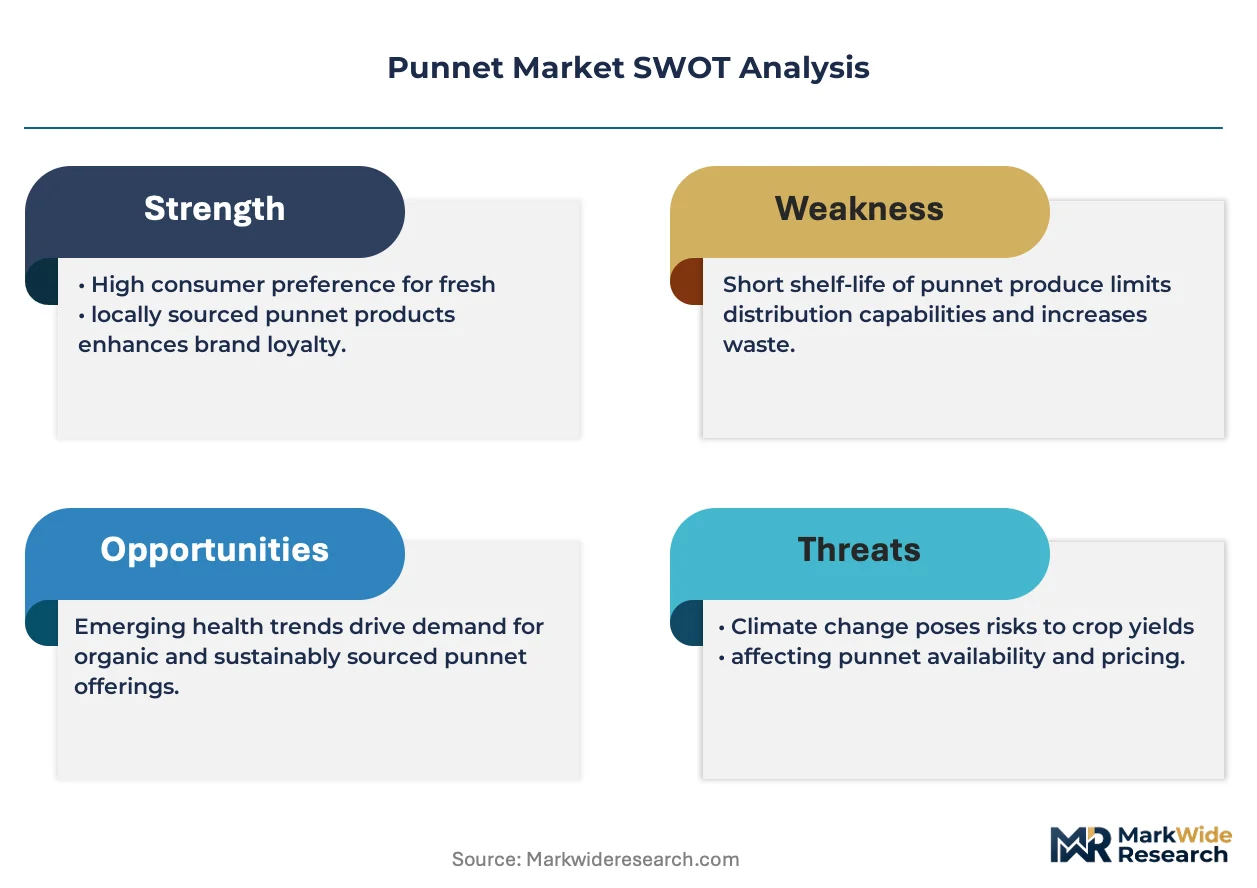
- EFSA migration testing timelines:Fiber-based alternatives require 12-18 month certification cycles that delay private-label program launches.
Strategic Opportunities
- Club-store bulk formats:Extra-large punnets for wholesale tomato and stone-fruit distribution remain underdeveloped relative to standard retail sizes.
- Extended producer responsibility schemes:France's Citeo fee structures and upcoming Dutch packaging taxes favor compostable substrates with lower eco-modulation rates.
- Smart ventilation apertures:Laser-perforation and micro-flute technologies converge to extend shelf life for premium berry exports.
Industry Challenges
- Molded fiber tooling capex:Wet-press fiber punnet production requires press investments that strain mid-cap converter balance sheets.
- Multi-substrate compliance:Operators must maintain parallel HACCP, BRC, and FSSC 22000 certifications for plastic, fiber, and hybrid product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Punnet Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Punnets, Cardboard Punnets, Compostable Punnets, Glass Punnets Size: Small, Medium, Large, Extra Large End User: Retailers, Farmers, Wholesalers, Exporters Distribution Channel: Online, Supermarkets, Local Markets, Direct Sales |
| Companies Covered | Smurfit Kappa Group Plc, Coveris Holdings SA, LC Packaging International BV, Groupe Guillin SA, Berry Global, Inc., Paccor Netherlands BV, Leeways Packaging Services Ltd., INFIA S.r.l., Amcor Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Punnet Market Evolving Landscape
Material science advances and retail sustainability mandates are compressing development cycles for next-generation punnet formats across European supply chains.
Dry-molded fiber technology is decentralizing punnet production geography by eliminating wet-press water treatment infrastructure. Smaller converters in Portugal and Greece are adopting portable fiber presses that slash entry capital requirements. This capability diffusion is compressing lead times for regional berry exporters who previously relied on centralized Northern European suppliers.
EFSA's updated guidance on food-contact recycled plastics tightens contamination thresholds for rPET punnets. French and Spanish thermoformers must upgrade extrusion and sorting equipment to meet detectable substance limits. Soft-fruit exporters in Morocco and Southern France face extended recertification timelines that favor early-mover converters with validated decontamination systems.
Supermarket private-label directors now mandate shelf-ready packaging that eliminates secondary outer cases. Tesco and Carrefour buyers specify printed, handled punnets that flow directly from distribution center to produce display. This specification compression is most visible in UK and French berry categories where labor cost reduction outweighs per-unit packaging premiums.
Punnet Market Segmentation
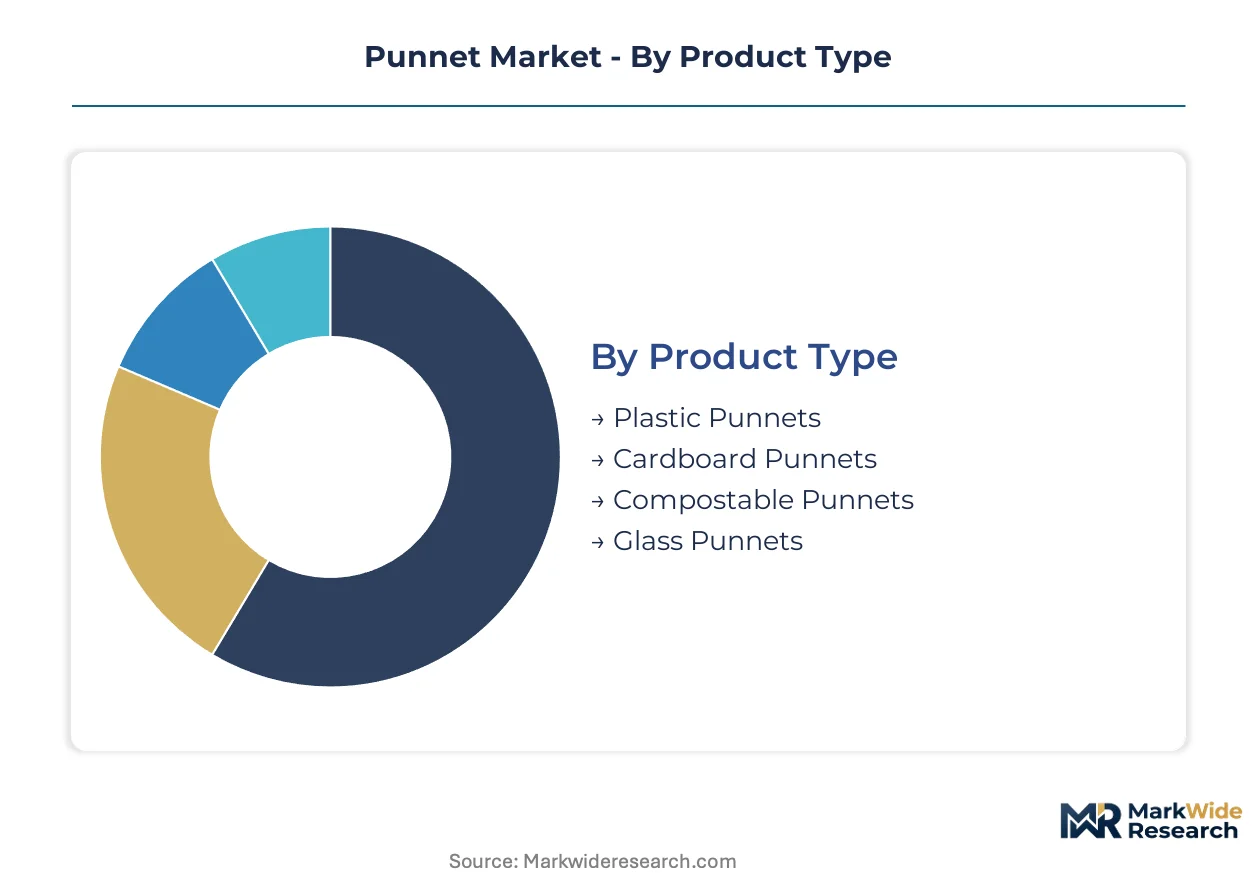
Punnet selection hinges on material compliance, shelf-life requirements, and retail format specifications. Each segmentation dimension reveals distinct procurement patterns across European soft-fruit supply chains.
Product Type:
Volume applications favor cost-optimized substrates, while premium positioning drives adoption of certified sustainable alternatives.
- Plastic Punnets:Thermoformed PET and rPET formats dominate high-throughput berry packing operations with proven moisture resistance and optical clarity. German and Italian retail channels concentrate demand where REACH substance restrictions on plasticizers elevate mechanically recycled formulations.
- Compostable Punnets:PLA and bagasse blends achieve commercial scale at unit economics competitive with conventional plastics in organic segments. France's Citeo extended-producer-responsibility fee structures and Dutch packaging taxes favor these substrates with lower eco-modulation rates.
- Cardboard Punnets:Molded fiber and corrugated formats lead premium organic segments where retailers enforce plastic bans.
- Glass Punnets:Specialty preserves and high-value confectionery applications in boutique retail channels.
Today's leader: Plastic Punnets. Tomorrow's challenger: Compostable Punnets.
Size:
Standard retail portions anchor volume, though format diversification accelerates across emerging distribution channels.
- Small:Single-serve berry and grape portions for convenience retail and foodservice grab-and-go formats. Spain's Almería greenhouse cluster ships these configurations to Northern European supermarket chains requiring strict portion control.
- Medium:Family-size strawberry and cherry tomato packs constitute the workhorse specification for Tesco and Carrefour private-label programs.
- Large:Club-store and wholesale formats for bulk tomato distribution.
- Extra Large:Stone-fruit and wholesale tomato channels remain underdeveloped relative to standard retail sizes.
Medium formats command current volume leadership. Extra Large configurations present the steepest expansion trajectory as club-store penetration deepens.
End User:
Procurement sophistication varies sharply across the value chain, from compliance-driven exporter specifications to price-sensitive farm-gate purchasing.
- Retailers:Supermarket private-label directors mandate shelf-ready printed and handled punnets that eliminate secondary outer cases. UK and French berry categories concentrate this demand where labor cost reduction outweighs per-unit packaging premiums.
- Exporters:Moroccan and Southern French soft-fruit shippers require ventilated, stackable formats with EFSA food-contact certification for Northern European destination markets.
- Farmers:Direct-produce-market and local supply chain participants prioritize lowest unit cost over format standardization.
- Wholesalers:Volume-focused intermediaries with limited specification control.
Retailers set the specification agenda today. Exporters are gaining procurement sophistication fastest.
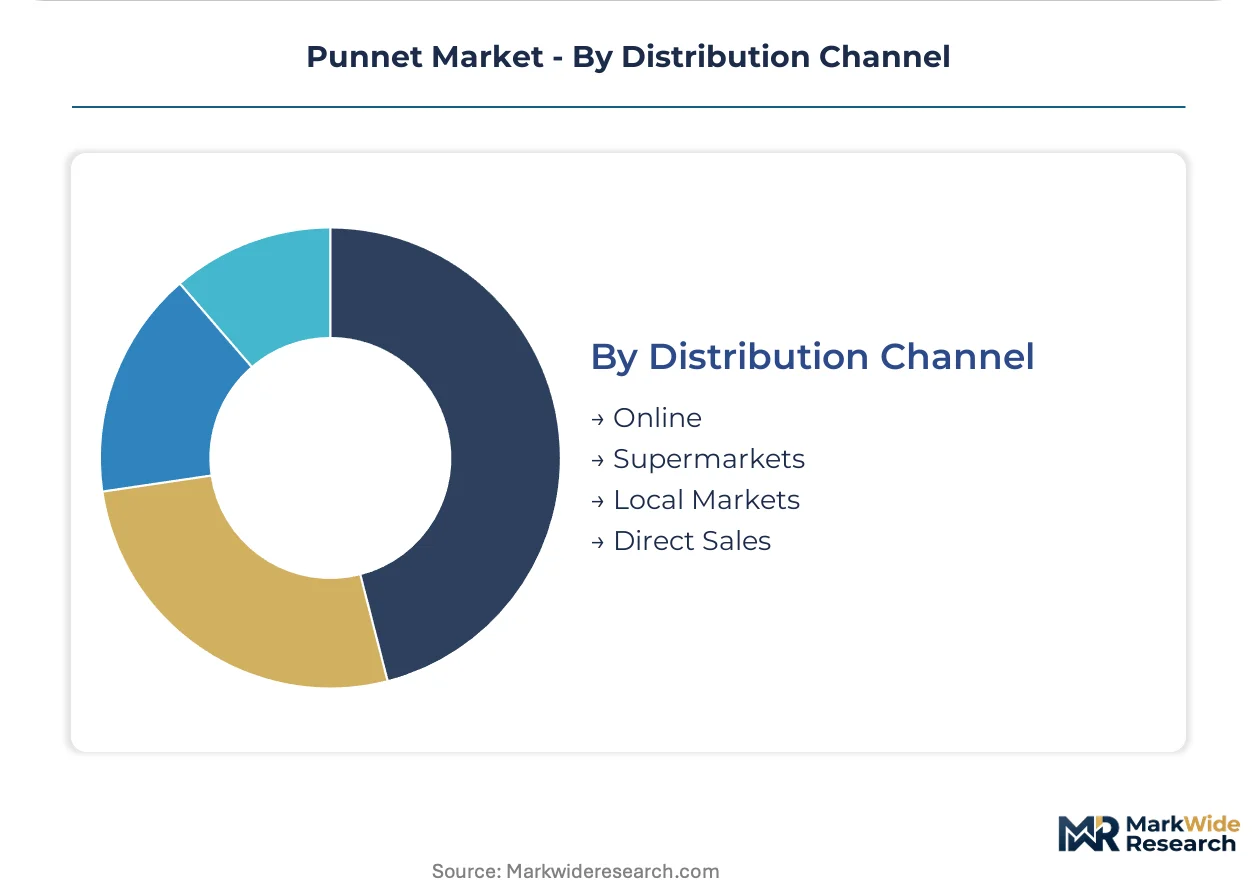
Distribution Channel:
Channel-specific handling requirements and display economics reshape punnet format selection.
- Supermarkets:Shelf-ready packaging with integral handles and printed branding flows direct from distribution center to produce display. This specification compression dominates UK and French berry procurement.
- Online:Home-delivery grocery platforms demand enhanced structural integrity and modified atmosphere compatibility for last-mile handling.
- Direct Sales:Farm-shop and pick-your-own operations favor lowest-cost unprinted formats.
- Local Markets:Traditional wholesale and street-market channels with minimal standardization.
Supermarkets anchor format standardization. Online channels are forcing the fastest packaging innovation cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The punnet packaging industry traces its modern commercial roots to post-war European fresh produce retailing, where standardized ventilated containers first enabled long-distance soft-fruit distribution from Mediterranean growing regions to Northern European supermarkets.
Spain
Almería's greenhouse cluster generates concentrated demand for ventilated, stackable punnet formats tailored to berry and tomato exports bound for German and British retail chains. The country's national food safety authority enforces EFSA-aligned migration limits that accelerate fiber-based packaging adoption among Southern Spanish converters. Valencia's packaging belt hosts specialized thermoformers supplying Moroccan soft-fruit exporters with certified rPET formats.
Germany
REACH substance restrictions on specific plasticizers elevate mechanically recycled pulp and rPET formulations across discount and premium retail channels alike. The Federal Institute for Risk Assessment maintains stringent food-contact certification timelines that favor early-mover converters with validated decontamination infrastructure. Bavaria's machinery corridor supplies high-speed thermoforming equipment to Southern European converters facing capacity expansion bottlenecks.
France
Citeo's extended-producer-responsibility fee structures favor compostable substrates with lower eco-modulation rates, reshaping procurement patterns for Carrefour and Intermarché private-label programs. The national food safety agency enforces EFSA migration testing protocols that delay fiber-based alternative launches by 12-18 months. Provence-Alpes-Côte d'Azur hosts specialized thermoformers serving Moroccan berry exporters with shelf-ready printed formats.
Netherlands
Upcoming national packaging taxes accelerate demand for compostable PLA and bagasse formulations among Dutch supermarket chains and their cross-border suppliers. The Food and Consumer Product Safety Authority mandates parallel HACCP and BRC certifications for multi-substrate operators. Rotterdam's logistics hub concentrates distribution infrastructure for Iberian and North African soft-fruit imports requiring compliant secondary packaging.
United Kingdom
Tesco and Sainsbury's private-label directors mandate shelf-ready handled punnets that eliminate secondary outer cases, compressing supplier qualification timelines. The Food Standards Agency maintains post-Brexit alignment with EFSA food-contact standards while streamlining fiber-alternative approval pathways. Kent's produce distribution corridor anchors demand for medium-format berry punnets serving London and Southeast retail concentration.
Punnet Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material certification and shelf-ready format capabilities, creating a tiered structure where EFSA-validated fiber alternatives command pricing power over conventional thermoformed PET. The vendor base distributes across integrated packaging conglomerates, regional thermoforming specialists, and emerging fiber-technology entrants. Three archetypes dominate: pulp-fiber specialists with wet-press expertise, rPET thermoformers with validated decontamination systems, and diversified converters with multi-substrate compliance infrastructure. Capacity expansion and strategic partnerships represent the dominant competitive moves, as converters secure raw material supply agreements and shared tooling investments to defray molded fiber press capital requirements.
Among Irish and French packaging conglomerates, Smurfit Kappa Group Plc and Groupe Guillin SA exemplify divergent archetype positioning—one anchored in molded fiber shelf-ready formats, the other in thermoformed rPET specialization for soft-fruit export corridors. Berry Global, Inc. occupies a position within the scale-driven, multi-substrate tier, representing North American capacity deployment into European berry supply chains. These three entities illustrate how geographic origin and corporate structure correlate with strategic emphasis on fiber versus plastic substrate portfolios.
| Leading Market Players |
|---|
| Smurfit Kappa Group Plc |
| Coveris Holdings SA |
| LC Packaging International BV |
| Groupe Guillin SA |
| Berry Global, Inc. |
| Paccor Netherlands BV |
| Leeways Packaging Services Ltd. |
| INFIA S.r.l. |
| Amcor Plc |
| Others |
Value Network & Pricing Analysis
Recycled paperboard and bagasse fiber costs cascade through three distinct pricing tiers, with agricultural residue harvest cycles and energy-intensive drying expenses compressing margins at the converter level before reaching retailer procurement desks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EFSA-validated molded fiber formats from conventional thermoformed rPET and unprinted commodity punnets. Certification grade and volume scale drive price differentiation, with shelf-ready printed formats commanding premiums over plain configurations. Pricing pressure stems from pulp fiber input volatility that strains mid-cap converter balance sheets. Farmers and direct-produce-market participants exhibit highest price sensitivity, while Tesco and Carrefour private-label directors prioritize labor cost reduction over per-unit packaging premiums.
Supply Chain Analysis
EFSA migration testing and BRC certification requirements gate supplier qualification timelines, creating 12-18 month entry barriers that protect incumbent positions. Supply concentrates in Germany, Spain, and France, with Bavaria's machinery corridor feeding high-speed thermoforming equipment to Southern European converters. Raw material dependencies center on recycled PET flake, bagasse agricultural residue, and food-grade pulp fibers. Single-source vulnerability runs through thermoforming equipment suppliers clustered in Northern Italy. Distribution runs through Rotterdam's logistics hub for Iberian and North African soft-fruit imports requiring compliant secondary packaging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The punnet market compounds steadily as fresh produce retailing mandates shelf-ready formats that eliminate secondary handling labor across European supermarket chains.
For Market Incumbents: Extend fiber-alternative certification portfolios to capture Citeo eco-modulation advantages before Dutch packaging taxes activate. Smurfit Kappa and Groupe Guillin should deepen wet-press fiber press deployments in Portugal and Greece to preempt portable dry-molded fiber technology diffusion. Vertical integration into bagasse supply agreements insulates against agricultural residue harvest volatility. For New Entrants and Emerging Players: Supermarket private-label directors represent the most penetrable channel partner type for shelf-ready handled formats that bypass secondary outer cases. Target club-store extra-large configurations for bulk tomato and stone-fruit distribution, a whitespace segment underdeveloped relative to standard retail sizes. Pursue co-development partnerships with Almería greenhouse exporters seeking ventilated, stackable formats for Northern European destination markets. For Investors and Strategic Acquirers: Roll-up economics work for regional thermoforming specialists with validated EFSA decontamination systems because certification infrastructure creates acquirer leverage over uncertified competitors. Focus on mid-cap converters with multi-substrate HACCP and BRC compliance infrastructure. Watch for inflection when France and Netherlands extend producer responsibility fee structures favoring compostable substrates.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Fiber Certification Investment | 12-18 month validation cycles lock out competitors from Carrefour and Tesco programs. |
| Dry-Molded Fiber Technology Deployment | Portable presses in Portugal and Greece compress lead times for regional berry exporters. |
| Bagasse Supply Agreement | Agricultural residue offtake contracts stabilize input costs against harvest cycle volatility. |
| Shelf-Ready Format Development | Printed handled punnets eliminate secondary outer cases for UK and French supermarket chains. |
| Extended Producer Responsibility Positioning | Citeo eco-modulation rates favor compostable substrates in French private-label procurement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with packaging converters, supermarket category buyers, and soft-fruit export logistics managers with secondary validation from EFSA guidance documents, EU Packaging and Packaging Waste Regulation filings, and customs trade data. Bottom-up capacity assessments at thermoforming and fiber press facilities triangulated against top-down retail procurement surveys.
Comparable historical periods anchored volume and value projections across the analysis window, with segmentation modeling across material substrate, format size, end-user archetype, and distribution channel. CAGRs derived from fitted growth curves incorporating EFSA regulatory phase-in schedules and supermarket sustainability mandate adoption curves. Forecast inputs included Almería greenhouse export volumes and Citeo fee structure implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA migration limit revisions and national extended producer responsibility rollouts. Model assumptions reflect REACH substance restriction enforcement intensity and pulp fiber energy cost trajectories. A model refresh is warranted upon material change in EU Single-Use Plastics Directive implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Commercial Seed Market
Seeds
Asia-Pacific Vegetable Seed Market
Seeds
Perilla Seed Oil Market
Seeds
Global Soybean Seed Market
Seeds
South America Quinoa Seeds Market
Seeds
E. Angustifolium Market
Seeds
Cucumber Seeds Market
Seeds
India Maize Seed Market
Seeds
Hemp Seed Oil Market
Seeds
Agricultural Seeder Market
Seeds
Middle East and Africa Cannabis Seeds Market
Seeds
Tallow Tree Seed Market
Seeds
North America Quinoa Seeds Market
Seeds
Asia-Pacific Quinoa Seeds Market
Seeds
Global Fruit and Vegetable Seeds Market
Seeds
Global Maize Seed Market