
 Polybutylene Succinate (PBS) Market | 2026-2036
Polybutylene Succinate (PBS) Market Size, Share, and Industry Trends Forecast 2026-2036
Polybutylene Succinate (PBS) Market Analytics
Specialized polymer engineering talent is reorganizing competitive dynamics as biopolymer process optimization outpaces conventional plastics training pipelines. BASF SE leverages its Ludwigshafen research complex to sustain catalyst innovation for direct esterification routes. Showa Denko K.K. anchors Japanese domestic supply through integrated succinic acid fermentation assets. Mitsubishi Chemical Corporation competes via controlled ring-opening polymerization expertise that differentiates molecular weight distribution.
Polybutylene succinate is an aliphatic polyester synthesized from 1,4-butanediol and succinic acid through polycondensation or ring-opening polymerization, exhibiting melting points near 114°C and biodegradability in soil, freshwater, and marine environments. The material serves primarily as a drop-in replacement for polypropylene and polyethylene in applications requiring compostable performance. Copolymer grades command premium positioning as adipic acid or lactic acid incorporation broadens thermal and mechanical property windows for food-contact flexible packaging. Blends represent the fastest-expanding product category as compounders optimize cost-performance ratios by mixing PBS with polylactic acid or starch derivatives. Packaging applications dominate volume offtake, though automotive interior trim segments are gaining traction as OEMs pursue cabin air quality certifications and landfill diversion targets.
China's SAMR enforces GB standards for biodegradable plastics labeling and composting facility acceptance criteria, while the EU REACH framework and F-Gas Regulation indirectly channel investment toward bio-based polyester alternatives. Japan's METI bioplastics roadmap and container recycling laws create procurement mandates that institutionalize PBS demand across convenience retail supply chains. Stakeholders must monitor fermentation feedstock cost volatility and regional composting infrastructure buildout rates to calibrate capacity commitments against actual end-of-life pathway availability.
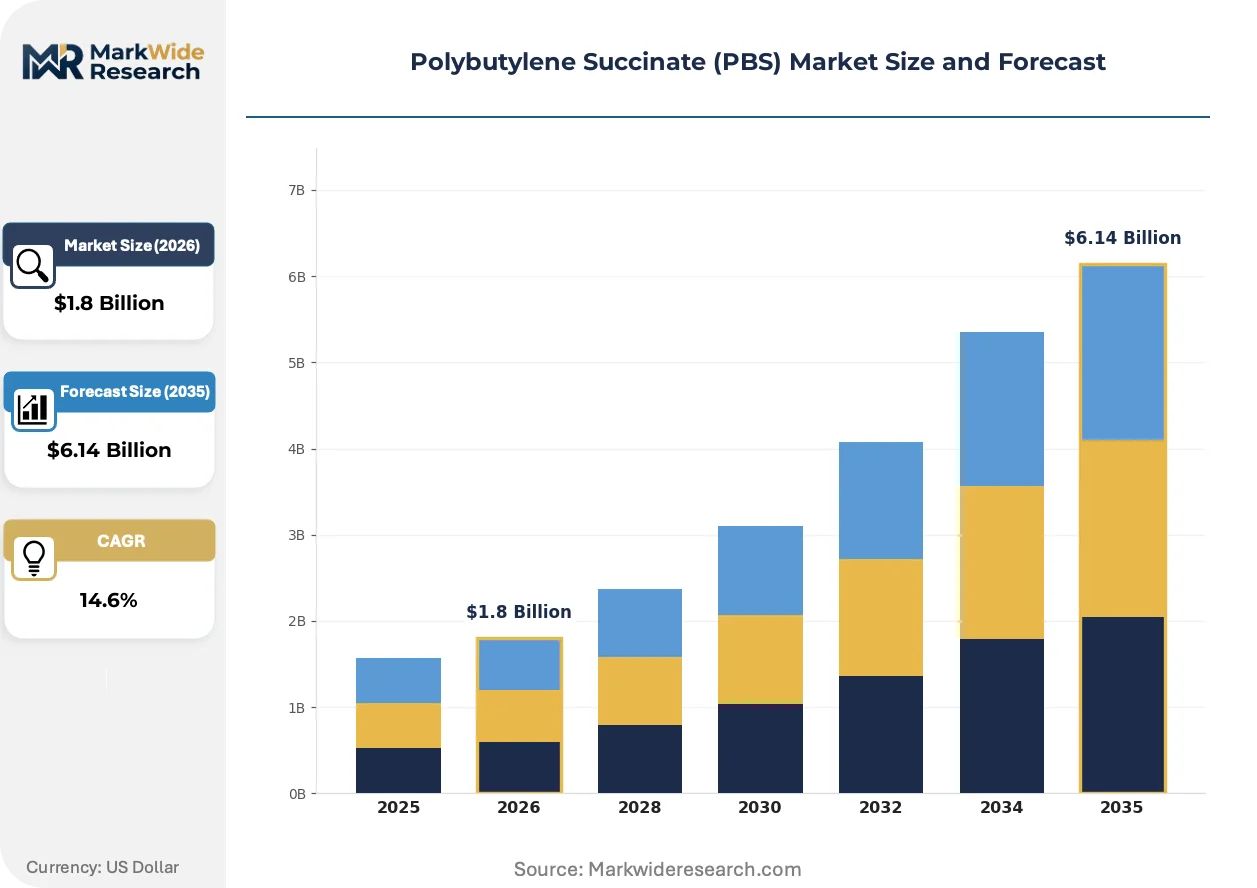
Market Dynamics
Fermentation-based succinic acid substitution for petrochemical feedstocks is compressing cost structures and redrawing supplier hierarchies across biopolymer value chains. China's dual carbon goals and Japan's METI circular economy directives institutionalize this feedstock transition, while packaging converters scramble to secure qualified resin supply ahead of single-use plastic enforcement deadlines.
Growth Catalysts
- EU F-Gas Regulation:Industrial gas phase-down mandates indirectly channel capital toward bio-based polyester alternatives in flexible packaging laminates.
- Food-contact flexible packaging:Copolymer grades with adipic acid incorporation command premium positioning as thermal property windows expand for hot-fill applications.
- East China's chemical corridor:Integrated PBS resin-to-compound operations near Shanghai and Ningbo concentrate technical talent and reduce logistics friction for export-oriented converters.
Market Restraints
- Corn and glucose feedstock volatility:Fermentation input costs swing with agricultural commodity markets, squeezing margin predictability for biopolymer producers without long-term supply contracts.
- Composting infrastructure gaps:Regional buildout rates lag resin capacity expansion, creating end-of-life pathway uncertainty that deters brand owner commitments at scale.
- Polylactic acid substitution:PLA price erosion and established composting certification create switching pressure in cold-chain food service applications where PBS held technical advantages.
Strategic Opportunities
- Automotive interior trim:OEM cabin air quality certifications and landfill diversion targets open specification windows for PBS in injection-molded dashboard components.
- China's SAMR biodegradable labeling standards:GB standard enforcement creates procurement mandates that institutionalize demand across convenience retail supply chains.
- Starch-PBS blend compounds:Cost-performance optimization through hybrid formulations is capturing flexible film applications in agricultural mulch and retail carry bags.
Industry Challenges
- Polymer engineering talent scarcity:Bioprocess optimization expertise outpaces conventional plastics training pipelines, creating recruitment bottlenecks for scale-up operations.
- Composting facility certification timelines:GB standards acceptance criteria require extended validation cycles that delay product launches and tie up working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polybutylene Succinate (PBS) Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homopolymer, Copolymer, Blends, Composites Application: Packaging, Agriculture, Textiles, Automotive End User: Manufacturers, Retailers, Distributors, Exporters Distribution Channel: Online, Offline, Direct Sales, Wholesale |
| Companies Covered | Eastman Chemical Company, Showa Denko K.K., PTT MCC Biochem Co., Ltd., Vizag Chemicals, Shandong LanDian Biological Technology Co., Ltd., Mitsubishi Chemical Corporation, BASF SE, SK Chemicals, Anhui Sealong Biotechnology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polybutylene Succinate (PBS) Market Evolving Landscape
Direct esterification catalyst innovation and controlled ring-opening polymerization advances are compressing molecular weight distribution tolerances and enabling thinner-gauge film applications. Technical differentiation now concentrates in process chemistry rather than feedstock sourcing alone.
Continuous polycondensation reactor designs with titanium-based catalyst systems are displacing batch esterification for commodity-grade PBS resin. Packaging converters in Japan's convenience retail sector adopt these materials for onigiri wrappers and bento trays at accelerating pace. The shift enables 15-micron gauge reduction without seal strength degradation, compressing resin consumption per unit and reshaping procurement specifications.
Japan's METI bioplastics roadmap and container recycling laws tighten procurement mandates across retail supply chains. Convenience store operators face 2030 biopolymer content targets that institutionalize PBS volume offtake regardless of fossil resin price differentials. Food-contact flexible packaging segments respond by locking multi-year supply agreements with integrated fermentation-to-resin producers.
Compounders now specify custom starch-PBS ratios rather than purchasing off-grade resin for cost dilution. Agricultural mulch film distributors in China's Shandong province blend 30-50% modified starch into PBS base resin to hit target degradation rates in soil burial tests. The specification shift fragments supplier relationships and rewards compounders with in-house formulation laboratories over pure resin traders.
Polybutylene Succinate (PBS) Market Segmentation
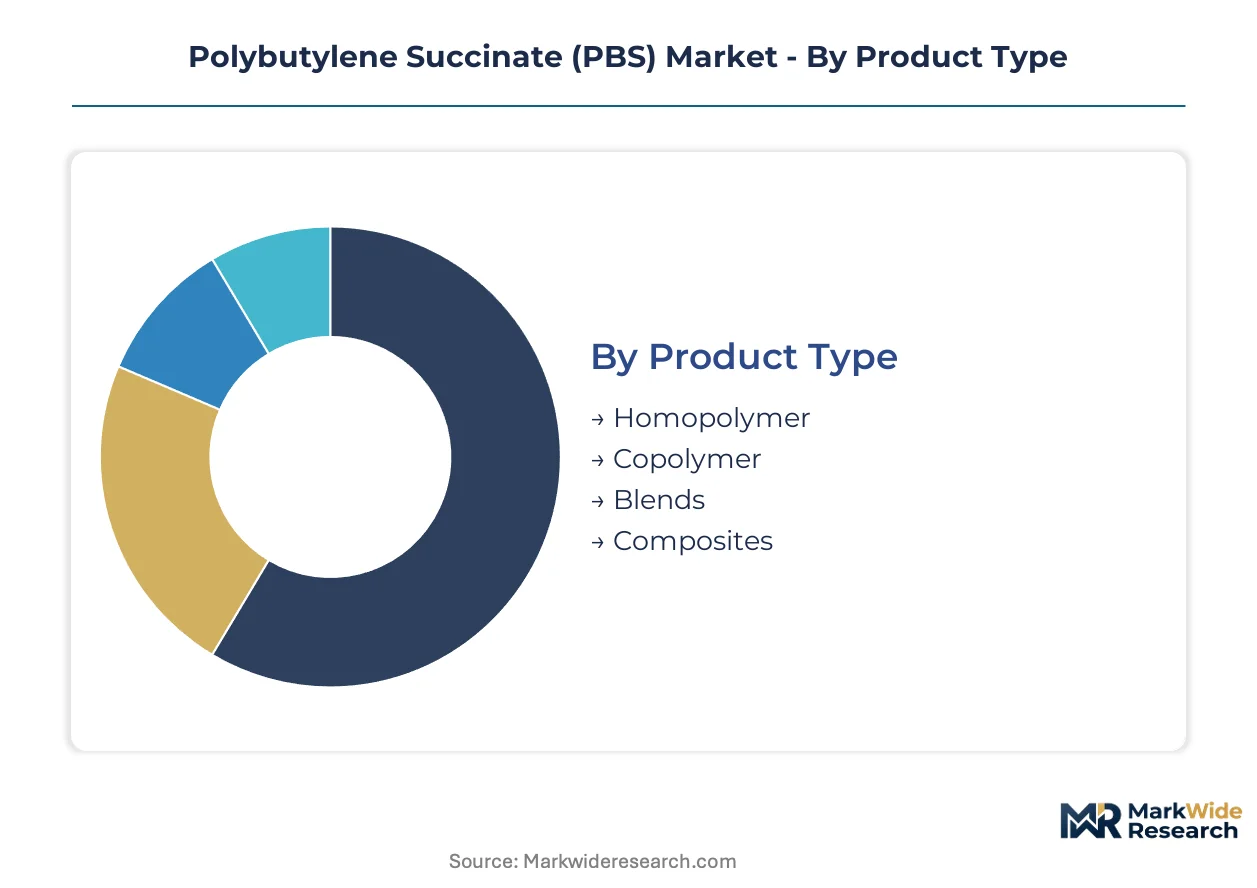
PBS market segmentation reflects divergent certification requirements across composting standards and end-of-life pathways. Product grades, application specifications, and channel structures each carry distinct regulatory and technical constraints that shape procurement decisions.
Product Type:
GB standards from China's SAMR and EU REACH substance restrictions create tiered compliance obligations that separate commodity grades from certified compostable formulations.
- Homopolymer:Pure PBS resin synthesized through direct esterification or ring-opening polymerization delivers melting points near 114°C with consistent biodegradation rates. Japanese convenience retail chains specify homopolymer grades for onigiri wrappers to satisfy METI container recycling mandates.
- Copolymer:Adipic acid or lactic acid incorporation broadens thermal windows and mechanical flexibility for hot-fill food-contact applications. Premium positioning in flexible packaging laminates reflects expanded processing tolerances demanded by EU F-Gas Regulation compliance strategies.
- Blends:Hybrid formulations with polylactic acid or starch derivatives optimize cost-performance ratios for agricultural mulch films.
- Composites:Reinforced grades with natural fiber fillers serve automotive interior trim specifications requiring dimensional stability.
Established volume favors homopolymer for commodity packaging; emerging adoption favors copolymer for temperature-critical food service.
Application:
Customer procurement patterns cluster around end-of-life infrastructure availability and brand owner sustainability commitments.
- Packaging:Flexible films and rigid containers dominate resin offtake as drop-in replacements for polypropylene and polyethylene. China's chemical corridor near Shanghai concentrates converter operations serving export markets with GB-certified compostable specifications.
- Agriculture:Mulch films and planting trays leverage soil biodegradability to eliminate retrieval labor costs. Shandong province blend formulations specify 30-50% starch content to hit target degradation rates in burial tests.
- Textiles:Non-woven fiber applications for hygiene products exploit PBS marine biodegradability credentials.
- Automotive:Dashboard components and interior trim gain specification windows through OEM cabin air quality certifications and landfill diversion targets.
Packaging commands current volume leadership; automotive interior trim is climbing the fastest as OEM procurement mandates tighten.
End User:
Supply chain position determines technical service requirements and inventory risk exposure.
- Manufacturers:Integrated resin-to-compound operations in East China manage formulation complexity and quality certification internally.
- Retailers:Convenience store operators in Japan face institutionalized biopolymer content targets that lock multi-year supply agreements regardless of fossil resin price differentials.
- Distributors:Agricultural mulch film distributors in Shandong specify custom starch-PBS ratios rather than purchasing off-grade resin.
- Exporters:Packaging converters serving EU markets navigate REACH compliance and composting facility acceptance criteria across member states.
Manufacturer direct procurement dominates resin volume; retailer mandates are gaining share fastest as circular economy directives institutionalize demand.
Distribution Channel:
Channel selection reflects order scale, technical support needs, and certification documentation requirements.
- Online:Digital procurement platforms serve small-batch compounders and research institutions requiring rapid sample access.
- Offline:Traditional distributor networks maintain technical service relationships for agricultural mulch and retail bag applications.
- Direct Sales:Integrated fermentation-to-resin producers in China and Japan lock multi-year agreements with major packaging converters.
- Wholesale:Volume traders manage inventory positions for commodity-grade homopolymer serving standardized applications.
Direct sales capture premium copolymer and certified grades; wholesale channels dominate undifferentiated homopolymer volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's GB standards enforcement anchors China's dominance in PBS demand generation, with dual carbon goals institutionalizing fermentation-based feedstock transitions across East Asia. Regulatory mandates in Japan and South Korea accelerate procurement timelines, while European REACH compliance and North American composting infrastructure investments reshape trade flows.
China
Packaging converters in Shanghai and Ningbo expand biopolymer procurement ahead of single-use plastic bans. SAMR enforces biodegradable labeling standards that institutionalize demand across convenience retail supply chains. The Yangtze River Delta chemical corridor concentrates integrated PBS resin-to-compound operations serving export-oriented manufacturers.
Japan
METI's circular economy directives mandate biopolymer content targets for convenience store operators by 2030. Container recycling laws create procurement obligations that lock multi-year supply agreements regardless of fossil resin price differentials. Kanto region compounders optimize starch-PBS blend ratios for onigiri wrappers and bento tray specifications.
Germany
EU F-Gas Regulation phase-down mandates channel capital toward bio-based polyester alternatives in flexible packaging laminates. BASF SE leverages Ludwigshafen research complexes for catalyst innovation in direct esterification routes. North Rhine-Westphalia's chemical cluster anchors fermentation-to-resin technical development for automotive interior trim applications.
South Korea
OEM cabin air quality certifications and landfill diversion targets open specification windows for PBS in injection-molded dashboard components. MFDS food-contact regulations align with EU standards to enable export-oriented compounder operations. Seoul Capital Area distributors manage custom formulation inventory for agricultural mulch film specifications.
United States
EPA composting facility certification timelines and state-level plastic bans create fragmented demand patterns across regional markets. California's SB 54 implementation accelerates brand owner commitments to certified biodegradable packaging. Midwest agricultural distributors specify soil-biodegradable mulch films to eliminate retrieval labor costs in specialty crop operations.
Polybutylene Succinate (PBS) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the PBS value chain. The market structure consolidates around integrated fermentation-to-resin producers with captive succinic acid supply, while specialized compounders fragment the downstream blend and composite segments. Two dominant archetypes emerge: diversified chemical conglomerates with catalyst R&D depth, and biotech-focused specialists with fermentation process optimization. Competitive moves concentrate on backward integration into feedstock supply and multi-year offtake agreements with packaging converters.
Among German chemical conglomerates, BASF SE exemplifies the diversified archetype with integrated research infrastructure. Japanese specialists Showa Denko K.K. and Mitsubishi Chemical Corporation occupy positions reflecting distinct process chemistry expertise. Chinese players Shandong LanDian Biological Technology Co., Ltd. and Anhui Sealong Biotechnology Co., Ltd. represent the fermentation-focused tier with regional supply chain concentration. Eastman Chemical Company and SK Chemicals anchor transnational positioning across premium copolymer specifications.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Showa Denko K.K. |
| PTT MCC Biochem Co., Ltd. |
| Vizag Chemicals |
| Shandong LanDian Biological Technology Co., Ltd. |
| Mitsubishi Chemical Corporation |
| BASF SE |
| SK Chemicals |
| Anhui Sealong Biotechnology Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Fermentation-based succinic acid substitution for petrochemical feedstocks simultaneously redraws supply geography toward East China's chemical corridor and compresses pricing economics for biopolymer grades. This feedstock transition concentrates cost advantage with integrated producers while fragmenting pricing power among compounders lacking captive fermentation assets.
Pricing Analysis
East Asian price spreads widen against European quotations as China's dual carbon goals accelerate domestic capacity buildout. Three-tier pricing structure across premium copolymer, certified homopolymer, and commodity-grade resin reflects certification complexity and volume scale. Cost compression in standard grades intensifies because polylactic acid substitution pressure forces margin sacrifice. Agricultural mulch distributors exhibit highest price sensitivity due to starch-blend formulation flexibility, while Japanese convenience retailers show lowest sensitivity under METI-mandated procurement floors.
Supply Chain Analysis
Inventory cycles stretch to twelve-week lead times for certified compostable grades awaiting GB standards validation. Supply concentrates in China, Japan, and South Korea where fermentation-to-resin integration anchors production. Raw material flows draw from corn-derived glucose, 1,4-butanediol, and adipic acid modifiers. Single-source vulnerability concentrates in fermentation strain intellectual property controlled by select biotechnology licensors. Distribution runs through direct sales agreements for premium grades and wholesale channels for commodity homopolymer.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect around composting infrastructure interoperability, where GB standards acceptance creates network effects that institutionalize demand across convenience retail supply chains.
For Market Incumbents: Fortify backward integration into fermentation strain development to defend against biotech specialist encroachment. Lock multi-year offtake agreements with packaging converters ahead of single-use plastic enforcement deadlines. Capacity addition in East China's Yangtze River Delta preserves logistics advantage for export-oriented compounders. For New Entrants and Emerging Players: Lead with automotive interior trim specifications where OEM cabin air quality certifications create specification windows unclaimed by established packaging-focused incumbents. Agricultural mulch film in China's Shandong province offers penetrable volume through custom starch-PBS blend formulation services. Go-to-market angle centers on soil-biodegradability certification support bundled with resin supply. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fermentation technology platforms seeking downstream resin integration. Long-term viability hinges on composting infrastructure buildout rates outpacing resin capacity expansion. Acquisition target archetype: compounders with in-house formulation laboratories and GB standards certification relationships. Signal to watch: convenience retailer multi-year supply agreement announcements as demand commitment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Assets | Captive succinic acid supply locks cost advantage against petrochemical feedstock volatility. |
| Long-term Supply Agreement with Retailers | METI-mandated biopolymer content targets institutionalize volume regardless of fossil resin spreads. |
| Joint Venture for Composting Certification | GB standards validation partnerships accelerate product launch timelines and reduce working capital drag. |
| Capacity Expansion in East China Corridor | Shanghai-Ningbo cluster proximity reduces logistics friction for export-oriented packaging converters. |
| Green Manufacturing Transition | Dual carbon goals compliance secures preferential licensing and procurement mandates from SAMR. |
Research Methodology
Initial hypotheses were tested against primary input from fermentation plant managers, packaging converter procurement leads, agricultural mulch film distributors, and METI regulatory affairs specialists and refined through secondary validation. Bottom-up triangulation combined customs trade data, SEC filings of listed chemical conglomerates, SAMR biodegradable standards documentation, and IHS Markit polymer production databases with top-down macroeconomic factor integration.
Variance decomposition across the projection horizon isolates feedstock cost volatility, regulatory enforcement timing, and composting infrastructure buildout rates as primary uncertainty sources. Segmentation dimensions modeled include product grade tier, end-use application, regional production hub, and certification status. CAGRs derive from capacity-expansion announcements, announced plant utilization rates, and brand owner sustainability commitment disclosures tracked across the analysis window.
Forecasts assume regulatory continuity in China's SAMR enforcement regime and Japan's METI circular economy directives; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Flexible Polyurethane Foam Market
Polymers & Resins
Solid-Grade Thermoplastic Acrylic (Beads) Resin Market
Polymers & Resins
Paper Processing Resins Market
Polymers & Resins
Medical Fluoropolymers Market
Polymers & Resins
Africa Polyether Ether Ketone (PEEK) Market
Polymers & Resins
Europe Expanded Polystyrene (EPS) Market
Polymers & Resins
Middle East Engineering Plastics Market
Polymers & Resins
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market
Polymers & Resins
Global Engineering Plastic Market
Polymers & Resins
EVA Copolymer Market
Polymers & Resins
Styrenics Market
Polymers & Resins
Biaxially Oriented Polypropylene Market
Polymers & Resins
Marine-grade Polyurethane Market
Polymers & Resins
Middle-East and Africa Epoxy Resins Market
Polymers & Resins
HDPE Large Blow Molded Products Market
Polymers & Resins
Global Chlorinated Polyethylene Market