
 Global Fluoropolymer Tubing Market | 2026-2036
Global Fluoropolymer Tubing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fluoropolymer Tubing Market Foresight
China is narrowing its fluoropolymer tubing supply gap through domestic PTFE and PFA resin capacity additions. Zeus Industrial Products leverages advanced extrusion capabilities to sustain North American aerospace and medical tubing dominance. Saint-Gobain Performance Plastics anchors European chemical processing demand through specialized high-purity product lines. Parker Hannifin competes across industrial distribution channels with integrated fitting-and-tubing systems.
Fluoropolymer tubing consists of extruded thermoplastic conduits manufactured from polytetrafluoroethylene, fluorinated ethylene propylene, perfluoroalkoxy, and related fluorocarbon resins, typically achieving operating temperatures from minus seventy-three degrees Celsius to two hundred sixty degrees Celsius with near-universal chemical inertness. These properties enable critical fluid transport in corrosive chemical environments, ultra-pure semiconductor manufacturing, and sterile pharmaceutical processing where metallic contamination risks are unacceptable. PTFE tubing occupies the largest volume share due to its cost position and established specification in legacy chemical processing infrastructure. PFA tubing commands premium positioning in semiconductor cleanroom applications where extractable limits approach parts-per-billion thresholds. FEP tubing extends into laboratory and analytical instrumentation segments where optical clarity and flexibility outweigh maximum temperature requirements.
FDA food-contact regulations, EPA emissions standards for chemical processing equipment, and REACH substance restrictions collectively shape material selection and certification burdens across the value chain. The EU F-Gas Regulation and evolving MEE oversight in China are tightening production emissions controls for fluoropolymer resin manufacturers, indirectly constraining tubing supply elasticity. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate certification cost impacts and supply qualification timelines.
Market Dynamics
Semiconductor equipment manufacturers are consolidating fluoropolymer tubing procurement around ultra-pure PFA specifications, compressing supplier qualification timelines and elevating extractable contamination thresholds as the dominant market-shaping force.
Growth Catalysts
- REACH substance restrictions:European chemical processors are replacing metal piping with fluoropolymer tubing to eliminate metallic contamination risks in corrosive fluid handling, tightening material certification standards across the value chain.
- East Asian chip fabrication clusters:South Korean and Taiwanese semiconductor manufacturers are expanding cleanroom infrastructure, concentrating demand for high-purity PFA tubing with parts-per-billion extractable limits.
- Dual carbon goals:China's MEE oversight is accelerating domestic PTFE and PFA resin capacity additions, narrowing the country's fluoropolymer tubing supply gap through backward integration into raw material production.
Market Restraints
- Fluoropolymer resin supply concentration:A limited number of specialized chemical producers control global PTFE and PFA resin supply, creating input cost volatility when environmental compliance disruptions occur at major manufacturing sites.
- F-Gas Regulation production constraints:The EU's tightening emissions controls on fluoropolymer resin manufacturing are indirectly constraining tubing supply elasticity, extending lead times for European chemical processing customers.
- Metallic piping substitution in low-corrosion applications:Stainless steel and advanced polymer composites retain cost advantages in non-critical fluid transport, limiting fluoropolymer tubing penetration in price-sensitive industrial segments.
Strategic Opportunities
- Pharmaceutical sterile processing expansion:FDA food-contact regulations and aseptic manufacturing mandates are opening new specification windows for FEP tubing in biologics production, where optical clarity supports in-line quality monitoring.
- Integrated fitting-and-tubing systems:Industrial distributors are capturing margin through bundled fluid handling solutions, creating channel innovation opportunities for tubing manufacturers with in-house fitting fabrication capabilities.
- Indian chemical processing infrastructure:BIS standards alignment with international purity specifications is enabling fluoropolymer tubing qualification in the country's expanding specialty chemical manufacturing zones.
Industry Challenges
- Cleanroom certification timeline compression:Semiconductor equipment OEMs are demanding supplier qualification cycles below historical norms, straining tubing manufacturers' analytical testing and documentation capabilities.
- Multi-jurisdiction regulatory divergence:Stakeholders must simultaneously satisfy EPA emissions standards, REACH substance restrictions, and evolving MEE oversight, multiplying compliance engineering overhead.
- Extractable testing capability scarcity:Parts-per-billion contamination analysis requires specialized mass spectrometry infrastructure that few tubing producers maintain in-house, creating bottlenecks in new product introduction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fluoropolymer Tubing Market |
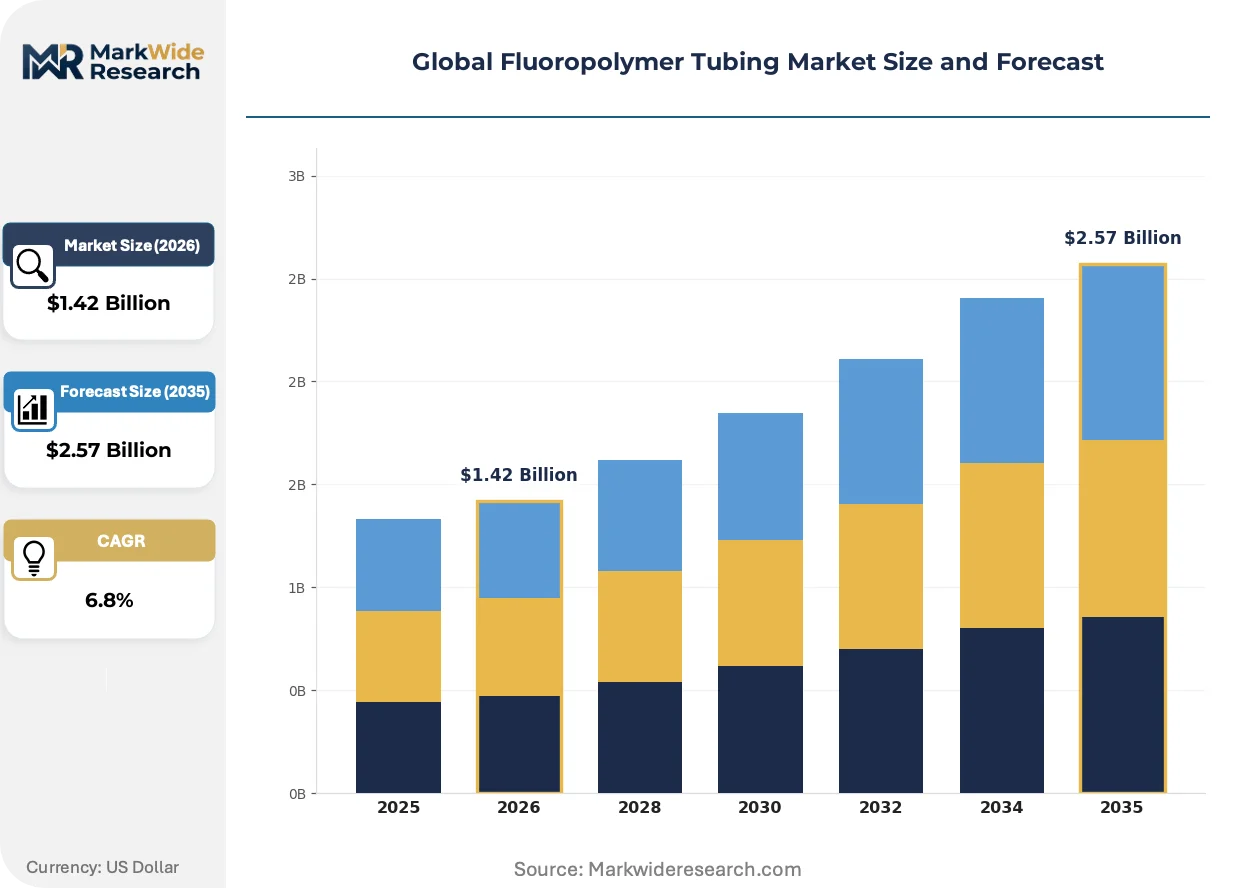
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTFE Tubing, FEP Tubing, PFA Tubing, ETFE Tubing, PVDF Tubing Application: Chemical Processing, Semiconductor Equipment, Pharmaceutical Production, Food & Beverage Processing, Aerospace Systems End User: Process Manufacturers, Chip Fabricators, Drug Manufacturers, Food Processing Plants, Aircraft Manufacturers Installation Type: Laboratory Setup, Industrial Plants, Automated Assembly Lines, Clean Rooms, Field Operations |
| Companies Covered | Saint-Gobain Performance Plastics, Zeus Industrial Products, Optinova, Parker Hannifin, TE Connectivity, Adtech Polymer Engineering Ltd., AMETEK Inc., Swagelok Company, Tef-Cap Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fluoropolymer Tubing Market Shifts & Advancements
Extrusion precision and resin purification are advancing in parallel, collapsing the performance gap between legacy PTFE specifications and premium PFA grades while regulatory emissions frameworks reshape manufacturing location decisions.
Multi-layer co-extrusion technology is collapsing traditional single-material tubing architectures by embedding conductive or barrier layers within fluoropolymer matrices. Semiconductor OEMs in South Korea and Taiwan are specifying these structures for static-dissipative chemical delivery systems. This convergence is collapsing the distinction between commodity tubing and engineered fluid handling components.
The EU F-Gas Regulation is tightening production emissions controls for fluoropolymer resin manufacturers, forcing capacity relocation and process retrofits. Industrial consequences include extended European supply lead times and elevated certification burdens for tubing processors sourcing EU-origin resin. Chemical processing segments are responding by diversifying qualification across multiple resin supply geographies.
Specification consolidation around ultra-pure grades is compressing buyer-seller contracting cycles, with semiconductor equipment manufacturers demanding multi-year supply agreements with fixed extractable thresholds. Direct procurement relationships are displacing traditional distribution channels in high-volume cleanroom applications. This pattern is most visible in Taiwanese and South Korean fabrication zones where equipment OEMs centralize tubing sourcing decisions.
Global Fluoropolymer Tubing Market Segmentation
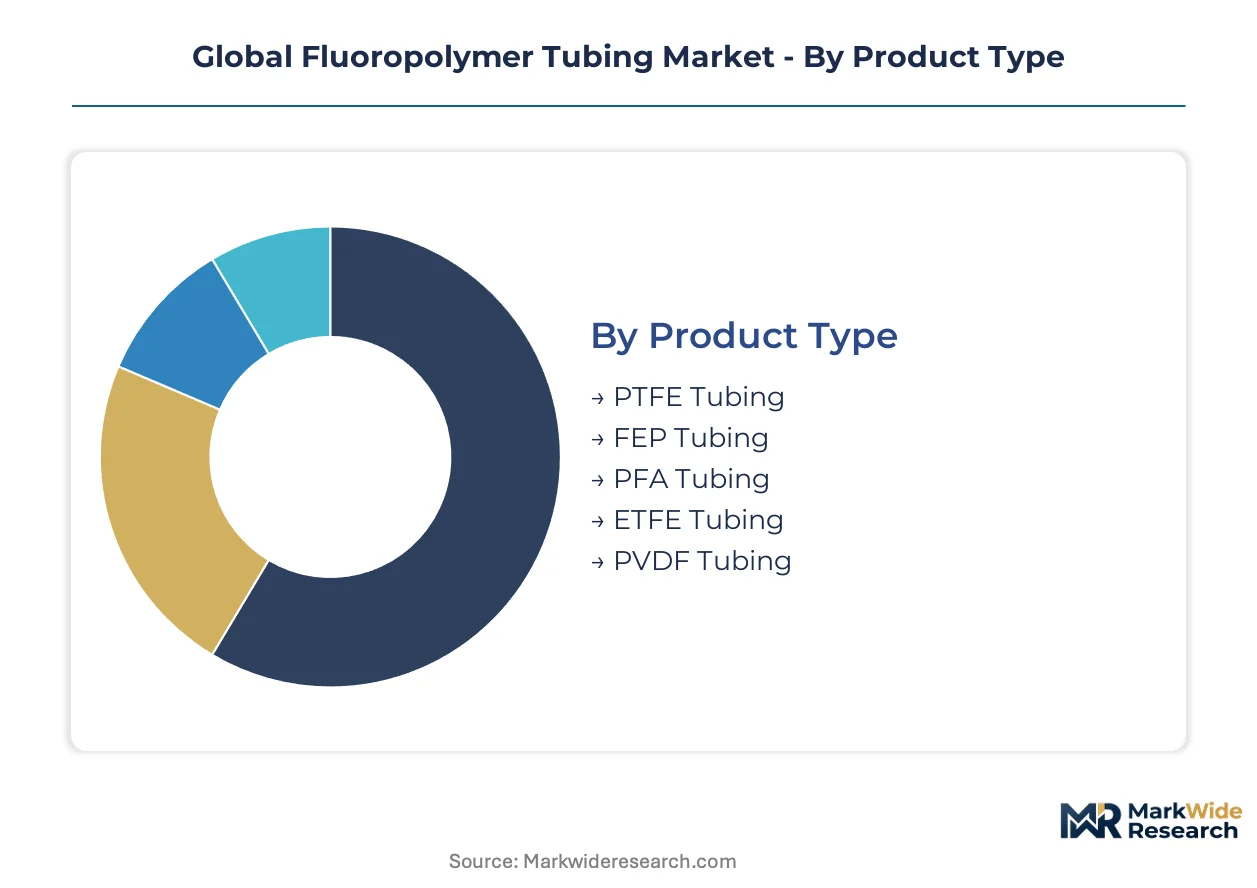
Fluoropolymer tubing procurement cycles vary dramatically across specifications. Semiconductor cleanroom installations demand multi-year qualification timelines. Chemical processing replacements run on decades-long infrastructure refresh schedules.
Product Type:
PTFE and PFA formulations command the longest replacement cycles due to infrastructure permanence, while ETFE and PVDF segments turn over faster as application requirements evolve.
- PTFE Tubing:Extruded polytetrafluoroethylene conduits achieve the broadest operating temperature range among commercial fluoropolymers. Chemical processing infrastructure in Germany and the United States specifies PTFE for sulfuric acid and caustic handling, though REACH substance documentation burdens are extending European procurement timelines.
- PFA Tubing:Perfluoroalkoxy resins deliver superior extractable purity with parts-per-billion metallic contamination thresholds. Taiwanese and South Korean chip fabricators concentrate demand here, compressing supplier qualification windows below historical norms as equipment OEMs consolidate procurement.
- FEP Tubing:Fluorinated ethylene propylene offers optical clarity and flexibility for laboratory analytical instrumentation.
- ETFE Tubing:Ethylene tetrafluoroethylene balances mechanical toughness with chemical resistance for aerospace fluid routing.
- PVDF Tubing:Polyvinylidene fluoride serves cost-sensitive industrial applications where temperature extremes are less critical.
PTFE dominates installed base. PFA is where expansion concentrates.
Application:
Margin structures diverge sharply across these end-use environments. Semiconductor and pharmaceutical specifications command certification premiums. Food processing and chemical applications compete on total installed cost.
- Chemical Processing:Corrosive fluid transport infrastructure specifies fluoropolymer tubing to eliminate metallic contamination risks. European processors under ECHA REACH oversight are accelerating replacement of legacy metal piping, though F-Gas Regulation constraints on resin supply are extending lead times.
- Semiconductor Equipment:Ultra-pure chemical delivery systems in cleanroom environments demand PFA tubing with sub-ppb extractable limits. South Korean and Taiwanese fabrication clusters concentrate global procurement volume, with equipment OEMs demanding multi-year supply agreements with fixed contamination thresholds.
- Pharmaceutical Production:Aseptic manufacturing mandates FDA-compliant fluid handling for biologics processing.
- Food & Beverage Processing:FDA food-contact regulations govern material selection for sanitary fluid transport.
- Aerospace Systems:Fuel and hydraulic routing specifications prioritize fire resistance and weight reduction.
Chemical processing holds the largest replacement volume. Semiconductor equipment is climbing the fastest.
End User:
Procurement sophistication varies enormously across buyer types. Chip fabricators employ dedicated materials engineers. Food processors rely on distributor recommendations.
- Process Manufacturers:Specialty chemical producers operate continuous-process infrastructure with decades-long asset lifecycles. German and Belgian chemical clusters specify high-purity fluoropolymer tubing for chlorine and fluorine handling, with ECHA compliance documentation requiring dedicated regulatory affairs staffing.
- Chip Fabricators:Taiwan Semiconductor Manufacturing Company and Samsung Electronics centralize tubing procurement decisions at the equipment OEM level. These buyers demand integrated fitting-and-tubing systems with full extractable certification packages, displacing traditional distribution channels.
- Drug Manufacturers:Biologics producers require aseptic fluid handling with in-line quality monitoring capabilities.
- Food Processing Plants:Sanitary applications specify FDA-compliant materials with clean-in-place compatibility.
- Aircraft Manufacturers:Boeing and Airbus tier suppliers manage fluoropolymer tubing qualification through airframe system integrators.
Process manufacturers represent the deepest installed base. Chip fabricators are gaining share fastest.
Installation Type:
Environmental control requirements drive specification stratification. Cleanroom and laboratory installations demand the highest purity grades. Field operations prioritize mechanical durability.
- Laboratory Setup:Analytical and research facilities specify FEP tubing for optical clarity in spectroscopy and chromatography applications. University and corporate R&D centers in the United States and Japan concentrate demand, with procurement cycles tied to grant funding and capital equipment refresh schedules.
- Clean Rooms:ISO 14644-compliant environments in Hsinchu and Pyeongtaek specify static-dissipative multi-layer tubing architectures. Semiconductor OEMs are qualifying co-extruded conductive layers for chemical delivery systems, collapsing the distinction between commodity tubing and engineered components.
- Industrial Plants:Process manufacturing infrastructure runs on extended replacement cycles with specification inertia.
- Automated Assembly Lines:High-volume production environments demand consistent dimensional tolerances for robotic handling.
- Field Operations:Remote chemical and energy applications prioritize mechanical toughness over maximum purity.
Industrial plants dominate cumulative installed length. Clean rooms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PTFE and PFA resin production concentrates among specialized chemical manufacturers in China, the United States, Germany, Japan, and South Korea. This geographic clustering shapes tubing supply elasticity and qualification timelines across end-use segments.
United States
Zeus Industrial Products anchors North American aerospace and medical tubing supply through advanced extrusion capabilities. FDA food-contact regulations and EPA emissions standards govern material certification for pharmaceutical and chemical processing applications. The Southeast and Midwest manufacturing corridors host concentrated tubing fabrication capacity serving domestic semiconductor equipment OEMs.
China
Domestic PTFE and PFA resin capacity additions are narrowing the country's fluoropolymer tubing supply gap. MEE oversight under dual carbon goals is tightening production emissions controls for resin manufacturers, indirectly constraining tubing supply elasticity. Yangtze River Delta and Pearl River Delta clusters are expanding cleanroom infrastructure for chip fabrication, concentrating demand for high-purity specifications.
Germany
REACH substance restrictions and the EU F-Gas Regulation are tightening material certification standards for chemical processing applications. ECHA compliance documentation requirements are extending procurement timelines for specialty chemical producers. The North Rhine-Westphalia and Bavaria industrial corridors specify high-purity fluoropolymer tubing for corrosive fluid handling in chlorine and fluorine processing.
South Korea
Samsung Electronics and domestic chip fabricators are consolidating fluoropolymer tubing procurement around ultra-pure PFA specifications. MFDS pharmaceutical regulations and cleanroom standards govern aseptic fluid handling requirements. The Pyeongtaek and Seoul Capital Area fabrication clusters are compressing supplier qualification windows below historical norms.
Taiwan
TSMC and semiconductor equipment OEMs centralize tubing sourcing decisions, demanding multi-year supply agreements with fixed extractable thresholds. ISO 14644-compliant cleanroom standards govern static-dissipative multi-layer tubing architectures. The Hsinchu Science Park concentration is displacing traditional distribution channels through direct procurement relationships.
Global Fluoropolymer Tubing Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base stratifies across three tiers: multinational industrial conglomerates with integrated fitting-and-tubing systems, mid-cap extrusion specialists with resin purification capabilities, and regional fabricators serving price-sensitive industrial segments. Two dominant competitive moves are reshaping positioning: backward integration into captive resin supply, and multi-layer co-extrusion technology licensing for static-dissipative specifications.
Among North American fabricators, Zeus Industrial Products and Parker Hannifin occupy positions at opposite ends of the integration spectrum. Zeus exemplifies the extrusion specialist archetype with concentrated aerospace and medical tubing dominance. Parker Hannifin represents the platform integrator model, competing across industrial distribution channels with bundled fluid handling solutions. Saint-Gobain Performance Plastics anchors European chemical processing demand, sitting within the multinational specialty materials tier. These three companies illustrate the structural divergence between component purity and system integration strategies.
| Leading Market Players |
|---|
| Saint-Gobain Performance Plastics |
| Zeus Industrial Products |
| Optinova |
| Parker Hannifin |
| TE Connectivity |
| Adtech Polymer Engineering Ltd. |
| AMETEK Inc. |
| Swagelok Company |
| Tef-Cap Industries |
| Others |
Supply & Pricing Matrix
Yangtze River Delta resin capacity additions are compressing regional price premiums while elevating bargaining power for tubing fabricators with captive supply arrangements. This geographic supply shift is redistributing pricing leverage from European specialty chemical producers toward integrated East Asian manufacturers.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure by constraining European resin supply and elevating certification costs for REACH-compliant tubing grades. Three-tier pricing structure across premium, standard, and economy levels separates sub-ppb PFA for semiconductor cleanrooms from industrial-grade PTFE and cost-optimized PVDF alternatives. Cost compression in standard grades is intensifying because Chinese domestic resin additions are expanding supply elasticity. Food processing plants exhibit highest price sensitivity due to specification inertia and distributor-dependent procurement, while Taiwanese chip fabricators prioritize contamination thresholds over unit economics.
Supply Chain Analysis
Extended payment terms from South Korean semiconductor OEMs are squeezing working capital for mid-cap extrusion specialists without balance-sheet depth. Resin supply concentrates in China, the United States, and Japan, with tubing fabrication anchored in Germany, South Korea, and Taiwan. PTFE and PFA resin, specialized purification equipment, and multi-layer co-extrusion tooling constitute critical input dependencies. Single-source vulnerability runs through German resin producers facing F-Gas Regulation compliance retrofits. Distribution runs through industrial distributors for chemical processing segments, while semiconductor equipment OEMs displace channels via direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extractable certification and analytical testing services are expanding faster than base tubing hardware as semiconductor OEMs compress qualification timelines and outsource contamination analysis. This service-attach dynamic elevates recurring revenue stability relative to commodity extrusion margins.
For Market Incumbents: Harden qualification documentation capabilities against cleanroom certification timeline compression from TSMC and Samsung Electronics. Deepen backward integration into captive PFA resin supply to insulate margin structures from EU F-Gas Regulation supply disruptions. Anchor channel control through integrated fitting-and-tubing system bundling to defend against distributor disintermediation in semiconductor procurement consolidation. For New Entrants and Emerging Players: Indian specialty chemical manufacturing zones in Gujarat and Maharashtra represent the most penetrable entry point as BIS standards alignment accelerates fluoropolymer tubing qualification. Pharmaceutical sterile processing expansion for biologics production offers secondary white-space with lower incumbent saturation than semiconductor segments. Lead with FEP tubing optical clarity specifications for laboratory analytical instrumentation where extractable testing capability scarcity creates partnership opportunities with established mass spectrometry providers. For Investors and Strategic Acquirers: Long-term, this sits as a specialty materials consolidation play because resin purification and multi-layer co-extrusion capabilities concentrate in fragmented mid-cap specialists with limited succession planning. Target acquisition archetypes include European extrusion specialists with ECHA compliance documentation depth and East Asian fabricators with cleanroom qualification relationships. Monitor South Korean and Taiwanese equipment OEM procurement centralization patterns as inflection indicators for distributor displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive PTFE and PFA production insulates margins from EU F-Gas Regulation supply constraints. |
| Multi-Layer Co-Extrusion Capacity Addition | Static-dissipative tubing architectures qualify for Samsung Electronics and TSMC chemical delivery specifications. |
| Extractable Testing Service Expansion | Parts-per-billion contamination analysis addresses semiconductor OEM timeline compression and qualification bottlenecks. |
| Integrated Fitting-and-Tubing System Launch | Bundled fluid handling solutions capture distributor margin and defend against channel disintermediation. |
| Indian Market Qualification Investment | BIS standards alignment enables penetration of Gujarat and Maharashtra specialty chemical manufacturing expansion. |
Research Methodology
The analysis maps PTFE, PFA, FEP, ETFE, and PVDF tubing segments, each validated through plant managers at chemical processors, procurement leads at semiconductor equipment OEMs, distribution channel partners, and technical R&D directors at extrusion specialists. Primary interview intelligence combined with customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from disclosed market participants, and ECHA substance restriction databases. Bottom-up fabrication capacity estimates triangulated against top-down end-use demand modeling across chemical processing, semiconductor, pharmaceutical, and aerospace applications.
Fixed assumptions across the analysis window include continued REACH and RoHS compliance stringency, sustained East Asian chip fabrication cluster expansion, and stable fluoropolymer resin production emissions frameworks in China under MEE oversight. Segmentation dimensions modeled encompass material grade tier, end-use application, installation environment, and regional production hub concentration. CAGRs derived from elasticity-adjusted demand projections incorporating semiconductor capital expenditure cycles and chemical processing infrastructure replacement schedules. Industry-specific inputs included cleanroom ISO classification adoption rates and pharmaceutical aseptic manufacturing mandate expansion trajectories.
Stress conditions across resin supply disruption severity, regulatory timeline acceleration, and semiconductor capital expenditure contraction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding compliance cost trajectories and geographic demand concentration. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Global PEX (Cross-Linked Polyethylene) Market
Pipes and Tubes
Chlorinated Polyvinyl Chloride (Cpvc) Pipes Market
Pipes and Tubes
Plastic Pipes and Fittings Market
Pipes and Tubes
Global Lance Tubes Market
Pipes and Tubes
Global Tracer Wires Market
Pipes and Tubes
Industrial Draft Tube Crystallizer Market
Pipes and Tubes
Saw Pipes Market
Pipes and Tubes
HDPE Corrugated Pipe Market
Pipes and Tubes
GCC Polyethylene (PE) Pipes Market
Pipes and Tubes
Global Municipal Pipes Market
Pipes and Tubes
Heat Shrink Tubing Market
Pipes and Tubes
North America Hydraulic Fluid Connectors Market
Pipes and Tubes
UAE PVC Pipes Market
Pipes and Tubes
Welded Pipes Market
Pipes and Tubes
FEP Tubing Products Market
Pipes and Tubes
Perfusion Tubing Systems Market