
 Global Flavors Market | 2026-2036
Global Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flavors Market Analysis
Subscription-based flavor formulation services is hardening as a distinct revenue layer in the industry. Givaudan SA leverages its captive biotechnology platform to supply tailored natural extracts on recurring contracts. Kerry Group plc anchors its position through backward integration into dairy-derived flavor precursors. Sensient Technologies Corporation competes by controlling regional distribution nodes across Southeast Asia.
Flavors comprise volatile and non-volatile organic compounds—esters, aldehydes, terpenes, and pyrazines—synthesized through steam distillation, solvent extraction, or microbial fermentation to impart sensory character to food and beverage matrices. Natural flavors command premium positioning as clean-label procurement by beverage producers displaces artificial alternatives in North American and European accounts. Powder form concentrates margin pools in bakery applications where thermal stability during oven processing determines supplier selection.
FDA GRAS determinations and EFSA flavoring substance evaluations create divergent compliance thresholds that fragment product registration costs across jurisdictions. China's NMPA and SAMR enforce GB standard compliance for imported flavor compounds, conditioning market access for foreign suppliers. Stakeholders must monitor regulatory harmonization gaps between FSSAI's evolving additive schedules and EU REACH annex updates to anticipate reformulation liabilities.
Market Dynamics
Clean-label procurement mandates from beverage producers are compressing artificial flavor inventories while biotechnology platforms scale natural extract fermentation capacity to meet contract volumes.
Growth Catalysts
- EU REACH Annex Updates:ECHA's tightening restrictions on synthetic additives accelerate reformulation toward natural alternatives across European food processing clusters.
- India FSSAI Labeling Mandates:Domestic manufacturers face disclosure requirements that favor certified natural flavor suppliers over unverified imports.
- Precision Fermentation:Microbial production of terpenes and esters reduces extraction costs from agricultural feedstocks while preserving sensory fidelity.
Market Restraints
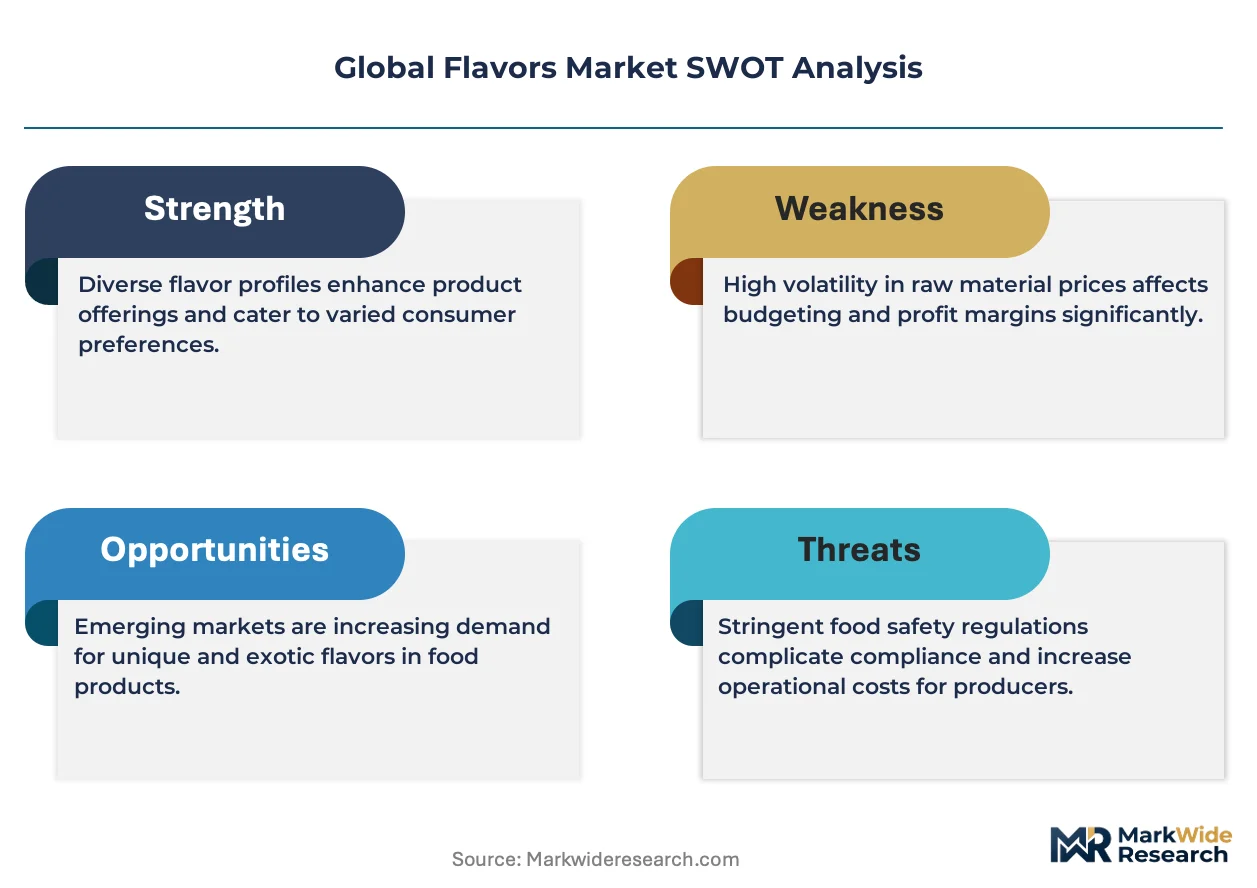
- Agricultural Input Volatility:Vanilla, citrus, and spice harvest fluctuations in Madagascar, Mexico, and Indonesia destabilize natural extract pricing.
- Supplier Concentration Risk:Three biotechnology platforms control most industrial-scale microbial fermentation capacity for high-value flavor molecules.
- Regulatory Fragmentation:Divergent FDA GRAS and EFSA flavoring substance evaluations multiply registration costs for cross-Atlantic suppliers.
Strategic Opportunities
- Vietnam and Indonesia:Underpenetrated Southeast Asian beverage markets lack domestic natural flavor infrastructure, creating first-mover positioning for fermentation-based suppliers.
- Plant-Based Meat Analogues:Fat-soluble flavor systems for extruded protein matrices represent unserved formulation demand distinct from traditional seasoning.
- China Dual Carbon Goals:NMPA and SAMR incentives for low-carbon production processes favor biotech-derived flavors over solvent-extracted alternatives in GB standard compliance.
Industry Challenges
- Flavor Chemist Talent Scarcity:Cross-disciplinary expertise spanning organic chemistry, sensory science, and regulatory affairs concentrates at established suppliers.
- Clean-Label Certification Timelines:Third-party natural certification audits extend supplier qualification cycles beyond typical procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flavors Market |
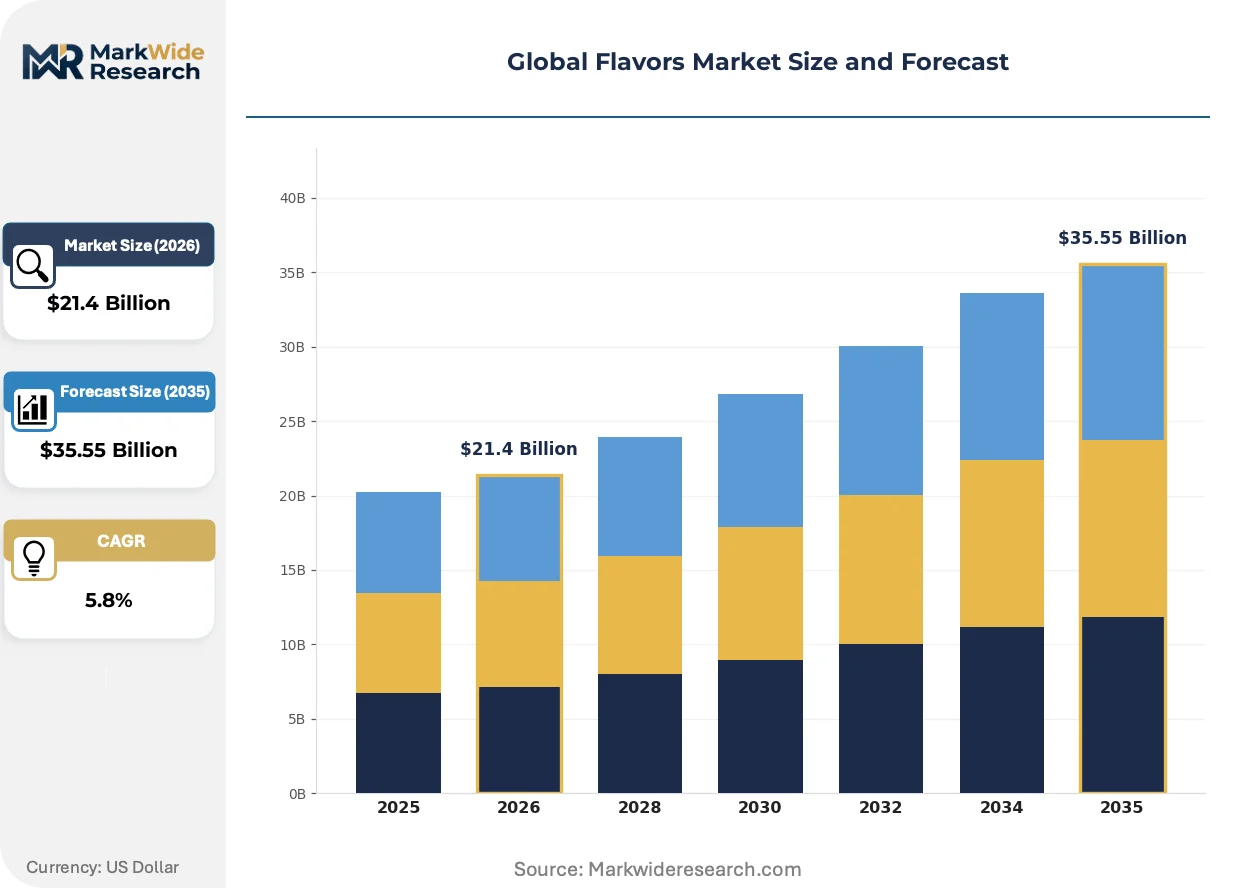
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $35.55 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Artificial Flavors, Flavor Enhancers, Flavoring Agents Form: Liquid, Powder, Paste, Granules Application: Beverages, Bakery, Dairy, Confectionery End User: Food Manufacturers, Beverage Producers, Restaurants, Retailers |
| Companies Covered | Givaudan SA, International Flavors & Fragrances Inc., DSM-Firmenich AG, Symrise AG, Archer Daniels Midland Company, Kerry Group plc, Sensient Technologies Corporation, Takasago International Corporation, Robertet Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flavors Market Emerging Trajectories
Biotechnology platforms and regulatory disclosure requirements are restructuring how flavor compounds reach formulation labs, compressing development cycles while expanding molecular libraries beyond traditional extraction sources.
Cell-culture production of rare botanical compounds is electrifying supply security for ingredients previously constrained by climate-dependent harvests. Beverage manufacturers in North America and Europe are integrating these fermentation-derived extracts into clean-label portfolios at commercial scale. The technology is electrifying competitive positioning by decoupling flavor supply from agricultural commodity cycles.
EFSA's systematic re-evaluation of flavoring substances under REACH-aligned protocols is eliminating synthetic molecules from approved food additive lists. European reformulation costs are rising as manufacturers replace delisted compounds with natural alternatives ahead of enforcement deadlines. Powder-form bakery applications face the steepest substitution pressure given thermal stability requirements that limit viable replacements.
Subscription-based flavor formulation services are displacing traditional spot purchasing in beverage and dairy accounts. Recurring contracts for tailored extract development lock in multi-year supplier relationships while reducing R&D overhead for mid-sized manufacturers. This procurement evolution is most visible in India and Brazil where domestic brands lack captive flavor chemistry capabilities.
Global Flavors Market Segmentation
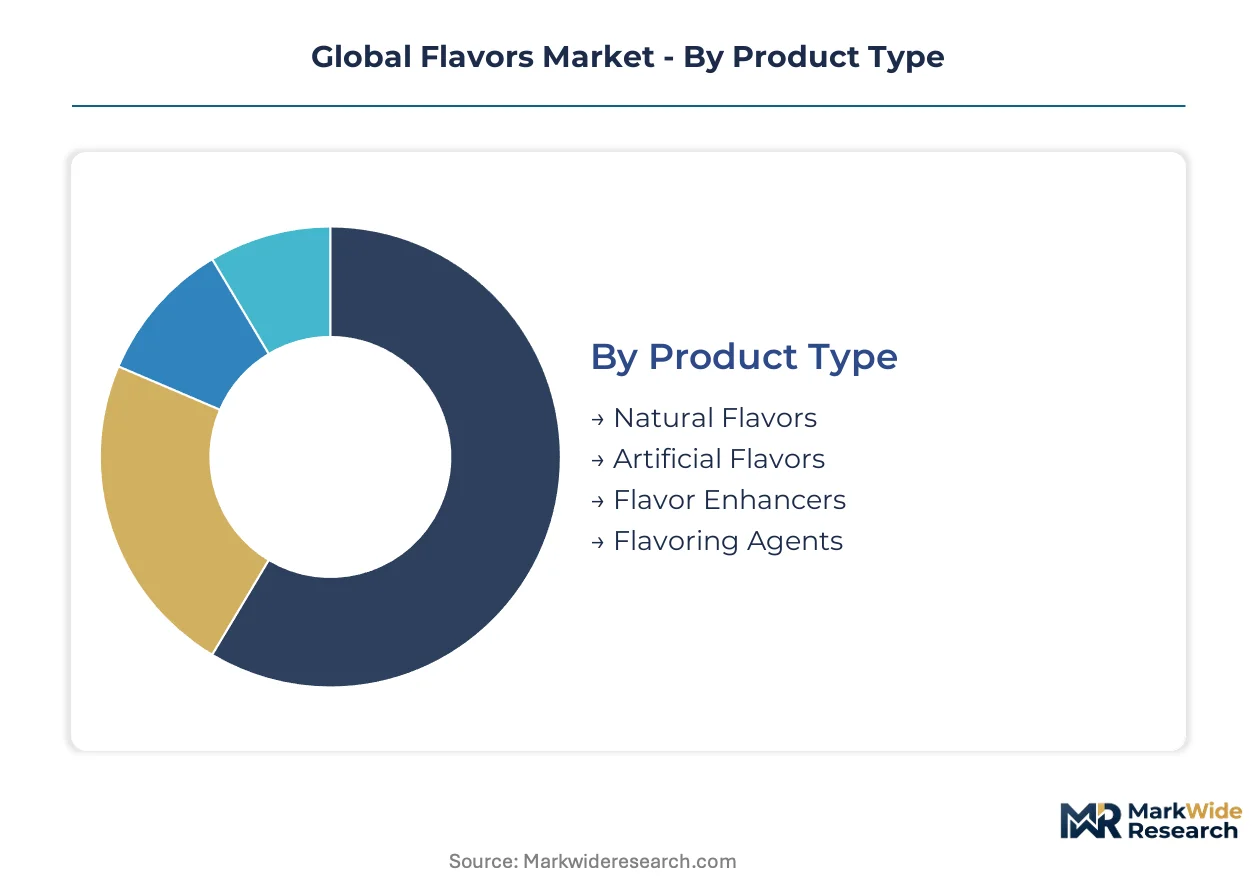
Segmentation in the Global Flavors Market reveals how formulation requirements, regulatory thresholds, and supply chain configurations fragment procurement strategies across end-use categories. Distinct technical specifications for thermal stability, solubility, and labeling compliance drive supplier selection patterns that rarely overlap between applications.
Product Type:
Customization intensity varies sharply across this category, with fermentation-derived natural extracts demanding bespoke development cycles while artificial compounds offer standardized catalog procurement.
- Natural Flavors:Volatile organic compounds derived from botanical, animal, or microbial sources through steam distillation, solvent extraction, or precision fermentation. Beverage producers across Germany, France, and Italy are contracting dedicated fermentation capacity as EFSA REACH-aligned protocols eliminate synthetic alternatives from approved additive lists.
- Artificial Flavors:Chemically synthesized esters, aldehydes, and pyrazines engineered for cost efficiency and batch consistency. Food manufacturers in India and Indonesia retain procurement of artificial compounds where FSSAI and national regulator disclosure requirements remain less stringent than EU equivalents.
- Flavor Enhancers:Glutamates, nucleotides, and yeast-derived compounds that amplify existing taste perception without contributing independent sensory character.
- Flavoring Agents:Carrier solvents, emulsifiers, and encapsulation matrices that stabilize volatile compounds during processing and shelf storage.
Most installed capacity flows through Natural Flavors. Expansion is steepest in Flavor Enhancers as umami-focused reformulation spreads beyond Asian markets into North American and European savory applications.
Form:
Processing economics and thermal exposure requirements divide this category into high-margin specialty formats versus commodity liquid concentrates.
- Liquid:Solvent-based or oil-soluble solutions offering rapid dispersion in beverage matrices and cold-process dairy applications.
- Powder:Spray-dried or encapsulated particles engineered for thermal stability during oven processing in bakery and extruded snack manufacturing. European and North American bakery accounts concentrate procurement of powder formats as EFSA-mandated reformulation eliminates heat-sensitive synthetic carriers.
- Paste:High-viscosity suspensions with extended flavor release profiles for confectionery and frozen dessert applications.
- Granules:Free-flowing agglomerated particles optimized for dry-blend seasoning and instant beverage premixes. Food manufacturers in Brazil and Mexico favor granule procurement for seasoning blends where moisture control during tropical distribution determines supplier selection.
Powder form commands premium positioning in heat-exposed applications. Granules are gaining share fastest in emerging market dry-blend segments where distribution infrastructure favors shelf-stable formats.
Application:
End-use thermal regimes and clean-label exposure create divergent margin structures across this category.
- Beverages:Water-soluble and alcohol-stable flavor systems for carbonated, still, and functional drinks. Precision fermentation platforms in Switzerland and Denmark are scaling capacity for rare botanical extracts as North American and European beverage producers displace artificial inventories.
- Bakery:Heat-stable encapsulated systems surviving oven temperatures above 180°C. Powder formats dominate procurement as thermal degradation of natural alternatives forces reformulation investment ahead of EFSA enforcement deadlines.
- Dairy:Fat-compatible and acid-stable flavors for yogurt, ice cream, and fermented milk products.
- Confectionery:Long-release and bloom-resistant systems for chocolate, chewing gum, and hard candy manufacturing.
Beverage applications absorb the majority of fermentation-derived natural extract volume. Bakery faces the steepest substitution pressure as heat-stable natural alternatives remain technically constrained.
End User:
Scale and captive capability determine whether procurement flows through spot purchasing or subscription-based formulation partnerships.
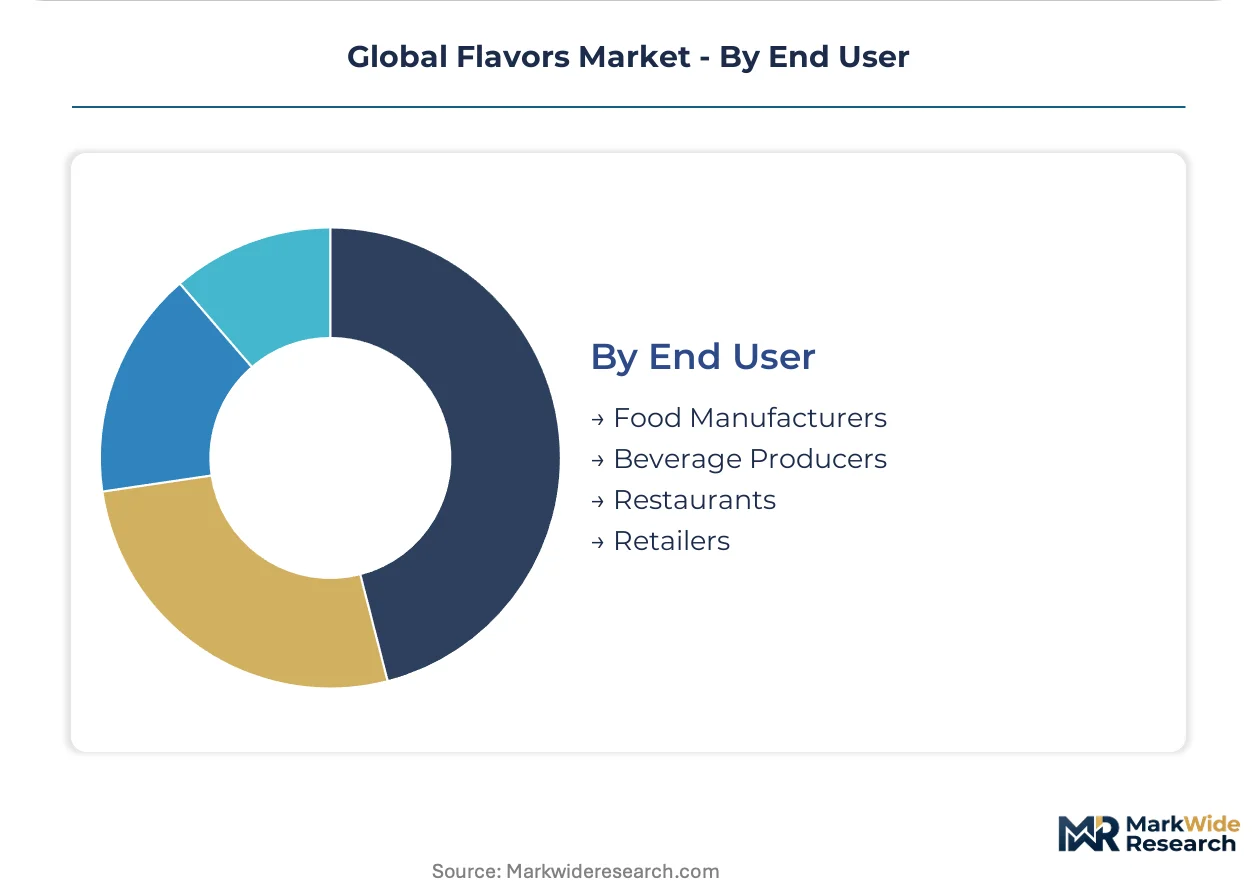
- Food Manufacturers:Mid-sized processors lacking in-house flavor chemistry capabilities. Accounts across India and Brazil are contracting subscription-based formulation services from biotechnology platforms as FSSAI and national regulator labeling mandates intensify.
- Beverage Producers:Large-scale accounts with dedicated procurement teams and multi-year supplier relationships. Clean-label mandates from North American and European beverage producers are compressing artificial flavor inventories while locking in fermentation-derived supply contracts.
- Restaurants:Foodservice operators sourcing finished flavor systems through distribution intermediaries.
- Retailers:Private-label brand owners specifying flavor profiles through co-manufacturing arrangements.
Food Manufacturers represent the largest addressable base for outsourced formulation services. Beverage Producers are expanding contract volumes fastest as biotechnology platforms prove commercial scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting flavor production toward jurisdictions with lower compliance costs while premium natural extract demand concentrates in high-disclosure markets. Manufacturers are relocating fermentation capacity to exploit gaps between EFSA REACH enforcement and emerging-market labeling standards.
United States
Beverage producers in California and Texas are contracting precision fermentation capacity as FDA GRAS determinations for novel natural extracts outpace EFSA timelines. The EPA monitors solvent extraction emissions from New Jersey and Illinois flavor facilities under Clean Air Act protocols. Chicago and Philadelphia host concentrated bakery flavor formulation labs serving mid-Atlantic and Midwest food manufacturers.
Germany
EFSA REACH-aligned protocols are eliminating synthetic flavor molecules from approved additive lists, forcing Cologne and Munich food processors into reformulation cycles. ECHA restrictions on petrochemical-derived carriers accelerate biotechnology platform partnerships. The Bavarian chemical cluster around Ludwigshafen anchors natural extract distillation capacity for European beverage accounts.
India
FSSAI-mandated disclosure requirements are displacing unverified flavor imports as Maharashtra and Gujarat food manufacturers pivot toward certified natural suppliers. The regulator's evolving additive schedules create compliance windows that domestic biotechnology platforms exploit. Mumbai and Ahmedabad concentrate contract fermentation capacity for regional dairy and savory applications.
China
NMPA and SAMR GB standard compliance conditions market access for imported flavor compounds while dual carbon goals incentivize biotech-derived alternatives over solvent extraction. Yangtze River Delta beverage producers are integrating low-carbon fermentation extracts into export formulations. Shanghai and Hangzhou host the majority of domestic natural flavor R&D facilities.
Brazil
Domestic beverage brands lacking captive flavor chemistry capabilities are subscribing to outsourced formulation services as national regulator disclosure requirements intensify. São Paulo and Minas Gerais concentrate granule production for tropical distribution of dry-blend seasonings. ANVISA's evolving food additive protocols favor certified natural suppliers over legacy artificial compound inventories.
Global Flavors Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with biotechnology platforms commanding premium positioning in natural extracts while commodity compound suppliers defend volume in artificial categories. The vendor base concentrates around three strategic tiers: integrated multinationals with captive fermentation capacity, regional specialists controlling distribution nodes, and subscription-based formulation service providers. Dominant competitive moves include backward integration into agricultural feedstocks and strategic partnerships with precision fermentation technology licensors.
Within the integrated multinational tier, Givaudan SA and Kerry Group plc exemplify divergent paths to supply security. Givaudan leverages Swiss biotechnology infrastructure to anchor recurring contract relationships with beverage producers seeking clean-label alternatives. Kerry Group's Irish dairy heritage translates into upstream control over flavor precursor supply chains. Sensient Technologies Corporation represents the regional specialist archetype, with U.S.-based operations concentrated in Southeast Asian distribution node management.
| Leading Market Players |
|---|
| Givaudan SA |
| International Flavors & Fragrances Inc. |
| DSM-Firmenich AG |
| Symrise AG |
| Archer Daniels Midland Company |
| Kerry Group plc |
| Sensient Technologies Corporation |
| Takasago International Corporation |
| Robertet Group |
| Others |
Supply Flow & Price Mechanics
Clean-label procurement mandates from North American and European beverage producers are forcing supply chains to pivot toward fermentation-derived natural extracts, compressing margins on artificial compounds while biotechnology platforms capture premium pricing power through dedicated contract capacity.
Pricing Analysis
Distributor margin layering separates spot-market artificial compounds from subscription-locked natural extracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under EFSA REACH-aligned protocols and volume scale of fermentation capacity commitments. Pricing pressure stems from agricultural input volatility in Madagascar and Indonesia destabilizing vanilla and spice extract costs. Mid-sized food manufacturers in India and Brazil exhibit highest price sensitivity as FSSAI and ANVISA disclosure requirements accelerate without corresponding R&D budgets.
Supply Chain Analysis
Single-source vulnerability sits with Swiss and Danish precision fermentation platforms controlling industrial-scale microbial production of high-value terpenes and esters. Geographic supply concentration centers on Switzerland, Denmark, and the Bavarian chemical cluster around Ludwigshafen for natural extract distillation. Raw material dependencies draw from agricultural feedstocks in Madagascar, Mexico, and Indonesia alongside bioreactor-grade glucose and nitrogen sources. Tariff exposure on solvent-extracted imports into China under NMPA GB standard enforcement creates reformulation risk. Distribution runs through regional formulation service partnerships rather than commodity spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as beverage producers across Germany, France, and Italy displace artificial inventories with fermentation-derived natural extracts that command certification premiums.
For Market Incumbents: Cement supply security through backward integration into dairy-derived flavor precursors and dedicated fermentation capacity expansion in Switzerland or Denmark. Biotechnology platform partnerships anchor recurring contract relationships against emerging precision fermentation specialists. EFSA REACH-aligned protocol enforcement threatens synthetic compound portfolios requiring accelerated reformulation investment. For New Entrants and Emerging Players: Enter via Vietnam and Indonesia's underpenetrated beverage markets lacking domestic natural flavor infrastructure. Plant-based meat analogues offer unserved formulation demand for fat-soluble flavor systems distinct from traditional seasoning. Subscription-based formulation services for mid-sized food manufacturers in Brazil provide the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with biotechnology platforms possessing captive fermentation capacity and EFSA-certified extract portfolios. Long-term viability hinges on decoupling flavor supply from agricultural commodity cycles through cell-culture production. Acquisition targets should display regional distribution node control across Southeast Asia. Monitor EFSA flavoring substance re-evaluation timelines as inflection indicators for synthetic compound delisting acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Swiss and Danish biotechnology platforms lock in multi-year beverage producer contracts under EFSA REACH-aligned protocols. |
| Backward Integration into Agricultural Feedstocks | Kerry Group's Irish dairy heritage secures captive supply of flavor precursors for bakery and dairy applications. |
| Regional Distribution Node Control | Sensient Technologies' Southeast Asian network captures procurement from Vietnam and Indonesia's emerging beverage markets. |
| Subscription-Based Formulation Services | Recurring contracts reduce R&D overhead for mid-sized food manufacturers facing FSSAI-mandated disclosure requirements. |
| Clean-Label Certification Investment | Third-party natural certification audits extend supplier qualification cycles beyond typical procurement windows in India and Brazil. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary interviews engaged flavor chemists, beverage procurement directors, regulatory affairs specialists at biotechnology platforms, and bakery formulation lab managers. Secondary validation drew from EFSA flavoring substance evaluations, FDA GRAS determinations, FSSAI additive schedules, customs data on natural extract imports, and SEC filings from listed flavor suppliers. Bottom-up segment sizing triangulated against top-down market value estimates.
Historical reference periods anchored volume and value projections across the analysis window. Segmentation dimensions modeled include product type, form, application, end user, and regional regulatory cluster. CAGRs were derived from trend extrapolation calibrated to documented contract volumes and capacity expansion announcements. Forecast inputs incorporated precision fermentation yield improvements and EFSA REACH enforcement timeline assumptions.
Inputs from regulatory filings and industry trade data were available through the study window; gaps in proprietary contract pricing introduce uncertainty bands around segment value estimates. Forecasts reflect documented assumptions about biotechnology platform scale-up timelines and agricultural harvest stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Middle East and Africa Flavors and Fragrances Market
Flavorings and Food Additives
Beef Flavors Market
Flavorings and Food Additives
Fenchol Market
Flavorings and Food Additives
Natural Flavor Extract Market
Flavorings and Food Additives
Global Syrup Market
Flavorings and Food Additives
Australia Vanilla Flavor Market
Flavorings and Food Additives
Kokumi Flavor Market
Flavorings and Food Additives
Egypt Food Flavor and Enhancer Market
Flavorings and Food Additives
Japan Food Flavor and Enhancer Market
Flavorings and Food Additives
Carvone Market
Flavorings and Food Additives
Chicory Extract Market
Flavorings and Food Additives
Dairy Flavors Market
Flavorings and Food Additives
Orange Extract Market
Flavorings and Food Additives
Ginkgo Biloba Extract Market
Flavorings and Food Additives
Food-Grade Gellan Gum Market
Flavorings and Food Additives
North America Vanilla and Vanillin Market