
 Australia & New Zealand Food Flavors and Enhancers Market | 2026-2036
Australia & New Zealand Food Flavors and Enhancers Market Size, Share, and Industry Trends Forecast 2026-2036
Australia & New Zealand Food Flavors and Enhancers Market Insights
The premium and commodity tiers within Australia and New Zealand food flavors is decoupling as clean-label natural extracts command procurement premiums while artificial flavor volumes face margin compression. Givaudan leverages its botanical extraction capabilities to anchor supply relationships with Australian dairy processors. Kerry Group competes through its integrated taste and nutrition platform, while dsm-firmenich differentiates via biotechnology-derived flavor molecules.
Food flavors and enhancers comprise volatile aromatic compounds, taste-active molecules, and savory modulators engineered to replicate or intensify sensory profiles in processed foods, typically dosed at parts-per-million to percent-level concentrations depending on application heat stability requirements. Natural extracts lead product type demand as FSANZ labeling transparency pushes manufacturers toward recognizable ingredient declarations, while liquid forms dominate beverage applications due to dispersion efficiency. Snacks represent the fastest-growing application as Australasian producers expand flavored crisp and extruded product lines.
FSANZ governs ingredient safety and labeling standards across both countries, while the Australia New Zealand Food Standards Code mandates additive disclosure thresholds that directly influence formulation choices. TGA oversight of novel food ingredients creates additional compliance layers for enzyme-derived and fermentation-based enhancers. Stakeholders must monitor evolving FSANZ consultation pathways for natural flavor definition revisions that could recategorize extraction methodologies.
Market Dynamics
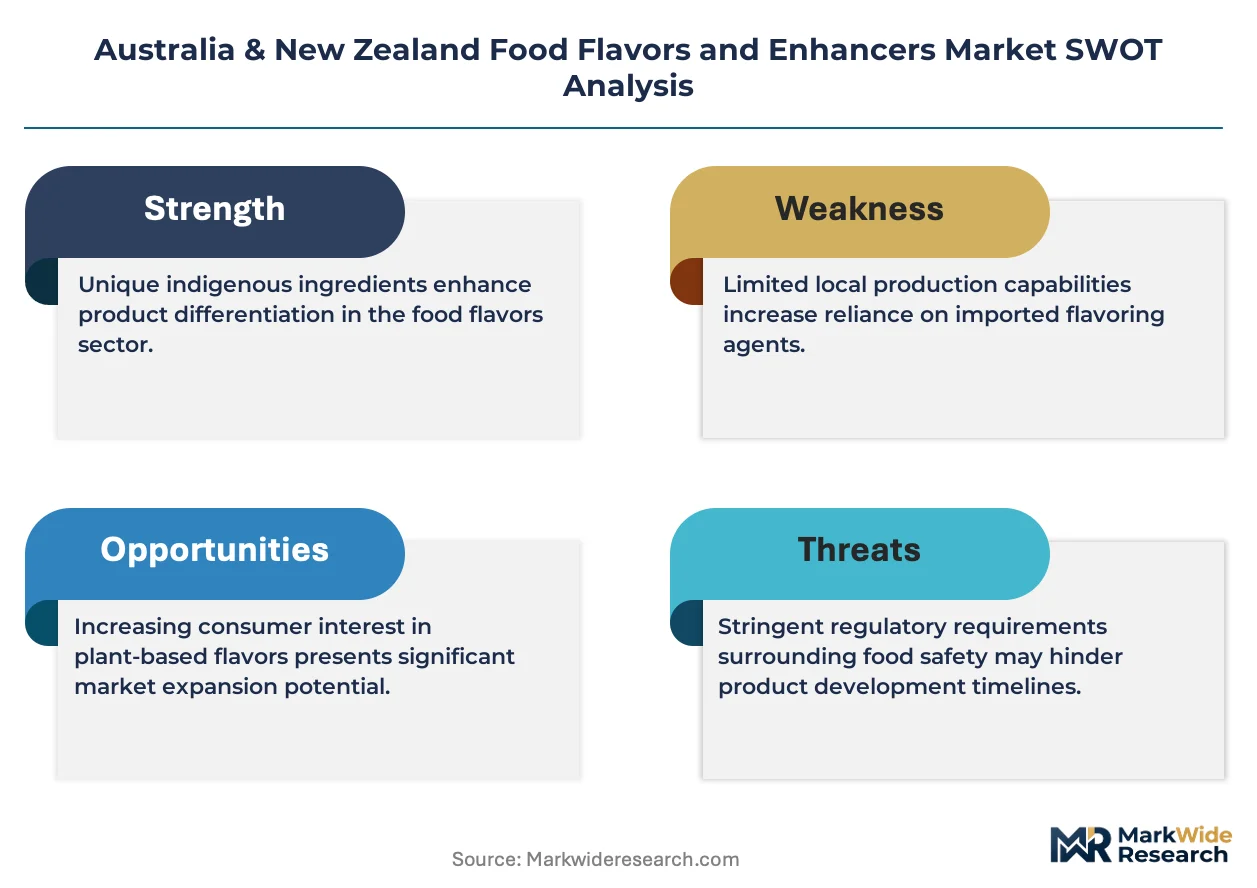
FSANZ disclosure mandates are compressing formulation timelines across Australian and New Zealand food processors, forcing simultaneous reformulation of legacy product lines while scaling clean-label alternatives to maintain shelf positioning.
Growth Catalysts
- New South Wales manufacturing concentration:Sydney's food processing corridor generates concentrated procurement volumes for natural flavor suppliers, with bakery and dairy clusters anchoring regional demand pull.
- FSANZ Code transparency thresholds:Mandated additive disclosure is redirecting R&D budgets toward recognizable ingredient declarations that satisfy retailer and consumer scrutiny.
- Enzymatic extraction methods:Biotechnology-derived flavor molecules are reducing dependency on solvent-based processes while meeting TGA novel food ingredient pathways.
Market Restraints
- Botanical raw material volatility:Australian native extract supply fluctuates with seasonal harvest cycles, compressing margins for natural flavor producers during drought periods.
- Dual jurisdiction compliance:FSANZ and TGA overlapping oversight creates redundant testing requirements for fermentation-derived enhancers entering both food and therapeutic pathways.
- Artificial flavor substitution pressure:Synthetic vanillin and ester compounds face volume displacement as clean-label mandates cascade through retail private-label programs.
Strategic Opportunities
- Victoria specialty dairy expansion:Melbourne's artisan cheese and cultured product segment presents underpenetrated demand for region-specific flavor profiling.
- Extruded snack application growth:Australasian crisp manufacturers are expanding flavored product lines, creating white space for heat-stable savory modulators.
- Liquid flavor dispersion technology:Beverage processors are adopting micro-emulsion systems that improve stability in low-pH functional drinks.
Industry Challenges
- Formulation chemist scarcity:Australia faces limited talent pools for natural extract stability optimization, particularly for heat-processed applications.
- Legacy equipment retrofit costs:Dairy processors must reconfigure mixing systems to handle higher-viscosity natural extracts without capital-intensive line replacements.
- FSANZ consultation timeline uncertainty:Pending natural flavor definition revisions create formulation freeze risks as manufacturers await extraction methodology recategorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia & New Zealand Food Flavors and Enhancers Market |
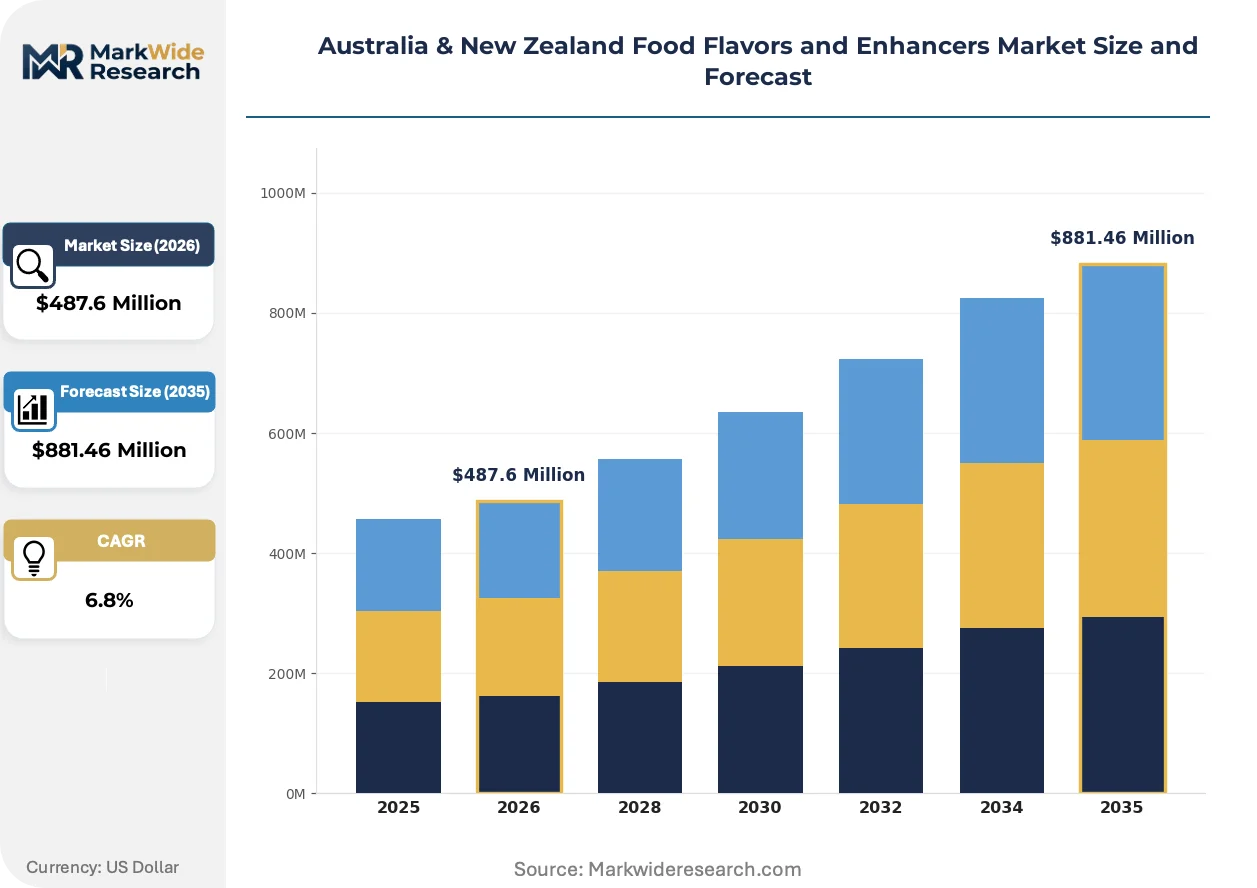
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Extracts, Artificial Flavors, Spices, Seasonings Application: Bakery, Dairy, Beverages, Snacks End User: Food Manufacturers, Restaurants, Retailers, Households Form: Liquid, Powder, Granulated, Paste |
| Companies Covered | Givaudan, International Flavors & Fragrances, Symrise, dsm-firmenich, Kerry Group, Takasago International, Sensient Technologies, Archer Daniels Midland, The Flavor Factory, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia & New Zealand Food Flavors and Enhancers Market Trends and Innovations
Biotechnology and precision fermentation are displacing conventional extraction across Australian flavor supply chains, while regulatory transparency mandates compress product development cycles.
Precision fermentation-derived aromatic compounds is rewriting supply security for heat-sensitive flavor molecules. Australian dairy processors are adopting these inputs at pilot scale ahead of full TGA novel food approvals. The technology is rewriting procurement risk profiles by decoupling flavor supply from agricultural harvest variability.
FSANZ natural flavor definition consultations are forcing preemptive reformulation across bakery and snack segments. Manufacturers are front-loading R&D expenditure to secure compliant ingredient declarations before mandate enforcement tightens. Victorian processors face the steepest compliance curve given their concentration of legacy artificial flavor dependencies.
Direct-procurement relationships between flavor houses and New Zealand dairy cooperatives are displacing traditional distributor intermediaries. Anchor processors are negotiating captive supply agreements for seasonal botanical extracts, compressing spot-market participation. This pattern is most visible across Canterbury's ingredient manufacturing cluster.
Australia & New Zealand Food Flavors and Enhancers Market Segmentation
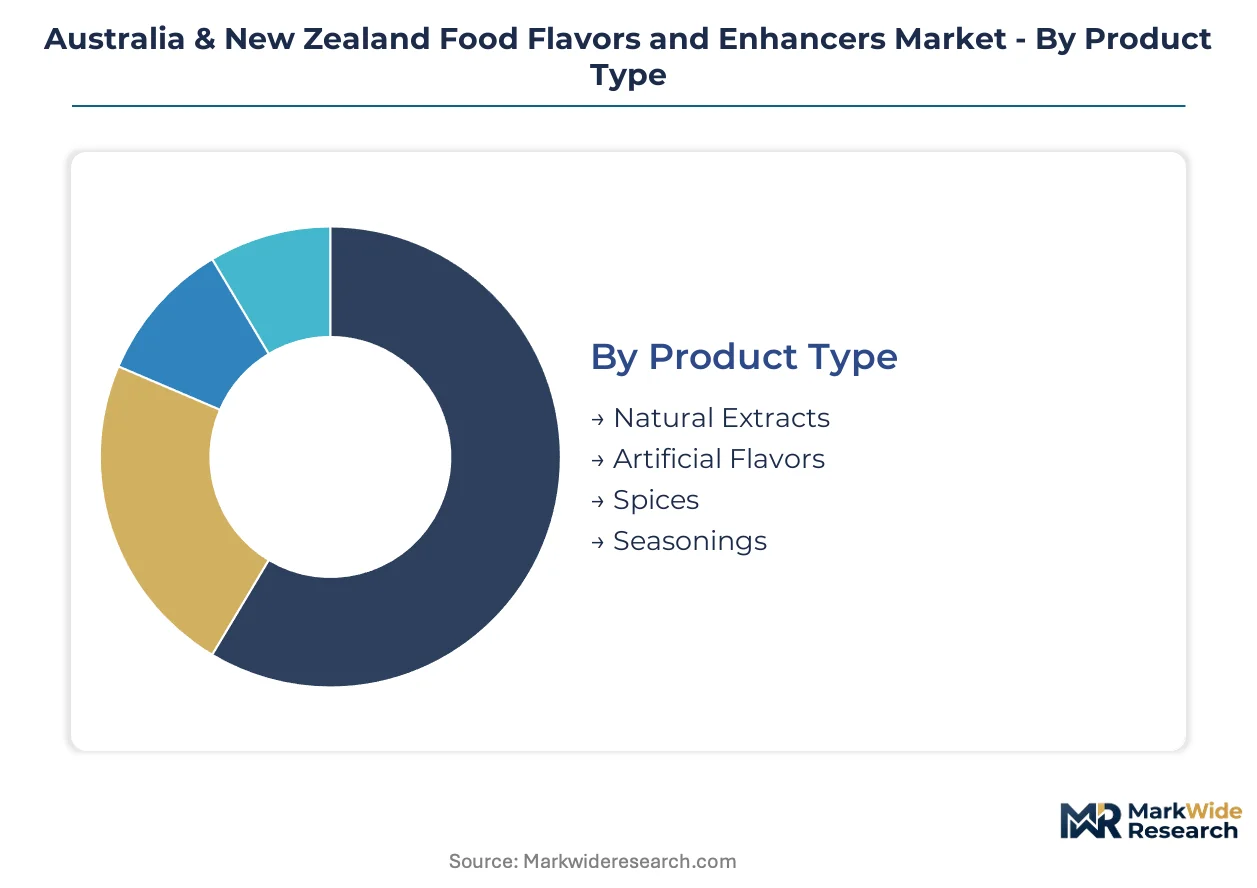
Segmentation in the Australia & New Zealand food flavors and enhancers market reflects divergent compliance burdens across FSANZ disclosure tiers. Procurement patterns cluster around certification intensity, with natural extract categories commanding premium validation workflows while artificial alternatives face substitution pressure.
Product Type:
FSANZ natural flavor definition consultations impose tiered approval burdens: botanical extracts require harvest-to-shelf traceability documentation, while synthetic molecules navigate simpler safety assessments. TGA novel food pathways add complexity for fermentation-derived aromatic compounds.
- Natural Extracts:Volatile aromatic compounds derived from Australian native botanicals and imported plant matter. Demand concentrates in New South Wales dairy processors seeking recognizable ingredient declarations for clean-label positioning. FSANZ transparency mandates compress formulation timelines for these inputs.
- Artificial Flavors:Synthetic esters, aldehydes, and vanillin compounds engineered for cost efficiency and heat stability. Victorian bakery clusters retain volume demand for legacy applications, though retail private-label programs are accelerating displacement. Margin compression intensifies as reformulation budgets redirect toward natural alternatives.
- Spices:Whole and ground botanicals delivering pungency and color functionality.
- Seasonings:Blended savory profiles incorporating salt carriers, yeast extracts, and nucleotide enhancers.
Leading the category by volume: Natural Extracts. Growing fastest: Natural Extracts.
Application:
Heat stability requirements and pH tolerance dictate formulation choices across processing environments, with high-temperature applications demanding specialized encapsulation investments.
- Snacks:Extruded crisp and savory biscuit applications requiring heat-stable savory modulators that survive barrel temperatures above 150°C. Australasian manufacturers expanding flavored product lines in Victoria and Queensland drive procurement pull for encapsulated yeast extracts and nucleotide blends.
- Beverages:Low-pH functional drinks and carbonated soft drinks utilizing liquid flavor micro-emulsions for dispersion efficiency. New South Wales beverage processors adopt advanced emulsion systems to improve stability in acidic formulations.
- Bakery:Yeast-leavened and chemically leavened products incorporating volatile top notes and baked flavor precursors.
- Dairy:Cultured products, ice cream, and processed cheese requiring fat-compatible flavor delivery systems.
Snacks dominate volume contribution. Beverages climb fastest on functional drink expansion.
End User:
Procurement scale and technical capability separate tiers, with integrated manufacturers investing in captive flavor development while smaller operators rely on distributor intermediaries.
- Food Manufacturers:Integrated processors with in-house application laboratories and direct supplier relationships. Sydney and Melbourne manufacturing corridors anchor concentrated procurement volumes for natural extract suppliers, with annual contract structures displacing spot-market participation.
- Restaurants:Commercial kitchens and foodservice chains purchasing bulk seasoning blends and concentrated flavor bases. Queensland tourism corridor drives seasonal demand spikes for standardized taste profiles across multi-site operations.
- Retailers:Private-label program managers specifying clean-label declarations for house-brand snack and dairy lines.
- Households:Consumer-packaged goods purchasers of table sauces, cooking pastes, and retail seasoning sachets.
Food Manufacturers lead procurement volume. Retailers expand fastest on private-label clean-label mandates.
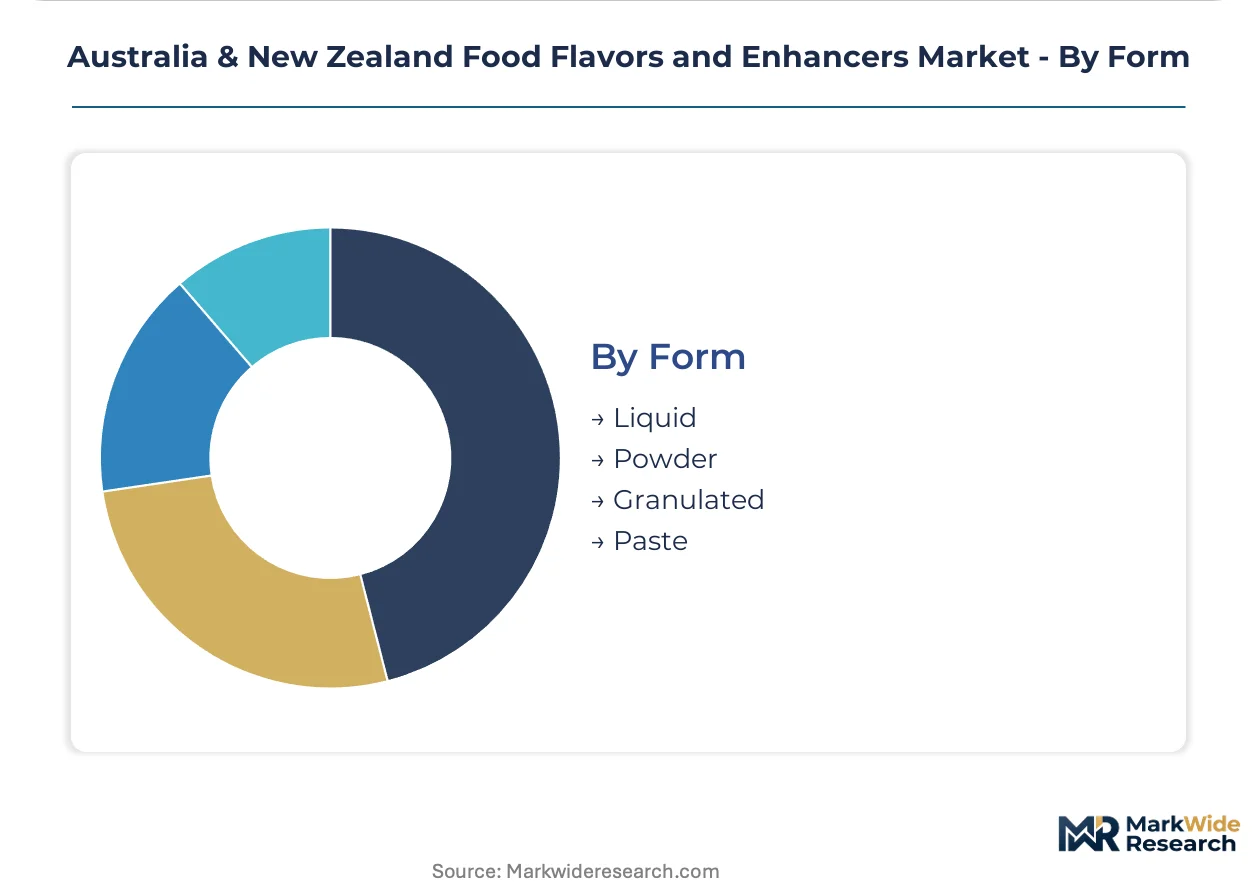
Form:
Physical state determines handling infrastructure requirements, with liquid systems demanding stainless steel containment and powder formats enabling simpler dry-blend integration.
- Liquid:Solvent-based and oil-based concentrates dosed via automated metering systems. Beverage applications in New South Wales and Victoria favor liquid formats for dispersion efficiency in high-speed filling lines.
- Powder:Spray-dried and plated flavor systems compatible with dry-mix processing. Snack seasoning tumble drums across Australasian extrusion facilities prefer powder carriers for uniform adhesion.
- Granulated:Agglomerated particles reducing dust generation during handling.
- Paste:High-viscosity concentrates requiring heated transfer lines and specialized pumping equipment.
Liquid leads by volume. Powder gains fastest on snack expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sydney's food processing corridor generates concentrated procurement volumes for natural flavor suppliers, anchoring Australasia's demand pull. Melbourne's manufacturing clusters and Queensland's tourism-dependent foodservice operations complete the regional demand map.
New South Wales
Bakery and dairy processors in Sydney's western suburbs drive concentrated natural extract procurement. FSANZ disclosure mandates compress formulation timelines for clean-label repositioning. The Parramatta-Rosehill industrial zone hosts captive supply negotiations between flavor houses and integrated food manufacturers.
Victoria
Artisan cheese and cultured product segments in Melbourne's northern suburbs present underpenetrated demand for region-specific flavor profiling. TGA novel food ingredient pathways add compliance layers for fermentation-derived enhancers entering therapeutic adjacent categories. The Laverton-Derrimut corridor anchors extruded snack manufacturing expansion.
Queensland
Tourism corridor foodservice chains generate seasonal demand spikes for standardized taste profiles across multi-site operations. FSANZ Code transparency thresholds redirect procurement toward recognizable ingredient declarations. Brisbane's Archerfield industrial precinct concentrates beverage processing capacity for functional drink micro-emulsion adoption.
Western Australia
Mining camp catering and remote foodservice operations sustain bulk seasoning blend demand despite population dispersion. The country's national food standards regulator maintains equivalent disclosure requirements across all states. Perth's Kewdale industrial zone hosts limited flavor manufacturing, relying on eastern states supply chains.
New Zealand
Canterbury's dairy cooperative processing cluster anchors direct-procurement relationships displacing traditional distributor intermediaries. Anchor processors negotiate captive supply agreements for seasonal botanical extracts. Auckland's food manufacturing corridor concentrates beverage and snack applications with emerging clean-label mandates.
Australia & New Zealand Food Flavors and Enhancers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across extraction methodology and certification intensity. The vendor base organizes into three tiers: integrated taste-nutrition platforms, biotechnology-derived specialists, and regional extraction houses. Consolidation pressure intensifies as clean-label mandates cascade through retail private-label programs. Dominant competitive moves include backward integration into botanical supply chains and strategic partnerships with dairy cooperatives for captive offtake agreements.
Within the integrated platform tier, Kerry Group and dsm-firmenich exemplify scale-driven positioning across taste and nutrition convergence. Givaudan anchors the botanical extraction specialist archetype with Swiss-heritage positioning. These three entities represent the premium-tier competitive set, each occupying distinct vectors: integrated service platforms, biotechnology-derived molecules, and native extract capabilities.
| Leading Market Players |
|---|
| Givaudan |
| International Flavors & Fragrances |
| Symrise |
| dsm-firmenich |
| Kerry Group |
| Takasago International |
| Sensient Technologies |
| Archer Daniels Midland |
| The Flavor Factory |
| Others |
Pricing and Supply Chain Analysis
Integrated food manufacturers in Sydney's Parramatta-Rosehill corridor anchor procurement volumes through annual contract structures that compress spot-market liquidity and concentrate pricing power among certified natural extract suppliers. This buyer concentration enforces value-based pricing tied to FSANZ-compliant ingredient declarations rather than commodity spot benchmarks.
Pricing Analysis
Value-based pricing tied to clean-label certification outcomes dominates as FSANZ transparency mandates recalibrate procurement priorities toward recognizable ingredient declarations. Price differentiation separates botanical extraction grade from fermentation-derived molecule purity tiers, with TGA novel food pathway validation commanding additional premiums. Cost compression in artificial flavor tiers is intensifying as retail private-label programs accelerate substitution toward natural alternatives. Small-scale Victorian artisan processors exhibit highest price sensitivity, while New South Wales dairy integrators prioritize certification reliability over unit cost.
Supply Chain Analysis
Workforce scarcity for natural extract stability optimization in New South Wales and Victoria constrains processing capacity expansion and extends lead times for heat-stable formulation development. Supply concentrates in Australian native botanical harvest zones and New Zealand Canterbury dairy cooperative networks, with both regions drawing from seasonal agricultural cycles. Raw material dependencies include Australian native plant matter, imported vanilla and citrus extracts, and fermentation feedstocks. Single-source vulnerability runs through drought-exposed native extract harvests. Distribution runs through direct-procurement agreements displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where FSANZ disclosure mandates erect barrier-to-entry moats favoring incumbent players with validated traceability infrastructure and established TGA consultation pathways.
For Market Incumbents: Lock in captive supply agreements with Canterbury dairy cooperatives and New South Wales bakery clusters before pending natural flavor definition revisions recategorize extraction methodologies. Deepen backward integration into Australian native botanical cultivation to insulate margin structures from drought-driven raw material volatility. Priority lever: enzymatic extraction capacity expansion ahead of TGA novel food approval finalization. For New Entrants and Emerging Players: Begin with Victoria's artisan cheese and cultured product segments where region-specific flavor profiling demand remains underpenetrated by integrated taste-nutrition platforms. Target precision fermentation-derived aromatic compounds for heat-sensitive applications where incumbent botanical extraction capabilities face technical constraints. Go-to-market angle: pilot-scale partnerships with Melbourne's Laverton-Derrimut extruded snack manufacturers seeking heat-stable savory modulators. For Investors and Strategic Acquirers: The window for entry favors biotechnology-derived flavor specialists with TGA novel food pathway progress and established precision fermentation infrastructure. Long-term viability hinges on regulatory compliance scalability rather than commodity volume positioning. Acquisition target archetype: regional extraction houses with validated Australian native botanical supply relationships. Signal to watch: FSANZ consultation outcome on extraction methodology recategorization as inflection indicator for natural flavor definition enforcement timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Native Botanical Cultivation | Captive supply of Australian native extracts insulates margins from drought-driven harvest volatility. |
| Precision Fermentation Capacity Buildout | Biotechnology-derived molecules reduce dependency on solvent-based extraction while awaiting TGA approvals. |
| Direct-Procurement Agreement with Dairy Cooperatives | Canterbury anchor processors negotiate seasonal botanical extract offtake, compressing spot-market participation. |
| FSANZ Compliance Certification Investment | Harvest-to-shelf traceability documentation secures shelf positioning under tightening disclosure mandates. |
| Liquid Flavor Micro-Emulsion Technology Partnership | New South Wales beverage processors adopt advanced dispersion systems for low-pH functional drink stability. |
Research Methodology
Independent corroboration across formulation chemists at integrated food manufacturers, procurement leads at New South Wales dairy processors, regulatory affairs specialists navigating FSANZ consultation pathways, and TGA novel food assessment officers underwrites the qualitative findings. Secondary validation draws from FSANZ consultation documents, Australia New Zealand Food Standards Code amendments, TGA novel food ingredient guidelines, and trade data on botanical extract imports. Bottom-up procurement volume estimates triangulate against top-down market sizing derived from manufacturing cluster concentration analysis.
Rate-of-change decomposition separates volume growth drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type tier, application heat stability requirements, end-user procurement scale, and physical form handling infrastructure. CAGRs were derived from trend-line analysis of disclosed manufacturing capacity expansions and contract procurement patterns. Industry-specific forecast inputs incorporate FSANZ regulatory timeline assumptions and TGA approval pathway probability weightings.
Regulatory consultation delays, drought severity in Australian native botanical harvest zones, and precision fermentation scale-up failures are the dominant revision risks. Forecasts reflect documented assumptions regarding FSANZ mandate enforcement timing and TGA novel food pathway throughput rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Dough Conditioners Market
Food Enhancers and Additives
Resveratrol Market
Food Enhancers and Additives
Lignans Market
Food Enhancers and Additives
India Food Flavor and Enhancer Market
Food Enhancers and Additives
Brazzein Market
Food Enhancers and Additives
Europe Water Enhancer Market
Food Enhancers and Additives
Gut Modifiers Market
Food Enhancers and Additives
Charcoal-Infused Food Market
Food Enhancers and Additives
Asia-Pacific Food Stabilizers Market
Food Enhancers and Additives
Spain Food Flavor and Enhancer Market
Food Enhancers and Additives
Used Cooking Oil Market
Food Enhancers and Additives
Food Raising Agents Market
Food Enhancers and Additives
Dysphagia Diet Thickening Market
Food Enhancers and Additives
North America Food Thickeners Market
Food Enhancers and Additives
Instant Whipping Agents Market
Food Enhancers and Additives
Asia-Pacific Food Flavor and Enhancer Market