
 Carvone Market | 2026-2036
Carvone Market Size, Share, and Industry Trends Forecast 2026-2036
Carvone Market Intelligence
Flavor and fragrance applications is consolidating as the dominant demand vertical for carvone, displacing slower-growing industrial uses. Paramount Aromachem leverages its specialized distillation infrastructure to anchor supply for premium natural grades. Renessenz competes through synthetic route efficiency, while Symrise differentiates via integrated flavor compound portfolios that embed carvone into finished formulations.
Carvone is a monoterpene ketone with the molecular formula C10H14O, occurring naturally in spearmint oil or produced synthetically from d-limonene through selective oxidation processes; it functions primarily as a flavoring agent, fragrance ingredient, and chiral building block in pharmaceutical synthesis. Natural carvone occupies the premium tier due to clean-label preferences and EU organic certification requirements, whereas synthetic carvone captures volume in cost-sensitive household product applications. The food and beverage segment leads absolute consumption, while pharmaceuticals represents the fastest-growing application as chiral purity standards tighten for active pharmaceutical ingredient precursors.
REACH registration requirements in Europe, FDA food additive regulations in the United States, and FSSAI flavoring substance standards in India collectively elevate compliance costs and screen out non-specialized suppliers. These frameworks push manufacturers toward documented supply chain traceability and certified analytical testing protocols. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation mandates and qualification timelines.
Market Dynamics
REACH registration deadlines and FDA food additive purity mandates are compressing the supplier base, forcing documented traceability and certified analytical testing protocols across the Carvone Market.
Growth Catalysts
- Clean-label food formulations:EU organic certification requirements and consumer preference for natural flavoring agents are pulling premium-grade carvone into beverage and confectionery applications.
- REACH compliance deadlines:European chemical registration requirements are screening out non-specialized suppliers, consolidating volume with documented supply chain operators.
- Chiral pharmaceutical synthesis:Tightening purity standards for active pharmaceutical ingredient precursors are accelerating demand for high-enantiomeric-grade carvone in drug manufacturing.
Market Restraints
- Spearmint oil feedstock volatility:Weather-dependent agricultural yields in India and China create input cost instability for natural carvone extraction.
- Synthetic route energy intensity:Selective oxidation of d-limonene requires controlled thermal processing, elevating utility costs relative to other aroma chemicals.
- Regulatory divergence friction:Misaligned FSSAI flavoring substance standards in India with EU REACH specifications forces dual qualification costs for exporters.
Strategic Opportunities
- Pharmaceutical chiral building blocks:Underpenetrated demand for enantiopure carvone in antipodal drug synthesis offers margin expansion beyond commodity flavor grades.
- Bio-based oxidation catalysts:Convergence of enzymatic catalysis with continuous flow processing is opening synthetic routes with lower carbon intensity credentials.
- Direct-to-compounder distribution:Bypassing traditional aroma chemical traders through digital procurement platforms is compressing lead times for mid-sized flavor houses.
Industry Challenges
- Analytical chemistry talent scarcity:Enantiomeric purity verification and contaminant profiling require specialized chromatography expertise that outpaces training pipeline output.
- Multi-jurisdiction certification timelines:Parallel FSSAI, FDA, and REACH qualification processes extend product launch cycles by 18-24 months for new suppliers.
- Legacy batch reactor retrofit costs:Continuous processing adoption demands capital redeployment that strains mid-scale distillation operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carvone Market |
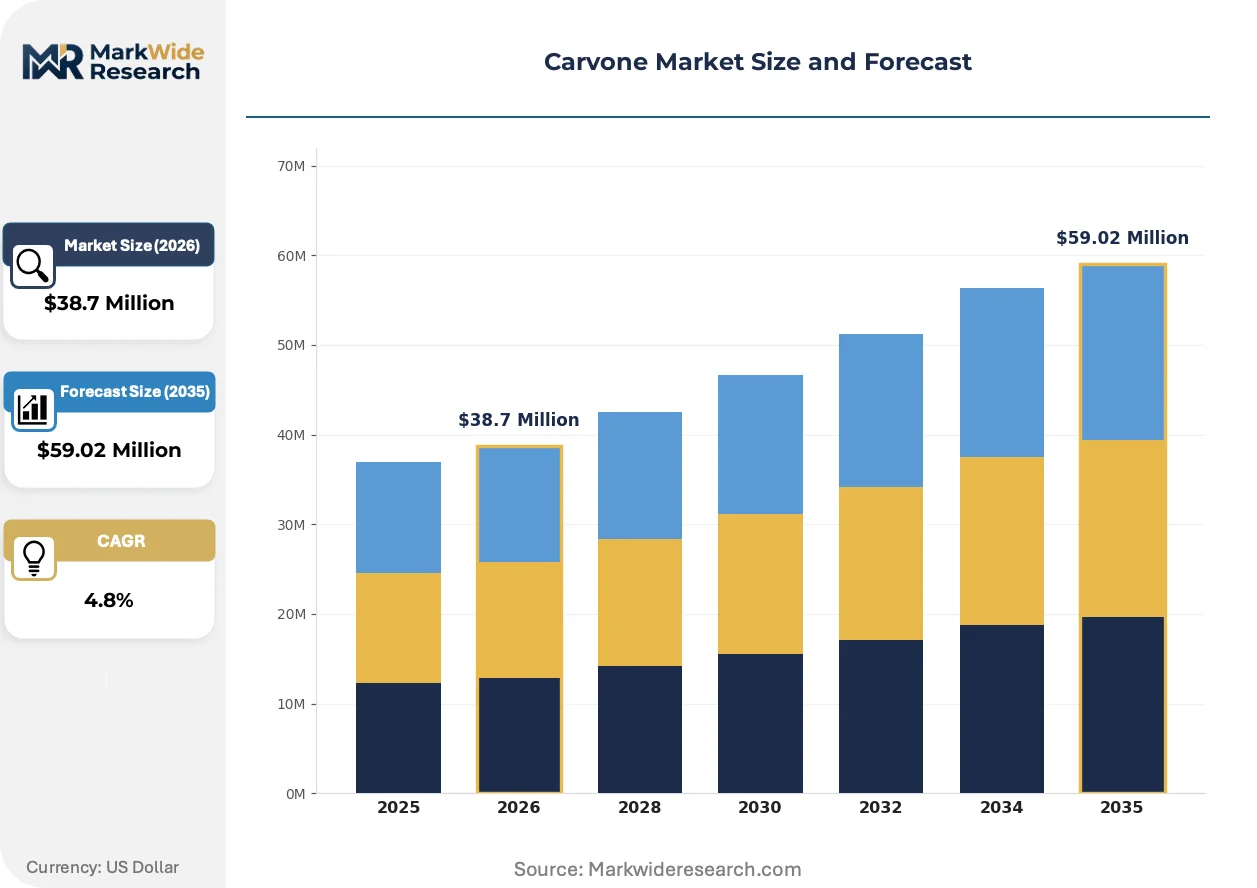
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $59.02 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Carvone, Synthetic Carvone, Flavoring Agents, Fragrance Components Application: Food & Beverage, Pharmaceuticals, Cosmetics, Household Products End User: Manufacturers, Retailers, Wholesalers, Distributors Packaging Type: Glass Bottles, Plastic Containers, Drums, Sachets |
| Companies Covered | Paramount Aromachem, Renessenz, Wanxiang International, Gem Aromatics, Shree Bankey Behari Lal Aromatics, Jishui County Shunmin Medicinal, Symrise, Vigon International, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carvone Market Strategic Shifts & Innovations
Enzymatic catalysis and continuous flow chemistry are rewriting process economics, while regulatory data requirements and shifting procurement models are redrawing competitive boundaries across supply tiers.
Continuous flow oxidation technology is integrating selective transformation of d-limonene into synthetic carvone with tighter temperature control and reduced solvent volumes. Specialty chemical manufacturers in Germany and the Netherlands are adopting these systems to meet EU Green Deal carbon intensity benchmarks. The technology is integrating synthetic production into premium-grade supply chains previously reserved for natural extraction.
REACH Article 33 extended SCIP database obligations now require disclosure of carvone-containing articles throughout the supply chain, elevating documentation burdens for fragrance compounders. ECHA enforcement is tightening analytical test method harmonization across member states. Small-scale Indian exporters face particular strain in aligning with these protocols, accelerating partnerships with EU-registered laboratories.
Flavor house procurement teams are consolidating supplier panels and demanding fixed-price contracts with volume commitments to hedge agricultural feedstock volatility. This concentration is squeezing trading intermediaries and favoring integrated producers with captive spearmint oil processing or synthetic manufacturing assets. The shift is most pronounced in North American beverage and oral care formulations, where reformulation cycles have compressed from annual to semi-annual intervals.
Carvone Market Segmentation
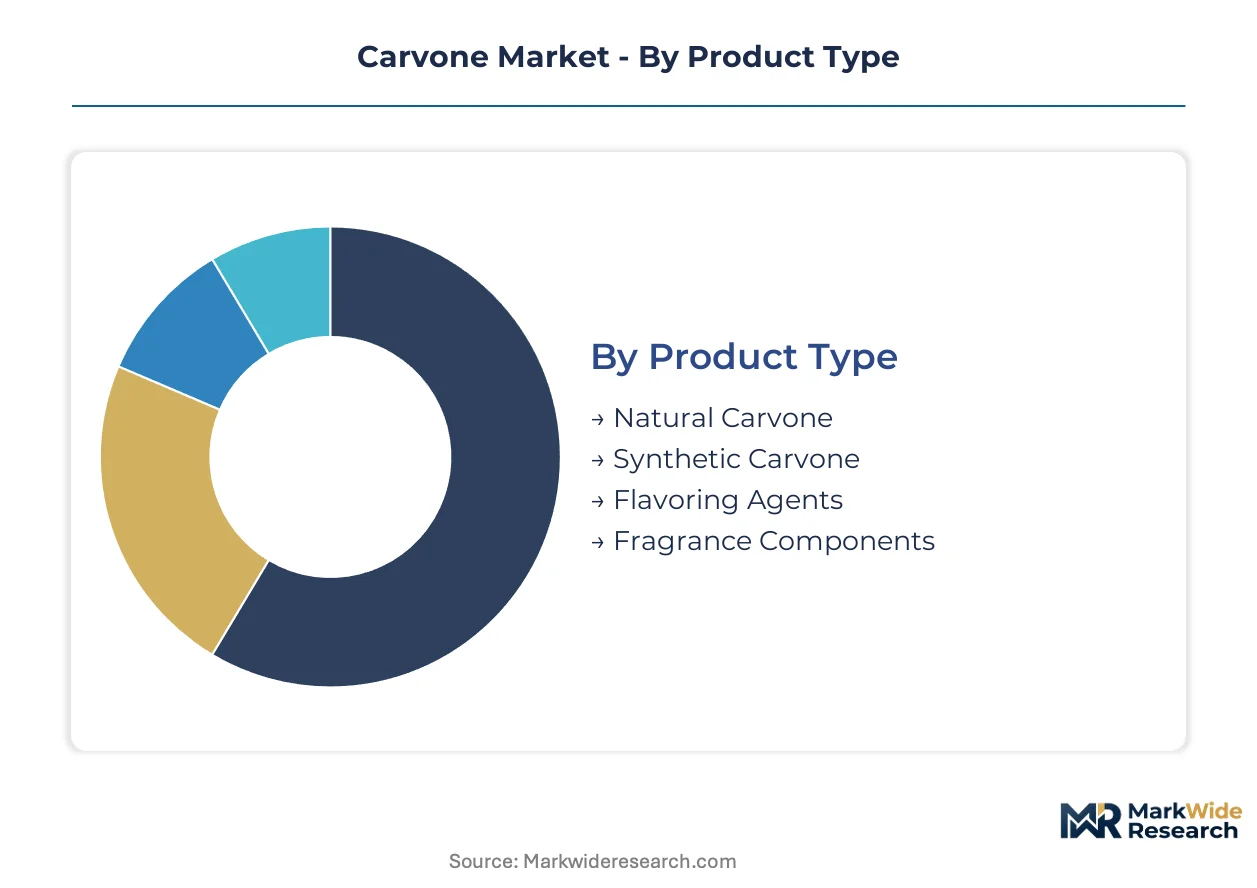
Carvone procurement decisions hinge on purity certification, chiral specifications, and regulatory alignment across multiple jurisdictions. Segmentation reveals how buyers trade off natural-origin premiums against synthetic cost efficiency, while application-specific purity tiers fragment supplier targeting strategies.
Product Type:
Buyers select product grades based on label-positioning requirements and end-market regulatory thresholds, with natural-origin commanding substantial premiums in EU organic formulations.
- Natural Carvone:Extracted from spearmint oil through fractional distillation, this grade carries EU organic certification and clean-label credentials essential for premium beverage and confectionery applications in Germany and France. Demand concentrates in flavor houses serving organic-certified product lines where REACH documentation and traceability mandates screen out non-compliant suppliers.
- Synthetic Carvone:Manufactured via selective oxidation of d-limonene, synthetic grades offer batch-to-batch consistency and lower unit economics for high-volume household product formulations. Volume concentrates in cost-sensitive oral care and air freshener applications across North American private-label manufacturers.
- Flavoring Agents:Compounded carvone preparations blended with carrier solvents or co-flavorants for direct manufacturing integration.
- Fragrance Components:Purified carvone fractions formulated into fine fragrance and functional perfume bases.
Natural Carvone leads on scale; Synthetic Carvone leads on momentum.
Application:
Application selection determines purity thresholds, with pharmaceutical synthesis imposing the most stringent enantiomeric specifications.
- Food & Beverage:The largest consumption channel, spanning chewing gum, mint-flavored beverages, and confectionery. FDA food additive standards and FSSAI flavoring substance requirements in India create dual-qualification burdens for exporters serving multiple markets simultaneously.
- Pharmaceuticals:Chiral carvone serves as a building block for antipodal drug synthesis, with tightening purity standards for active pharmaceutical ingredient precursors. Demand climbs fastest in contract manufacturing organizations serving innovator drug portfolios.
- Cosmetics:Fragrance and personal care applications utilize carvone in toothpaste, mouthwash, and skincare formulations.
- Household Products:Air fresheners, cleaning agents, and insect repellents incorporate lower-purity grades where cost dominates specification.
Food & Beverage dominates absolute volume; Pharmaceuticals shows steepest expansion trajectory.
End User:
Channel structure reflects procurement sophistication, with direct manufacturer relationships displacing intermediary trading for volume accounts.
- Manufacturers:Integrated flavor houses, pharmaceutical compounders, and consumer product formulators purchasing bulk quantities under fixed-price contracts with volume commitments.
- Retailers:Specialty chemical distributors and ingredient supermarkets serving small-batch formulators and regional product developers.
- Wholesalers:Traditional aroma chemical traders consolidating fragmented supply for mid-tier compounders.
- Distributors:Logistics-focused intermediaries managing inventory and customs clearance for cross-border procurement.
Manufacturers lead on scale; Retailers lead on momentum.
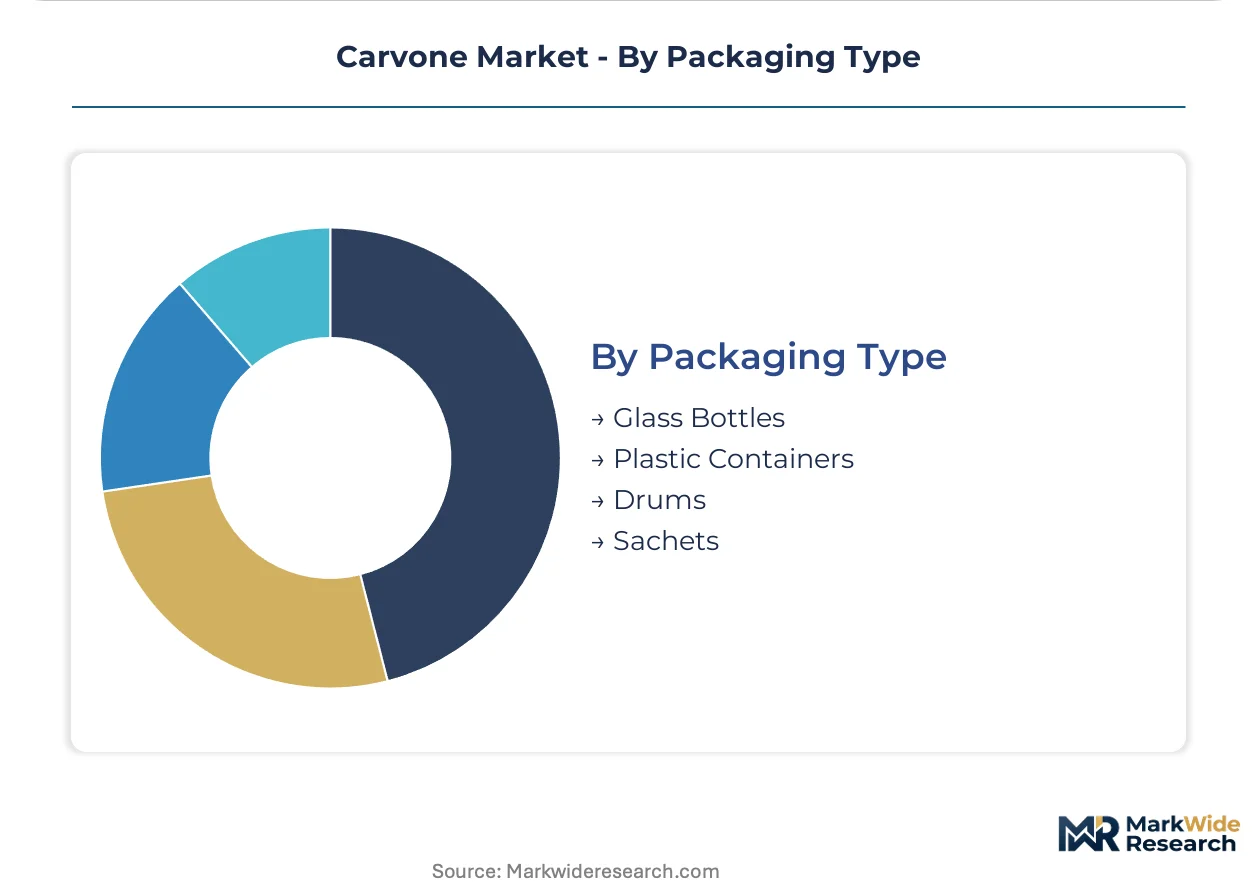
Packaging Type:
Packaging selection balances contamination risk, handling efficiency, and regulatory documentation requirements for hazardous material transport.
- Glass Bottles:Preferred for high-purity pharmaceutical and premium fragrance grades where inert containment prevents degradation. Glass dominates small-lot shipments to analytical laboratories and specialty compounders.
- Plastic Containers:HDPE and fluoropolymer vessels serve mid-volume flavor and cosmetic applications where cost and weight reduction outweigh premium material costs.
- Drums:Standard 200-liter steel and fiber drums handle bulk industrial shipments for household product manufacturing.
- Sachets:Single-use foil and laminate pouches support sample distribution and just-in-time formulation trials.
Drums lead on scale; Glass Bottles lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting carvone production toward jurisdictions where REACH-equivalent compliance costs remain lower, even as EU documentation mandates tighten traceability standards for importers. India and China absorb volume migration from European synthetic producers, while Germany and the United States anchor premium-grade extraction and pharmaceutical-grade purification.
India
Domestic essential oil processing clusters in Uttar Pradesh and Madhya Pradesh supply bulk natural carvone to flavor houses serving FSSAI-compliant formulations. The country's national food safety regulator mandates contaminant thresholds that align partially with EU specifications, creating dual-qualification pathways for export-oriented aroma chemical units. Kanpur and Kannauj distillation belts are scaling fractional distillation capacity to meet European organic certification demand.
Germany
Specialty chemical manufacturers in North Rhine-Westphalia adopt continuous flow oxidation systems to produce synthetic carvone meeting EU Green Deal carbon intensity benchmarks. ECHA enforcement of REACH Article 33 SCIP database obligations elevates documentation burdens for fragrance compounders using imported material. Leverkusen and Düsseldorf industrial corridors integrate enzymatic catalysis into premium-grade supply chains.
United States
Flavor houses in New Jersey and Illinois consolidate supplier panels under fixed-price contracts to hedge spearmint oil feedstock volatility. FDA food additive purity mandates for chewing gum and beverage applications compress reformulation cycles to semi-annual intervals. Chicago-area pharmaceutical compounders source high-enantiomeric-grade carvone for chiral building block synthesis under cGMP protocols.
China
Selective oxidation facilities in Jiangsu and Zhejiang provinces manufacture synthetic carvone from d-limonene feedstock for cost-sensitive household product exporters. The national chemical safety administration enforces contaminant profiling standards that diverge from REACH test method harmonization, forcing parallel laboratory qualification. Nantong aroma chemical parks are retrofitting batch reactors with continuous processing infrastructure.
Netherlands
Rotterdam logistics hubs manage customs clearance and inventory positioning for Indian natural carvone entering EU distribution channels. The national environmental agency enforces REACH implementation with stricter enforcement timelines than southern member states, screening out non-registered suppliers. Amsterdam-region flavor compounders demand certified analytical testing protocols for enantiomeric purity verification.
Carvone Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated aroma chemical houses capturing volume in food and beverage while pharmaceutical-grade purifiers anchor high-margin chiral synthesis. The supplier base compresses into three tiers: multinational flavor houses with captive extraction assets, mid-scale Indian distillers serving export markets, and synthetic specialists leveraging continuous flow technology. Consolidation pressures favor backward integration into spearmint oil processing and strategic partnerships with EU-registered analytical laboratories.
Among integrated flavor and fragrance conglomerates, Symrise represents the portfolio-diversified archetype, embedding carvone into finished formulations rather than selling commodity grades. Paramount Aromachem and Renessenz occupy distinct production-technology positions, with the former exemplifying specialized distillation infrastructure for natural grades and the latter representing synthetic route efficiency through selective oxidation. These three anchors illustrate how competitive positioning fragments across natural-origin premiums, synthetic cost leadership, and integrated formulation value capture.
| Leading Market Players |
|---|
| Paramount Aromachem |
| Renessenz |
| Wanxiang International |
| Gem Aromatics |
| Shree Bankey Behari Lal Aromatics |
| Jishui County Shunmin Medicinal |
| Symrise |
| Vigon International |
| BASF |
| Others |
Cost & Logistics Intelligence
Spearmint oil feedstock costs from Uttar Pradesh and Madhya Pradesh processing clusters cascade through natural carvone pricing tiers, with EU organic certification premiums widening spreads between certified and uncertified grades. Synthetic carvone manufactured via d-limonene oxidation in Jiangsu and Zhejiang provinces anchors the economy tier through lower unit economics, while REACH compliance documentation costs concentrate margin pressure on Indian exporters serving European flavor houses.
Pricing Analysis
Distributor margins compress as direct-to-manufacturer procurement platforms displace traditional aroma chemical traders. Three-tier pricing structure across premium natural, standard synthetic, and economy industrial grades separates EU-certified organic extracts from uncertified Indian distillations and bulk household product formulations. Price differentiation hinges on enantiomeric purity certification and FSSAI-REACH dual-qualification status. Pricing pressure stems from spearmint oil yield volatility and energy-intensive selective oxidation processing. Small-batch pharmaceutical compounders show least price sensitivity; private-label oral care manufacturers exhibit highest elasticity.
Supply Chain Analysis
Direct-to-compounder digital procurement channels handle mid-sized flavor house demand, while traditional distributors manage customs clearance for cross-border shipments. Geographic supply concentration centers on India for natural extraction, China for synthetic oxidation, and Germany for continuous flow pharmaceutical-grade production. Raw material dependencies include spearmint oil agricultural yields, d-limonene feedstock from citrus processing, and specialized chromatography resins for purity verification. Single-source vulnerability runs through Indian monsoon-dependent spearmint harvests. Distribution runs through Rotterdam logistics hubs for EU-bound Indian natural grades and Nantong aroma chemical parks for cost-sensitive synthetic volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge where FSSAI flavoring substance standards in India diverge from REACH Article 33 documentation burdens in Europe, creating cost differentials for exporters with dual-qualification capabilities.
For Market Incumbents: Lock in spearmint oil processing capacity through backward integration into Uttar Pradesh and Kannauj distillation belts before feedstock volatility intensifies. Secure EU-registered laboratory partnerships to deflect ECHA enforcement pressure on SCIP database compliance. Prioritize continuous flow oxidation retrofitting to meet EU Green Deal carbon intensity benchmarks and displace batch reactor competitors. For New Entrants and Emerging Players: Mid-tier pharmaceutical contract manufacturing organizations represent the most penetrable buyer archetype, with tightening chiral purity standards for active pharmaceutical ingredient precursors creating qualification gaps. Target enantiopure carvone supply for antipodal drug synthesis where incumbent synthetic producers lack pharmaceutical-grade certification. Deploy bio-based oxidation catalyst partnerships as a sustainability-led go-to-market wedge against legacy thermal processing suppliers. For Investors and Strategic Acquirers: Consolidation pressure builds where analytical chemistry talent scarcity intersects with multi-jurisdiction certification timeline extension, favoring acquirers with in-house chromatography expertise. Mid-scale Indian distillers with fractional distillation infrastructure and emerging EU organic certification represent prime acquisition targets. Watch enzymatic catalysis adoption rates in German and Dutch synthetic facilities as inflection signals for carbon-intensity-driven supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spearmint Processing | Captive supply from Uttar Pradesh clusters hedges agricultural yield volatility for natural grade producers. |
| Continuous Flow Oxidation Retrofit | German specialty chemical manufacturers adopt tighter temperature control to meet EU Green Deal benchmarks. |
| EU-Registered Laboratory Partnership | Indian exporters align with ECHA SCIP database protocols to maintain European market access. |
| Enzymatic Catalysis Development | Bio-based synthetic routes open premium-grade supply chains previously reserved for natural extraction. |
| Direct-to-Compounder Digital Platform | Mid-sized flavor houses compress lead times by bypassing traditional aroma chemical trading intermediaries. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with plant managers at Indian distillation facilities, procurement leads at European flavor houses, distribution channel partners in Rotterdam logistics hubs, and technical R&D directors at German synthetic producers. Secondary validation drew from customs and trade data, ECHA registration databases, FSSAI flavoring substance notifications, and SEC filings of listed aroma chemical conglomerates. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates across natural and synthetic supply tiers.
Historical reference periods anchored the projection horizon to observed capacity utilization rates, feedstock cost trajectories, and regulatory implementation timelines. Segmentation dimensions modeled include product grade tier, end-use application, packaging format, and regional production hub classification. CAGRs were derived from slope analysis of fitted trend lines across the modeling period. Industry-specific forecast inputs incorporated spearmint oil yield correlations with monsoon indices and pharmaceutical chiral purity standard evolution timelines.
Underlying measurement precision varies by segment; pharmaceutical-grade enantiomeric purity specifications carry tighter precision than household product industrial grades due to analytical method standardization. Forecasts reflect base assumptions regarding REACH enforcement continuity, FSSAI-EU specification alignment trajectories, and energy cost normalization for selective oxidation processing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Blueberry Extract Market
Flavorings and Food Additives
Flavor Compounds Market
Flavorings and Food Additives
Beef Flavors Market
Flavorings and Food Additives
United States Food Colorants Market
Flavorings and Food Additives
Maple Extracts Market
Flavorings and Food Additives
Flavor Oil Market
Flavorings and Food Additives
United States Food Flavor Market
Flavorings and Food Additives
Ginkgo Biloba Extract Market
Flavorings and Food Additives
Food Flavors & Flavor Enhancers Market
Flavorings and Food Additives
Marshmallow Root Extract Market
Flavorings and Food Additives
Chocolate Flavoring Compounds Market
Flavorings and Food Additives
Flavanones Market
Flavorings and Food Additives
Mexico Food Colorants Market
Flavorings and Food Additives
North America Food Colorants Market
Flavorings and Food Additives
Japan Food Flavor and Enhancer Market
Flavorings and Food Additives
Citrus Flavonoid Complexes from Mediterranean Peels Market