
 Middle East and Africa Flavors and Fragrances Market | 2026-2036
Middle East and Africa Flavors and Fragrances Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Flavors and Fragrances Market Foresight
Direct sales channels in the Middle East and Africa Flavors and Fragrances Market is fragmenting as multinational suppliers and regional distributors compete for access to cosmetic companies and beverage producers. Givaudan SA leverages its Swiss technical heritage to anchor premium fragrance development for Gulf luxury brands. Aromatic Flavours and Fragrances S.A.E. specializes in locally sourced botanical extracts for Egyptian food manufacturers seeking authentic regional taste profiles. Sensient Technologies Corporation competes on color-flavor integration systems that simplify formulation for personal care clients.
The Middle East and Africa flavors and fragrances sector comprises volatile aromatic compounds, essential oil distillates, and synthetic aroma molecules formulated at concentrations ranging from 0.01% to 20% depending on application intensity, serving primarily to enhance sensory appeal and brand differentiation in consumer products. Natural flavors and essential oils command premium positioning among Gulf cosmetic companies targeting halal-certified and clean-label positioning, while synthetic flavors sustain volume leadership in mass-market beverage applications across North Africa where cost efficiency governs procurement decisions. Aroma chemicals represent the fastest-expanding product category as regional manufacturers backward-integrate into captive production of key synthetic building blocks.
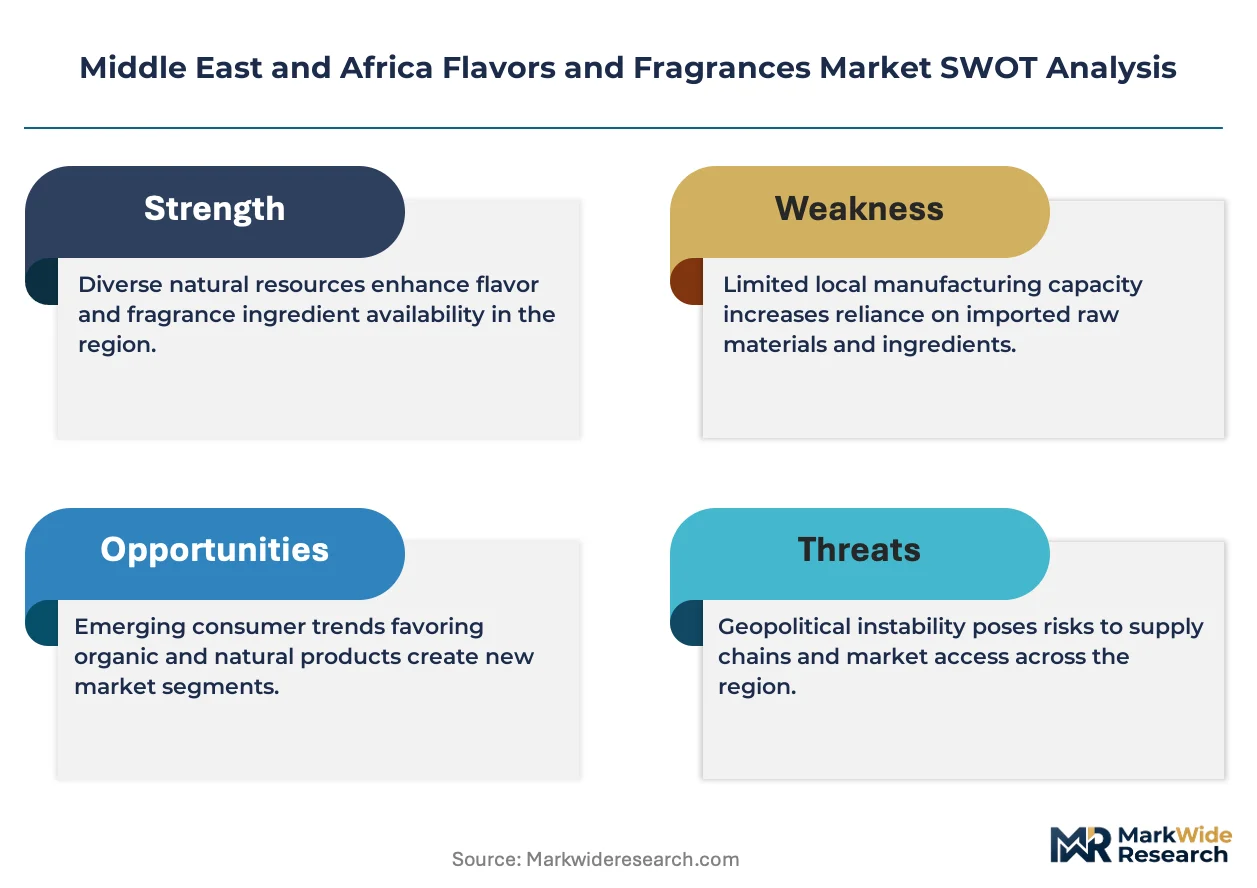
SFDA in Saudi Arabia and MOHAP in the UAE enforce fragrance allergen labeling and ingredient disclosure rules that elevate compliance costs for importers while creating technical barriers for unqualified suppliers. Egypt's CDSCO-aligned cosmetic safety assessments and South Africa's SABS standards for food-grade flavor additives further fragment regulatory requirements across the region. Stakeholders must monitor divergence between Gulf harmonization initiatives and sub-Saharan national standards when structuring regional supply architectures.
Market Dynamics
REACH-aligned chemical safety standards from the EU Green Deal are reshaping import compliance across North African trade corridors, forcing reformulation investments and supplier qualification protocols that favor capitalized multinationals over regional traders.
Growth Catalysts
- Halal certification mandates:Gulf cosmetic regulators now require halal-compliant fragrance sourcing, opening dedicated production lines for certified manufacturers.
- Oud and amber portfolio expansion:Premium personal care brands across Saudi Arabia and the UAE are doubling fragrance SKUs built on indigenous aromatic profiles.
- Captive aroma chemical production:Regional manufacturers are backward-integrating into synthetic building blocks to reduce import dependency.
Market Restraints
- Essential oil price volatility:Climate-driven harvest variability in Moroccan rose and Somali frankincense regions compresses margin predictability for natural extract suppliers.
- Regulatory fragmentation:Divergent SFDA, MOHAP, and SABS standards force parallel compliance architectures that inflate fixed costs.
- Synthetic substitution pressure:Lab-grown aroma molecules from Asian producers undercut botanical extracts on cost in mass-market beverage applications.
Strategic Opportunities
- Egyptian CDSCO-aligned export hub:Cairo-based flavor houses can leverage mutual recognition agreements to access sub-Saharan African markets with reduced retesting burdens.
- Clean-label positioning:Natural flavor demand from South African food processors creates premium tier expansion for certified organic suppliers.
- Direct-to-manufacturer digital platforms:B2B procurement portals are disintermediating traditional distributor networks in Nigeria's beverage sector.
Industry Challenges
- Specialized formulation chemist scarcity:Gulf fragrance houses face recruitment gaps for perfumers trained in both synthetic chemistry and regional olfactory traditions.
- Multi-jurisdiction allergen labeling:SFDA and MOHAP disclosure requirements demand SKU-specific packaging runs that fragment production economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Flavors and Fragrances Market |
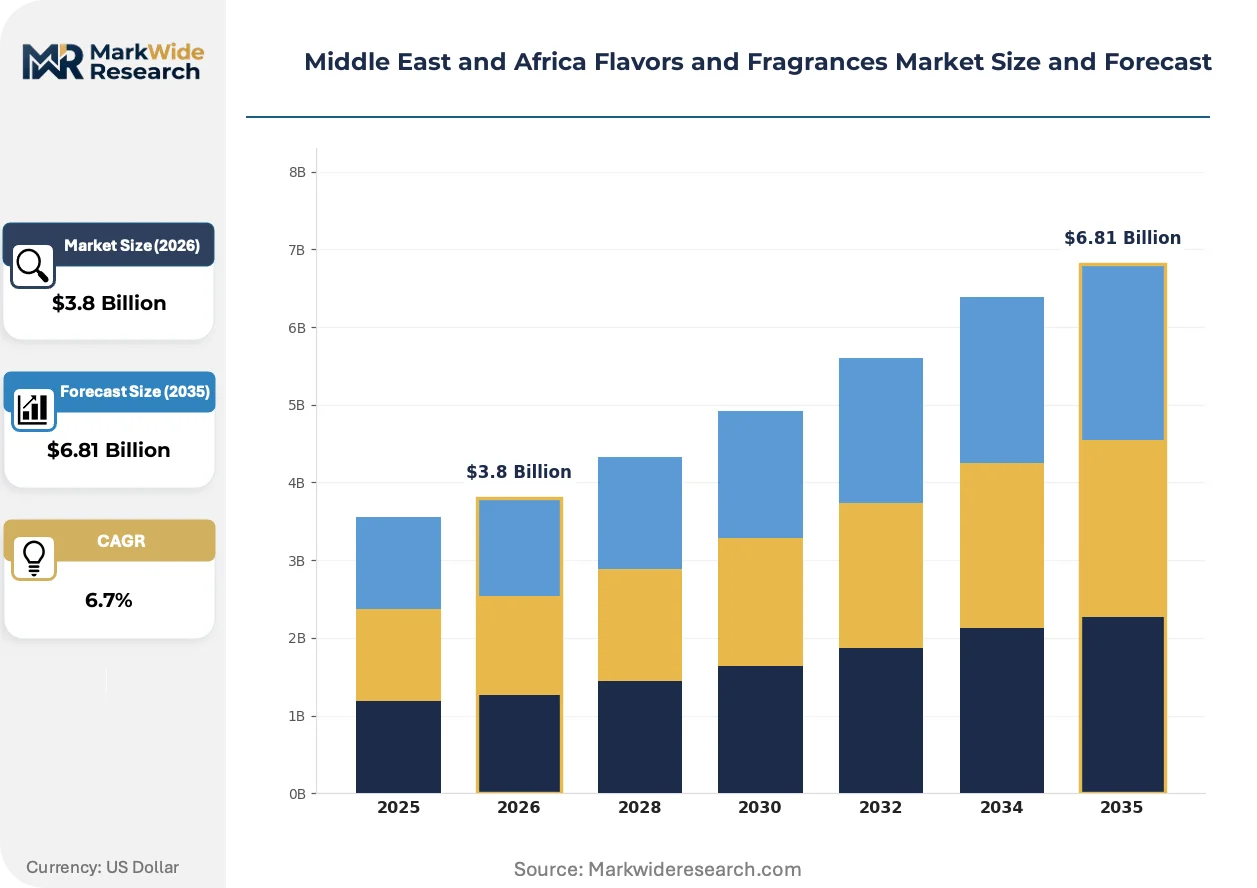
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Synthetic Flavors, Essential Oils, Aroma Chemicals Application: Food & Beverages, Personal Care, Household Products, Pharmaceuticals End User: Food Manufacturers, Beverage Producers, Cosmetic Companies, Health Care Providers Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesalers |
| Companies Covered | DSM-Firmenich, Sensient Technologies Corporation, Givaudan SA, Takasago International Corporation, MANE SA, Symrise AG, Kerry Group PLC, Aromatic Flavours and Fragrances S.A.E., International Flavors & Fragrances Inc., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Flavors and Fragrances Market Shifts & Advancements
Biotechnology and regulatory transparency mandates are compressing traditional supply hierarchies while digitizing quality verification across Middle East and Africa flavor and fragrance procurement.
Precision fermentation for rare botanical molecules is rendering obsolete conventional solvent extraction from endangered or climate-vulnerable plant species. Gulf luxury fragrance developers are adopting these bio-identical materials at pilot scale. The technology is rendering obsolete multi-year cultivation contracts that previously locked working capital in agricultural offtake agreements.
EU Green Deal REACH alignment is cascading into Egyptian and Moroccan import protocols, requiring full chemical safety dossiers for synthetic aroma ingredients. North African customs authorities now reject shipments lacking extended safety data sheets. Fragrance compounders serving these markets are consolidating supplier bases to reduce documentation complexity.
Clean-label preference is compressing switching cycles between synthetic and natural flavor suppliers among South African food processors. Gauteng-based manufacturers now require third-party organic certification as a baseline qualification. This behavioral shift is most visible in ready-to-drink beverage categories where ingredient transparency dominates consumer marketing.
Middle East and Africa Flavors and Fragrances Market Segmentation
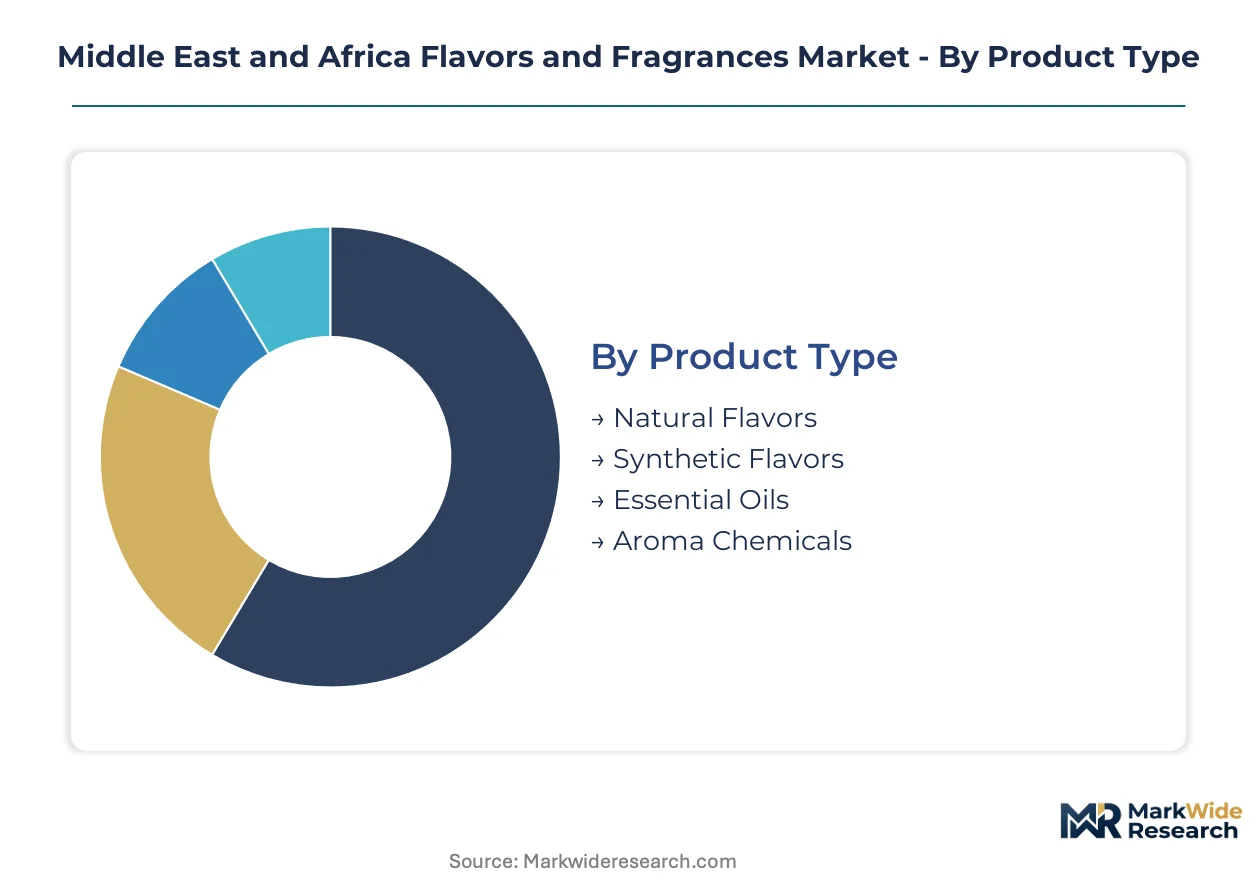
Segmentation in the Middle East and Africa flavors and fragrances market reveals divergent margin structures across product origins and application intensities. Procurement patterns split between Gulf luxury fragrance houses demanding certified natural inputs and North African mass-market beverage producers prioritizing synthetic cost efficiency.
Product Type:
Cost tier stratification separates premium botanical extracts from commodity synthetic alternatives, with certification requirements and raw material scarcity driving pricing spreads.
- Natural Flavors:Derived from plant, animal, or microbial sources through extraction, fermentation, or distillation. Halal certification mandates from Saudi Arabia's SFDA and the UAE's MOHAP concentrate demand among Gulf cosmetic companies targeting clean-label positioning. Climate-driven harvest variability in Moroccan rose and Somali frankincense regions compresses margin predictability.
- Synthetic Flavors:Chemically synthesized aroma compounds engineered for consistency and scale. North African beverage manufacturers in Egypt and Tunisia source these for cost efficiency in mass-market applications. REACH-aligned chemical safety standards from the EU Green Deal are reshaping import compliance documentation requirements.
- Essential Oils:Volatile aromatic compounds obtained through steam distillation or cold pressing. Regional distillers in Egypt and Morocco serve both domestic cosmetic formulators and export markets.
- Aroma Chemicals:Isolated synthetic molecules providing specific olfactory notes. Regional manufacturers are backward-integrating into captive production of key building blocks to reduce import dependency.
Synthetic flavors command the established base. The steepest expansion runs through aroma chemicals as local production capacity scales.
Application:
Application intensity varies from sub-0.1% flavor loads in pharmaceuticals to 20% concentrations in fine fragrance compounds, dictating supplier technical service requirements.
- Food & Beverages:Flavor systems dosed at 0.01% to 5% depending on matrix stability and heat processing requirements. South African food processors in Gauteng province drive demand for third-party organic certification as baseline qualification. Clean-label preference is compressing switching cycles between synthetic and natural suppliers.
- Personal Care:Fragrance compounds formulated at 5% to 20% concentration in fine perfumes, lower in functional products. Premium personal care brands across Saudi Arabia and the UAE are doubling fragrance SKUs built on oud and amber accords. Biotechnology-derived bio-identical molecules are rendering obsolete multi-year cultivation contracts.
- Household Products:Functional fragrances masking base odors in cleaners and air care. Mass-market positioning favors synthetic aroma chemicals for cost control.
- Pharmaceuticals:Flavor masking systems for pediatric and geriatric dosage forms. Regulatory scrutiny from Egypt's CDSCO-aligned cosmetic safety assessments elevates documentation burdens.
Food and beverages anchor volume throughput. Personal care generates the steepest margin expansion.
End User:
Customer type determines technical engagement depth, from commodity spot purchasing by beverage bottlers to collaborative development partnerships with luxury fragrance houses.
- Food Manufacturers:Industrial-scale processors requiring consistent flavor delivery across batch production. South African manufacturers serve both domestic retail and regional export networks into sub-Saharan markets.
- Beverage Producers:Ready-to-drink and concentrated soft drink formulators. Nigerian beverage sector procurement is shifting toward direct-to-manufacturer digital platforms disintermediating traditional distributor networks.
- Cosmetic Companies:Fragrance compounders and finished goods manufacturers. Gulf luxury brands demand perfumers trained in both synthetic chemistry and regional olfactory traditions, creating recruitment gaps.
- Health Care Providers:Pharmaceutical manufacturers and compounding pharmacies. Compliance with multi-jurisdiction allergen labeling from SFDA and MOHAP fragments production economics.
Beverage producers dominate transaction frequency. Cosmetic companies drive innovation partnership revenue.
Distribution Channel:
Channel selection reflects buyer sophistication, with multinationals bypassing intermediaries while regional traders serve fragmented local markets.
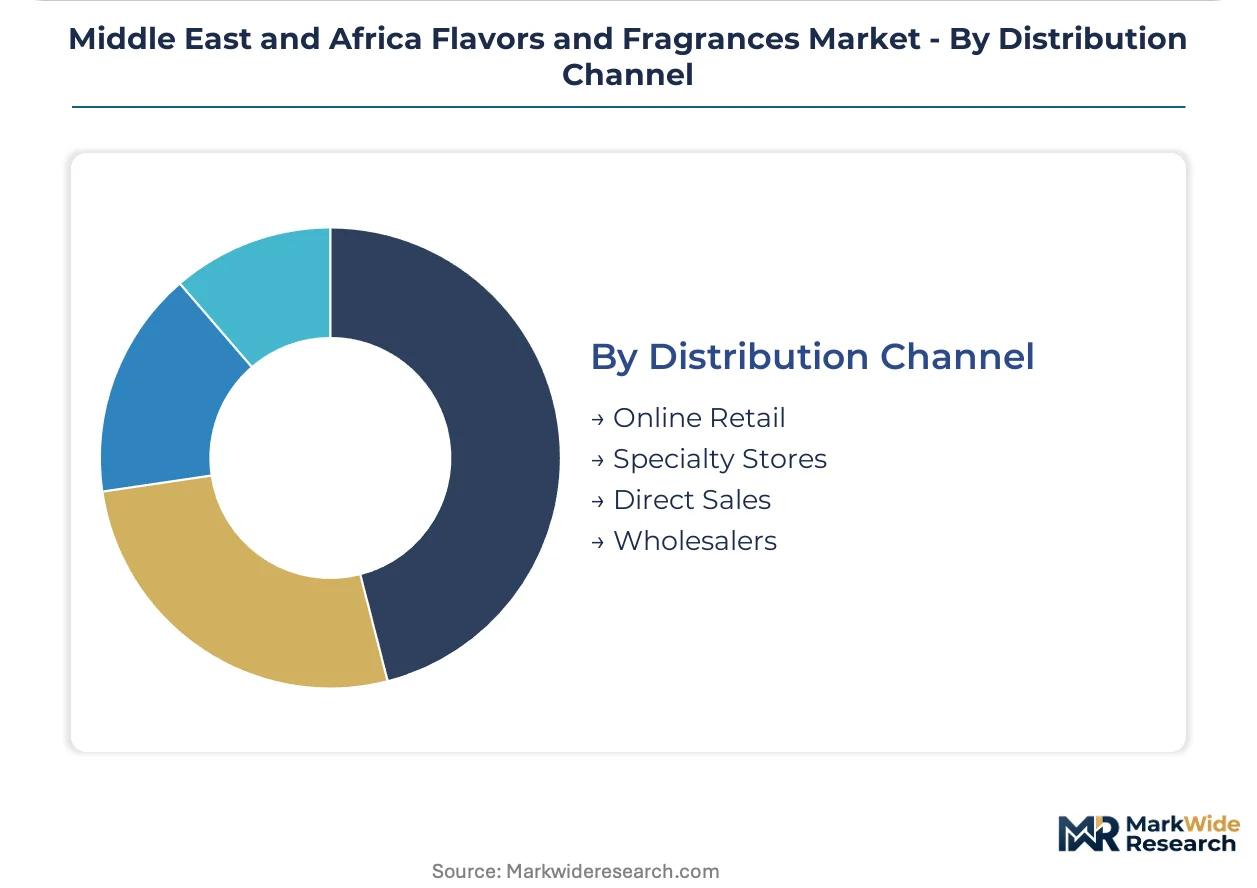
- Online Retail:B2B procurement portals enabling transparent pricing and technical documentation access. Digital adoption concentrates among Nigerian and South African mid-tier manufacturers.
- Specialty Stores:Local distributors offering technical consultation and sample fulfillment. Traditional network serving Egyptian and Moroccan small-scale food processors.
- Direct Sales:Multinational suppliers maintaining dedicated account teams for strategic customers. Givaudan SA leverages Swiss technical heritage to anchor premium fragrance development for Gulf luxury brands.
- Wholesalers:Regional traders aggregating fragmented demand across North African trade corridors. EU Green Deal compliance requirements are consolidating supplier bases to reduce documentation complexity.
Direct sales capture premium account value. Online retail is climbing fastest as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium fragrance compounders in the UAE command pricing power that Egyptian mass-market flavor suppliers cannot match, creating a two-tier procurement architecture across the region. This asymmetry shapes investment flows and regulatory compliance burdens.
Saudi Arabia
Halal-certified fragrance demand from Riyadh-based luxury cosmetic houses drives premium natural extract procurement. SFDA allergen disclosure mandates force SKU-specific packaging investments that fragment production economics. Jeddah's Red Sea port cluster handles concentrated imports of oud distillates for domestic compounding.
United Arab Emirates
Dubai's fragrance houses double oud and amber SKU counts for Gulf luxury retail expansion. MOHAP ingredient transparency rules elevate technical documentation costs for importers. Abu Dhabi's Khalifa Industrial Zone anchors biotechnology pilot facilities producing bio-identical aromatic molecules.
Egypt
Cairo-based flavor houses serve both domestic food processors and sub-Saharan export networks through CDSCO-aligned mutual recognition agreements. Egyptian customs authorities now enforce REACH-aligned chemical safety dossiers for synthetic aroma imports. Alexandria's port corridor consolidates botanical extract shipments from regional agricultural suppliers.
South Africa
Gauteng province manufacturers demand third-party organic certification as baseline qualification for natural flavor suppliers. SABS food-grade additive standards create technical barriers for unqualified traders. Cape Town's specialty chemical corridor houses regional distributors serving sub-Saharan beverage networks.
Morocco
Climate-driven harvest variability in Moroccan rose-growing regions compresses margin predictability for essential oil distillers. EU Green Deal alignment is reshaping export documentation for European-bound fragrance shipments. Casablanca's industrial zone concentrates solvent extraction capacity for domestic cosmetic formulators.
Middle East and Africa Flavors and Fragrances Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in a structure that rewards formulation chemistry depth over raw material trading scale. The vendor base splits between Swiss-heritage fragrance houses, Egyptian botanical extract specialists, and multinational flavor systems providers. Three archetypes dominate: heritage perfumers leveraging technical reputation, regional botanical sourcers with agricultural offtake control, and integrated color-flavor compounders. Competitive moves concentrate on captive aroma chemical production and direct-to-manufacturer digital procurement platforms.
Within the heritage perfumer tier, Givaudan SA and Symrise AG anchor premium fragrance development for Gulf luxury brands through technical service depth. Sensient Technologies Corporation occupies a position among integrated color-flavor specialists competing on formulation simplification. Aromatic Flavours and Fragrances S.A.E. exemplifies the regional botanical sourcing archetype with Egyptian agricultural network access.
| Leading Market Players |
|---|
| DSM-Firmenich |
| Sensient Technologies Corporation |
| Givaudan SA |
| Takasago International Corporation |
| MANE SA |
| Symrise AG |
| Kerry Group PLC |
| Aromatic Flavours and Fragrances S.A.E. |
| International Flavors & Fragrances Inc. |
| Others |
Supply & Pricing Matrix
EU Green Deal REACH alignment cascading into North African import protocols creates a dual compliance burden that simultaneously widens pricing spreads between certified and uncertified suppliers while forcing consolidation of fragmented distributor networks. This regulatory chokepoint compresses margin predictability for regional traders unable to absorb documentation costs, concentrating procurement power among capitalized multinationals with dedicated regulatory affairs functions.
Pricing Analysis
The customization-premium spread separates configured-to-order fragrance compounds from standard synthetic alternatives, with halal certification and third-party organic verification driving the widest price differentials. Three-tier pricing structure across premium, standard, and economy levels governs the market, where Gulf cosmetic houses absorb certification premiums while North African beverage producers prioritize volume scale. Cost compression in mass-market synthetic tiers is intensifying because lab-grown aroma molecules from Asian producers undercut botanical extracts. Beverage bottlers in Egypt and Tunisia exhibit highest price sensitivity; UAE luxury fragrance houses demonstrate lowest.
Supply Chain Analysis
Contract-manufacturing concentration sits with Egyptian flavor houses and Moroccan essential oil distillers serving both domestic formulators and European export markets. Supply draws from agricultural networks in Morocco's rose-growing regions, Somali frankincense corridors, and Egyptian botanical cultivation zones. Raw material dependencies center on oud distillates, amber resins, and synthetic aroma chemical precursors. Single-source vulnerability runs through climate-exposed harvest zones where drought patterns disrupt Moroccan rose oil availability. Distribution runs through Jeddah's Red Sea port cluster for Gulf-bound compounds and Alexandria's corridor for European exports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biotechnology-derived bio-identical molecules are disrupting traditional cultivation-based supply hierarchies, compressing investment timelines from multi-year agricultural contracts to pilot-scale fermentation facilities. This technological inflection favors capitalized players with R&D infrastructure over commodity traders.
For Market Incumbents: Harden compliance architecture against REACH-aligned documentation requirements by consolidating supplier bases and embedding regulatory specialists within Cairo and Casablanca procurement offices. Threat of synthetic substitution from Asian lab-grown producers demands captive aroma chemical production in Khalifa Industrial Zone and backward integration into key building blocks. For New Entrants and Emerging Players: Pursue white-space opportunities in Nigeria's direct-to-manufacturer digital procurement platforms and South Africa's third-party organic certification tier for Gauteng food processors. The most penetrable segment is mid-tier beverage producers seeking transparent supply chains without multinational minimum order requirements. Go-to-market angle: B2B portals offering technical documentation and sample fulfillment at distributor-competitive pricing. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform integrators with formulation chemistry depth over raw material trading scale. Long-term viability over the analysis window rests on biotechnology adoption curves and regulatory harmonization progress. Acquisition target archetype: Egyptian botanical extract specialists with CDSCO-aligned export capabilities and established agricultural offtake networks. Signal to watch: divergence between Gulf harmonization initiatives and sub-Saharan national standards as inflection indicator for compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Aroma Chemical Production | Backward integration into synthetic building blocks reduces import dependency for Egyptian and Moroccan manufacturers. |
| Halal Certification Investment | SFDA and MOHAP mandates open dedicated production lines for Saudi and UAE cosmetic suppliers. |
| Direct-to-Manufacturer Digital Platforms | B2B procurement portals disintermediate traditional distributor networks in Nigeria's beverage sector. |
| Biotechnology Pilot Facilities | Precision fermentation for rare botanical molecules renders obsolete multi-year cultivation contracts in Abu Dhabi. |
| CDSCO-Aligned Export Hub Development | Cairo-based flavor houses leverage mutual recognition agreements to access sub-Saharan African markets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fragrance compounders, flavor formulation chemists, regulatory affairs specialists at Gulf cosmetic houses, and procurement directors at North African beverage manufacturers; and secondary validation through customs trade data, SFDA and MOHAP regulatory filings, SABS standards documentation, and SEC disclosures from listed suppliers. Bottom-up demand modeling triangulated against top-down market sizing across product type, application intensity, and regional regulatory clusters.
Forecast inputs considered biotechnology adoption rates, REACH alignment implementation timelines, and halal certification penetration curves across the projection horizon. Segmentation dimensions modeled include natural versus synthetic origin, food and beverage versus personal care application, and Gulf versus North African versus sub-Saharan procurement patterns. CAGRs were derived from historical trajectory analysis adjusted for regulatory inflection points and technology substitution curves. Industry-specific inputs encompassed climate-driven harvest variability indices and distributor consolidation velocity.
Macroeconomic conditions sit as an overlay; deviation in currency volatility across Egyptian pound and Nigerian naira corridors, or sustained drought in Moroccan agricultural zones, would shift the trajectory. Forecasts reflect documented assumptions about regulatory harmonization progress and biotechnology scale-up timelines. Quarterly review of SFDA allergen disclosure implementation, EU Green Deal enforcement intensity at North African customs, and precision fermentation capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Mouth Freshener Market
Flavorings and Food Additives
Cheese Flavor Market
Flavorings and Food Additives
Dry Powder Flavors Market
Flavorings and Food Additives
Global Artichoke Extract Market
Flavorings and Food Additives
Global Beverage Flavoring Systems Market
Flavorings and Food Additives
Marshmallow Root Extract Market
Flavorings and Food Additives
Vanilla Oleoresin Market
Flavorings and Food Additives
Sour Cream Powder Market
Flavorings and Food Additives
Culinary Essence Market
Flavorings and Food Additives
Flavor Modulators Market
Flavorings and Food Additives
Chokeberry Extract Market
Flavorings and Food Additives
Feed Flavors and Sweeteners Market
Flavorings and Food Additives
Vanilla Bean Market
Flavorings and Food Additives
Flavor Oil Market
Flavorings and Food Additives
Yeast Based Savory Flavors Market
Flavorings and Food Additives
Food Texturizers Market