
 Beef Flavors Market | 2026-2036
Beef Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Beef Flavors Market Analysis
Precision fermentation and enzymatic extraction is rewriting how savory flavor compounds are synthesized without direct animal sourcing. Givaudan leverages biotechnology platforms to produce standardized beef flavor molecules with batch-to-batch consistency. Kerry Group anchors its position through backward integration into dairy and meat processing byproducts that feed its flavor precursor streams. Takasago International Corporation specializes in thermal reaction flavors developed through controlled Maillard chemistry.
Beef flavors comprise thermally processed mixtures of amino acids, reducing sugars, and lipid-derived volatiles designed to replicate the organoleptic signature of cooked beef. These formulations typically achieve target flavor intensity at dosage rates between 0.1% and 2.0% by weight in finished food matrices. Smoked and grilled flavor types dominate volume due to their compatibility with barbecue sauce and snack seasoning applications, while marinated profiles command premium positioning in ready-to-eat meal formats. Liquid forms lead in food service channels for pump-metered dispensing, whereas powder forms sustain growth in dry seasoning blends and instant soup bases where shelf stability and flowability determine procurement decisions.
EFSA flavoring regulation EC 1331/2008 governs safety evaluation and maximum use levels for beef-derived flavor precursors in European food manufacturing, while FDA 21 CFR Part 172 specifies conditions for safe use of hydrolyzed protein flavorings in the United States. Both frameworks are tightening scrutiny on artificial smoke and grill flavor carriers, pushing reformulation toward natural extractives and yeast-derived alternatives. Stakeholders must monitor evolving maximum residue limits for process contaminants like polycyclic aromatic hydrocarbons in thermally generated beef flavors, as regulatory thresholds in major markets will determine which production technologies retain commercial viability.
Market Dynamics
Precision fermentation platforms are collapsing the traditional reliance on animal-derived precursors, forcing flavor houses to restructure R&D spend toward cell-culture infrastructure and bioreactor capacity. This biotechnology pivot redistributes competitive advantage from extraction expertise to strain engineering capabilities.
Growth Catalysts
- Plant-based meat proliferation:Food manufacturers require authentic beef profiles for burger analogues and snack applications, creating pull-through for natural flavor concentrates.
- EFSA EC 1331/2008 compliance pathways:Clear safety evaluation frameworks for yeast-derived and enzymatic flavor precursors reduce regulatory uncertainty for European formulators.
- Quick-service restaurant expansion:Chains in the United States deploy liquid beef flavors for sauce consistency across thousands of locations.
Market Restraints
- Input cost volatility:Amino acid feedstocks and specialized yeast extracts face price swings tied to fermentation substrate markets.
- Technical limitation:Thermally generated flavors struggle to replicate the full volatile complexity of slow-cooked beef fat without polycyclic aromatic hydrocarbon contamination.
- Substitution threat:Mushroom-derived umami compounds and yeast extracts capture share in clean-label applications where "beef flavor" declarations face consumer scrutiny.
Strategic Opportunities
- Underpenetrated geography:Brazil's processed meat sector offers expansion potential as ANVISA modernizes flavor additive regulations.
- Regulatory tailwind:FDA 21 CFR Part 172 revisions on hydrolyzed protein labeling create first-mover advantage for enzymatic extraction specialists.
- Technology convergence:Combining precision fermentation with AI-driven volatile profiling accelerates novel compound discovery timelines.
Industry Challenges
- Skill gap:Strain engineering and bioprocess optimization expertise concentrates in pharmaceutical and biofuel sectors, not traditional flavor houses.
- Capex intensity:Commercial-scale precision fermentation requires bioreactor investments that strain mid-tier flavor manufacturers.
- Certification timeline:Novel Food approvals under EFSA and GRAS self-affirmations with FDA extend product launch cycles by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beef Flavors Market |
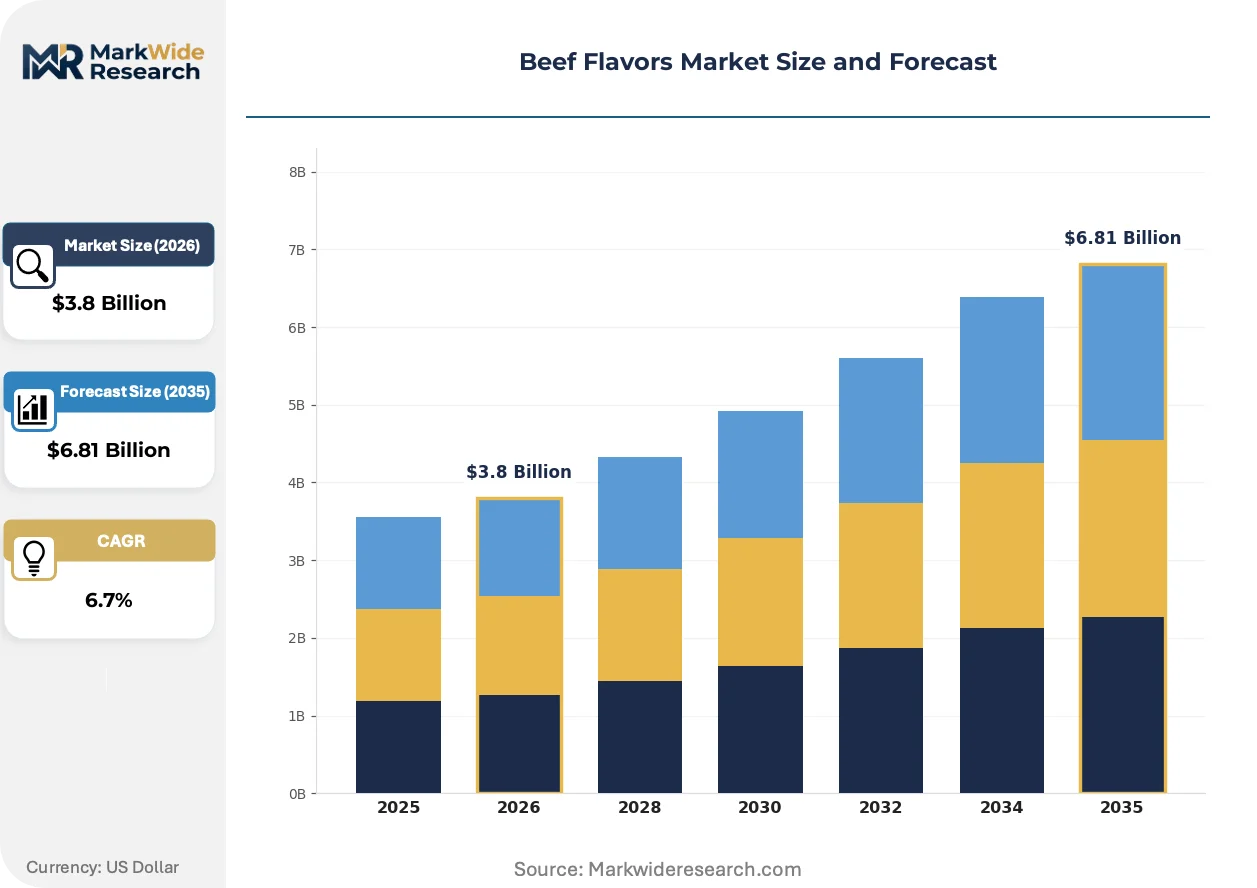
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Flavor Type: Smoked, Grilled, Barbecued, Seasoned Application: Ready-to-Eat Meals, Sauces, Snacks, Marinades End User: Restaurants, Food Manufacturers, Retailers, Food Service Form: Liquid, Powder, Paste, Granular |
| Companies Covered | Givaudan, Kerry Group, Symrise AG, Firmenich, International Flavors & Fragrances, Sensient Technologies Corporation, Takasago International Corporation, Robertet Group, Synergy Flavors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beef Flavors Market Emerging Trajectories
Biotechnology is collapsing boundaries between natural and synthetic flavor production, while regulatory tightening on thermal process contaminants accelerates alternative pathway development. These forces reshape how beef flavors are sourced, validated, and deployed across food matrices.
Precision fermentation is collapsing the cost structure of rare sulfur-containing volatiles like 2-methyl-3-furanthiol that define cooked beef aroma. Snack seasoning manufacturers in the United States adopt these biosynthesized molecules to replace thermally reacted extracts. The technology compresses minimum viable scale for specialty flavor production from industrial reactors to modular bioreactor farms.
EFSA's evolving maximum residue limits for polycyclic aromatic hydrocarbons in thermally processed flavors is forcing European manufacturers toward enzymatic and fermentation-derived alternatives. The regulation disproportionately impacts smoked and grilled beef flavor categories that rely on high-temperature reactions. Reformulation timelines now dominate product development roadmaps for suppliers serving EU food manufacturers.
Direct procurement relationships between quick-service restaurant chains and biotechnology-enabled flavor houses are displacing traditional distributor intermediaries. Chains seek batch-to-batch consistency guarantees that commodity traders cannot provide. This channel compression is most advanced in the United States, where vertical integration between restaurant R&D and flavor innovation labs accelerates custom profile development.
Beef Flavors Market Segmentation
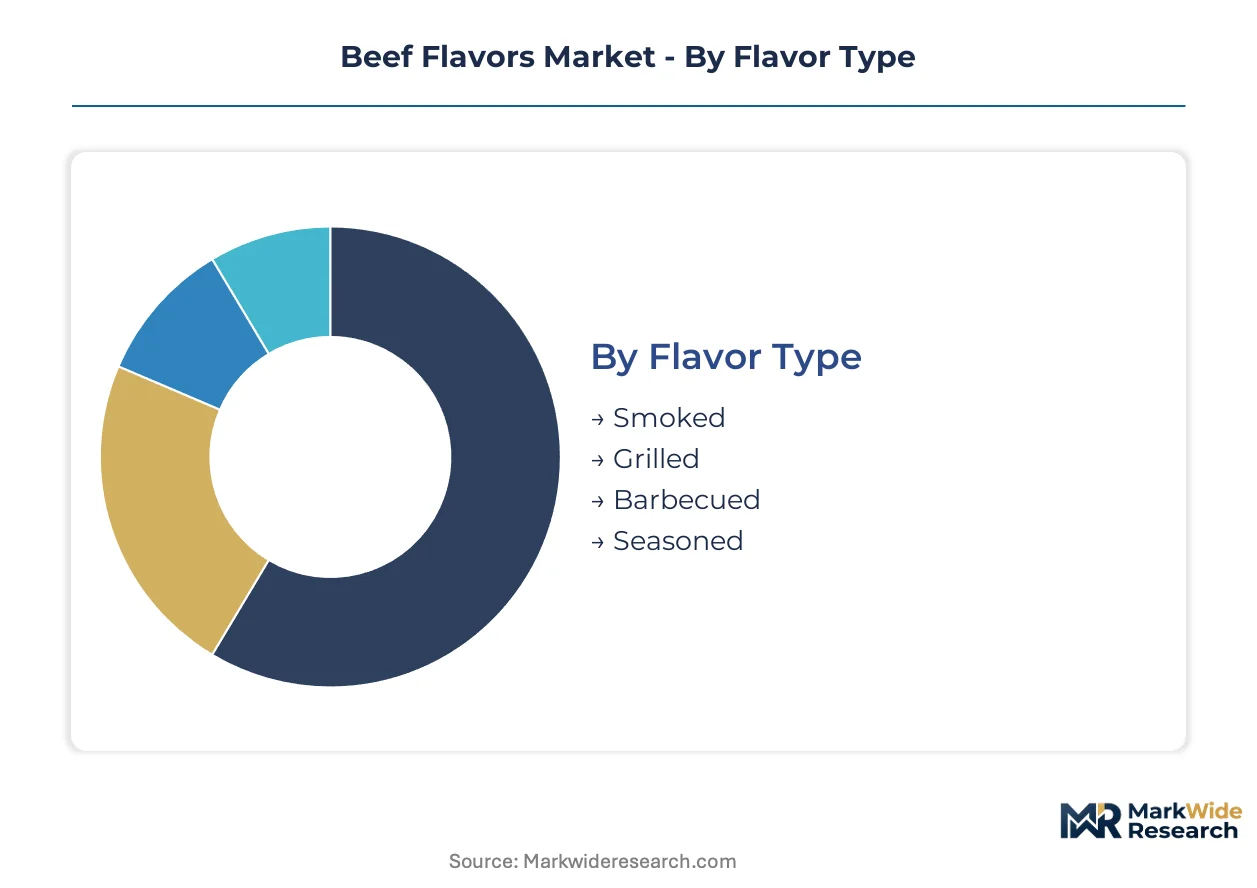
Beef flavor procurement patterns diverge sharply across end-use channels, with quick-service restaurants demanding liquid concentrates for sauce consistency while snack manufacturers prioritize shelf-stable powders. Understanding these segment dynamics reveals where formulation investments concentrate and which delivery formats capture margin expansion.
Flavor Type:
Cycle times vary dramatically across flavor profiles, with smoked variants requiring extended thermal reaction periods while seasoned formats permit rapid blending turnaround.
- Smoked:Thermally processed mixtures incorporating wood-derived phenolic compounds and lipid oxidation products to replicate slow-smoked beef aroma. Quick-service restaurants in the United States deploy these in barbecue sauce formulations where consistency across thousands of locations is non-negotiable. EFSA's tightening polycyclic aromatic hydrocarbon limits are forcing reformulation toward liquid smoke alternatives.
- Grilled:Maillard-reacted amino acid and reducing sugar combinations generating heterocyclic sulfur compounds that signal charred beef fat. Snack seasoning manufacturers represent the dominant demand channel, particularly for potato chip and extruded snack applications requiring intense surface flavor deposition.
- Barbecued:Composite profiles balancing sweet, smoky, and savory notes through layered thermal and enzymatic processing.
- Seasoned:Blended spice and extract formulations permitting rapid customization without extended reaction cycles.
Smoked anchors the volume base while seasoned gains share at the steepest rate.
Application:
Margin structures stratify across applications, with marinades commanding premium positioning due to clean-label complexity while sauces operate on volume-driven efficiency models.
- Ready-to-Eat Meals:Retort-stable flavor systems designed to withstand thermal processing without volatile loss. Food manufacturers in the United States concentrate procurement here as chilled and frozen meal formats expand shelf space allocation.
- Sauces:Pump-dispersed liquid concentrates achieving target flavor intensity at 0.5% to 2.0% dosage rates. Quick-service restaurant chains drive bulk procurement through direct supplier relationships that bypass traditional distribution.
- Snacks:Surface-applied powders and slurries requiring adhesion optimization and resistance to oxidative degradation during shelf life.
- Marinades:Complex formulations integrating tenderization enzymes with flavor precursors for protein penetration.
Sauces dominate absolute volume while ready-to-eat meals expand most quickly.
End User:
Procurement sophistication separates institutional buyers, with food manufacturers deploying technical specification teams while food service operators prioritize logistical reliability.
- Restaurants:Independent operators and mid-size chains sourcing through broadline distributors with limited custom formulation access. FDA 21 CFR Part 172 compliance requirements shape supplier qualification protocols.
- Food Manufacturers:Industrial-scale buyers with captive R&D capabilities driving co-development relationships with flavor houses. These stakeholders specify batch-to-batch consistency metrics that strain mid-tier supplier quality systems.
- Retailers:Private-label program managers sourcing standardized profiles for store-brand processed meats and sauce lines.
- Food Service:Institutional feeding operations emphasizing cost control and supply security over organoleptic differentiation.
Food manufacturers anchor the volume base while restaurants climb the fastest.
Form:
Capital intensity divides production infrastructure, with liquid formats requiring specialized filling and aseptic packaging lines while powders leverage existing spray-drying assets.
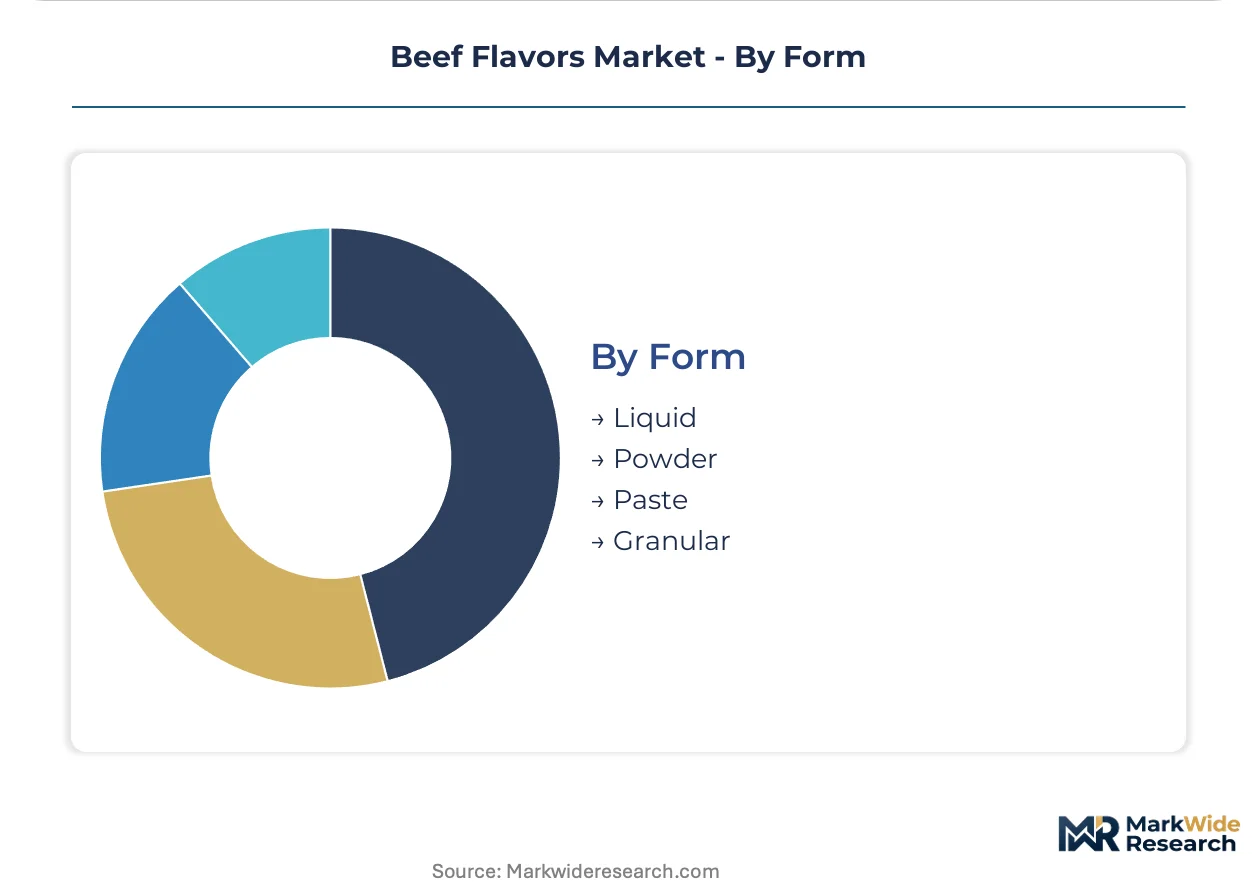
- Liquid:Aqueous or oil-based solutions optimized for pump metering and uniform dispersion in sauce matrices. Food service channels in the United States prefer this format for operational efficiency in high-throughput kitchen environments.
- Powder:Spray-dried or plated flavor systems offering extended shelf stability and flowability for dry seasoning blends. Snack manufacturers sustain growth here as instant soup bases and seasoning packets retain procurement priority.
- Paste:High-solids concentrates for applications requiring viscosity control and reduced water activity.
- Granular:Agglomerated particles balancing solubility with resistance to caking in humid storage conditions.
Powder anchors the volume base while liquid gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Netherlands-based flavor houses export precision-fermented beef flavor precursors to German and French food manufacturers seeking EFSA-compliant alternatives to thermally processed extracts. This trade corridor channels biotechnology-enabled savory compounds into the European Union's largest processed meat and ready-meal production zones.
United States
Quick-service restaurant chains in the United States deploy liquid beef concentrates for sauce consistency across thousands of locations. FDA 21 CFR Part 172 governs hydrolyzed protein flavoring safety and labeling requirements. Chicago and Dallas-Fort Worth anchor procurement clusters where direct supplier relationships bypass traditional distribution intermediaries.
Germany
EFSA EC 1331/2008 compliance pathways drive German food manufacturers toward enzymatic extraction and yeast-derived flavor precursors. The country's national food safety regulator enforces tightening maximum residue limits for polycyclic aromatic hydrocarbons in thermally processed flavors. Bavaria's processed meat sector concentrates reformulation investment as smoked and grilled profile alternatives gain regulatory clearance.
Brazil
ANVISA modernization of flavor additive regulations creates procurement flexibility for Brazilian processed meat exporters targeting European and North American buyers. The national health surveillance agency's evolving framework permits novel enzymatic and fermentation-derived flavor systems. São Paulo's industrial corridor attracts multinational flavor houses establishing technical service laboratories for South American market development.
Japan
Japanese food manufacturers integrate beef flavor concentrates into retort-stable ready-to-eat meal formats for aging demographics and convenience-seeking consumers. METI industrial policy supports biotechnology platform development for sustainable flavor production. The Kansai region's traditional fermentation expertise converges with precision biology in Osaka-Kobe industrial clusters developing next-generation savory compounds.
Beef Flavors Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base stratifies between multinational flavor houses with captive biotechnology platforms and regional compounders serving price-sensitive food service segments. Strategic archetypes include precision-fermentation specialists, thermal-reaction flavor experts, and backward-integrated meat processing byproduct processors. Dominant competitive moves encompass bioreactor capacity expansion and direct procurement relationships with quick-service restaurant chains that displace distributor intermediaries.
Within the biotechnology-enabled tier, Givaudan and Kerry Group exemplify platform-scale competitors. Givaudan leverages strain engineering capabilities developed through pharmaceutical sector crossover. Kerry Group anchors its position through upstream control over dairy and meat processing byproducts feeding flavor precursor streams. Takasago International Corporation occupies a specialized position in thermal-reaction flavor chemistry. These three entities represent divergent strategic postures: fermentation-platform scale, agricultural-commodity integration, and precision thermal processing expertise.
| Leading Market Players |
|---|
| Givaudan |
| Kerry Group |
| Symrise AG |
| Firmenich |
| International Flavors & Fragrances |
| Sensient Technologies Corporation |
| Takasago International Corporation |
| Robertet Group |
| Synergy Flavors |
| Others |
Supply Flow & Price Mechanics
Overcapacity in European thermal-reaction flavor production is compressing margins and forcing suppliers toward precision fermentation platforms that command premium positioning. This utilization imbalance redistributes pricing power toward biotechnology-enabled producers with batch-to-batch consistency guarantees.
Pricing Analysis
Cost-plus contracts indexed to amino acid feedstock and yeast extract spot markets dominate procurement between flavor houses and food manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates precision-fermented molecules from enzymatic extracts and commodity thermally reacted bases. Cost compression in standard-tier thermal flavors is intensifying because EFSA polycyclic aromatic hydrocarbon limits are disqualifying legacy production methods. Quick-service restaurant chains exhibit lowest price sensitivity due to consistency requirements, while independent food service operators drive hardest bargain.
Supply Chain Analysis
Tariff exposure between the United States and China disrupts amino acid precursor flows that feed enzymatic extraction processes. Supply concentrates in the Netherlands for precision-fermented precursors, the United States for thermal-reaction expertise, and Brazil for meat processing byproduct sourcing. Raw material dependencies span fermentation substrates, specialized yeast strains, and hydrolyzed protein feedstocks. Single-source vulnerability in strain engineering talent pools threatens capacity expansion timelines. Distribution runs through direct procurement relationships with multinational food manufacturers that displace traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and regulatory compliance subscriptions now expand faster than commodity flavor concentrate sales, transforming capital-light formulation partnerships into recurring-revenue anchors.
For Market Incumbents: Build regulatory data moats through GRAS self-affirmation dossiers and EFSA Novel Food submission libraries that delay competitor entry. Deepen backward integration into dairy and meat processing byproduct streams to secure precursor supply. Acquire strain engineering capabilities from pharmaceutical sector crossovers before talent scarcity hardens. Defensive consolidation around bioreactor capacity in the Netherlands and United States protects against emerging precision fermentation specialists. For New Entrants and Emerging Players: Brazilian processed meat exporters facing ANVISA modernization represent the most penetrable entry point for enzymatic extraction specialists. Mid-tier snack manufacturers in Southeast Asia seeking clean-label alternatives offer second white-space target. Partner with quick-service restaurant R&D labs on custom profile co-development rather than competing through distributor channels. Position around EFSA-compliant natural extractives as European reformulation deadlines accelerate. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among flavor houses with captive technical service laboratories and regulatory submission capabilities. Five-to-ten-year viability favors platforms combining precision fermentation with AI-driven volatile discovery rather than standalone thermal-reaction assets. Target acquisition archetype: mid-cap enzymatic extraction specialists with ANVISA or FDA submission track records. Monitor EFSA maximum residue limit announcements as inflection signal for thermally processed flavor obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Bioreactor capacity expansion in the Netherlands and United States captures EFSA-driven reformulation demand. |
| Regulatory Submission Investment | GRAS and Novel Food dossier libraries create multi-year entry barriers against emerging competitors. |
| Backward Integration | Captive supply of dairy and meat processing byproducts secures flavor precursor cost stability. |
| Direct Procurement Relationships | Bypassing distributors with quick-service restaurant chains locks in volume and consistency premiums. |
| AI-Driven Volatile Profiling | Machine learning acceleration of sulfur-compound discovery compresses R&D timelines for biosynthesized molecules. |
Methodological Framework
Initial hypotheses were tested against primary input from flavor house R&D directors, food manufacturer procurement leads, regulatory affairs specialists at EFSA and FDA, and quick-service restaurant supply chain executives, then refined through secondary validation. Bottom-up triangulation combined trade data on amino acid and yeast extract flows, EFSA flavoring regulation EC 1331/2008 compliance filings, FDA 21 CFR Part 172 submission records, and food service distribution channel audits with top-down market sizing.
Demand-supply-balance framing anchored the forecast framework across flavor type, application, end user, and form segmentation dimensions. CAGRs were derived from modeled volume trajectories in each segment against capacity expansion announcements and regulatory clearance timelines. Industry-specific inputs included EFSA maximum residue limit evolution scenarios and precision fermentation cost-curve assumptions.
Practitioners should monitor EFSA polycyclic aromatic hydrocarbon threshold revisions, ANVISA regulatory modernization pace, and strain engineering talent migration patterns for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Brazil Food Flavor and Enhancer Market
Flavorings and Food Additives
Global Natural Food Flavors Market
Flavorings and Food Additives
Apple Essence Market
Flavorings and Food Additives
Citrus Flavonoid Complexes from Mediterranean Peels Market
Flavorings and Food Additives
Flavor Oil Market
Flavorings and Food Additives
FTNF Flavors Market
Flavorings and Food Additives
Citrus Oil Market
Flavorings and Food Additives
Dry Powder Flavors Market
Flavorings and Food Additives
Global Syrup Market
Flavorings and Food Additives
Beverage Flavoring Agent Market
Flavorings and Food Additives
Mandarin Oil Market
Flavorings and Food Additives
Rose Water Market
Flavorings and Food Additives
Keto Friendly Flavors Market
Flavorings and Food Additives
Cheese Flavor Market
Flavorings and Food Additives
Global Beverage Flavoring Systems Market
Flavorings and Food Additives
Global Floral Flavors Market