
 Chicory Extract Market | 2026-2036
Chicory Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Chicory Extract Market Analytics
Buyer concentration in the food and beverage sector is rebalancing as mid-sized clean-label brands fragment procurement while large multinationals consolidate long-term supply agreements. Cargill Incorporated leverages its global agricultural sourcing network to secure raw chicory root supply across multiple growing regions. Cosucra Groupe Warcoing anchors European production capacity through integrated farming and extraction operations near its Belgian processing facilities. BENEO GmbH differentiates through specialized inulin and oligofructose variants targeting digestive health positioning in functional foods.
Chicory extract comprises soluble fibers, bitter compounds, and roasted derivatives obtained through hot water extraction, enzymatic hydrolysis, or dry roasting of Cichorium intybus roots, with inulin purity grades ranging from 90% to 99% for pharmaceutical applications. The ingredient serves primarily as a sugar replacer, prebiotic fiber, and caffeine-free coffee alternative in commercial formulations. Inulin commands the largest value share among product types due to its dual functionality in texture modification and gut health claims, while chicory root fiber experiences accelerated growth from bakery and dairy reformulation trends. Roasted chicory maintains stable demand in traditional European markets but faces slower expansion compared to fiber isolates.
EFSA evaluates prebiotic health claim submissions for chicory-derived inulin under EU Regulation 1924/2006, shaping product positioning and label compliance across member states. FDA GRAS status for inulin and oligofructose enables U.S. market access but requires adherence to specific purity and manufacturing specifications. The F-Gas Regulation in Europe pressures processors to transition extraction equipment toward lower-emission alternatives. Stakeholders must monitor evolving novel food approvals in Asia-Pacific jurisdictions and assess backward integration into chicory cultivation to secure supply chain resilience against climate volatility.
Market Dynamics
The F-Gas Regulation is compelling European processors to retrofit extraction equipment, while sugar-reduction mandates across multiple jurisdictions accelerate inulin adoption in reformulated packaged foods.
Growth Catalysts
- EU sugar-reduction frameworks:Member state levies on sweetened beverages push manufacturers toward chicory-derived fiber systems in dairy and bakery applications.
- Prebiotic health claim pipelines:EFSA evaluations under Regulation 1924/2006 validate gut microbiome positioning, enabling premium pricing in functional food segments.
- Belgian-Dutch cultivation clusters:Established chicory farming infrastructure around the North Sea provides cost-competitive raw material access for regional processors.
Market Restraints
- Input cost volatility:Chicory root prices fluctuate with regional weather patterns and competing crop economics in northern European growing zones.
- Supply concentration risk:A limited number of integrated Belgian and Dutch processors control the majority of high-purity inulin extraction capacity.
- Substitution pressure:Polydextrose and resistant maltodextrin compete for sugar-replacement formulations in cost-sensitive beverage applications.
Strategic Opportunities
- Asia-Pacific novel food approvals:Regulatory harmonization efforts in China and South Korea open pathways for chicory fiber in regional functional food markets.
- Sports nutrition expansion:Prebiotic-fortified protein bars and recovery beverages represent an underdeveloped application channel for oligofructose variants.
- Clean-label confectionery:Hard candy and chocolate segments seeking sugar reduction without artificial sweeteners present formulation partnership potential.
Industry Challenges
- Specialized extraction engineering:F-Gas-compliant equipment retrofits require scarce technical expertise in supercritical CO2 and membrane filtration systems.
- Multi-jurisdiction certification timelines:Synchronized novel food dossier preparation for FDA GRAS, EFSA health claims, and Asia-Pacific regulators strains regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chicory Extract Market |
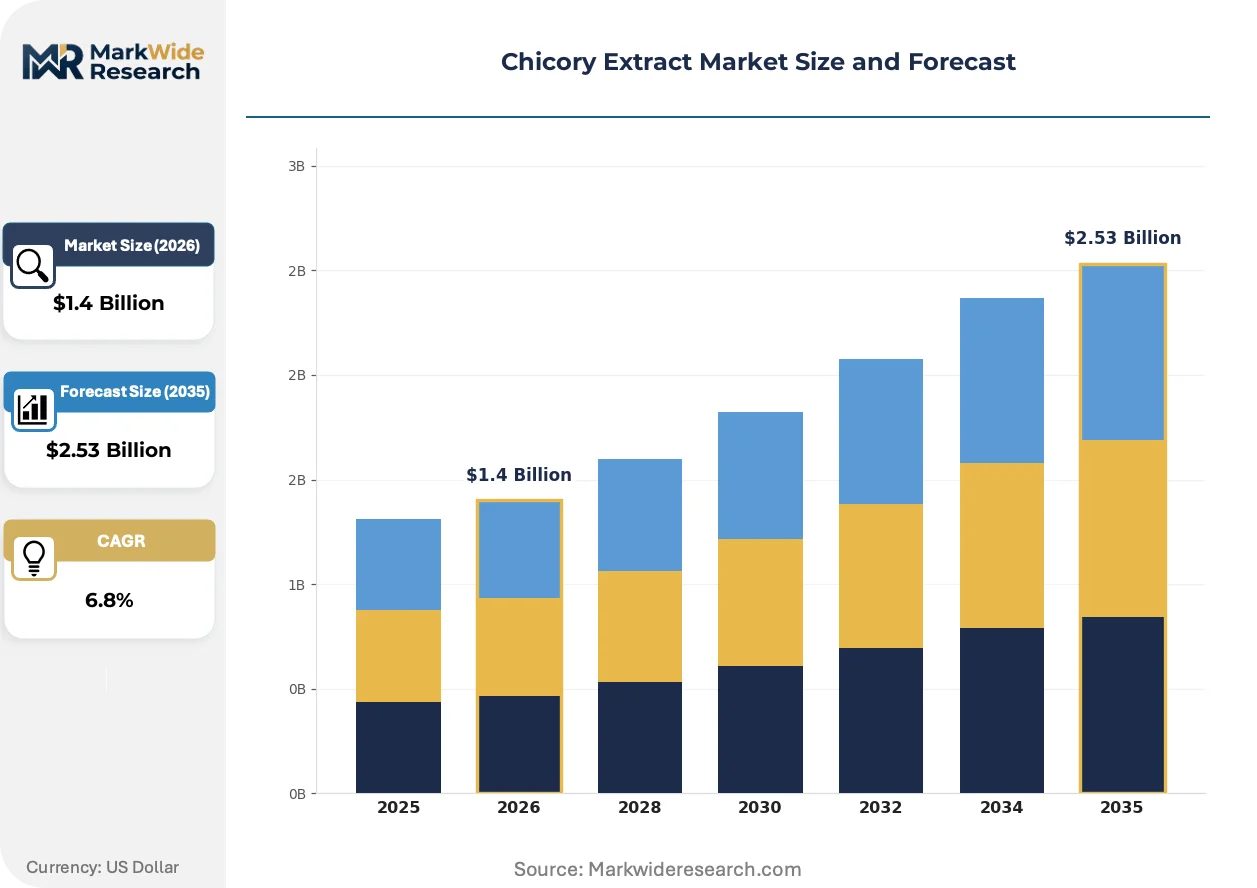
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inulin, Chicory Root Fiber, Chicory Coffee, Roasted Chicory End User: Food & Beverage, Pharmaceuticals, Dietary Supplements, Animal Feed Distribution Channel: Online, Supermarkets, Health Food Stores, Distributors Service Type: Contract Manufacturing, Private Labeling, Bulk Supply, Custom Formulation |
| Companies Covered | Cargill Incorporated, Cosucra Groupe Warcoing, BENEO GmbH, Starwest Botanicals, Delecto Foods Pvt Ltd, NP Nutra, STOKROS Company Ltd, Sensus, Leroux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chicory Extract Market Evolving Landscape
Enzymatic hydrolysis and precision fermentation techniques are reshaping extraction economics, while regulatory clarity on prebiotic claims enables new product positioning strategies across food and pharmaceutical channels.
Membrane filtration technology is expanding into chicory processing facilities as processors seek to replace solvent-based extraction with lower-emission alternatives. Dairy and beverage manufacturers in Germany and the Netherlands are piloting these systems at commercial scale. The shift is compressing capital payback periods for integrated operators while raising barriers for smaller toll processors dependent on legacy equipment.
EFSA's evolving interpretation of prebiotic health claim substantiation under EU Regulation 1924/2006 is tightening clinical evidence requirements for inulin and oligofructose. Manufacturers must now commission human intervention studies demonstrating measurable microbiome effects. Pharmaceutical-grade inulin suppliers with existing clinical data portfolios are capturing disproportionate label claim access in member states with active enforcement.
Ingredient sourcing contracts are compressing from multi-year frameworks to 12-18 month agreements with volume flexibility clauses. Mid-sized clean-label brands are fragmenting procurement across multiple suppliers to secure supply security, displacing the concentrated buyer power of large multinationals. This pattern is most visible in German and Belgian markets where established chicory processors face new negotiation dynamics with emerging organic and free-from brands.
Chicory Extract Market Segmentation
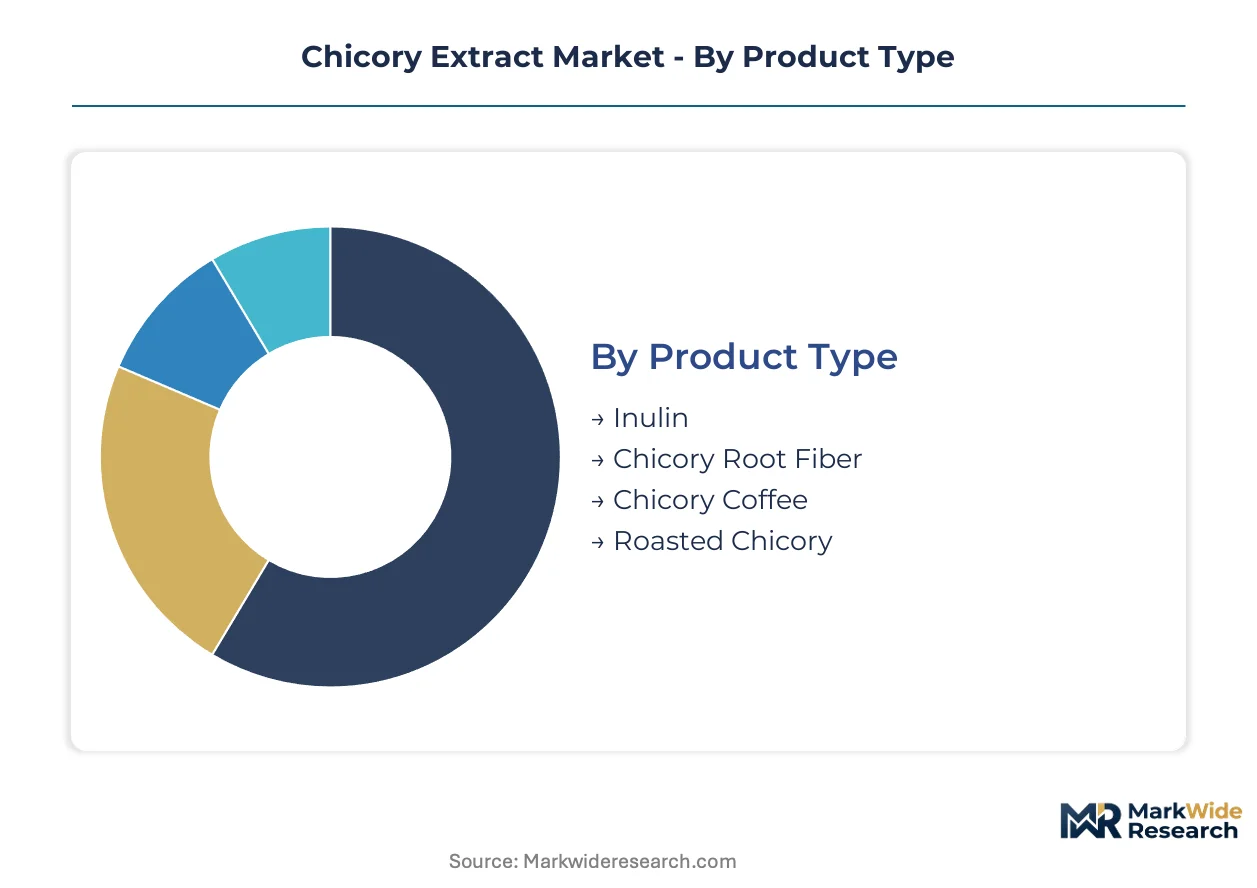
Segmentation in the chicory extract market reveals divergent value capture strategies across functional applications. Product purity grades and end-use certification requirements create distinct margin tiers that reshape procurement patterns among food manufacturers and pharmaceutical formulators.
Product Type:
Integration depth varies sharply across product types, with pharmaceutical-grade isolates demanding standalone processing infrastructure while roasted derivatives integrate into conventional coffee supply chains.
- Inulin:Soluble fiber extracted through hot water processing yields purity grades from 90% to 99% for pharmaceutical applications. German dairy reformulators and Belgian bakery manufacturers concentrate procurement of high-purity variants to meet EFSA prebiotic claim substantiation under EU Regulation 1924/2006. The dual functionality in texture modification and gut health positioning commands premium pricing in functional food segments.
- Chicory Root Fiber:Less refined fiber matrices retain broader polysaccharide profiles suitable for cost-sensitive bakery and beverage applications. Netherlands-based processors supply this grade to mid-sized clean-label brands fragmenting procurement away from multiyear supply agreements. Sugar-reduction mandates across EU member states accelerate adoption in reformulated packaged foods.
- Chicory Coffee:Roasted and ground root material serves caffeine-free beverage alternatives with established demand in traditional European markets.
- Roasted Chicory:Dark-roasted derivatives provide flavoring agents for coffee blends and standalone hot beverages with stable but slower expansion compared to fiber isolates.
Inulin leads volumes today; chicory root fiber is gaining share fastest.
End User:
Cost tier stratification separates pharmaceutical-grade certification requirements from commodity food applications, with dietary supplements occupying an intermediate compliance tier.
- Food & Beverage:Dairy, bakery, and beverage manufacturers across Germany, Belgium, and the Netherlands drive inulin procurement for sugar-reduction formulations. EU sugar-reduction frameworks and member state levies on sweetened beverages push reformulation toward chicory-derived fiber systems.
- Pharmaceuticals:High-purity inulin grades for drug delivery and prebiotic therapeutic applications require EMA-aligned manufacturing standards and clinical evidence portfolios. Suppliers with existing human intervention studies capture disproportionate label claim access in enforcement-active member states.
- Dietary Supplements:Capsule and powder formats targeting digestive health position oligofructose variants in sports nutrition and wellness channels with emerging demand in protein bars and recovery beverages.
- Animal Feed:Prebiotic fiber inclusion in livestock and pet nutrition formulations represents a developing application with lower purity tolerance and price sensitivity.
Food and beverage dominates current offtake; pharmaceuticals shows the steepest expansion trajectory.
Distribution Channel:
Customer type fragmentation distinguishes consolidated multinational procurement through distributors from direct relationships that emerging clean-label brands pursue with integrated processors.
- Online:Direct-to-manufacturer platforms and ingredient marketplaces serve mid-sized brands seeking supply security through multi-supplier relationships.
- Supermarkets:Retail shelf presence for finished consumer products containing chicory fiber, primarily in German and Belgian markets with established consumer familiarity.
- Health Food Stores:Specialty retail channels for organic and free-from positioned chicory coffee and supplement products.
- Distributors:Traditional intermediaries maintain relevance for large multinationals consolidating long-term supply agreements with Belgian and Dutch processors.
Distributors handle the largest contract volumes; online channels are climbing the fastest.
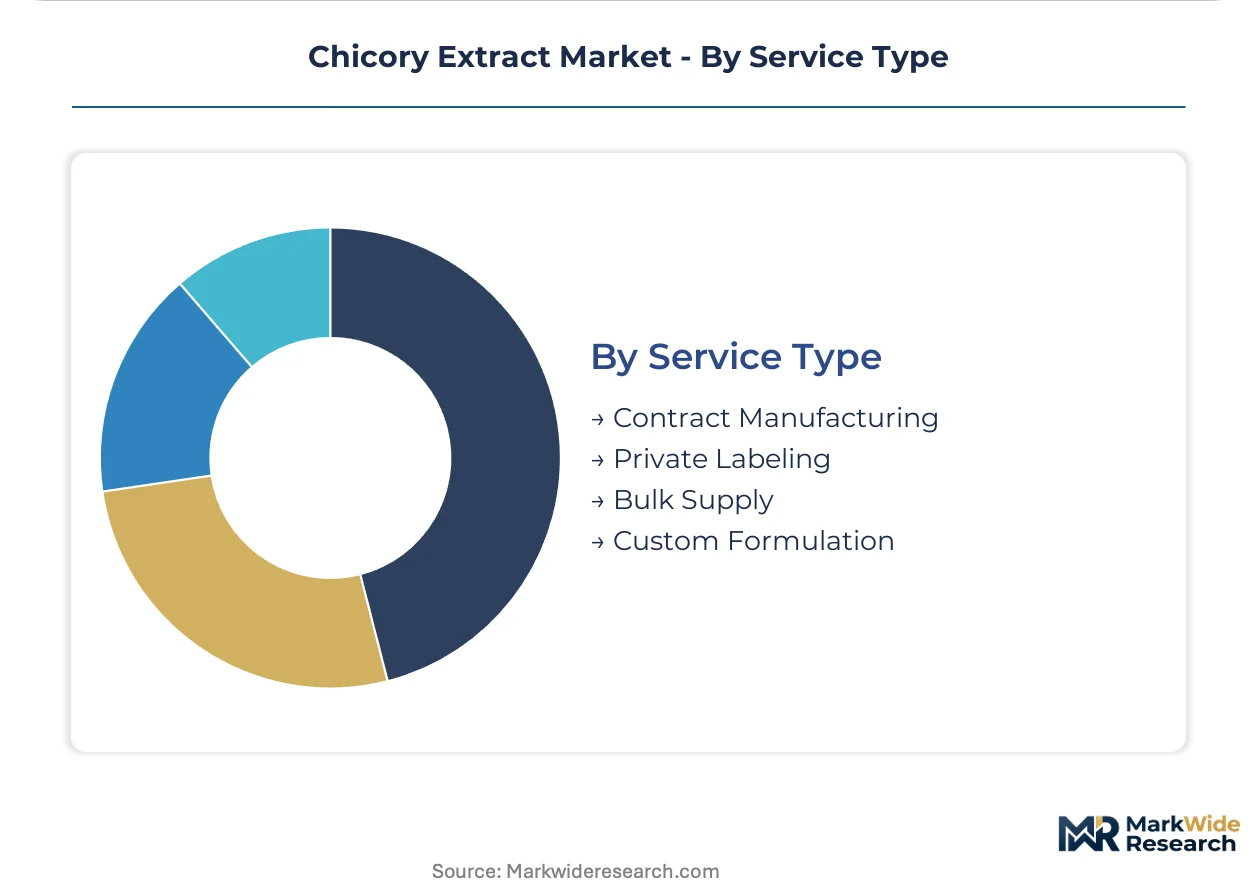
Service Type:
Supply concentration among integrated Belgian and Dutch operators shapes which service tiers remain captive versus outsourced to toll processors.
- Contract Manufacturing:Integrated processors with F-Gas-compliant extraction equipment offer toll processing for brands lacking in-house purification capacity.
- Private Labeling:Finished product packaging and branding services for retailers entering the chicory coffee and supplement segments.
- Bulk Supply:Unbranded inulin and fiber isolates in industrial quantities for food and pharmaceutical manufacturers with internal formulation capabilities.
- Custom Formulation:Application-specific fiber blends and co-processed ingredients developed in partnership with dairy and bakery R&D teams.
Bulk supply anchors current revenue; custom formulation is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands larger inulin procurement volumes than Belgium, though Belgian processors retain tighter integration with cultivation infrastructure. France and the Netherlands occupy intermediate positions with specialized extraction capabilities. The United States and China represent emerging demand centers with divergent regulatory pathways.
Germany
Dairy reformulators and bakery manufacturers drive inulin procurement for sugar-reduced formulations. EFSA prebiotic health claim evaluations under EU Regulation 1924/2006 shape product positioning compliance. Processing clusters in North Rhine-Westphalia and Bavaria host toll extraction facilities serving domestic food manufacturers.
Belgium
Integrated farming and extraction operations anchor European production capacity for high-purity pharmaceutical grades. The F-Gas Regulation pressures processors toward lower-emission extraction equipment retrofits. The Warcoing region maintains captive chicory cultivation supply chains with direct pipeline connections to purification plants.
Netherlands
Mid-sized clean-label brands fragment procurement across multiple suppliers seeking supply security. Dutch processors supply less refined fiber matrices to emerging organic and free-from positioned brands. The North Sea cultivation corridor provides cost-competitive raw material access for regional toll processors.
United States
FDA GRAS status for inulin and oligofructose enables market access but requires adherence to specific purity specifications. Sports nutrition and wellness channels drive emerging demand for prebiotic-fortified protein formats. California and Northeast corridor formulators pilot custom fiber blends for beverage applications.
China
Novel food approval pathways for chicory-derived ingredients remain under regulatory harmonization review. Domestic functional food manufacturers assess import substitution strategies for prebiotic fiber systems. Yangtze River Delta ingredient distributors evaluate partnership structures with European processors.
Chicory Extract Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across extraction and formulation tiers. The vendor base organizes around three strategic archetypes: agricultural trading houses with global sourcing networks, integrated European processors with captive cultivation, and specialized fiber variant developers. Capacity expansion and backward integration into chicory farming represent dominant competitive moves as processors seek supply chain resilience against climate volatility.
Among integrated European processors, Cosucra Groupe Warcoing and BENEO GmbH exemplify the cultivation-anchored archetype with Belgian and German operational footprints respectively. Cargill Incorporated represents the diversified agricultural conglomerate model with multi-region sourcing capabilities. These three entities occupy distinct positioning vectors based on integration depth and product specialization rather than scale alone.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Cosucra Groupe Warcoing |
| BENEO GmbH |
| Starwest Botanicals |
| Delecto Foods Pvt Ltd |
| NP Nutra |
| STOKROS Company Ltd |
| Sensus |
| Leroux |
| Others |
Value Network & Pricing Analysis
Chicory root spot prices in northern European growing zones cascade through extraction economics into three-tier pricing structure across premium, standard, and economy levels. Pharmaceutical-grade inulin isolates command substantial premiums over food-grade fiber matrices, while Belgian and Dutch processors leverage captive cultivation to defend margin positions against toll-dependent competitors.
Pricing Analysis
Capacity additions in Belgium and the Netherlands are reshaping price floors for standard-grade inulin as integrated operators compress extraction economics. Pricing stratifies across premium, standard, and economy tiers based on purity certification and EFSA health claim substantiation status. Cost compression in economy-grade fiber is intensifying because mid-sized clean-label brands fragment procurement across multiple suppliers. Large multinationals consolidating long-term supply agreements exhibit lowest price sensitivity, while emerging organic brands in Germany and the Netherlands drive hardest bargaining.
Supply Chain Analysis
Dual-sourcing requirements from German dairy reformulators and Belgian bakery manufacturers now mandate multi-supplier qualification for critical inulin volumes. Geographic supply concentrates in Belgium, the Netherlands, and northern France, with raw material sourcing anchored in the North Sea cultivation corridor. Extraction capacity hinges on chicory root supply, F-Gas-compliant processing equipment, and specialized technical expertise in membrane filtration systems. Single-source vulnerability persists around high-purity pharmaceutical-grade extraction. Distribution runs through integrated processors for bulk industrial offtake, with toll processors serving fragmented clean-label demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between European processing infrastructure and Asia-Pacific regulatory opening, with novel food approval timelines in China and South Korea creating cost and access differentials against established EU compliance frameworks.
For Market Incumbents: Cement supply security through backward integration into chicory cultivation in climate-resilient growing zones, while retrofitting extraction equipment to meet F-Gas Regulation emission standards before enforcement tightens. Resistant maltodextrin and polydextrose substitution in beverage applications threatens volume retention in cost-sensitive segments. Capacity addition in Belgian processing clusters remains the priority defensive lever.
For New Entrants and Emerging Players: Mid-sized sports nutrition brands seeking prebiotic-fortified protein formats represent an underserved buyer archetype with limited incumbent penetration. White-space targets include custom formulation partnerships for dairy and bakery R&D teams, plus toll processing services for brands lacking in-house purification capacity. The most penetrable entry point sits in oligofructose variants for recovery beverages, with go-to-market through direct technical sales to formulation scientists.
For Investors and Strategic Acquirers: Asymmetric upside sits with integrated European processors possessing captive cultivation and existing EFSA health claim portfolios. Long-term viability over the coming decade favors operators with clinical evidence databases and multi-jurisdiction regulatory approvals already secured. Acquisition target archetype: Belgian or Dutch mid-cap specialists with F-Gas-compliant equipment and established API-grade certification. The signal to watch as inflection indicator is novel food approval acceleration in China and South Korea.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captive chicory root supply secures margin resilience against climate volatility in northern European growing zones. |
| F-Gas Equipment Retrofit | Lower-emission extraction infrastructure preserves market access under tightening EU environmental enforcement. |
| Novel Food Dossier Preparation | Regulatory harmonization efforts in Asia-Pacific jurisdictions unlock geographic expansion for compliant processors. |
| Custom Formulation Partnership | Application-specific fiber blends deepen relationships with dairy and bakery manufacturers reformulating for sugar reduction. |
| Clinical Evidence Portfolio Investment | Human intervention studies demonstrating microbiome effects enable premium EFSA prebiotic health claim positioning. |
Research Methodology
Coverage spans Germany, Belgium, the Netherlands, France, the United States, and China, with primary inputs from each jurisdiction triangulated against secondary validation. Primary interviews engaged extraction plant managers at integrated processors, procurement leads at dairy and bakery manufacturers, regulatory affairs specialists navigating EFSA and FDA pathways, and distribution channel partners serving mid-sized clean-label brands. Secondary sources included EFSA health claim submission databases, FDA GRAS notification filings, EU customs trade data on chicory root and fiber isolates, F-Gas Regulation implementation reports, and SEC filings from diversified agricultural conglomerates. Bottom-up volume modeling across product grades and end-use segments was reconciled with top-down market sizing from trade flow analysis.
Granularity-level modeling captured inulin purity grades from 90% to 99%, chicory root fiber matrices, and roasted derivatives across food and beverage, pharmaceutical, dietary supplement, and animal feed end uses. Segmentation by distribution channel distinguished direct processor relationships from distributor-mediated and online marketplace procurement. CAGRs were derived from trend extrapolation of sugar-reduction mandate implementation, prebiotic claim approval timelines, and cultivation area expansion patterns. Industry-specific forecast inputs included EFSA evaluation queue progress for prebiotic health claims and F-Gas Regulation compliance deadlines affecting extraction capacity.
Underlying measurement precision varies by segment; pharmaceutical-grade inulin with established clinical evidence carries tighter precision than emerging animal feed applications. Forecasts reflect assumptions about regulatory approval trajectories, climate patterns in northern European growing zones, and substitution dynamics from competing fiber systems. Deviation in novel food approval timelines or F-Gas enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Maple Extracts Market
Flavorings and Food Additives
Beverage Flavoring Market
Flavorings and Food Additives
Winter Melon Peel Extract Market
Flavorings and Food Additives
Edible Food Paints Market
Flavorings and Food Additives
Italy Food Colorants Market
Flavorings and Food Additives
France Food Flavor and Enhancer Market
Flavorings and Food Additives
Hops Essential Oil Market
Flavorings and Food Additives
Marshmallow Root Extract Market
Flavorings and Food Additives
Oleoresin Market
Flavorings and Food Additives
1-Decanol Market
Flavorings and Food Additives
Africa Food Flavor Market
Flavorings and Food Additives
Australia Vanilla Flavor Market
Flavorings and Food Additives
Asia-Pacific Food Flavor Market
Flavorings and Food Additives
Global Beverage Flavoring Systems Market
Flavorings and Food Additives
Global Natural Food Flavors Market
Flavorings and Food Additives
Farnesol Market