
 Kokumi Flavor Market | 2026-2036
Kokumi Flavor Market Size, Share, and Industry Trends Forecast 2026-2036
Kokumi Flavor Market Analytics
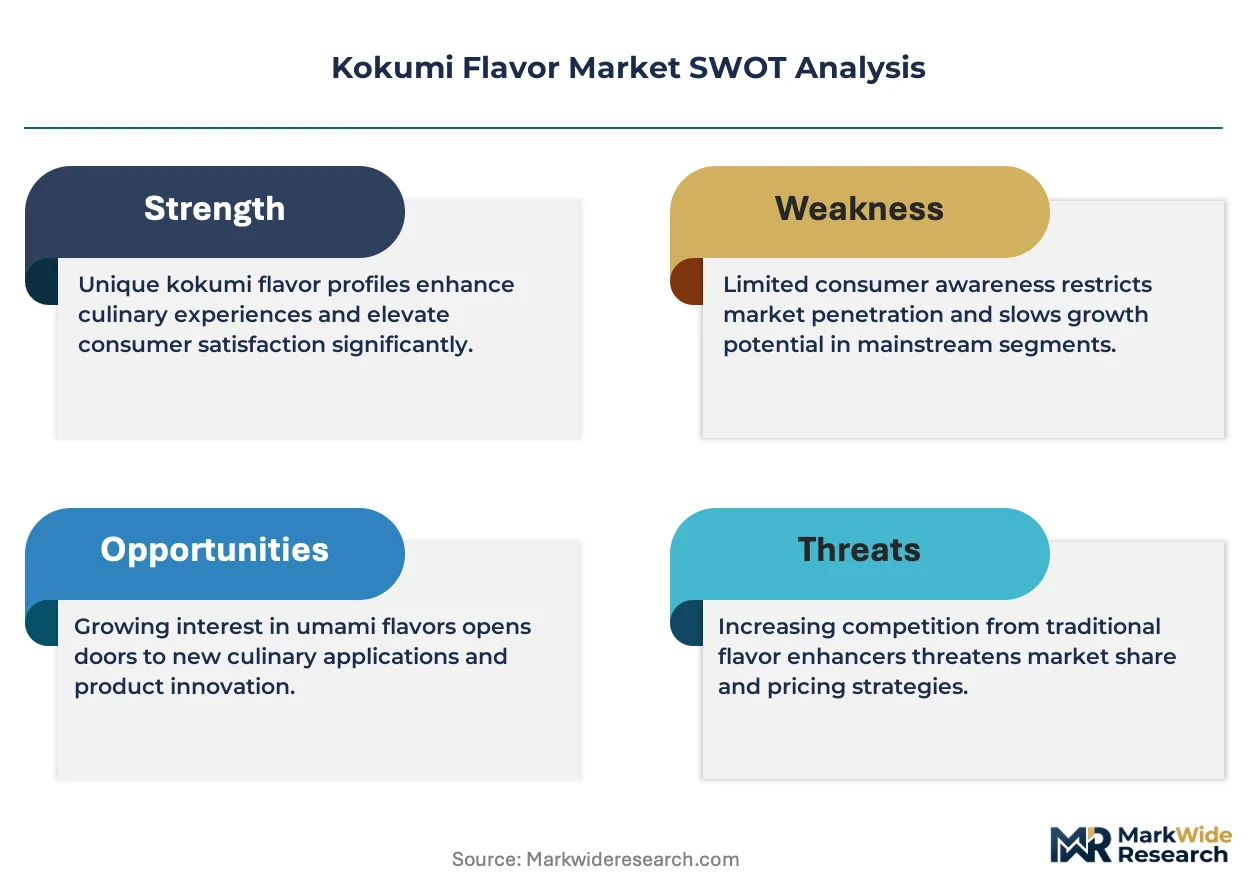
Flavor-as-a-service subscription models for recurring formulation updates is recalibrating how kokumi compounds reach commercial kitchens and industrial R&D labs. Ajinomoto Co. Inc. leverages its peptide synthesis expertise to anchor supply for savory enhancement applications across Asia. DSM-Firmenich sustains competitive positioning through integrated biotechnology platforms that reduce batch-to-batch variability in kokumi-active compounds. Kerry Group plc differentiates via controlled-release encapsulation systems that extend kokumi perception duration in processed foods.
Kokumi refers to taste-active compounds—primarily glutathione and specific γ-glutamyl peptides—that generate mouthfulness, continuity, and thickness perception without contributing dominant flavor notes themselves. These molecules typically function at concentrations below standard taste thresholds, requiring precision fermentation or enzymatic hydrolysis of yeast or vegetable proteins for commercial production. Seasonings and sauces represent the established revenue base where kokumi integration is now standard practice, while health supplements emerge as the fastest-growing application segment as consumers seek functional savory alternatives to sodium-heavy formulations. Powder forms dominate manufacturing logistics for dry-blend operations, though liquid concentrates capture premium margins in culinary arts and high-end restaurant supply chains.
Japan's Ministry of Health, Labour and Welfare FOSHU system and the FDA's GRAS self-affirmation pathway collectively shape market access timelines and label claim permissibility for kokumi ingredients in their respective jurisdictions. EFSA's evolving stance on peptide-based flavor modulators under the EU Flavouring Regulation influences reformulation strategies for exporters targeting European food manufacturers. Stakeholders must monitor regulatory divergence between Japan's explicit functional food categories and the United States' broader GRAS framework when allocating R&D resources across geographic portfolios.
Market Dynamics
Precision fermentation scale-up is compressing production costs for γ-glutamyl peptides while Japan's FOSHU framework accelerates functional food formulation approvals, creating dual momentum for kokumi ingredient commercialization.
Growth Catalysts
- Enzymatic Hydrolysis Advancement:Novel protease cocktails from fungal sources reduce peptide extraction cycles by half, enabling cost-competitive supply for mid-tier sauce manufacturers in Thailand and Vietnam.
- Clean-Label Sodium Reduction Mandates:Health Canada and FDA sodium targets in processed foods are pulling kokumi compounds into reformulated soups and ready meals as flavor-compensating agents.
- East Asian Culinary Premiumization:High-end restaurant chains in Seoul and Singapore deploy liquid kokumi concentrates to differentiate umami-forward tasting menus.
Market Restraints
- Yeast Protein Feedstock Volatility:Saccharomyces cerevisiae biomass prices fluctuate with bioethanol co-product markets, squeezing margins for peptide fermenters.
- Peptide Stability Limitations:Glutathione degrades under thermal processing above 80°C, restricting application in retort-pouched meals and UHT dairy.
- EFSA Regulatory Uncertainty:Pending classification of γ-glutamyl peptides under EU Flavouring Regulation (EC) No 1334/2008 delays market entry for European food manufacturers.
Strategic Opportunities
- Plant-Based Meat White Space:Pea and fava protein hydrolysates offer underexploited kokumi precursor streams for alt-meat texture enhancement in German and Dutch formulations.
- Direct-to-Chef Distribution Channels:Specialty foodservice platforms bypass traditional ingredient distributors, capturing premium pricing from Michelin-tier kitchens in Paris and New York.
- South Korean Functional Food Incentives:MFDS streamlined health claim pathways accelerate kokumi-fortified positioning in aging-population targeted products.
Industry Challenges
- Peptide Analytical Capability Scarcity:Commercial labs with LC-MS/MS quantification expertise for γ-glutamyl dipeptides remain concentrated in Japan and Switzerland, creating QC bottlenecks.
- Batch-to-Batch Sensory Variability:Enzymatic hydrolysis produces heterogeneous peptide profiles, requiring costly sensory calibration for each production lot.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kokumi Flavor Market |
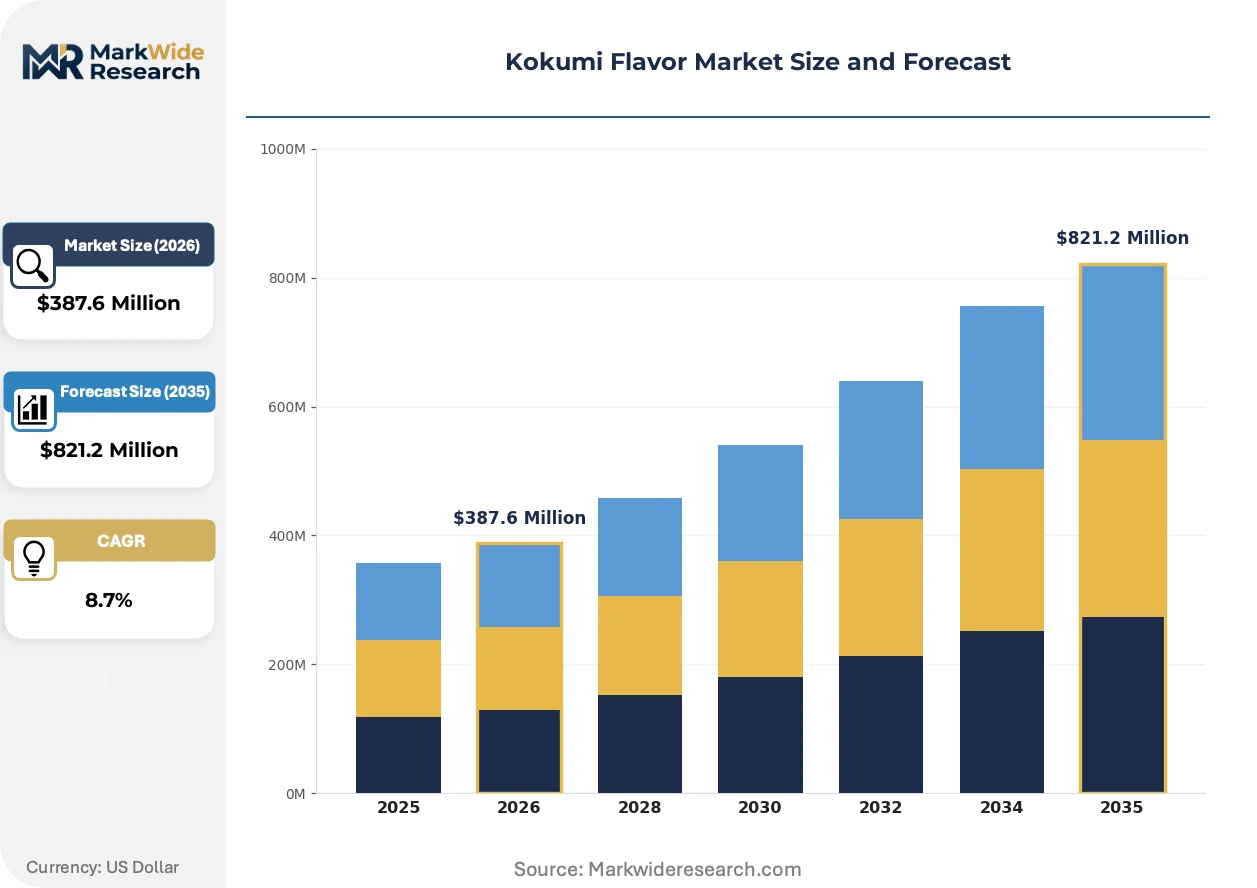
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seasonings, Sauces, Snack Foods, Beverages Application: Food Processing, Ready-to-Eat Meals, Culinary Arts, Health Supplements End User: Food Manufacturers, Restaurants, Catering Services, Retailers Form: Liquid, Powder, Granular, Paste |
| Companies Covered | International Flavors & Fragrances Inc., Takasago International Corporation, Ajinomoto Co. Inc., Nikken Foods, T. Hasegawa, Givaudan, DSM-Firmenich, Archer Daniels Midland Company, Kerry Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kokumi Flavor Market Evolving Landscape
Biotechnology platforms and regulatory recalibration are compressing development timelines while demand-side purchasing power consolidates around functional positioning claims.
Continuous fermentation systems using cell-retention perfusion bioreactors are converging with automated metabolite monitoring to enable real-time γ-glutamyl peptide titer optimization. Contract manufacturers in Denmark and the Netherlands deploy these integrated platforms to serve mid-sized European sauce producers. The technology is converging with quality-by-design protocols that reduce release testing burdens and accelerate customer onboarding cycles.
Japan's FOSHU system expansion to include oral processing-related functional claims creates explicit regulatory space for kokumi ingredients in thickness-perception positioning. PMDA guidance documents clarify peptide stability data requirements, reducing submission preparation timelines for domestic applicants. Domestic seasoning houses leverage this clarity to front-load R&D pipelines ahead of anticipated South Korean and Taiwanese regulatory harmonization.
Foodservice procurement teams now specify kokumi-active compound certificates of analysis as standard tender requirements, displacing informal supplier relationships. Large contract catering operators in Singapore and Hong Kong centralize purchasing through approved vendor lists with peptide specification compliance. This pattern concentrates volume with fermentation houses demonstrating consistent analytical documentation.
Kokumi Flavor Market Segmentation
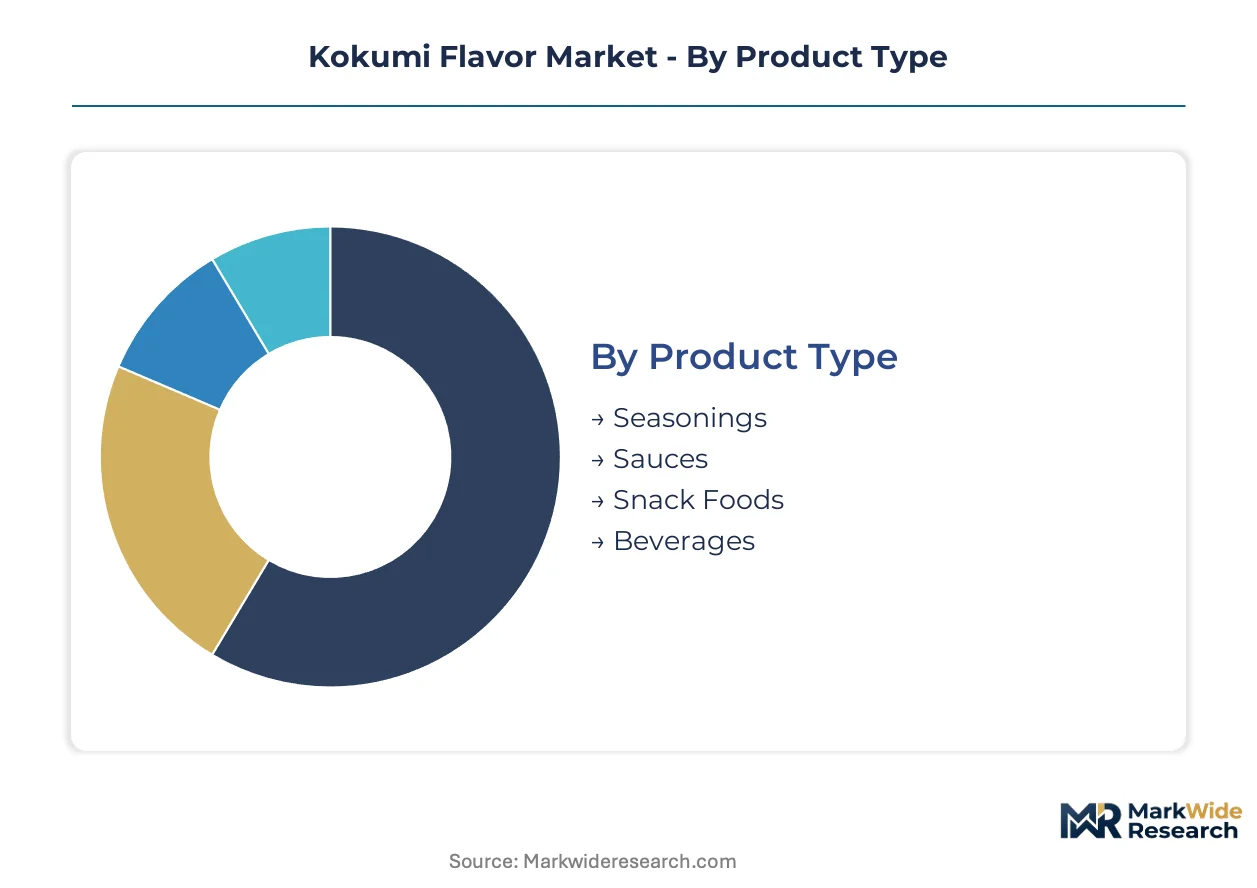
Kokumi compounds deploy differently across standalone flavor systems versus embedded processing applications, with integration depth determining specification requirements and margin capture. Manufacturers calibrate peptide concentrations and delivery formats based on whether kokumi serves as a primary positioning claim or a background texture modifier.
Product Type:
Standalone kokumi positioning dominates in formats where savory depth functions as the core value proposition, while embedded applications treat peptides as supporting cast in complex flavor architectures.
- Seasonings:Dry-blend spice mixes incorporate γ-glutamyl peptides at 0.1-0.5% loading to amplify umami continuity without sodium spike. Japanese seasoning houses in Chiba and Osaka prefectures drive formulation standardization for export markets.
- Sauces:Soy-based and tonkatsu sauce categories integrate liquid kokumi concentrates during thermal processing, though glutathione degradation above 80°C forces cold-fill or post-pasteurization addition protocols. Thai and Vietnamese manufacturers prioritize this segment for mid-tier export growth.
- Snack Foods:Extruded and coated applications require encapsulated peptide forms to survive high-temperature processing; powder dominates seasoning drum operations.
- Beverages:Functional savory drinks and broth-based RTDs represent emerging territory with limited current commercial traction.
Seasonings lead volumes today; sauces are gaining share fastest.
Application:
Cost-tier stratification separates mass-market processing from premium culinary deployment, with health positioning commanding formulation premiums.
- Food Processing:Industrial sauce and soup manufacturers embed kokumi for sodium reduction compliance under FDA and Health Canada targets. Enzymatic hydrolysis supply chains in Denmark and the Netherlands serve mid-tier European processors.
- Ready-to-Eat Meals:Retort pouch and chilled meal formats face thermal stability constraints; glutathione loss during sterilization limits peptide efficacy. Japanese FOSHU-approved functional meal lines circumvent this through post-processing addition.
- Culinary Arts:Michelin-tier kitchens in Paris and New York source liquid concentrates through specialty distribution, paying 3-4x manufacturing cost for provenance documentation and batch consistency certificates.
- Health Supplements:Capsule and functional food formats leverage Japan's FOSHU thickness-perception claims for aging-population targeting. MFDS in South Korea is streamlining parallel pathways.
Food processing anchors current revenue; health supplements climb the fastest.
End User:
Customer-type concentration shapes procurement sophistication, with centralized purchasing demanding analytical documentation that fragmented buyers rarely specify.
- Food Manufacturers:Large seasoning and sauce houses in Japan, Thailand, and Vietnam negotiate multi-year peptide supply agreements with fermentation houses demonstrating LC-MS/MS batch certification.
- Restaurants:High-end chains in Seoul and Singapore specify kokumi-active compound certificates as tender requirements, displacing informal supplier relationships.
- Catering Services:Singapore and Hong Kong contract catering operators centralize purchasing through approved vendor lists with peptide specification compliance.
- Retailers:Private-label development teams at premium grocery chains in urban Japan experiment with kokumi-positioned soup and sauce lines.
Food manufacturers dominate procurement volumes; restaurants expand most quickly.
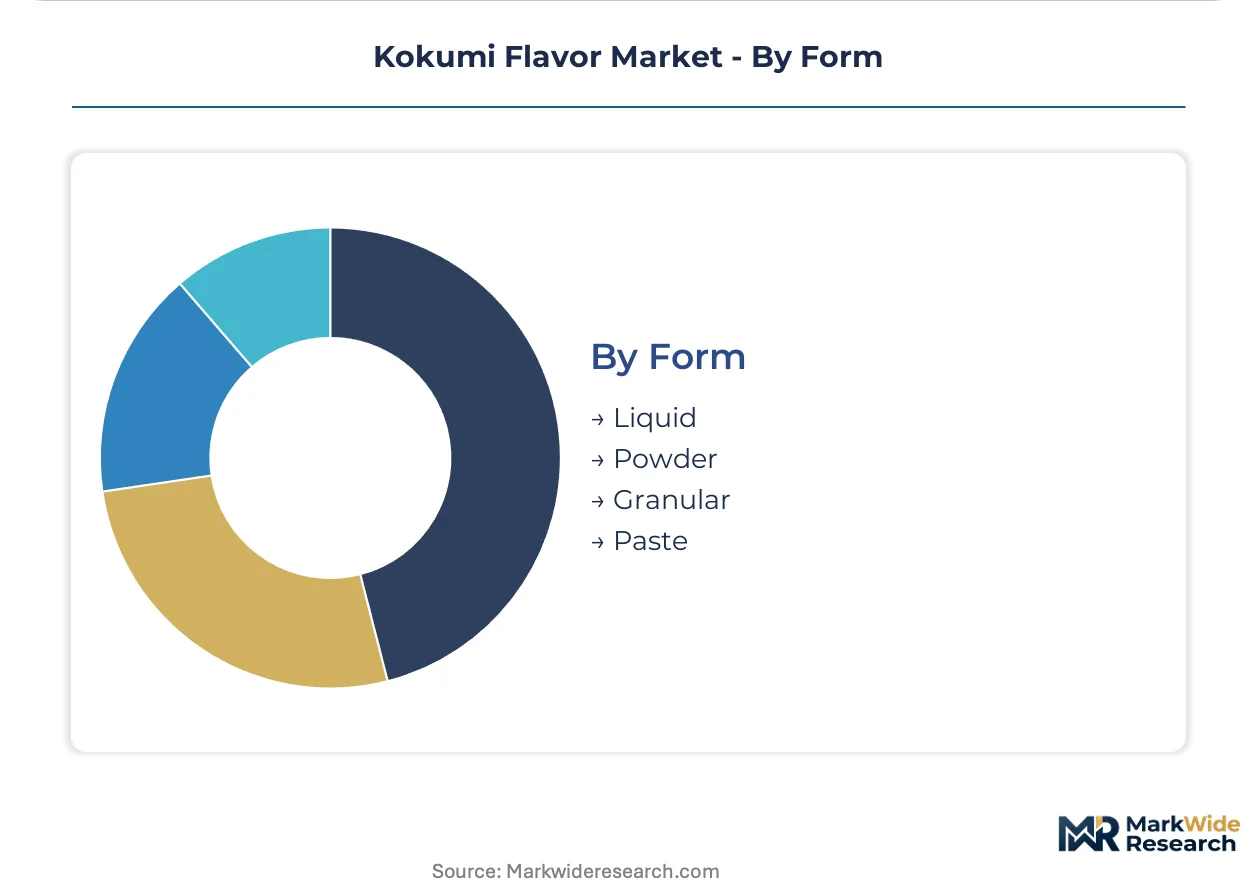
Form:
Manufacturing logistics and thermal processing requirements dictate format selection, with stability-margin tradeoffs determining commercial viability.
- Powder:Spray-dried peptide fractions dominate dry-blend operations for seasoning and soup base manufacturing; bulk logistics favor this format for mid-tier sauce producers.
- Liquid:Aqueous concentrates capture premium margins in culinary arts and high-end restaurant supply chains where dissolution speed and dosing precision matter.
- Granular:Agglomerated forms improve flow properties for automated seasoning equipment in snack food processing lines.
- Paste:High-solids formulations serve niche applications in traditional miso and fermented seasoning bases where moisture content aligns with existing process parameters.
Powder leads manufacturing volumes; liquid expands fastest in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is pulling kokumi peptide production toward jurisdictions with explicit functional food frameworks, as Japan's FOSHU approval costs and timelines diverge sharply from the United States' GRAS self-affirmation pathway. Manufacturers calibrate facility investments against these compliance cost differentials.
Japan
Japan's Ministry of Health, Labour and Welfare FOSHU system anchors the world's most mature kokumi regulatory pathway, with thickness-perception claims now explicitly permissible. PMDA guidance documents reduce peptide stability data preparation timelines for domestic applicants. Chiba and Osaka prefectures concentrate seasoning house R&D pipelines leveraging this clarity.
United States
FDA GRAS self-affirmation allows faster market entry for yeast-derived γ-glutamyl peptides without pre-market notification burdens. Sodium reduction mandates under FDA processed food targets pull kokumi into reformulated soups and ready meals. Chicago and New Jersey industrial corridors host mid-tier sauce manufacturers adopting enzymatic hydrolysis supply chains.
South Korea
MFDS streamlined health claim pathways accelerate kokumi-fortified positioning in aging-population targeted products. Domestic functional food incentives reduce submission preparation costs versus Japanese FOSHU equivalents. Seoul metropolitan area high-end restaurant chains specify kokumi-active compound certificates as tender requirements.
Germany
EFSA's pending classification of γ-glutamyl peptides under EU Flavouring Regulation (EC) No 1334/2008 delays market entry, creating regulatory uncertainty for exporters. Danish and Dutch contract manufacturers deploy continuous fermentation platforms to serve mid-sized European sauce producers. Bavaria and North Rhine-Westphalia clusters experiment with pea and fava protein hydrolysates for alt-meat applications.
Singapore
Urban foodservice procurement centralization concentrates volume with fermentation houses demonstrating consistent LC-MS/MS analytical documentation. Large contract catering operators maintain approved vendor lists with peptide specification compliance. The city-state functions as a distribution hub for liquid kokumi concentrates reaching Michelin-tier kitchens across Southeast Asia.
Kokumi Flavor Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with fermentation houses commanding premium pricing in culinary arts while enzymatic hydrolysis suppliers capture mid-tier sauce volumes. The vendor base organizes around three strategic archetypes: integrated biotechnology platforms, peptide synthesis specialists, and controlled-release encapsulation providers. Dominant competitive moves include precision fermentation scale-up investments and geographic expansion into South Korean functional food channels.
Within the biotechnology platform tier, DSM-Firmenich and Ajinomoto Co. Inc. occupy positions representing integrated fermentation and peptide synthesis expertise respectively. Kerry Group plc exemplifies the encapsulation specialist archetype. These three companies anchor competitive dynamics across Asia-Pacific and European supply chains, with their geographic origins and corporate structures reflecting divergent strategic foundations in Dutch-Swiss integration, Japanese amino acid heritage, and Irish-British ingredient systems.
| Leading Market Players |
|---|
| International Flavors & Fragrances Inc. |
| Takasago International Corporation |
| Ajinomoto Co. Inc. |
| Nikken Foods |
| T. Hasegawa |
| Givaudan |
| DSM-Firmenich |
| Archer Daniels Midland Company |
| Kerry Group plc |
| Others |
Value Network & Pricing Analysis
Yeast protein feedstock costs cascade through kokumi peptide manufacturing tiers, with Saccharomyces cerevisiae biomass price swings from bioethanol co-product markets compressing margins for mid-tier sauce producers in Thailand and Vietnam while premium liquid concentrate suppliers to Michelin-tier kitchens in Paris and New York capture 3-4x manufacturing cost markups through provenance documentation.
Pricing Analysis
Distributor margin layers separate fermentation houses from end-formulators, with three-tier pricing structure across premium, standard, and economy levels anchored by LC-MS/MS batch certification quality. Premium tier pricing draws from Japan's FOSHU thickness-perception claim validation, while standard tier faces cost compression from enzymatic hydrolysis supply chain expansion in Denmark and the Netherlands. Price differentiation hinges on peptide stability documentation and thermal processing compatibility. Food manufacturers in Japan and South Korea exhibit lowest price sensitivity due to functional food claim premiums, whereas mid-tier sauce producers in Southeast Asia prioritize cost-per-kilogram metrics.
Supply Chain Analysis
Regional distribution centers in Singapore and Hong Kong function as hub-and-spoke patterns for liquid kokumi concentrates reaching Southeast Asian foodservice operators. Manufacturing gravity centers on Japan, Denmark, and the Netherlands, with Chiba and Osaka prefectures anchoring precision fermentation capacity for γ-glutamyl peptides. Raw material dependencies include Saccharomyces cerevisiae biomass, fungal protease enzymes, and pea protein hydrolysate streams for alt-meat applications. Single-source vulnerability concentrates in peptide analytical capability, with LC-MS/MS quantification expertise limited to laboratories in Japan and Switzerland. Distribution runs through approved vendor lists maintained by large contract catering operators demanding consistent analytical documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in precision fermentation scale-down economics and FOSHU-claim premium capture, with continuous bioreactor technology reducing batch-to-batch variability costs for peptide suppliers.
For Market Incumbents: Lock in multi-year peptide supply agreements with seasoning houses in Chiba and Osaka prefectures before South Korean and Taiwanese regulatory harmonization expands competitor access. Defend positioning through captive LC-MS/MS analytical capability investment, addressing the QC bottleneck that constrains mid-tier competitors. Prioritize controlled-release encapsulation R&D to circumvent glutathione thermal degradation above 80°C, opening retort-pouch and UHT dairy applications currently restricted to post-processing addition protocols. For New Entrants and Emerging Players: Begin with plant-based meat white space in German and Dutch formulations, where pea and fava protein hydrolysates offer underexploited kokumi precursor streams for texture enhancement. Target direct-to-chef distribution channels bypassing traditional ingredient distributors, capturing premium pricing from specialty foodservice platforms serving Michelin-tier kitchens. Deploy provenance documentation and batch consistency certificates as primary go-to-market angle, mirroring incumbent positioning in culinary arts segments. For Investors and Strategic Acquirers: Consolidation pressure builds where batch-to-batch sensory variability creates customer churn risk for mid-tier enzymatic hydrolysis suppliers lacking quality-by-design protocols. Long-term viability favors fermentation houses with integrated continuous bioreactor platforms and automated metabolite monitoring capabilities. Acquisition target archetype: European contract manufacturers in Denmark and the Netherlands serving mid-sized sauce producers with demonstrated LC-MS/MS batch certification. Signal to watch: EFSA classification resolution for γ-glutamyl peptides under EU Flavouring Regulation (EC) No 1334/2008, which would unlock European market entry and trigger geographic expansion investments.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Continuous perfusion bioreactor deployment reduces γ-glutamyl peptide production costs for mid-tier manufacturers. |
| FOSHU Regulatory Expansion | Japan's thickness-perception claim pathway creates explicit positioning space for functional food formulations targeting aging populations. |
| Controlled-Release Encapsulation | Kerry Group's thermal protection systems extend kokumi perception duration in high-temperature processed foods. |
| Direct-to-Chef Distribution | Specialty foodservice platforms bypass traditional distributors, capturing premium margins from Michelin-tier kitchens. |
| Plant-Based Protein Hydrolysates | Pea and fava protein streams offer alternative kokumi precursors for alt-meat texture enhancement in European formulations. |
Research Methodology
Direct dialogue with fermentation house technical directors, seasoning house R&D leads, foodservice procurement managers, and regulatory affairs specialists at Japan's PMDA and South Korea's MFDS grounded qualitative findings. Secondary validation drew from FOSHU approval databases, FDA GRAS notifications, EFSA scientific opinions on peptide-based flavor modulators, and customs trade data for yeast protein feedstock flows. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Segment-level outputs across product type, application, end user, and form dimensions integrated with geographic regulatory cluster variations to generate CAGRs. The analytical framework incorporated precision fermentation yield curves, enzymatic hydrolysis cycle time improvements, and FOSHU submission timeline distributions as industry-specific forecast inputs. Value projections reflected peptide concentration specifications and delivery format premium differentials.
Several conditions sit outside the modeled scope, including pending EFSA classification outcomes, Saccharomyces cerevisiae biomass price volatility from bioethanol market fluctuations, and thermal stability breakthroughs for glutathione compounds. Forecasts reflect documented assumptions around regulatory pathway timelines and peptide analytical capability expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Cocoa Extract Market
Flavorings and Food Additives
Seaweed Flavor Market
Flavorings and Food Additives
Flavor Compounds Market
Flavorings and Food Additives
Flavor and Flavor Enhancers Market
Flavorings and Food Additives
Cheese Flavor Market
Flavorings and Food Additives
Russia Food Colorants Market
Flavorings and Food Additives
Citrus Oil Market
Flavorings and Food Additives
Pumpkin Spice Products Market
Flavorings and Food Additives
Citrus Flavors Market
Flavorings and Food Additives
Orange Peel Extract Market
Flavorings and Food Additives
Citrus-Based Sugar-Reduction Flavor Modulators Market
Flavorings and Food Additives
Food Flavors & Flavor Enhancers Market
Flavorings and Food Additives
Asia-Pacific Vanilla Beans and Extract Market
Flavorings and Food Additives
Food Texturizers Market
Flavorings and Food Additives
Dairy Flavors Market
Flavorings and Food Additives
Chicory Extract Market