
 Japan Food Flavor and Enhancer Market | 2026-2036
Japan Food Flavor and Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Food Flavor and Enhancer Market Outlook
Convenience-oriented food manufacturers is unwinding share from traditional restaurant suppliers as at-home consumption patterns persist. Ajinomoto Co., Inc. leverages its amino acid science heritage to dominate savory enhancer formulations. T. Hasegawa Co., Ltd. anchors premium natural flavor development for bakery and confectionery clients. Takasago International Corporation competes through biotechnology-driven fermentation processes that yield consistent botanical extracts.
Food flavor and enhancer systems comprise volatile aromatic compounds, taste-active molecules, and carrier substrates engineered to deliver specific sensory profiles at precise dosage thresholds, typically measured in parts per million for high-potency ingredients. These formulations serve to standardize palatability across processed food production batches while masking off-notes from reduced-sodium or reduced-fat reformulations. Natural flavors commands premium positioning as FSSAI-aligned clean-label expectations permeate Japanese retail channels, while flavor enhancers extract margin from umami-intensive applications in broths and seasonings. Liquid form leads volume throughput for beverage and sauce integration, though powder formats gain traction in snack seasoning lines seeking extended shelf stability.
PMDA oversight of novel food ingredient safety, METI enforcement of Food Labeling Standards, and JIS quality benchmarks collectively elevate compliance costs for imported flavor compounds while privileging domestic formulation expertise. These frameworks compel foreign suppliers to establish local testing partnerships or reformulate to pre-approved substance lists. Stakeholders must monitor pending amendments to genetically modified microorganism disclosure rules that could redirect R&D investment toward classical extraction methods.
Market Dynamics
METI's Food Labeling Standards revisions are compressing formulation timelines for clean-label flavor systems. Ready-to-eat meal manufacturers now face accelerated disclosure obligations that privilege domestic R&D capabilities.
Growth Catalysts
- Clean-label reformulation mandates:METI disclosure rules compel manufacturers to source transparent flavor systems. This regulatory pressure accelerates demand for naturally derived aromatic compounds in processed foods.
- Umami-intensive application expansion:Broth and seasoning manufacturers are intensifying purchases of amino acid-based enhancers. This end-use vertical drives volume concentration in savory flavor categories.
- Kanto processing cluster density:Tokyo's food manufacturing concentration creates procurement efficiencies. Flavor suppliers co-locate technical service teams to support just-in-time integration.
Market Restraints
- Import compliance cost escalation:PMDA novel ingredient safety reviews and JIS quality benchmarks elevate testing expenditures for foreign flavor compounds. This regulatory friction limits supplier diversification.
- Natural extract supply volatility:Botanical raw material sourcing faces agricultural yield fluctuations. Fermentation-derived alternatives remain capacity-constrained for premium applications.
- Classical extraction R&D redirection:Pending genetically modified microorganism disclosure amendments threaten biotechnology investments. Developers face stranded innovation risk in fermentation platforms.
Strategic Opportunities
- Kansai underpenetration:Osaka-Kobe food processing corridors offer expansion headroom beyond Kanto saturation. Regional flavor preferences diverge toward bolder savory profiles.
- Reduced-sodium masking systems:Sodium reduction mandates in processed foods create demand for off-note masking technologies. Flavor houses can capture value from salt-reformulation partnerships.
- Extended shelf-life powder formats:Snack seasoning lines are converting from liquid to powder systems. This format shift enables new distribution through regional co-manufacturing networks.
Industry Challenges
- Fermentation microbiology talent scarcity:Biotech-driven flavor extraction requires specialized metabolic engineering expertise. Japanese universities produce limited graduates in industrial microbiology.
- Clean-label certification timeline compression:METI disclosure deadlines compress third-party verification cycles. Formulators face batch approval bottlenecks during peak product launch windows.
- Legacy liquid system integration friction:Powder format adoption requires capital reconfiguration of existing seasoning lines. Mid-size manufacturers defer equipment conversion amid margin pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Food Flavor and Enhancer Market |
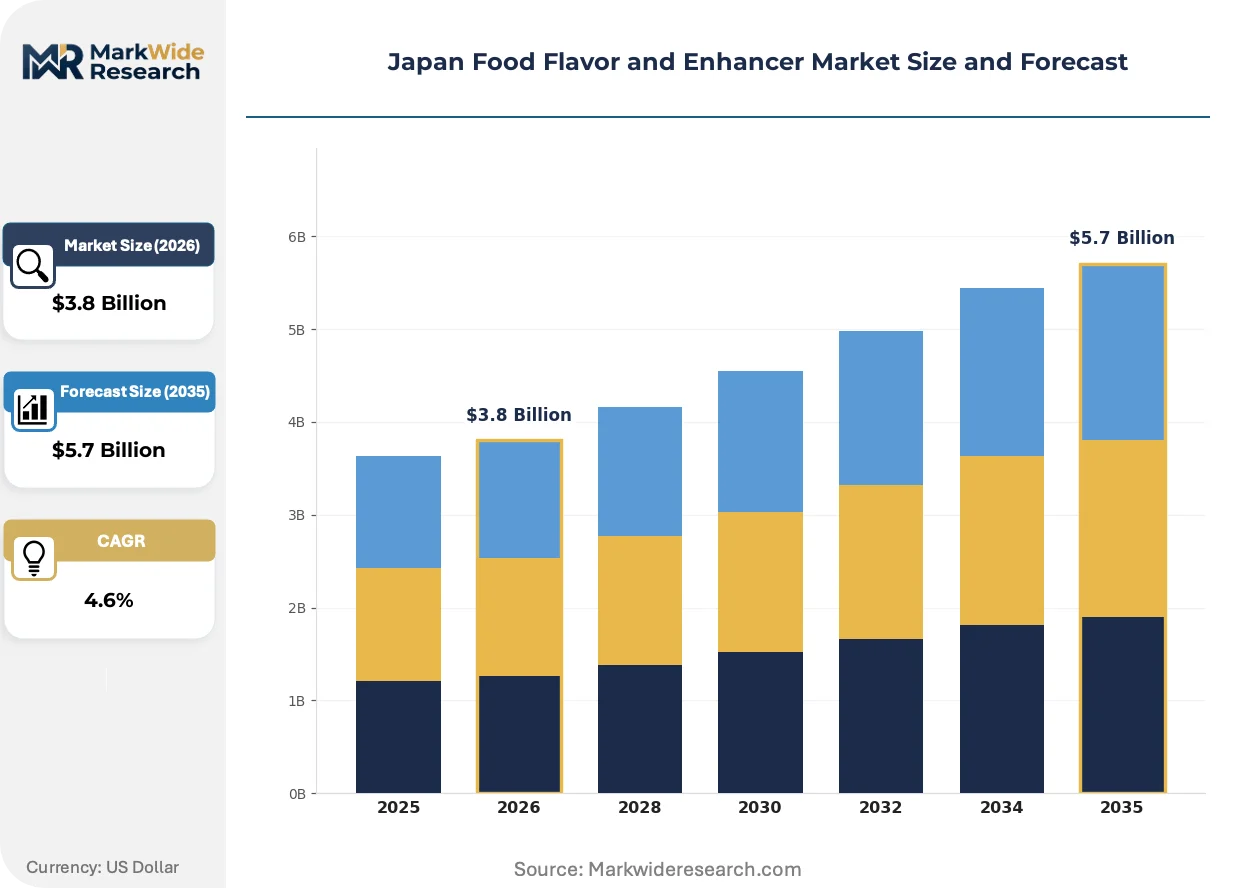
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Artificial Flavors, Flavor Enhancers, Seasonings Application: Bakery, Beverages, Dairy, Snacks Form: Liquid, Powder, Granular, Paste End User: Food Manufacturers, Restaurants, Supermarkets, Retailers |
| Companies Covered | Symrise AG, Firmenich SA, Ajinomoto Co., Inc., Mane Group, Kikkoman Corporation, Takasago International Corporation, International Flavors and Fragrances Inc., T. Hasegawa Co., Ltd., Givaudan SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Food Flavor and Enhancer Market Strategic Shifts
Biotechnology platforms are reconfiguring competitive advantage in botanical flavor extraction. Regulatory disclosure requirements and at-home consumption patterns are simultaneously reshaping formulation priorities.
Precision fermentation for botanical extracts is displacing solvent-based extraction for high-value aromatic compounds. Premium confectionery and bakery manufacturers are adopting these biotech-derived flavors at accelerated procurement cycles. This technology shift compresses cost structures for natural-positioned products while constraining traditional extraction capacity investments.
METI's additive disclosure amendments are tightening label transparency obligations for processed food manufacturers. Industrial consequence includes reformulation sprint cycles and accelerated domestic testing partnerships. Savory enhancer categories face the steepest compliance burden as umami-active compounds attract heightened scrutiny.
Direct technical service engagement is supplanting distributor-mediated flavor procurement. Large ready-to-eat meal manufacturers now require embedded formulation support at production facilities. This channel compression concentrates purchasing power with suppliers maintaining Kanto-based application laboratories.
Japan Food Flavor and Enhancer Market Segmentation
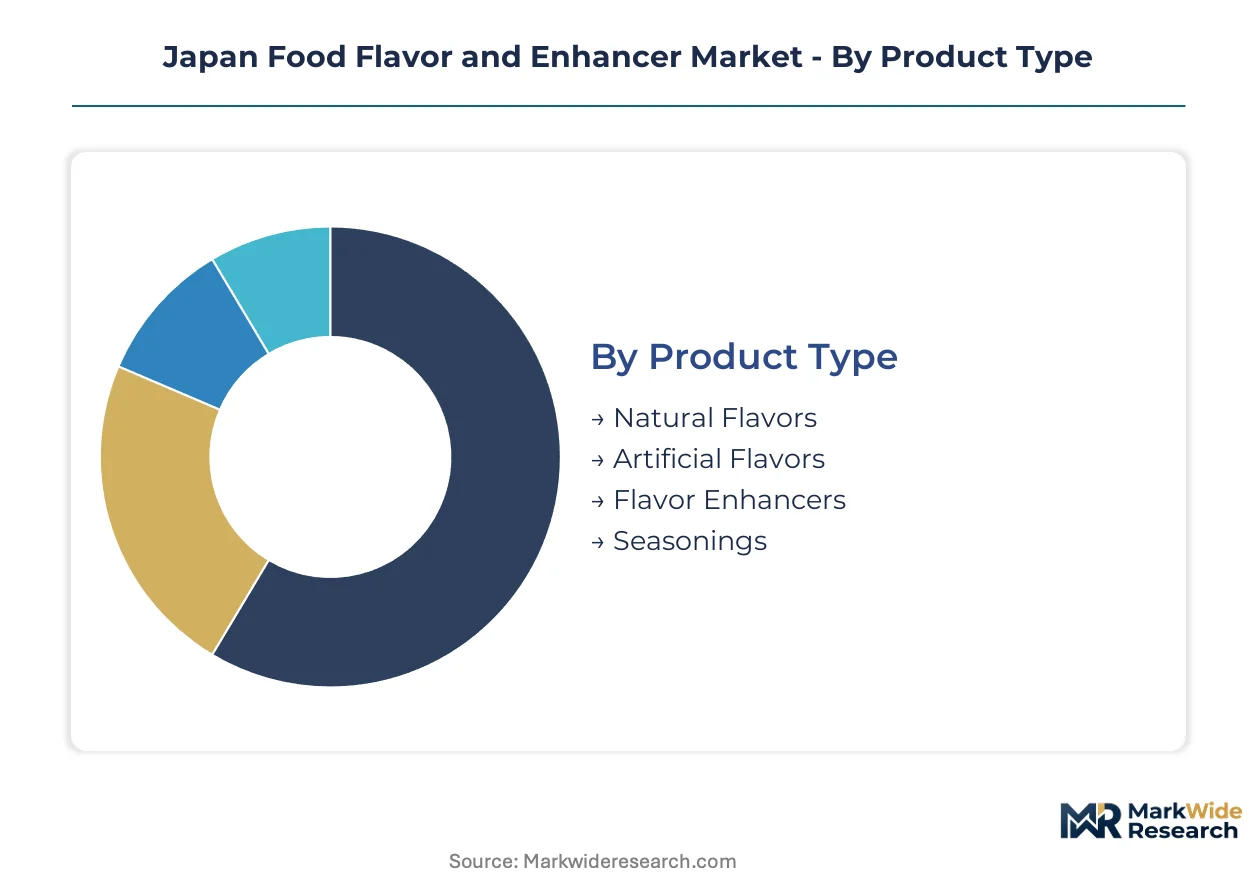
Flavor and enhancer procurement patterns diverge sharply across product chemistry, application requirements, and end-user scale. Segmentation reveals where METI compliance costs concentrate and which formats command technical service investment from suppliers.
Product Type:
Natural flavors draw disproportionate domestic R&D investment as export-oriented manufacturers seek JIS-compliant positioning for Asian retail markets. Artificial flavors and enhancers serve cost-sensitive processed food segments with shorter reformulation cycles.
- Natural Flavors:Botanical and fermentation-derived aromatic compounds meeting FSSAI-aligned clean-label specifications. Tokyo-based confectionery and premium sauce manufacturers concentrate procurement here, pressured by METI disclosure deadlines for additive transparency.
- Artificial Flavors:Synthetic aromatic molecules engineered for thermal stability in high-temperature processing. Mid-size snack and instant noodle producers in Osaka-Kobe corridors rely on these for cost-controlled umami delivery.
- Flavor Enhancers:Amino acid-based taste activators, predominantly glutamates and nucleotides. Broth manufacturers and seasoning compounders drive volume through savory-intensive applications.
- Seasonings:Blended flavor systems incorporating enhancers, aromatics, and carrier substrates. Retail-ready meal kit suppliers source these for standardized home-cooking solutions.
Natural flavors holds the largest share; momentum sits with flavor enhancers.
Application:
End-use concentration determines technical service intensity from Kanto-based flavor houses. Bakery and beverage segments lead natural flavor adoption, while snacks and dairy balance cost against clean-label positioning.
- Bakery:Heat-stable vanilla, butter, and fruit profiles formulated for Maillard reaction compatibility. Premium Tokyo confectioners drive demand for precision fermentation-derived alternatives to solvent-extracted botanicals.
- Beverages:Water-soluble aromatic systems with acid stability for carbonated and still drinks. Major bottlers in Saitama and Chiba prefectures require rapid batch approval cycles under compressed METI timelines.
- Dairy:Fat-compatible flavor carriers masking off-notes in reduced-fat yogurts and desserts. Hokkaido processing clusters source these for export-oriented production.
- Snacks:Powder-format savory coatings with extended shelf-life stability. Regional manufacturers in Nagoya and Fukuoka are converting liquid seasoning lines to dry systems.
Beverage applications command the steepest compliance investment; snack seasoning shows the fastest volume expansion trajectory.
Form:
Physical format selection shapes supply chain configuration and equipment capital requirements. Liquid systems dominate established beverage and sauce operations, while powder and granular formats gain traction in shelf-stable categories.
- Liquid:Pumpable aromatic concentrates with standardized viscosity for automated dosing. Major ready-to-eat meal plants in Kanagawa prefecture rely on bulk tanker delivery with just-in-time inventory.
- Powder:Spray-dried or plated flavor systems with low water activity for extended stability. Snack seasoning compounders in Gunma and Tochigi prefectures are accelerating line conversions from liquid.
- Granular:Agglomerated particles balancing solubility with flow characteristics. Instant soup and broth manufacturers favor these for controlled dissolution rates.
- Paste:High-viscosity concentrates for bakery and confectionery cream fillings. Artisan-scale producers in Kyoto and Kobe source these for premium positioning.
Liquid formats retain volume leadership; powder systems are climbing the fastest.
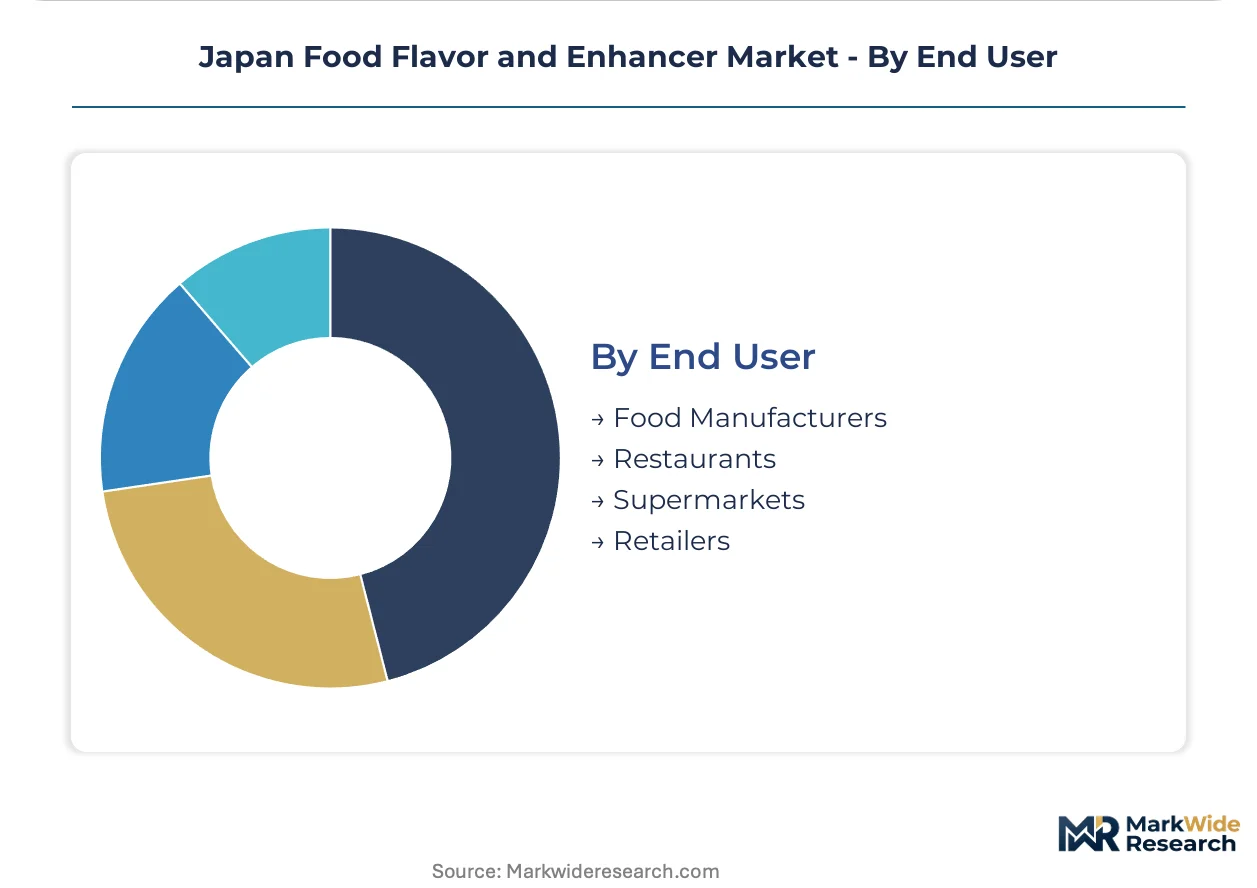
End User:
Procurement scale and technical service expectations fragment sharply across customer types. Food manufacturers consolidate purchasing power through embedded formulation partnerships, while retail channels demand shorter lead times for private-label development.
- Food Manufacturers:Large-scale processors with captive application laboratories requiring co-development relationships. Tokyo and Osaka metropolitan area plants dominate procurement value.
- Restaurants:Chain operators and central kitchens sourcing standardized seasoning systems for menu consistency. Kansai-based izakaya chains drive savory enhancer volume.
- Supermarkets:Private-label ready-meal programs with compressed development cycles. Regional banners in Sendai and Hiroshima seek domestic testing partnerships for METI compliance.
- Retailers:E-commerce meal kit providers and specialty food platforms. These channels prioritize rapid reformulation capabilities for trending flavor profiles.
Food manufacturers holds the largest share; momentum sits with supermarket private-label programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ready-to-eat meal manufacturers and broth compounders drive procurement concentration across Japan's food processing corridors. METI disclosure rules and PMDA oversight elevate compliance costs unevenly across sub-regional clusters. Technical service intensity from flavor houses correlates directly with manufacturing density.
Kanto/Tokyo
Tokyo's metropolitan food processing cluster anchors national demand for clean-label flavor systems. METI Food Labeling Standards revisions compress formulation timelines for manufacturers in Saitama and Chiba prefectures. Ajinomoto Co., Inc. maintains technical service laboratories in Kanagawa to support just-in-time integration with major ready-to-eat meal plants.
Kansai/Osaka
Osaka-Kobe processing corridors exhibit underpenetrated expansion headroom with divergent regional taste preferences toward bolder savory profiles. Izakaya chains and central kitchens drive amino acid-based enhancer volume through standardized seasoning procurement. Domestic formulation expertise in Hyogo prefecture privileges local testing partnerships over imported compound compliance.
Chubu/Nagoya
Snack seasoning manufacturers in Aichi and Gifu prefectures are accelerating powder-format conversions from legacy liquid systems. Regional co-manufacturing networks enable distribution reach into secondary markets. Equipment reconfiguration timelines create procurement friction for mid-size producers deferring capital investment.
Hokkaido
Dairy processing clusters in Hokkaido source fat-compatible flavor carriers for reduced-fat yogurt and dessert export production. FSSAI-aligned clean-label positioning for Asian retail channels concentrates domestic R&D investment in Sapporo-based application facilities. Agricultural yield fluctuations for botanical raw materials constrain natural extract supply stability.
Kyushu
Fukuoka's emerging food manufacturing base adopts powder-format savory coatings for shelf-stable snack export programs. Biotechnology-driven fermentation capacity remains constrained relative to Kanto technical service density. Regional flavor houses face talent scarcity in industrial microbiology metabolic engineering expertise.
Japan Food Flavor and Enhancer Market Competitive Environment
Player mix skews toward integrated amino acid specialists and premium natural flavor developers. Market structure concentrates procurement power with domestic formulation houses maintaining captive application laboratories. Three archetypes dominate: biotechnology-driven fermentation platforms, precision extraction specialists, and savory science heritage incumbents. Competitive moves center on embedded technical service partnerships and regional co-manufacturing network expansion.
Among domestic savory science incumbents, Ajinomoto Co., Inc. and T. Hasegawa Co., Ltd. exemplify divergent specialization vectors within the Japanese market. Ajinomoto Co., Inc. occupies a position anchored in amino acid heritage for umami-intensive applications, while T. Hasegawa Co., Ltd. represents premium natural flavor development for confectionery and bakery segments. Takasago International Corporation sits within the biotechnology-driven tier, with fermentation-derived botanical extraction capabilities. International Flavors and Fragrances Inc. and Givaudan SA represent global flavor house presence requiring domestic testing partnerships for METI compliance. Symrise AG, Firmenich SA, and Mane Group occupy positions as European-origin houses navigating PMDA novel ingredient review processes.
| Leading Market Players |
|---|
| Symrise AG |
| Firmenich SA |
| Ajinomoto Co., Inc. |
| Mane Group |
| Kikkoman Corporation |
| Takasago International Corporation |
| International Flavors and Fragrances Inc. |
| T. Hasegawa Co., Ltd. |
| Givaudan SA |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty-day inventory cycles for fermentation-derived botanical extracts concentrate procurement leverage with Kanto-based flavor houses and amplify price premiums for clean-label positioning. METI disclosure deadlines compress batch approval timelines, forcing mid-size manufacturers to absorb expedited testing costs or cede volume to integrated domestic suppliers.
Pricing Analysis
Next-generation precision fermentation platforms command 15-25% premiums over solvent-extracted naturals and 40-60% over synthetic alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment. Pricing pressure stems from natural extract supply volatility as agricultural yield fluctuations constrain botanical raw material availability. Mid-size snack and instant noodle producers in Osaka-Kobe corridors exhibit highest price sensitivity; premium Tokyo confectioners accept premium positioning for FSSAI-aligned export positioning.
Supply Chain Analysis
Japan and China anchor fermentation capacity and botanical raw material sourcing respectively. The supply chain draws from Indonesian vanilla cultivation, Indian spice extraction, and domestic amino acid production. Single-source vulnerability concentrates in precision fermentation microbiology strains held by limited domestic developers. Distribution runs through embedded technical service partnerships rather than arm's-length distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect as direct technical service engagement supplants distributor-mediated procurement, with interoperability standards emerging around METI-compliant disclosure data formats.
For Market Incumbents: Compound technical service density in Kanto by embedding formulation laboratories at major ready-to-eat meal plants. Deepen backward integration into fermentation microbiology capacity to offset talent scarcity in industrial metabolic engineering. METI's pending genetically modified microorganism disclosure amendments threaten biotechnology investments; accelerate classical extraction R&D redirection to derisk stranded innovation.
For New Entrants and Emerging Players: Lead with Kansai underpenetration, where Osaka-Kobe processing corridors exhibit divergent regional taste preferences toward bolder savory profiles. Target snack seasoning powder-format conversions in Nagoya and Fukuoka where equipment reconfiguration timelines create procurement friction for mid-size incumbents. Establish regional co-manufacturing partnerships as the primary go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity arbitrage play because METI disclosure rules and PMDA novel ingredient reviews elevate compliance costs that privilege domestic formulation expertise. Acquisition targets include biotechnology-driven fermentation platforms with captive strain libraries and Kanto-based application laboratories. The signal to watch is amendment timing for genetically modified microorganism disclosure rules that would redirect R&D investment toward classical extraction methods.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Technical Service Expansion | Direct laboratory co-location with Saitama and Chiba ready-to-eat meal plants secures just-in-time integration contracts. |
| Precision Fermentation Capacity Buildout | Biotechnology-driven botanical extraction platforms displace solvent-based methods for premium confectionery procurement cycles. |
| Regional Co-Manufacturing Network | Nagoya and Fukuoka powder-format conversions enable distribution reach into secondary snack seasoning markets. |
| Classical Extraction R&D Redirection | Pre-positioned innovation pipelines derisk stranded biotechnology assets under pending METI disclosure amendments. |
| Domestic Testing Partnership Establishment | Local JIS compliance verification privileges foreign suppliers against PMDA novel ingredient review cost escalation. |
Study Parameters
Operator-level perspectives from flavor formulation chemists, ready-to-eat meal procurement directors, METI regulatory compliance officers, and biotechnology R&D managers anchored the qualitative base. Primary interview data combined with secondary validation from METI Food Labeling Standards documentation, PMDA novel ingredient safety filings, JIS quality benchmark databases, and customs trade records for botanical raw material imports. Bottom-up volume modeling and top-down value triangulation cross-verified segment outputs.
Sensitivity analysis across the projection horizon tested demand elasticity for natural versus artificial flavor positioning and regulatory compliance cost pass-through rates. Segmentation dimensions modeled include product chemistry tier, application heat-stability requirements, physical format, and end-user procurement scale. CAGRs derived from historical trajectory analysis adjusted for METI disclosure rule implementation timing and at-home consumption pattern persistence. Industry-specific inputs incorporated fermentation capacity utilization rates and botanical agricultural yield variance bands.
The analysis sits within stated boundaries; outcomes outside sustained clean-label reformulation mandates or accelerated biotechnology disclosure requirements would require recalibration. Forecasts reflect documented assumptions regarding METI amendment timing and precision fermentation scale-up trajectories. Recalibration cycles align with material shifts in PMDA novel ingredient review processing timelines and agricultural commodity price volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Food-Grade Gellan Gum Market
Flavorings and Food Additives
Fractionated Lecithin Market
Flavorings and Food Additives
Global Bitterness Suppressors and Flavor Carriers Market
Flavorings and Food Additives
Fiber Syrup Market
Flavorings and Food Additives
Oleoresin Market
Flavorings and Food Additives
Italy Food Colorants Market
Flavorings and Food Additives
Food Colorants Market
Flavorings and Food Additives
Orange Essential Oil Market
Flavorings and Food Additives
Feed Flavors and Sweeteners Market
Flavorings and Food Additives
Global Vanilla (B2B) Market
Flavorings and Food Additives
1-Decanol Market
Flavorings and Food Additives
Chicory Extract Market
Flavorings and Food Additives
Brazil Food Flavor and Enhancer Market
Flavorings and Food Additives
Smoked Condensates Market
Flavorings and Food Additives
Citrus Flavors Market
Flavorings and Food Additives
Tangerine Essential Oil Market