
 Natural Flavor Extract Market | 2026-2036
Natural Flavor Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Flavor Extract Market Foresight
Market Context
Multi-source procurement among flavor houses is consolidating as large food manufacturers reduce dependency on single suppliers. Givaudan leverages its botanical sourcing network across three continents to secure raw material continuity. Symrise anchors its position through captive vanilla and citrus operations in Madagascar and Brazil. International Flavors & Fragrances competes on enzyme-assisted extraction platforms that shorten production cycles.
Technical Definition and Segment Structure
Natural flavor extract comprises volatile and non-volatile compounds derived from plant, animal, or microbial sources through distillation, solvent extraction, enzymatic treatment, or fermentation, typically standardized to specific flavor potency measured in fold concentration. These extracts serve primarily to impart, enhance, or modify taste and aroma profiles in processed foods and beverages without synthetic additive labeling. Liquid extracts dominate volume shipments due to ease of dosing in beverage and dairy applications, while concentrated pastes command margin premiums in artisanal bakery and confectionery segments where flavor intensity and clean-label positioning justify higher input costs. Powdered extracts represent the fastest-growing form category as spray-drying technology improves heat-sensitive compound retention for dry-mix applications.
Regulatory Framework and Outlook
EFSA and FDA both enforce stringent substantiation requirements for natural flavor claims, with EFSA's 2023 guidance on botanical safety assessments creating additional compliance layers for European suppliers. REACH and FSSC 22000 certification now function as baseline market access credentials rather than differentiators for ingredient vendors selling into multinational food manufacturers. Stakeholders must monitor evolving definitions of naturalness across jurisdictions, as divergence between FDA's "natural flavor" standard and emerging EU proposals on biotechnologically produced compounds threatens to fragment formulation strategies.
Market Dynamics
Clean-label reformulation mandates from EU and US regulators are compressing synthetic flavor substitution timelines, forcing beverage and dairy manufacturers to requalify entire supply chains around botanical provenance documentation and extraction method verification.
Growth Catalysts
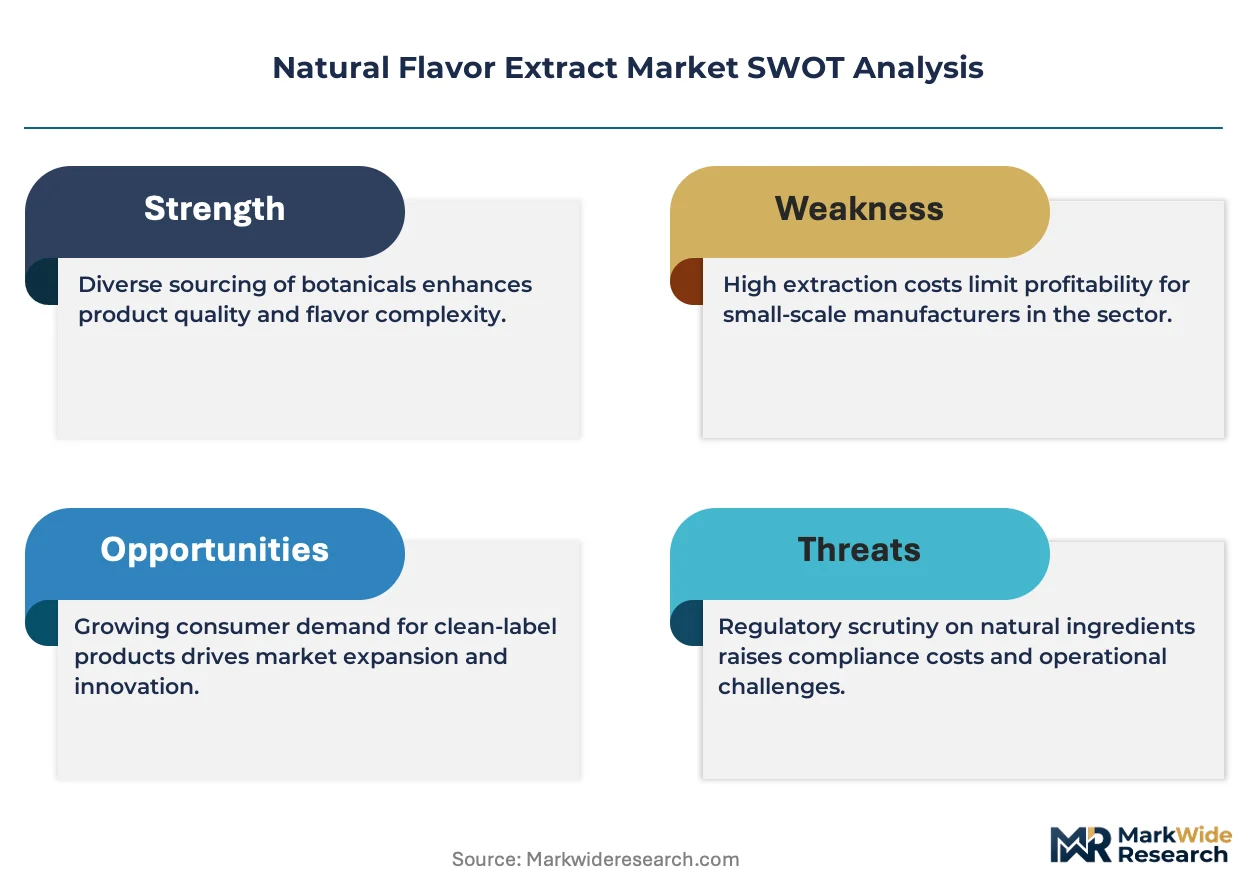
- EFSA additive disclosure tightening:European beverage producers face mandatory ingredient transparency rules that accelerate natural extract procurement. Reformulation budgets are redirecting toward plant-derived systems.
- Enzyme-assisted extraction platforms:These technologies shorten production cycles from weeks to days. Flavor houses deploy them to meet compressed customer delivery windows.
- Madagascar vanilla sourcing consolidation:Captive plantation operations secure raw material continuity against climate volatility. Premium confectionery segments absorb higher input costs for supply assurance.
Market Restraints
- Vanillin price volatility:Natural vanilla bean harvests fluctuate 40% year-to-year due to cyclone exposure. Extractors cannot fully hedge through forward contracts.
- REACH compliance burden:European botanical suppliers face escalating registration costs for novel plant sources. Small-scale producers exit rather than absorb documentation expenses.
- Biotech flavor molecule substitution:Precision-fermented compounds achieve cost parity with botanical extracts in vanilla and citrus categories. Clean-label positioning loses differentiation power.
Strategic Opportunities
- India FSSAI natural claim recognition:Domestic food manufacturers lack qualified local extract suppliers. Joint ventures with established European flavor houses capture import substitution demand.
- Spray-dried heat-sensitive formats:Dry-mix beverage applications previously excluded natural extracts due to thermal degradation. Improved encapsulation technology opens formulation possibilities.
- Direct-to-manufacturer digital platforms:Artisanal bakery and craft distillery segments bypass traditional distributor markups. Traceability dashboards justify premium positioning.
Industry Challenges
- Botanical identification expertise scarcity:Analytical chemists capable of authenticating plant species via DNA barcoding and isotope analysis command salaries 35% above industry norms. Recruitment timelines extend six months.
- FSSC 22000 certification backlog:Audit appointment availability constrains supplier qualification for multinational food manufacturers. Smaller extractors face 18-month queue times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Flavor Extract Market |
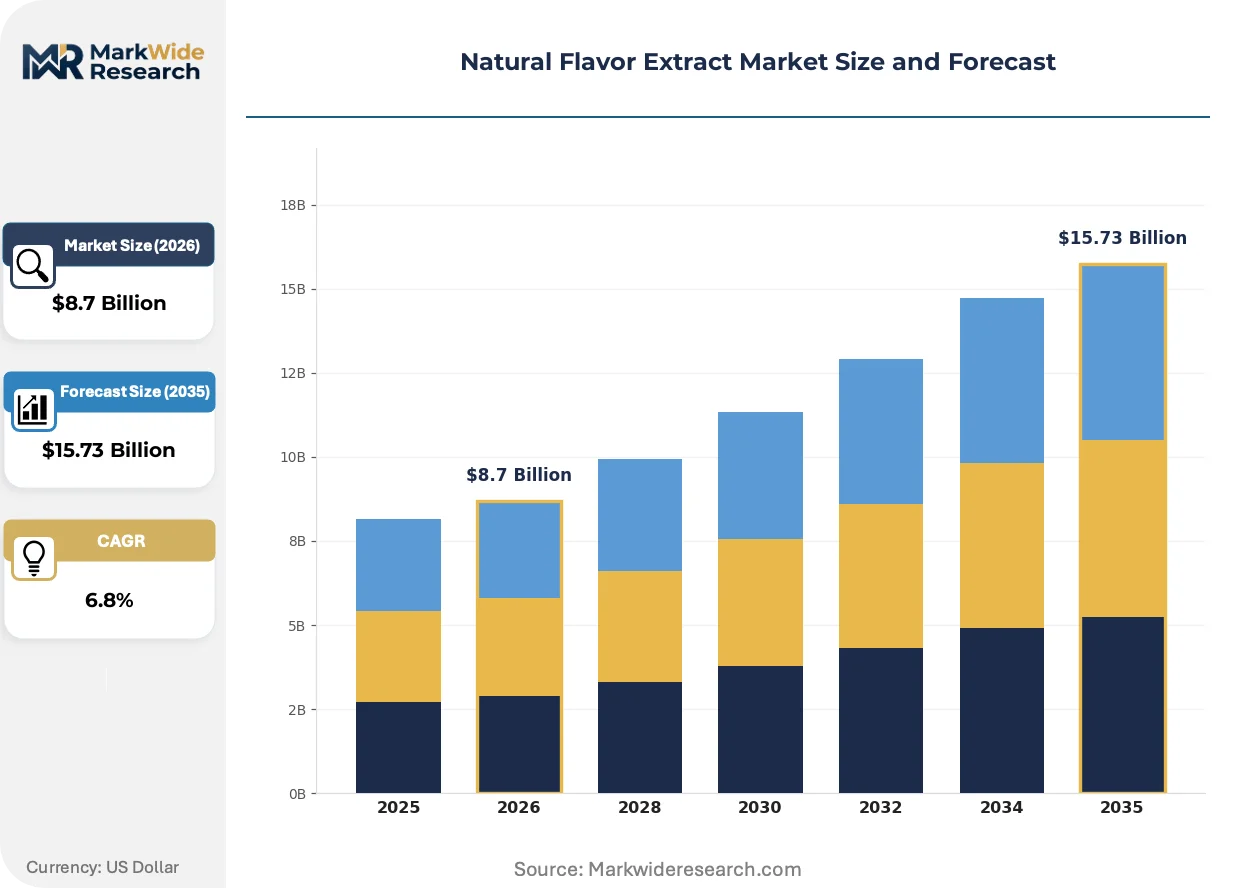
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extracts, Powdered Extracts, Concentrated Pastes, Emulsions Application: Beverage, Bakery, Dairy, Confectionery End User: Food Manufacturers, Beverage Producers, Retailers, Restaurants Form: Organic, Non-Organic, Synthetic, Natural |
| Companies Covered | Symrise, Kikkoman Corporation, Givaudan, Novozymes, Corbion, Firmenich, Sensient Technologies, Robertet, International Flavors & Fragrances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Flavor Extract Market Shifts & Advancements
Extraction technology convergence with biotechnology is dissolving traditional boundaries between botanical and fermented flavor production. Regulatory definitions lag behind technical capabilities, creating formulation strategy divergence across jurisdictions.
Supercritical CO2 extraction systems are absorbing capital investment from flavor houses seeking solvent-free processing credentials. Premium chocolate and organic juice manufacturers specify this method in procurement contracts. The technology is absorbing market share from conventional ethanol extraction in high-value applications where residual solvent detection risks rejection.
EFSA's 2023 botanical safety assessment guidance introduces mandatory toxicity evaluation for novel plant sources. European suppliers must submit comprehensive dossiers before market authorization. Artisanal extract producers in France and Italy face particular strain, as generational family formulations lack modern toxicological documentation.
Beverage manufacturers are consolidating supplier relationships from fifteen-plus vendors to three-to-five strategic partners. Procurement teams prioritize extractors with integrated quality laboratories and geographic sourcing diversification. This concentration is most visible in Germany, where mid-sized mineral water and functional drink producers now demand single-source accountability for entire flavor portfolios.
Natural Flavor Extract Market Segmentation
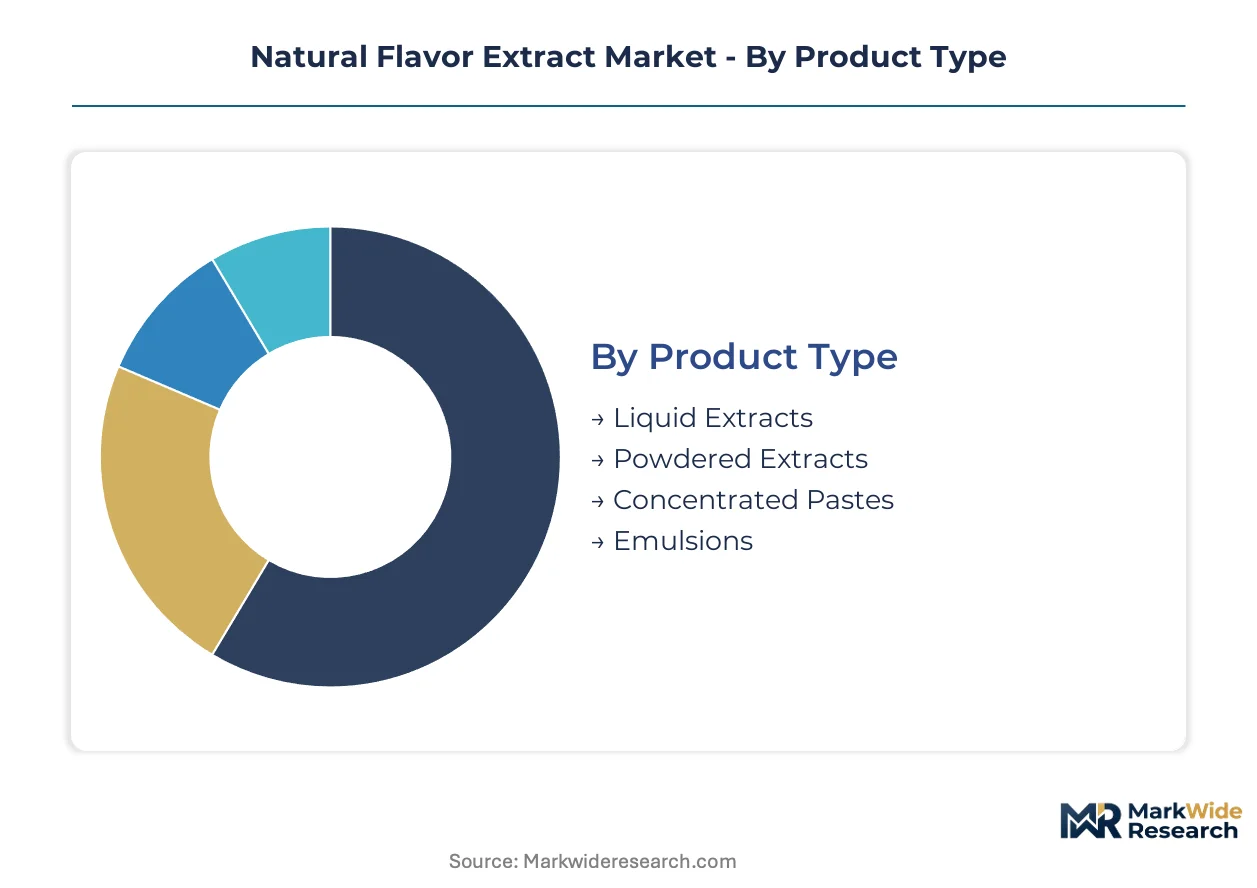
Segmentation in natural flavor extracts reflects divergent supply chain configurations across physical formats and end-use requirements. Procurement teams align supplier qualification protocols with specific application demands, from high-volume beverage dosing to precision bakery formulations.
Product Type:
Supply concentration varies sharply by physical format, with liquid extraction infrastructure dominating capital deployment while spray-drying capacity expands fastest.
- Liquid Extracts:Ethanol and aqueous solutions standardized to fold concentrations between 2x and 20x serve high-throughput beverage lines. German and US dairy processors specify liquid formats for automated dosing compatibility.
- Powdered Extracts:Spray-dried or drum-dried carriers encapsulate volatile compounds for dry-mix stability. Functional drink manufacturers in France and California are absorbing expanding output as encapsulation technology improves heat-sensitive retention.
- Concentrated Pastes:High-viscosity suspensions with minimal carrier content deliver intensity for artisanal confectionery. Madagascar vanilla paste commands premium positioning in premium chocolate segments.
- Emulsions:Oil-in-water dispersions stabilize lipophilic flavor compounds for cloudy beverages and dressings.
Liquid extracts absorb the bulk of installed capacity; powdered extracts are expanding most quickly.
Application:
Cost tier stratification separates commodity-scale beverage procurement from precision-formulated confectionery sourcing.
- Beverage:Carbonated soft drinks, functional waters, and alcoholic beverages consume standardized extracts in 10,000-liter batch quantities. EFSA disclosure mandates are compressing synthetic substitution timelines across European bottling operations.
- Bakery:Heat-stable vanilla and citrus extracts withstand proofing and baking thermal profiles. Artisanal sourdough and viennoiserie segments in France and Italy specify provenance-documented botanical sources.
- Dairy:Yogurt and ice cream applications demand cold-process compatible extracts with clean-label positioning. US processors reformulate around natural vanilla as FDA scrutiny intensifies.
- Confectionery:Premium chocolate and hard candy segments absorb highest-margin paste and extraction formats. Madagascar and Brazilian captive sourcing secures supply continuity for multinational confectioners.
Beverage applications absorb the bulk of volume throughput; confectionery commands the steepest margin expansion trajectory.
End User:
Customer type determines qualification depth, with multinational food manufacturers imposing FSSC 22000 and REACH documentation requirements that exclude smaller extractors.
- Food Manufacturers:Processed food and ingredient companies procure extracts as formulation inputs. Integrated quality laboratories and geographic sourcing diversification now function as baseline supplier credentials.
- Beverage Producers:Bottling and brewing operations prioritize dosing precision and batch consistency. Mid-sized German mineral water producers are consolidating vendor relationships from fifteen-plus suppliers to three-to-five strategic partners.
- Retailers:Private-label food and beverage programs specify extracts for store-brand formulations.
- Restaurants:Foodservice distributors supply extracts for commercial kitchen and catering applications.
Food manufacturers absorb the bulk of procurement volume; beverage producers are consolidating supplier relationships fastest.
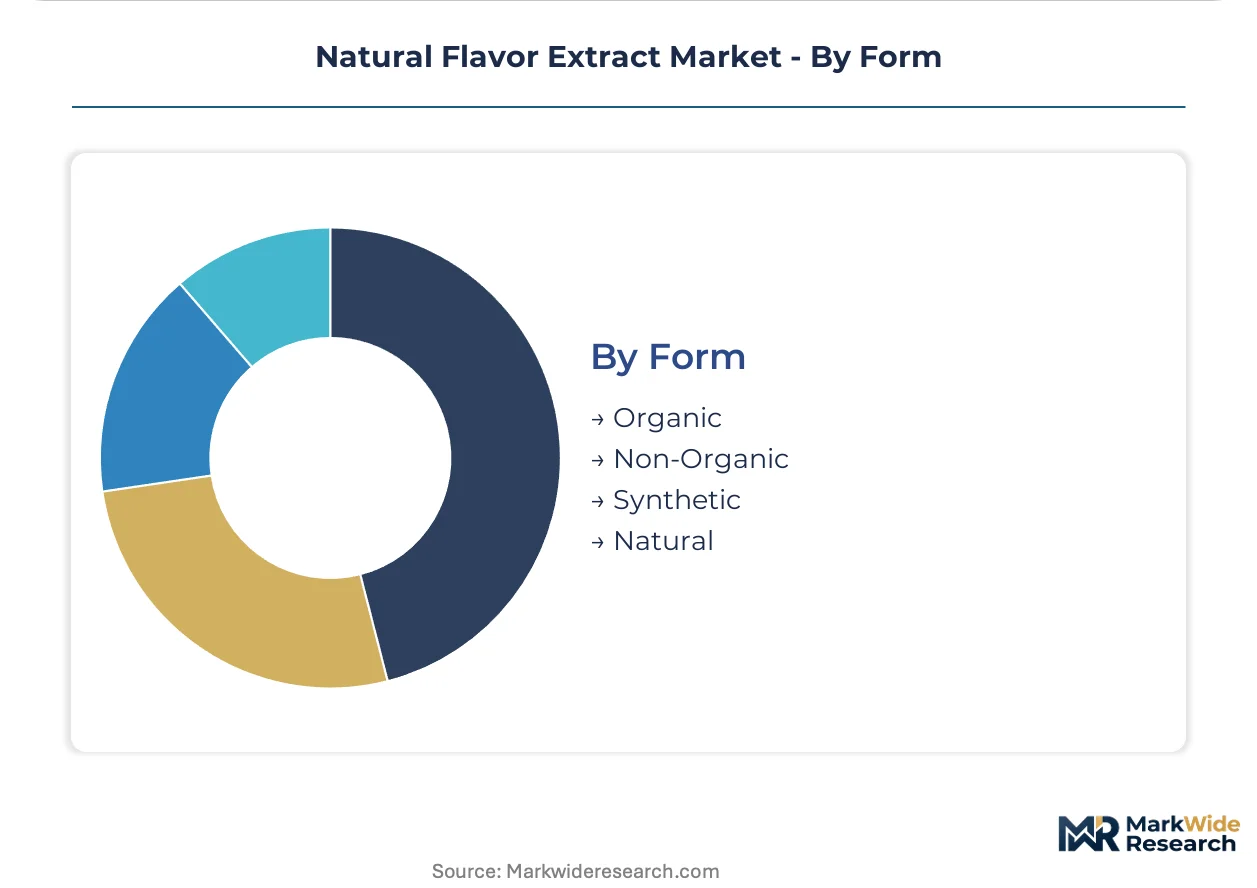
Form:
Margin structure separates certified organic supply chains from conventional botanical sourcing, with synthetic alternatives losing positioning under tightening clean-label mandates.
- Organic:USDA and EU organic certification requires full supply chain traceability from cultivation through extraction. Supercritical CO2 processing commands price premiums in premium chocolate and organic juice procurement contracts.
- Non-Organic:Conventional botanical extraction serves cost-sensitive mass-market applications where certification documentation is not specified.
- Synthetic:Chemically synthesized flavor compounds face displacement as EFSA and FDA disclosure requirements intensify.
- Natural:Plant, animal, or microbial-derived compounds meeting regulatory naturalness definitions serve reformulation mandates across EU and US markets.
Non-organic forms absorb the bulk of current volume; organic certification is climbing the fastest as procurement specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany, France, and the United States concentrate procurement demand as beverage manufacturers accelerate clean-label reformulation timelines. EFSA disclosure mandates and FDA scrutiny are compressing synthetic substitution windows across these markets.
Germany
Mid-sized mineral water and functional drink producers are consolidating vendor relationships from fifteen-plus suppliers to three-to-five strategic partners. REACH compliance and FSSC 22000 certification function as baseline market access credentials rather than differentiators. The Rhine-Main cluster around Frankfurt anchors flavor house technical service operations serving Central European beverage bottlers.
France
Artisanal bakery and viennoiserie segments specify provenance-documented botanical sources for vanilla and citrus extracts. EFSA's 2023 botanical safety assessment guidance imposes mandatory toxicity evaluation burdens on generational family formulations. The Provence-Alpes-Côte d'Azur region hosts extraction specialists serving premium chocolate and confectionery manufacturers.
United States
Dairy processors reformulate around natural vanilla as FDA scrutiny of "natural flavor" claims intensifies. Enzyme-assisted extraction platforms shorten production cycles from weeks to days to meet compressed delivery windows. California's Central Valley and Wisconsin dairy corridors absorb expanding volumes of cold-process compatible extracts.
Brazil
Captive citrus operations anchor supply continuity for multinational confectioners seeking geographic sourcing diversification. ANVISA alignment with international disclosure standards is accelerating procurement of botanical-derived systems. The São Paulo state industrial belt concentrates extraction capacity serving Latin American beverage markets.
India
Domestic food manufacturers lack qualified local extract suppliers as FSSAI natural claim recognition expands addressable market scope. Joint ventures with established European flavor houses capture import substitution demand. Maharashtra and Gujarat industrial corridors concentrate formulation partnerships targeting processed food export growth.
Natural Flavor Extract Market Competitive Landscape
Supplier relationship consolidation dominates the current landscape as procurement teams reduce dependency on fragmented vendor bases. The market structures around three tiers: integrated multinational flavor houses with captive sourcing networks, mid-sized regional specialists with botanical identification expertise, and artisanal extractors serving provenance-sensitive niche segments. Technology licensing and backward integration into raw material sourcing represent the two dominant competitive vectors reshaping participant positioning.
Within the integrated multinational tier, Givaudan, Symrise, and International Flavors & Fragrances exemplify archetypes built on geographic sourcing diversification and extraction technology platforms. Givaudan's three-continent botanical network represents the captive supply model. Symrise's Madagascar and Brazilian operations exemplify vertical control over vanilla and citrus supply chains. International Flavors & Fragrances occupies a position defined by enzyme-assisted processing capabilities. These three entities anchor the competitive structure through which smaller regional specialists and artisanal producers must navigate.
| Leading Market Players |
|---|
| Symrise |
| Kikkoman Corporation |
| Givaudan |
| Novozymes |
| Corbion |
| Firmenich |
| Sensient Technologies |
| Robertet |
| International Flavors & Fragrances |
| Others |
Supply & Pricing Matrix
EFSA's 2023 botanical safety assessment guidance gates qualified supply and premium-tier pricing access, forcing extractors to absorb documentation costs or exit European markets entirely. Buyers seeking REACH-compliant, FSSC 22000-certified suppliers face compressed vendor pools that concentrate pricing power among integrated flavor houses with captive laboratory infrastructure.
Pricing Analysis
Volume throughput concentrates in commodity-grade liquid extracts for beverage dosing, while margin expansion accrues to concentrated pastes and certified organic formats for artisanal confectionery. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and provenance documentation depth. Cost compression in mid-tier ethanol-extracted vanilla runs through biotech precision-fermented substitutes achieving cost parity. Mass-market beverage processors exhibit highest price sensitivity; premium chocolate manufacturers absorb steep premiums for supercritical CO2-processed, single-origin botanicals.
Supply Chain Analysis
Direct-to-manufacturer digital platforms bypass traditional distributor markups for craft distillery and artisanal bakery segments. Raw material sourcing concentrates in Madagascar for vanilla, Brazil for citrus, and India for spice-derived compounds. Extraction infrastructure draws from ethanol and aqueous processing systems, supercritical CO2 equipment, and spray-drying encapsulation lines. Single-source vulnerability in Madagascar vanilla bean harvests exposes extractors to cyclone-driven supply interruptions. Distribution runs through integrated flavor house technical service operations, regional specialist networks, and emerging direct-to-manufacturer traceability platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story. EFSA's mandatory toxicity evaluation dossiers create a barrier-to-entry moat that rewards incumbents with existing laboratory infrastructure and documentation capabilities while excluding artisanal family operations.
For Market Incumbents: Deploy captive sourcing networks as the primary defensive lever. Deepen backward integration into Madagascar vanilla plantations and Brazilian citrus operations to secure raw material continuity against climate volatility. Accelerate FSSC 22000 certification pre-qualification programs for strategic accounts before audit appointment backlogs extend qualification timelines further. Biotech precision-fermented substitutes threaten differentiation power in vanilla and citrus categories; counter with supercritical CO2 processing credentials that synthetic alternatives cannot replicate. For New Entrants and Emerging Players: Mid-sized Indian food manufacturers lacking qualified local extract suppliers represent the most penetrable buyer archetype. Joint venture structures with established European flavor houses capture FSSAI natural claim recognition demand without requiring full certification infrastructure investment. Direct-to-manufacturer digital platforms with traceability dashboards offer a go-to-market angle that bypasses traditional distributor markups in artisanal bakery and craft distillery segments. For Investors and Strategic Acquirers: Consolidation of supplier relationships from fifteen-plus vendors to three-to-five strategic partners among German beverage producers is the leading indicator that mid-sized regional specialists with botanical identification expertise face acquisition pressure. Long-term viability over the projection horizon favors extractors with integrated quality laboratories and geographic sourcing diversification. Target acquisition archetype: regional specialists with FSSC 22000 certification and DNA barcoding capabilities. Monitor EFSA guidance divergence from FDA natural flavor definitions as the signal for formulation strategy fragmentation requiring dual-compliance infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Sourcing | Madagascar and Brazilian plantation control secures supply continuity against cyclone and drought exposure. |
| Supercritical CO2 Processing Certification | Solvent-free credentials command procurement contract premiums from premium chocolate and organic juice manufacturers. |
| Enzyme-Assisted Extraction Platform Deployment | Production cycle compression from weeks to days meets compressed customer delivery windows in beverage reformulation. |
| FSSC 22000 Pre-Qualification Acceleration | Early audit scheduling captures supplier consolidation demand from multinational food manufacturers reducing vendor counts. |
| Direct-to-Manufacturer Digital Platform Launch | Traceability dashboards justify premium positioning in artisanal bakery and craft distillery segments bypassing distributor markups. |
Research Methodology
Document review covered EFSA guidance documents, FDA natural flavor substantiation requirements, FSSC 22000 certification standards, and REACH registration databases, complemented by interviews with flavor house procurement directors, extraction technology specialists, botanical identification chemists, and food manufacturer reformulation managers. Secondary validation drew from customs and trade flow data, botanical sourcing network disclosures, and extraction equipment capital expenditure records. Bottom-up segment sizing triangulated against top-down market aggregation.
Segment-level value and volume outputs across the analysis window reflect product type, application, end user, and form stratification with geographic production cluster overlay. CAGRs were derived from regression analysis of historical procurement volume patterns and forward projection of regulatory-driven reformulation timelines. Industry-specific forecast inputs incorporated EFSA disclosure mandate implementation schedules and enzyme-assisted extraction platform adoption curves.
Revisions become necessary when biotech precision-fermented compounds achieve cost undercutting of botanical extracts, when EFSA-FDA regulatory divergence fragments formulation strategies, or when Madagascar vanilla harvest volatility exceeds historical cyclone exposure patterns. Practitioners should monitor FSSC 22000 audit appointment availability, REACH registration cost escalations for novel plant sources, and FSSAI natural claim recognition enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Smoked Condensates Market
Flavorings and Food Additives
Ginkgo Biloba Extract Market
Flavorings and Food Additives
United States Food Flavor and Enhancer Market
Flavorings and Food Additives
Chicken Flavor Market
Flavorings and Food Additives
Clean Label Flavors Market
Flavorings and Food Additives
Jujube Extracts Market
Flavorings and Food Additives
Flavoring Oil Market
Flavorings and Food Additives
Salts and Flavored Salts Market
Flavorings and Food Additives
South America Food Flavor Market
Flavorings and Food Additives
South America Flavors and Fragrances Market
Flavorings and Food Additives
Russia Food Flavor and Enhancer Market
Flavorings and Food Additives
Global Acerola Extracts Market
Flavorings and Food Additives
Orange Terpenes Market
Flavorings and Food Additives
Menthol Market
Flavorings and Food Additives
China Food Colorants Market
Flavorings and Food Additives
Oleoresin Market