
 Ginkgo Biloba Extract Market | 2026-2036
Ginkgo Biloba Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Ginkgo Biloba Extract Market Analysis
Good Manufacturing Practice certification for active pharmaceutical ingredients is unwinding competitive access across European and North American supply chains. Indena S.p.A. leverages its phytochemical extraction expertise to dominate high-purity pharmaceutical-grade supply. Schwabe sustains its position through backward integration into controlled cultivation programs in Germany and France. Bio-Botanica Inc. anchors North American demand with certified organic extract lines for nutraceutical brands.
Ginkgo biloba extract is a concentrated botanical preparation standardized to 24% flavone glycosides and 6% terpene lactones, typically produced through ethanol or supercritical CO2 extraction of dried leaves for cognitive and circulatory therapeutic applications. The dietary supplements segment occupies the largest volume channel as direct-to-consumer brands expand online retail penetration. Liquid extracts represent the fastest-growing product format among functional beverage and tincture manufacturers seeking rapid bioavailability claims. Memory enhancement applications lead clinical positioning while antioxidant support formulations attract premium pricing in cosmeceutical channels.
The European Medicines Agency enforces monograph standards for THMP-registered ginkgo preparations, while the FDA oversees New Dietary Ingredient notifications for novel extract concentrations entering US commerce. China's National Medical Products Administration applies dual carbon goals to solvent recovery mandates at extraction facilities, raising compliance costs for smaller processors. Stakeholders must monitor evolving pharmacovigilance requirements for anticoagulant interaction labeling as regulatory scrutiny of botanical-drug combinations intensifies across major markets.
Market Dynamics
Pharmaceutical-grade certification requirements are compressing supplier margins while concentrating procurement among vertically integrated extractors with captive cultivation assets. The EU's Traditional Herbal Medicinal Products Directive has created a two-tier market split between prescription-grade monograph compliance and unregulated nutraceutical supply.
Growth Catalysts
- EMA Monograph Harmonization:Standardized potency thresholds for THMP-registered ginkgo preparations are consolidating demand toward certified European manufacturers with analytical testing capabilities.
- Supercritical CO2 Extraction Adoption:Solvent-free processing technology is capturing share from ethanol-based methods in premium pharmaceutical contracts due to residual solvent compliance advantages.
- China's Dual Carbon Mandates:NMPA enforcement of solvent recovery requirements at Shaanxi and Hunan processing clusters is accelerating capital investment in closed-loop extraction infrastructure.
Market Restraints
- Raw Material Concentration Risk:Wild-harvested leaf supply from specific Anhui and Zhejiang collection zones creates weather-dependent input volatility for non-integrated processors.
- Anticoagulant Interaction Labeling Burden:FDA pharmacovigilance requirements for bleeding risk warnings are extending product registration timelines and limiting clinical positioning claims.
- Terpenoid Synthesis Substitution:Biotechnologically produced ginkgolide analogs are emerging as standardized alternatives for circulatory therapeutic applications in regulated pharmaceutical channels.
Strategic Opportunities
- Cosmeceutical Antioxidant Positioning:Premium topical formulations leveraging flavone glycoside content are opening price-insensitive demand in Korean and Japanese beauty markets.
- Functional Beverage Integration:Liquid extract formats with rapid bioavailability claims are penetrating direct-to-consumer channels through tincture and adaptogenic drink formulations.
- Organic Certification Arbitrage:USDA and EU organic standards for leaf sourcing are creating margin expansion potential for certified cultivation programs in France and Germany.
Industry Challenges
- Phytochemical Standardization Expertise Gap:Analytical chemists capable of validating 24% flavone glycoside and 6% terpene lactone batch consistency remain scarce across contract manufacturing organizations.
- GMP-API Certification Timeline Compression:European pharmaceutical manufacturers are demanding 12-month qualification windows that strain smaller extractors' quality management system upgrade capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ginkgo Biloba Extract Market |
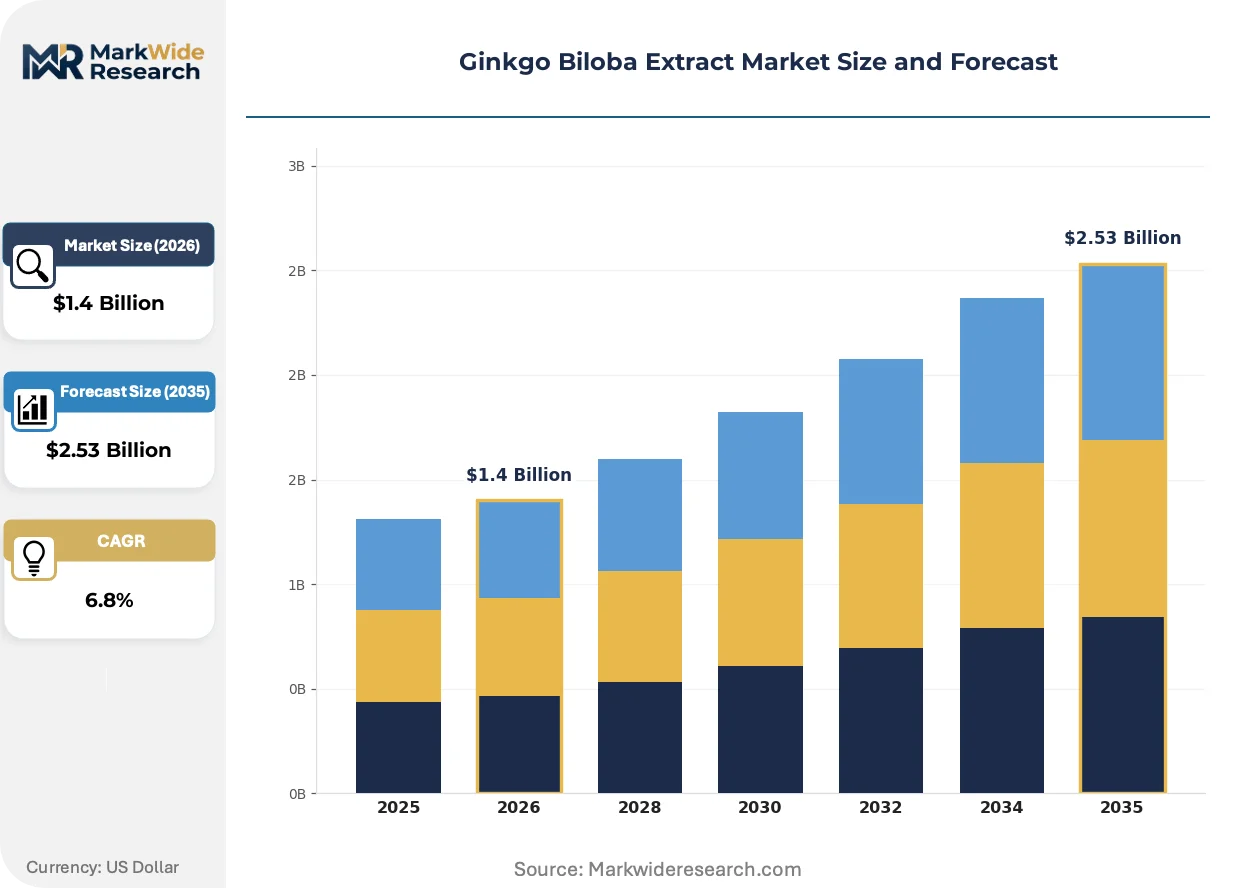
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Liquid Extracts, Powder End User: Pharmaceuticals, Nutraceuticals, Cosmetics, Dietary Supplements Distribution Channel: Online Retail, Health Stores, Pharmacies, Supermarkets Application: Memory Enhancement, Cognitive Function, Blood Circulation, Antioxidant Support |
| Companies Covered | Indena S.p.A., Givaudan, Schwabe, Bio-Botanica Inc., Hunan NutraMax Inc., Ipsen, Sabinsa Corporation, BIOLANDES Group, Nature's Bounty Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ginkgo Biloba Extract Market Emerging Trajectories
Extraction technology convergence with precision analytical validation is reshaping competitive differentiation. Regulatory fragmentation across pharmaceutical and nutraceutical channels is forcing dual-track compliance investment. Demand is rotating toward format-flexible supply partnerships capable of serving both clinical and consumer positioning.
Supercritical CO2 extraction with integrated terpene fractionation is supplanting conventional ethanol maceration in high-purity pharmaceutical contracts. German and French API manufacturers are adopting these systems to meet EMA residual solvent limits without multiple purification stages. The technology is compressing batch-to-batch variability while raising capital barriers for mid-scale competitors.
REACH registration requirements for novel extraction solvents are extending chemical safety documentation obligations to botanical processors using alternative polar solvents. ECHA substance evaluation is forcing reformulation of proprietary extraction blends previously grandfathered under generic ethanol classifications. Smaller Italian and Spanish contract manufacturers are consolidating to share toxicology study costs.
Direct-to-consumer brands are unbundling traditional distributor relationships to capture margin through subscription-based extract delivery models. Online retail penetration is displacing pharmacy and health food store stocking fees as the primary customer acquisition channel. This channel rotation is most visible among North American and Australian nutraceutical marketers targeting cognitive wellness positioning.
Ginkgo Biloba Extract Market Segmentation
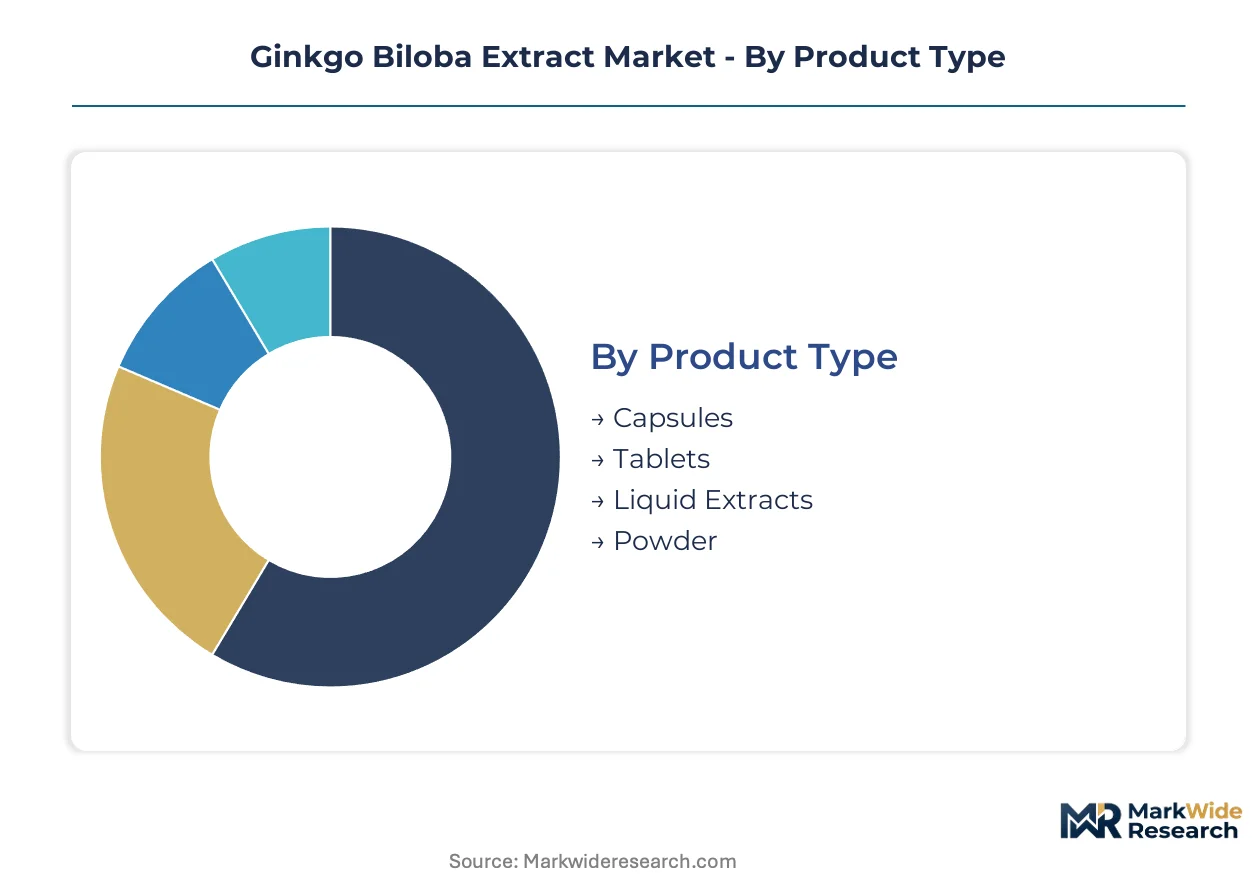
Ginkgo biloba extract markets fragment across formulation formats, therapeutic positioning, and channel access tiers. Margin capture varies sharply by certification burden and end-use regulatory intensity.
Product Type:
Premium margin pools concentrate in formats with bioavailability claims and pharmaceutical compliance pathways.
- Liquid Extracts:Tincture and functional beverage formulations deliver rapid absorption profiles through sublingual or diluted delivery. Korean adaptogenic drink manufacturers and North American direct-to-consumer wellness brands are expanding procurement of alcohol-free glycerite bases for clean-label positioning. EMA residual solvent limits are compressing supplier qualification to CO2-extraction specialists.
- Capsules:Hard-shell gelatin and vegetarian capsule formats dominate prescription circulatory medicines in Germany and France, with standardized 24% flavone glycoside content mandatory for THMP registration. Schwabe and Indena S.p.A. supply chains anchor European pharmaceutical procurement through backward integration into controlled cultivation.
- Tablets:Compressed formulations with excipient binding serve mass-market nutraceutical channels with cost-optimized unit economics.
- Powder:Bulk extract for contract manufacturing and food fortification applications concentrates in Shaanxi processing clusters for export blending.
Capsules hold installed capacity. Liquid extracts are rotating up the share rankings.
End User:
Regulatory pathway intensity determines pricing power and customer concentration risk across therapeutic positioning tiers.
- Dietary Supplements:Direct-to-consumer brands bypass pharmacy distribution through subscription models and influencer marketing. Online retail penetration is displacing health food store slotting fees as the primary customer acquisition channel in North America and Australia.
- Pharmaceuticals:EMA-monograph compliance for circulatory indications requires validated 24/6 standardization and GMP-API certification. German and French manufacturers concentrate procurement among three vertically integrated extractors with captive Anhui leaf supply.
- Nutraceuticals:Positioning between pharmaceutical and supplement tiers leverages clinical trial citations for cognitive wellness without prescription registration burden.
- Cosmetics:Topical antioxidant formulations with flavone glycoside content are penetrating Korean and Japanese beauty markets through premium pricing and dermal absorption claims.
Pharmaceuticals command price premiums. Dietary supplements are expanding volume fastest.
Distribution Channel:
Channel control determines margin retention and customer data access for repeat purchase engineering.
- Online Retail:Direct-to-consumer brands capture subscription revenue and bypass distributor markups through proprietary storefronts and marketplace presence. Australian and North American cognitive wellness marketers lead channel migration.
- Pharmacies:THMP-registered ginkgo preparations require pharmacist consultation in Germany and France, creating prescription-adjacent positioning for circulatory indications.
- Health Stores:Independent and chain natural products retailers stock certified organic lines for consumer self-selection with staff recommendation dependency.
- Supermarkets:Mass-market placement of standardized capsules reaches occasional users through convenience purchasing with minimal clinical positioning.
Pharmacies retain regulatory moats. Online retail is climbing the fastest.
Application:
Therapeutic claim substantiation requirements separate premium pharmaceutical positioning from commodity antioxidant supply.
- Memory Enhancement:Clinical trial citations for cognitive decline modulation support premium pricing in aging population segments. FDA NDI notifications for novel extract concentrations extend registration timelines for substantiated positioning.
- Blood Circulation:EMA monograph recognition for peripheral arterial disease indications creates prescription-channel access in European markets with reimbursement eligibility.
- Cognitive Function:Broad wellness positioning without disease claims navigates supplement regulatory pathways with lower compliance burden.
- Antioxidant Support:Cosmeceutical and general wellness applications compete on price with limited differentiation beyond organic certification and extraction method marketing.
Blood circulation anchors pharmaceutical value. Memory enhancement is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade buyers concentrate procurement among vertically integrated extractors with captive cultivation assets and validated analytical capabilities across Germany, France, China, and North America.
China
Shaanxi and Hunan provinces host dense clusters of raw leaf processing facilities serving both domestic TCM formulations and export contract manufacturing. NMPA enforcement of dual carbon goals mandates solvent recovery systems at extraction facilities, raising compliance costs for smaller processors. Anhui and Zhejiang wild-harvested leaf supply creates weather-dependent input volatility for non-integrated operators.
Germany
Pharmaceutical manufacturers expand procurement of standardized extracts for prescription circulatory medicines through backward integration into controlled cultivation programs. EMA monograph standards for THMP-registered ginkgo preparations enforce 24% flavone glycoside and 6% terpene lactone potency thresholds. Schwabe anchors European pharmaceutical supply through captive production assets in German and French cultivation zones.
France
API manufacturers adopt supercritical CO2 extraction systems to meet EMA residual solvent limits without multiple purification stages. ANSM enforces pharmacovigilance requirements for anticoagulant interaction labeling on botanical-drug combinations. BIOLANDES Group exemplifies French extraction expertise serving cosmetic and pharmaceutical channels.
United States
Direct-to-consumer brands bypass pharmacy distribution through subscription models and influencer marketing targeting cognitive wellness positioning. FDA oversight of New Dietary Ingredient notifications extends registration timelines for novel extract concentrations. Bio-Botanica Inc. anchors North American demand with certified organic extract lines for nutraceutical brands.
Japan
Premium topical formulations leveraging flavone glycoside content penetrate Korean and Japanese beauty markets through dermal absorption claims. METI standards guide functional food and cosmetic ingredient safety assessments. PMDA pharmacovigilance systems monitor bleeding risk interactions for ginkgo-containing products in aging population segments.
Ginkgo Biloba Extract Market Vendor Landscape
Player mix skews toward vertically integrated European specialists with pharmaceutical-grade certification and Asian contract manufacturers serving bulk nutraceutical demand. Market structure concentrates procurement among three to five extractors with captive Anhui leaf supply and validated GMP-API quality systems. Strategic archetypes include monograph-compliant pharmaceutical suppliers, certified organic premium extractors, and scale-driven bulk processors. Dominant competitive moves center on supercritical CO2 extraction technology licensing and backward integration into controlled cultivation programs.
Within the pharmaceutical-grade tier, Indena S.p.A. and Schwabe represent European extraction expertise with monograph-compliant supply chains. Among North American-certified organic specialists, Bio-Botanica Inc. occupies a position serving nutraceutical brand demand. At the Asian contract manufacturing end, Hunan NutraMax Inc. exemplifies Shaanxi-Hunan processing cluster capacity for export blending operations.
| Leading Market Players |
|---|
| Indena S.p.A. |
| Givaudan |
| Schwabe |
| Bio-Botanica Inc. |
| Hunan NutraMax Inc. |
| Ipsen |
| Sabinsa Corporation |
| BIOLANDES Group |
| Nature's Bounty Co. |
| Others |
Supply Flow & Price Mechanics
EMA monograph standards for THMP-registered ginkgo preparations gate both supply qualification and price differentiation simultaneously, compressing margins for uncertified processors while rewarding validated extractors with pharmaceutical-grade premiums. The EU's Traditional Herbal Medicinal Products Directive creates a bifurcated market where GMP-API certification determines access to prescription circulatory medicine contracts.
Pricing Analysis
Cost-plus contracts with Anhui leaf price indexation dominate procurement between European pharmaceutical manufacturers and vertically integrated extractors. Three-tier pricing structure across pharmaceutical-grade, certified organic, and bulk nutraceutical levels reflects differentiation by certification burden and analytical validation depth. Pricing pressure stems from biotechnologically produced ginkgolide analogs entering circulatory therapeutic applications. Dietary supplement brands exhibit highest price sensitivity through spot market purchasing, while German API manufacturers accept premium pricing for validated batch consistency.
Supply Chain Analysis
China, Germany, and France anchor ginkgo biloba extract production through distinct specializations—Shaanxi-Hunan processing clusters, supercritical CO2 extraction systems, and controlled cultivation programs respectively. Raw material supply draws from wild-harvested Anhui and Zhejiang leaf collection zones, ethanol and CO2 extraction solvents, and gelatin or vegetarian capsule excipients. Single-source vulnerability concentrates in weather-dependent wild-harvested leaf supply from specific Chinese provinces. Distribution runs through direct-to-consumer subscription platforms, pharmacy chains with THMP consultation requirements, and contract manufacturing arrangements for bulk export blending.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities emerge as regulatory pathway intensity splits demand between pharmaceutical-grade monograph compliance and flexible nutraceutical positioning, creating distinct competitive arenas for differentiated supply partnerships.
For Market Incumbents: Consolidate analytical testing capabilities and captive Anhui leaf supply to defend against terpenoid synthesis substitution threatening circulatory therapeutic applications. Deepen backward integration into controlled cultivation programs in France and Germany to secure organic certification arbitrage margins. Prioritize supercritical CO2 extraction technology licensing to mid-scale competitors seeking EMA residual solvent compliance. For New Entrants and Emerging Players: Differentiate on cosmeceutical antioxidant positioning for Korean and Japanese beauty markets where premium pricing tolerates higher input costs. Target liquid extract formats for North American functional beverage and tincture manufacturers seeking rapid bioavailability claims. Pursue USDA organic certification for French cultivation zones to capture margin expansion in certified nutraceutical channels. For Investors and Strategic Acquirers: NMPA dual carbon mandate enforcement reshapes the acquisition landscape by raising compliance costs for smaller Shaanxi processors and accelerating consolidation. Long-term viability favors extractors with closed-loop extraction infrastructure and validated GMP-API quality systems. Monitor EMA pharmacovigilance guidance on anticoagulant interaction labeling as signal for regulatory burden trajectory and pharmaceutical channel access stability.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Scale-Up | Enables EMA residual solvent compliance without multiple purification stages for German API manufacturers. |
| Backward Integration into Controlled Cultivation | Secures organic certification arbitrage through captive French and German leaf supply programs. |
| Direct-to-Consumer Subscription Launch | Captures margin from bypassing pharmacy distributor markups in North American cognitive wellness channels. |
| Cosmeceutical Antioxidant Formulation Development | Penetrates Korean and Japanese beauty markets through premium dermal absorption positioning. |
| GMP-API Certification Investment | Unlocks THMP-registered prescription circulatory medicine contracts with German and French manufacturers. |
Methodological Framework
A standing panel of extraction facility technical directors, pharmaceutical procurement managers at German API manufacturers, EMA regulatory affairs consultants, and Shaanxi-Hunan processing cluster operators provided ongoing calibration across primary interviews and secondary validation. Bottom-up and top-down triangulation combined customs records from Chinese extract export filings, EMA THMP registration databases, FDA New Dietary Ingredient notification logs, and SEC filings from publicly traded nutraceutical marketers.
Outputs were validated against external benchmarks including EMA monograph compliance rates, supercritical CO2 extraction capacity installations, and organic certification penetration in European cultivation zones. The analytical framework modeled volume and value across product type, end user regulatory pathway, distribution channel control tier, and therapeutic application claim intensity. CAGRs were derived from regression analysis of historical procurement patterns and regulatory enforcement trajectory assumptions.
The analysis sits within stated boundaries; outcomes outside sustained EMA monograph enforcement, stable Anhui leaf harvest yields, or continued anticoagulant interaction scrutiny would require recalibration. Forecasts reflect assumptions regarding NMPA dual carbon mandate implementation pace and FDA pharmacovigilance labeling burden trajectory. Recalibration cycles align with material shifts in THMP registration volumes, biotechnological substitution rates, and organic certification program expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Coconut Syrup Market
Flavorings and Food Additives
Asia-Pacific Flavor and Fragrance Market
Flavorings and Food Additives
United States Food Flavor and Enhancer Market
Flavorings and Food Additives
Food Flavors & Flavor Enhancers Market
Flavorings and Food Additives
Smoked Dextrose Market
Flavorings and Food Additives
Roast Flavoring Market
Flavorings and Food Additives
Keto Friendly Flavors Market
Flavorings and Food Additives
Italy Food Colorants Market
Flavorings and Food Additives
Natural Flavors Market
Flavorings and Food Additives
Water Flavoring Drop Market
Flavorings and Food Additives
Tangerine Peel Extract Market
Flavorings and Food Additives
Pumpkin Spice Products Market
Flavorings and Food Additives
Smoked Condensates Market
Flavorings and Food Additives
Chicory Extract Market
Flavorings and Food Additives
Blueberry Extract Market
Flavorings and Food Additives
Global Beverage Flavoring Systems Market