
 Fenchol Market | 2026-2036
Fenchol Market Size, Share, and Industry Trends Forecast 2026-2036
Fenchol Market Intelligence
China is tilting toward biotransformation capacity for fenchol production, with Jiangxi Global Natural Spice Co., Ltd. leveraging its extraction infrastructure across provincial growing zones. Takasago International Corporation anchors its position through R&D intensity in enzymatic conversion pathways. Merck KGaA competes via pharmaceutical-grade certification and tight quality controls for European API markets.
Fenchol is a bicyclic monoterpene alcohol with a camphoraceous aroma profile, typically derived from essential oils such as basil or synthesized via pinene hydration, serving primarily as a fragrance modifier and flavoring intermediate in consumer goods. Natural fenchol commands premium positioning in fine fragrance formulations where ISO 9235 compliance matters, while synthetic fenchol dominates volume in mass-market personal care applications. Biotransformation methods are gaining fastest among production routes as enzyme engineering reduces solvent intensity and improves stereoselectivity for specific isomer targets.
REACH registration requirements in the European Union, alongside FDA food additive regulations in the United States, shape product specifications and cross-border market access for fenchol suppliers. China's SAMR oversees domestic terpene quality standards and biomanufacturing facility licensing. Stakeholders must monitor evolving biocidal product regulations in Europe, where fenchol's insect-repellent applications face separate BPR compliance pathways distinct from fragrance and flavor registrations.
Market Dynamics
Biomanufacturing scale-up is compressing fenchol production economics as enzyme engineering matures, forcing legacy chemical synthesis to defend cost positions against stereoselective biocatalysis.
Growth Catalysts
- REACH purity mandates:ECHA registration requirements for terpene imports are filtering low-grade suppliers, concentrating procurement among certified extractors serving European fragrance houses.
- Basil cultivation expansion:Jiangxi province extraction facilities are scaling raw material throughput to capture downstream flavor compounder demand.
- Enzymatic conversion maturation:Biotransformation pathways are achieving commercial yields that narrow the cost gap with pinene hydration routes.
Market Restraints
- Pinene feedstock volatility:Turpentine derivative pricing fluctuates with paper industry output cycles, squeezing synthetic fenchol margins.
- Natural extraction concentration:Basil oil sourcing clusters in specific growing zones, exposing supply chains to climate and agricultural policy shocks.
- Stereoisomer complexity:α-fenchol and β-fenchol separation requirements add purification costs that synthetic routes partially avoid.
Strategic Opportunities
- Insect-repellent bioproducts:Fenchol's mosquito-deterrent properties open BPR-registered applications outside fragrance, requiring separate compliance investment.
- Pharmaceutical-grade certification:API markets reward GMP-compliant terpene suppliers with premium positioning in European drug manufacturing.
- ISO 9235 natural labeling:Certified natural fenchol commands price premiums in fine fragrance formulations where clean-label positioning drives selection.
Industry Challenges
- Biocatalyst engineering talent:Protein design and fermentation scale-up expertise remains scarce relative to chemical process engineering pools.
- Dual registration burden:Suppliers serving both fragrance and biocidal applications must maintain parallel REACH and BPR compliance systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fenchol Market |
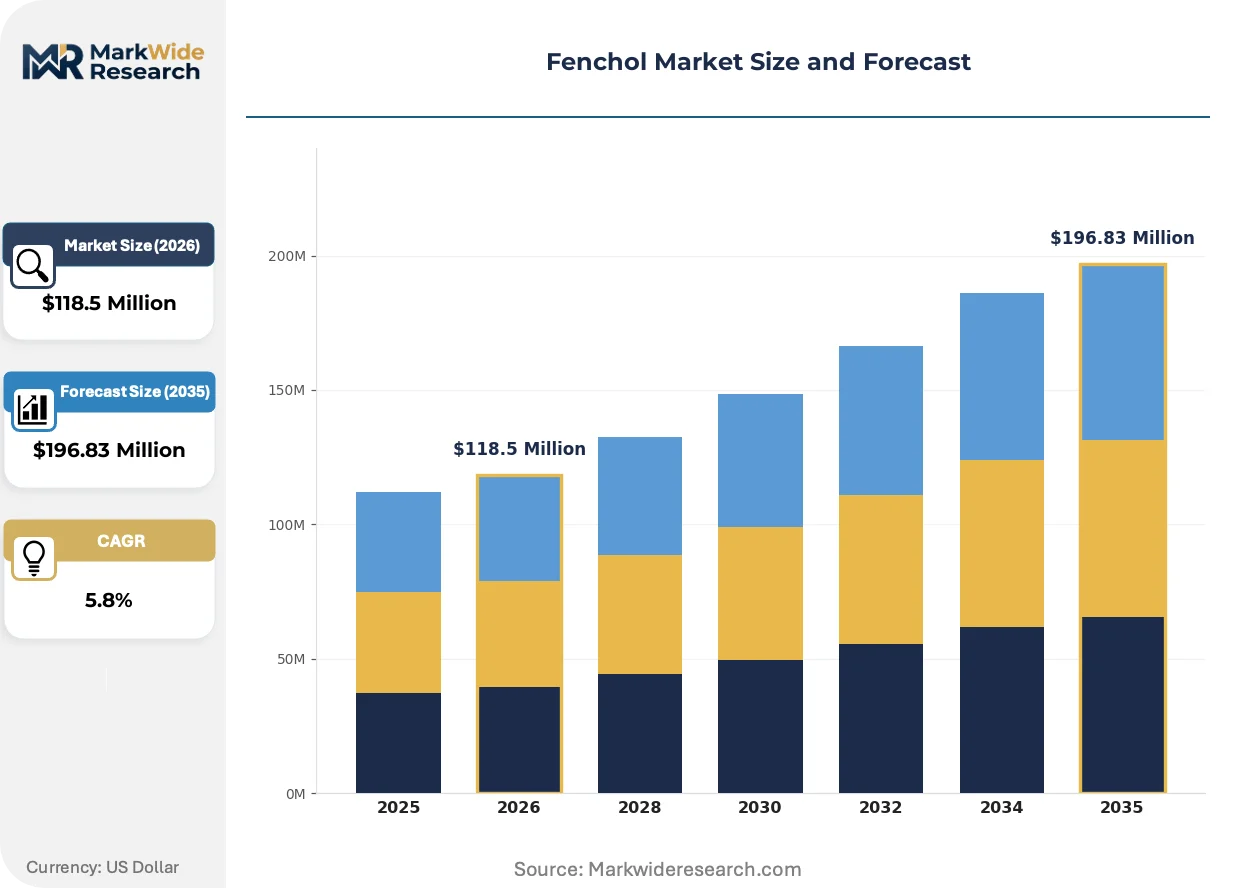
| Market Size in 2026 | $118.5 Million |
| Market Size in 2035 | $196.83 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Fenchol, Synthetic Fenchol, Fenchol Isomers, Fenchol Derivatives Application: Fragrances, Flavoring Agents, Insect Repellents, Pharmaceuticals, Personal Care Products Production Method: Extraction, Biotransformation, Chemical Synthesis, Fermentation Distribution Channel: Direct Sales, Distributors, Online Marketplaces, Wholesale Suppliers |
| Companies Covered | Merck KGaA, Takasago International Corporation, Bedoukian Research Inc., Penta Manufacturing Company, Jiangxi Global Natural Spice Co., Ltd., Foreverest Resources Ltd., Nanning Venusson Bio-Technology Co., Ltd., Pfaltz and Bauer Inc., Augustus Oils Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fenchol Market Strategic Shifts & Innovations
Production technology divergence is fragmenting competitive advantage sources, with biological and chemical routes pursuing incompatible scale economics and customer qualification requirements.
Biocatalytic fenchol synthesis is migrating from pilot-scale demonstration to commercial deployment as engineered oxidoreductases achieve space-time yields competitive with acid-catalyzed pinene hydration. Fragrance houses in Grasse and Paris are qualifying enzymatic batches for fine perfume formulations where stereochemical purity determines odor profile. This technology shift is compressing the viable scale threshold for new market entry, favoring mid-size biomanufacturing investments over petrochemical-scale chemical plants.
REACH Article 33 disclosure obligations are tightening supply chain transparency requirements for terpene importers into the European Union. Substance volume tracking and downstream user communication mandates are increasing administrative overhead for traders serving multiple fragrance compounders. Small-batch natural extractors in China are responding by consolidating shipments through larger intermediaries capable of maintaining SVHC documentation systems.
Fragrance compounders are consolidating supplier panels to reduce qualification burden, compressing the viable vendor base for fenchol procurement. Mass-market personal care brands are shifting volume toward synthetic grades with consistent specifications, while fine fragrance houses concentrate natural sourcing among pre-certified extractors. This bifurcation is most visible in China, where domestic flavor and fragrance multinationals are building captive extraction relationships in Jiangxi growing zones.
Fenchol Market Segmentation
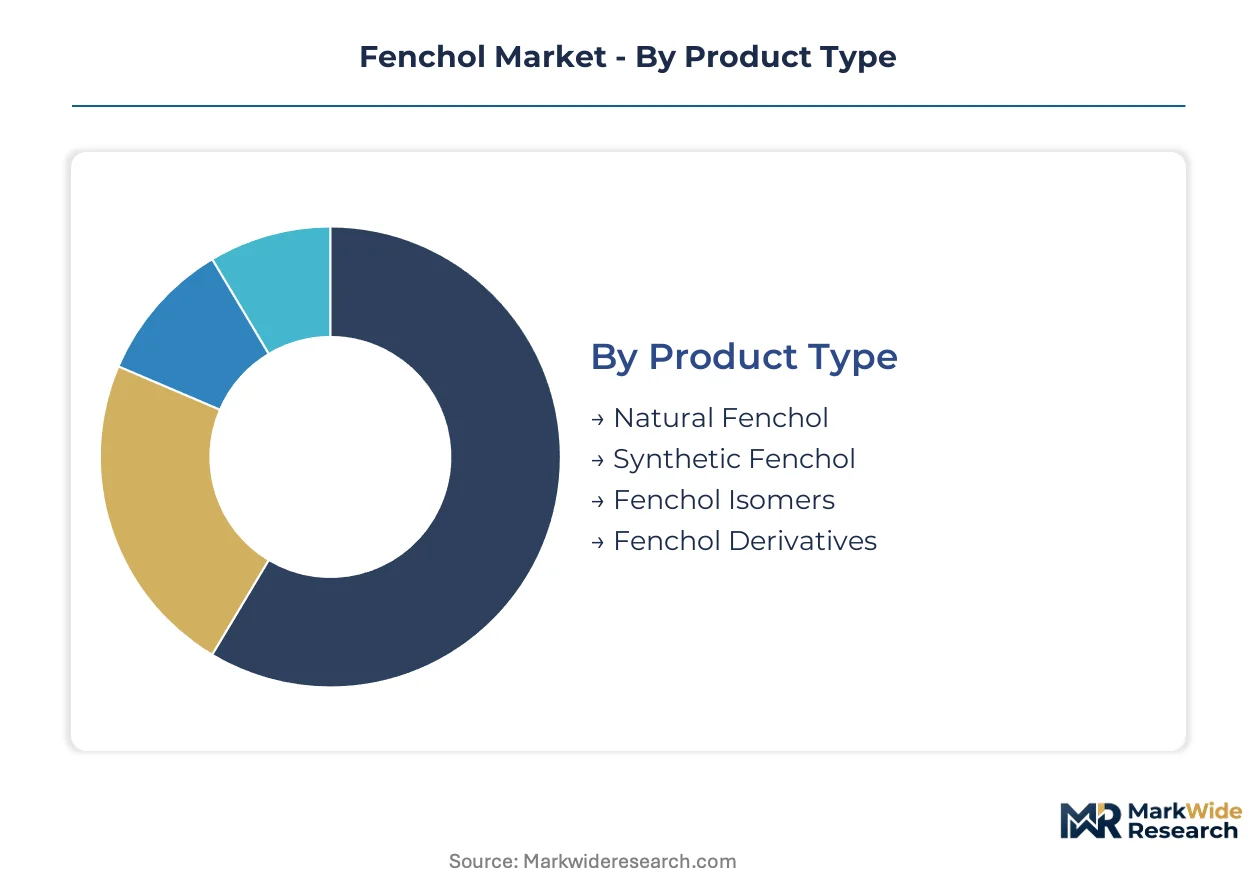
Fenchol's commercial structure fragments across certification grades, production technologies, and regulatory pathways. Each segmentation axis carries distinct margin profiles and compliance burdens that reshape supplier competitive positioning.
Product Type:
Natural certification tiers command premium positioning in fragrance formulations, while synthetic grades dominate volume applications through cost-engineered specifications.
- Natural Fenchol:Derived from basil essential oil with ISO 9235 compliance for fine fragrance labeling. Procurement concentrates among Grasse and Paris fragrance houses where clean-label positioning drives selection, constrained by REACH Article 33 disclosure requirements for EU importers.
- Synthetic Fenchol:Manufactured via pinene hydration with consistent stereochemical profiles for mass-market personal care. Demand clusters in China where domestic compounders prioritize cost stability over natural certification, though feedstock volatility from paper industry turpentine cycles squeezes margins.
- Fenchol Isomers:α-fenchol and β-fenchol separation adds purification overhead that enzymatic routes increasingly circumvent through stereoselective biocatalysis.
- Fenchol Derivatives:Functionalized analogs for pharmaceutical API intermediates requiring GMP certification and EMA-compliant documentation.
The dominant share belongs to Synthetic Fenchol, while Natural Fenchol is closing the gap fastest through fragrance house consolidation around certified extractors.
Application:
End-use specifications diverge sharply between sensory-driven fragrance selection and efficacy-regulated biocidal registration.
- Fragrances:Fine perfume formulations in Paris and Grasse demand stereochemical precision for odor profile consistency. Natural grades with full supply chain documentation command 40-60% price premiums over synthetic alternatives in this segment.
- Flavoring Agents:Food-grade fenchol requires FDA or EFSA safety assessments with strict purity thresholds for ingestion applications, concentrating procurement among pharmaceutical-certified suppliers.
- Insect Repellents:Biocidal Product Regulation compliance in Europe creates parallel registration pathways distinct from fragrance approvals, favoring suppliers with dedicated regulatory affairs capacity.
- Pharmaceuticals:API-grade material demands GMP manufacturing and ICH Q3C residual solvent compliance, with European drug manufacturers paying substantial premiums for qualified terpene sources.
- Personal Care Products:Mass-market brands prioritize synthetic consistency and scale economics over natural certification, consolidating volumes through distributor relationships.
Fragrances holds the largest revenue position, though Insect Repellents is expanding most quickly through BPR-registered product development.
Production Method:
Technology selection determines capital intensity, regulatory qualification burden, and access to premium customer segments.
- Extraction:Basil oil distillation in Jiangxi province serves natural-grade demand with agricultural supply chain exposure to climate and policy shocks.
- Biotransformation:Engineered oxidoreductase pathways achieve stereoselective conversion with reduced solvent intensity, narrowing cost gaps with chemical synthesis as enzyme engineering matures.
- Chemical Synthesis:Acid-catalyzed pinene hydration dominates volume production but faces margin compression from biomanufacturing scale-up and stereoisomer complexity.
- Fermentation:Microbial cell factory approaches remain pre-commercial for fenchol specifically, though platform technologies from adjacent terpene production suggest future viability.
Chemical Synthesis retains volume leadership, while Biotransformation is gaining share fastest through fragrance house qualification of enzymatic batches.
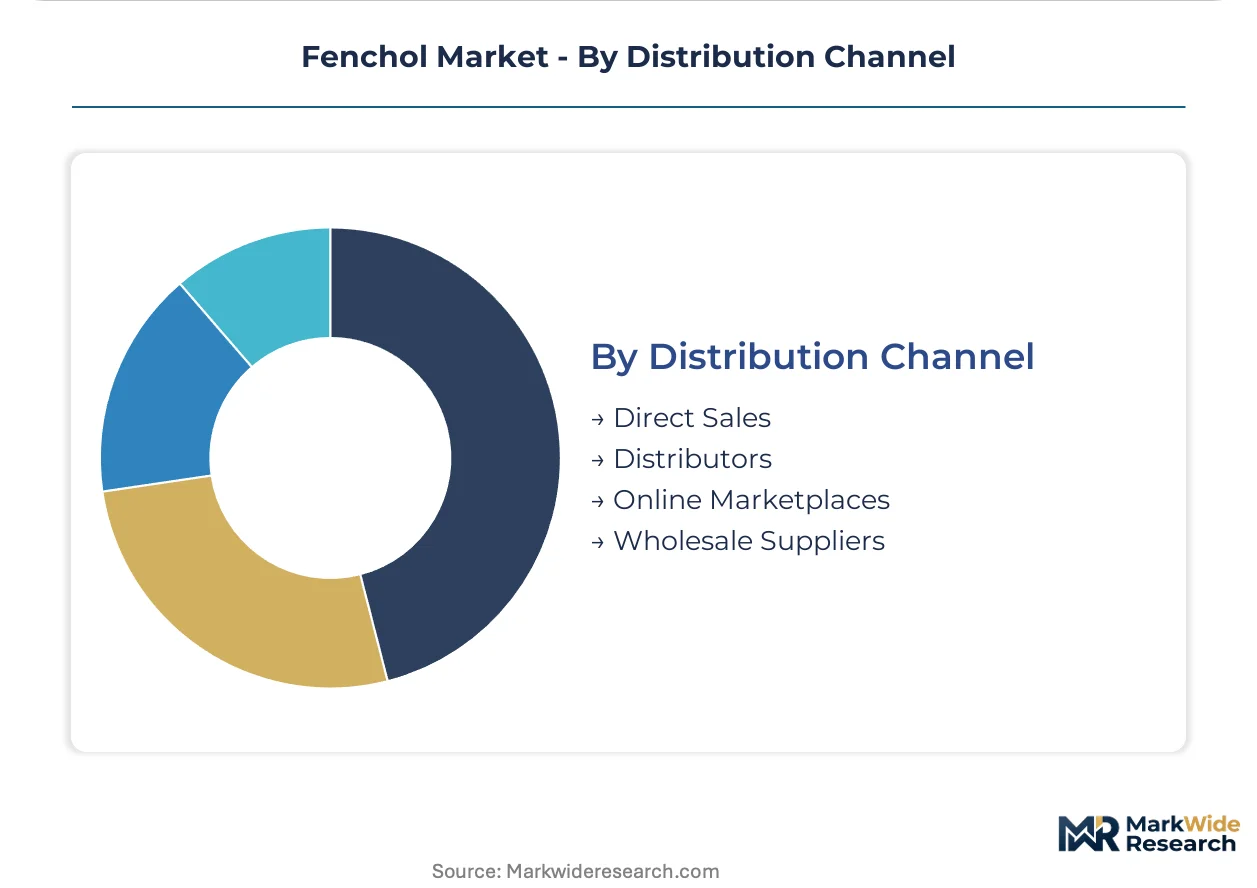
Distribution Channel:
Channel structure reflects customer scale, documentation requirements, and the fragmentation of end-use specifications across regulatory jurisdictions.
- Direct Sales:Captive relationships between Jiangxi extractors and domestic Chinese flavor multinationals, or between certified European suppliers and Grasse fragrance houses, minimize documentation handoff friction.
- Distributors:Regional intermediaries maintain SVHC tracking systems for REACH compliance, consolidating small-batch Chinese extractor shipments for European compounder panels.
- Online Marketplaces:Limited to standard-grade synthetic material with generic specifications, constrained by chemical substance registration requirements for cross-border trade.
- Wholesale Suppliers:Volume aggregation for personal care manufacturers prioritizing cost efficiency over supply chain transparency, with limited penetration in fine fragrance or pharmaceutical segments.
Direct Sales commands the dominant position, while Distributors is climbing fastest through REACH documentation consolidation services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extraction infrastructure clusters heavily in Jiangxi province, while fragrance qualification and pharmaceutical certification concentrate in Western European industrial basins. This geographic split shapes procurement patterns across natural and synthetic grade segments.
China
Jiangxi province hosts expanding basil oil extraction facilities serving domestic flavor compounders. SAMR oversees terpene quality standards and biomanufacturing facility licensing with tightening purity mandates. Nanning and Nanchang anchor the natural fenchol supply base, with provincial growers scaling cultivation to capture downstream fragrance demand.
France
Grasse and Paris fragrance houses drive premium natural fenchol procurement for fine perfume formulations. REACH Article 33 disclosure obligations filter supplier panels toward certified extractors with full SVHC documentation. The Provence-Alpes-Côte d'Azur cluster concentrates compounding expertise where ISO 9235 compliance determines selection.
Germany
Pharmaceutical-grade fenchol demand from Merck KGaA and European drug manufacturers rewards GMP-certified terpene suppliers. ECHA registration requirements for terpene imports enforce purity thresholds that exclude low-grade sources. The Rhine-Main and Bavarian chemical corridors host API-grade qualification and ICH Q3C residual solvent testing capacity.
United States
FDA food additive regulations shape fenchol specifications for flavoring agent applications with strict ingestion safety thresholds. Personal care manufacturers in New Jersey and California prioritize synthetic grades with consistent specifications for mass-market brands. The EPA registers fenchol for insect-repellent applications under separate biocidal pathways distinct from fragrance approvals.
Japan
Takasago International Corporation anchors R&D intensity in enzymatic conversion pathways for stereoselective fenchol production. METI supports biomanufacturing scale-up through industrial technology grants targeting reduced solvent intensity. The Kansai region concentrates fragrance technology development where engineered oxidoreductases achieve odor profile precision.
Fenchol Market Key Industry Players
Specialized extractors and diversified chemical conglomerates split the market across incompatible scale economics. The vendor base organizes around three strategic archetypes: natural extraction specialists with agricultural supply chain control, synthetic terpene producers with petrochemical feedstock access, and biomanufacturing innovators with enzyme engineering capabilities. Competitive moves concentrate on backward integration into basil cultivation and captive supply of pharmaceutical-grade certification.
Among diversified chemical conglomerates, Merck KGaA occupies a position exemplifying pharmaceutical-grade terpene supply with European regulatory qualification. Takasago International Corporation represents the biomanufacturing innovation archetype, anchoring enzymatic conversion expertise within Japanese industrial technology clusters. Jiangxi Global Natural Spice Co., Ltd. sits within the natural extraction specialist tier, with geographic naming indicating Chinese provincial concentration in Jiangxi growing zones.
| Leading Market Players |
|---|
| Merck KGaA |
| Takasago International Corporation |
| Bedoukian Research Inc. |
| Penta Manufacturing Company |
| Jiangxi Global Natural Spice Co., Ltd. |
| Foreverest Resources Ltd. |
| Nanning Venusson Bio-Technology Co., Ltd. |
| Pfaltz and Bauer Inc. |
| Augustus Oils Ltd. |
| Others |
Cost & Logistics Intelligence
Jiangxi province's basil oil extraction clusters concentrate upstream supply control, funneling margin capture toward fragrance houses in Grasse and Paris that command ISO 9235 certification premiums. REACH Article 33 disclosure obligations add compliance overhead that synthetic-grade traders absorb through volume scale, while natural-grade suppliers pass documentation costs downstream to fine fragrance compounders.
Pricing Analysis
REACH registration dictates the pricing tier structure across the European trade corridor, separating GMP-certified pharmaceutical grades from standard fragrance and food-additive specifications. Three-tier pricing structure across premium certified-natural, mid-grade synthetic, and economy unlabeled tiers reflects certification investment and stereochemical purity. Cost compression in synthetic grades is intensifying because pinene feedstock volatility from paper industry turpentine cycles squeezes hydration-route margins. Mass-market personal care manufacturers exhibit highest price sensitivity, while API-grade pharmaceutical buyers accept substantial premiums for qualified European sources.
Supply Chain Analysis
Contract manufacturing for enzymatic conversion concentrates with Takasago International Corporation's Kansai facilities and emerging Chinese biotransformation specialists. Raw material sourcing draws from Jiangxi basil cultivation zones, turpentine derivative streams from paper industry byproducts, and engineered oxidoreductase enzyme supplies from Japanese and European biotechnology foundries. Single-source vulnerability runs through Jiangxi agricultural concentration exposed to climate shocks and provincial water policy shifts. Distribution runs through direct captive relationships for premium natural grades, with regional distributors consolidating REACH documentation for fragmented Chinese extractor shipments into European compounder panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic biotransformation maturity is disrupting legacy pinene hydration economics, creating a technology inflection that rewards enzyme engineering capabilities and GMP certification investments across the forecast horizon.
For Market Incumbents: Build regulatory moats through dual REACH-BPR registration systems that emerging biotransformation specialists cannot easily replicate. Deepen backward integration into Jiangxi basil cultivation through offtake agreements with provincial growers, securing raw material priority as climate volatility intensifies. Defend against synthetic-grade margin compression by accelerating pharmaceutical-grade certification timelines for European API markets.
For New Entrants and Emerging Players: Japanese biotransformation technology licensing represents the most penetrable entry vector, where METI-supported enzyme engineering programs reduce R&D capital requirements. Target insect-repellent biocidal applications as a white-space segment with separate BPR compliance pathways that incumbent fragrance specialists have underdeveloped. Pursue direct sales relationships with Chinese domestic flavor multinationals building captive extraction partnerships in Jiangxi growing zones.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed natural extraction specialists holding Jiangxi agricultural supply chain control but lacking biotransformation scale-up expertise. The five-to-ten year viability window favors acquisition of enzymatic conversion platform technologies from adjacent terpene production, where protein engineering and fermentation scale-up capabilities transfer across molecules. Monitor ECHA registration withdrawal rates for low-grade synthetic suppliers as the signal to watch for consolidation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Basil Cultivation | Jiangxi provincial growing zone control secures raw material priority against climate-exposed competitors. |
| Dual REACH-BPR Registration Investment | Parallel compliance systems unlock insect-repellent biocidal revenue streams beyond fragrance applications. |
| Enzymatic Conversion Scale-Up | Engineered oxidoreductase deployment narrows cost gaps with pinene hydration while improving stereoselectivity. |
| Pharmaceutical-Grade GMP Certification | EMA-compliant documentation commands premium positioning in European API manufacturing supply chains. |
| Captive Distributor Consolidation | SVHC documentation systems aggregate fragmented Chinese extractor shipments for REACH-compliant European trade. |
Research Approach
A standing panel of fragrance house procurement directors, Jiangxi extraction facility managers, enzyme engineering R&D leads, and ECHA regulatory affairs specialists provided ongoing calibration across the study period. Primary interview insights combined with secondary validation from customs trade databases, REACH registration filings, SAMR facility licensing records, and SEC 10-K disclosures from diversified chemical conglomerates. Bottom-up volume modeling from individual extractor capacities triangulated against top-down demand estimates from fragrance compounder consumption patterns.
Scenario-bracketing anchored the analytical framework across the projection horizon, testing enzyme engineering maturation timelines against pinene feedstock volatility assumptions. Segmentation dimensions modeled include certification grade tier, end-use application, production technology route, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to baseline volume estimates, with cross-checks against pharmaceutical API demand trends and biocidal product registration pipelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese biotransformation specialists or accelerated METI funding for enzyme engineering would shift outcomes beyond modeled ranges. Quarterly review of ECHA registration withdrawal rates, Jiangxi provincial water policy announcements, and fragrance house supplier panel consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Food Grade Menthol Crystal Market
Flavorings and Food Additives
Food Texturizers Market
Flavorings and Food Additives
Edible Food Paints Market
Flavorings and Food Additives
Global Paprika Oleoresin Market
Flavorings and Food Additives
Lemon Oil Market
Flavorings and Food Additives
Argentina Food Flavor and Enhancer Market
Flavorings and Food Additives
Menthol Market
Flavorings and Food Additives
Tangerine Essential Oil Market
Flavorings and Food Additives
FTNF Flavors Market
Flavorings and Food Additives
Global Artichoke Extract Market
Flavorings and Food Additives
Global Anthocyanin Market
Flavorings and Food Additives
Roast Flavoring Market
Flavorings and Food Additives
Poria Cocos Extract Market
Flavorings and Food Additives
Orange Essential Oil Market
Flavorings and Food Additives
North America Vanilla and Vanillin Market
Flavorings and Food Additives
Natural and Organic Flavors Market