
 Commercial Aerospace Market | 2026-2036
Commercial Aerospace Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aerospace Market Analysis
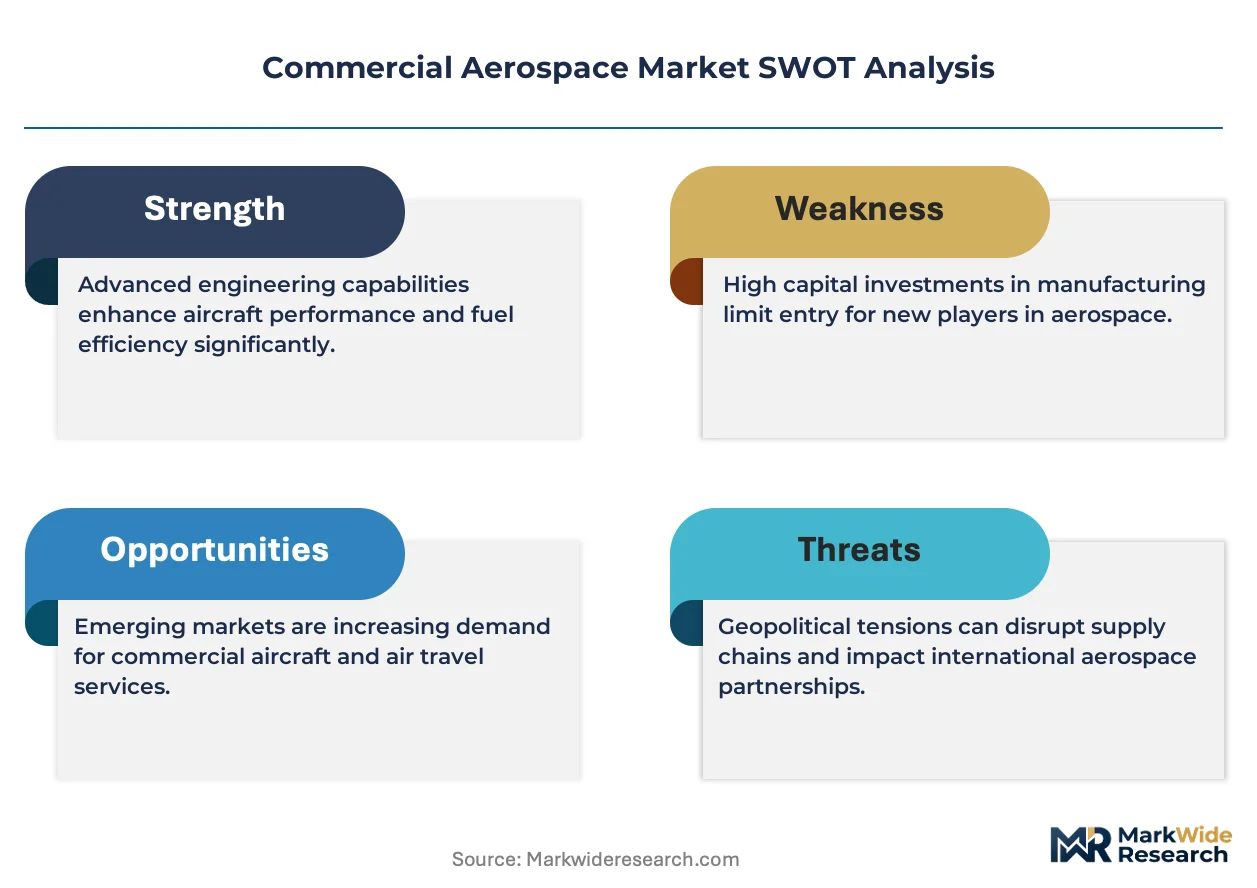
The capital-intensity divergence between full-airframe integrators and tier-two suppliers is unwinding as OEMs internalize critical subsystems. Boeing sustains enormous manufacturing scale across its Everett and Charleston complexes. Airbus dominates the single-aisle category with its A320 family production lines in Toulouse, Hamburg, and Mobile. Spirit AeroSystems navigates structural consolidation pressures as the largest independent aerostructures supplier.
Commercial aerospace encompasses the design, manufacture, and support of aircraft operated for profit, typically featuring aluminum-lithium alloys and carbon-fiber reinforced polymers in primary structures to achieve operating empty weights below fifty percent of maximum takeoff mass. These platforms serve scheduled passenger transport, cargo logistics, and specialized mission profiles requiring pressurized cabins certified to differential pressures exceeding eight psi. Airliners anchor the value pool as airlines prioritize fuel-efficient narrow-bodies for route density expansion. Advanced composites displace conventional aluminum in wing and fuselage applications, concentrating margin capture among specialized material suppliers. Propulsion systems command sustained aftermarket revenue through engine overhaul cycles tied to flight-hour accumulation.
FAA certification requirements under Part 25 shape airframe design standards and production approval timelines for US-market aircraft. EASA's CS-25 framework and the EU Green Deal emissions benchmarks constrain European fleet planning and propulsion technology roadmaps. China's CAAC and NMPA parallel pathways increasingly influence supplier qualification for Asia-Pacific deliveries. Stakeholders must monitor regulatory divergence on sustainable aviation fuel blending mandates and carbon border adjustments affecting long-haul fleet economics.
Market Dynamics
Airlines are compressing fleet renewal cycles as fuel economics and emissions mandates force earlier retirements of aging narrow-bodies, concentrating procurement power among lessors and flag carriers with balance-sheet capacity.
Growth Catalysts
- Sustainable Aviation Fuel mandates:The EU Green Deal's blending requirements are forcing refiners to scale hydrotreated esters and fatty acids production, creating captive demand for biofuel-compatible engine platforms.
- India's airport privatization wave:Greenfield terminals in Navi Mumbai and Jewar are unlocking route density for low-cost carriers, driving narrow-body orders from domestic start-ups.
- Thermoplastic composites:Automated fiber placement of PEEK-based polymers is cutting wing component cycle times by half, rewarding early adopters with assembly line throughput gains.
Market Restraints
- Titanium sponge supply concentration:Russian and Ukrainian feedstock disruptions have shifted sourcing to Chinese and Japanese smelters, exposing airframers to price volatility in landing gear forgings.
- FAA-EASA certification divergence:Differing interpretation of single-pilot operational concepts is forcing redundant flight control architectures, inflating development costs for cockpit avionics suppliers.
- Skilled composite technician scarcity:Layup certification programs require 18-month apprenticeships, constraining output at tier-two aerostructures facilities in Wichita and Broughton.
Strategic Opportunities
- Vietnam's open skies agreements:Bilateral traffic rights with ASEAN neighbors are enabling point-to-point international routes, creating demand for 150-seat aircraft from VietJet and Bamboo Airways.
- Digital thread integration:Model-based systems engineering is collapsing design-to-manufacturing handoffs, allowing OEMs to compress first-flight schedules for derivative programs.
- US Inflation Reduction Act clean fuel credits:Section 45Q incentives for carbon capture at refineries are improving SAF project economics, drawing capital to Gulf Coast production hubs.
Industry Challenges
- Airworthiness directive backlogs:FAA staffing constraints are extending supplemental type certificate approval timelines, delaying cabin reconfiguration programs for retrofit specialists.
- Legacy MRO software integration:Predictive maintenance platforms require API bridges to 1990s-era inventory systems, fragmenting data visibility across airline technical operations divisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aerospace Market |
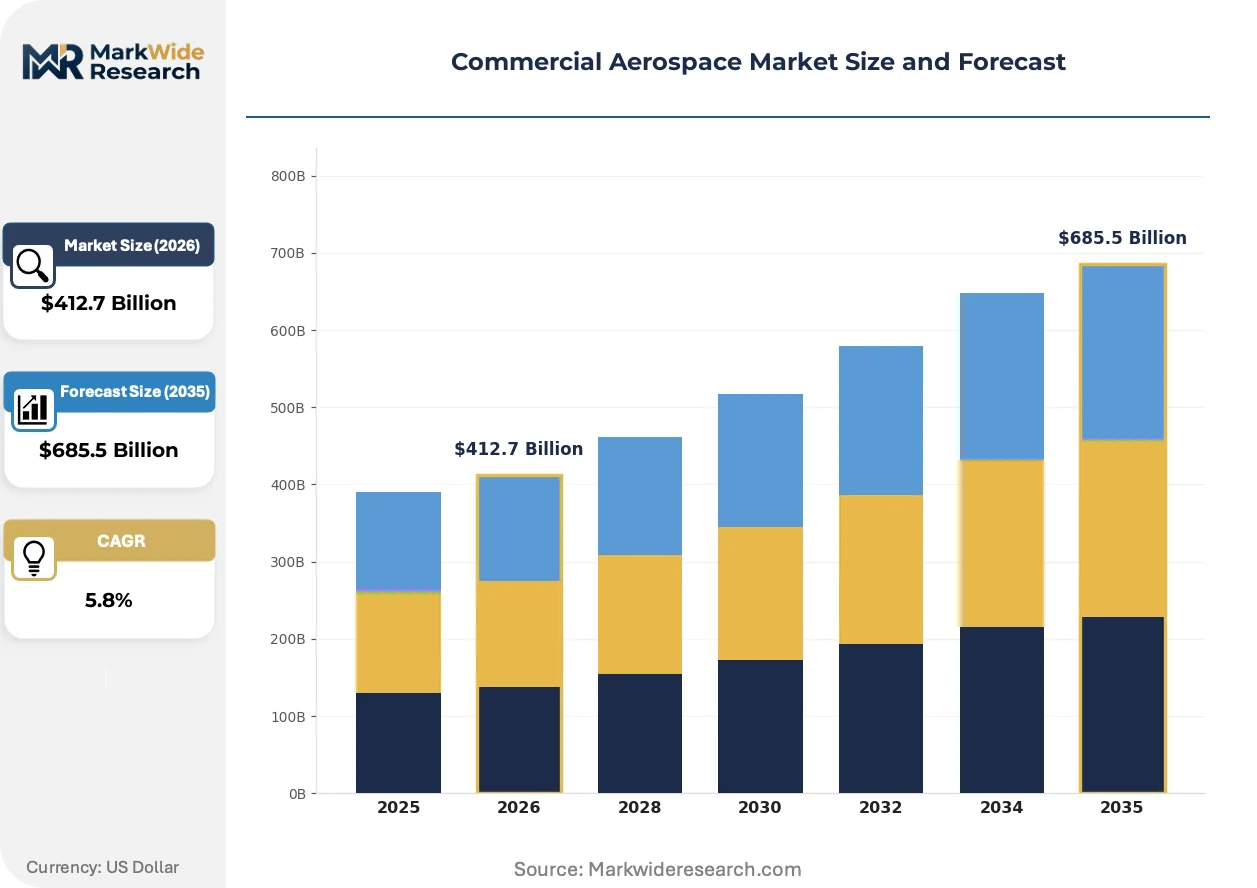
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $685.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Airliners, Business Jets, Helicopters, Cargo Aircraft Technology: Advanced Composites, Avionics, Lightweight Materials, Propulsion Systems End User: Airlines, Charter Services, Freight Operators, Private Owners Application: Commercial Transport, Air Cargo, Special Mission, VIP Transport |
| Companies Covered | Howmet Aerospace, GE Aviation, Boeing, Loar Holdings, FTAI Aviation, Airbus, Spirit AeroSystems, L3Harris Technologies, Embraer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aerospace Market Emerging Trajectories
Propulsion electrification and airframe digitalization are converging to redefine platform economics, while regulatory pressure on lifecycle emissions accelerates technology substitution timelines.
Advanced thermoplastic composites are displacing thermoset prepregs in wing rib and spar applications. Airbus and Boeing are qualifying automated fiber placement lines for PEEK-based laminates at their Broughton and Kinston facilities. The shift is displacing autoclave curing bottlenecks, compressing wing box assembly cycles from weeks to days.
EASA's CS-25 amendments on single-pilot operations during cruise phases are forcing flight control redundancy upgrades. The regulation is mandating enhanced autopilot fail-operational architectures for new type certifications. Long-haul twin-aisle programs targeting 2030 entry-into-service are absorbing the largest systems integration costs.
Power-by-the-hour contracts are displacing traditional time-and-material MRO arrangements. Lessors like AerCap and SMBC Aviation Capital are bundling engine coverage with airframe heavy checks, compressing airline procurement cycles. The model is most visible in Southeast Asia, where flag carriers lack in-house overhaul capacity.
Commercial Aerospace Market Segmentation
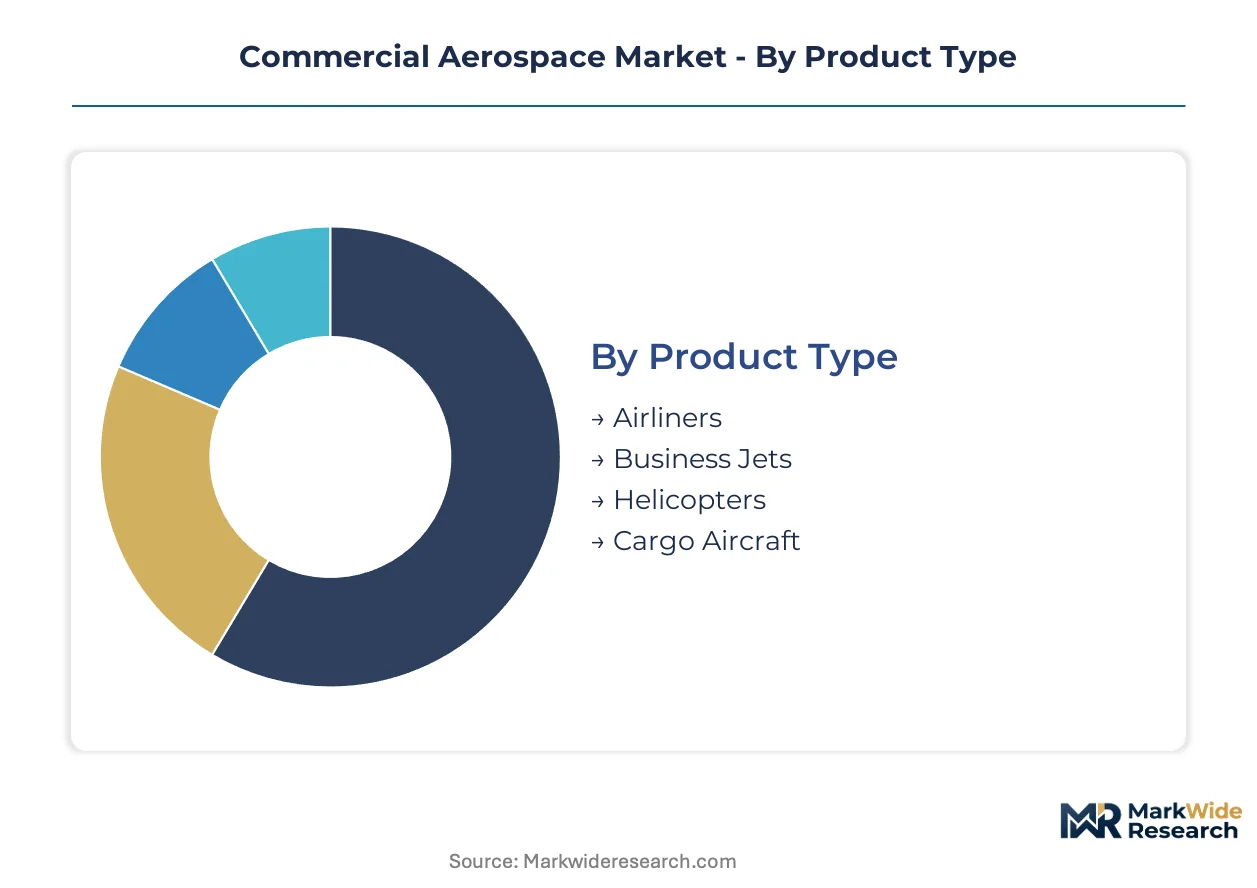
Segmentation in commercial aerospace reveals how capital allocation, regulatory pressure, and route economics fragment procurement patterns across platform categories. Understanding these divisions exposes where OEMs capture margin versus where price competition dominates.
Product Type:
Margin pools concentrate in narrow-body airliners where production scale and aftermarket parts commonality protect pricing power, while wide-body profitability erodes amid demand cyclicality.
- Airliners:Single-aisle platforms dominate fleet renewal programs across India and Vietnam, with airlines prioritizing fuel burn metrics over cabin amenities for sub-four-hour sectors. Airbus A320 family and Boeing 737 MAX production backlogs extend through the decade, concentrating supplier leverage among engine OEMs and avionics integrators.
- Business Jets:Super-mid and large-cabin categories absorb the strongest pricing power as fractional ownership models expand in the US and Middle East. Gulfstream and Bombardier defend margins through bespoke cabin completion services that extend delivery timelines but capture 40% of platform lifetime value.
- Helicopters:Offshore oil-and-gas transport and emergency medical services drive twin-engine turbine demand, particularly in Brazil's pre-salt basin operations.
- Cargo Aircraft:E-commerce fulfillment networks are converting passenger wide-bodies through supplemental type certificates, pressuring feedstock availability for dedicated freighter programs.
The dominant share belongs to Airliners, while Business Jets is closing the gap fastest.
Technology:
Cost tier stratification separates qualified aerospace-grade systems from commercial-off-the-shelf alternatives, with certification burden determining viable supplier pools.
- Advanced Composites:Thermoplastic automated fiber placement is displacing thermoset autoclave curing at Airbus Broughton and Boeing Kinston facilities, cutting wing box cycle times from weeks to days. PEEK-based laminates now qualify for primary structure loads, rewarding early adopters with throughput gains and scrap reduction.
- Propulsion Systems:Turbofan architectures command the largest aftermarket revenue pools through power-by-the-hour contracts tied to flight-hour accumulation. Pratt & Whitney geared turbofan and CFM LEAP programs concentrate MRO demand in Southeast Asia where flag carriers lack in-house overhaul capacity.
- Avionics:Single-pilot operational concepts are forcing redundant flight control architectures under EASA CS-25 amendments, inflating development costs for cockpit systems suppliers.
- Lightweight Materials:Titanium sponge supply disruptions from Russian and Ukrainian feedstock sources have shifted sourcing to Chinese and Japanese smelters, exposing airframers to price volatility in landing gear forgings.
Propulsion Systems holds the dominant share, though Advanced Composites is expanding most quickly as OEMs internalize critical subsystems.
End User:
Customer type determines contract structure, with lessors extracting volume discounts unavailable to balance-sheet-constrained operators.
- Airlines:Full-service carriers and low-cost operators drive divergent specification requirements—lie-flat seats and premium cabins versus maximum seat density and quick-turn galleys. India's airport privatization wave at Navi Mumbai and Jewar is unlocking route density for domestic start-ups with narrow-body orders concentrated at Airbus and Boeing.
- Freight Operators:Integrators like FedEx and DHL operate dedicated freighter fleets with 30-year asset horizons, prioritizing dispatch reliability over fuel efficiency in procurement criteria.
- Charter Services:On-demand operators in the US and Europe favor mid-cabin business jets with 5,000nm range for transatlantic missions without fuel stops.
- Private Owners:Ultra-high-net-worth individuals in the Middle East and Asia-Pacific specify VIP completion standards that extend delivery timelines 12-18 months beyond green airframe production.
Airlines commands the dominant share, while Freight Operators is gaining share fastest as e-commerce reshapes air cargo networks.
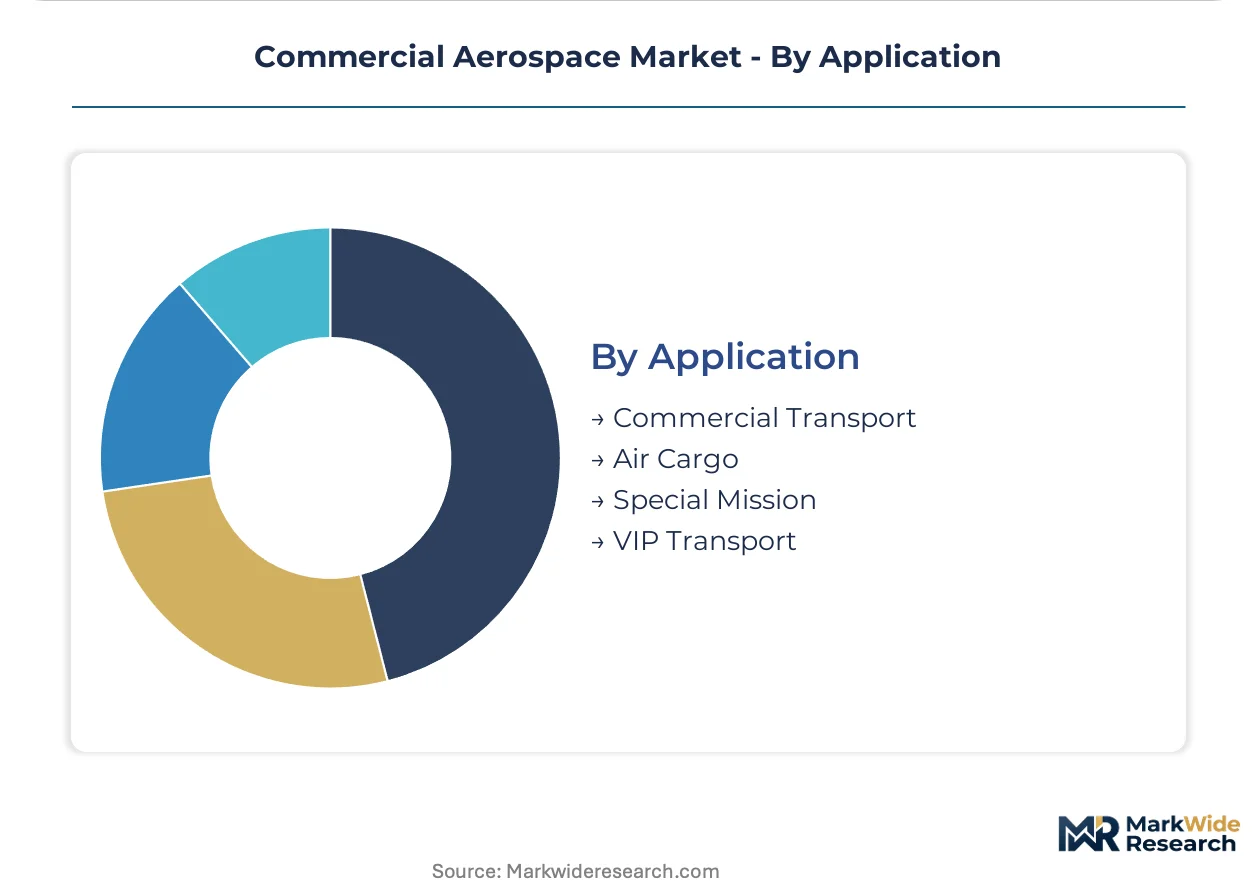
Application:
Volume concentration in scheduled passenger transport obscures margin variation across mission profiles, with specialized applications commanding premium pricing for limited competition.
- Commercial Transport:Scheduled passenger operations absorb 70% of airliner deliveries, with route density economics favoring 180-seat narrow-bodies over regional jets for hub-and-spoke networks. Asia-Pacific traffic recovery is outpacing North American and European growth rates, shifting delivery priority to Vietnam and India.
- Air Cargo:Belly-hold capacity constraints during passenger fleet groundings accelerated dedicated freighter demand, though conversion feedstock scarcity now limits expansion. Amazon Air and Alibaba's Cainiao are building captive fleets with specifications optimized for parcel density rather than palletized freight.
- Special Mission:Maritime patrol, airborne early warning, and signals intelligence platforms require extensive systems integration that extends development timelines and protects incumbent suppliers.
- VIP Transport:Head-of-state and corporate shuttle configurations demand electromagnetic hardening and secure communications suites that add 15-25% to platform cost.
Commercial Transport holds the dominant share, while Air Cargo is climbing the fastest as supply chain resilience priorities reshape fleet planning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in US and French manufacturing clusters where OEM final assembly lines command supplier discounts unavailable elsewhere. Asian operators absorb delivery premiums as they lack indigenous narrow-body alternatives. Regulatory divergence between FAA and EASA certification timelines fragments aftermarket service economics.
United States
Domestic carriers are accelerating 737 MAX fleet deployments as travel demand recovers to pre-pandemic levels. The FAA's Part 25 certification framework shapes airframe design standards for all US-market aircraft. Everett and Charleston production complexes anchor Boeing's manufacturing footprint, with Charleston expanding final assembly capacity for the 787 program.
France
Airbus commands single-aisle backlog dominance through A320 family production scaling. EASA's CS-25 amendments on emissions benchmarks constrain European fleet planning timelines. Toulouse and Hamburg final assembly lines coordinate output across the A220, A320, and A350 programs, with Hamburg specializing in cabin customization for premium carriers.
China
CAAC certification pathways increasingly influence supplier qualification for Asia-Pacific deliveries as COMAC C919 enters service. The country's national aviation regulator maintains parallel type certification requirements that extend timelines for Western OEMs. Shanghai and Tianjin assembly facilities concentrate domestic narrow-body production and import substitution efforts.
India
Airport privatization at Navi Mumbai and Jewar terminals unlocks route density for low-cost carrier expansion. The Directorate General of Civil Aviation enforces airworthiness standards aligned with ICAO annexes. Bangalore and Hyderabad aerospace clusters host engine MRO facilities and component manufacturing for global supply chains.
Vietnam
Open skies agreements with ASEAN neighbors enable point-to-point international route proliferation. The Civil Aviation Administration of Vietnam coordinates bilateral traffic rights that shape fleet requirements. Ho Chi Minh City and Hanoi bases anchor VietJet and Bamboo Airways growth strategies focused on 150-seat aircraft procurement.
Commercial Aerospace Market Vendor Landscape
Concentration sits with full-airframe integrators who internalize critical subsystems and compress tier-two supplier margins. Boeing and Airbus command duopoly pricing power in narrow-body categories where production backlogs extend through the decade. Two strategic archetypes dominate: diversified conglomerates with defense-aerospace portfolios, and specialized aerostructures suppliers exposed to OEM insourcing pressure. Competitive moves center on backward integration into avionics and propulsion systems, plus geographic expansion of final assembly capacity to capture local content requirements.
Among US-based integrators, Boeing represents the manufacturing-scale archetype with dual final assembly complexes. GE Aviation exemplifies the propulsion-systems specialist position through engine platform development and aftermarket service contracts. Howmet Aerospace occupies the advanced materials tier, supplying specialized components to multiple OEM programs. These three anchors illustrate how market position depends on certification depth and production volume rather than technology differentiation alone.
| Leading Market Players |
|---|
| Howmet Aerospace |
| GE Aviation |
| Boeing |
| Loar Holdings |
| FTAI Aviation |
| Airbus |
| Spirit AeroSystems |
| L3Harris Technologies |
| Embraer |
| Others |
Supply Flow & Price Mechanics
Thermoplastic composite substitution for thermoset prepregs is redrawing supplier geography toward automated fiber placement hubs in the UK and US while compressing wing component pricing through reduced autoclave bottlenecks. This materials transition simultaneously concentrates margin capture among PEEK laminate specialists and erodes traditional thermoset processor premiums.
Pricing Analysis
The customization-premium spread between VIP completion programs and standard narrow-body configurations captures forty percent of platform lifetime value at Gulfstream and Bombardier. Contract structures stratify across power-by-the-hour bundled arrangements, traditional time-and-material MRO, and green airframe spot purchases. Cost compression in standard narrow-body deliveries is intensifying as lessors extract volume discounts unavailable to balance-sheet-constrained flag carriers. Freight operators demonstrate lowest price sensitivity with thirty-year asset horizons prioritizing dispatch reliability.
Supply Chain Analysis
China and Japan anchor titanium sponge refining capacity following Russian and Ukrainian feedstock disruptions, exposing landing gear forging suppliers to price volatility. The aerospace supply chain draws from Chinese smelters for titanium, Japanese producers for specialized alloys, and US facilities for PEEK-based thermoplastic laminates. Single-source vulnerability concentrates in qualified aerostructures facilities requiring eighteen-month layup certification apprenticeships. Distribution runs through tier-one integrators with final assembly complexes in Everett, Charleston, Toulouse, and Hamburg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial aerospace sits in early-cycle expansion as sustainable aviation fuel mandates force fleet renewal timelines faster than historical replacement patterns. Regulatory pressure on lifecycle emissions accelerates technology substitution across propulsion and airframe categories.
For Market Incumbents: Fortify backward integration into flight control avionics as EASA CS-25 amendments on single-pilot operations inflate development costs for external suppliers. Expand captive thermoplastic composite capacity at Broughton and Kinston facilities to capture throughput gains from automated fiber placement. OEM insourcing pressure threatens tier-two aerostructures margins at Wichita and Broughton facilities.
For New Entrants and Emerging Players: Differentiate on digital thread integration capabilities that collapse design-to-manufacturing handoffs for derivative programs. Target Vietnam's point-to-point route proliferation and India's airport privatization wave at Navi Mumbai and Jewar for narrow-body aftermarket services. Pursue power-by-the-hour contract structures with ASEAN flag carriers lacking in-house overhaul capacity.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized material suppliers with qualified aerospace-grade thermoplastic composite processes and established OEM qualification pathways. The five-to-ten year viability window favors suppliers with certification depth over technology differentiation alone. Monitor FAA staffing constraints on supplemental type certificate timelines as inflection indicator for retrofit specialist demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fiber Placement Scale-Up | PEEK-based thermoplastic qualification at Airbus Broughton cuts wing box cycles from weeks to days. |
| Power-by-the-Hour Contract Expansion | Lessors bundle engine coverage with airframe checks in Southeast Asia where carriers lack overhaul capacity. |
| SAF-Compatible Engine Platform Development | EU Green Deal blending mandates create captive demand for biofuel-qualified turbofan architectures. |
| Digital Thread Integration Investment | Model-based systems engineering compresses first-flight schedules for Boeing and Airbus derivative programs. |
| Regional MRO Facility Establishment | Bangalore and Hyderabad clusters host engine overhaul capacity serving Asia-Pacific delivery growth. |
Methodological Framework
Cross-validation between primary interviews with airline fleet planners, aerostructures procurement directors, and MRO operations heads anchors the qualitative findings against secondary validation. FAA Part 25 certification databases, EASA CS-25 amendment records, and CAAC type certification filings provide regulatory trajectory inputs. Customs data on titanium sponge trade flows, OEM production disclosures, and airline order backlogs furnish demand-side calibration. Bottom-up program-level analysis triangulates against top-down market sizing across narrow-body, wide-body, and business jet categories.
Sensitivity analysis tests forecast robustness across sustainable aviation fuel mandate acceleration scenarios, single-pilot certification timeline variations, and titanium supply disruption assumptions. Segmentation dimensions span platform type, propulsion architecture, composite material grade, end-user contract structure, and regional regulatory cluster. CAGRs derive from production rate projections, aftermarket flight-hour accumulation models, and fleet replacement cycle analysis. Input variables include engine overhaul interval extensions, thermoplastic adoption curves, and lessor market share trajectories.
Material uncertainties — airworthiness directive backlogs, skilled composite technician scarcity, and FAA-EASA regulatory divergence — sit outside the modeled envelope. Forecasts reflect assumptions on traffic recovery patterns, oil price corridors, and carbon border adjustment implementation. Recalibration cycles align with material shifts in SAF blending mandates, single-pilot operational approvals, and titanium supply geography.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market
Aircraft
Aircraft Galley Systems Market
Aircraft
America Attack Helicopter Market
Aircraft
Aerospace Turbojet Market
Aircraft
Aircraft Wheels Market
Aircraft
Global Aircraft Electric Brake Control System Market
Aircraft
North America Turboprop Aircraft Market
Aircraft
Middle-East and Africa Turboprop Aircraft Market
Aircraft
GCC General Aviation Market
Aircraft
Aeronautical Wind Tunnel Market
Aircraft
Aviation Crew Management System Market
Aircraft
Aircraft Container & Pallet Loader Market
Aircraft
Freighter Aircraft Market
Aircraft
Middle-East and Africa Helicopters Market
Aircraft
Southeast Asia Aviation Market
Aircraft
France Aviation Market