
 Commercial Aerospace 3D Printing Market | 2026-2036
Commercial Aerospace 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aerospace 3D Printing Market Insights
AS9100D quality tier upgrades are redrawing procurement standards across the commercial aerospace 3D printing landscape. Materialise leverages its certified medical-to-aerospace quality systems to compete for flight-critical polymer components. EOS GmbH dominates metal powder-bed systems for titanium engine brackets, while Stratasys anchors the polymer composite segment with FAA-qualified cabin interior parts.
Commercial aerospace 3D printing encompasses the layer-by-layer fabrication of flight-worthy components from titanium alloys, nickel superalloys, and thermoplastic composites using directed energy deposition or powder-bed fusion processes, primarily to reduce buy-to-fly ratios and consolidate multi-part assemblies into single printed geometries. Selective laser melting of titanium alloys leads the technology mix due to its established qualification pathway for structural brackets and hydraulic manifolds. Engine parts command the deepest margin pools among component types, while maintenance repair providers represent the fastest-growing end-user channel as airlines seek on-demand spare part production to minimize AOG downtime.
FAA airworthiness directives and EASA's MDR framework govern material qualification and process certification for printed aerospace components, creating compliance barriers that favor suppliers with established regulatory dossiers. AS9100D and NADCAP accreditation requirements further filter market access, concentrating qualified supply among tier-one manufacturers with dedicated quality engineering teams. Stakeholders must monitor evolving powder reuse protocols and in-process monitoring standards as regulators tighten traceability requirements for flight-critical printed parts.
Market Dynamics
AS9100D quality tier upgrades are redrawing procurement standards across the commercial aerospace 3D printing landscape, concentrating qualified supply among manufacturers with dedicated regulatory dossiers and NADCAP-accredited facilities.
Growth Catalysts
- FAA airworthiness certification pathways:Accelerated regulatory clarity for printed turbine blades and fuel nozzles enables flight-critical service qualification. OEMs now embed additive manufacturing into engine production roadmaps.
- Directed energy deposition of titanium alloys:This process reduces buy-to-fly ratios from 15:1 to near-net-shape yields. Structural bracket manufacturers capture material cost savings while consolidating multi-part assemblies.
- NASA-funded research clusters in Texas and California:Public-private partnerships anchor the largest concentration of qualified production capacity. Federally backed R&D de-risks process qualification for private suppliers.
Market Restraints
- Titanium powder supply concentration:Spherical plasma-atomized feedstock depends on a limited supplier base in Germany and the United States. Price volatility and lot-to-lot consistency create input cost risk.
- EASA MDR framework material qualification timelines:Multi-year certification dossiers for nickel superalloy engine components delay revenue recognition. Smaller suppliers lack capital to sustain pre-qualification phases.
- Conventional five-axis machining substitution:Mature subtractive methods retain cost advantages for low-complexity geometries below 500-unit production runs. Bridge production often defaults to legacy CNC.
Strategic Opportunities
- Maintenance repair operations channel expansion:Airlines seek on-demand spare part production to minimize AOG downtime. Distributed printing networks at MRO hubs in Singapore and Dubai bypass traditional supply chains.
- EU Green Deal sustainable aviation fuel alignment:Additive manufacturing's material efficiency supports Scope 3 emissions reduction targets. OEMs qualify printed lightweight brackets as sustainability-linked procurement criteria.
- Hybrid manufacturing convergence:Powder-bed fusion combined with CNC finishing centers enables single-workflow production of precision engine components. Integrated cells reduce work-in-process inventory and handling damage.
Industry Challenges
- In-process monitoring standardization gaps:Real-time melt pool analytics lack universal acceptance criteria across FAA and EASA inspectors. Suppliers invest in redundant quality systems pending regulatory harmonization.
- Additive manufacturing technician scarcity:Qualified operators for electron beam melting systems command premium wages in Texas and California clusters. Vocational pipelines have not scaled to match installed base growth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aerospace 3D Printing Market |
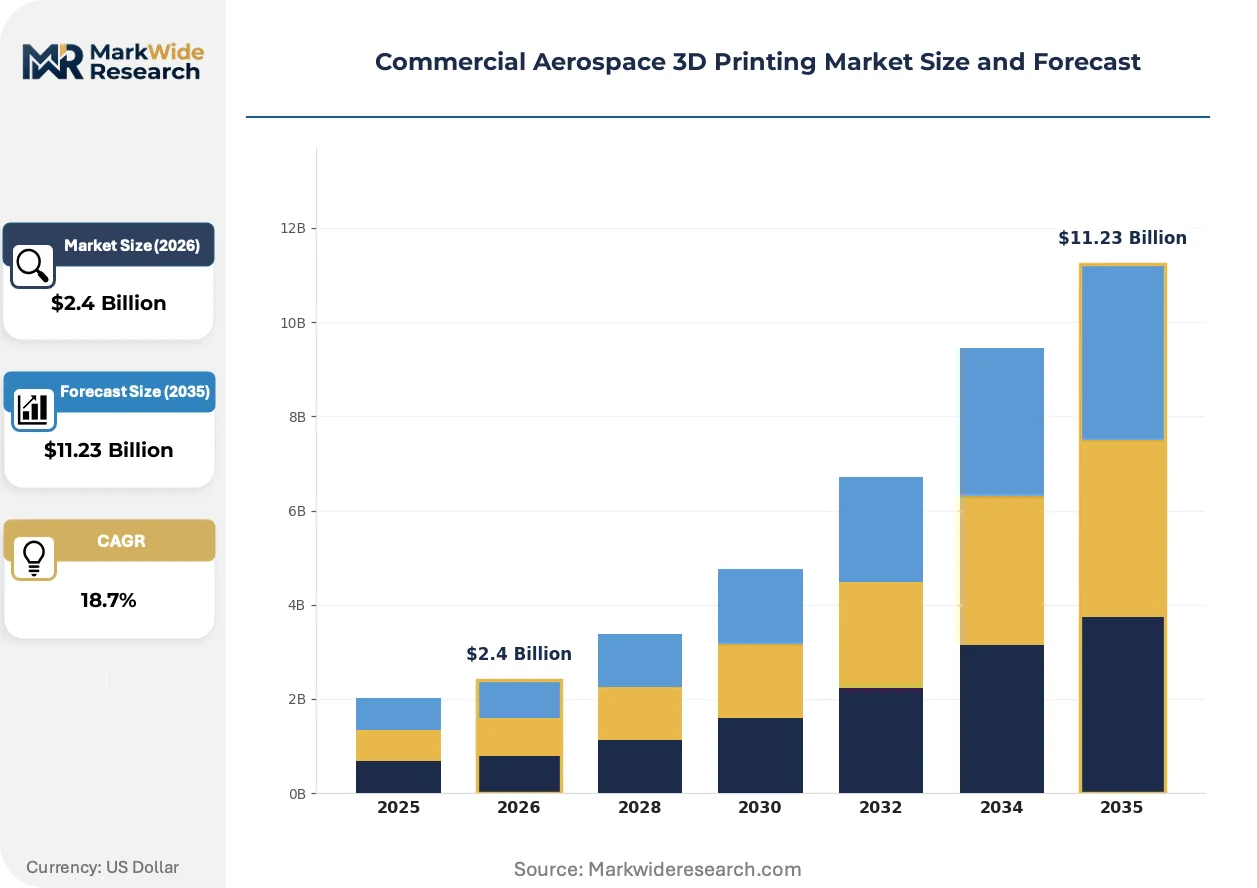
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $11.23 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Engine Parts, Structural Components, Cabin Interiors, Landing Gear, Hydraulic Systems Printing Technology: Selective Laser Melting, Electron Beam Melting, Binder Jetting, Fused Deposition Modeling, Material Jetting Material Type: Titanium Alloys, Nickel Alloys, Aluminum Alloys, Composite Polymers, Stainless Steel End User: Aircraft Manufacturers, Maintenance Repair Providers, Aero Engine Suppliers, Aftermarket Service Companies |
| Companies Covered | Materialise, Norsk Titanium, 3D Systems, Arcam, Ultimaker, Stratasys, Aerojet Rocketdyne, MTU Aero Engines, EOS GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aerospace 3D Printing Market Trends and Innovations
Selective laser melting of titanium alloys is bifurcating the technology landscape between flight-critical engine components and non-structural cabin parts. This divergence reshapes equipment procurement and facility investment priorities across the supply base.
Multi-laser powder-bed fusion systems are bifurcating production economics for titanium structural brackets. Tier-one suppliers in the United States deploy 12-laser configurations to amortize qualification costs across higher throughput, while mid-tier competitors retreat to single-laser niches in polymer composites. The technology gap widens between capital-rich OEM-integrated facilities and independent job shops.
EASA's additive manufacturing qualification standards are compressing certification timelines for nickel superalloy fuel nozzles. European engine manufacturers now embed printed components into type-certified designs without case-by-case exemptions. The MRO sector in Germany and France accelerates spare part qualification to capture aftermarket margin pools.
Airline procurement teams are consolidating supplier panels around AS9100D-certified additive manufacturers with demonstrated FAA repair station credentials. Long-term flight-hour agreements replace transactional spot-buying for printed brackets and manifolds. This concentration is most visible among US-based carriers rebuilding post-pandemic fleet availability.
Commercial Aerospace 3D Printing Market Segmentation
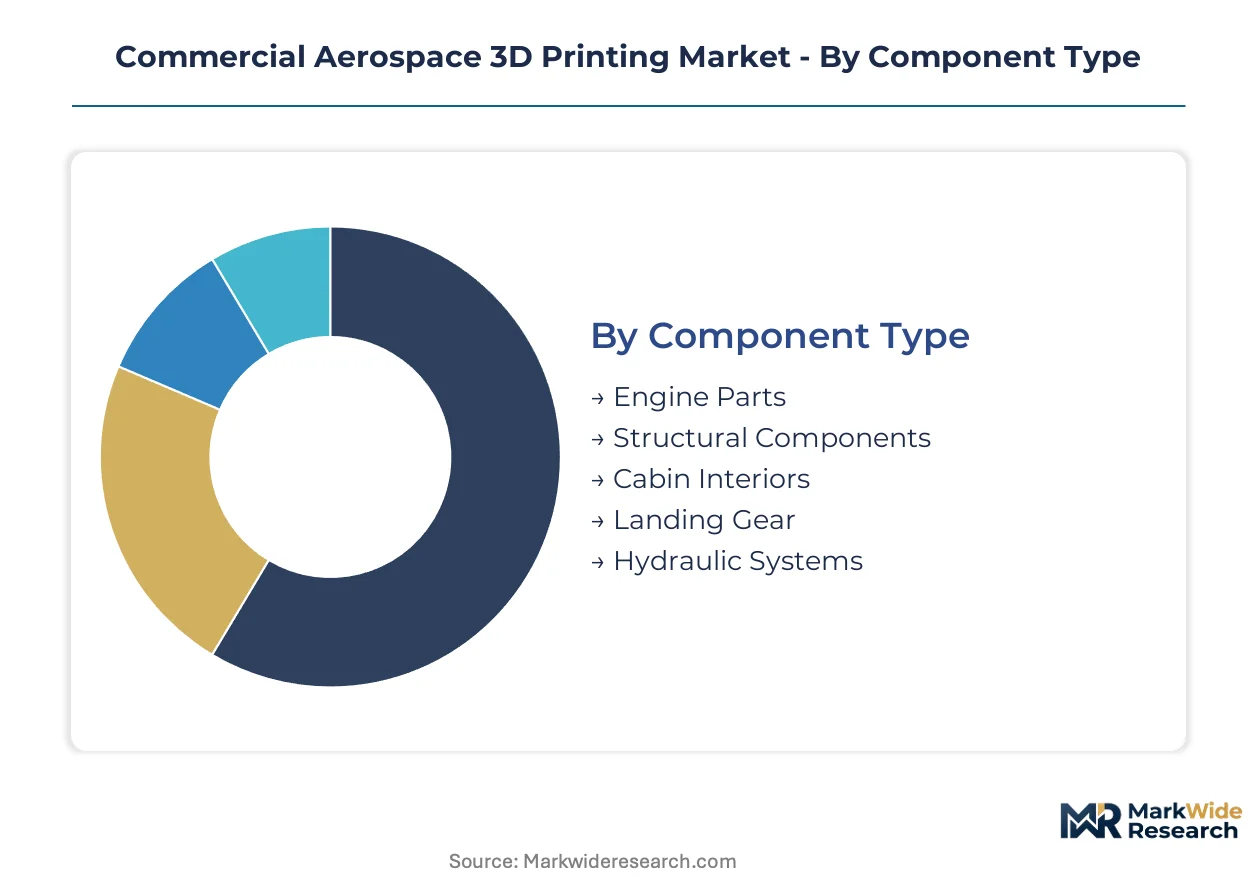
Segmentation in commercial aerospace 3D printing reveals how qualification costs and flight-critical certification tiers concentrate margin capture. Each dimension exposes different competitive moats: component type governs regulatory burden, technology determines capital intensity, material type shapes supply security, and end-user channel dictates contract duration.
Component Type:
Engine parts command the deepest margin pools within this category, with flight-critical certification creating pricing power that structural and cabin applications cannot replicate.
- Engine Parts:Turbine blades and fuel nozzles fabricated from nickel superalloys via selective laser melting undergo multi-year FAA and EASA qualification cycles. Demand concentrates at GE Aviation and Pratt & Whitney supply chains in the United States, where engine OEMs amortize qualification investments across decade-long production contracts. Thermal barrier coating compatibility and creep resistance specifications filter out unqualified suppliers.
- Structural Components:Titanium brackets and pylons reduce buy-to-fly ratios from forged billet waste. Boeing's supply base in Washington and California drives specification adoption, with directed energy deposition gaining traction for near-net-shape geometries that minimize finish machining. Weight reduction targets in next-generation narrowbody programs accelerate design-for-additive transitions.
- Cabin Interiors:Polymer seat frames and ducting panels face lower certification barriers than flight-critical segments. Stratasys-qualified Ultem components serve FAA flammability requirements without the multi-year dossiers of engine parts.
- Landing Gear:High-strength steel and titanium actuators require fatigue testing protocols that lag engine component maturity. Airbus suppliers in Germany and France pilot wire-arc additive for landing gear struts.
- Hydraulic Systems:Manifolds and valve bodies consolidate multi-part welded assemblies into single printed geometries. Parker Hannifin supply chains in Ohio and Michigan qualify aluminum-silicon alloys for pressure-rated applications.
Engine parts hold installed capacity. Structural components are rotating up the share rankings.
Printing Technology:
Capital deployment intensity varies by an order of magnitude across this category, with powder-bed systems demanding facility investments that electron beam and extrusion methods avoid.
- Selective Laser Melting:Multi-laser configurations from EOS and SLM Solutions dominate titanium and nickel alloy production for flight-critical brackets and nozzles. Tier-one suppliers in Texas deploy 12-laser cells to amortize qualification costs across higher throughput, while mid-tier competitors retreat to single-laser niches.
- Electron Beam Melting:Vacuum-chamber processing of titanium alloys eliminates residual stress and supports thicker-section builds than laser methods. Arcam systems at Saab and GKN Aerospace facilities in Sweden and the United Kingdom process structural brackets with minimal post-processing.
- Binder Jetting:ExOne and Desktop Metal systems offer lower capital entry points for stainless steel and tool steel components. Sintering furnace requirements and green part handling limit adoption for flight-critical applications.
- Fused Deposition Modeling:Stratasys Fortus systems produce FAA-qualified Ultem 9085 cabin parts with material extrusion economics. Polymer composite segments favor this technology for non-structural interior components.
- Material Jetting:PolyJet systems from Stratasys serve prototyping and tooling applications rather than production flight hardware. Multi-material capability supports jigs and fixtures for assembly operations.
Selective laser melting anchors production volumes. Binder jetting is climbing the fastest as sintering protocols mature for aerospace-grade densities.
Material Type:
Feedstock supply security and lot-to-lot consistency requirements create divergent procurement economics across metallic and polymer categories.
- Titanium Alloys:Ti-6Al-4V powder from plasma atomization commands premium pricing due to spherical morphology requirements. Suppliers in Germany and the United States concentrate production, with Boeing and Airbus long-term agreements locking up qualified lots.
- Nickel Alloys:Inconel 718 and 625 superalloys withstand turbine operating temperatures exceeding 650°C. GE Aviation's Auburn, Alabama facility consumes the largest single-site volume of nickel powder for printed fuel nozzles.
- Aluminum Alloys:AlSi10Mg offers weight reduction for non-structural brackets and housings. Scalmalloy and Aheadd specialized alloys from APWorks and Elementum 3D gain traction for performance-critical applications.
- Composite Polymers:Carbon fiber-reinforced PEEK and PEKK from Victrex and Solvay serve high-temperature ducting and brackets. Continuous fiber deposition from Anisoprint and Markforged challenges chopped-fiber legacy methods.
- Stainless Steel:17-4 PH and 316L grades serve tooling, fixtures, and non-flight hardware. Lower powder costs and established supply chains support maintenance repair operations channel adoption.
Titanium alloys dominate flight-critical applications. Nickel alloys are expanding most quickly as engine OEMs qualify superalloy turbine components.
End User:
Contract duration and technical specification control vary sharply across OEM-integrated versus aftermarket channels.
- Aircraft Manufacturers:Boeing and Airbus design-for-additive programs in Washington, South Carolina, Toulouse, and Hamburg embed printed components into original equipment specifications. Long-term flight-hour agreements replace spot-buying for qualified suppliers.
- Maintenance Repair Providers:Lufthansa Technik, ST Engineering, and Delta TechOps pursue distributed printing networks to minimize aircraft-on-ground downtime. Singapore and Dubai MRO hubs bypass traditional supply chains for obsolete spare parts.
- Aero Engine Suppliers:GE Aviation, Rolls-Royce, and Pratt & Whitney vertical integration into additive manufacturing captures margin pools from castings and forgings suppliers. Dedicated additive centers in Ohio, Indiana, and Derby control critical process parameters.
- Aftermarket Service Companies:Independent distributors and parts brokers source from qualified job shops to serve aging fleet requirements. AS9100D certification filters panel participation for US-based carriers.
Aircraft manufacturers retain specification control. Maintenance repair providers are gaining share fastest as airlines rebuild post-pandemic fleet availability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified production capacity clusters where FAA and EASA certification pathways intersect with titanium powder supply chains and engine OEM vertical integration. Four countries anchor the geographic distribution of flight-critical additive manufacturing.
United States
Boeing's supply base in Washington and California drives specification adoption for structural brackets, while GE Aviation's Auburn facility consumes the largest single-site nickel powder volume for printed fuel nozzles. FAA airworthiness directives govern material qualification timelines. NASA-funded research clusters in Texas and California de-risk process qualification for private suppliers.
Germany
EOS GmbH and SLM Solutions anchor powder-bed system production for European engine manufacturers. EASA's additive manufacturing qualification standards compress certification timelines for nickel superalloy components. Industrial concentration in Bavaria and Baden-Württemberg supports tier-one supplier networks serving Airbus Toulouse and Hamburg assembly lines.
United Kingdom
Rolls-Royce's Derby additive center controls critical process parameters for printed turbine components. The country's national aerospace regulator aligns with EASA MDR framework requirements for flight-critical parts. GKN Aerospace facilities in the West Midlands process structural brackets via electron beam melting systems.
France
Safran and Airbus integrate printed components into type-certified designs without case-by-case exemptions. EASA qualification standards enable European engine manufacturers to embed additive manufacturing into production roadmaps. The Île-de-France and Occitanie regions concentrate MRO spare part qualification for aftermarket margin capture.
Singapore
ST Engineering pursues distributed printing networks to minimize aircraft-on-ground downtime for Asia-Pacific carriers. The country's civil aviation authority maintains bilateral recognition with FAA and EASA certification pathways. Changi-based MRO hubs bypass traditional supply chains for obsolete spare parts.
Commercial Aerospace 3D Printing Market Competitive Landscape
Concentration sits with tier-one manufacturers possessing AS9100D certification and NADCAP-accredited facilities. Equipment suppliers and qualified job shops divide margin capture along the value chain. Two archetypes dominate: powder-bed system OEMs with regulatory dossiers, and certified job shops with demonstrated FAA repair station credentials. Competitive moves center on capacity expansion into multi-laser configurations and strategic partnerships with engine OEMs for decade-long production contracts.
Among European equipment specialists, EOS GmbH and Arcam occupy positions within the powder-bed and electron beam melting tiers respectively. Materialise represents the medical-to-aerospace quality systems crossover archetype. Stratasys anchors the polymer composite segment for cabin interior applications. Norsk Titanium exemplifies the directed energy deposition specialist model for near-net-shape titanium components.
| Leading Market Players |
|---|
| Materialise |
| Norsk Titanium |
| 3D Systems |
| Arcam |
| Ultimaker |
| Stratasys |
| Aerojet Rocketdyne |
| MTU Aero Engines |
| EOS GmbH |
| Others |
Pricing and Supply Chain Analysis
Plasma-atomized titanium powder replacing conventional wrought billet simultaneously concentrates supply geography among German and United States atomization specialists and compresses material cost premiums for flight-critical brackets. AS9100D certification tiers stratify pricing power between qualified tier-one suppliers and unaccredited job shops.
Pricing Analysis
FAA airworthiness certification pathways dictate the pricing tier structure across component categories. Three-tier pricing separates flight-critical engine parts from structural brackets and cabin interiors, with nickel superalloy nozzles commanding premiums due to multi-year EASA dossier requirements. Cost compression in polymer cabin segments intensifies because Stratasys-qualified suppliers compete on throughput scale. MRO procurement teams exhibit highest price sensitivity for obsolete spare parts, while engine OEMs prioritize qualification reliability over unit cost.
Supply Chain Analysis
Container availability on Hamburg-Charleston and Bremerhaven-Houston trade lanes constrains spherical powder inbound logistics for Texas and California production clusters. Titanium feedstock draws from plasma atomization facilities in Germany and the United States, with nickel superalloy powder sourcing concentrated in Alabama and Bavaria. Single-source vulnerability persists for electron beam melting system components from Arcam's Swedish facility. Distribution runs through Boeing and Airbus tier-one supplier networks with NADCAP-accredited facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Airline procurement consolidation around AS9100D-certified additive manufacturers has shifted bargaining power toward buyers with long-term flight-hour agreements, fragmenting spot-buying channels.
For Market Incumbents: Consolidate multi-laser capacity investments in Texas and California to amortize qualification costs across higher throughput. Defend against binder jetting specialists by deepening electron beam melting expertise for thick-section titanium brackets. Lock in spherical powder supply agreements with German atomizers before EASA traceability requirements tighten. For New Entrants and Emerging Players: FAA repair station certification fast-tracks entry into the MRO spare parts channel, where distributed printing networks at Singapore and Dubai hubs bypass incumbent supply chains. Target polymer composite cabin interiors as the most penetrable segment, leveraging lower flammability certification barriers. Pursue white-label production partnerships with AS9100D-certified job shops to accelerate credential acquisition. For Investors and Strategic Acquirers: EASA's additive manufacturing qualification standards reshapes the acquisition landscape toward suppliers with demonstrated regulatory dossiers. Five-to-ten year viability favors tier-one manufacturers with captive engine OEM relationships over equipment-dependent job shops. Watch for harmonization of in-process monitoring standards between FAA and EASA as the inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Laser Capacity Expansion | Twelve-laser configurations from EOS amortize qualification costs across higher titanium bracket throughput. |
| AS9100D Certification Investment | Materialise leverages medical-to-aerospace quality systems to compete for flight-critical polymer components. |
| Backward Integration into Powder Supply | GE Aviation's Auburn facility secures nickel superalloy feedstock for printed fuel nozzle production. |
| MRO Hub Distributed Printing Network | ST Engineering at Changi bypasses traditional supply chains for obsolete spare parts. |
| Hybrid Manufacturing Cell Deployment | Powder-bed fusion combined with CNC finishing reduces work-in-process inventory for precision engine components. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with additive manufacturing technicians, quality engineering directors at tier-one suppliers, MRO procurement managers, and FAA certification specialists. Secondary validation drew from EASA additive manufacturing qualification standards, FAA airworthiness directives, AS9100D accreditation databases, and NASA-funded research cluster disclosures. Bottom-up build-ups of installed equipment capacity triangulated against top-down OEM procurement spend estimates.
Across the analysis window, volume and value outputs reflect segmentation modeling across component type, printing technology, material alloy grade, and end-user channel. CAGRs were derived from equipment shipment trajectories and qualification timeline compression rates. Forecast inputs incorporated powder-bed fusion adoption curves and electron beam melting technician wage inflation in Texas and California clusters.
Underlying assumptions cover sustained FAA-EASA regulatory harmonization progress, with deviation risk concentrated in titanium powder lot-to-lot consistency failures and in-process monitoring standardization gaps. Practitioners should keep alternative scenarios live as EASA MDR framework implementation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Europe Aerospace Composites Market
Aerospace and Aircraft Materials
Aircraft Aluminium Plate Market
Aerospace and Aircraft Materials
Global Composite Materials Aluminum Alloys Aerospace Market
Aerospace and Aircraft Materials
Aerospace Lightweight Materials Market
Aerospace and Aircraft Materials
Global Aerospace Metal Closed-Die Forging Market
Aerospace and Aircraft Materials
Aerospace Composite Ducting Market
Aerospace and Aircraft Materials
Global High Strength Aluminum Alloys Market
Aerospace and Aircraft Materials
Aerospace Titanium Market
Aerospace and Aircraft Materials
Aerogel Blanket Market
Aerospace and Aircraft Materials
Global Aerospace Titanium Machining Market
Aerospace and Aircraft Materials
Aerospace Raw Materials Market
Aerospace and Aircraft Materials
Composites in United States Defense Market
Aerospace and Aircraft Materials
Aerospace Fiber Optics Market
Aerospace and Aircraft Materials
Titanium Sponge for Aerospace and Defense Market
Aerospace and Aircraft Materials
Aramid Honeycomb Market
Aerospace and Aircraft Materials
Aerospace and Defense Metal Stamping Market