
 Aeroengine Composites Market | 2026-2036
Aeroengine Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Aeroengine Composites Market Outlook
North America is reconfiguring aeroengine composites supply chains through dedicated thermoplastic capacity additions. GE Aerospace leverages its Cincinnati-based R&D campus to sustain vertical integration into fan blade preforming. Rolls-Royce Holdings plc anchors European output through its Bristol composites facility while competing aggressively on widebody engine contracts. Hexcel Corporation dominates carbon fiber prepreg supply to both programs, controlling critical material qualification pathways.
Aeroengine composites are fiber-reinforced polymer systems, typically carbon fiber-epoxy laminates with service temperatures exceeding 120°C, manufactured via automated fiber placement to achieve the strength-to-weight ratios essential for rotating engine hardware. Carbon fiber leads material type segments due to its established qualification for fan blades and compressor cases, where margin pools concentrate among qualified suppliers. Automated fiber placement is displacing hand layup across original equipment manufacturing as aerospace OEMs demand repeatable fiber orientation tolerances within 0.5 degrees.
The FAA certifies composite engine components under Part 33 airworthiness standards, while EASA enforces comparable CS-E requirements that shape global product acceptance criteria. EPA aircraft emissions rules and the EU Green Deal carbon benchmarks are forcing engine redesign cycles toward lighter composite architectures. Stakeholders must monitor thermoplastic resin qualification timelines and emerging recycling mandates that will reshape material selection decisions.
Market Dynamics
Automated fiber placement is compressing manufacturing cycle times for rotating engine hardware while thermoplastic resin systems challenge epoxy dominance in next-generation architectures. This equipment transition is redrawing qualification requirements and supplier tier structures across the aeroengine composites value chain.
Growth Catalysts
- FAA Part 33 Certification Pathways:Streamlined composite airworthiness approvals for fan blade applications are accelerating OEM adoption of carbon fiber-epoxy laminates in narrowbody engine programs.
- Widebody Fleet Renewal Cycles:Airlines replacing aging twin-aisle aircraft are specifying engines with composite-intensive architectures to meet payload-range efficiency targets.
- EU Green Deal Carbon Benchmarks:Engine manufacturers face binding emissions reduction mandates that favor lightweight composite components over metallic alternatives in compressor sections.
Market Restraints
- Acrylonitrile Price Volatility:Carbon fiber precursor costs fluctuate with petrochemical feedstock markets, squeezing margin predictability for prepreg suppliers.
- Single-Source Qualification Risk:Fan blade preforming capabilities concentrate among qualified autoclave operators in the United States and United Kingdom, creating supply vulnerability.
- Thermoset Recycling Limitations:Cross-linked epoxy matrices lack viable end-of-life processing routes, exposing OEMs to emerging extended producer responsibility frameworks.
Strategic Opportunities
- India Defense Aerospace Procurement:Indigenous combat aircraft programs are creating first-mover openings for composite engine component suppliers establishing local preforming partnerships.
- Thermoplastic-Thermoset Hybrid Processing:Converging automated fiber placement with in-situ consolidation is enabling out-of-autoclave production for non-rotating engine cases.
- Japan METI Green Innovation Fund:Public co-financing for sustainable aviation technologies is subsidizing demonstration programs for recyclable engine composite architectures.
Industry Challenges
- Automated Fiber Placement Programming Talent:Shortages of machine path optimization specialists are extending commissioning timelines for new thermoplastic production lines.
- Part 33 Certification Timeline Compression:FAA validation protocols for novel resin systems require multi-year thermal-structural test campaigns that delay program entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aeroengine Composites Market |
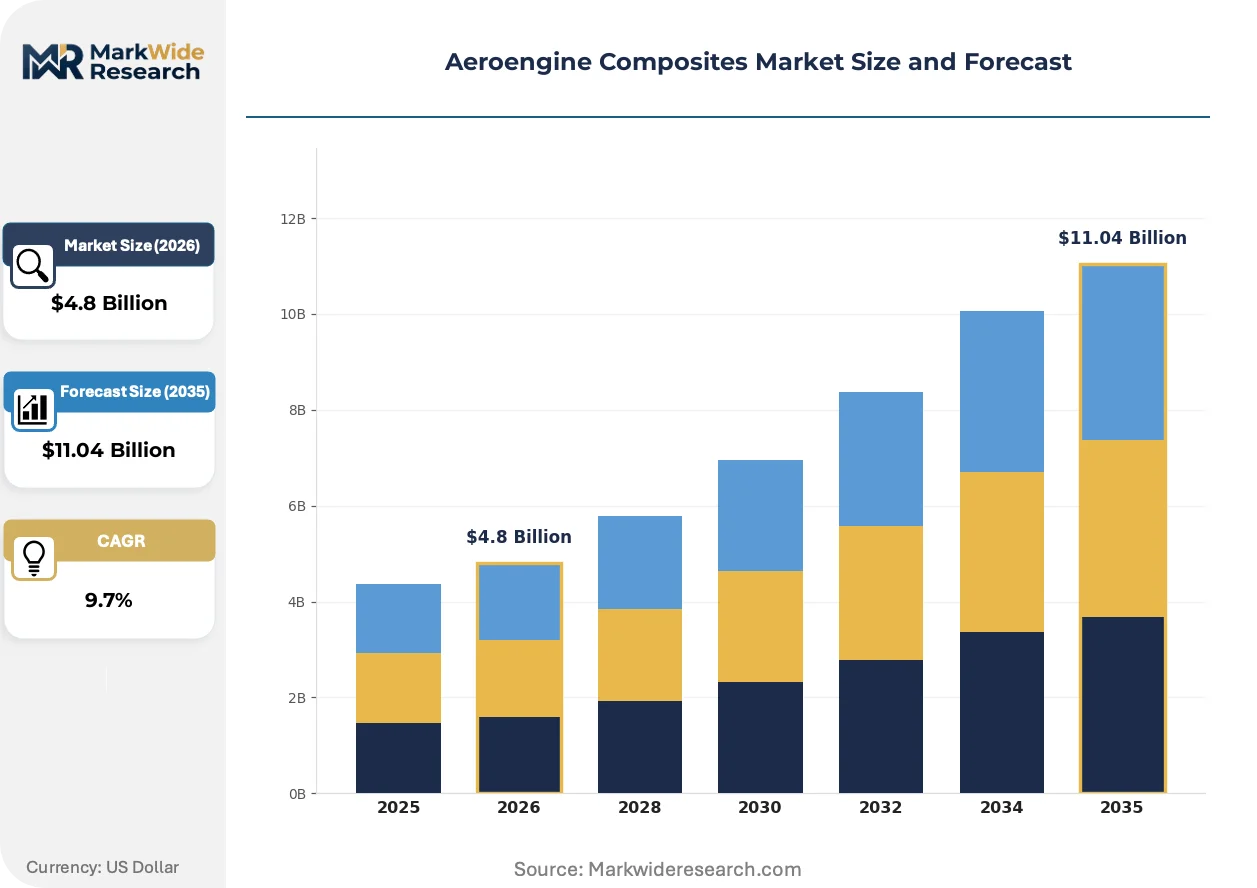
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Carbon Fiber, Glass Fiber, Aramid Fiber, Metal Matrix Application: Fan Blades, Compressor Cases, Turbine Housings, Structural Components Manufacturing Technique: Hand Layup, Automated Fiber Placement, Infusion, Prepreg End User: Aerospace OEMs, Defense Forces, Aftermarket Providers, Maintenance Repair Organizations |
| Companies Covered | GE Aerospace, CFM International, Rolls-Royce Holdings plc, Pratt & Whitney (RTX Corporation), Safran SA, Meggitt PLC, GKN Aerospace, Hexcel Corporation, Solvay SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aeroengine Composites Market Strategic Shifts
Material-process combinations are fragmenting as established thermoset qualifications compete with emerging thermoplastic performance claims. This technical divergence is forcing OEMs to place parallel bets across resin chemistry families.
PEEK-based thermoplastic composites are hybridizing with continuous carbon fiber architectures to deliver damage tolerance exceeding thermoset benchmarks while enabling weldable assembly methods. Engine manufacturers are piloting these systems in static structural applications ahead of rotating hardware qualification. The technology is hybridizing supply chain structures as chemical companies acquire fiber placement equipment makers to secure downstream integration.
EPA aircraft emissions rules are tightening NOx and particulate standards for engines entering service after 2028, compelling redesign cycles that prioritize weight reduction through composite substitution. The regulatory pressure is accelerating preform automation investments to achieve the fiber orientation precision required for thinner, lighter compressor cases. European OEMs are responding fastest due to overlapping EU Green Deal compliance deadlines.
Aftermarket service contracts are unbundling composite component repair from traditional engine maintenance agreements, creating specialized channel intermediaries focused on non-destructive inspection and patch restoration. Airlines with large leased fleets are driving this fragmentation to capture residual value from damaged fan blades rather than accepting standard exchange pricing. The shift is most advanced in North America where lessor concentration supports standardized repair specification development.
Aeroengine Composites Market Segmentation
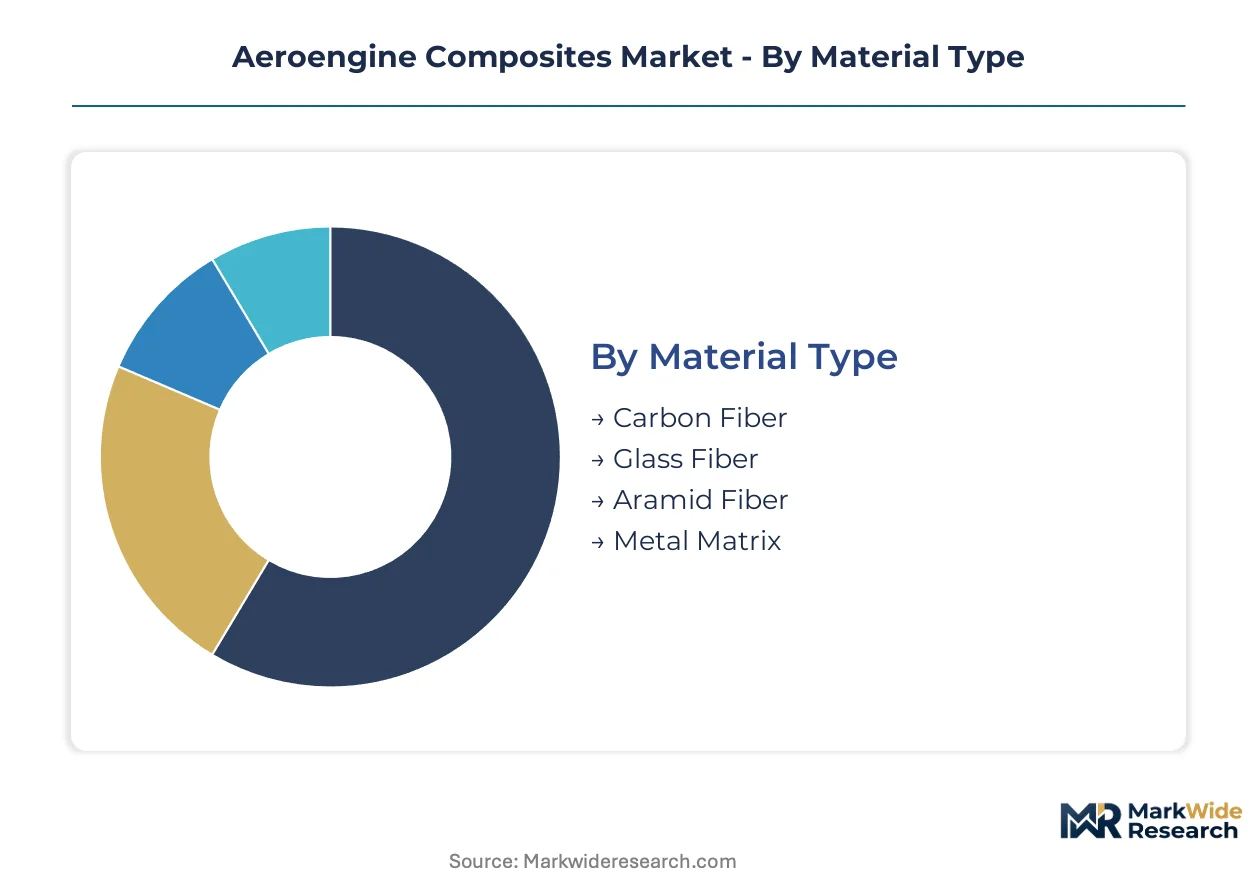
Aeroengine composites segmentation reflects competing qualification regimes across material chemistries and manufacturing processes. Each category carries distinct certification burdens that reshape supplier economics and OEM sourcing patterns.
Material Type:
Mature thermoset systems anchor current production while emerging thermoplastic formulations challenge incumbent positions.
- Carbon Fiber:Continuous carbon fiber-epoxy prepregs dominate rotating hardware applications where specific strength requirements exceed 300 MPa per density unit. Fan blade programs at Boeing and Airbus anchor demand in the United States and France, though acrylonitrile feedstock volatility compresses margin stability for qualified suppliers.
- Glass Fiber:E-glass and S-glass reinforcements serve non-rotating static structures including acoustic liners and nacelle fairings where cost sensitivity outweighs extreme performance thresholds. Procurement concentrates among European nacelle integrators responding to EASA CS-E noise certification deadlines.
- Aramid Fiber:Kevlar and Twaron hybrids provide impact resistance in containment systems and ballistic shielding for military engine architectures.
- Metal Matrix:Aluminum and titanium matrix composites address intermediate temperature zones between polymer limits and superalloy requirements.
Carbon fiber handles the majority of throughput; glass fiber is gaining share fastest in cost-optimized regional jet programs.
Application:
Application segmentation tracks thermal gradient exposure and rotational stress exposure across engine architectures.
- Fan Blades:Hollow titanium leading edges bonded to carbon fiber-epoxy airfoils represent the most qualification-intensive application, with FAA Part 33 certification cycles exceeding five years for new entrants. GE Aerospace and Rolls-Royce captive production in Cincinnati and Bristol locks in supply concentration.
- Compressor Cases:Multi-piece filament-wound or tape-laid cylinders contain blade release events while managing thermal expansion mismatches. Automated fiber placement adoption is climbing fastest here as OEMs pursue out-of-autoclave processing for narrowbody engine variants.
- Turbine Housings:Ceramic matrix composite transitions and metallic hybrid designs address combustor exit temperatures beyond polymer service limits.
- Structural Components:Mounts, brackets, and auxiliary hardware complete the composite content portfolio with lower qualification barriers.
Fan blades command premium positioning; compressor cases show the steepest expansion trajectory from automation investments.
Manufacturing Technique:
Volume concentration and margin distribution diverge sharply between labor-intensive and capital-intensive process categories.
- Automated Fiber Placement:Multi-axis robotic systems deposit thermoset or thermoplastic tows with fiber orientation tolerances within 0.3 degrees, enabling thinner laminates for weight-critical rotating hardware. Cincinnati, Bristol, and Toulouse house the qualified installed base serving engine OEM direct contracts.
- Prepreg:Refrigerated carbon fiber-epoxy unidirectional and fabric preforms remain the qualified baseline for fan blade production, with Hexcel and Toray controlling qualification pathways through proprietary resin formulations.
- Hand Layup:Skilled technician deposition persists in low-rate defense programs and prototype fabrication where automation capital cannot be amortized.
- Infusion:Resin transfer molding and vacuum-assisted resin infusion serve nacelle and thrust reverser applications with moderate structural loads.
Automated fiber placement captures the throughput majority; thermoplastic-capable AFP systems are expanding most quickly on capital deployment.
End User:
Customer type segmentation reveals diverging procurement sophistication and contract structures across the value chain.
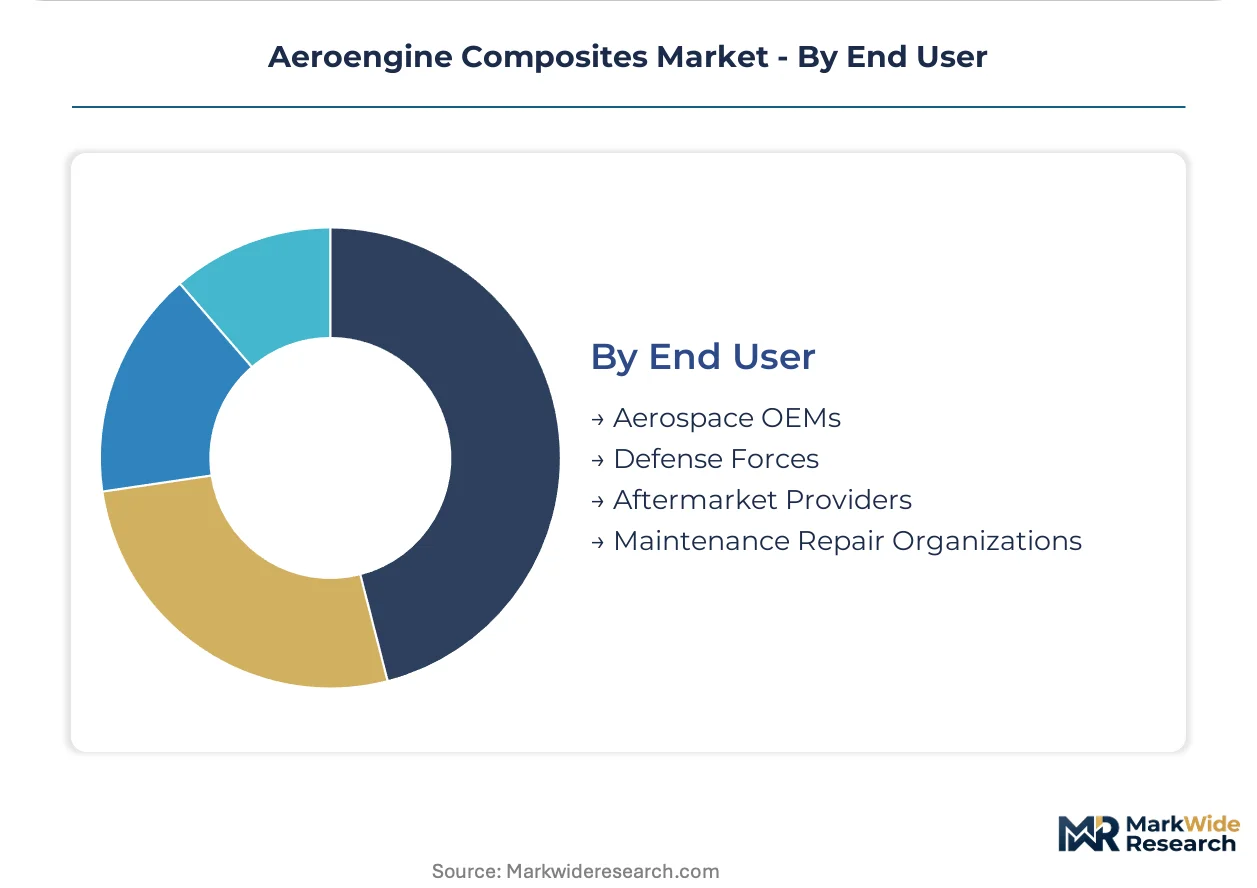
- Aerospace OEMs:Boeing, Airbus, and COMAC direct procurement for engine-integrated structures follows program lifecycle milestones with long-term material qualification locks. These customers specify composite architectures at the platform definition phase, constraining supplier substitution.
- Defense Forces:Indigenous combat aircraft programs in India and Japan are creating qualified supplier development opportunities with offset-driven local content requirements.
- Aftermarket Providers:Specialized repair stations are unbundling from traditional engine overhaul contracts, building non-destructive inspection and patch restoration capabilities for leased fleet operators.
- Maintenance Repair Organizations:Airline-affiliated and independent MROs handle line maintenance composite damage assessment with growing in-house scarf repair authorization.
Aerospace OEMs direct the volume majority; aftermarket providers are climbing fastest on fleet age accumulation and lessor value capture strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between mature aerospace clusters pursuing thermoplastic transitions and emerging defense programs building first-generation composite capabilities from greenfield bases.
United States
Commercial engine OEMs dominate demand through narrowbody and widebody platform cycles. FAA Part 33 certification protocols shape global qualification standards that suppliers must satisfy for rotating hardware access. Cincinnati anchors GE Aerospace's captive fan blade production, while Hexcel Corporation's Utah and California facilities control carbon fiber prepreg supply to multiple engine programs.
United Kingdom
Rolls-Royce Holdings plc drives composite-intensive engine architectures for next-generation widebody contracts. EASA CS-E requirements parallel FAA standards but impose additional noise certification constraints on nacelle-integrated structures. Bristol houses the company's dedicated composites facility, concentrating qualified autoclave capacity for fan case and blade production.
France
Safran SA leverages domestic supply chains for LEAP engine composite components through its joint venture with GE Aerospace. EU Green Deal carbon benchmarks accelerate lightweight material substitution in compressor sections ahead of 2030 compliance deadlines. Toulouse clusters automated fiber placement equipment serving both engine and airframe OEMs with shared qualification pathways.
Japan
Defense aerospace procurement is expanding qualified supplier bases for indigenous fighter engine programs. METI Green Innovation Fund co-financing supports demonstration programs for recyclable thermoplastic architectures. Nagoya and surrounding Chubu region concentrate carbon fiber precursor production and automated placement R&D through Toray Industries and partner facilities.
India
Indigenous combat aircraft development is creating first-mover openings for composite engine component suppliers establishing local preforming partnerships. Ministry of Defence offset requirements mandate progressive local content increases across engine subsystem tiers. Bengaluru and Hyderabad clusters host emerging aerospace manufacturing zones where international suppliers are qualifying domestic preform fabrication capabilities.
Aeroengine Composites Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. The market structures around qualified material suppliers controlling certification pathways and engine OEMs with captive fabrication for the most demanding rotating applications. Three archetypes dominate: chemical companies with resin formulation IP, tier-one aerostructures suppliers with qualified autoclave networks, and engine manufacturers with backward integration into fan blade production. Competitive moves center on thermoplastic resin qualification timelines and strategic partnerships to secure automated fiber placement programming talent.
Among the integrated engine OEM tier, GE Aerospace, Rolls-Royce Holdings plc, and Safran SA exemplify the captive production model for safety-critical rotating hardware. These companies occupy positions where material qualification history and FAA Part 33 certification depth create structural barriers to supplier substitution. Hexcel Corporation represents the qualified material supplier archetype, with carbon fiber prepreg formulations embedded in multiple engine program specifications.
| Leading Market Players |
|---|
| GE Aerospace |
| CFM International |
| Rolls-Royce Holdings plc |
| Pratt & Whitney (RTX Corporation) |
| Safran SA |
| Meggitt PLC |
| GKN Aerospace |
| Hexcel Corporation |
| Solvay SA |
| Others |
Value Chain & Pricing Dynamics
Single-source qualification risk for fan blade preforming capabilities determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic clustering of qualified autoclave capacity. Acrylonitrile feedstock volatility feeds directly into prepreg supplier margin compression, compressing price spreads between qualified and unqualified material tiers while reinforcing captive production advantages for engine OEMs with backward integration into carbon fiber-epoxy laminate fabrication.
Pricing Analysis
Price differentiation between United States and European delivery points reflects acrylonitrile precursor cost volatility and qualified autoclave capacity scarcity. Contract-based long-term offtake dominates fan blade programs where FAA Part 33 certification locks create switching costs, while spot procurement persists for nacelle fairings and acoustic liners. Pricing pressure stems from thermoplastic resin qualification timelines as OEMs demand cost parity with established epoxy benchmarks. Defense forces exhibit highest price sensitivity due to offset-driven local content mandates, whereas aerospace OEMs prioritize qualification depth over unit cost.
Supply Chain Analysis
Extended payment terms from engine OEMs to prepreg suppliers are compressing working capital cycles across tier-two fabricators. Supply concentrates in the United States, United Kingdom, and France where qualified automated fiber placement capacity anchors fan blade and compressor case production. Raw material dependencies center on acrylonitrile precursor, carbon fiber tow, and proprietary epoxy resin formulations controlled by Hexcel and Toray. Single-source vulnerability runs through qualified autoclave operators in Cincinnati and Bristol. Distribution runs through program-specific direct contracts rather than merchant distribution, with aftermarket repair channels emerging as specialized intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service contracts for composite component repair are expanding faster than original hardware procurement as airlines with leased fleets capture residual value from damaged fan blades. This recurring-revenue layer offers margin stability absent from cyclical engine program volumes.
For Market Incumbents: Insulate qualified supplier status by accelerating thermoplastic resin qualification investments ahead of EU Green Deal compliance deadlines. Deepen backward integration into automated fiber placement programming talent pools to offset commissioning timeline extensions. Secure captive preforming capacity in Bristol and Cincinnati against emerging competition from Toulouse-clustered equipment.
For New Entrants and Emerging Players: India's indigenous combat aircraft programs represent the most penetrable defense aerospace procurement cluster, with Ministry of Defence offset requirements mandating progressive local content increases. Target Bengaluru and Hyderabad manufacturing zones for preform fabrication partnerships. Pursue non-rotating engine case applications where out-of-autoclave thermoplastic processing lowers qualification barriers.
For Investors and Strategic Acquirers: EASA CS-E noise certification deadlines reshaping the acquisition landscape toward nacelle-integrated composite specialists with established qualification pathways. Long-term viability over the next decade hinges on thermoplastic resin system IP and automated fiber placement equipment access. Watch for FAA Part 33 certification timeline compression as the inflection signal for program entry acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Resin Qualification | Enables weldable assembly methods for next-generation compressor cases at Safran and GE Aerospace. |
| Automated Fiber Placement Capacity Expansion | Secures fiber orientation precision within 0.3 degrees for thinner, lighter rotating hardware. |
| Aftermarket Repair Channel Development | Captures unbundled service contracts from traditional engine overhaul agreements at lessor-affiliated MROs. |
| Defense Offset Partnership Formation | Qualifies domestic preform fabrication in India and Japan through METI and Ministry of Defence programs. |
| Recyclable Architecture Demonstration | Addresses emerging extended producer responsibility frameworks for cross-linked epoxy matrices. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FAA Part 33 certification databases, EASA CS-E submission records, engine program procurement disclosures, and carbon fiber trade flow data. Interviews with composite engineering directors, supply chain managers at tier-one aerostructures suppliers, automated fiber placement equipment operators, and aftermarket repair station managers informed demand-side validation. Bottom-up program-level build-up and top-down industry consensus triangulation anchored volume estimates.
Forecast inputs include narrowbody and widebody engine delivery schedules, thermoplastic resin qualification milestone projections, and EU Green Deal carbon benchmark compliance timelines across the analysis window. Segmentation modeling incorporates material type, application thermal gradient exposure, manufacturing technique capital intensity, and end-user procurement sophistication. CAGRs derive from fitted growth curves applied to qualified supplier capacity expansion and OEM adoption rates for composite-intensive architectures.
The forecast holds incumbent behavior within observed patterns; aggressive moves by chemical companies acquiring fiber placement equipment makers would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerogel Blanket Market
Aerospace and Aircraft Materials
Commercial Aircraft Materials Market
Aerospace and Aircraft Materials
Aerospace Composite Ducting Market
Aerospace and Aircraft Materials
Aerospace Foam Market
Aerospace and Aircraft Materials
Aerogel Market
Aerospace and Aircraft Materials
Global High Strength Aluminum Alloys Market
Aerospace and Aircraft Materials
Global AFP/ATL Machines Market
Aerospace and Aircraft Materials
Aerographite Market
Aerospace and Aircraft Materials
Europe Aerospace Composites Market
Aerospace and Aircraft Materials
Stealth Coating Market
Aerospace and Aircraft Materials
Additive Manufactured Pressure Vessel Proof and Burst Test Rigs Market
Aerospace and Aircraft Materials
Fiberglass for Aerospace Market
Aerospace and Aircraft Materials
Defense Aircraft Material Market
Aerospace and Aircraft Materials
Aerospace Ceramic Matrix Composites Market
Aerospace and Aircraft Materials
Aerographene Market
Aerospace and Aircraft Materials
Aerospace Plastics Market