
 Aircraft Coatings Market | 2026-2036
Aircraft Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Coatings Market Analytics
The EU Green Deal is hardening sustainability benchmarks for aerospace materials, compelling coating suppliers to reformulate product lines around chromate-free chemistries and lower-VOC systems. PPG Industries leverages its integrated R&D infrastructure to develop compliant primer technologies for next-generation airframes. Akzo Nobel N.V. anchors its competitive stance through specialized topcoat portfolios serving both OEM and aftermarket channels. BASF SE differentiates via advanced polymer science capabilities that address combined corrosion and UV-resistance specifications.
Aircraft coatings constitute engineered film systems applied to exterior and interior substrates to protect against corrosion, erosion, ultraviolet degradation, and thermal cycling while managing aerodynamic drag and signature control. These formulations typically incorporate polyurethane, epoxy, or fluoropolymer binders with thickness specifications ranging from 0.5 to 4 mils depending on substrate location and functional requirement. Solvent-based formulations currently dominate installed capacity due to proven durability under extreme altitude and temperature conditions, though water-based and UV-curable alternatives are gaining traction as regulatory pressure intensifies. Commercial Aviation represents the largest application segment by volume, while Military Aviation commands premium pricing through specialized radar-absorbing and infrared-suppressive functional requirements.
EMA and REACH frameworks in Europe restrict hexavalent chromium and specific solvent constituents, directly constraining formulation choices and supplier registration obligations. The FAA enforces airworthiness directives and material fireworthiness standards under 14 CFR that govern coating qualification for U.S.-registered aircraft. EPA regulations on hazardous air pollutants further shape domestic manufacturing process requirements and facility compliance investments. Stakeholders must monitor evolving regulatory convergence between jurisdictions, as divergence in approval pathways could fragment supply chain efficiency and inflate qualification costs for multi-regional operators.
Market Dynamics
REACH and EU Green Deal restrictions on volatile organic compounds are hardening formulation standards, compelling coating suppliers to rebuild product lines around chromate-free chemistries and lower-VOC systems while maintaining altitude-rated durability.
Growth Catalysts
- Commercial Aviation Fleet Expansion:OEM production rate increases and MRO activity acceleration in the United States are intensifying substrate protection requirements across narrow-body and wide-body platforms.
- REACH Compliance Mandates:European hexavalent chromium restrictions are forcing formulation upgrades that create competitive differentiation for suppliers with advanced polymer science capabilities.
- Military Functional Requirements:Radar-absorbing and infrared-suppressive coating specifications command premium pricing and sustained R&D investment from defense procurement channels.
Market Restraints
- Raw Material Concentration:Fluoropolymer and specialty epoxy resin supply concentrates among a limited base of chemical producers, exposing formulators to input cost volatility and allocation risk.
- Qualification Timeline Friction:FAA airworthiness directives under 14 CFR impose multi-year coating qualification cycles that delay new formulation commercialization and tie up capital in testing infrastructure.
- Water-Based Performance Gap:Solvent-based systems retain proven durability under extreme thermal cycling and UV exposure, slowing displacement despite regulatory pressure.
Strategic Opportunities
- UV-Curable Formulation Development:Curing technology convergence with energy-efficient production processes offers pathway to reduce VOC emissions while compressing application cycle times.
- Aftermarket Channel Expansion:Specialized MRO facilities in Singapore and Dubai are consolidating volume and seeking direct coating supply relationships outside OEM-captive networks.
- EU Green Deal Tailwind:Sustainability-linked procurement mandates from European flag carriers are creating preferential purchasing terms for suppliers with verified chromate-free portfolios.
Industry Challenges
- Formulation Chemistry Expertise Gap:The specialized knowledge required to balance corrosion resistance, UV stability, and VOC compliance resides with a shrinking cohort of senior chemists approaching retirement.
- Multi-Jurisdictional Registration Burden:Divergent approval pathways between EMA, FAA, and national regulators fragment supply chain efficiency and inflate qualification costs for coatings serving multi-regional operators.
- Legacy Fleet Compatibility:New low-VOC primers and topcoats must demonstrate adhesion and performance parity with existing substrate preparations, constraining reformulation freedom.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Coatings Market |
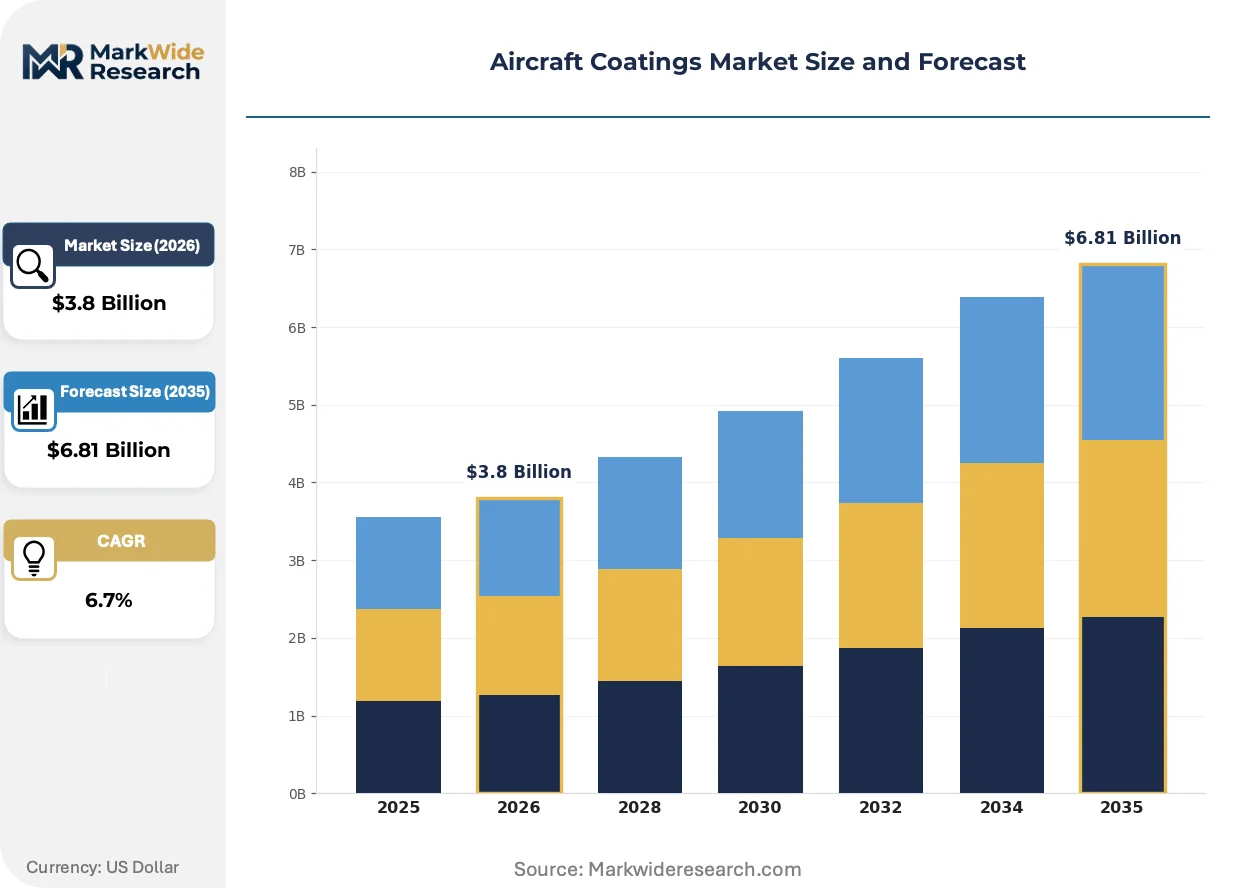
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primer, Topcoat, Basecoat, Clearcoat Application: Commercial Aviation, Military Aviation, General Aviation, Helicopters Formulation: Solvent-Based, Water-Based, UV-Curable, Powder Coating End User: OEMs, MROs, Airlines, Defense Contractors |
| Companies Covered | Akzo Nobel N.V., PPG Industries Inc., Sherwin-Williams Company, Axalta Coating Systems LLC, Mankiewicz Gebr. & Co., BASF SE, Henkel AG & Co. KGaA, Hentzen Coatings Inc., Saint-Gobain S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Coatings Market Evolving Landscape
Formulation science is pivoting toward modular coating architectures that separate functional layers, enabling targeted upgrades without full system replacement and accelerating response to regulatory shifts.
Multi-layer coating systems are modularizing around discrete functional strata: corrosion-inhibiting primers, erosion-resistant intermediate coats, and UV-stable topcoats with independent formulation cycles. Commercial aviation OEMs are adopting this architecture to isolate regulatory-driven primer changes from proven topcoat performance. The approach is modularizing supplier relationships, allowing airlines to mix tier-1 primers with specialized topcoat formulations rather than accepting bundled systems.
EPA hazardous air pollutant regulations are tightening facility emission thresholds for coating manufacturing operations, forcing capital deployment into solvent recovery and thermal oxidizer systems. Domestic production capacity is consolidating toward larger integrated sites with compliance infrastructure. Military aviation contractors with existing environmental management systems are absorbing these costs more readily than smaller MRO-focused formulators.
Airline procurement departments are unbundling coating supply from airframe maintenance contracts, creating direct specification authority over primer and topcoat selection. This disintermediation shifts technical qualification burden from MRO providers to coating suppliers themselves. The pattern is most visible in North American and European flag carrier fleets with centralized technical procurement functions and sustainability-linked supplier scorecards.
Aircraft Coatings Market Segmentation
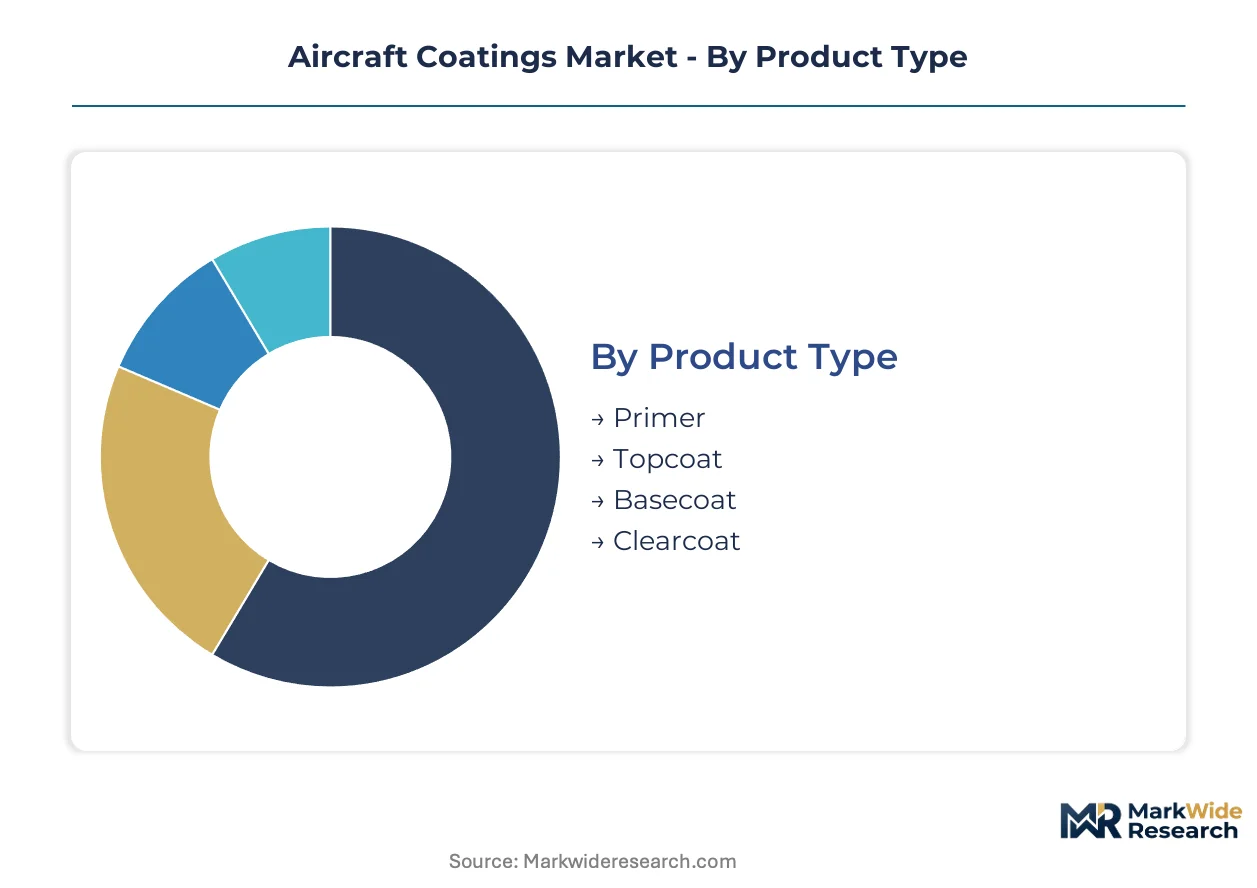
Aircraft coatings segment along four critical dimensions that determine formulation chemistry, qualification pathways, and margin structures. Product type and application govern technical specifications, while formulation and end-user channels shape regulatory exposure and pricing power.
Product Type:
Standardization dominates primers where regulatory compliance drives uniformity, while topcoats permit greater customization around color, gloss, and aerodynamic performance.
- Primer:Chromate-free epoxy formulations now dominate new qualification cycles, with corrosion-inhibiting pigments replacing hexavalent chromium under REACH mandates. Boeing and Airbus production lines in the United States are standardizing on single-source primer systems to streamline airworthiness documentation.
- Topcoat:Polyurethane and fluoropolymer systems manage UV degradation and aerodynamic smoothness, with color-matching precision becoming a competitive differentiator for airline livery refresh programs. European flag carriers are unbundling topcoat selection from MRO contracts, creating direct procurement relationships with specialized suppliers.
- Basecoat:Pigmented intermediate layers provide color saturation and hiding power, typically applied in 0.5-1.0 mil thicknesses.
- Clearcoat:Transparent protective films preserve gloss and chemical resistance, gaining traction in premium livery applications.
Leading the category by volume: Primer systems. Growing fastest: Clearcoat adoption in executive aviation refurbishment.
Application:
Volume concentration in commercial narrow-body platforms contrasts with military specialization around signature management, creating divergent margin profiles across the application spectrum.
- Commercial Aviation:Narrow-body and wide-body platforms consume standardized coating systems in high-volume OEM application, with durability specifications targeting 6-8 year maintenance intervals. FAA airworthiness directives under 14 CFR govern qualification, while airline sustainability scorecards are elevating chromate-free and low-VOC specifications in RFPs.
- Military Aviation:Radar-absorbing materials and infrared-suppressive topcoats command specialized formulation expertise and extended qualification cycles through defense procurement channels. Lockheed Martin and Northrop Grumman programs drive R&D investment in multi-spectral stealth coatings with thermal cycling resistance beyond commercial specifications.
- General Aviation:Business jet and turboprop platforms balance performance requirements with smaller batch sizes and custom color demands.
- Helicopters:Rotor blade erosion resistance and marine environment protection drive specialized intermediate coat formulations.
Commercial Aviation captures the largest volume share. Military Aviation maintains the steepest expansion trajectory through next-generation platform procurement.
Formulation:
Performance-proven solvent systems face displacement pressure from regulatory-driven alternatives, with curing technology emerging as the critical pivot point for capital deployment.
- Solvent-Based:Proven durability under extreme thermal cycling and UV exposure at altitude maintains installed base dominance, though EPA hazardous air pollutant regulations are tightening manufacturing emission thresholds and consolidating production toward integrated facilities with recovery infrastructure.
- Water-Based:Lower VOC profiles align with EU Green Deal procurement mandates, though adhesion and cure time performance gaps persist in extreme climate operations.
- UV-Curable:Energy-efficient curing compresses application cycle times and reduces VOC emissions, attracting investment from MRO facilities in Singapore and Dubai seeking throughput advantages.
- Powder Coating:Near-zero VOC emissions and overspray recovery economics suit component-level applications in landing gear and interior hardware.
Solvent-Based formulations retain volume leadership. UV-Curable systems are climbing the fastest through MRO channel adoption.
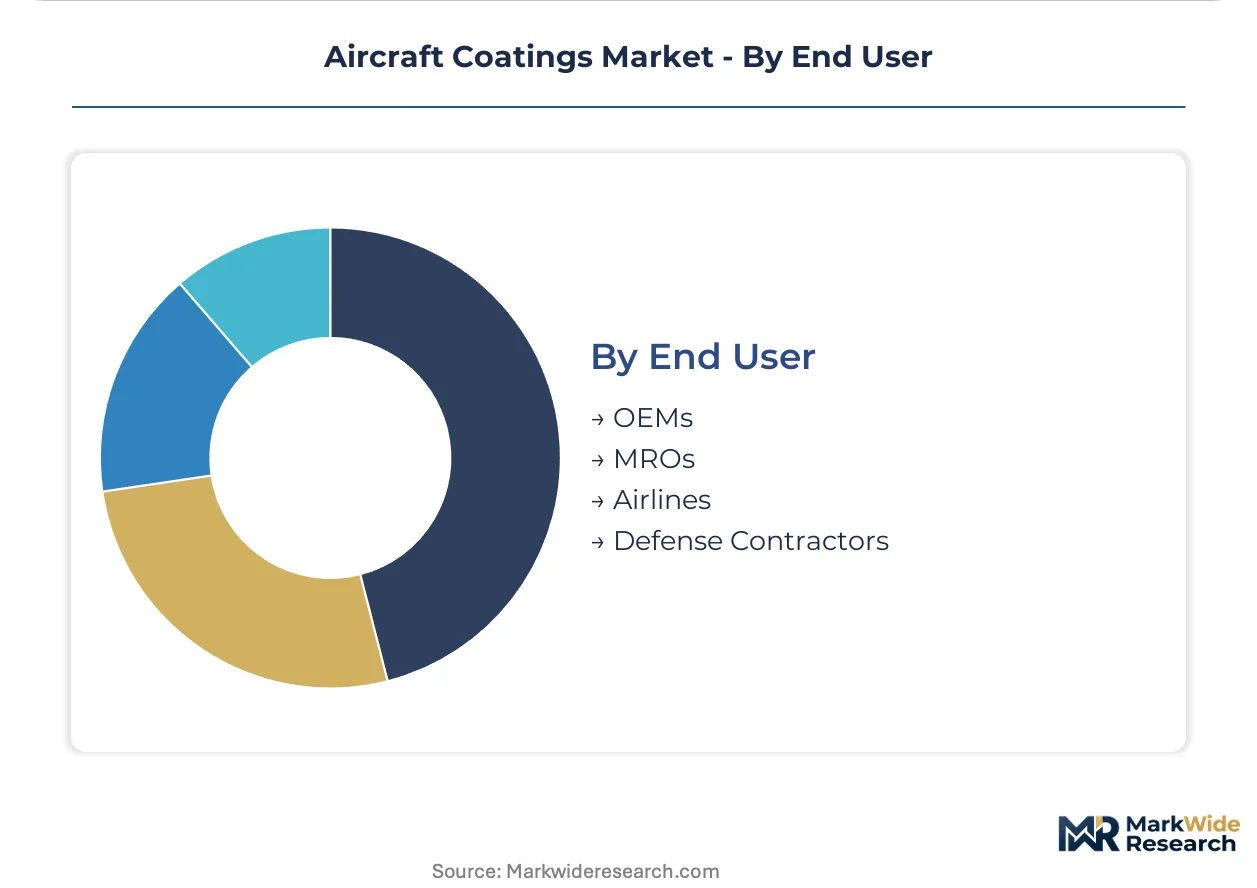
End User:
OEM specification authority is fragmenting as airlines assert direct procurement control, while MRO consolidation is reshaping coating supply relationships.
- OEMs:Boeing, Airbus, and Embraer production lines specify qualified coating systems at airframe assembly, with supplier approval processes spanning 18-36 months and requiring extensive substrate compatibility testing.
- MROs:Singapore and Dubai facilities are consolidating volume and seeking direct supply relationships outside OEM-captive networks, unbundling primer and topcoat procurement.
- Airlines:North American and European flag carriers with centralized technical procurement are implementing sustainability-linked supplier scorecards that prefer chromate-free portfolios.
- Defense Contractors:Long-term platform sustainment contracts and classified specification requirements create captive supply relationships with specialized formulators.
OEMs anchor the category by volume. Airlines are gaining share fastest through procurement disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in the United States and Germany, while consumption growth accelerates in the Middle East and Southeast Asia where fleet expansion outpaces domestic coating supply.
United States
Boeing production lines in Washington and South Carolina drive OEM coating demand alongside MRO hubs in Georgia and Texas. EPA hazardous air pollutant regulations under the Clean Air Act tighten manufacturing emission thresholds, consolidating production toward integrated facilities with thermal oxidizer infrastructure. Dallas-Fort Worth anchors aftermarket volume as American Airlines and Southwest Airlines centralize technical procurement functions.
Germany
Airbus Hamburg and Bremen assembly operations sustain precision coating application requirements for A320 and A350 programs. ECHA REACH restrictions on hexavalent chromium and specific solvent constituents constrain formulation choices and impose registration obligations on chemical suppliers. Bavaria hosts specialized formulators serving both commercial aviation OEMs and defense contractors with stealth coating specifications.
France
Toulouse anchors Airbus final assembly and associated coating qualification activity for wide-body platforms. EU Green Deal sustainability benchmarks harden procurement mandates from Air France-KLM, elevating chromate-free and low-VOC specifications in supplier scorecards. The Paris-Saclay research cluster supports advanced polymer science development for next-generation primer technologies.
Singapore
Seletar Aerospace Park and Changi-based MRO facilities consolidate Southeast Asian fleet maintenance volume, driving direct coating supply relationships outside OEM-captive networks. Singapore's national environmental agency enforces VOC emission controls on manufacturing and surface treatment operations. The city-state's MRO sector is adopting UV-curable systems to compress application cycle times and reduce energy consumption.
United Arab Emirates
Dubai Aerospace Enterprise and Emirates Engineering facilities generate concentrated demand for exterior refurbishment and livery refresh programs. The UAE's Ministry of Climate Change and Environment implements Gulf-standard restrictions on hazardous substance use in industrial coatings. Dubai South's aviation district is attracting specialized coating suppliers seeking direct airline procurement relationships.
Aircraft Coatings Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive polymer science capabilities. Tier-1 suppliers combine primer and topcoat portfolios under unified airworthiness qualification, while specialized formulators occupy niche positions in military stealth and executive aviation segments. Two strategic archetypes dominate: diversified coating giants leveraging R&D scale, and regional specialists capturing MRO channel disintermediation. Competitive moves center on chromate-free formulation registration and direct airline procurement relationship development.
Among diversified chemical conglomerates, Akzo Nobel N.V., PPG Industries Inc., and BASF SE exemplify the integrated archetype. These Amsterdam-, Pittsburgh-, and Ludwigshafen-based entities anchor competitive positioning through combined primer-topcoat portfolios and sustained qualification investment. Their scale permits parallel development tracks for REACH-compliant chromate-free systems and altitude-rated durability specifications. The three companies occupy positions that smaller formulators cannot replicate without multi-year capital deployment into testing infrastructure and regulatory registration.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| PPG Industries Inc. |
| Sherwin-Williams Company |
| Axalta Coating Systems LLC |
| Mankiewicz Gebr. & Co. |
| BASF SE |
| Henkel AG & Co. KGaA |
| Hentzen Coatings Inc. |
| Saint-Gobain S.A. |
| Others |
Value Network & Pricing Analysis
OEM procurement concentration at Boeing and Airbus assembly lines anchors contract-based long-term offtake as the dominant pricing model, with qualification timelines and regulatory compliance costs embedding premium capture for incumbent suppliers.
Pricing Analysis
Margin tightening in military aviation coatings reflects extended defense procurement cycles and specialized stealth formulation requirements. Three-tier pricing structure across OEM-specified, MRO-direct, and aftermarket refurbishment levels separates volume scale from certification grade and application complexity. Price differentiation hinges on REACH chromate-free registration status and FAA airworthiness qualification tier. Airlines with centralized technical procurement exhibit highest price sensitivity, while defense contractors absorb premium pricing for radar-absorbing and infrared-suppressive specifications.
Supply Chain Analysis
Freight costs for fluoropolymer and specialty epoxy resin shipments from Germany, Japan, and the United States elevate landed costs for formulators in Southeast Asian MRO hubs. Raw material supply draws from concentrated chemical producers, with titanium dioxide corrosion inhibitors and polyurethane binders representing critical input dependencies. Single-source vulnerability in chromate-free pigment supply creates exposure to allocation risk during qualification surges. Distribution runs through OEM-captive networks and direct airline procurement channels, with Singapore and Dubai facilities consolidating aftermarket volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where ECHA REACH hexavalent chromium restrictions erect formidable barrier-to-entry moats favoring suppliers with established registration infrastructure and parallel qualification tracks.
For Market Incumbents: Cement chromate-free formulation leadership through accelerated primer registration at EMA and FAA, while absorbing smaller regional formulators facing qualification cost strain. Threat from emerging UV-curable specialists demands captive polymer science investment in Ludwigshafen and Pittsburgh R&D clusters. For New Entrants and Emerging Players: Capture white-space in Singapore and Dubai MRO direct supply relationships outside OEM-captive networks, where airline procurement disintermediation creates specification authority openings. Water-based formulation gaps in extreme climate operations present the most penetrable technical entry point alongside UV-curable curing technology partnerships with Seletar Aerospace Park facilities. For Investors and Strategic Acquirers: The window for entry favors specialized formulators with existing military stealth coating portfolios and ECHA-registered chromate-free primer lines. Long-term viability rests on qualification asset durability rather than volume scale alone. Signal to monitor: airline sustainability scorecard weighting shifts toward verified low-VOC supply chain documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Chromate-Free Formulation Registration | ECHA REACH compliance creates defensible positioning against unregistered competitors in European procurement channels. |
| UV-Curable Technology Licensing | Singapore MRO adoption of energy-efficient curing compresses cycle times and reduces VOC emission exposure. |
| Direct Airline Procurement Relationship | American Airlines and Southwest Airlines centralized technical functions enable specification authority outside OEM bundles. |
| Military Stealth Coating R&D Partnership | Lockheed Martin and Northrop Grumman programs sustain premium pricing through classified multi-spectral requirements. |
| Backward Integration into Specialty Resin Supply | Captive fluoropolymer production mitigates raw material concentration risk among limited chemical producers. |
Research Methodology
Independent corroboration across coating formulator technical directors, airline procurement managers, and MRO facility operations heads underwrites the qualitative findings. Primary interviews with ECHA regulatory affairs specialists, FAA certification engineers, and defense contractor supply chain directors combined with secondary validation from ECHA registration databases, FAA airworthiness directives under 14 CFR, and customs trade data for fluoropolymer and epoxy resin shipments. Bottom-up volume modeling triangulated against top-down OEM production rate projections.
Comparable-period anchoring to historical qualification cycle durations and fleet expansion trajectories structured the forecast framework across the analysis window. Segmentation dimensions modeled include product type tier, application platform, formulation chemistry, and end-user channel authority. CAGRs derived from regression analysis of coating consumption per airframe against delivery forecasts. Industry-specific inputs incorporated REACH compliance cost absorption rates and MRO channel disintermediation velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence between EMA and FAA approval pathways and raw material supply concentration disruptions. Forecasts reflect documented assumptions regarding fleet replacement rates and sustainability procurement mandate adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace Cold Forgings Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives and Sealants Market
Aerospace and Aircraft Materials
Advanced Materials for Flying Cars Market
Aerospace and Aircraft Materials
Aerospace Titanium Market
Aerospace and Aircraft Materials
Aerogel Market
Aerospace and Aircraft Materials
Aerospace and Defense Metal Stamping Market
Aerospace and Aircraft Materials
Radiation Shielding Market
Aerospace and Aircraft Materials
Aircraft Carbon Brake Disc Market
Aerospace and Aircraft Materials
India Aerospace Coating Market
Aerospace and Aircraft Materials
Aerospace Lightweight Materials Market
Aerospace and Aircraft Materials
Commercial Aerospace 3D Printing Market
Aerospace and Aircraft Materials
Aviation Carbon Fiber Market
Aerospace and Aircraft Materials
Aerospace Sealants Market
Aerospace and Aircraft Materials
Aerospace Forging Market
Aerospace and Aircraft Materials
Global High Strength Aluminum Alloys Market
Aerospace and Aircraft Materials
Global Aerospace Insulation Market