
 Global Farm Animal Healthcare Market | 2026-2036
Global Farm Animal Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Global Farm Animal Healthcare Market Analysis
Recombinant DNA vaccines are broadening product economics in livestock immunization. Zoetis Inc leverages its transgenic platform to anchor production of single-dose cattle vaccines. Boehringer Ingelheim International GmbH sustains competitive pressure through backward integration into antigen manufacturing. Merck & Co. Inc. differentiates via thermostable formulations suited for tropical distribution.
Farm animal healthcare encompasses pharmaceuticals, biologicals, and diagnostic tools administered to cattle, swine, poultry, and sheep to prevent disease, treat infection, and maintain herd productivity; vaccine formulations typically require cold-chain stability between 2°C and 8°C and adjuvant systems that stimulate cell-mediated immunity. Parasiticides command the largest revenue pool among product types due to recurring seasonal application cycles, while nutraceuticals represent the fastest-expanding category as producers phase out growth-promoting antibiotics under regulatory pressure. Preventive care applications now absorb the majority of farm-level spending as integrated operations prioritize prophylaxis over curative intervention.
The FDA Center for Veterinary Medicine enforces residue monitoring protocols that shape product withdrawal periods and label claims in the United States. EMA's updated Veterinary Medicines Regulation restricts antimicrobial use to prescription-only frameworks across EU member states, compressing over-the-counter sales channels. India's CDSCO mandates batch-release testing for imported biologicals, creating procedural friction for multinational suppliers. Stakeholders must weigh regulatory compliance investments against portfolio exposure to jurisdictions with divergent antibiotic stewardship timelines.
Market Dynamics
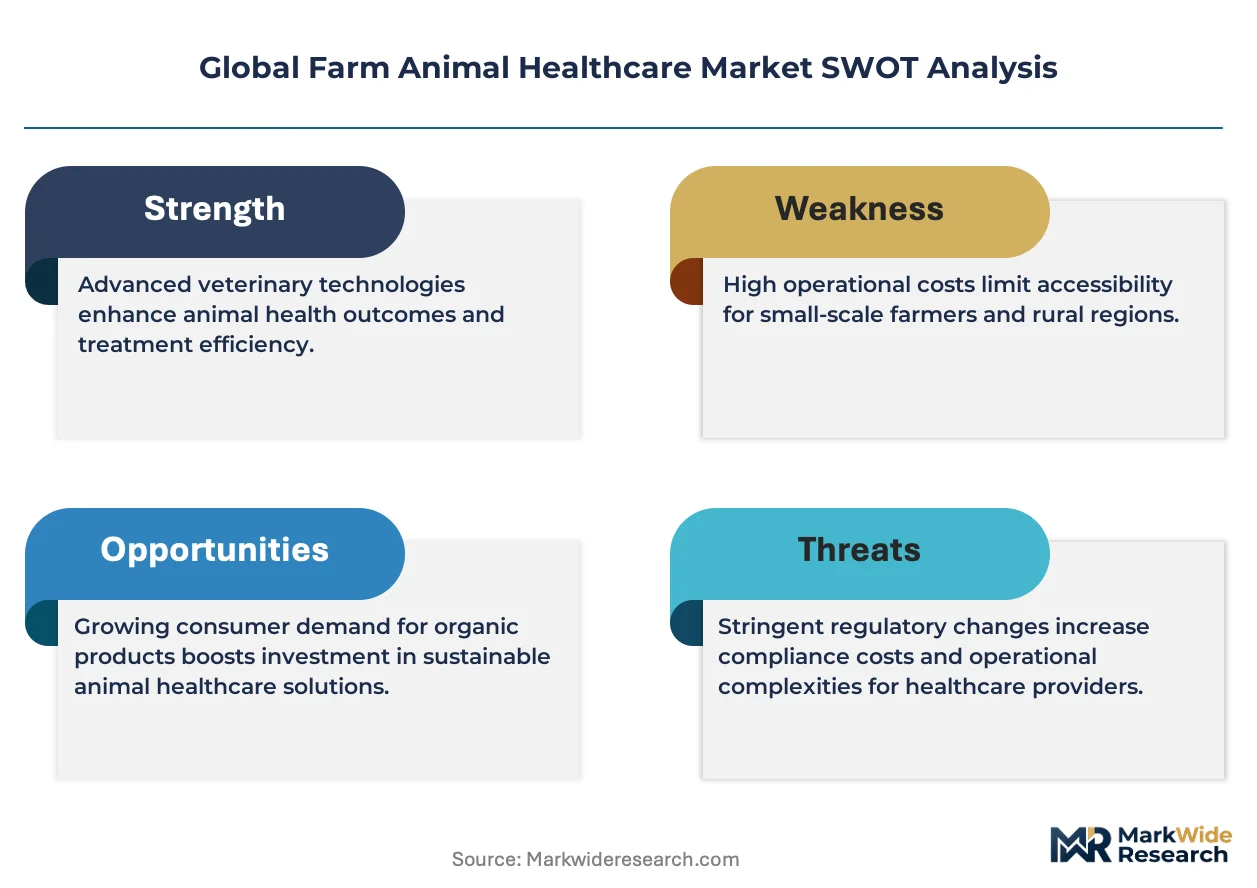
The EU Veterinary Medicines Regulation's antimicrobial restrictions are compressing antibiotic sales channels while simultaneously elevating demand for preventive biologicals and diagnostics across integrated livestock operations.
Growth Catalysts
- EMA Prescription Mandates:The EU's tightened antibiotic stewardship framework forces producers toward vaccines and probiotics, expanding the addressable market for preventive biologicals in member states.
- Precision Livestock Technologies:Sensor-based health monitoring systems enable early disease detection, driving recurring demand for diagnostic consumables and data-integrated treatment protocols.
- Brazil Dairy Expansion:Large-scale cattle operations in São Paulo and Minas Gerais states are systematizing vaccination schedules, creating sustained pull for multivalent vaccine formulations.
Market Restraints
- Cold-Chain Infrastructure Gaps:Temperature-controlled distribution requirements for biologicals limit penetration in regions with unreliable 2°C-8°C logistics networks, particularly in sub-Saharan Africa and parts of Southeast Asia.
- Antigen Manufacturing Concentration:A small cluster of European and North American suppliers controls critical adjuvant and antigen production, creating vulnerability to supply disruptions.
- Regulatory Divergence Costs:India's CDSCO batch-release testing for imported biologicals adds 4-6 week procedural delays, raising working capital requirements for multinational suppliers.
Strategic Opportunities
- Vietnam Poultry Belt:Commercial layer and broiler operations around Đồng Nai Province remain underpenetrated by thermostable vaccine formulations suited to tropical storage conditions.
- Nutraceutical Substitution:Phytogenic feed additives and enzyme supplements capture share from withdrawn antibiotic growth promoters, with EU producers leading adoption.
- Telemedicine Integration:Remote veterinary consultation platforms enable diagnostic product bundling and subscription-based preventive care programs for dispersed smallholder herds.
Industry Challenges
- Veterinary Diagnostic Skill Scarcity:Field-level capacity for molecular diagnostic interpretation lags behind instrument deployment, particularly in India's commercial poultry corridor.
- Multivalent Formulation Complexity:Combining antigens for respiratory, reproductive, and enteric pathogens without immunological interference demands extended R&D timelines and elevated regulatory submission costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Farm Animal Healthcare Market |
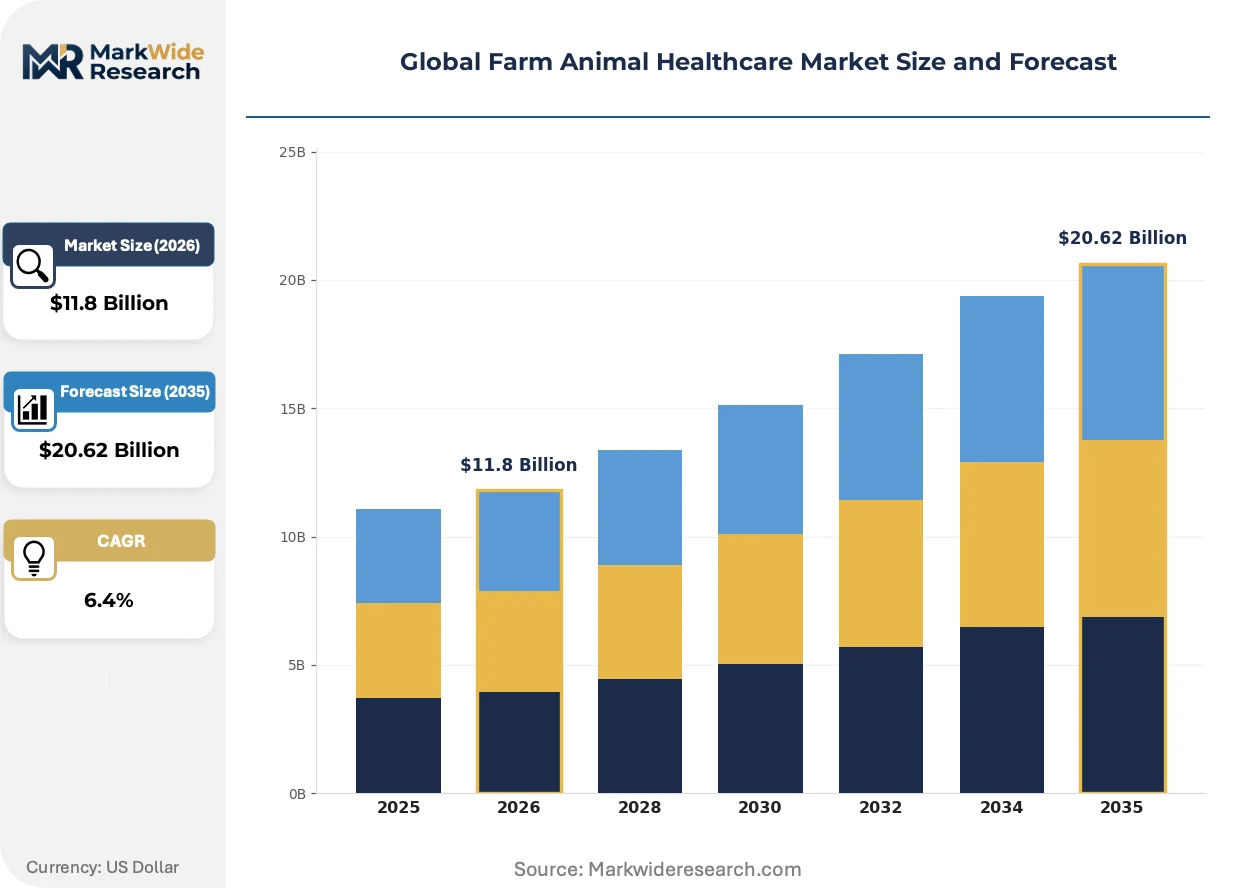
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antibiotics, Parasiticides, Nutraceuticals End User: Veterinary Clinics, Farms, Research Institutions, Pet Hospitals Application: Preventive Care, Treatment, Diagnosis, Research Distribution Channel: Veterinary Pharmacies, E-Commerce, Distributors, Direct Sales |
| Companies Covered | Zoetis Inc, Boehringer Ingelheim International GmbH, Elanco, Ceva Animal Health Inc, Merck & Co. Inc., Vetoquinol, Phibro Animal Health, Virbac, IDEXX Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Farm Animal Healthcare Market Emerging Trajectories
Recombinant platforms and thermostable formulations are restructuring product economics while regulatory pressure on antimicrobial residues accelerates substitution toward preventive modalities.
mRNA vaccine architectures adapted from human medicine are overtaking conventional killed-virus platforms in development pipelines for swine respiratory diseases. Large integrated pork producers in Denmark and the Netherlands are piloting these formulations for porcine reproductive and respiratory syndrome. The shift is compressing development timelines from years to months while raising manufacturing complexity and capital requirements.
EMA's updated Veterinary Medicines Regulation establishes prescription-only frameworks for antimicrobial use across EU member states. This policy compresses over-the-counter sales channels and elevates veterinary consultation requirements. Producers are responding by consolidating supplier relationships and demanding integrated preventive care packages from animal health companies.
Subscription-based preventive health programs are displacing transactional product purchasing among mid-scale dairy operations. These bundled offerings combine vaccines, parasiticides, and diagnostic monitoring into per-animal monthly fees. The model is most visible in Brazil's southeastern dairy belt, where cooperatives negotiate enterprise-wide contracts with animal health providers.
Global Farm Animal Healthcare Market Segmentation
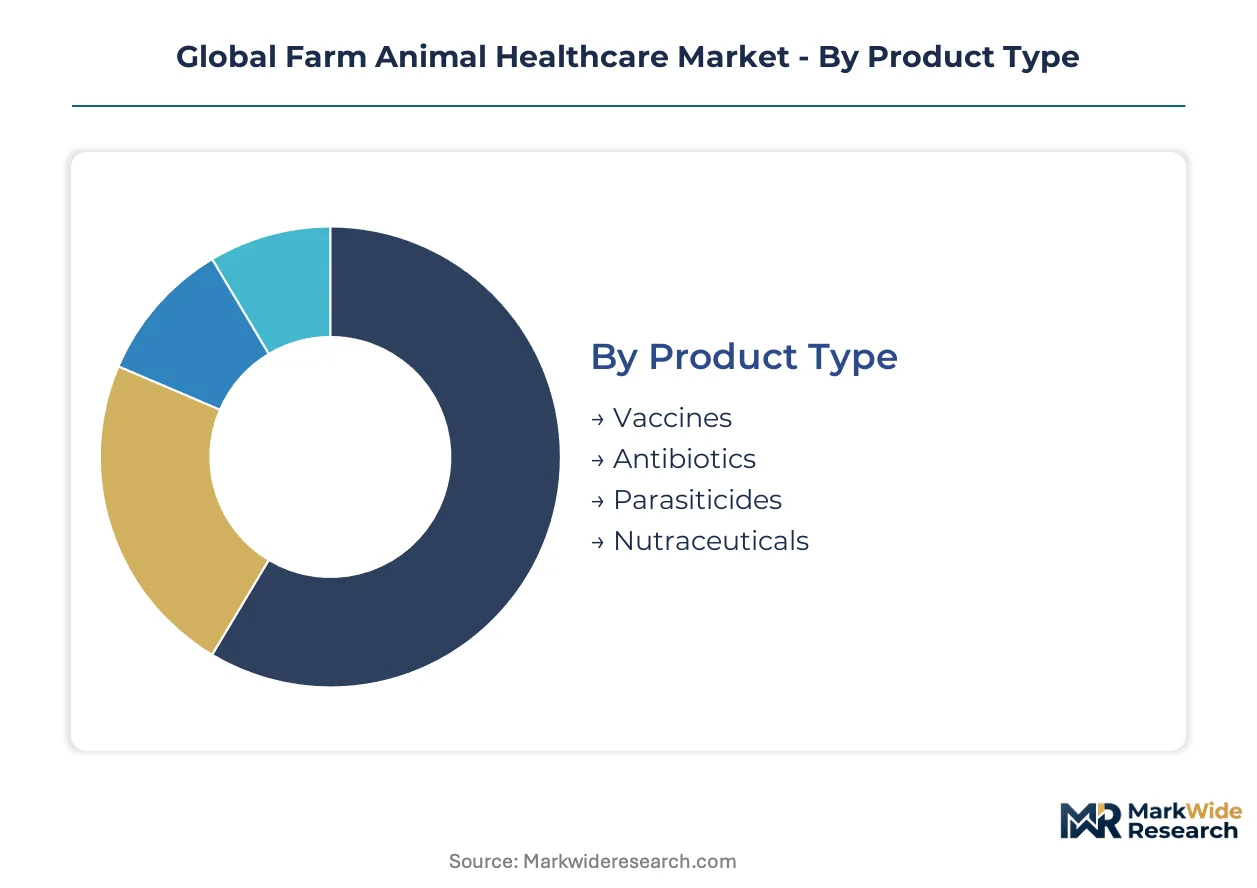
Product portfolios in farm animal healthcare fragment across biologicals, pharmaceuticals, and nutritional interventions. Supply-side capabilities and regulatory compliance requirements create distinct competitive dynamics within each category.
Product Type:
Manufacturing concentration clusters around adjuvant production and cold-chain biologicals, with formulation complexity determining margin structures.
- Parasiticides:Endectocides, anthelmintics, and ectoparasiticides require seasonal reapplication cycles. Demand concentrates in Brazil's expanding dairy belt and Australia's sheep stations, driven by climate-intensified parasite pressure and export certification requirements.
- Nutraceuticals:Phytogenic feed additives, enzymes, and probiotic formulations displace withdrawn antibiotic growth promoters. EU producers lead adoption as EMA prescription mandates compress antimicrobial channels, with fastest expansion trajectory among all product categories.
- Vaccines:Killed-virus, live-attenuated, and recombinant DNA platforms for respiratory, reproductive, and enteric pathogens. India's CDSCO batch-release testing creates procedural friction for imported biologicals.
- Antibiotics:Therapeutic and metaphylactic formulations face tightening stewardship frameworks. Prescription-only mandates across EU member states and FDA residue monitoring in the United States constrain over-the-counter distribution.
Today's leader: Parasiticides. Tomorrow's challenger: Nutraceuticals.
End User:
Customer scale and veterinary access determine procurement patterns and service bundling requirements.
- Farms:Integrated livestock operations and cooperatives drive volume procurement through enterprise contracts. Brazil's southeastern dairy belt systematizes vaccination schedules, creating sustained demand for multivalent formulations and subscription-based preventive programs.
- Veterinary Clinics:Mixed-animal and food-animal practices serve as gatekeepers for prescription products. EMA's antimicrobial restrictions elevate consultation requirements, consolidating supplier relationships around integrated care packages.
- Research Institutions:Universities and government laboratories conduct field trials and regulatory studies. Molecular diagnostic skill scarcity in India's commercial poultry corridor limits instrument deployment effectiveness.
- Pet Hospitals:Companion animal facilities with incidental farm animal caseloads. Limited cold-chain infrastructure and species-specific expertise constrain service depth.
Procurement is shifting toward Farms as cooperatives negotiate enterprise-wide contracts.
Application:
Revenue allocation reflects producer prioritization of herd productivity maintenance over curative intervention.
- Preventive Care:Vaccination, parasiticide programs, and nutritional optimization absorb majority of farm-level spending. Precision livestock technologies enable early disease detection, driving recurring diagnostic consumable demand in Denmark and Netherlands pork operations.
- Treatment:Therapeutic intervention for acute infection and injury. Antibiotic stewardship timelines diverge across jurisdictions, compressing channels in the EU while sustaining demand elsewhere.
- Diagnosis:Laboratory and point-of-care testing for pathogen identification and surveillance. Sensor-based health monitoring systems integrate with data-driven treatment protocols.
- Research:Vaccine development trials, resistance monitoring, and regulatory submission studies. mRNA platform adaptation from human medicine compresses swine respiratory disease development timelines.
Preventive Care captures current spending majority. Diagnosis is gaining share fastest through technology integration.
Distribution Channel:
Cold-chain requirements and regulatory compliance shape channel viability across geographies.
- Distributors:Regional wholesalers with temperature-controlled logistics networks dominate biological product flow. Concentration in European and North American antigen manufacturing creates supply vulnerability.
- Veterinary Pharmacies:Prescription-dispensing outlets with professional consultation services. EMA mandates elevate their gatekeeper role for antimicrobial products.
- E-Commerce:Direct-to-producer platforms for non-restricted products. Cold-chain infrastructure gaps in sub-Saharan Africa and parts of Southeast Asia limit biological penetration.
- Direct Sales:Manufacturer relationships with large integrated operations. Subscription-based preventive health programs displace transactional purchasing in Brazil's dairy sector.
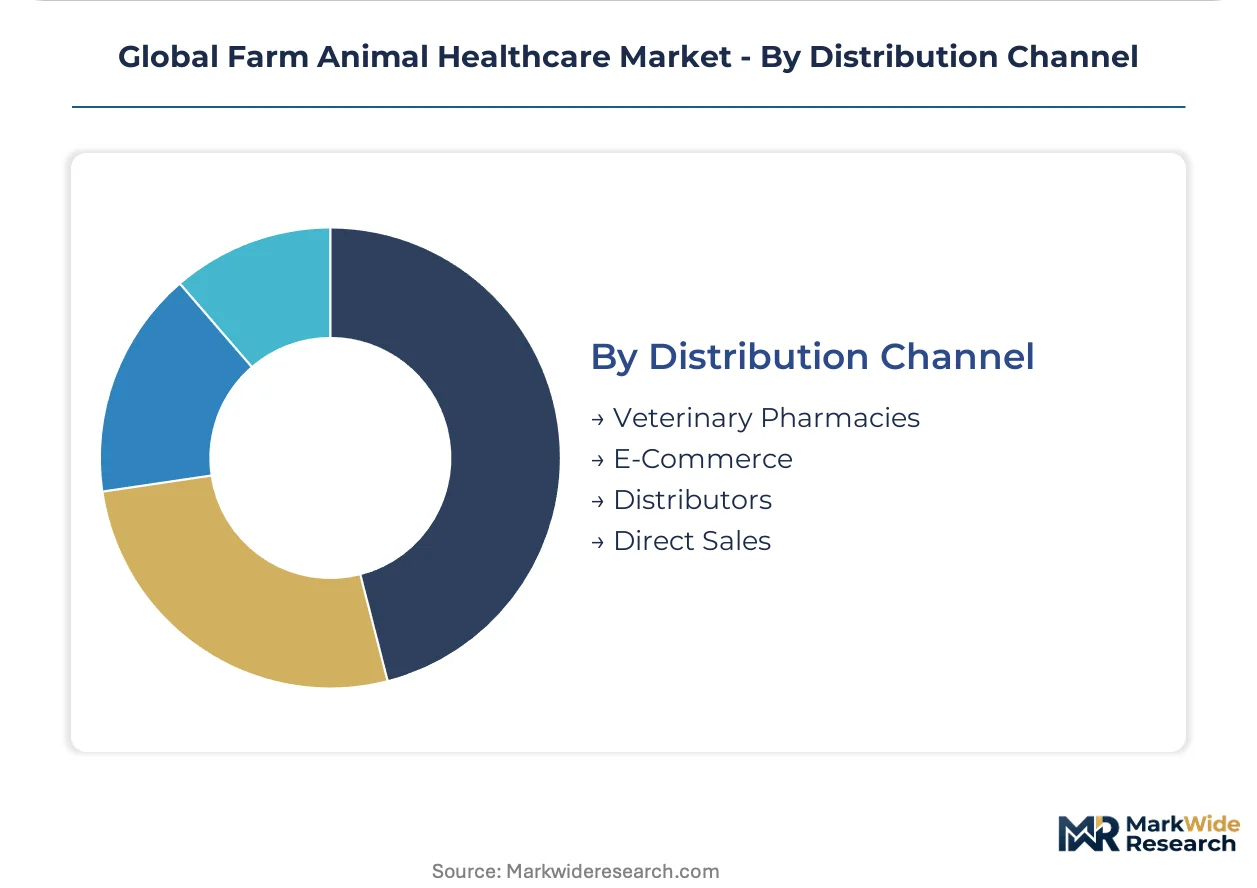
Distributors anchor biological supply. Direct Sales is climbing the fastest through enterprise contract consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's southeastern dairy belt anchors the strongest regional growth trajectory, with São Paulo and Minas Gerais states systematizing preventive vaccination schedules. Large-scale cattle operations there negotiate enterprise-wide contracts for multivalent formulations, creating sustained pull for cold-chain biologicals. Precision livestock technologies are diffusing rapidly across this corridor.
United States
Integrated pork producers in Iowa and North Carolina drive demand for mRNA vaccine platforms adapted from human medicine. The FDA Center for Veterinary Medicine enforces residue monitoring protocols that shape product withdrawal periods and label claims. Large-scale feedlot operations in the Texas Panhandle prioritize subscription-based preventive programs over transactional purchasing.
Germany
Denmark and Netherlands pork operations pilot recombinant DNA formulations for porcine respiratory diseases, compressing development timelines. EMA prescription mandates for antimicrobial use elevate veterinary consultation requirements across member states. Bavarian dairy cooperatives consolidate supplier relationships around integrated care packages combining diagnostics and biologicals.
India
Commercial poultry operations in Telangana and Andhra Pradesh absorb the majority of biological demand, though molecular diagnostic skill scarcity limits instrument deployment effectiveness. CDSCO batch-release testing for imported vaccines adds procedural delays, raising working capital requirements for multinational suppliers. Haryana's layer farms expand precision monitoring systems for early disease detection.
Vietnam
Commercial broiler and layer operations around Đồng Nai Province remain underpenetrated by thermostable vaccine formulations suited to tropical storage conditions. The country's national pharmaceutical regulator maintains import licensing frameworks for biological products. Mekong Delta aquaculture-livestock integration creates cross-species health management demand.
Australia
Sheep stations across New South Wales and Victoria sustain seasonal parasiticide application cycles driven by climate-intensified parasite pressure. Export certification requirements for red meat access to Asian markets elevate herd health investment. Queensland beef operations expand sensor-based health monitoring for extensive grazing systems.
Global Farm Animal Healthcare Market Vendor Landscape
Global majors compete with regional champions across biological manufacturing and distribution networks, creating a tiered structure where scale-driven players anchor premium segments while specialized suppliers capture niche therapeutic categories. Three strategic archetypes dominate: integrated pharmaceutical conglomerates with transgenic platforms, mid-scale specialists in thermostable formulations, and regional distributors with captive cold-chain logistics. Competitive intensity centers on backward integration into antigen production and geographic expansion through enterprise contract consolidation.
Within the integrated pharmaceutical tier, Zoetis Inc and Boehringer Ingelheim International GmbH occupy positions exemplifying platform-based competitive advantage, while Merck & Co. Inc. represents the thermostable formulation specialization vector. These three entities anchor the premium segment through distinct technical capabilities rather than undifferentiated scale, with each occupying a definable position in the recombinant DNA and distribution technology landscape. Their collective presence establishes the baseline against which regional challengers and emerging platform specialists must differentiate.
| Leading Market Players |
|---|
| Zoetis Inc |
| Boehringer Ingelheim International GmbH |
| Elanco |
| Ceva Animal Health Inc |
| Merck & Co. Inc. |
| Vetoquinol |
| Phibro Animal Health |
| Virbac |
| IDEXX Laboratories |
| Others |
Supply Flow & Price Mechanics
EMA prescription mandates for antimicrobial use gate qualified supply and premium-tier pricing access for preventive biologicals, compressing over-the-counter channels while elevating veterinary consultation requirements that bundle diagnostics with biological procurement.
Pricing Analysis
Input-cost pass-through from concentrated adjuvant manufacturing shapes margin structures across vaccine tiers. Subscription-based preventive programs in Brazil's dairy belt displace per-unit transactional purchasing, with price differentiation anchored in cold-chain reliability and thermostable formulation certification. Cost compression in standard-tier parasiticides intensifies as generic manufacturers expand production capacity. Smallholder operations in Southeast Asia exhibit highest price sensitivity, while integrated pork producers in Denmark and the Netherlands absorb premium pricing for mRNA platform access.
Supply Chain Analysis
EMA batch-release certification and FDA residue monitoring protocols gate supplier participation, with antigen manufacturing concentrated in Germany, the United States, and the Netherlands. Production draws from recombinant DNA platform inputs, thermostable formulation chemistries, and molecular diagnostic reagents. Single-source vulnerability in European adjuvant supply creates exposure to regulatory inspection delays. Distribution runs through regional wholesalers with captive cold-chain networks, with direct sales climbing fastest through enterprise contract consolidation in Brazil and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in preventive biologicals as antibiotic stewardship timelines compress therapeutic channels and elevate subscription-based care economics.
For Market Incumbents: Deepen backward integration into antigen manufacturing to defend against supply disruption risks from European adjuvant concentration. Expand thermostable formulation capacity for tropical distribution, capturing share in Vietnam's underpenetrated poultry belt. Lock in enterprise contracts with Brazilian dairy cooperatives before regional distributors consolidate channel control. For New Entrants and Emerging Players: EMA prescription mandates in Europe open a window for diagnostic-integrated preventive packages that bundle sensors with biological subscriptions. Target India's commercial poultry corridor with point-of-care molecular platforms that address veterinary skill scarcity. Pursue telemedicine partnerships as the go-to-market angle for dispersed smallholder herds in sub-Saharan Africa. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors with captive cold-chain logistics and established veterinary pharmacy relationships. Long-term viability hinges on exposure to preventive care modality shifts rather than therapeutic antibiotic channels. Watch for CDSCO regulatory harmonization signals in India as the inflection indicator for multinational supplier working capital efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Antigen Manufacturing | Boehringer Ingelheim's captive production insulates margin structures from European supply concentration. |
| Thermostable Formulation Development | Merck's tropical-stability platforms unlock Vietnam poultry belt penetration without 2°C-8°C infrastructure. |
| Subscription Preventive Program Launch | Brazilian dairy cooperatives now contract per-animal monthly fees bundling vaccines with diagnostic monitoring. |
| Precision Livestock Technology Integration | Sensor-based health monitoring in Denmark pork operations drives recurring diagnostic consumable demand. |
| Regulatory Compliance Investment | Zoetis navigates CDSCO batch-release testing through dedicated India regulatory affairs infrastructure. |
Methodological Framework
Coverage spans the United States, Brazil, Germany, India, and Vietnam, with primary inputs from each market combining structured interviews with animal health company executives, veterinary clinic procurement managers, dairy cooperative technical directors, and poultry operation veterinarians. Secondary validation draws from FDA Center for Veterinary Medicine filings, EMA regulatory submission databases, CDSCO import licensing records, and customs trade data on biological product flows. Bottom-up demand modeling and top-down supply capacity estimates undergo triangulation against precision livestock technology deployment metrics.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon. Segmentation dimensions include product type, end user scale tier, preventive versus therapeutic application, and distribution channel structure. CAGRs derive from logistic diffusion curves for technology adoption and regulatory phase-in timelines. Industry-specific forecast inputs incorporate EMA prescription mandate compliance trajectories and Brazilian dairy herd expansion schedules.
Revisions become necessary when antimicrobial stewardship timelines accelerate, cold-chain infrastructure investment lags in target geographies, or mRNA platform manufacturing yields diverge from baseline assumptions. A model refresh is warranted upon material change in CDSCO regulatory harmonization progress or EMA veterinary consultation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
China Companion Animal Health Market
Animal Health
Animal Health Software Market
Animal Health
Laboratory Animal Models Market
Animal Health
Global Companion Animal Health Market
Animal Health
Swine Healthcare Market
Animal Health
Equine Fluid Therapy Market
Animal Health
Companion Animal Healthcare Market
Animal Health
Animal Health Market
Animal Health
Companion Animal Ear Infection Treatment Market
Animal Health
Canine Arthritis Treatment Market
Animal Health
Cattle Healthcare Market
Animal Health
Canine Influenza Treatment Market
Animal Health
Rat Model Market
Animal Health
Zoonotic Disease Treatment Market
Animal Health
Companion Animal Medicine Market
Animal Health
US Companion Animal Health Market